
 Tomato Paste Market | 2026-2036
Tomato Paste Market Size, Share, and Industry Trends Forecast 2026-2036
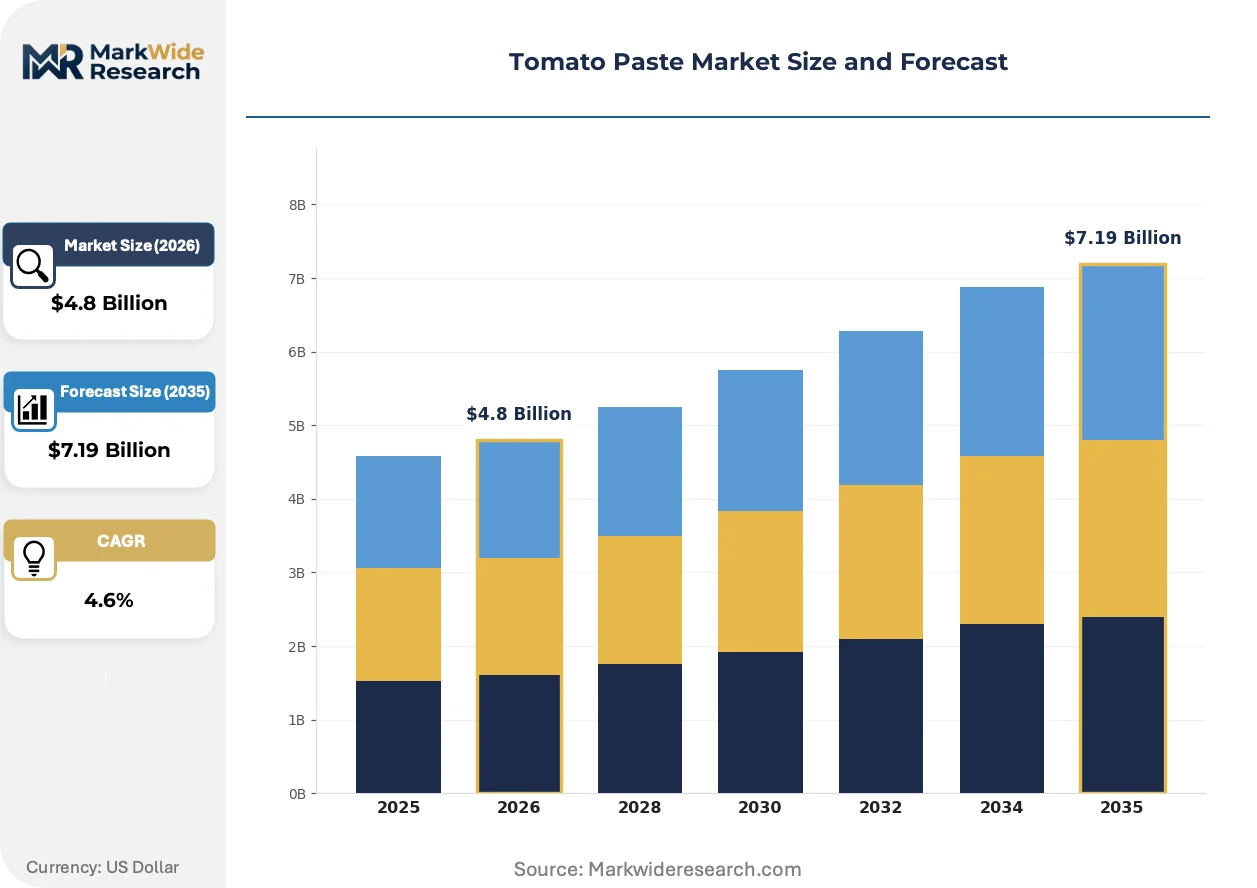
Tomato Paste Market Outlook
China's Xinjiang processing corridor is reshaping global tomato paste supply dynamics through massive solvent extraction and triple-concentrate capacity additions. COFCO Tunhe Tomato Co., Ltd. leverages state-controlled agricultural contracts to lock in raw tomato supply at scale. The Morning Star Company sustains its position through vertically integrated California tomato farming and industrial processing. Mutti S.p.A. differentiates via single-origin Italian sourcing and premium positioning in European retail channels.
Tomato paste is a concentrated tomato product manufactured by reducing fresh tomatoes to 24-36% soluble solids through evaporation, yielding a shelf-stable ingredient with standardized color, acidity, and viscosity for industrial formulation. The concentrate typically serves as a base for sauces, soups, and processed foods where consistent tomato flavor and long storage life are required. Concentrated product forms dominate industrial procurement due to lower shipping costs and longer shelf stability, while retail-packaged puree and crushed formats compete for household pantry share. Glass jar packaging commands premium positioning in European specialty retail, whereas metal can and aseptic pouch formats anchor food service and industrial bulk purchasing.
EFSA pesticide residue limits and FDA food safety modernization rules govern import access and processing standards across major consuming regions. EU Green Deal carbon accounting requirements and California's agricultural water regulations are tightening compliance costs for processors dependent on irrigation-intensive farming. Stakeholders must monitor water rights allocations in California's Central Valley and China's Yellow River basin, as these constrain raw material availability before demand shifts materialize.
Market Dynamics
California's Central Valley processing corridor and China's Xinjiang basin now control over two-thirds of global tomato paste volume, concentrating supply leverage among irrigation-dependent mega-processors who face tightening water allocation regimes.
Growth Catalysts
- Food service menu expansion:North American and European restaurant chains are embedding tomato-based sauces into prepared meal formats, pulling industrial concentrate demand upward.
- EU Green Deal traceability mandates:EFSA's tightened pesticide residue documentation is advantaging large processors with integrated farm-to-fork data systems over fragmented Mediterranean suppliers.
- Triple-concentrate extraction technology:Solvent extraction advances in Xinjiang are compressing unit production costs below Mediterranean break-even thresholds.
Market Restraints
- Water rights constraints:California's agricultural water regulations and China's Yellow River basin allocation limits threaten raw tomato availability before demand signals adjust.
- Input cost volatility:Natural gas prices directly govern evaporation energy costs, exposing processors to European energy market swings.
- Substitution pressure:Tomato powder and freeze-dried alternatives are capturing premium formulation share in dehydrated soup and sauce applications.
Strategic Opportunities
- Single-origin retail positioning:Glass jar formats with Italian provenance certification command shelf price multiples in European specialty channels.
- Aseptic pouch industrial adoption:Food service operators are replacing metal drums with bag-in-box formats to reduce waste handling and improve dispensing efficiency.
- Carbon accounting transparency:EU CSRD reporting requirements are creating first-mover advantage for processors with verified irrigation carbon footprints.
Industry Challenges
- Skill gaps in precision agriculture:Variable rate irrigation and drone-based crop monitoring require agronomists with data science competencies that existing tomato farming regions lack.
- Legacy equipment retrofit costs:Evaporator energy efficiency upgrades demand capital deployment that mid-scale Mediterranean cooperatives cannot finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tomato Paste Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Concentrated, Puree, Diced, Crushed Packaging Type: Glass Jar, Tetra Pack, Metal Can, Plastic Pouch End User: Food Service, Retail, Industrial, Household Distribution Channel: Online, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | Del Monte Foods, Inc., Kagome Co., Ltd., COFCO Tunhe Tomato Co., Ltd., Mutti S.p.A., CONESA Group, Xinjiang Chalkis Company Ltd., Campbell Soup Company, The Morning Star Company, Conagra Brands, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tomato Paste Market Strategic Shifts
Processing technology and packaging formats are compressing cost structures while regulatory transparency requirements reshape competitive differentiation across the concentrate supply chain.
Membrane filtration concentration systems are replacing thermal evaporation in Xinjiang and California facilities, slashing natural gas consumption per ton of paste produced. Industrial buyers in the prepared soup and sauce sectors are specifying membrane-processed concentrate for carbon footprint reduction targets. Traditional multi-effect evaporator infrastructure is rendering obsolete across new capacity investments.
EFSA's updated maximum residue levels for neonicotinoid pesticides are forcing third-country exporters to implement farm-level integrated pest management documentation. Mediterranean suppliers without contract farming control face exclusion from EU retail and food service procurement. Italian and Spanish processors are responding by consolidating backward into controlled agricultural supply.
Buyer concentration among multinational food manufacturers is compressing supplier margins through formula pricing tied to spot tomato paste futures. Long-term offtake agreements with fixed escalators are displacing spot market procurement for volume-stable industrial accounts. This shift is most visible in German and Dutch processed food manufacturing corridors where three buyers control over half of import demand.
Tomato Paste Market Segmentation
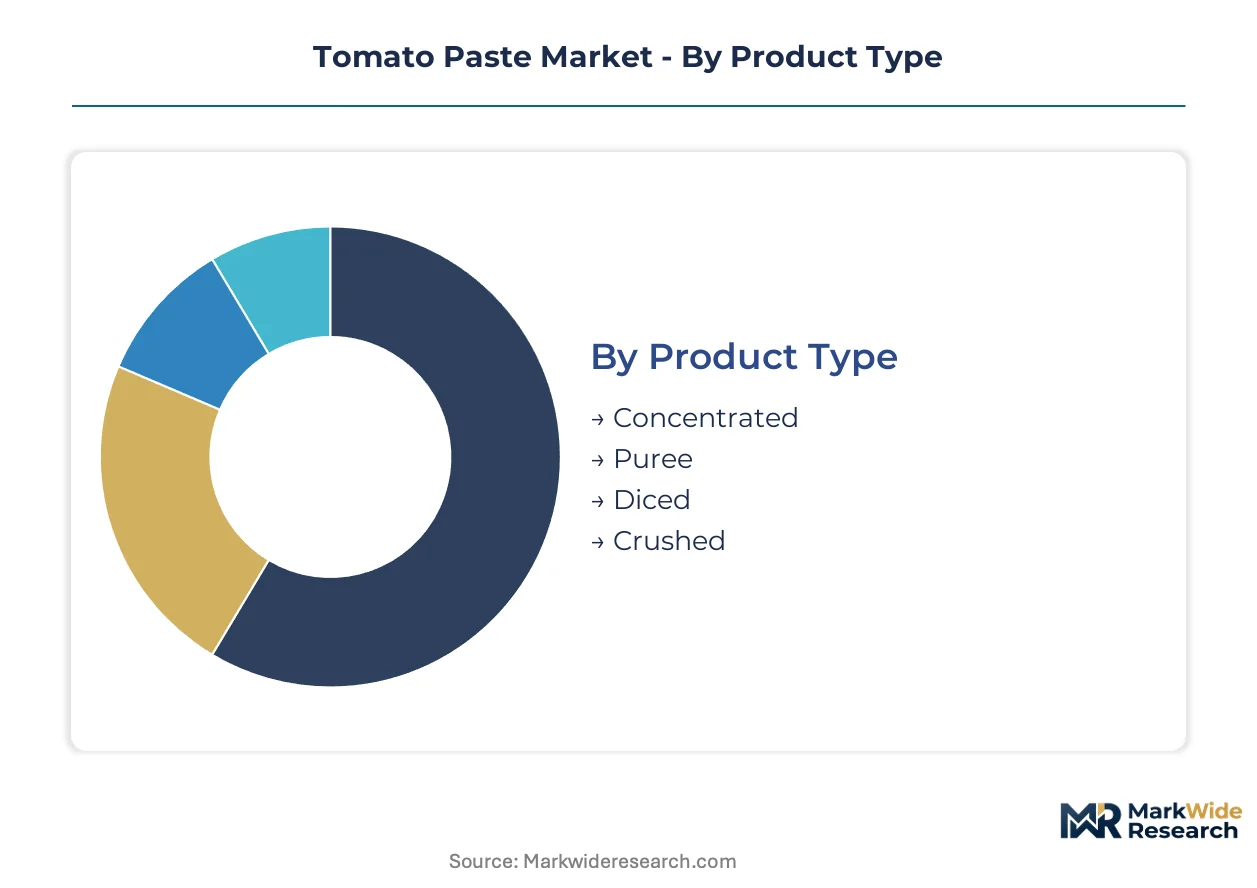
Tomato paste procurement patterns diverge sharply across product concentration levels and packaging formats. Industrial buyers prioritize shipping efficiency and shelf stability, while retail channels reward provenance certification and dispensing convenience.
Product Type:
Cost tier separates commodity concentrate from value-added formats with shorter processing chains and higher per-unit margins.
- Concentrated:Triple-concentrate paste at 36-38% soluble solids dominates bulk industrial procurement for sauce and soup manufacturing. Food service operators in Germany and the Netherlands specify aseptic bag-in-box concentrate to minimize waste handling.
- Puree:Single-strength tomato puree at 8-10% solids serves retail cooking applications requiring pourable consistency. Italian specialty retailers stock glass-jar puree with DOP certification for home cooks seeking authentic provenance.
- Diced:Canned diced tomatoes in juice retain texture for pizza and pasta sauce applications where visual tomato identity matters.
- Crushed:Coarse-crushed format bridges whole and pureed states for rustic sauce formulations in Mediterranean food service.
Concentrated commands the established base. The steepest expansion runs through puree as retail premiumization accelerates.
Packaging Type:
Application determines format selection, with food service automation driving pouch adoption and European retail sustaining glass jar premiums.
- Glass Jar:Premium positioning vehicle for single-origin Italian and Spanish products in specialty retail channels. EFSA traceability documentation travels with jarred goods more easily than bulk formats, advantaging integrated processors.
- Tetra Pack:Aseptic brick format extends ambient shelf life for retail puree without refrigeration infrastructure. Swedish and Dutch retailers favor Tetra Pak for private-label concentrate lines targeting carbon footprint reduction.
- Metal Can:Standard industrial drum and retail can formats anchor food service and institutional procurement with lowest unit cost.
- Plastic Pouch:Stand-up pouches with dispensing caps gain traction in US household channels for squeeze convenience and reduced shipping weight.
Metal can holds volume leadership. Pouch formats are climbing the fastest as e-commerce fulfillment prioritizes damage resistance and dimensional weight savings.
End User:
Customer type dictates specification stringency, from industrial formula compliance to retail shelf aesthetics.
- Food Service:Chain restaurants and contract caterers specify 4.5kg aseptic bags for back-of-house sauce production with consistent viscosity batch-to-batch.
- Retail:Supermarkets and specialty grocers stock branded and private-label jarred paste with country-of-origin labeling for consumer pantry replenishment.
- Industrial:Multinational soup and sauce manufacturers procure concentrate under long-term offtake agreements with fixed escalators tied to tomato futures.
- Household:Direct-to-consumer subscription services deliver small-format pouches and tubes to home cooks seeking recipe-specific quantities.
Industrial procurement anchors volume commitment. Food service is gaining share fastest as prepared meal formats multiply across European and North American chains.
Distribution Channel:
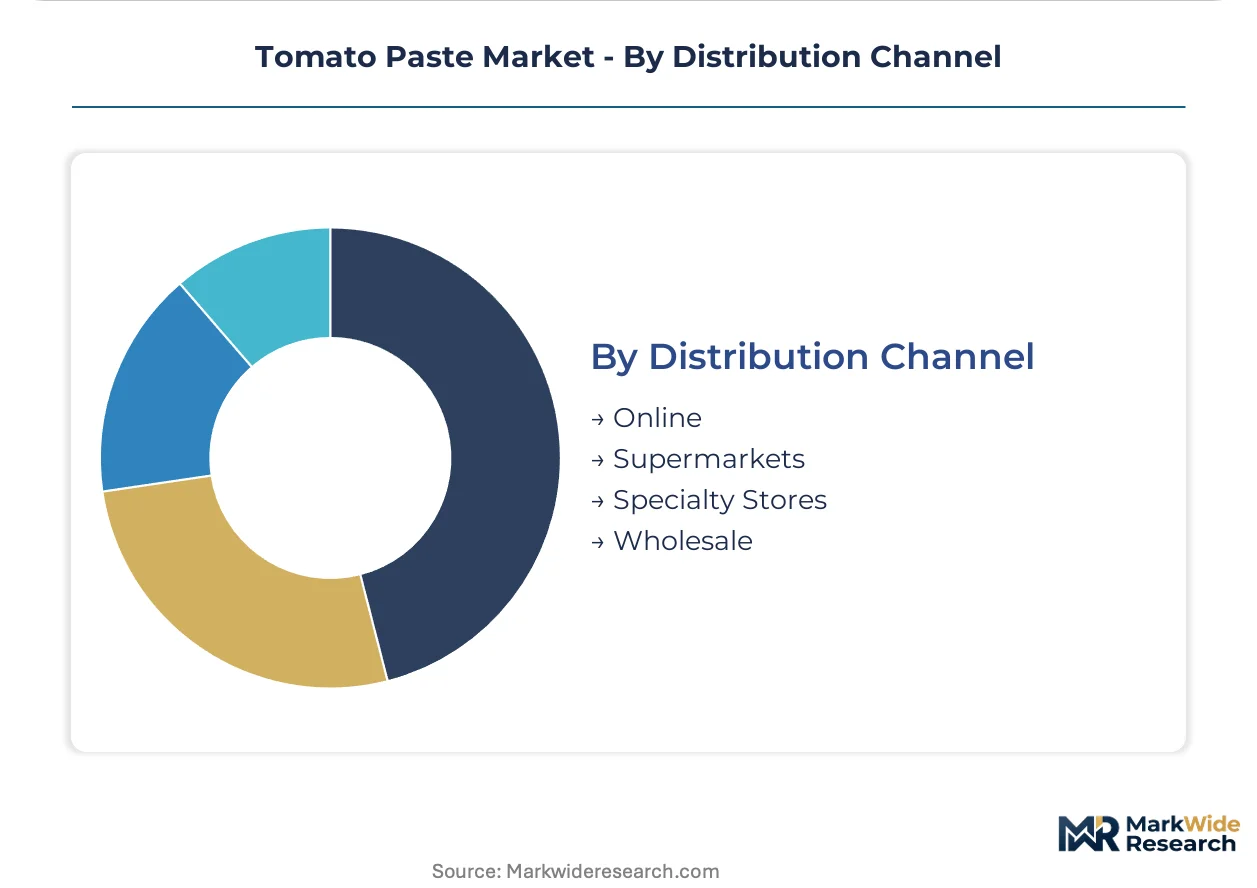
Volume scale and margin structure diverge across channel types, with wholesale consolidating procurement power and online fragmenting brand control.
- Online:Direct-to-consumer and B2B platforms enable specialty processors to bypass distributor markups, though cold-chain requirements limit paste concentrate viability.
- Supermarkets:Hypermarket and supermarket chains in France and Italy dominate retail jarred paste placement with slotting fee barriers for new entrants.
- Specialty Stores:Gourmet food retailers in London and Milan stock DOP-certified Italian paste at price multiples supporting small-batch processor margins.
- Wholesale:Food service distributors and industrial ingredient brokers concentrate buying power for bulk concentrate, compressing supplier margins through formula pricing.
Wholesale channels command procurement leverage. Online direct sales are expanding most quickly as specialty processors seek margin recovery outside distributor networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's Central Valley and China's Xinjiang basin now process over two-thirds of global tomato paste volume. Water allocation regimes in both corridors constrain expansion before demand adjustments materialize.
United States
Food service chains embed tomato-based sauces into prepared meal formats, pulling industrial concentrate demand upward. FDA food safety modernization rules govern processing standards and import access. The Central Valley processing corridor concentrates irrigation-efficient farming and scale advantages over Mediterranean suppliers.
China
State-controlled agricultural contracts lock in raw tomato supply at massive scale for export-oriented processing. The country's national food safety regulator enforces tightening traceability requirements under dual carbon goals. Xinjiang's triple-concentrate extraction capacity additions compress unit production costs below European break-even thresholds.
Italy
Specialty retailers stock glass-jar paste with DOP certification for home cooks seeking authentic provenance. EFSA pesticide residue limits and EU Green Deal traceability mandates advantage integrated processors over fragmented suppliers. The Po Valley agricultural cluster consolidates backward into controlled farming supply to meet documentation requirements.
Germany
Multinational soup and sauce manufacturers procure concentrate under long-term offtake agreements with fixed escalators. EU CSRD reporting requirements create first-mover advantage for processors with verified carbon footprints. The Rhine-Ruhr industrial corridor concentrates buyer power among three manufacturers controlling over half of import demand.
Spain
Mediterranean cooperatives face exclusion from EU retail procurement without contract farming control for integrated pest management documentation. EFSA's updated maximum residue levels for neonicotinoid pesticides force farm-level traceability systems. The Extremadura processing region struggles with legacy equipment retrofit costs that mid-scale operations cannot finance.
Tomato Paste Market Competitive Environment
State-backed agricultural conglomerates and vertically integrated private processors split the market into competing supply models. California-based operators sustain position through captive farming and industrial scale, while Chinese state enterprises leverage contract agriculture at basin-wide scope. Three strategic archetypes dominate: irrigation-dependent mega-processors, single-origin premium specialists, and multinational diversified food manufacturers. Competitive dynamics center on backward integration into farming supply and membrane filtration technology licensing.
Within the state-enterprise tier, COFCO Tunhe Tomato Co., Ltd. exemplifies contract agriculture lock-in at national scale. Among premium-positioned specialists, Mutti S.p.A. occupies a position anchored on Italian provenance certification. The Morning Star Company represents the vertically integrated California model with captive Central Valley farming. These three anchors illustrate how geographic concentration and supply structure shape competitive positioning across the concentrate value chain.
| Leading Market Players |
|---|
| Del Monte Foods, Inc. |
| Kagome Co., Ltd. |
| COFCO Tunhe Tomato Co., Ltd. |
| Mutti S.p.A. |
| CONESA Group |
| Xinjiang Chalkis Company Ltd. |
| Campbell Soup Company |
| The Morning Star Company |
| Conagra Brands, Inc. |
| Others |
Value Chain & Pricing Dynamics
Xinjiang's triple-concentrate capacity overhang is compressing spot pricing for industrial buyers while forcing California processors toward long-term contract structures. This utilization asymmetry between Chinese state-backed expansion and irrigation-constrained American supply reshapes how procurement managers balance cost certainty against origin flexibility.
Pricing Analysis
EU Green Deal traceability mandates dictate the pricing tier structure across the concentrate value chain. Three-tier pricing structure across premium, standard, and economy levels separates DOP-certified Italian glass-jar products from aseptic bag-in-box industrial concentrate and unbranded bulk drum shipments. Price differentiation rests on carbon accounting documentation depth and integrated pest management certification completeness. Pricing pressure stems from membrane filtration technology diffusion in Xinjiang, which is displacing thermal evaporation cost structures. Industrial soup and sauce manufacturers exhibit highest price sensitivity due to formula pricing tied to tomato futures, while specialty retailers absorbing provenance premiums show lowest elasticity.
Supply Chain Analysis
Fresh tomato feedstock availability hinges on irrigation allocation regimes in California's Central Valley and China's Yellow River basin. Geographic supply concentrates in the United States, China, and Italy, with Spain's Extremadura region losing share to documentation-compliant competitors. Raw material dependencies center on natural gas for evaporation energy, neonicotinoid-compliant pest management inputs, and aseptic packaging films. Supply chain risk manifests as single-source vulnerability in Xinjiang's basin-wide contract agriculture system, where state-controlled water rights override market adjustment signals. Distribution runs through food service distributors and industrial ingredient brokers for bulk concentrate, while specialty retail channels sustain direct processor relationships for certified origin formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Tomato paste demand is in an early-cycle expansion phase as prepared meal formats penetrate European and North American food service channels. Membrane filtration adoption and carbon accounting transparency requirements create window for positioning moves before technology standardization locks in cost leaders.
For Market Incumbents: Harden membrane filtration technology licensing positions in California and Xinjiang corridors before evaporator retrofit cycles complete. Deepen backward integration into controlled farming supply to satisfy EFSA pesticide residue documentation requirements. Defensive consolidation into irrigation-rights portfolios in the Central Valley offsets water allocation tightening threats from California agricultural regulators. For New Entrants and Emerging Players: Southeast Asian food service markets present underpenetrated white-space for aseptic pouch concentrate formats as regional chains adopt sauce-based prepared meals. Premium single-origin retail positioning in Nordic markets offers second entry vector given Swedish and Dutch retailer preference for carbon-labeled Tetra Pak formats. Go-to-market execution should anchor on verified irrigation footprint transparency to satisfy emerging EU CSRD reporting requirements from downstream buyers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across membrane filtration-enabled processing sub-segments as energy cost advantages compound. Long-term viability over the next decade favors processors with captive water rights and integrated farm data systems. Acquisition target archetype: mid-scale Mediterranean cooperatives with DOP certification assets but legacy equipment requiring retrofit financing. Signal to watch: California agricultural water rights auction prices as inflection indicator for raw material availability constraints.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Filtration Technology Licensing | Natural gas cost reduction from thermal evaporation displacement secures margin advantage against Xinjiang competitors. |
| Backward Integration into Controlled Farming | Integrated pest management documentation satisfies EFSA neonicotinoid residue limits for EU retail access. |
| Aseptic Pouch Format Expansion | Bag-in-box adoption by German and Dutch food service operators reduces waste handling and improves dispensing efficiency. |
| Carbon Accounting Certification Investment | Verified irrigation footprint documentation creates first-mover advantage under EU CSRD reporting requirements. |
| Irrigation Rights Portfolio Consolidation | Water allocation security in California Central Valley offsets regulatory tightening from state agricultural authorities. |
Study Parameters
A spread of perspectives from tomato processing plant managers, food service procurement directors, agricultural water rights attorneys, and membrane filtration equipment engineers converged on the working assumptions. Primary interviews with industrial buyers at German and Dutch soup manufacturers, Italian specialty retailers, and California farming cooperatives combined with secondary validation from FDA food safety modernization filings, EFSA pesticide residue databases, California agricultural water board allocation records, and EU Green Deal implementation directives. Bottom-up volume modeling from processing capacity utilization rates and top-down demand triangulation from food service chain menu expansion data were cross-referenced.
Demand-supply balance dynamics across the projection horizon anchored the analytical framework. Segmentation dimensions modeled include product concentration level, packaging format, end-user procurement specification, and regional regulatory cluster. CAGRs were derived from iterative reconciliation between capacity expansion pipelines and food service menu embedding rates. Industry-specific forecast inputs incorporated natural gas price volatility scenarios for evaporation energy costs and water rights allocation tightening schedules in California and China's Yellow River basin.
The forecast holds incumbent behavior within observed patterns; aggressive membrane filtration licensing moves by Chinese state enterprises or sudden irrigation rights reallocations by California regulators would shift outcomes. Cross-checking against customs trade data for tomato paste import volumes and food service distributor inventory turnover benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed Foods
Low Fat Puddings Market
Processed Foods
India Spray Dried Food Market
Processed Foods
Chocolate Filling Market
Processed Foods
Margarine Market
Processed Foods
United States Ice Cream Market
Processed Foods
South America Soup Market
Processed Foods
Noodles Market
Processed Foods
Africa Soup Market
Processed Foods
Processed Eucheuma Seaweed Market
Processed Foods
Artisanal Ice Cream Market
Processed Foods
India Ready to Mix Food Market
Processed Foods
Low Fat Soups Market
Processed Foods
Soup Market
Processed Foods
Processed Potatoes Market
Processed Foods
North America Ice Cream Market
Processed Foods
South America Processed Meat Market