
 Processed Meat Market | 2026-2036
Processed Meat Market Size, Share, and Industry Trends Forecast 2026-2036
Processed Meat Market Analysis
Asset-light processing contracts and third-party co-manufacturing arrangements are reshaping competitive entry barriers in the processed meat sector. JBS S.A. leverages its integrated cattle-to-case-ready supply chain to sustain margin control across volatile feedstock cycles. Tyson Foods Inc. anchors North American poultry-based processed meat capacity, while Hormel Foods Corporation differentiates through branded retail positioning in shelf-stable and refrigerated categories.
Processed meat encompasses animal-derived proteins subjected to curing, smoking, fermentation, thermal processing, or mechanical restructuring to extend shelf life, enhance flavor, or modify texture for commercial distribution. Sodium nitrite concentrations typically range from 50 to 200 parts per million depending on regulatory jurisdiction and product category, with pH reduction and water activity control serving as complementary preservation mechanisms. Sausages occupy the largest product type position due to cross-cultural versatility and industrial scalability, while vacuum-sealed packaging commands premium shelf-life extension relative to conventional shrink-wrapped alternatives. Ready-to-eat forms are gaining velocity in convenience-oriented retail channels, though frozen formats retain dominance in foodservice bulk procurement.
The USDA Food Safety and Inspection Service enforces pathogen reduction performance standards and labeling integrity requirements that directly shape product formulation and plant certification thresholds. EU REACH chemicals regulation and EFSA nitrosamine risk assessments constrain additive portfolios available to exporters serving European destinations, while Brazil's Ministry of Agriculture MAPA oversees equivalency agreements that determine market access for Marfrig and JBS shipments. Stakeholders must monitor evolving maximum residue limits for veterinary pharmaceuticals and alternative protein competitive displacement in younger consumer cohorts.
Market Dynamics
Clean-label curing technologies and sodium reduction mandates are compressing formulation flexibility while quick-service restaurant procurement consolidation concentrates volume with vertically integrated processors capable of certifying supply chain integrity across volatile feedstock cycles.
Growth Catalysts
- EFSA Sodium Reduction Guidelines:Manufacturers reformulating with potassium chloride and natural nitrite sources from celery powder are capturing shelf space in European retail channels seeking compliant product lines.
- Quick-Service Restaurant Expansion:Operational efficiency demands across foodservice chains are standardizing case-ready and portion-controlled processed meat specifications that favor large-scale contract manufacturers.
- Brazilian Export Infrastructure:MAPA equivalency agreements with multiple destination markets enable integrated processors to redirect volume efficiently in response to shifting tariff environments.
Market Restraints
- Feedstock Cost Volatility:Corn and soybean meal price swings directly compress processor margins, particularly for poultry-based categories where feed conversion ratios amplify input sensitivity.
- Nitrosamine Regulatory Friction:EFSA risk assessments constrain residual nitrite limits in cured products, forcing reformulation investments that extend product development timelines by 12-18 months.
- Alternative Protein Substitution:Plant-based and cultivated meat technologies are capturing trial among younger consumer cohorts in North American and Western European urban markets.
Strategic Opportunities
- Clean-Label Curing Convergence:Combining high-pressure processing with natural fermentation cultures enables sodium reduction without sacrificing shelf stability or color fixation performance.
- Indian Foodservice Penetration:Quick-service chains and institutional caterers represent underdeveloped channels for standardized processed meat formats adapted to halal certification and local taste profiles.
- USDA Organic Certification Tailwind:Premium-positioned products carrying organic and animal welfare certifications command price premiums in conventional retail and natural channel distribution.
Industry Challenges
- Clean-Label Formulation Expertise Gap:Shortage of food scientists proficient in natural preservation chemistry and fermentation management is constraining R&D throughput at mid-scale processors.
- Capex Intensity for Pathogen Control:USDA FSIS performance standards require continuous thermal processing equipment upgrades and environmental monitoring infrastructure that strains balance sheets.
- Multi-Jurisdiction Labeling Complexity:Divergent additive approval lists between FDA, EFSA, and national regulators force SKU proliferation and inventory segmentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Processed Meat Market |
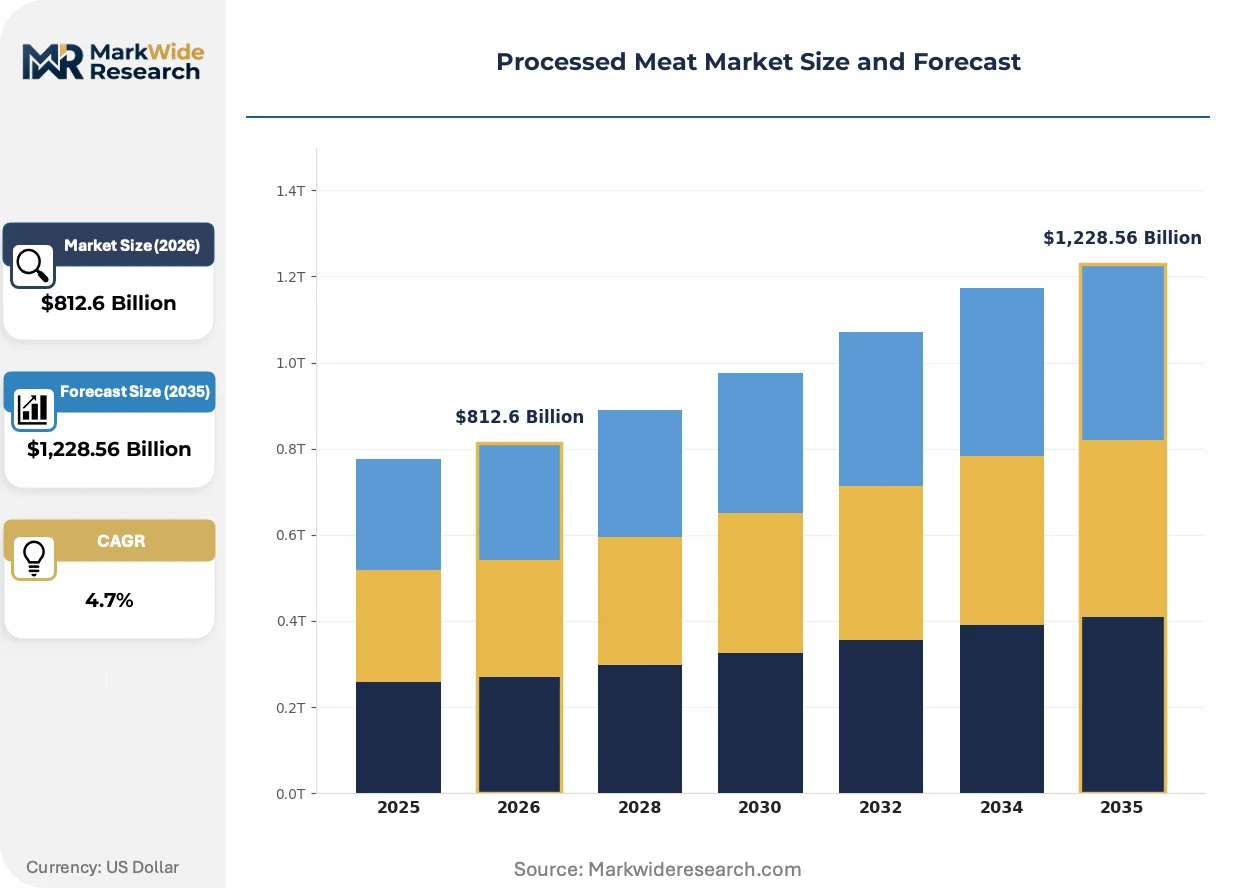
| Market Size in 2026 | $812.6 Billion |
| Market Size in 2035 | $1,228.56 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sausages, Bacon, Ham, Deli Meats Packaging Type: Vacuum Sealed, Canned, Shrink-Wrapped, Pre-Packaged Form: Ready-To-Eat, Cooked, Smoked, Frozen Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Meat Shops |
| Companies Covered | Tyson Foods Inc., JBS S.A., WH Group Limited, Marfrig Global Foods, Hormel Foods Corporation, Conagra Brands, Inc., Smithfield Foods, Inc., Cargill Incorporated, Danish Crown AS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Processed Meat Market Emerging Trajectories
Active technological substitution, regulatory compression of additive portfolios, and procurement consolidation across foodservice channels are restructuring competitive requirements and capital allocation priorities simultaneously.
High-pressure processing technology eliminates thermal degradation of proteins while achieving log reduction of Listeria monocytogenes without phosphate addition. Quick-service chains and prepared meal manufacturers are adopting HPP at accelerating rates for ready-to-eat deli categories. This non-thermal intervention is rendering obsolete traditional pasteurization-dependent production lines that required sodium phosphate for moisture retention and pathogen control.
EU REACH chemicals regulation and EFSA nitrosamine risk assessments are systematically delisting traditional curing aids and accelerating maximum limit reductions for residual nitrites. Exporters serving European destinations must maintain dual formulation capabilities or abandon those markets entirely. Small-to-mid scale processors without dedicated regulatory affairs functions face disproportionate compliance burdens relative to integrated multinationals.
Foodservice procurement is consolidating volume with processors capable of certifying full supply chain traceability and delivering case-ready products direct to restaurant back-of-house. Distributor intermediaries are losing share to direct manufacturer-restaurant relationships supported by vendor-managed inventory systems. This disintermediation is most visible in Brazil and the United States where large chain operators command sufficient volume to justify dedicated production lines.
Processed Meat Market Segmentation
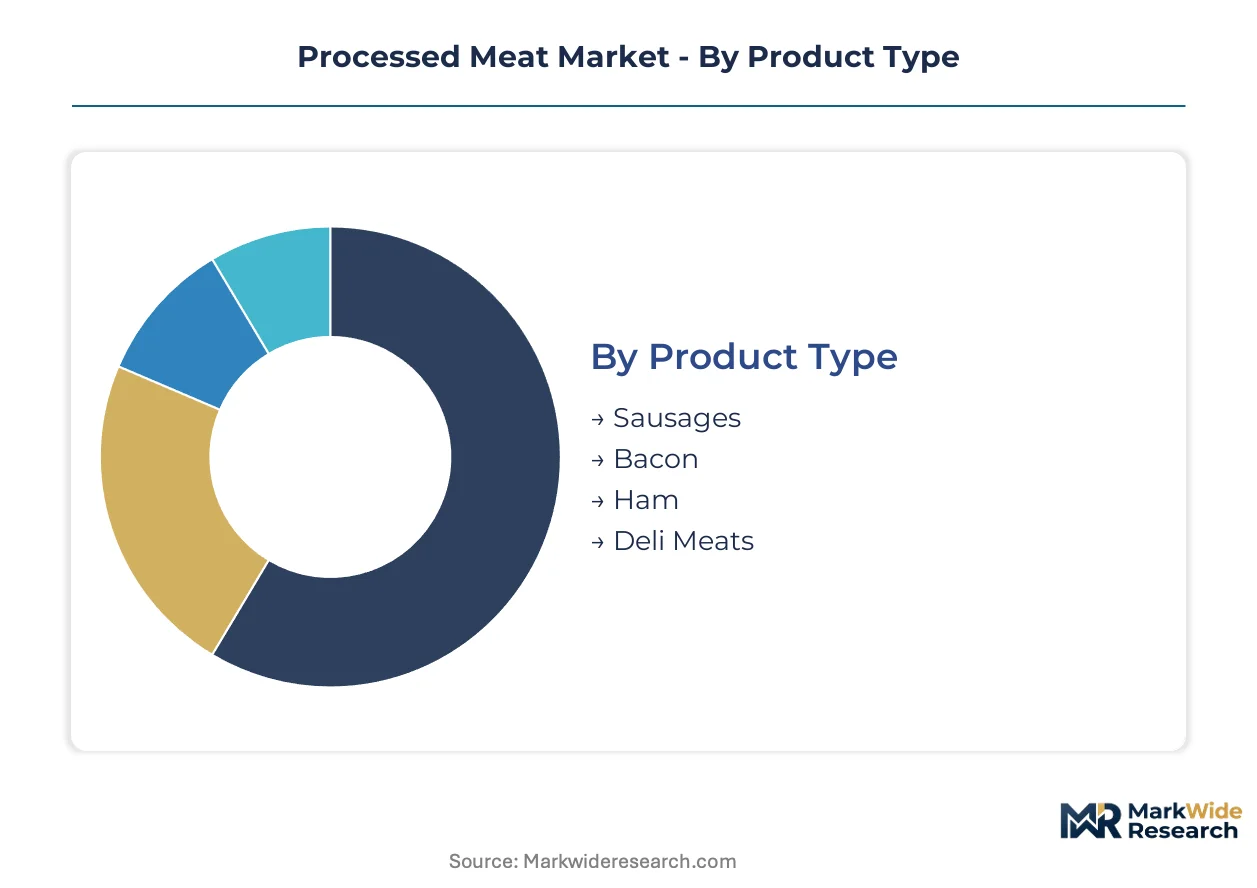
Processed meat segmentation reveals how formulation specifications, preservation chemistry, and channel economics fragment addressable demand across distinct technical and commercial profiles. Each dimension carries unique margin structures and regulatory exposure that reshape competitive positioning.
Product Type:
Use-case spectrum spans breakfast occasions, sandwich assembly, charcuterie platters, and protein ingredient applications with divergent frequency and price elasticity profiles.
- Sausages:Ground meat emulsions stuffed into natural or synthetic casings, spanning fresh, smoked, and dried variants. Demand concentrates in Brazilian and German retail channels where MAPA and BfR regulations respectively govern casing declarations and additive limits. Quick-service restaurant procurement of breakfast links and bratwurst formats drives volume consolidation with integrated processors.
- Bacon:Pork belly cured with sodium nitrite, thermal processed, and sliced for retail or foodservice distribution. US and UK retail channels dominate volume, with USDA FSIS pathogen standards and FSA salt reduction campaigns compressing formulation flexibility. Premium dry-cured variants command price premiums in specialty retail.
- Ham:Cured pork leg products ranging from fresh-cooked to dry-cured aged formats. Italian and Spanish export markets anchor premium positioning for DOP-protected aged hams.
- Deli Meats:Sliced ready-to-eat categories including turkey breast, roast beef, and mortadella. High-pressure processing adoption is accelerating in North American foodservice for Listeria control without phosphate addition.
The dominant share belongs to Sausages, while Bacon is closing the gap fastest.
Packaging Type:
Cost tier segmentation separates premium shelf-life extension from economy formats with divergent spoilage risk and distribution reach.
- Vacuum Sealed:Oxygen-depleted barrier films extending refrigerated shelf life. European retail channels mandate this format for EFSA-compliant reduced-sodium lines where oxidation sensitivity increases. Capital intensity for thermoforming equipment favors large-scale processors.
- Canned:Thermally sterilized products in metal containers for ambient distribution. Military procurement and emergency stockpiling in Japan and South Korea sustain demand despite retail decline.
- Shrink-Wrapped:Basic oxygen-permeable films for short-turnover fresh products. Brazilian supermarket private-label programs standardize this format for cost-sensitive consumers.
- Pre-Packaged:Modified atmosphere tray systems for case-ready retail. US supermarket delis require this format for direct-to-shelf distribution with barcode traceability.
Vacuum Sealed commands the largest volume share, though Pre-Packaged formats are expanding most quickly in foodservice direct delivery.
Form:
Processing intensity determines pathogen control requirements, cold chain dependency, and channel access permissions.
- Ready-To-Eat:Fully cooked products requiring no consumer thermal treatment. Listeria monocytogenes zero-tolerance standards under USDA FSIS and EFSA guidance force HPP or post-lethality treatment adoption.
- Cooked:Thermally processed but requiring refrigeration. Institutional foodservice in India and Saudi Arabia drives demand for halal-certified cooked poultry formats.
- Smoked:Traditional preservation via hardwood smoke or liquid smoke application. Polish and Czech retail channels maintain strong preference for cold-smoked pork varieties.
- Frozen:Blast-frozen products for extended distribution radius. Brazilian export infrastructure leverages frozen formats for MAPA-certified shipments to Middle Eastern markets.
Ready-To-Eat holds the dominant position, while Frozen formats are gaining share fastest in export-oriented production.
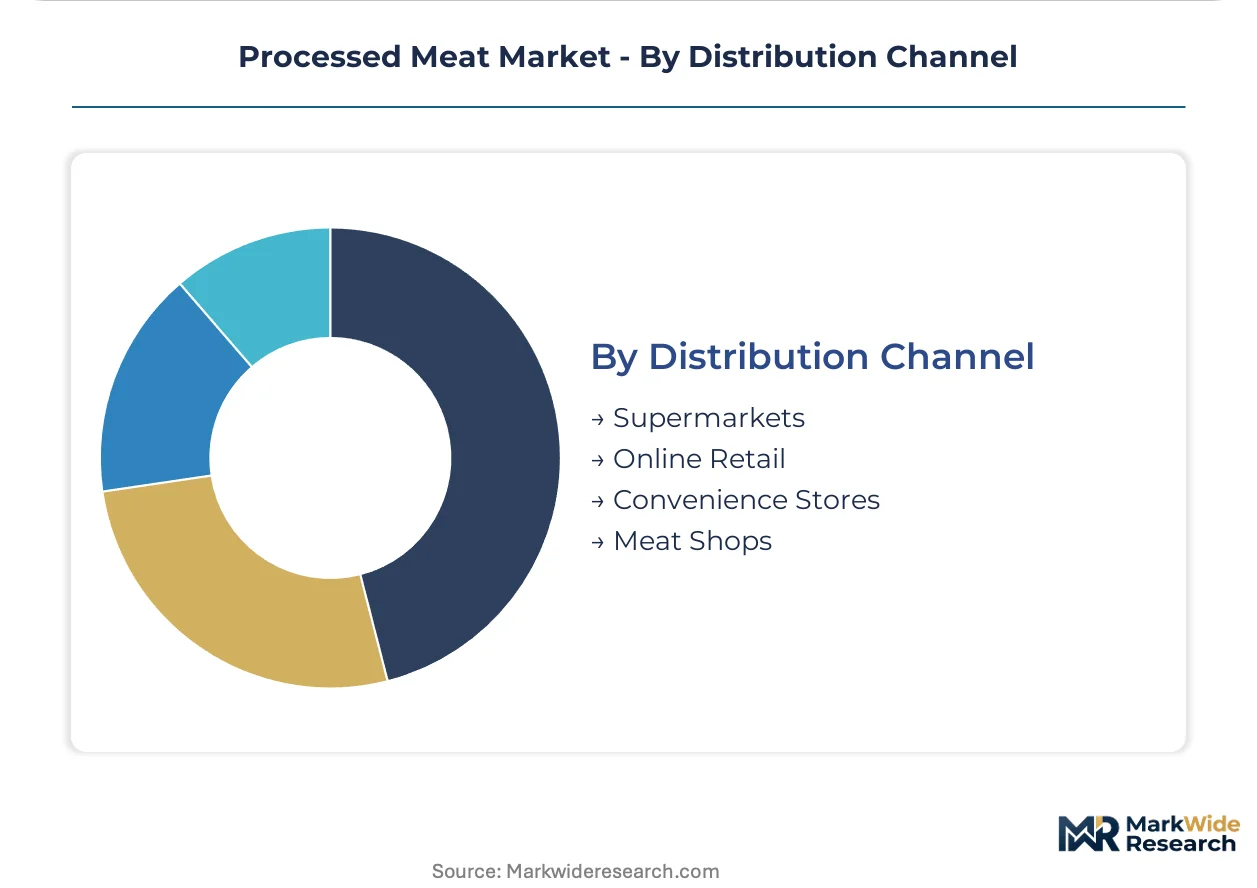
Distribution Channel:
Customer type fragmentation separates price-sensitive mass retail from convenience-premium and trust-dependent traditional trade.
- Supermarkets:Full-assortment retail with private-label and branded shelf space allocation. EFSA sodium reduction guidelines and clean-label demands concentrate reformulation investment for this channel.
- Online Retail:Direct-to-consumer and platform-mediated sales with cold chain logistics requirements. South Korean and Chinese urban markets show strongest penetration for premium imported cured products.
- Convenience Stores:Grab-and-go single-serve formats for immediate consumption. Japanese konbini chains standardize onigiri-compatible sliced ham and sausage portions.
- Meat Shops:Traditional butcher counters with custom slicing and local sourcing claims. German and Austrian independent fleischerei maintain loyalty through regional sausage specialties.
Supermarkets retain the largest volume share, though Online Retail is climbing the fastest in premium segment development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics are reconfiguring production footprints as processors seek tariff-efficient routing and MAPA equivalency access. Net exporters dominate capacity expansion while import-dependent markets drive formulation adaptation for local taste and regulatory compliance.
Brazil
Quick-service restaurant chains and Middle Eastern importers drive processed meat procurement from integrated processors. MAPA equivalency agreements with Saudi Arabia and UAE enable seamless halal-certified shipments. São Paulo state anchors JBS S.A. and Marfrig Global Foods production complexes serving both domestic retail and export markets.
United States
Foodservice consolidation and USDA Organic certification premiums reshape procurement toward large-scale contract manufacturers. USDA FSIS pathogen reduction standards enforce continuous thermal processing upgrades. Arkansas and Iowa host Tyson Foods Inc. poultry processing clusters optimized for case-ready distribution to national quick-service chains.
Germany
Retail private-label programs and discount channel expansion concentrate volume with processors capable of EFSA-compliant reduced-sodium formulations. BfR additive limits and REACH chemical regulations constrain curing aid portfolios. Bavaria maintains traditional sausage production clusters while North Rhine-Westphalia hosts industrial-scale deli meat facilities.
China
Urban convenience retail and cold-chain infrastructure expansion accelerate ready-to-eat format adoption. SAMR food safety standards and GB labeling requirements shape import compliance for foreign processors. Shandong Province and Jiangsu Province concentrate domestic pork processing capacity serving Yangtze River Delta consumption centers.
India
Quick-service penetration and institutional catering create demand for standardized halal-certified poultry formats. FSSAI labeling and safety standards govern additive declarations and shelf-life claims. Maharashtra and Telangana host emerging processing zones supplying Delhi-NCR and Bangalore foodservice channels.
Processed Meat Market Vendor Landscape
On the supply side, the industry is consolidating around vertically integrated processors capable of certifying supply chain integrity across volatile feedstock cycles. Three archetypes dominate: integrated livestock-to-retail conglomerates, branded portfolio specialists, and private-label contract manufacturers. Competitive moves center on backward integration into captive livestock supply and direct foodservice procurement relationships that disintermediate traditional distributors.
Among Brazil-based integrated processors, JBS S.A. and Marfrig Global Foods exemplify the livestock-to-retail archetype with MAPA-certified export infrastructure. Tyson Foods Inc. occupies a position within the North American poultry processing tier, while Hormel Foods Corporation represents the branded portfolio specialist archetype with shelf-stable and refrigerated category positioning.
| Leading Market Players |
|---|
| Tyson Foods Inc. |
| JBS S.A. |
| WH Group Limited |
| Marfrig Global Foods |
| Hormel Foods Corporation |
| Conagra Brands, Inc. |
| Smithfield Foods, Inc. |
| Cargill Incorporated |
| Danish Crown AS |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Brazilian beef processing capacity during the first half of the analysis window compressed processor margins and triggered aggressive pricing in export markets. JBS S.A. and Marfrig Global Foods responded by idling select production lines and redirecting volume toward Middle Eastern halal-certified channels where MAPA equivalency agreements sustain premium realizations.
Pricing Analysis
Foodservice procurement directors anchor contract-based long-term offtake structures with volume-scaled tiering. Pricing stratifies across premium clean-label tiers carrying USDA Organic or animal welfare certifications, standard EFSA-compliant formulations, and economy private-label programs for discount retail. Cost compression in economy tiers is intensifying because corn and soybean meal feedstock volatility transmits directly into processor margins. Quick-service restaurant chains demonstrate highest price sensitivity due to standardized menu pricing constraints, while specialty retail channels absorb premiums for provenance-verified products.
Supply Chain Analysis
Corn and soybean meal sourcing draws from the United States, Brazil, and Argentina as the dominant feedstock inputs for livestock finishing operations. Live cattle and hog procurement rests on long-term supplier relationships with integrated ranching operations in Mato Grosso and Iowa. Single-source vulnerability concentrates in Brazilian beef processing where JBS S.A. and Marfrig Global Foods control disproportionate export capacity. Distribution runs through direct manufacturer-to-restaurant relationships that disintermediate traditional foodservice distributors, with vendor-managed inventory systems supporting case-ready delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Clean-label curing technology adoption sits at early-cycle expansion penetration with EFSA sodium reduction guidelines accelerating reformulation investment across European retail channels.
For Market Incumbents: Harden supply chain integrity certification through backward integration into captive livestock supply and direct foodservice procurement relationships. Defend margin position against alternative protein substitution by accelerating high-pressure processing deployment for Listeria control without phosphate addition. Prioritize R&D investment in natural fermentation cultures that enable sodium reduction without sacrificing shelf stability. For New Entrants and Emerging Players: Mid-scale processors in India and Southeast Asia represent the most penetrable entry point for standardized halal-certified poultry formats serving quick-service expansion. Local taste profile adaptation combined with FSSAI compliance capability offers differentiation against integrated multinationals with limited regional customization agility. Direct institutional catering relationships bypass retail slotting fee barriers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among private-label contract manufacturers with multi-year quick-service chain agreements and vendor-managed inventory systems. Long-term viability across the analysis window favors processors with MAPA-certified export infrastructure and dual-formulation capabilities for EFSA-compliant markets. Monitor EFSA nitrosamine risk assessment timelines as inflection indicators for reformulation capex cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Livestock Supply | JBS S.A. and Marfrig Global Foods sustain margin control across volatile feedstock cycles through owned ranching operations. |
| High-Pressure Processing Technology Deployment | Non-thermal Listeria intervention eliminates phosphate addition requirements while achieving USDA FSIS compliance. |
| Clean-Label Curing Reformulation | Natural nitrite sources from celery powder capture European retail shelf space under EFSA sodium reduction guidelines. |
| Direct Foodservice Procurement Relationships | Vendor-managed inventory systems disintermediate traditional distributors and secure dedicated production line allocation. |
| MAPA Equivalency Certification Expansion | Halal-certified export infrastructure enables seamless volume redirection between Middle Eastern and Asian destination markets. |
Methodological Framework
A spread of perspectives from plant operations managers, foodservice procurement directors, regulatory affairs specialists at exporters, and retail category buyers converged on the working assumptions. Primary interviews combined with secondary validation from USDA FSIS enforcement data, EFSA scientific opinions, MAPA equivalency agreement documentation, and trade flow customs records. Bottom-up capacity utilization estimates and top-down consumption surveys underwent triangulation for convergence.
Demand-supply balance modeling across product type, preservation chemistry, packaging format, and distribution channel dimensions structured the analytical framework. CAGRs derived from segment-level volume trajectories and price realization trends across the projection horizon. Feedstock cost indices, regulatory timeline assumptions, and alternative protein penetration curves served as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in corn and soybean meal price volatility or EFSA additive limit revisions would shift the trajectory. Forecasts reflect documented assumptions about clean-label adoption rates and quick-service chain expansion timelines. Cross-checking against USDA livestock inventory reports and EFSA scientific committee outputs is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed Foods
Instant Cooking Food Market
Processed Foods
Low Fat Puddings Market
Processed Foods
Processed Beef Market
Processed Foods
Low Fat Chicken Soup Market
Processed Foods
Fat Free Food Market
Processed Foods
North America Soup Market
Processed Foods
United States Fresh Noodles Market
Processed Foods
United States Processed Meat Market
Processed Foods
Pates Market
Processed Foods
Low Fat Pasta Market
Processed Foods
Low Moisture Food Market
Processed Foods
Low-Fat Desserts to Buy Market
Processed Foods
High-Pressure Processing (HPP) Foods Market
Processed Foods
Global Potato Flake Market
Processed Foods
Asia-Pacific Food Spread Market
Processed Foods
Fat Free Soup Market