
 Methyl Diethanolamine Market | 2026-2036
Methyl Diethanolamine Market Size, Share, and Industry Trends Forecast 2026-2036
Methyl Diethanolamine Market Intelligence
The pool of specialty amine chemists with gas-treating expertise is bifurcating the competitive landscape between integrated majors and regional suppliers. INEOS leverages captive ethylene oxide supply to sustain margin control across European MDEA production. Huntsman anchors its position through deep technical service relationships with refinery operators seeking selective H2S removal. BASF competes by operating multi-purpose alkoxylation trains that flex between MDEA and higher-margin surfactant alcohols.
Methyl diethanolamine is a tertiary amine with the molecular formula C5H13NO2, produced via ethoxylation of methylamine with ethylene oxide under controlled temperature and pressure, functioning primarily as a selective absorbent for hydrogen sulfide and carbon dioxide in acid gas treating systems. Industrial grade MDEA dominates volume flows into refinery and natural gas processing applications where bulk sulfur recovery dictates procurement economics. Pharmaceutical grade commands premium positioning due to excipient purity requirements and batch-level documentation demanded by FDA and EMA filings. The emulsifiers application segment tracks fastest growth as formulators replace conventional surfactants with amine-derived alternatives in agricultural adjuvants and industrial coatings.
EPA New Source Performance Standards for petroleum refineries and EMA excipient certification requirements shape product specifications and market access corridors for MDEA manufacturers serving North American and European buyers. China's MEE enforces dual carbon goals that accelerate MDEA demand for post-combustion carbon capture retrofits at coal-fired power stations and steel complexes. Stakeholders must monitor how REACH authorization timelines and evolving ISO 14001 carbon accounting protocols redirect procurement criteria toward low-carbon MDEA production routes before committing to long-term supply agreements.
Market Dynamics
The Methyl Diethanolamine Market is bifurcating around captive ethylene oxide supply and specialty amine formulation expertise, with integrated producers pulling margin from merchant buyers while gas-treating chemist scarcity constrains regional supplier expansion.
Growth Catalysts
- REACH authorization timelines:EU Green Deal carbon-neutrality mandates tighten product purity standards across Germany, France, and the Netherlands, forcing refinery operators toward certified MDEA suppliers.
- Coal-to-chemical complexes:China's acid gas removal demand anchors volume consumption as steel and power sectors retrofit carbon capture systems.
- Ethoxylation process optimization:Controlled temperature-pressure reactor designs improve methylamine conversion yields, lowering unit production costs for selective H2S absorbents.
Market Restraints
- Ethylene oxide feedstock volatility:Cracker outages and derivative demand spikes from surfactant and glycol producers transmit directly to MDEA cost structures.
- Specialty amine chemist scarcity:Gas-treating expertise concentration at integrated majors limits formulation innovation at regional alkoxylation houses.
- MEA and DEA substitution:Primary and secondary amine alternatives retain cost advantage in non-selective bulk acid gas removal applications.
Strategic Opportunities
- Post-combustion carbon capture retrofits:China's MEE dual carbon goals accelerate MDEA demand at coal-fired power stations and integrated steel complexes.
- Agricultural adjuvant emulsifiers:Formulators replace conventional surfactants with amine-derived alternatives in crop protection formulations.
- Pharmaceutical excipient certification:FDA and EMA batch-level documentation requirements create premium positioning for GMP-grade MDEA producers.
Industry Challenges
- Multi-purpose alkoxylation train scheduling:Surfactant alcohol and MDEA demand cycles conflict, forcing producers to sacrifice margin in one product line.
- ISO 14001 carbon accounting integration:Procurement criteria now require Scope 3 emissions documentation that most merchant suppliers cannot provide.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Methyl Diethanolamine Market |
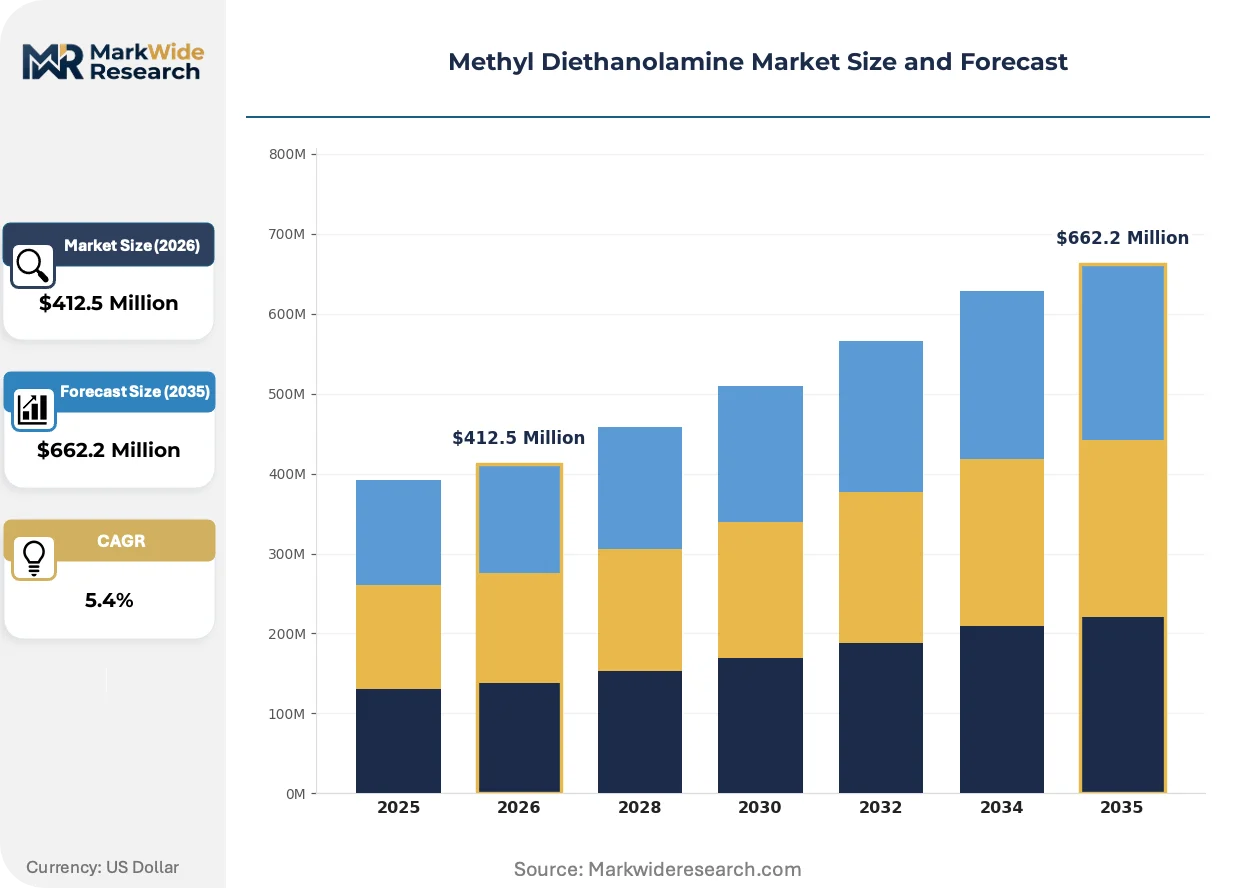
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $662.2 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, Cosmetic Grade, Pharmaceutical Grade, Food Grade Application: Surfactants, Solvents, Additives, Emulsifiers End User: Cosmetics, Pharmaceuticals, Agriculture, Coatings Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesalers |
| Companies Covered | INEOS, Sintez OKA, DowDuPont, Taihu New Materials, Maoming Yunlong, Eastman Chemical Company, Huntsman, Amines & Plasticizers, BASF, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Methyl Diethanolamine Market Strategic Shifts & Innovations
Formulation science and regulatory carbon accounting are reshaping how MDEA producers compete, with technical service relationships and low-carbon production credentials displacing price-only procurement.
Blended amine formulations combining MDEA with activators like piperazine are fragmenting the traditional selective absorption market. Refinery operators seeking higher CO2 slip rates in H2S-rich gas streams are adopting these hybrids faster than standard MDEA retrofits permit. The technology is fragmenting equipment supplier relationships as engineering firms develop proprietary activator packages tied to specific hardware configurations.
EPA New Source Performance Standards for petroleum refineries are tightening sulfur recovery benchmarks across US Gulf Coast processing complexes. The rule forces operators to evaluate amine system upgrades during turnaround cycles rather than deferring capital. California and Texas refineries face the steepest compliance curves, accelerating technical service engagements with formulation houses capable of modeling specific crude slate impacts.
Refinery procurement departments now unbundle after-sales technical service from bulk chemical supply contracts. Large integrated operators retain in-house amine specialists while mid-size processors purchase hourly consulting from MDEA suppliers. This unbundling is most pronounced in the US Midwest and Rotterdam-Antwerp refining corridors where margin compression has eliminated internal chemical engineering benches.
Methyl Diethanolamine Market Segmentation
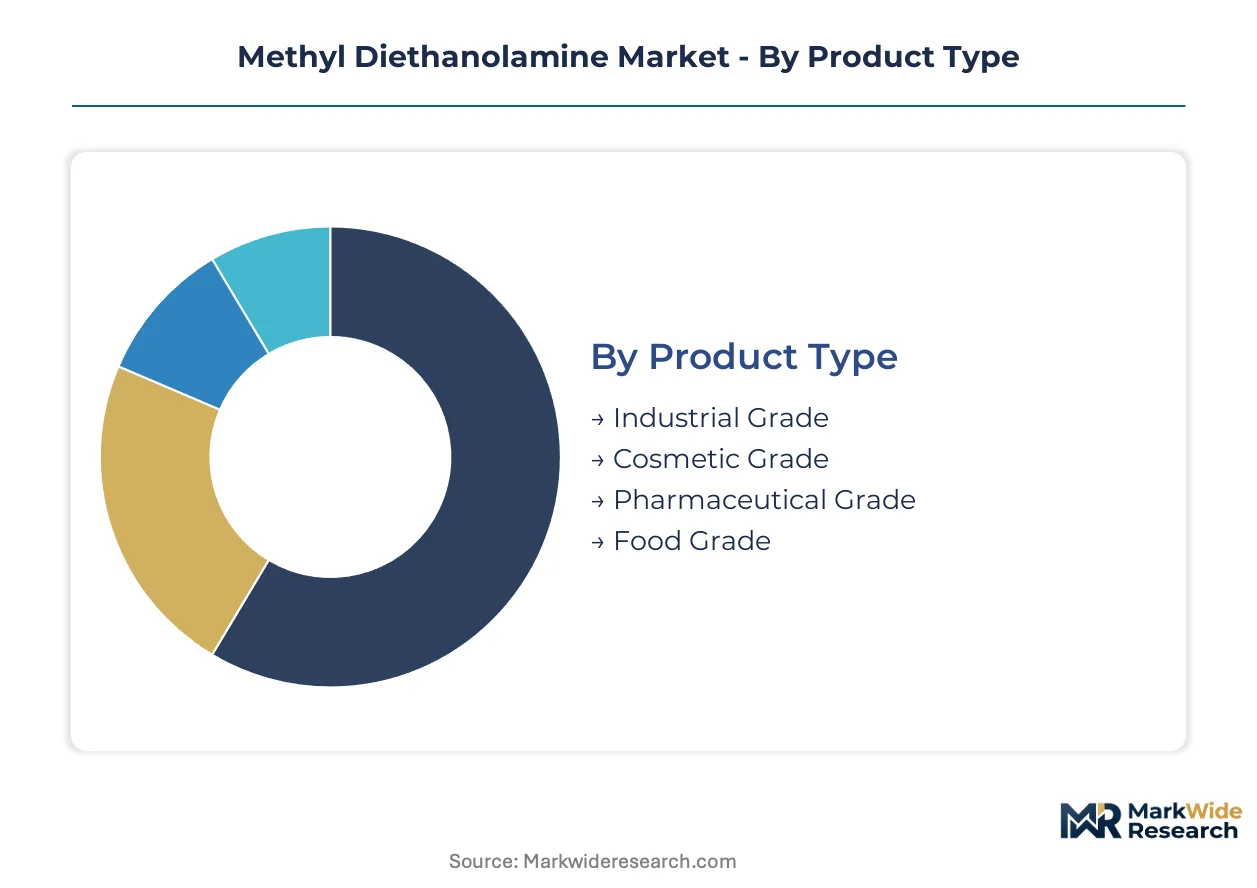
MDEA procurement patterns diverge sharply across purity grades and end-use specifications, with industrial buyers prioritizing bulk sulfur recovery economics while pharmaceutical and cosmetic formulators demand batch-level documentation that fragments supplier relationships.
Product Type:
Industrial grade MDEA flows predominantly to domestic refineries and gas processors, while pharmaceutical and food grades track export-led demand into regulated markets with stringent certification requirements.
- Industrial Grade:Produced via standard ethoxylation of methylamine with ethylene oxide, this specification carries 95-98% purity suitable for acid gas treating systems. Refinery operators in Texas, Louisiana, and Rotterdam-Antwerp clusters consume volumes tied to sulfur recovery mandates under EPA and EU Green Deal frameworks.
- Pharmaceutical Grade:GMP-compliant production with impurity profiles below 0.1% and full batch documentation enables excipient qualification for FDA and EMA filings. European and North American pharmaceutical manufacturers source this grade through qualified supplier audits that extend lead times.
- Cosmetic Grade:Moderate purity tier serving personal care formulators with color stability and low-odor specifications.
- Food Grade:Limited volume segment for food processing applications requiring migration testing and compliance with national food safety regulators.
Industrial grade holds the largest share; momentum sits with pharmaceutical grade as excipient documentation requirements tighten.
Application:
Cost tier differentiation separates commodity surfactant applications from premium emulsifier formulations where amine-derived alternatives command price premiums over conventional chemistries.
- Emulsifiers:Agricultural adjuvant formulators in Brazil, Australia, and the US Midwest replace conventional surfactants with MDEA-derived emulsifiers to improve pesticide spreading and retention. Crop protection companies specify these chemistries for compatibility with biological active ingredients.
- Surfactants:Industrial cleaning and oilfield chemical applications leverage MDEA as a tertiary amine building block for quaternary ammonium compounds. Demand concentrates in Texas and Alberta oilfield service corridors where produced water treatment drives formulation innovation.
- Solvents:Niche applications in coatings and electronics cleaning where amine basicity enables selective dissolution.
- Additives:Corrosion inhibition and pH buffering functions across metalworking fluids and water treatment systems.
Surfactants dominate current volume; emulsifiers are expanding most quickly as agricultural biologicals gain share.
End User:
Customer type fragmentation creates divergent procurement patterns, with coatings and agriculture buyers negotiating on specification flexibility while cosmetics and pharmaceuticals enforce rigid supplier qualification protocols.
- Coatings:Industrial and decorative paint manufacturers incorporate MDEA as a neutralizing amine for waterborne resin systems. Automotive OEM specifications in Germany, Japan, and Michigan drive consistency requirements that favor qualified regional suppliers.
- Agriculture:Formulators of herbicide and fungicide adjuvants specify MDEA emulsifiers for compatibility with glyphosate and dicamba systems. Brazilian and US Midwest distributors manage seasonal demand spikes through forward contracting.
- Cosmetics:Personal care brands in France, South Korea, and California specify low-odor, low-color grades for hair care and skin conditioning applications.
- Pharmaceuticals:Oral and topical drug manufacturers qualify MDEA as a pH-adjusting excipient with full ICH Q3D elemental impurity documentation.
Coatings represents the largest installed base; agriculture shows the steepest expansion trajectory as biological crop protection scales.
Distribution Channel:
Supply concentration among integrated producers favors direct sales for volume accounts, while distributor networks capture fragmented regional demand from mid-size formulators lacking technical specification expertise.
- Direct Sales:Refinery operators and multinational coatings manufacturers negotiate frame contracts with INEOS, Huntsman, and BASF for scheduled railcar or tanker deliveries. Technical service bundling distinguishes these relationships from transactional supply.
- Distributors:Regional chemical distributors in the US Midwest, Northern Italy, and China's Yangtze River Delta warehouse MDEA for cosmetics and agriculture formulators requiring smaller lot sizes and just-in-time delivery.
- Online Retail:Laboratory and pilot-scale quantities for R&D sampling and small-batch pharmaceutical development.
- Wholesalers:Bulk intermediaries serving secondary markets with limited direct producer relationships.
Direct sales commands the greatest volume; distributors are gaining share fastest among mid-size formulators seeking technical support.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese producers command pricing leverage through captive ethylene oxide supply, while European refiners absorb premium MDEA costs under REACH-mandated purity standards. This asymmetry concentrates margin capture in integrated chemical complexes and fragments procurement power across regional gas processors.
China
Coal-to-chemical complexes in Ningxia and Inner Mongolia anchor MDEA consumption for acid gas removal at integrated gasification facilities. The Ministry of Ecology and Environment enforces dual carbon goals that accelerate post-combustion carbon capture retrofits at coal-fired power stations. Yangtze River Delta chemical parks near Shanghai concentrate domestic MDEA production capacity serving steel and refining clusters.
Germany
Refinery operators in North Rhine-Westphalia and Bavaria source certified MDEA under EU Green Deal carbon-neutrality mandates tightening product purity standards. ECHA REACH authorization timelines force procurement departments toward documented low-carbon production routes. The BASF Ludwigshafen complex operates multi-purpose alkoxylation trains flexing between MDEA and higher-margin surfactant outputs.
United States
Texas and Louisiana Gulf Coast refineries consume industrial grade MDEA volumes tied to EPA New Source Performance Standards for sulfur recovery. California processors face steepest compliance curves, accelerating technical service engagements with formulation suppliers. Houston chemical corridors concentrate merchant MDEA distribution serving mid-size gas processors lacking in-house amine expertise.
Netherlands
Rotterdam-Antwerp refining corridors unbundle after-sales technical service from bulk chemical supply contracts under margin compression pressures. The Dutch national implementation of EU Green Deal frameworks redirects procurement criteria toward Scope 3 emissions documentation. Integrated producers leverage captive ethylene oxide supply from Rotterdam crackers to sustain margin control against merchant buyers.
Saudi Arabia
Natural gas processing complexes in the Eastern Province deploy MDEA for selective H2S removal at scale. The Saudi national industrial development program prioritizes downstream chemical integration, including amine derivative capacity. Jubail Industrial City hosts formulation operations serving regional refinery and petrochemical acid gas treating demand.
Methyl Diethanolamine Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes, with integrated petrochemical majors controlling feedstock economics while specialty amine houses capture premium through formulation expertise. The vendor base concentrates around three structural tiers: integrated producers with captive ethylene oxide, regional alkoxylation specialists, and pharmaceutical-grade qualification holders. Dominant competitive moves include backward integration into ethylene oxide supply and geographic expansion through technical service partnerships with refinery operators.
Among integrated chemical majors, INEOS and BASF exemplify the captive-feedstock archetype, leveraging in-house ethylene oxide production to sustain margin control across European MDEA supply. Huntsman occupies a position emphasizing deep technical service relationships with refinery operators seeking selective H2S removal modeling. These three anchors demonstrate how competitive positioning fragments between cost-driven bulk supply and specification-driven formulation partnerships.
| Leading Market Players |
|---|
| INEOS |
| Sintez OKA |
| DowDuPont |
| Taihu New Materials |
| Maoming Yunlong |
| Eastman Chemical Company |
| Huntsman |
| Amines & Plasticizers |
| BASF |
| Others |
Cost & Logistics Intelligence
Captive ethylene oxide production at integrated complexes in Germany, China, and the Netherlands anchors cost floors that merchant alkoxylation houses cannot match, compressing margins for regional suppliers serving refinery and gas processing buyers under EPA and EU Green Deal sulfur recovery mandates.
Pricing Analysis
The customization-premium spread between standard industrial grade and pharmaceutical-grade MDEA runs wide due to GMP compliance costs and batch documentation burdens. Three-tier pricing structure across pharmaceutical, industrial, and cosmetic grades reflects certification level and volume scale as primary differentiation drivers. Cost compression in industrial grade is intensifying because MEA and DEA substitutes retain cost advantage in non-selective bulk acid gas removal. Refinery operators in Texas and Rotterdam-Antwerp corridors show highest price sensitivity, while pharmaceutical manufacturers in North America and Europe accept premium positioning for excipient qualification.
Supply Chain Analysis
China and Germany anchor MDEA production through integrated ethylene oxide crackers at Ningxia coal-to-chemical complexes and BASF's Ludwigshafen multi-purpose alkoxylation trains. Feedstock draws from methylamine suppliers and ethylene oxide derivatives, with formulation expertise concentrated at Huntsman and INEOS technical service operations. Single-source vulnerability runs through specialty amine chemist scarcity constraining regional supplier expansion. Distribution runs through direct railcar contracts for refinery volume accounts and regional distributors serving mid-size agriculture and cosmetics formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The MDEA market tracks a cyclical recovery anchored to refinery turnaround cycles and carbon capture retrofit waves under China's MEE dual carbon enforcement.
For Market Incumbents: Compound technical service relationships with refinery operators by embedding gas-treating chemists at client sites during EPA-mandated sulfur recovery upgrades. Defend against MEA-DEA substitution threats by licensing proprietary activator formulations that standard MDEA retrofits cannot replicate. Prioritize backward integration into ethylene oxide supply where cracker economics permit margin control. For New Entrants and Emerging Players: Lead with agricultural adjuvant emulsifier qualification in Brazil and the US Midwest, where biological crop protection formulators seek amine-derived alternatives with shorter supplier audit timelines than pharmaceutical grades. Target cosmetics-grade positioning in South Korea and France, where low-odor specifications command premium positioning without GMP facility burdens. Pursue toll manufacturing partnerships with established alkoxylation houses to bypass captive feedstock disadvantages. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among MDEA suppliers with multi-year technical service contracts tied to refinery turnaround schedules. Long-term viability hinges on exposure to carbon capture retrofit cycles rather than commodity surfactant demand. Monitor blended amine formulation adoption rates as the inflection signal separating premium formulation houses from bulk chemical merchants.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethylene Oxide | Captive feedstock supply at INEOS and BASF complexes insulates margin from cracker outage volatility. |
| GMP-Grade Certification Investment | FDA and EMA batch documentation capabilities unlock pharmaceutical excipient premiums above industrial grades. |
| Technical Service Embedding | On-site gas-treating chemist placement at US Gulf Coast refineries differentiates from transactional bulk supply. |
| Blended Amine Formulation Development | Piperazine-activated MDEA hybrids address higher CO2 slip requirements in H2S-rich gas streams. |
| Carbon Capture Retrofit Partnerships | Long-term offtake agreements with Chinese steel and power complexes under MEE dual carbon goals anchor volume. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with refinery process engineers, gas-treatment procurement leads, specialty amine R&D directors, and agricultural adjuvant formulators. Secondary validation drew from EPA New Source Performance Standards filings, ECHA REACH authorization timelines, China MEE policy releases, and customs trade data tracking ethylene oxide derivative flows. Bottom-up volume estimates from end-use consumption patterns were triangulated against top-down capacity assessments at major alkoxylation complexes.
Across the analysis window, the forecasting framework modeled MDEA demand through grade tier, end-use industry, and regional regulatory cluster dimensions. CAGRs were derived from segment-level volume build-ups incorporating ethoxylation capacity utilization rates, refinery turnaround schedules, and carbon capture project pipelines. Key inputs included coal-to-chemical complex commissioning timelines in Ningxia and Inner Mongolia, plus EU Green Deal carbon-neutrality compliance curves affecting German and Dutch refinery procurement.
The analysis sits within stated boundaries; outcomes outside sustained enforcement of EPA sulfur recovery mandates or MEE dual carbon timelines would require recalibration. Forecasts reflect assumptions regarding specialty amine chemist availability and ethylene oxide feedstock cost trajectories. Recalibration cycles align with material shifts in refinery regulatory compliance deadlines and carbon capture subsidy frameworks.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
C2 Chlorinated Solvents Market
Solvents
Natural Distillates Market
Solvents
Acetone Market
Solvents
3-Butylene Glycol Market
Solvents
2-(4-Aminopentyl(Ethyl)Amino)Ethanol Market
Solvents
Phenylacetonitrile Market
Solvents
Methyl Formate Market
Solvents
Reactive Diluents Market
Solvents
Mesitylene Market
Solvents
Global Solvent Dyes Market
Solvents
Butyl Glycol Market
Solvents
Saudi Arabia Methanol Market
Solvents
Asia-Pacific Ethane Market
Solvents
Ethyl Pyruvate Market
Solvents
N-Pentyl Chloride Market
Solvents
Aprotic Solvents Market