
 Potassium Hydroxide Market | 2026-2036
Potassium Hydroxide Market Size, Share, and Industry Trends Forecast 2026-2036
Potassium Hydroxide Market Analysis
Specialty chemical buyers is rotating toward battery-grade specifications faster than traditional industrial purchasers. Solvay leverages its integrated chlor-alkali platform to sustain European supply reliability. INEOS KOH anchors significant production capacity across Northern Europe. Olin Corporation competes through geographic diversification of its caustic potash operations.
Potassium hydroxide is an inorganic compound with formula KOH, typically produced via electrolysis of potassium chloride brine in membrane or mercury cell processes, yielding a strongly alkaline solid or solution used for pH adjustment, saponification, and chemical synthesis. Industrial grade dominates volume flows into cleaning agents and basic chemical manufacturing, while battery grade commands premium positioning as cathode precursor demand intensifies. Food grade occupies a mature, specification-intensive niche serving pH regulation in processed products.
EPA oversight in the United States governs chlor-alkali emissions and workplace exposure limits, while REACH registration in Europe mandates comprehensive substance dossiers for KOH import and manufacture. China's MEE enforces wastewater discharge standards that constrain older electrolysis capacity. Stakeholders must monitor evolving battery-grade purity thresholds and electrolyzer technology shifts that could reshape cost structures across producer tiers.
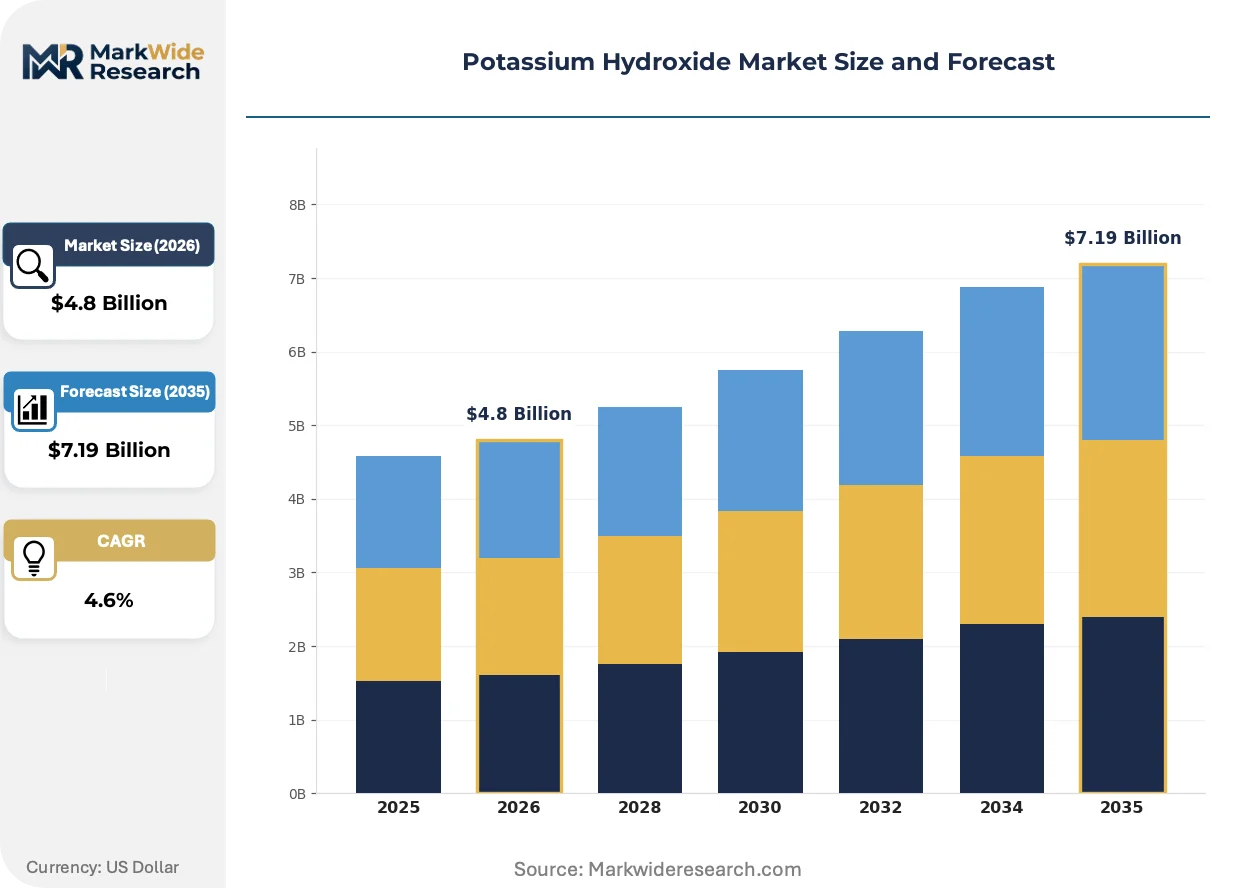
Market Dynamics
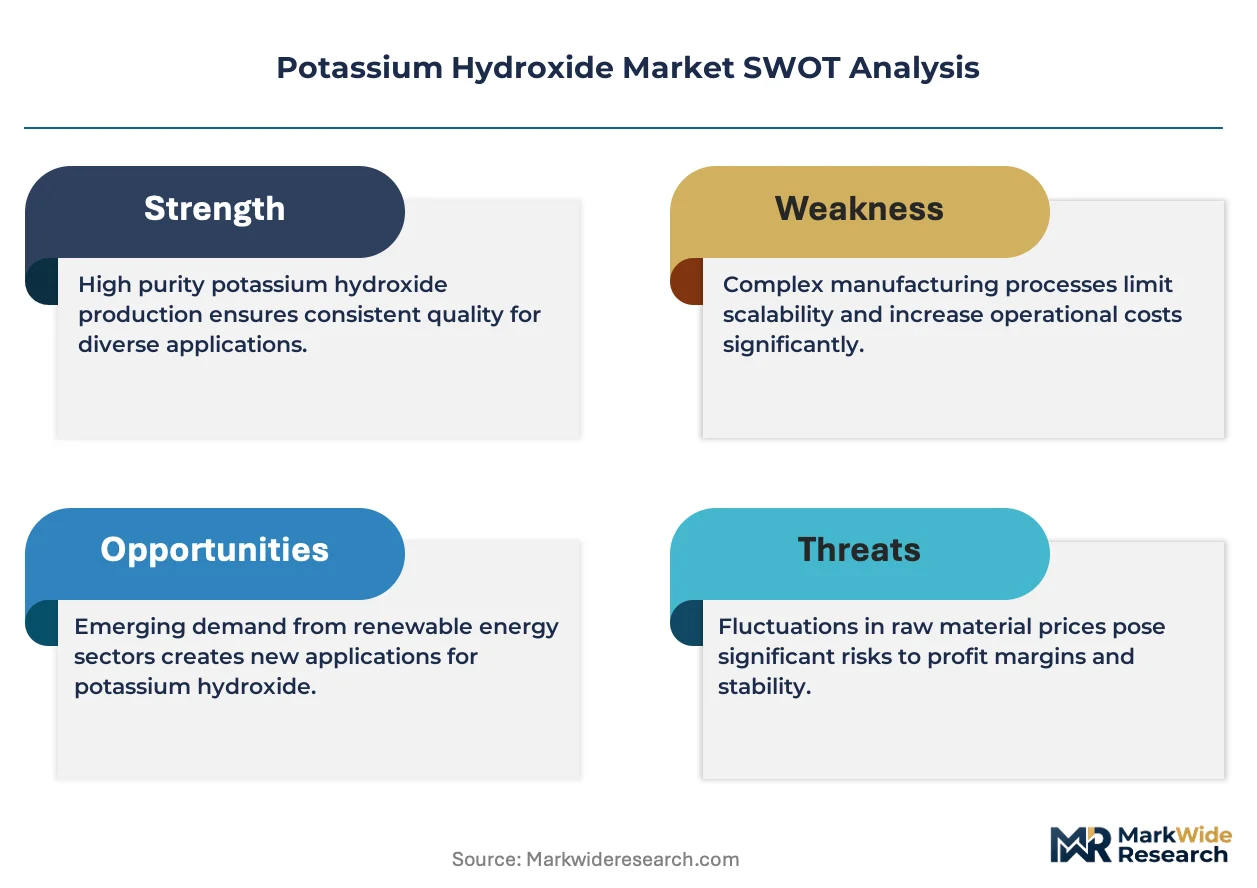
Membrane cell electrolysis technology is displacing mercury-based chlor-alkali processes across producer portfolios, while battery-grade purity specifications are compressing margins for legacy industrial-grade suppliers unable to retool.
Growth Catalysts
- Battery-grade electrolyte demand:Cathode precursor manufacturers in China are absorbing high-purity KOH volumes as domestic electric vehicle production scales. This demand stream is reshaping capacity allocation across integrated chlor-alkali operators.
- REACH registration thresholds:ECHA dossier requirements for KOH import and manufacture into Europe are consolidating qualified supplier lists. Registered producers gain preferential access to specialty chemical buyers seeking compliant sourcing.
- Membrane cell technology diffusion:Energy-efficient electrolysis platforms are reducing per-unit production costs for integrated producers. Technology adopters capture margin expansion unavailable to mercury cell operators facing MEE wastewater constraints in China.
Market Restraints
- Potassium chloride feedstock volatility:Mined KCl from Saskatchewan and Belarusian potash districts faces shipping disruptions and export licensing friction. Input cost swings compress producer margins during contract renegotiation windows.
- Supply concentration in integrated chlor-alkali:China's MEE-enforced capacity closures have concentrated viable production among state-affiliated chemical conglomerates with captive power and brine access. Geographic concentration elevates disruption risk from regional energy rationing or environmental enforcement spikes.
- Caustic soda substitution in cleaning formulations:Industrial lye applications are experiencing formulation shifts toward sodium hydroxide where alkali metal specificity is non-critical. KOH volume erosion in mature cleaning segments limits revenue diversification for pure-play producers.
Strategic Opportunities
- Underpenetrated Southeast Asian battery supply chain:Indonesia and Vietnam are constructing cathode active material plants without domestic KOH purification infrastructure. Qualified exporters can establish long-term offtake relationships during facility commissioning phases.
- EU Green Deal industrial decarbonization incentives:Carbon border adjustment mechanisms and renewable energy certificates are creating preference premiums for electrolysis operations with verified low-carbon intensity. Early certifiers capture price premiums from scope-conscious European buyers.
- Direct-to-formulator digital channels:Battery material startups and specialty chemical distributors are bypassing traditional merchant chemical wholesalers through platform-based procurement. Direct relationships enable specification co-development and faster qualification cycles.
Industry Challenges
- Electrolyzer engineering talent scarcity:Membrane cell design and zero-gap electrolyzer optimization require specialized electrochemical engineering expertise concentrated among retiring chlor-alkali veterans. Producer hiring pipelines are insufficient for technology transition timelines.
- Battery-grade certification timeline compression:OEM qualification protocols for cathode precursor supply chains now demand 18-24 month purity verification cycles. Producers must sustain capital deployment during revenue-negative qualification periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Potassium Hydroxide Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, Food Grade, Pharmaceutical Grade, Battery Grade End Use Industry: Chemicals, Agriculture, Food & Beverage, Cosmetics Application: pH Regulation, Cleaning Agents, Fertilizers, Electrolytes Packaging Type: Drums, Bags, IBC Totes, Bulk |
| Companies Covered | Solvay, UNID, Olin Corporation, INEOS KOH, Asahi Glass, Occidental Petroleum Corporation (OxyChem), Evonik Industries, Tessenderlo Chemie, BASF, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Potassium Hydroxide Market Emerging Trajectories
Electrolyzer technology evolution and regulatory purity mandates are compressing the viable producer base while opening margin capture opportunities for qualified specialists. Three developments are restructuring competitive positioning.
Zero-gap membrane electrolyzer architecture is miniaturizing cell room footprints while boosting current efficiency above 95%. Battery-grade KOH producers in China and South Korea are retrofitting legacy facilities with this technology to meet cathode precursor purity thresholds. The technology is compressing capital requirements for greenfield battery-grade capacity, enabling faster scale-up than traditional diaphragm or mercury cell platforms.
China's GB standards for battery materials are tightening trace metal impurity limits below 10 ppm for potassium hydroxide destined for lithium iron phosphate and high-nickel cathode production. The industrial consequence is disqualification of legacy industrial-grade capacity from electric vehicle supply chains. Producers in Jiangsu and Shandong provinces are most affected, responding with dedicated purification trains and third-party analytical certification investments.
Long-term offtake contracting is displacing spot market purchasing among cathode active material manufacturers seeking supply security. Korean and Japanese battery material specialists are locking in five-year KOH supply agreements with fixed-volume, escalator-priced structures. This pattern is most visible in the European electric vehicle supply chain, where cell producers are forcing cathode qualification backward onto chemical precursor specifications.
Potassium Hydroxide Market Segmentation
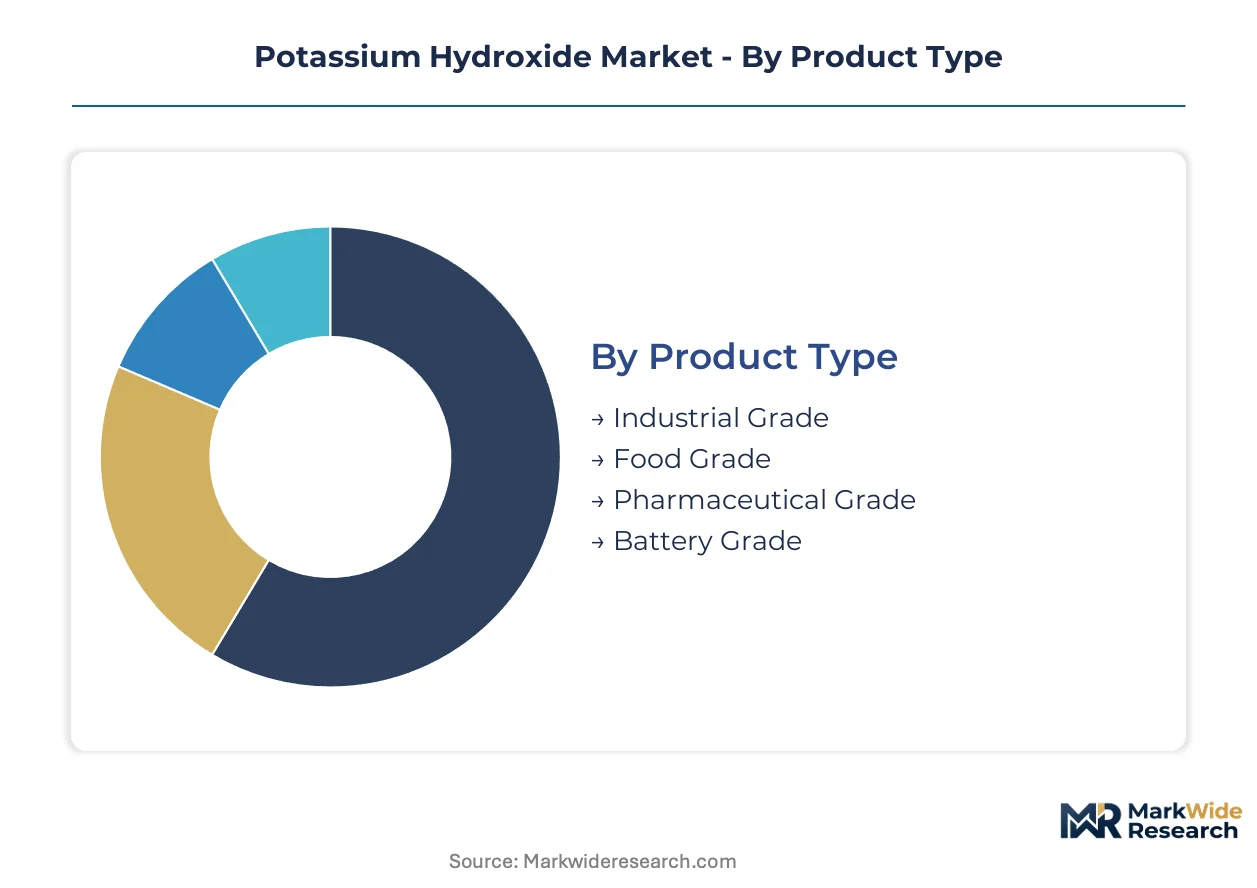
Potassium hydroxide market segmentation reveals divergent margin structures across purity tiers, with battery-grade commanding premium positioning while industrial-grade volumes anchor merchant chemical flows. Channel strategies differ markedly: specialty distributors handle food and pharmaceutical grades, integrated chlor-alkali producers serve battery material manufacturers directly, and bulk industrial volumes move through regional chemical wholesalers.
Product Type:
Channel-mix patterns separate commodity-grade flows through merchant distributors from battery-grade direct procurement by cathode precursor manufacturers.
- Industrial Grade:Standard 85-90% purity KOH serves pH adjustment, soap manufacturing, and basic chemical synthesis. Demand concentrates in China's Shandong and Jiangsu province chemical clusters, where integrated chlor-alkali operators supply regional cleaning compound formulators facing caustic soda substitution pressure.
- Battery Grade:Ultra-high purity specifications with trace metals below 10 ppm qualify this material for lithium iron phosphate and high-nickel cathode production. Chinese electric vehicle supply chain integration is absorbing expanding volumes as domestic cell manufacturing scales, with Korean and Japanese material specialists locking in long-term offtake agreements.
- Food Grade:FCC-compliant KOH regulates pH in processed foods, chocolate, and soft drinks through specialized food ingredient distributors.
- Pharmaceutical Grade:USP/NF specifications govern excipient and API manufacturing applications with intensive analytical documentation requirements.
By volume, Industrial Grade leads. By growth pace, Battery Grade is expanding most quickly.
End Use Industry:
Application maturity creates distinct margin profiles, with established chemical processing contrasting against emerging battery material demand.
- Chemicals:Derivative manufacturing consumes the largest KOH volumes for potassium carbonate, permanganate, and silicate production. China's integrated chlor-alkali platforms supply this segment through pipeline-connected chemical parks in Ningbo and Tianjin, where MEE wastewater enforcement is consolidating supply among state-affiliated producers.
- Agriculture:Liquid fertilizer and foliar feed formulations absorb merchant-grade volumes, particularly in Brazil's Cerrado expansion and India's Punjab wheat belt where potash-based alkalis supplement nitrogen-phosphorus programs.
- Food & Beverage:pH regulation in cocoa processing and olive curing drives specification-intensive procurement through food-grade certified distributors.
- Cosmetics:Saponification for premium personal care products requires low-mercury certification, with European formulators demanding REACH-registered supply chains.
Chemicals generates the highest absolute consumption. Battery precursor demand within Chemicals is climbing the fastest.
Application:
Functional requirements dictate packaging and logistics configurations, from bulk tanker deliveries for electrolyte manufacturing to palletized bags for agricultural blending.
- pH Regulation:Wastewater treatment and industrial process control consume standardized 45-50% solution concentrations. US EPA discharge limits and China's MEE standards are tightening specification windows, forcing municipal treatment operators toward certified low-mercury sources.
- Electrolytes:Battery-grade KOH serves as potassium source for electrolyte salts in nickel-metal hydride cells and emerging potassium-ion battery research. Korean cell manufacturers are qualifying Chinese purified material against domestic Japanese supply, with qualification timelines extending 18-24 months.
- Cleaning Agents:Institutional and industrial degreaser formulations face sodium hydroxide substitution where alkali metal specificity lacks technical justification.
- Fertilizers:Liquid potassium applications in precision agriculture require compatible storage and handling infrastructure at farm-gate distribution points.
pH Regulation dominates current volume flows. Electrolytes are gaining share fastest as electric vehicle production scales.
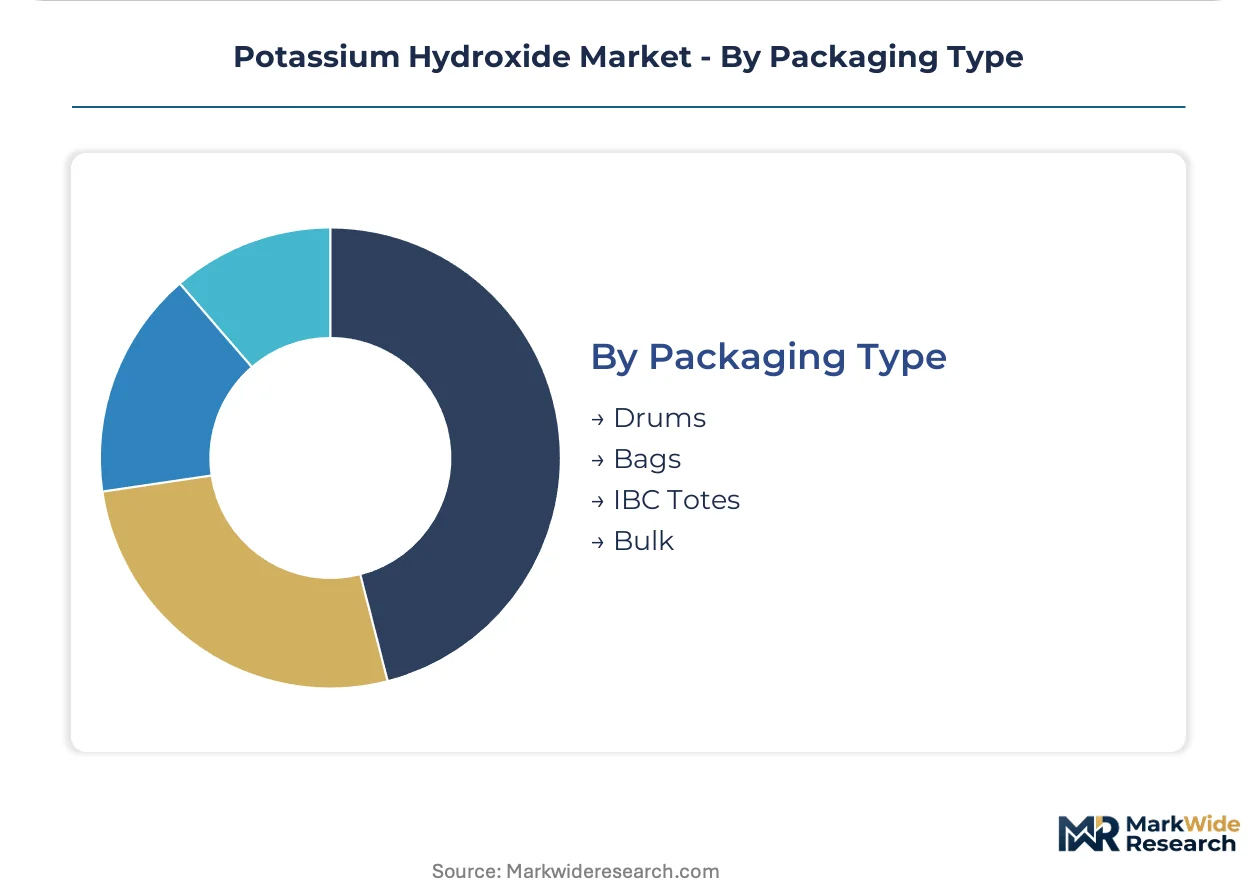
Packaging Type:
Logistics economics favor bulk for integrated chemical parks, while specialty grades require contamination-controlled intermediate packaging.
- Bulk:Tanker and railcar deliveries serve chlor-alkali-integrated derivative plants and large-scale battery material producers with dedicated unloading infrastructure. China's state chemical conglomerates favor this configuration for captive consumption within Yangtze River Delta industrial zones.
- IBC Totes:Intermediate bulk containers enable food-grade and pharmaceutical-grade distribution with reduced contamination risk compared to drum repackaging.
- Drums:Standard 200-liter steel and plastic drums serve mid-volume chemical processors and cleaning compound manufacturers.
- Bags:Multi-layer laminated sacks protect hygroscopic flake and pellet grades for agricultural and specialty chemical blending operations.
Bulk handles the greatest tonnage. IBC Totes are expanding most quickly for battery-grade material requiring controlled handling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated chlor-alkali capacity clusters in eastern China dominate viable KOH production, with state-affiliated chemical conglomerates controlling captive brine access and power supply. Geographic concentration elevates exposure to regional energy rationing and environmental enforcement cycles.
China
Battery-grade cathode precursor demand from Jiangsu and Shandong province manufacturers is absorbing expanding high-purity KOH volumes. MEE wastewater discharge standards are disqualifying legacy mercury cell capacity from electric vehicle supply chains. Yangtze River Delta chemical parks in Ningbo and Shanghai anchor membrane cell retrofit investments.
United States
EPA chlor-alkali emissions oversight governs membrane cell operations supplying pH regulation and cleaning compound markets. Gulf Coast petrochemical corridors sustain merchant KOH flows through pipeline-connected derivative plants. Olin Corporation operates caustic potash facilities across geographically diversified locations.
Germany
REACH registration requirements through ECHA are consolidating qualified supplier lists for specialty chemical buyers. INEOS KOH anchors significant production capacity across Northern Europe with integrated chlor-alkali infrastructure. Rhineland chemical clusters face carbon border adjustment pressure under EU Green Deal industrial decarbonization timelines.
South Korea
Korean cell manufacturers are qualifying Chinese purified material against domestic Japanese supply for battery electrolyte applications. MFDS pharmaceutical-grade specifications govern excipient manufacturing for domestic API producers. Busan-Ulsan industrial zones host cathode active material specialists locking in long-term KOH offtake structures.
Japan
METI industrial policy supports electrolyzer technology transitions away from mercury-based processes. Japanese battery material specialists maintain qualification protocols demanding 18-24 month purity verification cycles for cathode precursor supply chains. Kanto region chemical producers face feedstock cost pressure from Belarusian potash shipping disruptions.
Potassium Hydroxide Market Vendor Landscape
Concentration sits with integrated chlor-alkali conglomerates possessing captive power, brine access, and membrane cell technology platforms. State-affiliated Chinese chemical groups and Western multinational chemical corporations divide the viable producer base. Two strategic archetypes dominate: integrated energy-chemical conglomerates with backward control over potash feedstocks, and specialty chemical purifiers serving battery-grade specification tiers. Competitive moves center on membrane cell retrofit capital deployment and five-year offtake contracting with cathode material manufacturers.
Among European-registered chemical groups, Solvay leverages its integrated chlor-alkali platform to sustain supply reliability for REACH-compliant buyers. INEOS KOH occupies a position within the Northern European production tier. Olin Corporation exemplifies geographic diversification strategy across North American caustic potash operations. These three anchors represent distinct competitive responses to battery-grade purity threshold compression: European regulatory compliance, regional scale concentration, and multi-site operational flexibility.
| Leading Market Players |
|---|
| Solvay |
| UNID |
| Olin Corporation |
| INEOS KOH |
| Asahi Glass |
| Occidental Petroleum Corporation (OxyChem) |
| Evonik Industries |
| Tessenderlo Chemie |
| BASF |
| Others |
Supply Flow & Price Mechanics
Five-year offtake contracting with escalator-priced structures locks in supply access for cathode precursor manufacturers while stripping price volatility from membrane cell operators in Jiangsu and Shandong provinces. Korean battery material specialists enforce these terms to secure qualification-compliant volumes against Belarusian potash feedstock disruption.
Pricing Analysis
REACH registration dictates the pricing tier structure across European specialty chemical procurement, separating ECHA-registered producers from merchant importers facing dossier compliance costs. Battery-grade certification with trace metals below 10 ppm commands substantial premiums over industrial-grade flows into cleaning formulations. Pricing pressure stems from caustic soda substitution in non-critical alkali applications where sodium hydroxide displaces potassium hydroxide. Industrial cleaning compound manufacturers exhibit highest price sensitivity, while cathode active material specialists absorb premium tiers for supply security.
Supply Chain Analysis
Potash mining districts in Saskatchewan and Belarus anchor raw material flows for chlor-alkali electrolysis, with MEE-enforced wastewater standards in China concentrating viable membrane cell capacity among state-affiliated chemical conglomerates. Production draws from captive brine access in Yangtze River Delta chemical parks and integrated power supply in Shandong province. Single-source vulnerability runs through Belarusian export licensing friction and Baltic Sea shipping disruptions. Distribution runs through pipeline-connected derivative plants for bulk industrial volumes and IBC totes for battery-grade material requiring contamination-controlled handling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among cathode active material manufacturers as Korean and Japanese cell producers force qualification requirements backward onto chemical precursor specifications, consolidating procurement leverage with fewer qualified suppliers.
For Market Incumbents: Consolidate membrane cell retrofit investments in Jiangsu and Shandong province chemical parks to defend battery-grade positioning against mercury cell capacity closures under MEE enforcement. Anchor backward integration into Saskatchewan potash offtake agreements to neutralize Belarusian feedstock volatility. Certification investment in REACH dossier maintenance secures European specialty chemical access against emerging merchant importers. For New Entrants and Emerging Players: Anchor in Indonesia and Vietnam cathode active material plant commissioning phases where domestic KOH purification infrastructure remains underdeveloped. Battery-grade specification co-development with Southeast Asian cell manufacturers offers faster qualification timelines than established supply chains. Direct platform-based procurement channels bypass traditional chemical wholesalers for specification-intensive relationships. For Investors and Strategic Acquirers: Capital is best deployed toward membrane cell technology platforms with verified low-carbon intensity eligible for EU Green Deal premium capture. Long-term viability across the analysis window favors electrolyzer engineering talent concentration and zero-gap retrofit capability. Watch for carbon border adjustment mechanism implementation signals as inflection indicators for European pricing power shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Cell Retrofit | MEE wastewater standards disqualify mercury cell capacity from electric vehicle supply chains. |
| Backward Integration into Potash | Saskatchewan mining offtake agreements neutralize Belarusian export licensing friction. |
| Long-term Supply Agreement | Korean cathode manufacturers lock in five-year structures with fixed-volume escalator pricing. |
| Green Certification Program | EU carbon border adjustment creates preference premiums for low-carbon electrolysis operations. |
| Joint Venture | Indonesian cathode plant partnerships establish qualification relationships during facility commissioning. |
Methodological Framework
Cross-validation between chlor-alkali plant manager interviews and customs trade data anchors the qualitative findings on capacity allocation shifts. Primary fieldwork with procurement leads at cathode active material manufacturers, membrane cell engineering specialists, and REACH compliance consultants combined with secondary validation through ACC and Cefic industry reports, SEC 10-K filings from listed chemical conglomerates, and Chinese MEE wastewater discharge records. Bottom-up electrolyzer capacity modeling and top-down end-use demand estimation triangulate volume outputs.
Sensitivity analysis across grade tier, end-use industry, packaging format, and regional production hub dimensions structures the analytical framework over the projection horizon. CAGRs derive from segmented growth rate reconciliation against integrated chlor-alkali capacity expansion timelines. Membrane cell technology diffusion curves and battery-grade purity threshold evolution constitute key forecast inputs.
Material uncertainties — potassium chloride feedstock shipping disruptions, MEE enforcement spikes, and cathode precursor qualification timeline extensions — sit outside the modeled envelope. Forecasts reflect assumptions on membrane cell retrofit completion rates and electric vehicle production scaling. Practitioners should keep alternative scenarios live as EU carbon border adjustment mechanisms and Chinese dual carbon goals evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
High-Value Chemicals
High-Purity Acetic Acid Market
High-Value Chemicals
High-Nickel NCM Cathode Binder Latex Market
High-Value Chemicals
Europe Fine Chemical Market
High-Value Chemicals
Hydroxylamine Market
High-Value Chemicals
High Molecular Ammonium Polyphosphate Market
High-Value Chemicals
High Performance Mercury Sorbent Market
High-Value Chemicals
Global Hydrofluoric Acid Market
High-Value Chemicals
Ultra-High-Purity Anhydrous Hydrogen Chloride (Hcl) Gas Market
High-Value Chemicals
High-Silica Zeolite Market
High-Value Chemicals
Global High Potency Apis /HPAPI Market
High-Value Chemicals
Global Hyaluronidase Market
High-Value Chemicals
High-Temperature Epoxy Market
High-Value Chemicals
Phenanthroline Monohydrate Market
High-Value Chemicals
High-Purity Boehmite Market
High-Value Chemicals
High Purity Benzenethiol Market
High-Value Chemicals
Ammonium Metavanadate Market