
 Isopropylamine Market | 2026-2036
Isopropylamine Market Size, Share, and Industry Trends Forecast 2026-2036
Isopropylamine Market Analysis
Specialty chemical distribution is rewriting access patterns for isopropylamine buyers across agricultural and pharmaceutical channels. BASF SE leverages its integrated amines platform to sustain supply security for European agrochemical formulators. Arkema Group anchors its position through specialized aliphatic amine production in France. Alkyl Amines Chemicals Ltd. dominates South Asian supply with captive manufacturing and direct technical service to local pesticide producers.
Isopropylamine, a primary aliphatic amine with the formula C3H9N and a molecular weight of 59.11 g/mol, serves as a critical intermediate in glyphosate synthesis and pharmaceutical salt formation. Pharmaceutical grade material commands premium positioning due to stringent impurity limits enforced by pharmacopeial standards. Agricultural chemicals represents the largest application segment, where isopropylamine functions as a key building block for herbicide active ingredients. Coating agents and chemical reactions segments show faster structural growth as waterborne industrial coatings expand and specialty amine demand diversifies beyond crop protection.
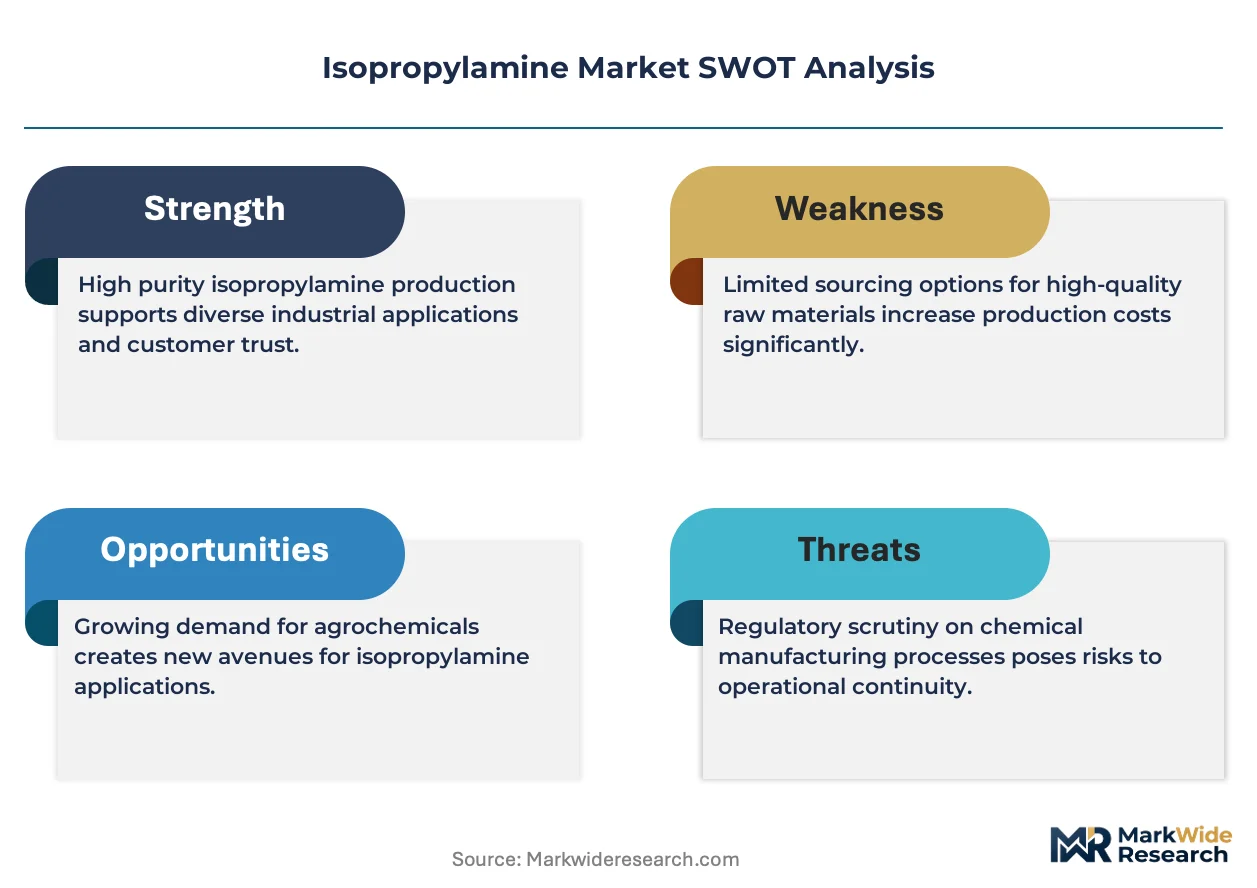
EPA registration requirements for pesticide intermediates shape product specifications and batch documentation burdens for US-bound supply. REACH and the EU Green Deal are accelerating purity benchmarks and carbon footprint disclosure for European market access. China's MEE enforces emission controls on amine manufacturing facilities, raising compliance costs for regional producers. Stakeholders must monitor regulatory divergence between jurisdictions to optimize manufacturing location and certification strategies.
Market Dynamics
Glyphosate manufacturers in China are consolidating procurement of isopropylamine intermediates, compressing supply chain tiers and forcing European formulators to secure alternative sourcing arrangements or absorb purity premium costs.
Growth Catalysts
- Herbicide formulation demand:Agricultural chemicals producers in China are scaling glyphosate output, pulling isopropylamine volumes through direct technical supply agreements.
- REACH purity escalation:ECHA-mandated impurity thresholds for amine imports into Europe are creating certified-grade supply premiums that reward compliant producers.
- Pharmaceutical salt applications:Pharmacopeial-grade material for active pharmaceutical ingredient synthesis is expanding as CDSCO and FDA filing volumes for generic drugs rise.
Market Restraints
- Propylene feedstock volatility:Crude-linked naphtha and propylene pricing swings transmit directly into isopropylamine cost structures, eroding margin predictability for non-integrated producers.
- Jiangsu-Zhejiang supply concentration:Over sixty percent of merchant capacity sits within a two-hundred-kilometer radius on China's eastern seaboard, exposing buyers to single-region weather and regulatory disruption.
- Monoethanolamine substitution:Certain herbicide formulators are trialing alternative amine neutralizing agents where label chemistry permits, threatening volume retention in agricultural applications.
Strategic Opportunities
- India agrochemical localization:PLI scheme incentives for crop protection manufacturing are drawing formulation investments that require captive amine supply, opening import substitution opportunities.
- Waterborne coatings convergence:Isopropylamine salts for pH control in low-VOC industrial coatings are gaining specification as EPA emission rules tighten solvent-based alternatives.
- Specialty distribution platforms:Digital procurement portals for certified pharmaceutical-grade amines are compressing traditional distributor margins while expanding geographic reach for qualified producers.
Industry Challenges
- Pharmacopeial certification timelines:USP and EP monograph compliance for pharmaceutical-grade batches requires twelve-to-eighteen-month validation cycles that delay revenue recognition.
- Emission control retrofit burden:China's MEE enforcement of amine facility scrubber and wastewater standards is forcing capital deployment that smaller merchant producers cannot finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Isopropylamine Market |
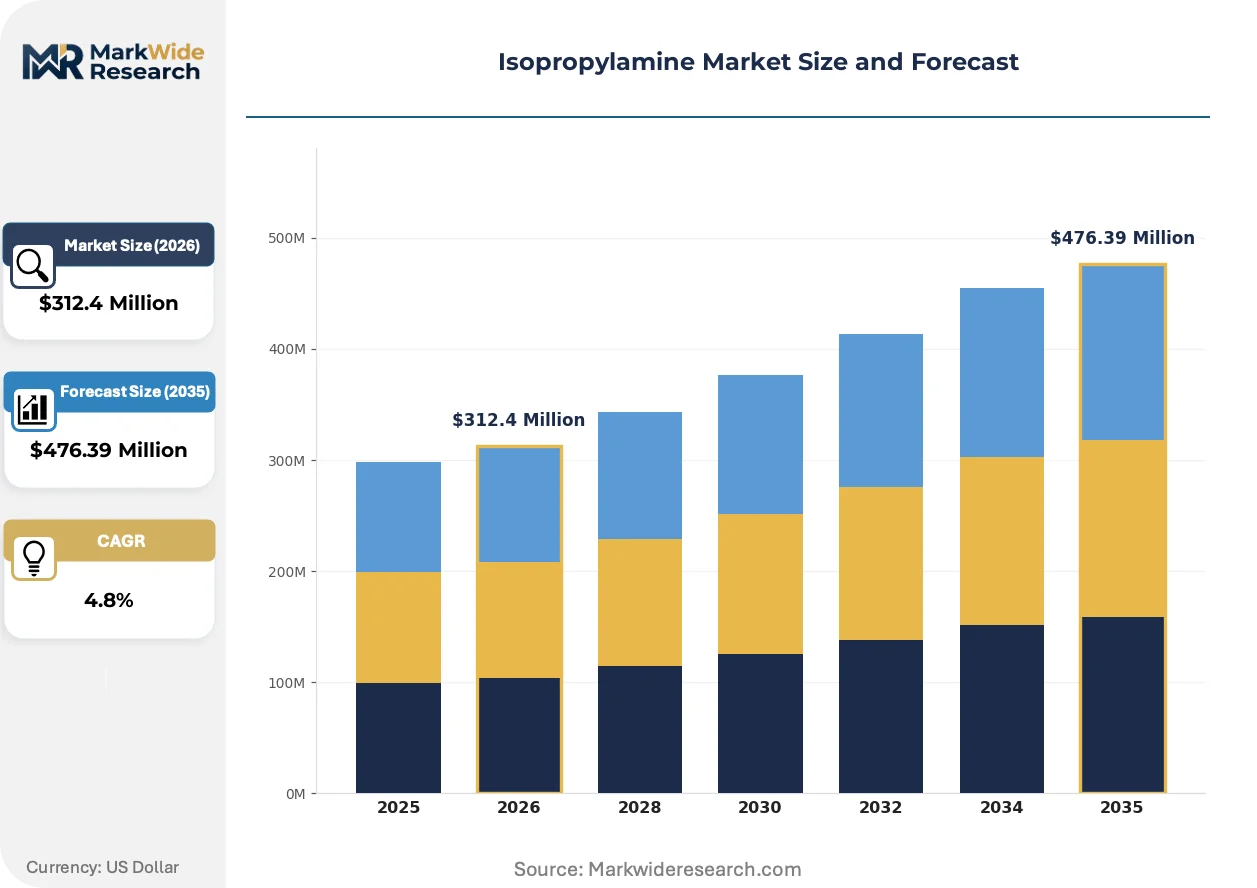
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $476.39 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Grade A, Grade B, Technical Grade, Pharmaceutical Grade Application: Agricultural Chemicals, Pharmaceutical Intermediates, Coating Agents, Chemical Reactions End User: Agriculture, Pharmaceuticals, Chemicals, Textile Packaging Type: Drums, Bags, IBC Totes, Pails |
| Companies Covered | Arkema Group, DuPont de Nemours Inc., BASF SE, Alkyl Amines Chemicals Ltd., Huntsman International LLC, Dow Chemical Co., Evonik Industries AG, Solvay SA, Eastman Chemical Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Isopropylamine Market Emerging Trajectories
Process intensification and regulatory disclosure requirements are compressing traditional batch manufacturing economics while rewarding continuous production platforms with integrated quality verification.
Continuous flow reactor technology for aliphatic amine synthesis is virtualizing conventional stirred-tank batch operations. BASF and Arkema are deploying modular skid-mounted units at European sites, cutting solvent use and thermal exposure. This virtualization is collapsing the capital intensity gap between commodity and specialty amine production, enabling smaller-lot pharmaceutical-grade output without prohibitive unit cost penalties.
REACH Article 33 extended supply chain disclosure obligations are forcing downstream formulators to document amine origin and carbon intensity. ECHA's SCIP database requirements for substances of very high concern are propagating through agrochemical and coating supply chains. European herbicide manufacturers are responding by demanding certified mass-balance documentation from Chinese suppliers, creating a two-tier market split between disclosure-compliant and undocumented material.
Direct technical service contracts are displacing traditional distributor relationships for large-volume agricultural chemical buyers. Formulators in Brazil and Argentina are contracting directly with Indian and Chinese producers for specification-tailored isopropylamine grades, bypassing regional chemical distributors. This pattern is most pronounced in glyphosate salt manufacturing, where technical collaboration on impurity profiles determines registration success in destination markets.
Isopropylamine Market Segmentation
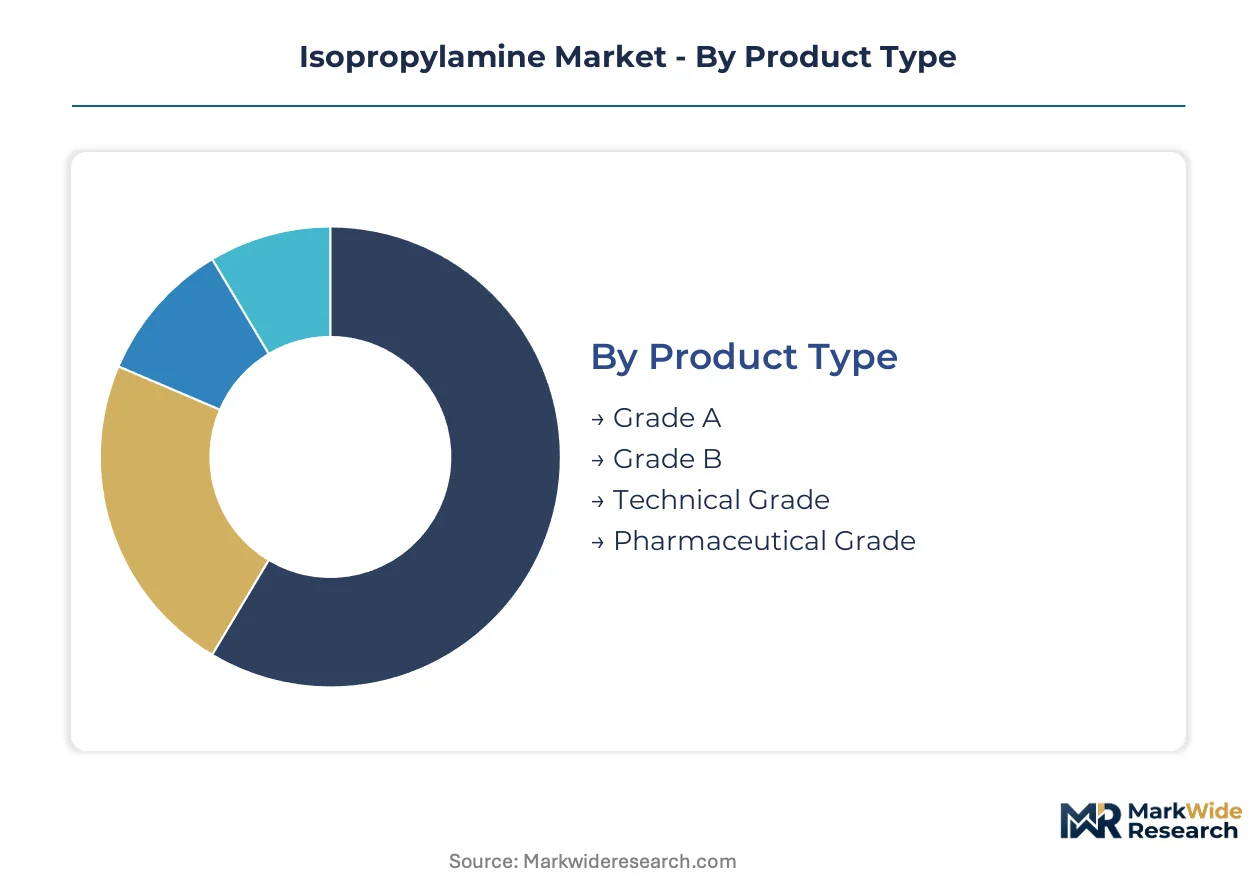
Isopropylamine procurement patterns diverge sharply across purity grades and end-use specifications, with agricultural chemical buyers prioritizing volume throughput while pharmaceutical customers demand validated batch documentation. Understanding these segment boundaries enables suppliers to align certification investments with margin capture potential.
Product Type:
Mature commodity grades dominate tonnage flows, while emerging certified segments command pricing premiums through regulatory compliance barriers.
- Pharmaceutical Grade:USP and EP monograph compliance mandates impurity profiling below 0.1% for specified contaminants, with twelve-to-eighteen-month validation cycles delaying supplier qualification. CDSCO and FDA filing volumes for generic drug synthesis are pulling certified material through dedicated distribution channels in India and the United States.
- Technical Grade:Standard purity specifications serve bulk agricultural chemical synthesis where glyphosate salt manufacturers prioritize consistent amine content over trace contaminant thresholds. Chinese glyphosate producers in Jiangsu and Zhejiang provinces absorb the majority of merchant technical grade volumes through direct procurement contracts.
- Grade A:Intermediate purity tier targeting coating and specialty chemical applications requiring controlled moisture and color specifications without full pharmacopeial overhead.
- Grade B:Entry-level specification for industrial chemical reactions where basic neutralization chemistry tolerates broader compositional variance.
Technical Grade retains volume leadership; Pharmaceutical Grade holds the steepest expansion curve.
Application:
Cost tier stratification separates high-volume commodity synthesis from premium formulation services, with regulatory documentation requirements determining segment boundaries.
- Agricultural Chemicals:Herbicide active ingredient synthesis consumes the dominant share of isopropylamine merchant supply, with glyphosate isopropylamine salt formation representing the single largest demand concentration. EPA registration requirements for pesticide intermediates enforce batch-level impurity documentation that shapes supplier qualification protocols for US-bound material.
- Chemical Reactions:Acid neutralization and pH control applications in waterborne industrial coatings are expanding specification volumes as EPA emission rules tighten solvent-based alternatives. Low-VOC coating formulators in Germany and the United States are specifying amine salts for corrosion resistance and application stability.
- Pharmaceutical Intermediates:Active pharmaceutical ingredient salt formation requires validated supply chains with pharmacopeial certification, creating margin premiums for compliant producers.
- Coating Agents:Surface treatment and adhesion promotion applications in automotive and industrial finishes utilize isopropylamine derivatives for substrate compatibility.
Agricultural Chemicals dominates absolute tonnage; Chemical Reactions is climbing the fastest on regulatory-driven coating substitution.
End User:
Customer type fragmentation separates price-sensitive bulk consumers from specification-driven buyers with captive quality verification requirements.
- Agriculture:Crop protection formulators and generic agrochemical producers in Brazil, Argentina, and China source isopropylamine through direct technical service agreements that bypass traditional distribution tiers. Glyphosate manufacturers consolidate procurement around specification-tailored grades with impurity profiles matched to destination market registration requirements.
- Pharmaceuticals:Generic drug manufacturers and contract development organizations require validated supply chains with pharmacopeial documentation, creating qualification barriers that sustain pricing premiums for certified producers.
- Chemicals:Diversified industrial consumers utilize isopropylamine for synthesis intermediates, extraction agents, and process chemistry applications across specialty and commodity chemical production.
- Textile:Fiber treatment and dye chemistry applications represent a niche consumption segment with specialized handling requirements for moisture-sensitive material.
Agriculture commands the largest volume share; Pharmaceuticals delivers the highest margin realization per kilogram.
Packaging Type:
Supply concentration in bulk formats reflects the commodity chemistry orientation of dominant end-use segments, with specialized packaging serving geographic and regulatory fragmentation.
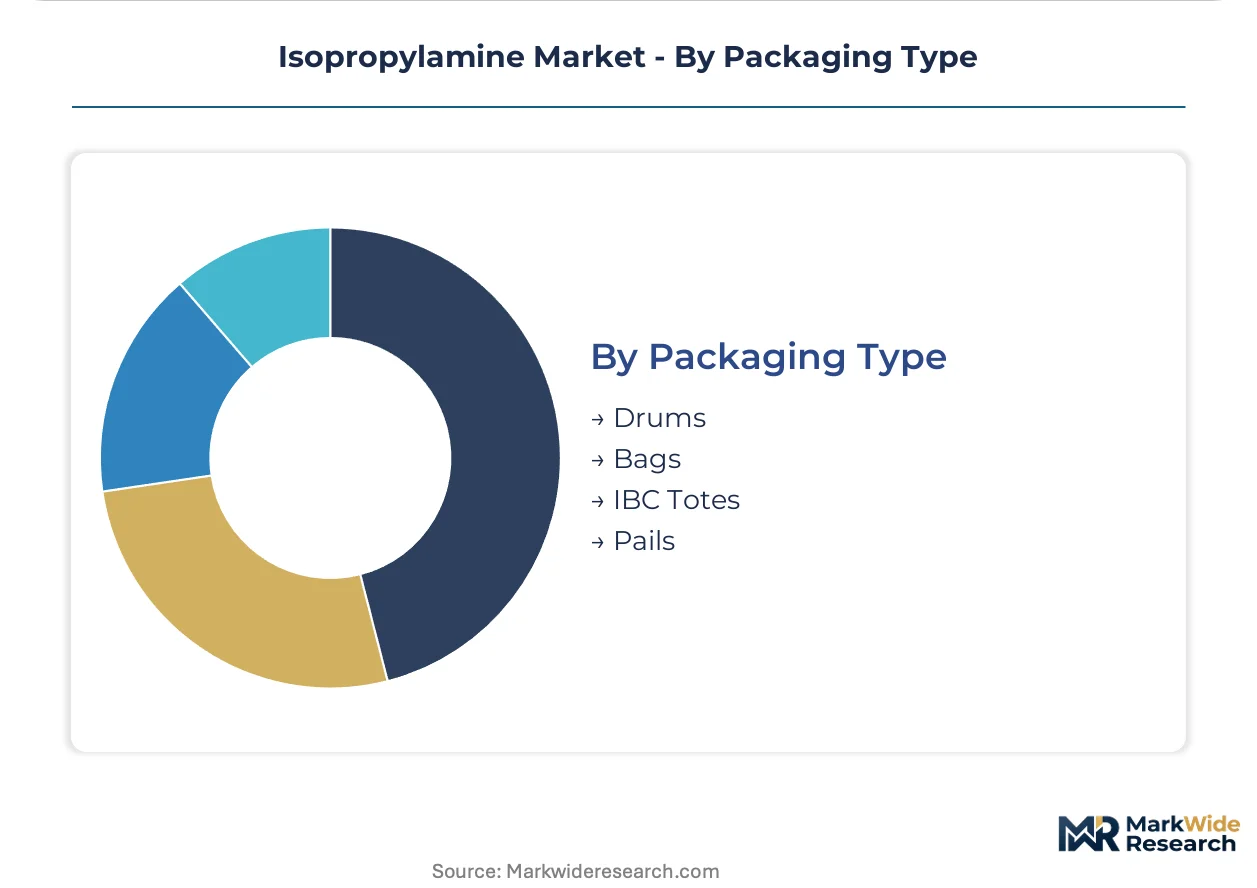
- Drums:Standard 200-liter steel and HDPE drum packaging serves mid-volume agricultural chemical producers and regional formulators requiring manageable batch sizes with established handling infrastructure. Drum specifications vary by destination market hazmat classification requirements.
- IBC Totes:Intermediate bulk containers enable efficient transfer to automated formulation lines at large-scale glyphosate manufacturing facilities, reducing handling labor and contamination exposure compared to smaller formats.
- Bags:Moisture-barrier flexible packaging serves powder and derivative formulations where solid amine salt handling replaces liquid bulk transfer.
- Pails:Small-format containers address laboratory, pilot-scale, and specialty chemical sampling requirements with controlled access and reduced headspace degradation.
Drums retain the broadest geographic penetration; IBC Totes is expanding most quickly on automation investments at major formulation sites.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese producers command pricing leverage over European buyers due to Jiangsu-Zhejiang supply concentration, while US formulators absorb premiums from EPA-mandated batch documentation requirements. This asymmetry reshapes procurement geography across agricultural and pharmaceutical channels.
China
Jiangsu and Zhejiang provinces host over sixty percent of global merchant capacity within a two-hundred-kilometer coastal corridor. MEE emission controls on amine manufacturing facilities are forcing scrubber retrofits and wastewater upgrades at production sites. Nantong and Taizhou chemical parks concentrate glyphosate intermediate synthesis, with domestic agrochemical producers scaling direct technical supply agreements that bypass traditional distribution tiers.
United States
EPA registration requirements for pesticide intermediates enforce batch-level impurity documentation that shapes supplier qualification protocols for agricultural chemical formulators. FDA filing volumes for generic drug synthesis are pulling pharmacopeial-grade material through dedicated distribution channels. Gulf Coast petrochemical corridors provide propylene feedstock integration for domestic amine producers serving coating and pharmaceutical applications.
Germany
REACH Article 33 extended supply chain disclosure obligations and ECHA SCIP database requirements are propagating through agrochemical supply chains. EU Green Deal carbon footprint disclosure mandates are creating certified-grade supply premiums that reward compliant producers. Ludwigshafen and Marl chemical clusters anchor integrated amines platforms supplying European formulators with mass-balance documented material.
India
PLI scheme incentives for crop protection manufacturing are drawing formulation investments that require captive amine supply, opening import substitution opportunities. CDSCO filing volumes for generic drug synthesis are expanding pharmacopeial-grade demand through dedicated technical service channels. Gujarat and Maharashtra industrial corridors concentrate aliphatic amine production with direct procurement relationships to domestic pesticide manufacturers.
Brazil
ANVISA registration alignment with EPA specifications enables herbicide formulators to leverage US-qualified supply chains for glyphosate salt manufacturing. Direct technical service contracts with Asian producers are displacing traditional regional distributor relationships for large-volume agricultural chemical buyers. São Paulo and Paraná agrochemical formulation hubs are consolidating procurement around specification-tailored grades with impurity profiles matched to destination market requirements.
Isopropylamine Market Vendor Landscape
Integrated petrochemical majors and specialized aliphatic amine producers split the market between feedstock-integrated scale and specification-tailored service. The vendor base concentrates around three strategic archetypes: multinational chemical conglomerates with captive propylene supply, regional specialists with dedicated amine production assets, and formulation-integrated distributors compressing traditional supply tiers. Dominant competitive moves include backward integration into propylene feedstock and geographic expansion through direct technical service contracts that bypass regional distribution.
Within the integrated multinational tier, BASF SE and Arkema Group exemplify petrochemical-backed scale positions. BASF anchors European supply security through its Ludwigshafen amines platform, while Arkema's French production assets serve specialized aliphatic amine demand. Alkyl Amines Chemicals Ltd. occupies a position within the regional specialist archetype, with South Asian manufacturing and direct technical service capabilities to local pesticide producers. These three entities represent divergent strategic postures: feedstock-integrated scale, regional production concentration, and formulation-proximate technical service.
| Leading Market Players |
|---|
| Arkema Group |
| DuPont de Nemours Inc. |
| BASF SE |
| Alkyl Amines Chemicals Ltd. |
| Huntsman International LLC |
| Dow Chemical Co. |
| Evonik Industries AG |
| Solvay SA |
| Eastman Chemical Co. |
| Others |
Supply Flow & Price Mechanics
Jiangsu and Zhejiang provinces concentrate over sixty percent of global merchant isopropylamine capacity within a two-hundred-kilometer coastal corridor, granting Chinese producers substantial leverage over European and North American buyers who must absorb purity premiums or secure alternative sourcing. This geographic concentration compresses margin negotiation space for formulators while rewarding integrated producers with captive propylene supply.
Pricing Analysis
Configured-to-order pricing for pharmaceutical-grade material commands substantial premiums over standard technical grade quotations, with USP and EP monograph compliance creating twelve-to-eighteen-month validation cycles that lock in supplier relationships. Three-tier pricing structure across pharmaceutical, technical, and industrial grades reflects certification burden and batch documentation intensity. Cost compression in technical grade is intensifying because glyphosate manufacturers in China are consolidating procurement volumes through direct technical agreements. Agricultural chemical formulators exhibit the highest price sensitivity, while pharmaceutical customers accept premium positioning for validated supply security.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from Chinese producers are displacing traditional distributor credit arrangements for Brazilian and Argentine formulators. Manufacturing gravity centers on China, India, and Germany, with feedstock dependency on propylene derivatives and naphtha-linked petrochemical streams. Single-region concentration in Jiangsu-Zhejiang exposes buyers to weather and regulatory disruption. Distribution runs through direct technical service contracts for large-volume agricultural buyers, bypassing regional chemical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward glyphosate manufacturers in China as they consolidate procurement tiers and force European formulators into premium-tier sourcing or supply restructuring.
For Market Incumbents: Pre-empt monoethanolamine substitution trials by deepening technical collaboration with formulators on impurity profile optimization for registration success. Secure backward integration into propylene feedstock or captive manufacturing in Gujarat and Maharashtra to defend against Indian import substitution. Prioritize REACH Article 33 mass-balance documentation investments to capture certified-grade premiums. For New Entrants and Emerging Players: Pursue waterborne coatings specification opportunities in Germany and the United States where EPA emission rules tighten solvent-based alternatives. Target pharmaceutical-grade distribution through digital procurement portals that compress traditional distributor margins. Enter via dedicated technical service contracts with mid-volume Brazilian formulators seeking ANVISA-aligned supply chains. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors continuous flow reactor platforms with integrated quality verification over conventional stirred-tank batch operations. Long-term viability rests on regulatory disclosure compliance capabilities rather than commodity scale. Watch for MEE enforcement intensity in China as inflection indicator for supply restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Flow Reactor Deployment | BASF and Arkema modular skid-mounted units cut solvent use and thermal exposure in European production. |
| Backward Integration into Propylene | Gulf Coast petrochemical corridors provide feedstock security for US coating and pharmaceutical applications. |
| Pharmacopeial Certification Investment | USP and EP monograph compliance sustains pricing premiums through twelve-to-eighteen-month validation barriers. |
| Direct Technical Service Contracts | Brazilian and Argentine formulators bypass regional distributors for specification-tailored isopropylamine grades. |
| Mass-Balance Documentation Compliance | REACH Article 33 SCIP database requirements create two-tier market split for European agrochemical supply. |
Methodological Framework
Cross-validation between primary interviews with plant managers at Jiangsu-Zhejiang manufacturing facilities and secondary customs trade data anchors the qualitative findings on supply concentration and procurement pattern shifts. Agrochemical procurement leads, pharmaceutical regulatory affairs directors, and coating formulator technical managers provided forward-looking demand calibration. Bottom-up triangulation against SEC filings from BASF, Arkema, and Alkyl Amines Chemicals Ltd. validated capacity and margin structure assumptions.
Calibration against historical price spreads across pharmaceutical, technical, and industrial grades informed elasticity assumptions over the projection horizon. Segmentation modeling incorporated grade tier, end-use industry, packaging format, and regional production hub dimensions. CAGRs derived from volume-weighted growth rates across these segments, with specific inputs including CDSCO and FDA filing volumes for generic drug synthesis and EPA registration timelines for pesticide intermediates.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by non-integrated Chinese producers or accelerated MEE enforcement would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
Trifluoroethanol Market
Solvents
Benzene Market
Solvents
Europe Acetonitrile Market
Solvents
Global Acetonitrile Market
Solvents
2-Phenylethanol Market
Solvents
Methyl Undecylenate Market
Solvents
Methyl Acetate Market
Solvents
Global Solvent Dyes Market
Solvents
Diethyl Ether Market
Solvents
Hydrosol Market
Solvents
Phenol Derivatives Market
Solvents
Ethyl Pyruvate Market
Solvents
Para Nitrochlorobenzene Market
Solvents
Aliphatic Solvents and Thinners Market
Solvents
Global Chloroform Market
Solvents
High Purity Solvents Market