
 Global Furfural Solvent Market | 2026-2036
Global Furfural Solvent Market Size, Share, and Industry Trends Forecast 2026-2036
Global Furfural Solvent Market Analysis
China is narrowing its cost advantage in furfural solvent output as Shandong Crownchem Industries Co. Ltd leverages captive corncob feedstock to anchor regional supply chains. Pennakem LLC sustains technical leadership in high-purity solvent grades for pharmaceutical extraction. Silvateam SpA differentiates through vertical integration from tannin co-products into specialty furfural derivatives.
Furfural solvent comprises a heterocyclic aldehyde derived from pentosan-rich agricultural residues, typically refined to 98.5% minimum purity for industrial use as a selective extraction medium and chemical reaction vehicle. Industrial solvents dominate volume throughput, while chemical intermediates capture expanding margin pools as downstream furfuryl alcohol and tetrahydrofuran producers seek bio-based feedstock security. Pharmaceutical applications lead growth within the application dimension, driven by FDA and EMA purity requirements for active pharmaceutical ingredient extraction protocols.
EPA oversight of volatile organic compound emissions shapes formulation substitution patterns in North American coatings, while REACH registration thresholds in Europe restrict non-compliant import volumes. China's MEE enforces wastewater discharge limits on furfural refineries, elevating capital requirements for new entrants. Stakeholders must monitor regulatory divergence between bio-based content mandates and traditional solvent performance specifications when allocating R&D budgets across regional product portfolios.
Market Dynamics
Shandong Province's captive corncob supply chains are compressing production costs and forcing non-integrated refiners into specialty grades or exit. This concentration dynamic is redrawing competitive boundaries between commodity and high-purity solvent tiers.
Growth Catalysts
- REACH bio-based mandates:ECHA registration thresholds for renewable solvent content are pulling agrochemical formulators toward furfural-derived extraction media in pesticide delivery systems.
- Pharmaceutical purity protocols:FDA and EMA specifications for active pharmaceutical ingredient extraction are elevating demand for refined furfural grades above 99.5% purity.
- Corncob residue valorization:Agricultural waste processing clusters in China's corn belt are securing pentosan feedstock at scale for integrated furfural-to-derivatives complexes.
Market Restraints
- Feedstock concentration risk:Over 60% of global pentosan supply chains originate within Shandong Province, creating single-point vulnerability for non-Chinese buyers.
- Petroleum solvent substitution:N-methyl-2-pyrrolidone and dimethylformamide retain cost advantages in high-volume coating applications where bio-content certification is not mandatory.
- Capital intensity barriers:MEE wastewater discharge compliance requires membrane filtration and anaerobic digestion systems that elevate entry costs for new refining capacity.
Strategic Opportunities
- Brazilian agrochemical expansion:ANVISA registration pathways for bio-based pesticide formulations are opening dedicated demand for furfural-derived carriers in Latin America's largest crop protection market.
- EU Green Deal procurement:Public sector solvent purchasing mandates with renewable content floors are creating preferential contracting channels for certified bio-based suppliers.
- Tetrahydrofuran feedstock security:Downstream polymer producers are seeking long-term offtake agreements with furfural refiners to hedge against petroleum-based butanediol volatility.
Industry Challenges
- Skilled operator scarcity:Furfural refining requires expertise in heterocyclic chemistry and continuous distillation that outpaces vocational training pipeline output in emerging production regions.
- Multi-jurisdiction certification lag:Simultaneous FDA, EMA, and NMPA pharmaceutical-grade approvals demand 18-24 month documentation cycles that delay revenue recognition for new entrants.
- Legacy equipment retrofit costs:Batch reactor installations from prior decades lack instrumentation for real-time purity monitoring required by current buyer specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Furfural Solvent Market |
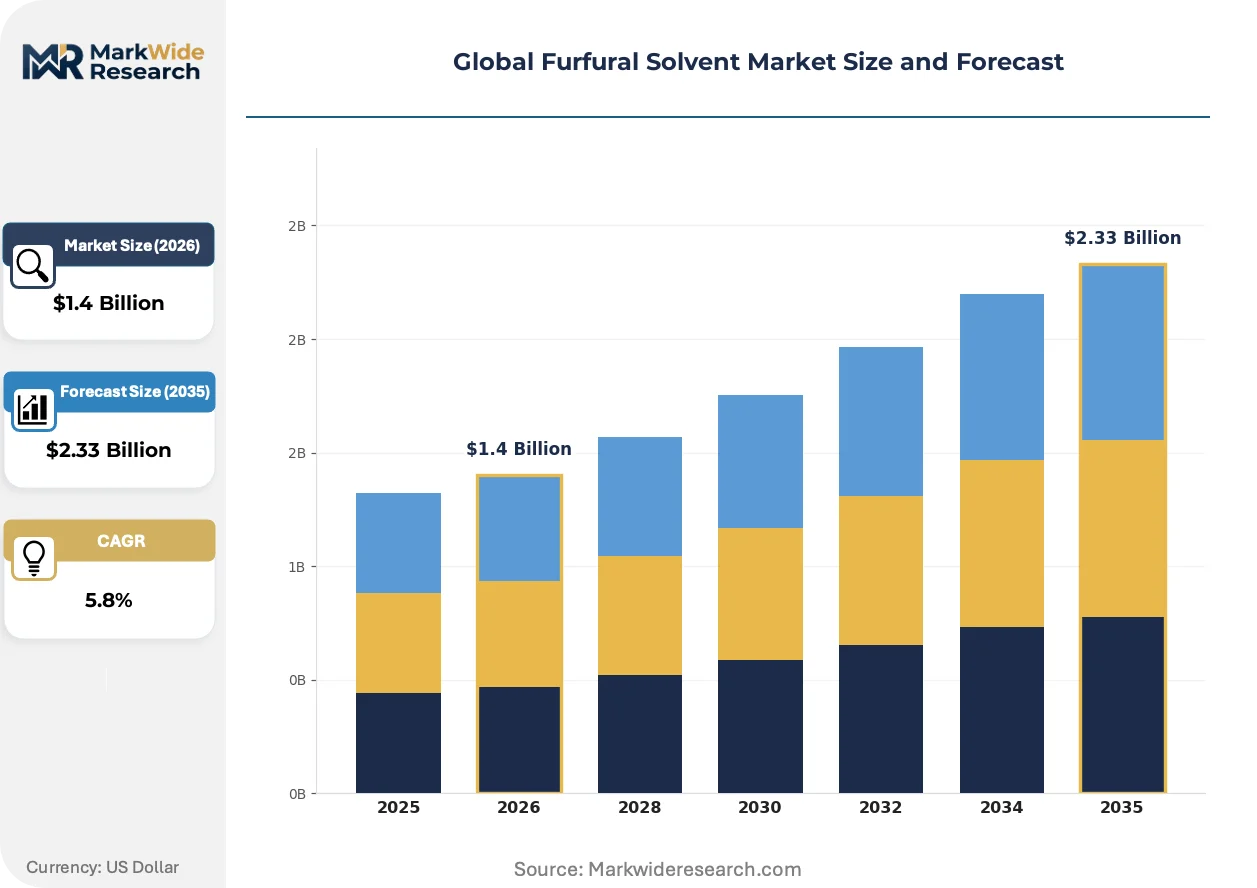
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.33 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Solvents, Solvent Extracts, Chemical Intermediates, Fuel Additives Application: Coatings, Adhesives, Agrochemicals, Pharmaceuticals End User: Automotive, Consumer Goods, Construction, Textile Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesale |
| Companies Covered | Pennakem LLC, Xing Tai Chunlei Furfural Alcohol Ltd, Silvateam SpA, Illovo Sugar Africa, Shandong Crownchem Industries Co. Ltd, Central Romana Corporation, Hongye Holding Group Corporation Ltd, Transfuran Chemicals, Linzi Organic Chemical Inc. Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Furfural Solvent Market Emerging Trajectories
Process intensification and regulatory chemistry are rewriting production economics. Refiners are abandoning conventional batch methods for continuous systems that cut energy inputs and satisfy tightening purity thresholds.
Membrane-assisted pervaporation technology is migrating from laboratory demonstration to commercial deployment in Shandong refining complexes. Coating manufacturers in Japan and South Korea are qualifying pervaporation-refined grades for automotive clearcoat formulations. This shift is compressing the margin gap between commodity furfural and pharmaceutical-grade product tiers.
China's MEE enforcement of dual carbon goals is tightening wastewater discharge limits on furfural refineries. Facilities lacking anaerobic digestion and biogas recovery systems face operating suspensions during inspection periods. Integrated producers with captive bioenergy generation are absorbing compliance costs while non-integrated competitors retreat from volume markets.
Long-term offtake contracting is displacing spot purchasing among pharmaceutical extractors. API manufacturers in India and Germany are locking three to five year supply agreements directly with refiners, bypassing traditional chemical distributor networks. This channel compression is most visible in tetrahydrofuran precursor procurement, where polymer producers seek feedstock security against petroleum price volatility.
Global Furfural Solvent Market Segmentation
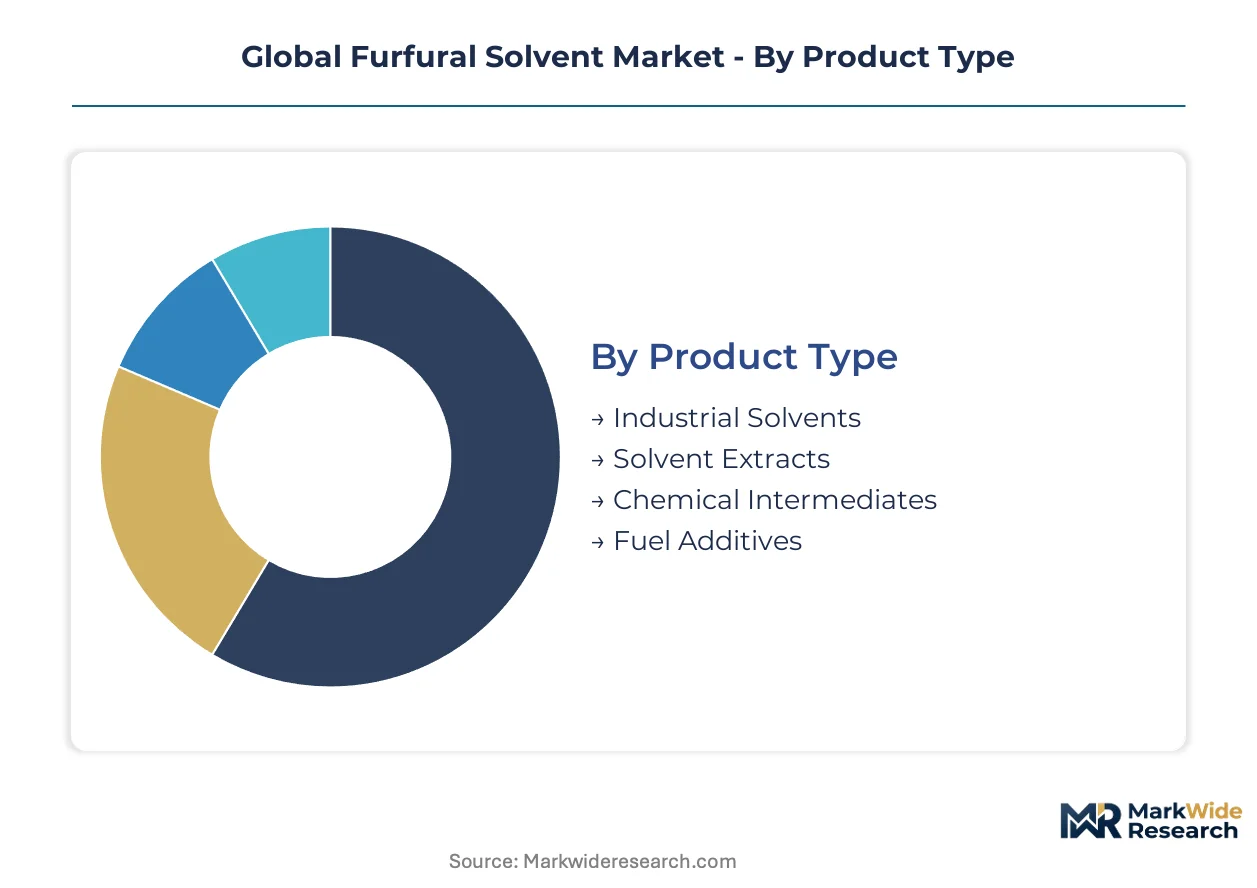
Furfural solvent segmentation reveals how feedstock economics and regulatory chemistry split demand across purity grades and end-use specifications. Each dimension carries distinct margin profiles and certification requirements that reshape supplier positioning.
Product Type:
Use-case spectrum spans commodity extraction media to high-purity pharmaceutical reaction vehicles, with each tier demanding different pentosan processing depth and distillation intensity.
- Industrial Solvents:Refined to 98.5% minimum purity, these grades serve as selective extraction media for lubricating oil refining and resin production. Demand concentrates in Shandong Province coating clusters where EPA VOC regulations in the US and REACH thresholds in Europe are forcing formulators toward bio-based alternatives. Capital intensity for wastewater compliance is compressing margins for non-integrated refiners.
- Chemical Intermediates:These grades feed downstream furfuryl alcohol and tetrahydrofuran production, capturing expanding margin pools as polymer producers seek petroleum feedstock hedges. German and Indian API manufacturers are locking three to five year offtake agreements directly with refiners, bypassing traditional distributor networks to secure supply against butanediol price volatility.
- Solvent Extracts:Specialized fractions for agricultural residue processing and lignin separation applications.
- Fuel Additives:Niche grades for biofuel oxygenation and combustion modifier formulations.
The dominant share belongs to Industrial Solvents, while Chemical Intermediates is closing the gap fastest.
Application:
Margin stratification follows regulatory stringency, with pharmaceutical extraction protocols commanding certification premiums that commodity coating formulations cannot support.
- Pharmaceuticals:FDA and EMA specifications for active pharmaceutical ingredient extraction mandate refined grades above 99.5% purity. Indian and German API manufacturers are driving demand concentration through long-term contracting, with 18-24 month multi-jurisdiction approval cycles creating barriers for new supplier entry. Membrane-assisted pervaporation technology is migrating from laboratory to commercial deployment to meet these thresholds.
- Agrochemicals:ANVISA registration pathways in Brazil are opening dedicated demand for furfural-derived carriers in pesticide delivery systems. REACH bio-based mandates from ECHA are pulling European formulators toward renewable extraction media, with pentosan feedstock security becoming a procurement priority for integrated agrochemical multinationals.
- Coatings:Automotive clearcoat formulations in Japan and South Korea are qualifying pervaporation-refined grades, though petroleum solvent substitution remains cost-competitive where bio-content certification is not mandatory.
- Adhesives:Industrial bonding applications requiring selective solvent properties for synthetic rubber and resin systems.
Pharmaceuticals commands the steepest expansion trajectory, while Agrochemicals is gaining share fastest in volume terms.
End User:
Customer concentration patterns reflect how downstream industry structure determines procurement power and specification bargaining.
- Automotive:Clearcoat and adhesive applications in Japanese and South Korean manufacturing clusters are qualifying higher-purity grades for VOC compliance. Tier-1 suppliers are consolidating supplier lists to refiners with integrated pervaporation capability.
- Construction:Coating and sealant applications with variable bio-content requirements depending on public procurement mandates.
- Consumer Goods:Packaging adhesive and coating applications with emerging sustainability specifications.
- Textile:Dye carrier and finishing agent applications in specialty fabric processing.
Automotive leads procurement sophistication, while Construction is expanding most quickly on emerging market infrastructure buildout.
Distribution Channel:
Channel compression is accelerating as downstream polymer and pharmaceutical producers seek direct refiner relationships to manage feedstock security.
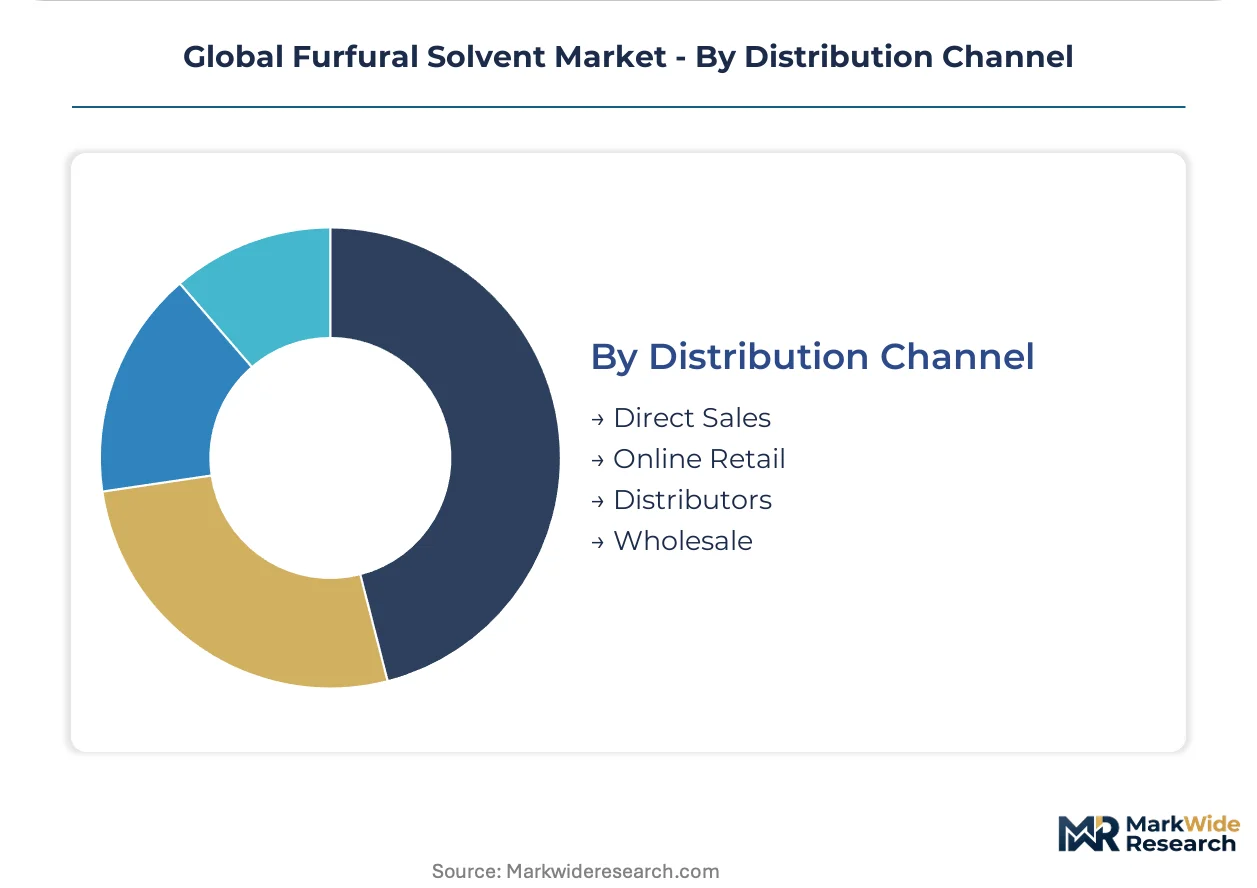
- Direct Sales:Long-term offtake contracting is displacing spot purchasing among tetrahydrofuran precursor buyers and API extractors. This channel captures the highest-margin pharmaceutical and chemical intermediate grades where supply security outweighs price sensitivity.
- Distributors:Traditional chemical distribution networks retain relevance for smaller coating and adhesive formulators lacking volume to justify direct refner negotiations.
- Wholesale:Volume aggregation for industrial solvent grades serving fragmented downstream users.
- Online Retail:Emerging channel for specialty grade samples and small-batch procurement.
Direct Sales holds the dominant share, though Distributors retain critical mass in fragmented end-use segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography: pharmaceutical extractors in Germany and India prioritize purity-certified grades, while coating formulators in Japan and South Korea emphasize VOC compliance, and agrochemical blenders in Brazil seek ANVISA-registered bio-based carriers.
China
Shandong Province hosts the densest concentration of furfural refining capacity worldwide, with integrated corncob-to-solvent complexes supplying coating manufacturers across East Asia. MEE enforcement of dual carbon goals and wastewater discharge limits is forcing facility upgrades toward anaerobic digestion and biogas recovery systems. Qingdao and Zibo industrial clusters are consolidating output as smaller refiners exit under environmental compliance pressure.
Germany
API manufacturers in Ludwigshafen and Leverkusen are locking multi-year offtake agreements directly with refiners to secure tetrahydrofuran precursor supply against petroleum feedstock volatility. ECHA REACH registration thresholds for renewable solvent content are pulling formulators toward bio-based extraction media. The Rhineland chemical corridor is becoming the procurement center for pharmaceutical-grade furfural across the European Union.
United States
EPA oversight of volatile organic compound emissions is accelerating substitution of petroleum solvents in North American coatings, though cost parity remains uneven outside mandated procurement zones. Pennakem LLC maintains technical leadership in high-purity grades for pharmaceutical extraction. Texas and Louisiana petrochemical corridors are seeing selective adoption for lubricating oil refining applications.
Brazil
ANVISA registration pathways for bio-based pesticide formulations are opening dedicated demand channels for furfural-derived carriers in Latin America's largest crop protection market. São Paulo and Campinas agrochemical clusters are qualifying renewable extraction media for integrated delivery systems. Brazilian formulators are prioritizing feedstock security from Shandong suppliers amid supply chain concentration risks.
India
API manufacturers in Hyderabad and Mumbai are driving demand concentration through three to five year direct contracting with refiners, bypassing traditional chemical distributor networks. CDSCO alignment with FDA and EMA purity specifications is elevating import requirements for grades above 99.5% purity. The Maharashtra-Gujarat pharmaceutical belt is becoming the fastest-growing consumption node for extraction-grade material.
Global Furfural Solvent Market Vendor Landscape
Capability concentration sits with one tier; scale advantage sits with another. The market structures around a tight oligopoly of integrated refiners controlling captive feedstock and a fragmented periphery of specialty-grade specialists. Three archetypes dominate: Shandong-based corncob-integrated producers, European pharmaceutical-purity specialists, and Latin American agrochemical-focused blenders. Competitive moves center on backward integration into agricultural residue supply chains and membrane-assisted pervaporation technology licensing.
Among Chinese integrated producers, Shandong Crownchem Industries Co. Ltd exemplifies the captive-feedstock archetype, while Xing Tai Chunlei Furfural Alcohol Ltd occupies a position within the regional derivatives complex. Pennakem LLC represents the high-purity specialist tier serving pharmaceutical extraction protocols. These three anchors illustrate how geographic feedstock access and end-use certification requirements stratify competitive positioning across commodity and premium-grade market tiers.
| Leading Market Players |
|---|
| Pennakem LLC |
| Xing Tai Chunlei Furfural Alcohol Ltd |
| Silvateam SpA |
| Illovo Sugar Africa |
| Shandong Crownchem Industries Co. Ltd |
| Central Romana Corporation |
| Hongye Holding Group Corporation Ltd |
| Transfuran Chemicals |
| Linzi Organic Chemical Inc. Ltd |
| Others |
Supply Flow & Price Mechanics
Qingdao-Zibo freight corridors carry pentosan feedstock from Shandong corncob processing clusters to East Asian coating manufacturers, with logistics cost dynamics amplifying the pricing power of integrated refiners while forcing non-integrated competitors into specialty grade premiums or market exit.
Pricing Analysis
Geographic price spreads between Shandong commodity grades and European pharmaceutical-certified material reflect contract-based long-term offtake structures for high-purity tiers against spot-market volatility in industrial solvents. Certification level—REACH registration, FDA pharmaceutical-grade approval, ANVISA bio-based registration—drives the steepest price differentiation alongside volume scale commitments. Cost compression in commodity industrial solvents is intensifying because MEE wastewater compliance investments elevate fixed costs for smaller refiners. Coating formulators in fragmented downstream segments exhibit highest price sensitivity, while API manufacturers in Germany and India accept premium pricing for supply security.
Supply Chain Analysis
Tariff exposure between China and key importing regions dominates supply chain risk assessment for non-integrated buyers dependent on Shandong-origin material. Production concentrates in China, with secondary refining capacity in Germany and Brazil serving regional pharmaceutical and agrochemical demand. Raw material dependencies center on corncob pentosan supply, membrane filtration equipment for pervaporation refining, and anaerobic digestion systems for MEE compliance. Single-source vulnerability from Shandong Province feedstock concentration creates procurement fragility for buyers lacking long-term offtake agreements. Distribution runs through direct refiner relationships for chemical intermediate and pharmaceutical grades, while traditional chemical distributors retain relevance for smaller coating and adhesive formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
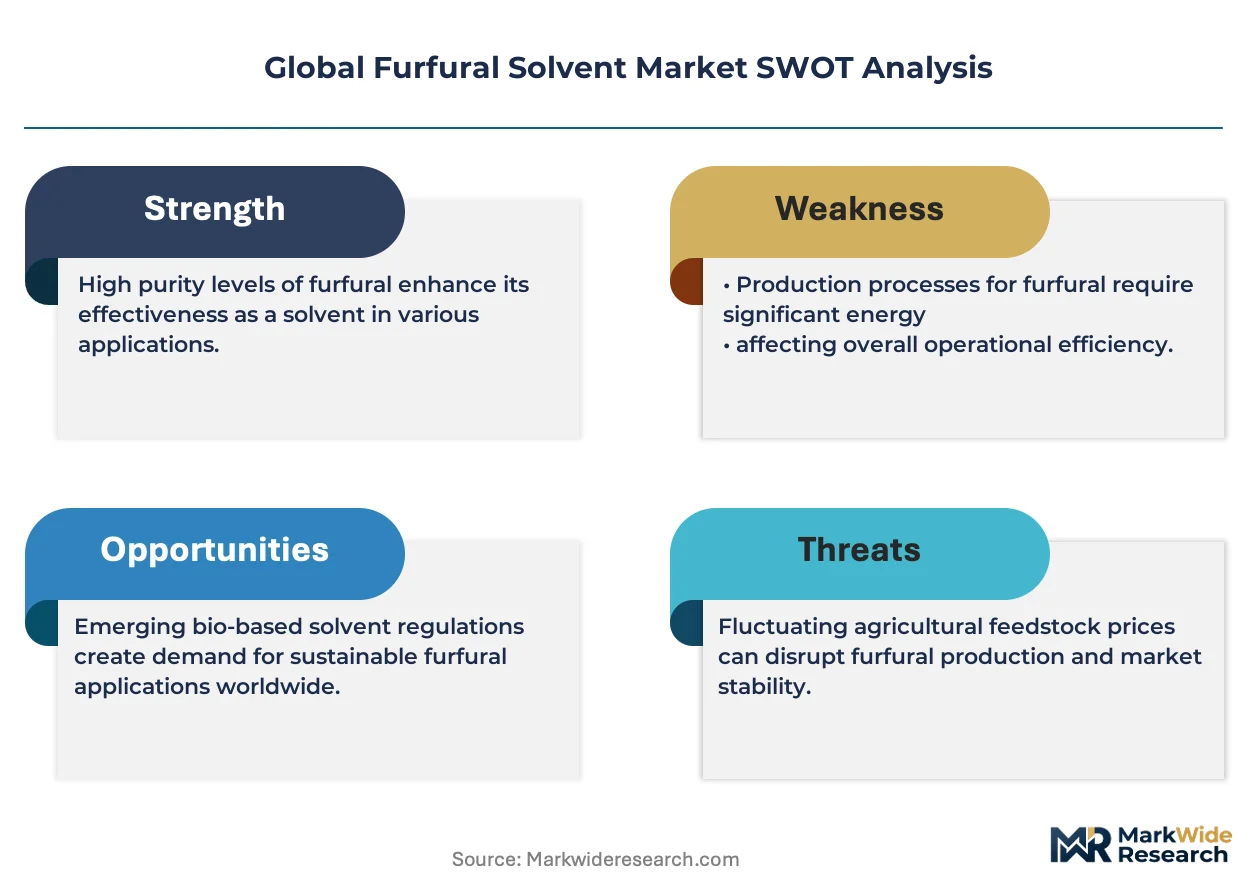
This market functions as a defensive-moat environment where regulatory entrenchment—18-24 month multi-jurisdiction pharmaceutical approval cycles and REACH registration thresholds—protects incumbent positioning against rapid competitive displacement.
For Market Incumbents: Harden captive feedstock security through backward integration into agricultural residue supply chains in Shandong and Hebei provinces, while accelerating membrane-assisted pervaporation technology licensing to capture margin compression between commodity and pharmaceutical grades. Emerging Brazilian agrochemical specialists with ANVISA registration capabilities represent the most credible entrant threat, requiring preemptive long-term contracting with São Paulo formulators to lock channel access.
For New Entrants and Emerging Players: Mid-volume coating formulators in Southeast Asia seeking REACH-compliant bio-based alternatives represent the most penetrable entry point, as these buyers lack scale for direct Shandong negotiations but face VOC regulatory pressure from domestic environmental agencies. ANVISA-registered bio-based pesticide carriers in Brazil's Campinas agrochemical cluster offer a second white-space target, with technical partnership with established membrane pervaporation equipment suppliers as the critical go-to-market angle.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with underutilized furfural refining assets lacking pharmaceutical-grade certification infrastructure. The five-to-ten year viability window favors integrated producers with captive corncob supply and anaerobic digestion capabilities over non-integrated commodity refiners facing MEE compliance pressure. Watch for CDSCO-FDA alignment acceleration in India as the signal indicating inflection toward direct contracting displacement of distributor networks.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Corncob Supply | Shandong refiners with captive agricultural residue access compress production costs below non-integrated competitors. |
| Membrane Pervaporation Technology Licensing | Japanese and South Korean automotive clearcoat manufacturers qualify pervaporation-refined grades for VOC compliance. |
| Long-term Supply Agreement with API Manufacturers | German and Indian pharmaceutical extractors bypass distributor networks to secure tetrahydrofuran precursor supply. |
| ANVISA Bio-based Registration Investment | Brazilian agrochemical formulators open dedicated demand channels for renewable pesticide delivery carriers. |
| Anaerobic Digestion System Deployment | China's MEE enforcement suspends operations at refineries lacking biogas recovery during inspection periods. |
Methodological Framework
Desk research of customs trade databases, ECHA REACH registration filings, and SEC chemical sector disclosures preceded structured interviews with Shandong refinery plant managers, German API procurement directors, Brazilian agrochemical formulators, and membrane pervaporation technology suppliers. Primary fieldwork combined with secondary validation across FDA 483 inspection records, CDSCO import certification data, and ANVISA bio-based product registries. Bottom-up capacity modeling and top-down demand triangulation anchored volume estimates.
Assumptions held MEE enforcement intensity and REACH bio-based mandate timelines fixed across the analysis window, while petroleum feedstock price volatility and Brazilian agricultural commodity cycles varied in sensitivity scenarios. Segmentation dimensions modeled include purity grade tier, end-use application, and regional regulatory cluster. CAGRs derived from production capacity buildout trajectories and downstream offtake contracting velocity, with membrane pervaporation adoption curves and pharmaceutical-grade certification pipeline throughput as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in corn agricultural commodity pricing, freight rate volatility on Asia-Europe routes, or dual carbon goal enforcement intensity in China would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory compliance cost pass-through and substitution elasticity in coating applications. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
Global Ink Solvents Market
Solvents
Aprotic Solvents Market
Solvents
Para Nitrochlorobenzene Market
Solvents
Solvent Green 7 Market
Solvents
3-Methyl-3-Penten-2-One (3M3P) Market
Solvents
1,2-Ethanedithiol Market
Solvents
Xylene Market
Solvents
Pharmaceutical Solvent Market
Solvents
Piperylene Market
Solvents
Hexylene Glycol Market
Solvents
Benzene-Toluene-Xylene (BTX) Market
Solvents
Acetone Market
Solvents
Methyl Acetate Market
Solvents
Solvent Cement Market
Solvents
Citrus Solvents Market
Solvents
Dihydromyrcenol Market