
 Potassium Chloride Market | 2026-2036
Potassium Chloride Market Size, Share, and Industry Trends Forecast 2026-2036
Potassium Chloride Market Analysis
Premium-grade fertilizer specifications is unwinding legacy commodity pricing across the potash value chain. Nutrien Ltd. leverages its integrated mine-to-farm network across Saskatchewan to control delivery timelines into North American corn belts. The Mosaic Company anchors its position through phosphate-potash co-location that sustains blending flexibility for NPK compounders. Uralkali competes on deep vertical shaft mining economics that dominate cost curves for standard muriate grades.
Potassium chloride is an alkali metal halide salt with formula KCl, typically refined to 60-62% K2O equivalent for agricultural use through solution mining or conventional underground extraction followed by flotation and crystallization. Its primary purpose is to correct potassium deficiency in soils, with pharmaceutical and food-grade variants requiring additional purification to meet USP and FCC purity thresholds. Granular product leads volume due to its compatibility with bulk blending equipment and controlled-release coating systems, while powder grades capture margin pools in chemical manufacturing and oilfield drilling fluids. Liquid potassium chloride is displacing solid forms in fertigation systems across high-value horticulture, though tablets remain a mature, low-growth channel serving clinical electrolyte replacement protocols.
EPA water quality standards and OSHA workplace exposure limits govern handling protocols for bulk KCl distribution in the United States, while REACH registration requirements in Europe restrict impurity profiles for imported material. China's GB standards and Ministry of Agriculture fertilizer registration rules shape product entry into the world's largest consumption market. Stakeholders must monitor how carbon border adjustment mechanisms and evolving low-carbon mining certifications will restructure competitive access between conventional and solution-mined supply sources.
Market Dynamics
Solution mining economics are compressing extraction costs while REACH and EU Green Deal compliance requirements force impurity threshold reductions across imported fertilizer-grade material. State-backed inventory programs in China tighten spot market liquidity, amplifying price volatility for standard muriate grades.
Growth Catalysts
- Fertigation system adoption:Liquid potassium chloride formulations penetrate high-value horticulture operations in Spain and the Netherlands, displacing granular product in drip-irrigation infrastructure.
- REACH registration tiers:ECHA's differentiated compliance pathways for fertilizer-grade versus technical-grade KCl create margin expansion for purification-capable producers serving pharmaceutical and food additive channels.
- Soil potassium deficiency mapping:Brazil's agricultural extension services deploy satellite-guided soil testing that identifies untreated acreage, expanding addressable demand for corrective KCl application in soybean-corn rotations.
Market Restraints
- Natural gas price volatility:Solution mining operations in Saskatchewan and the Ural region face energy input cost swings that erode margin predictability for standard-grade crystallization.
- Supply concentration in Belarus and Russia:Sanctions-linked export disruptions from state-controlled potash producers expose buyers to cargo rerouting delays and letter-of-credit complications.
- Sulfate of potash substitution:Chloride-sensitive crops in California's Central Valley and Florida's citrus belt shift toward SOP where irrigation water salinity already stresses root systems.
Strategic Opportunities
- Underpenetrated African markets:Ethiopia and Tanzania lack domestic blending infrastructure, creating first-mover advantage for granular KCl suppliers establishing bulk terminal partnerships.
- Controlled-release coating convergence:Polymer-sulfur hybrid coatings applied to KCl granules enable precision agriculture platforms in Australia's wheat belt to reduce application frequency.
- EU Carbon Border Adjustment Mechanism:CBAM phase-in rewards solution-mined KCl with lower embodied carbon versus conventional shaft-mined supply, reshaping import competitiveness for European compounders.
Industry Challenges
- Solution mining brine chemistry expertise:Shallow domestic talent pools in lithium-potash co-extraction regions constrain operational ramp timelines for greenfield projects.
- Dual certification timelines:Simultaneous USP and FCC qualification for pharmaceutical-grade KCl extends quality validation cycles, freezing working capital for 18-24 months.
- Legacy bulk blending equipment incompatibility:Powder-grade KCl handling systems at Midwestern US cooperatives require capital retrofit to accommodate anti-caking coated granules without segregation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Potassium Chloride Market |
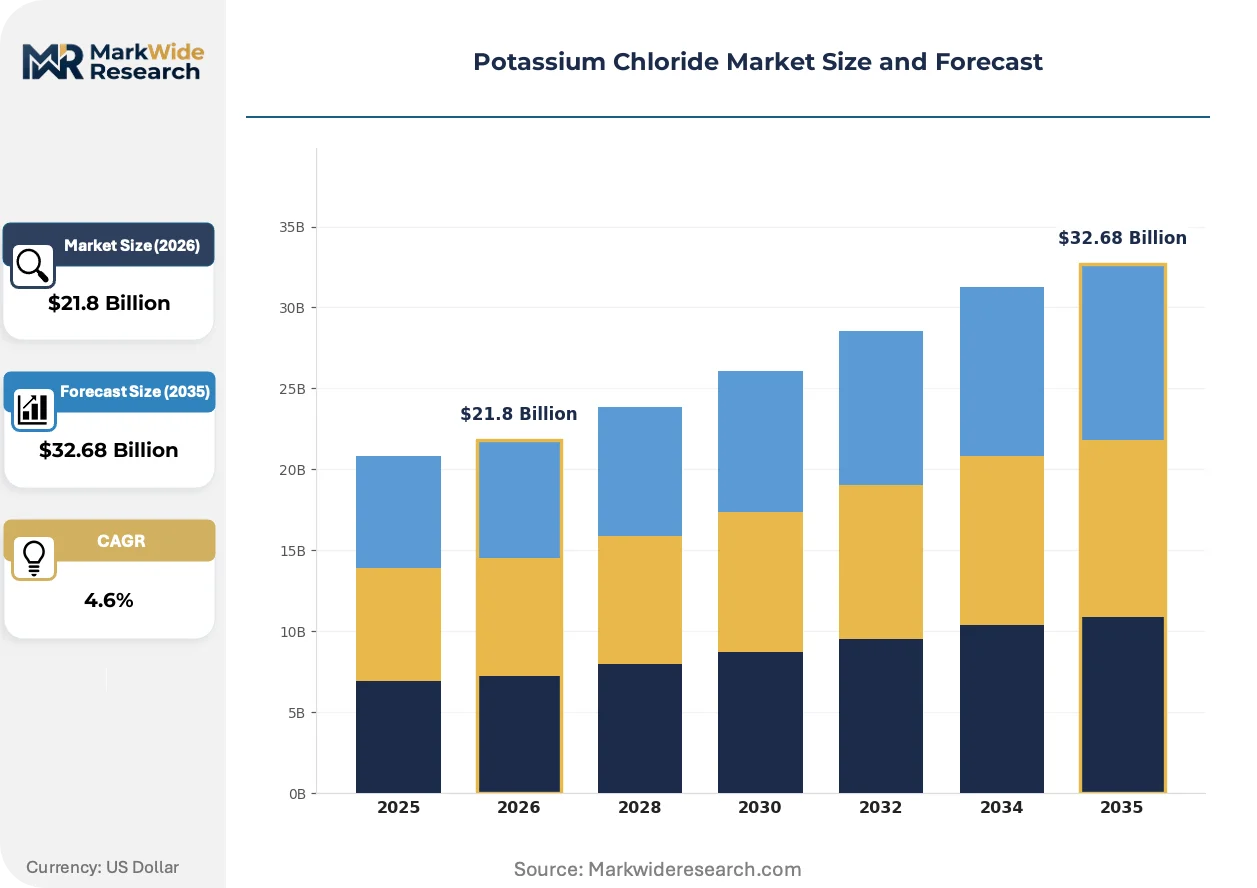
| Market Size in 2026 | $21.8 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granular, Powder, Liquid, Tablets End Use Industry: Agriculture, Pharmaceuticals, Food Processing, Water Treatment Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers Application: Fertilizers, Food Additives, Drug Formulation, Chemical Manufacturing |
| Companies Covered | Nutrien Ltd., The Mosaic Company, Uralkali, Belaruskali, ICL Group Ltd., Arab Potash Company, Sinofert Holdings Limited, Qinghai Salt Lake Industry Co., Ltd., Compass Minerals International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Potassium Chloride Market Emerging Trajectories
Extraction technology maturation and regulatory chemistry specifications are rewiring competitive advantage away from raw ore access toward purification capability and carbon-accounted supply chains.
Membrane filtration pre-concentration is supplanting traditional solar evaporation in solution mining circuits. Chilean lithium-potash co-producers deploy nanofiltration skids that cut evaporation pond footprints by half. This compression enables year-round production in high-altitude basins with seasonal freeze constraints.
REACH Annex XVII restrictions on cadmium and heavy metal content in fertilizers entered full enforcement across EU member states in 2026. ECHA compliance audits now reject KCl shipments exceeding 60 mg/kg cadmium without derogation. Baltic state importers have pivoted toward Saskatchewan and Jordanian supply with certified low-impurity profiles.
Compounders in Germany's Rhine-Ruhr corridor unbundle blending services from product supply, selling formulation expertise separately from KCl procurement. This decoupling lets farm cooperatives source muriate directly from mine sites while retaining local agronomic support. The model spreads through Benelux distribution networks where logistics optimization outweighs brand loyalty.
Potassium Chloride Market Segmentation
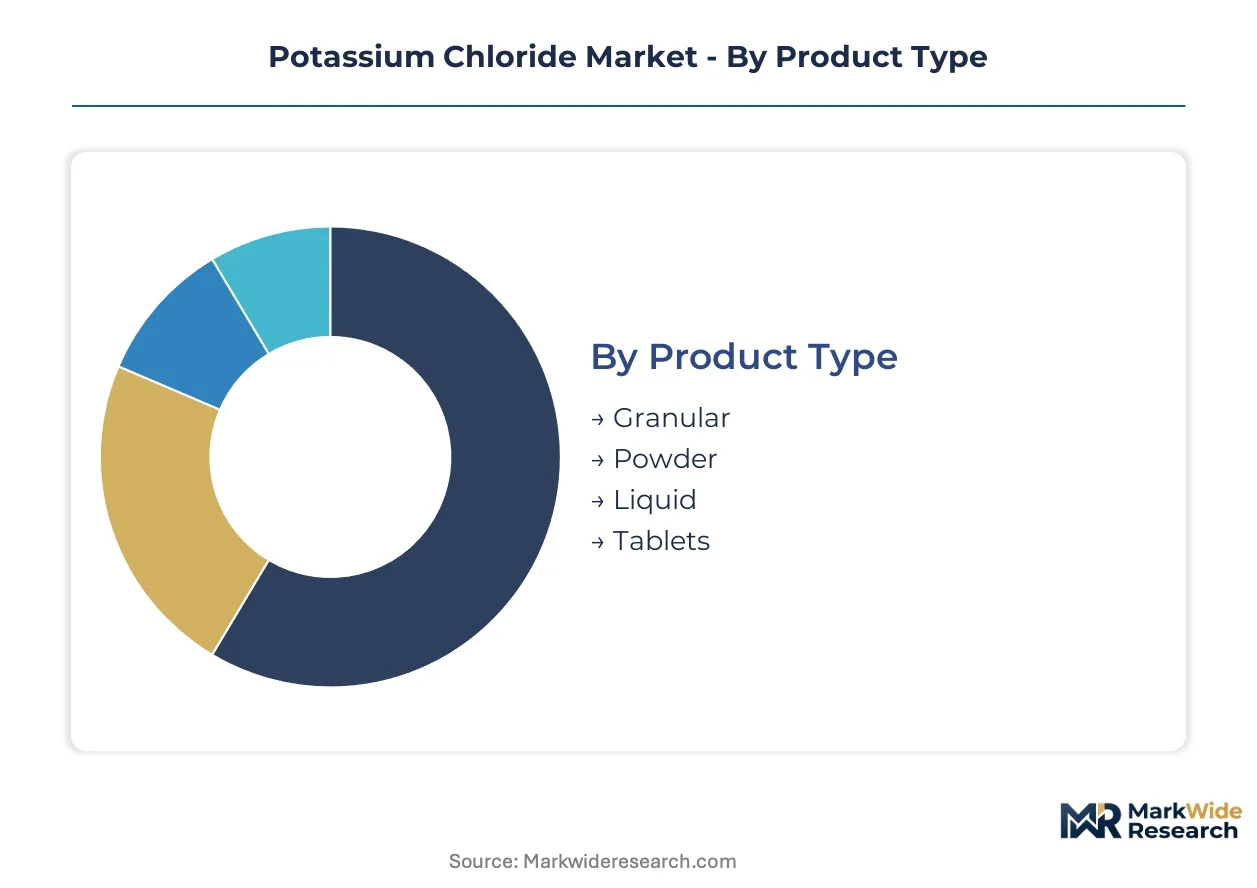
Potassium chloride markets fragment across purity grades and handling requirements that determine regulatory pathways and margin capture. Segmentation reveals where solution-mined supply competes against refined pharmaceutical grades, and which channels concentrate procurement power.
Product Type:
REACH Annex XVII cadmium thresholds and USP purity specifications create divergent compliance burdens across physical forms, with fertilizer-grade granules facing lighter metal content scrutiny than pharmaceutical tablets.
- Granular:Refined to 60-62% K2O equivalent through flotation and crystallization, granular product dominates bulk blending infrastructure across North American corn belts and Brazilian soybean regions. Compatibility with controlled-release coating systems and mechanical spreader equipment sustains volume concentration in mechanized agriculture.
- Powder:Milled to sub-100 micron specifications, powder grades serve chemical manufacturing and oilfield drilling fluid applications where rapid dissolution kinetics matter. Anti-caking additives become essential for Midwestern US cooperative handling systems originally designed for crystalline inputs.
- Liquid:Pre-dissolved KCl formulations penetrate fertigation networks in Spain's Almería greenhouse complexes and the Netherlands' precision horticulture sector.
- Tablets:USP-grade compressed forms serve clinical electrolyte replacement protocols with extended quality validation cycles.
Established volume favors Granular; emerging adoption favors Liquid.
End Use Industry:
Application-specific purity thresholds stratify procurement across FCC food-grade certification, USP pharmaceutical compliance, and agricultural-grade tolerance bands.
- Agriculture:Fertilizer-grade consumption anchors global volume, with potassium deficiency correction driving corrective application in Brazil's Cerrado and China's Northeast Plain. Satellite-guided soil testing expands addressable acreage in untreated soybean-corn rotations.
- Pharmaceuticals:USP and simultaneous FCC qualification extends quality validation cycles, freezing working capital for purification-capable producers serving parenteral and oral electrolyte formulations.
- Food Processing:FCC-grade KCl substitutes for sodium chloride in reduced-sodium processed foods, with EFSA and FDA GRAS status governing additive thresholds.
- Water Treatment:Regeneration salt for ion exchange systems competes on bulk logistics rather than purity premiums.
Agriculture commands absolute tonnage; Pharmaceuticals captures steepest margin expansion.
Distribution Channel:
Channel selection reflects buyer scale and formulation complexity, with compounders unbundling blending services from product supply in European Rhine-Ruhr corridors.
- Direct Sales:Mine-to-farm contracts and long-term offtake agreements dominate Saskatchewan and Ural region supply into North American and Asian markets. Volume concentration favors buyers with terminal storage and rail siding access.
- Distributors:Regional agronomic service providers in Germany's Benelux networks sell formulation expertise separately from KCl procurement, letting cooperatives source muriate directly while retaining local technical support.
- Wholesalers:Bulk terminal partnerships in underpenetrated African markets create first-mover infrastructure for Ethiopian and Tanzanian blending operations.
- Online Retail:Small-scale horticulture and hobby farming segments access bagged product through e-commerce platforms with limited volume impact.
Direct Sales lock in base volume; Distributors gain share where agronomic advice separates from commodity supply.
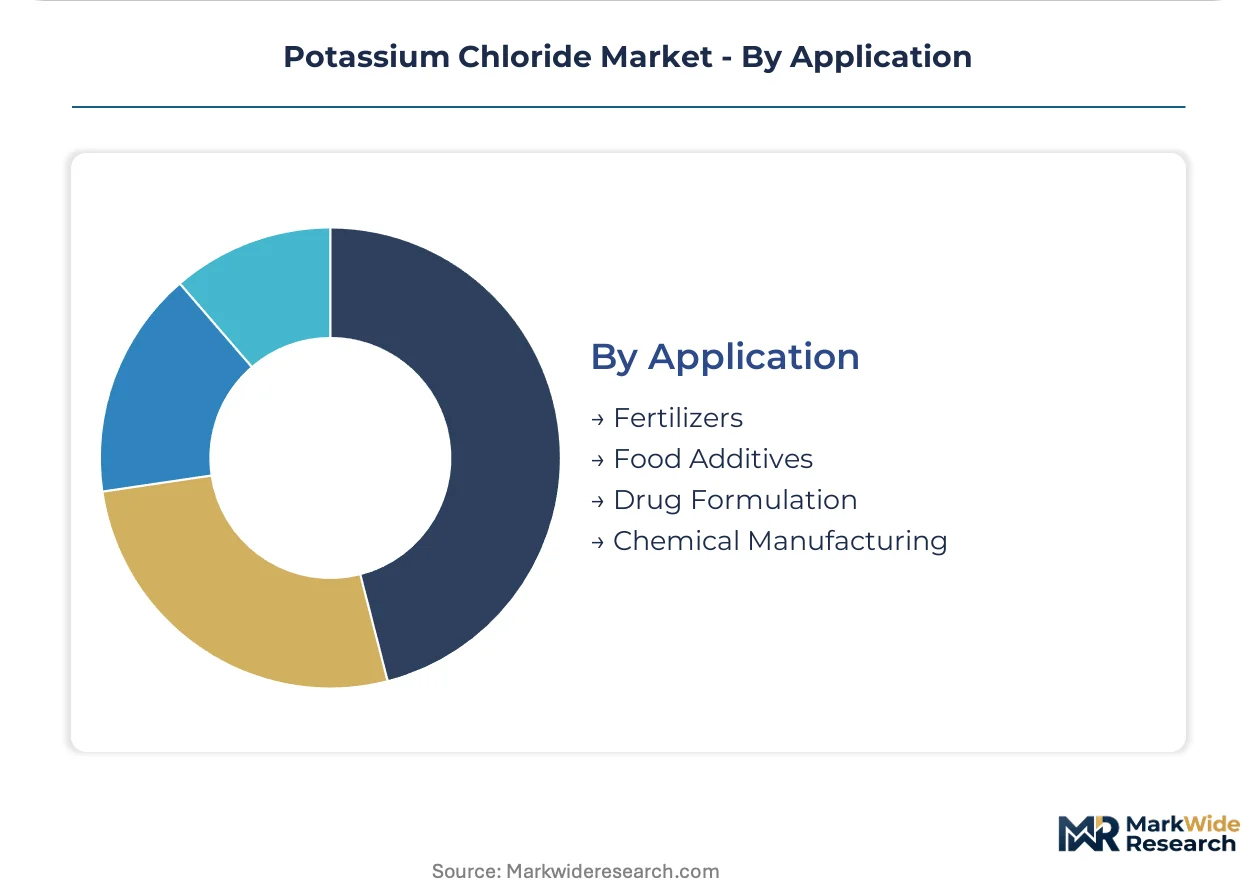
Application:
Functional requirements determine whether KCl serves as a bulk nutrient input, a precision additive, or a process chemical with distinct certification demands.
- Fertilizers:Muriate of potash dominates NPK compounding where chloride tolerance permits, with polymer-sulfur hybrid coatings enabling reduced application frequency in Australia's wheat belt. Sulfate of potash substitution pressures chloride-sensitive crop segments in California and Florida.
- Drug Formulation:Parenteral and oral electrolyte replacement protocols demand USP-grade material with extended validation timelines and dual-certification requirements.
- Food Additives:Sodium reduction trends in processed foods drive FCC-grade demand, with flavor masking technologies addressing potassium's bitter aftertaste.
- Chemical Manufacturing:Potassium source for specialty reagents and industrial processes competes on delivered cost rather than certification premiums.
Fertilizers absorb production scale; Drug Formulation extracts purification premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Brazil and India's agricultural heartlands exhibit acute price sensitivity to muriate of potash fluctuations, while European compounders absorbing REACH compliance costs show markedly inelastic demand for certified low-impurity grades.
China
State-backed inventory programs in Qinghai and Xinjiang tighten spot market liquidity for domestic potash production. GB standards and Ministry of Agriculture fertilizer registration rules shape product entry protocols for imported material. The Northeast Plain around Harbin anchors consumption clusters where satellite-guided soil testing expands corrective KCl application in soybean-corn rotations.
United States
Corn belt cooperatives in Iowa and Illinois drive bulk blending demand for granular product compatible with mechanical spreader equipment. EPA water quality standards and OSHA workplace exposure limits govern handling protocols for bulk KCl distribution. The Saskatchewan-to-Midwest rail corridor concentrates procurement power among buyers with terminal storage and siding access.
Brazil
Soybean-corn rotations in Mato Grosso and Goiás generate corrective potassium application at scale. Agricultural extension services deploy satellite-guided soil testing that identifies untreated acreage. The Santos port complex handles import volumes where price volatility directly shapes farm-gate purchasing decisions.
Germany
Rhine-Ruhr corridor compounders unbundle blending services from product supply, selling formulation expertise separately from KCl procurement. ECHA compliance audits enforce REACH Annex XVII cadmium thresholds below 60 mg/kg without derogation. Benelux distribution networks replicate this model where logistics optimization outweighs brand loyalty.
Canada
Saskatchewan's solution mining operations supply North American corn belts through integrated mine-to-farm networks. Carbon border adjustment mechanisms reward lower embodied carbon versus conventional shaft-mined supply. The province's vertical shaft and solution mining economics dominate cost curves for standard muriate grades.
Potassium Chloride Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the potassium chloride value chain. The market structure concentrates around integrated miners with captive ore access and regional purifiers serving pharmaceutical and food-grade certification tiers. Three archetypes dominate: Saskatchewan-based solution miners with rail-linked distribution, Ural and Belarusian shaft miners competing on extraction economics, and Jordanian-Israeli solar evaporation specialists. Competitive moves center on backward integration into blending infrastructure and purification capacity expansion for REACH-compliant grades.
Within the integrated mining tier, Nutrien Ltd. and The Mosaic Company occupy positions shaped by their geographic concentration in North American potash basins. Uralkali anchors the cost-driven segment with Ural region shaft mining operations. These three exemplify how ore quality, energy access, and logistics integration separate margin capture across standard and premium-grade muriate channels.
| Leading Market Players |
|---|
| Nutrien Ltd. |
| The Mosaic Company |
| Uralkali |
| Belaruskali |
| ICL Group Ltd. |
| Arab Potash Company |
| Sinofert Holdings Limited |
| Qinghai Salt Lake Industry Co., Ltd. |
| Compass Minerals International Inc. |
| Others |
Supply Flow & Price Mechanics
Sixty-to-ninety-day inventory cycles at Chinese state reserve facilities amplify spot price volatility while concentrating procurement leverage among buyers with terminal storage access. This lead-time compression binds Saskatchewan rail corridors to Brazilian port economics, with solution-mined supply commanding premium positioning against shaft-mined alternatives.
Pricing Analysis
Long-term offtake contracts anchor lifetime value for mine-to-farm networks, with granular product commanding premium-mid-economy pricing differentiation across certification tiers. Price differentiation rests on REACH Annex XVII cadmium thresholds and USP purity specifications, with European compounders absorbing compliance costs while Brazilian cooperatives exhibit acute spot-market sensitivity. Pricing pressure stems from natural gas volatility in solution mining circuits, eroding margin predictability for standard-grade crystallization.
Supply Chain Analysis
Port congestion at Santos and Vancouver terminals constrains inbound logistics for Atlantic and Pacific trade lanes serving Brazilian and Asian markets. Supply concentrates in Canada, Russia, and Belarus, with extraction economics drawing from natural gas inputs, brine chemistry expertise, and rail-linked distribution infrastructure. Single-source vulnerability runs through Belarusian state-controlled producers facing sanctions-linked cargo rerouting. Distribution runs through integrated mine-to-farm networks and unbundled European compounders selling formulation expertise separately from KCl procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Compounders unbundling blending from product supply signal platform-economics inflection, with interoperability between satellite-guided soil testing and precision application systems reshaping value capture.
For Market Incumbents: Secure backward integration into controlled-release coating capacity to defend against polymer-sulfur hybrid technology disruption. Anchor rail-siding access across Saskatchewan-to-Midwest corridors while investing in dual USP-FCC certification to capture pharmaceutical-grade margin pools. For New Entrants and Emerging Players: REACH fast-track compliance for fertilizer-grade material opens European compounder networks otherwise locked to incumbent suppliers. Target underpenetrated African bulk terminal partnerships in Ethiopia and Tanzania, leveraging agronomic service bundling as the primary go-to-market angle. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across solution-mined co-extraction circuits with lithium-potash synergies. Five-to-ten-year viability favors purification-capable mid-caps with certified low-impurity profiles. Watch membrane filtration adoption rates as the inflection signal separating scalable from stranded assets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Coating Capacity | Polymer-sulfur hybrid coatings enable precision agriculture platforms in Australia's wheat belt to reduce application frequency. |
| Dual Certification Investment | Simultaneous USP and FCC qualification extends quality validation cycles for pharmaceutical and food additive channels. |
| Long-term Supply Agreement | Mine-to-farm contracts lock in base volume across North American corn belts with terminal storage access. |
| Joint Venture in African Terminals | Bulk terminal partnerships in Ethiopia and Tanzania create first-mover infrastructure for regional blending operations. |
| Green Manufacturing Transition | Solution-mined KCl with lower embodied carbon captures EU Carbon Border Adjustment Mechanism advantages. |
Methodological Framework
Cross-validation between primary interviews with mine operations managers, procurement leads at NPK compounders, distribution channel partners, and technical R&D directors anchors the qualitative findings. Secondary validation draws from customs and trade data, SEC 10-K filings, ECHA compliance audit records, and Ministry of Agriculture fertilizer registration databases. Bottom-up volume modeling and top-down value triangulation reconcile extraction capacity announcements with import flow observations.
Sensitivity analysis tests forecast robustness across grade tier, end-use industry, packaging format, and regional production hub dimensions. CAGRs derive from segmented growth rate aggregation and cross-reference with macroeconomic drivers throughout the forecast period. Key inputs include solution mining brine chemistry maturation timelines and REACH enforcement intensity trajectories.
Decision-makers should treat outputs as directional under stable regulatory enforcement and unimpeded trade lane assumptions; material deviation would warrant model refresh. Forecasts reflect documented base-case parameters with acknowledged sensitivity to sanctions-linked supply disruptions and natural gas price swings. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
2,6-Dichlorobenzaldehyde Market
Bulk Chemicals
Global Cyclopentane Market
Bulk Chemicals
Lithium Chloride Market
Bulk Chemicals
North America Paraffin Wax and Emulsions Market
Bulk Chemicals
Potassium Carbonate Market
Bulk Chemicals
Tallow Market
Bulk Chemicals
Manganese Sulfate Market
Bulk Chemicals
Global Ethylene Market
Bulk Chemicals
Caprylic Acid Market
Bulk Chemicals
Zinc Acetate Market
Bulk Chemicals
India Chlorine Market
Bulk Chemicals
Terephthaloyl Chloride (TPC) Market
Bulk Chemicals
GCC Calcium Chloride Market
Bulk Chemicals
Cobalt Acetate Crystals Market
Bulk Chemicals
Saudi Arabia Formic Acid Market
Bulk Chemicals
Sodium Carbonate Market