
 Global Solvent Dyes Market | 2026-2036
Global Solvent Dyes Market Size, Share, and Industry Trends Forecast 2026-2036
Global Solvent Dyes Market Foresight
Specialized color chemist talent is collapsing across European and North American manufacturing hubs, constraining formulation innovation for high-heat polymer applications. LANXESS AG leverages its integrated aromatics chain to sustain captive supply of dye intermediates. BASF SE anchors its position through R&D intensity in metal-complex solvent dyes for automotive interiors. Clariant AG competes via geographic dominance in Asian plastics coloring markets.
Solvent dyes comprise synthetic organic colorants dissolved in non-aqueous carriers, typically exhibiting solubility parameters between 18 and 25 MPa½ and thermal stability exceeding 280°C for engineering polymer applications. These dyes color substrates through molecular dispersion rather than ionic bonding, delivering transparency and brilliance in rigid plastics, printing inks, and synthetic leather. Disperse dyes occupy the largest margin pool within the product type architecture, while plastics coloring represents the fastest-growing application segment driven by PET and polycarbonate packaging demand. Ink production sustains mature volume throughput among printing companies serving flexible packaging converters.
EPA regulations under the Toxic Substances Control Act restrict benzidine-derived intermediates in U.S. solvent dye imports, while REACH Annex XVII in Europe limits chlorinated solvent carriers in consumer-contact applications. China's MEE enforces dual carbon goals that elevate energy-efficiency thresholds for nitrobenzene reduction processes at Kiri Industries Ltd. and domestic competitors. India's BIS certification mandates heavy metal testing for leather dyeing exports, reshaping quality protocols at Atul Ltd. and Nitin Dye Chem Pvt. Ltd. Stakeholders must monitor regulatory divergence between jurisdictions to align formulation portfolios with evolving compliance thresholds.
Market Dynamics
REACH Annex XVII restrictions on chlorinated solvent carriers and EPA benzidine-derived intermediate bans are forcing simultaneous reformulation across European and North American solvent dye portfolios, compressing development timelines while elevating R&D intensity.
Growth Catalysts
- Engineering polymer packaging expansion:PET and polycarbonate rigid packaging producers in China and Germany require thermal stability above 280°C, pulling high-performance metal-complex dye volumes.
- EU Green Deal chemical sustainability mandates:The framework accelerates substitution of heavy metal-containing colorants with organic alternatives in consumer-contact plastics.
- India BIS certification for leather exports:Heavy metal testing protocols at tanneries in Kanpur and Chennai are standardizing quality thresholds, expanding addressable market for compliant dye suppliers.
Market Restraints
- Nitrobenzene feedstock volatility:Energy-intensive reduction processes face margin compression under China's MEE dual carbon enforcement, constraining intermediate supply.
- Specialized color chemist scarcity:European and North American manufacturing hubs report collapsing formulation talent pools for high-heat polymer applications.
- Aqueous pigment substitution:Water-based dispersion technologies advance in flexible packaging printing, threatening solvent dye share in mature ink segments.
Strategic Opportunities
- Underpenetrated Saudi synthetic leather sector:SFDA cosmetic-contact material standards are creating certified dye demand for automotive interior applications.
- Brazil ANVISA pharmaceutical packaging coloration:Blister pack and bottle dye compliance represents emerging specification work for solvent dye technical service teams.
- Digital printing convergence with solvent inks:Industrial inkjet heads tolerate higher dye loadings, enabling formulation premiums in narrow-web label production.
Industry Challenges
- Cross-jurisdiction formulation fragmentation:Divergent EPA, REACH, and MEE residue thresholds force parallel product line maintenance, elevating SKU complexity.
- Legacy batch reactor retrofit requirements:Continuous processing adoption demands capital deployment that mid-scale dye houses struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Solvent Dyes Market |
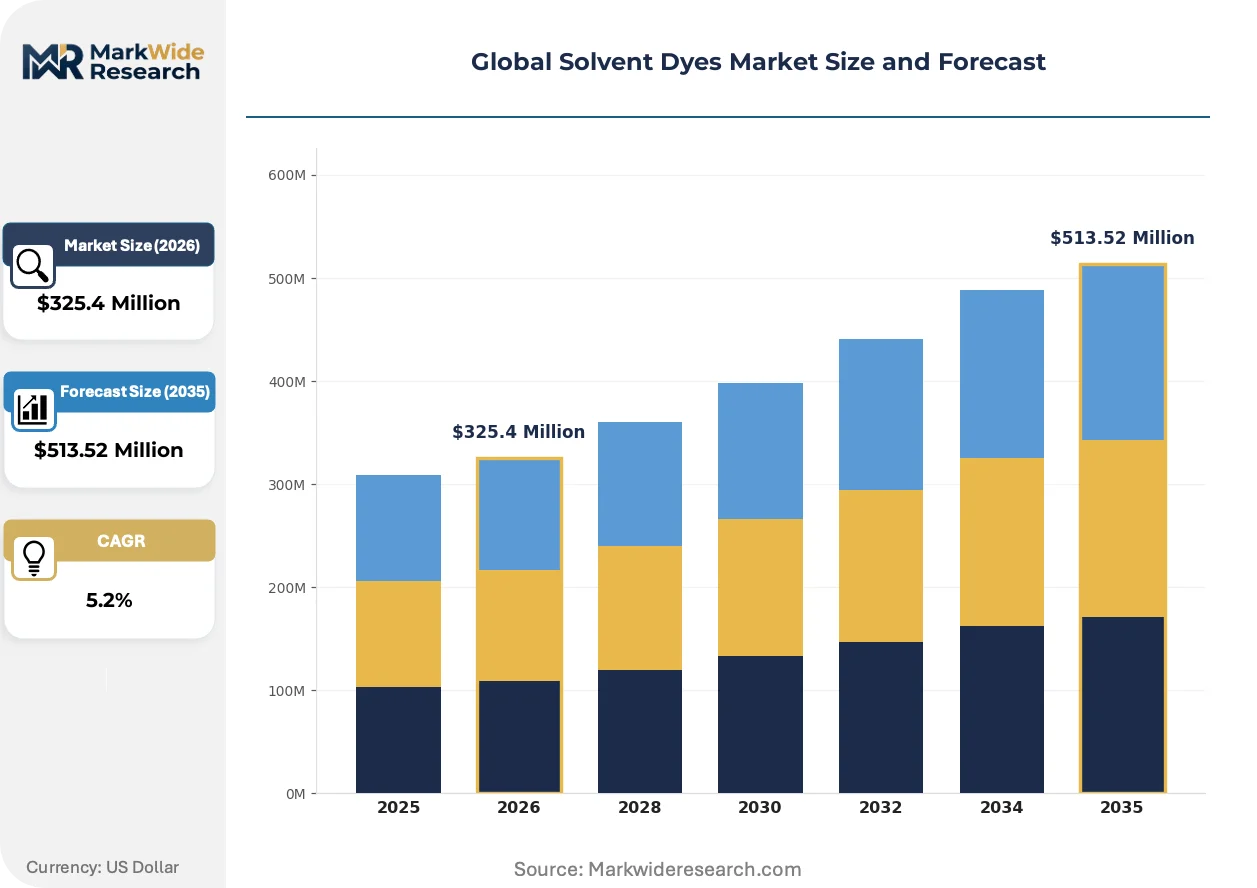
| Market Size in 2026 | $325.4 Million |
| Market Size in 2035 | $513.52 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Basic Dyes, Acid Dyes, Direct Dyes, Reactive Dyes, Disperse Dyes Application: Textile Dyeing, Ink Production, Plastics Coloring, Leather Dyeing, Paper Coloring End User Industry: Fabric Manufacturers, Printing Companies, Packaging Producers, Footwear Makers, Stationery Manufacturers Packaging Type: Drums, Bottles, Jerry Cans, Bags, Carboys |
| Companies Covered | LANXESS AG, DyStar Group, BASF SE, Atul Ltd., Kiri Industries Ltd., Clariant AG, Archroma, Nitin Dye Chem Pvt. Ltd., Huntsman Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Solvent Dyes Market Shifts & Advancements
Formulation science is pivoting from molecular weight optimization toward solubility parameter engineering, as transparency requirements in engineering polymers tighten and regulatory windows for legacy chemistries narrow.
Metal-complex solvent dyes with tailored solubility parameters between 18 and 25 MPa½ are supplanting conventional azo structures in polycarbonate automotive glazing and medical device housings. Tier-1 automotive suppliers in Stuttgart and Shanghai have accelerated qualification timelines from 18 months to 8 months. This compression is forcing intermediate producers to release specification-grade batches before full toxicological dossier completion, elevating liability exposure.
REACH Annex XVII amendments restricting chlorinated solvent carriers in consumer-contact applications took effect across EU member states in 2023. The regulation compels reformulation of disperse dye carriers used in synthetic leather finishing. Italian and Spanish automotive interior producers are shifting specification authority from purchasing departments to regulatory affairs teams, elongating vendor approval cycles.
Specification-driven procurement now dominates engineering polymer coloration, with buyers unbundling technical service from volume supply contracts. PET packaging converters in Zhejiang province and Bavaria negotiate separate fees for color matching, regulatory documentation, and batch certification. This unbundling compresses base dye margins while elevating service revenue pools for formulation houses with captive analytical laboratories.
Global Solvent Dyes Market Segmentation
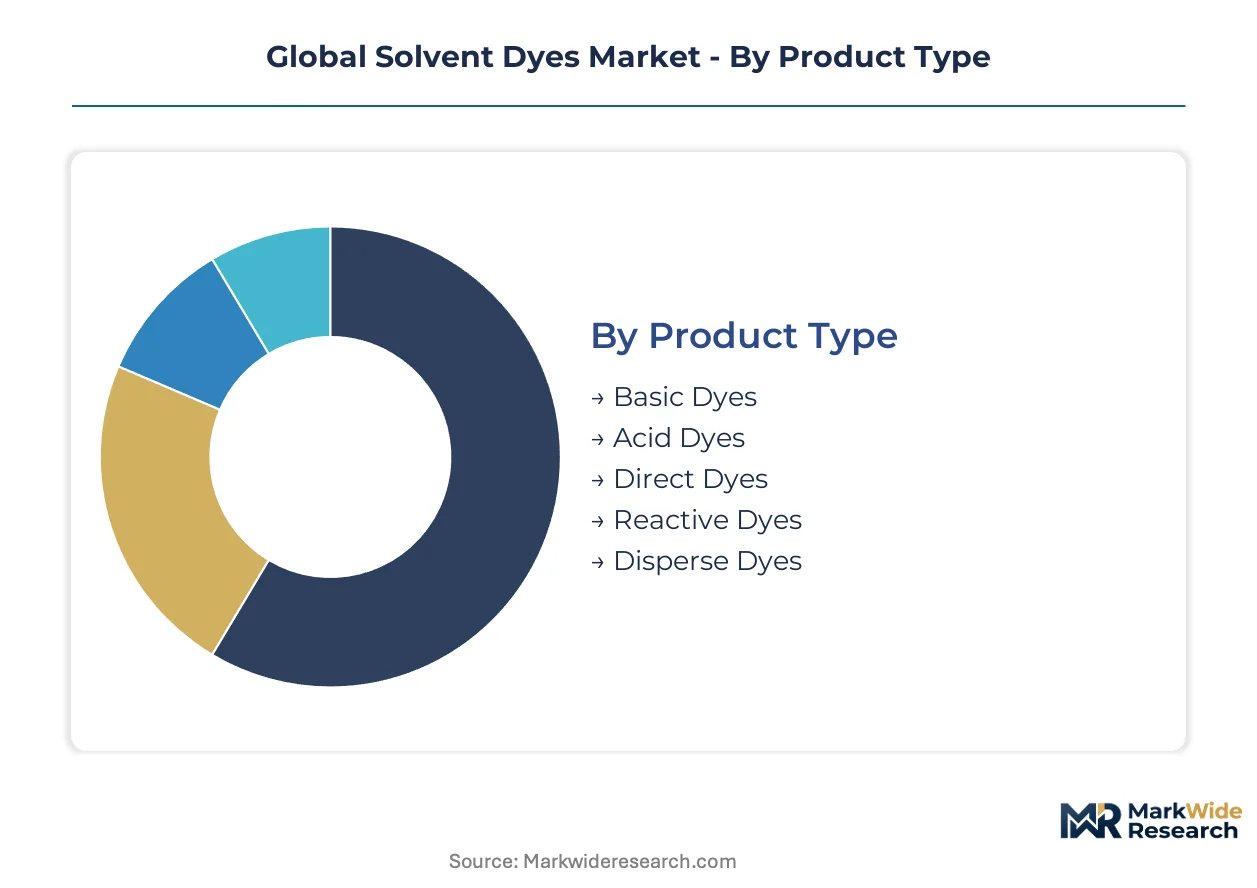
Solvent dye portfolios fragment across molecular architectures, application chemistries, and packaging formats. Each dimension carries distinct margin profiles, regulatory burdens, and geographic concentration patterns that reshape supplier strategy.
Product Type:
Domestic production clusters in China and India dominate commodity dye categories, while German and Swiss specialists control export-led metal-complex formulations for automotive and medical applications.
- Disperse Dyes:These non-ionic colorants achieve molecular dispersion in hydrophobic synthetic fibers and engineering polymers. Demand concentrates in Zhejiang province textile clusters and Bavarian automotive glazing plants, pulled by polycarbonate and PET packaging specifications requiring thermal stability above 280°C.
- Reactive Dyes:Covalent bonding chemistry delivers wash-fast coloration for cellulosic substrates. Export-led volumes flow to Bangladesh and Vietnam garment hubs, though China's MEE dual carbon enforcement is compressing nitrobenzene intermediate supply and elevating batch costs.
- Acid Dyes:Anionic structures optimized for protein fibers and nylon dominate Kanpur tannery procurement.
- Direct Dyes:Flat molecular configurations suit paper and leather applications with moderate fastness requirements.
- Basic Dyes:Cationic chemistries serve acrylic fiber coloration with high tinctorial strength.
Disperse dyes hold the largest share; momentum sits with reactive dye volumes climbing fastest in South Asian textile export zones.
Application:
Cost tier stratification separates specification-driven engineering polymer work from commodity textile and paper assignments.
- Plastics Coloring:Metal-complex solvent dyes with tailored solubility parameters between 18 and 25 MPa½ penetrate polycarbonate automotive glazing and medical device housings. Tier-1 suppliers in Stuttgart and Shanghai have compressed qualification timelines from 18 months to 8 months, forcing intermediate producers to release specification-grade batches before full toxicological dossier completion.
- Ink Production:Solvent-based formulations for flexible packaging printing sustain mature volume throughput, though water-based pigment dispersions threaten share in narrow-web label segments.
- Textile Dyeing:Polyester and acetate fiber coloration drives bulk consumption in Chinese domestic processing clusters.
- Leather Dyeing:Anionic and metal-complex dyes serve automotive interior and footwear applications subject to India's BIS heavy metal certification.
- Paper Coloring:Direct and basic dye applications in specialty packaging and stationery carry compressed margins.
Plastics coloring commands premium pricing tiers; textile dyeing retains volume dominance.
End User Industry:
Customer type determines procurement sophistication, with packaging producers unbundling technical service from base supply contracts.
- Packaging Producers:PET and polycarbonate rigid packaging converters in Germany and China negotiate separate fees for color matching, regulatory documentation, and batch certification. This unbundling compresses base dye margins while elevating service revenue pools for formulation houses with captive analytical laboratories.
- Printing Companies:Flexible packaging converters serving food and pharmaceutical clients drive solvent ink volumes with tightening residue thresholds under EPA and REACH frameworks.
- Fabric Manufacturers:Polyester weaving and knitting operations in Shaoxing and Surat purchase disperse dyes through distributor networks with limited formulation support.
- Footwear Makers:Synthetic leather finishers in Italy and Spain face REACH Annex XVII chlorinated solvent carrier restrictions, shifting specification authority from purchasing to regulatory affairs teams.
- Stationery Manufacturers:Paper and board coloration for premium packaging applications demands moderate fastness properties at commodity price points.
Packaging producers generate the steepest service revenue expansion; fabric manufacturers concentrate procurement volume.
Packaging Type:
Supply chain configuration and hazard classification dictate container selection across liquid and powder dye formats.
- Drums:Standard 200-liter steel and plastic drums dominate liquid solvent dye shipments to industrial dye houses and toll compounders, with UN-certified specifications for flammable carrier solvents.
- Jerry Cans:Intermediate volumes for specialty ink and coatings producers favor stackable HDPE containers with integrated dispensing systems.
- Bottles:Laboratory and sampling quantities for color matching services utilize amber glass or fluorinated polymer bottles to prevent photodegradation.
- Bags:Multi-wall paper and FIBC bulk bags handle powder disperse dye shipments to textile mills with pneumatic conveying systems.
- Carboys:Demountable glass or plastic containers serve legacy pharmaceutical and cosmetic colorant procurement protocols.
Drums capture the largest logistics volume; jerry cans are expanding most quickly with just-in-time ink formulation workflows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MEE dual carbon enforcement anchors the dominant geography, where nitrobenzene reduction processes face tightening energy-efficiency thresholds. Regulatory divergence across EPA, REACH, and MEE jurisdictions fragments formulation portfolios and elevates SKU complexity for multinational suppliers.
China
Zhejiang province textile clusters and Shaoxing polyester weaving operations drive bulk consumption of disperse dyes for PET packaging. MEE dual carbon goals compress margins at nitrobenzene reduction facilities, constraining intermediate supply for domestic formulators. Kiri Industries Ltd. and domestic competitors retrofit batch reactors to meet elevated energy-efficiency thresholds.
Germany
Stuttgart automotive suppliers compress qualification timelines for polycarbonate glazing from 18 months to 8 months, pulling metal-complex dye volumes. REACH Annex XVII chlorinated solvent carrier restrictions force reformulation of disperse dye carriers for synthetic leather finishing. Bavarian PET packaging converters negotiate unbundled contracts separating color matching from base supply.
United States
EPA benzidine-derived intermediate bans under the Toxic Substances Control Act restrict solvent dye imports for flexible packaging printing. Flexible packaging converters serving food and pharmaceutical clients drive solvent ink volumes with tightening residue thresholds. Midwest toll compounders handle standard 200-liter drum shipments for industrial dye houses.
India
Kanpur tanneries and Chennai leather finishers face BIS certification mandates for heavy metal testing on export shipments. Atul Ltd. and Nitin Dye Chem Pvt. Ltd. reshape quality protocols to access European and North American markets. Surat fabric manufacturers purchase disperse dyes through distributor networks with limited formulation support.
Italy
Automotive interior producers in Turin and Milan shift specification authority from purchasing departments to regulatory affairs teams under REACH Annex XVII amendments. Synthetic leather finishers reformulate disperse dye carriers away from chlorinated solvents for consumer-contact applications. Italian formulation houses with captive analytical laboratories capture elevated service revenue from unbundled technical contracts.
Global Solvent Dyes Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with captive aromatics chains and dedicated R&D facilities separating premium metal-complex formulators from commodity disperse dye producers. The structure rewards backward integration into dye intermediates and punishes mid-scale houses lacking continuous processing capital. Three archetypes dominate: integrated chemical conglomerates with aromatic feedstock control, specialty formulation houses with captive analytical laboratories, and regional commodity producers serving domestic textile clusters. Competitive moves concentrate on portfolio diversification toward high-heat polymer applications and geographic expansion into underpenetrated synthetic leather markets.
Within the integrated leader tier, LANXESS AG exemplifies captive supply chain architecture, while BASF SE anchors R&D intensity in metal-complex structures. Clariant AG occupies a position emphasizing Asian plastics coloring market presence. DyStar Group represents the specialty formulation house archetype with technical service capabilities. Kiri Industries Ltd. and Atul Ltd. sit within the regional commodity producer tier serving South Asian textile and leather processing clusters.
| Leading Market Players |
|---|
| LANXESS AG |
| DyStar Group |
| BASF SE |
| Atul Ltd. |
| Kiri Industries Ltd. |
| Clariant AG |
| Archroma |
| Nitin Dye Chem Pvt. Ltd. |
| Huntsman Corporation |
| Others |
Supply & Pricing Matrix
Metal-complex dye substitution for conventional azo structures in polycarbonate automotive glazing is simultaneously relocating specification authority toward regulatory affairs teams in Stuttgart and Shanghai while compressing base dye margins through unbundled procurement contracts. This substitution dynamic concentrates pricing power with formulation houses possessing captive analytical laboratories, even as commodity disperse dye producers face margin erosion from distributor-dominated textile procurement in Zhejiang province.
Pricing Analysis
Long-term offtake agreements dominate metal-complex solvent dye procurement for Tier-1 automotive suppliers, while spot-market transactions govern commodity disperse dye volumes flowing to Shaoxing textile clusters. Price differentiation rests on certification grade for REACH Annex XVII compliance and thermal stability performance above 280°C. Cost compression in commodity disperse tiers is intensifying because China's MEE dual carbon enforcement elevates nitrobenzene reduction energy costs. Fabric manufacturers in Surat exhibit highest price sensitivity; packaging producers in Bavaria demonstrate lowest sensitivity due to specification-driven procurement.
Supply Chain Analysis
Inbound logistics costs from Shanghai port congestion and constrained container availability on Asia-Europe trade lanes are elevating working capital requirements for European toll compounders. Supply concentrates in China, India, and Germany, with nitrobenzene intermediates, chlorinated solvent carriers, and aromatic feedstocks anchoring raw material dependencies. Single-source vulnerability from China's MEE-enforced production curbs at Kiri Industries Ltd. and domestic competitors threatens intermediate availability. Distribution runs through 200-liter drum shipments to industrial dye houses and toll compounders, with jerry can formats expanding for just-in-time ink formulation workflows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment. REACH Annex XVII, EPA benzidine bans, and China's MEE dual carbon goals create compliance barriers that protect incumbents with established toxicological dossiers and captive analytical infrastructure.
For Market Incumbents: Secure qualification pipeline compression advantages by expanding technical service teams in Stuttgart and Shanghai to capture unbundled color-matching revenue. Deepen backward integration into dye intermediates to offset nitrobenzene feedstock volatility from China's MEE enforcement. Capacity addition in Bavaria and Zhejiang province reinforces proximity to packaging converter clusters facing tightening residue thresholds. For New Entrants and Emerging Players: Anchor in underpenetrated synthetic leather segments in Saudi Arabia and Brazil where SFDA cosmetic-contact standards and ANVISA pharmaceutical packaging rules are creating certified dye demand without entrenched incumbent relationships. Target automotive interior applications in Turin and Milan where specification authority shifts toward regulatory affairs teams elongate vendor approval cycles but reduce price competition. A technical service-led go-to-market approach with captive analytical laboratories captures service revenue pools that commodity distributors cannot access. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed specialty formulation houses possessing regional laboratory networks but lacking integrated aromatics chains. The five-to-ten-year viability window favors acquisition targets with established REACH and EPA dossiers that would require multi-year replication. The signal to watch is qualification timeline compression below eight months for polycarbonate automotive glazing, which would indicate formulation science commoditization threatening premium metal-complex margins.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Dye Intermediates | Captive nitrobenzene supply secures margin protection against China's MEE dual carbon enforcement. |
| Green Manufacturing Transition | Substitution of chlorinated solvent carriers aligns with REACH Annex XVII amendments and EU Green Deal mandates. |
| Long-term Supply Agreement | Tier-1 automotive suppliers in Stuttgart compress qualification timelines, locking in specification-grade batch volumes. |
| Capacity Expansion | Proximity additions in Zhejiang province and Bavaria reduce logistics exposure from Shanghai port congestion. |
| Joint Venture | Regional partnerships with Kanpur tanneries navigate India's BIS certification for heavy metal testing protocols. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs, with plant managers at nitrobenzene reduction facilities, procurement leads at PET packaging converters, distribution channel partners serving Shaoxing textile clusters, and technical R&D directors at metal-complex formulation houses contributing qualitative inputs. Secondary validation drew from customs and trade data, ECHA REACH registration dossiers, SEC 10-K filings from listed chemical conglomerates, and MEE enforcement disclosures. Bottom-up volume modeling triangulated against top-down value estimates across product type, application chemistry, and end-user industry dimensions.
Across the analysis window, projections integrated thermal stability performance tiers, regulatory compliance grade stratification, and regional production hub clustering. CAGRs were derived from segmented growth rate reconciliation against aggregate market expansion. Forecast inputs included nitrobenzene intermediate availability constraints under China's dual carbon enforcement, qualification timeline compression for polycarbonate automotive glazing, and unbundled service revenue capture by formulation houses with captive analytical laboratories.
Material uncertainties — feedstock energy cost volatility, regulatory divergence between EPA and REACH residue thresholds, and aqueous pigment substitution rates in flexible packaging — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding MEE enforcement continuity and Tier-1 automotive supplier qualification behavior. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
Isoamylene Market
Solvents
2 - Ethyl Anthraquinone Market
Solvents
2,2-Dimethylbutyryl Chloride Market
Solvents
Toluene Derivatives Market
Solvents
Hydrophobic Solvents Market
Solvents
Japan Acetonitrile Market
Solvents
Global Ethyl Lactate Market
Solvents
N-Methyl Pyrrolidone Market
Solvents
Electronic Cleaning Solvents Market
Solvents
1,2-Ethanedithiol Market
Solvents
6-Xylenol Market
Solvents
Dimethyl Sulfoxide Market
Solvents
Tetraethyl Benzene Market
Solvents
Trifluoroethanol Market
Solvents
Diethylene Glycol (DEG) Market
Solvents
Propylene Glycol Ether Market