
 Diethanolamine (DEA) Market | 2026-2036
Diethanolamine (DEA) Market Size, Share, and Industry Trends Forecast 2026-2036
Diethanolamine (DEA) Market Outlook
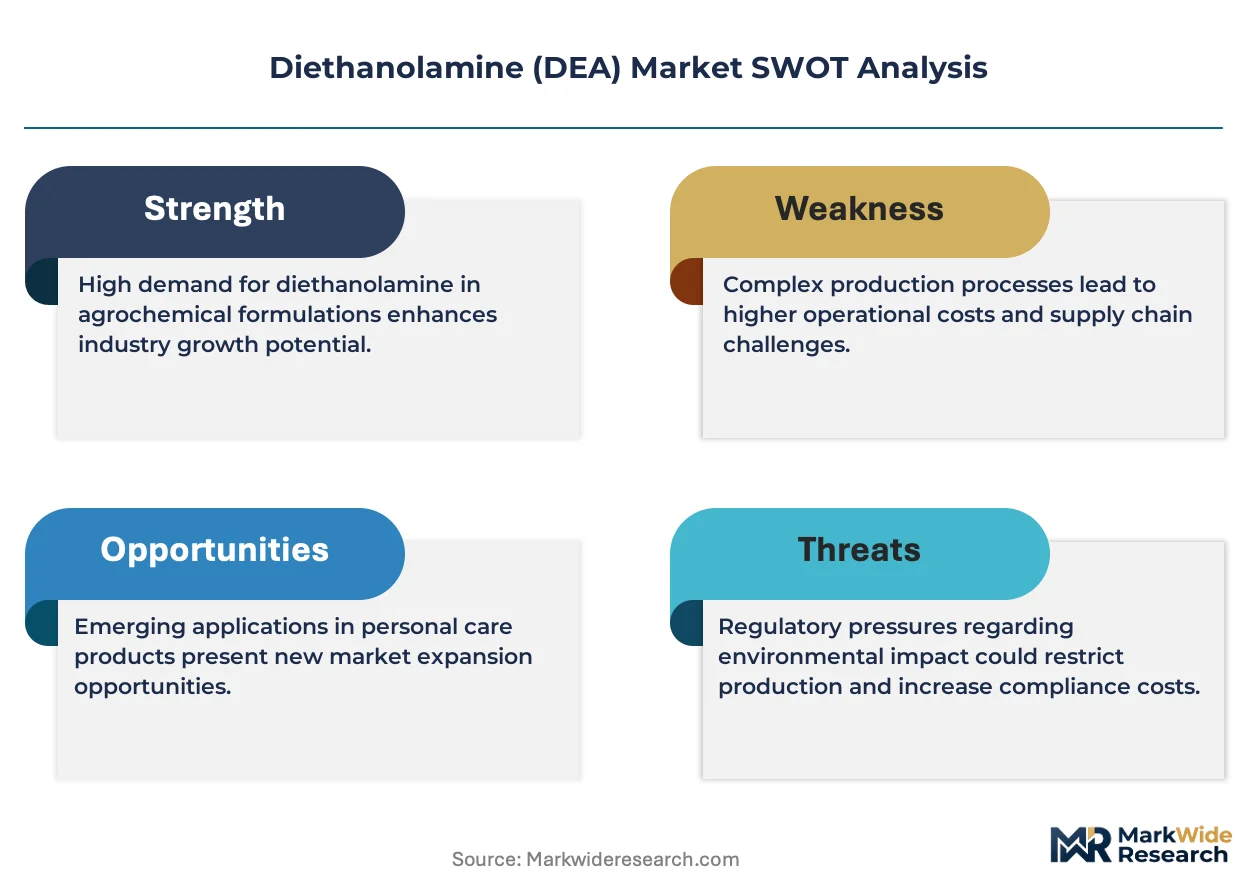
Pharmaceutical-grade purity specifications is collapsing the gap between commodity and specialty DEA tiers. BASF SE leverages its integrated ethylene oxide pipeline to sustain cost leadership across European supply chains. Dow anchors North American production with dedicated capacity serving agrochemical and coatings customers. SABIC competes through feedstock proximity to Saudi ethylene sources, extending margin capture into Asian export markets.
Diethanolamine is a secondary aliphatic amine produced via ethylene oxide ammonolysis, containing two hydroxyethyl groups that confer water solubility and alkalinity for pH adjustment and neutralization reactions. Its primary industrial purpose centers on surfactant synthesis, metalworking fluids, and gas-treatment formulations where selective acid-gas absorption is required. Surfactants command the largest share of product-type demand due to pervasive incorporation into institutional and industrial cleaning products. The emulsifiers segment is expanding fastest within personal care and agricultural formulations, while chemical intermediates for morpholine derivatives represent a mature, margin-stable pool. Solvent applications face substitution pressure from glycol ethers in coatings systems.
EPA oversight under the Toxic Substances Control Act shapes permissible DEA concentrations in consumer-facing cleaning products, while REACH registration requirements in Europe enforce full supply-chain toxicity documentation for imports above one tonne annually. FDA indirect food-contact limits further constrain lubricant and metalworking end uses where incidental migration risks exist. Stakeholders must monitor evolving state-level restrictions on alkanolamines in aerosol formulations, particularly in California and New York, where precursor notification rules are tightening faster than federal benchmarks.
Market Dynamics
REACH registration deadlines and EPA Toxic Substances Control Act enforcement are compressing the supplier base, forcing formulators to document full supply-chain toxicity for DEA imports above one tonne annually while state-level aerosol restrictions in California and New York outpace federal benchmarks.
Growth Catalysts
- REACH compliance deadlines:European manufacturers must complete full toxicity dossiers for DEA imports, consolidating demand around registered suppliers with validated purity specifications for downstream chemical intermediates.
- Gas-treatment formulations:Selective acid-gas absorption applications in natural gas processing are expanding DEA consumption for carbon capture and hydrogen sulfide removal systems.
- China's ethylene oxide capacity:Proximity to integrated petrochemical feedstocks lowers input costs for domestic DEA producers serving Asian surfactant demand.
Market Restraints
- Ethylene oxide feedstock volatility:DEA production costs track ethylene oxide pricing, which fluctuates with crude oil derivatives and refinery operating rates.
- Glycol ether substitution:Coatings formulators are replacing DEA solvent applications with glycol ether alternatives that offer lower toxicity profiles and equivalent solvency.
- Supply concentration in China, Germany, and the United States:Three-country dominance creates geographic risk exposure for buyers dependent on single-source supply chains.
Strategic Opportunities
- Pharmaceutical-grade purity tier:Collapsing margins between commodity and specialty DEA tiers create premium positioning for producers meeting FDA indirect food-contact specifications.
- Agricultural emulsifier demand:Personal care and agrochemical formulations are driving fastest expansion in the emulsifiers segment.
- EU Green Deal chemical sustainability targets:Carbon intensity disclosures favor producers with integrated ethylene oxide pipelines and lower Scope 3 emissions profiles.
Industry Challenges
- Alkanolamine handling certification:Industrial cleaning product formulators face tightening OSHA exposure limits and state-level precursor notification requirements that extend compliance timelines.
- Legacy metalworking fluid reformulation:FDA incidental migration limits constrain lubricant applications, requiring capital investment in alternative chemistries or barrier technologies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Diethanolamine (DEA) Market |
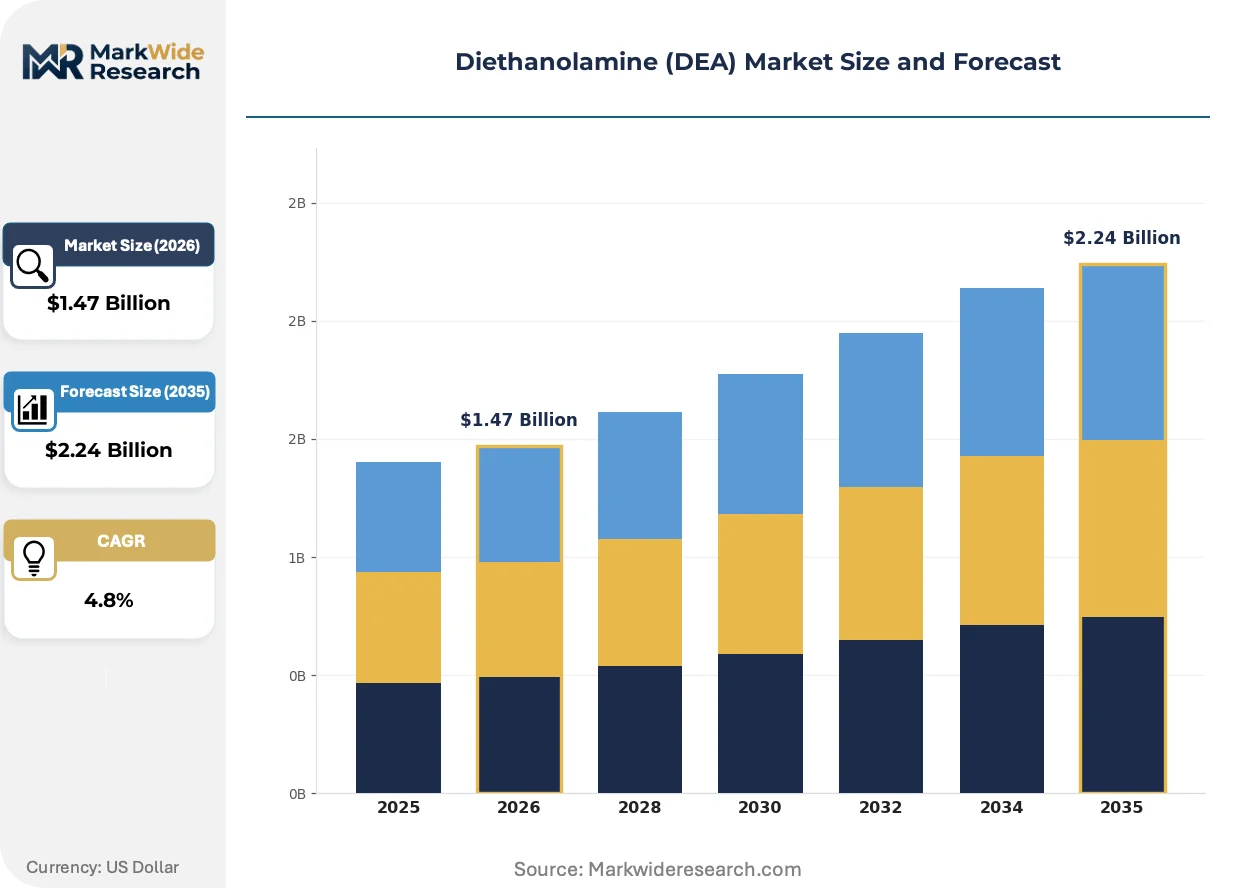
| Market Size in 2026 | $1.47 Billion |
| Market Size in 2035 | $2.24 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surfactants, Emulsifiers, Solvents, Chemical Intermediates End User: Personal Care, Agriculture, Textile, Pharmaceuticals Application: Cleaning Products, Coatings, Pesticides, Detergents Delivery Mode: Bulk, Packaged, Liquid, Solid |
| Companies Covered | BASF SE, Dow, SABIC, INEOS, HELM AG, Huntsman Corporation, AkzoNobel, Nippon Shokubai, Merck KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Diethanolamine (DEA) Market Strategic Shifts
Process intensification in ethylene oxide ammonolysis and regulatory-driven purity differentiation are reshaping competitive economics, while downstream formulators demand documented supply-chain transparency for institutional and industrial cleaning products.
Membrane separation technology for DEA purification is displacing conventional distillation sequences in new plant designs. Specialty chemical producers in Germany and the United States are adopting membrane systems to achieve pharmaceutical-grade specifications with lower energy intensity. This displacement is compressing capital requirements for purity upgrades while locking in margin premiums for certified supply.
REACH Article 33 extended SCIP database obligations now require DEA-containing articles to declare Substances of Very High Concern throughout the supply chain. Industrial cleaning equipment manufacturers must track component-level DEA content for circular economy compliance. Metalworking fluid formulators in the European Union are responding by accelerating substitution programs or securing registered supplier status ahead of 2025 enforcement waves.
Direct procurement contracts between institutional cleaning end-users and DEA producers are consolidating distributor intermediaries. Large facility management groups in the United States are negotiating volume commitments with registered REACH suppliers to secure price stability and documentation continuity. This disintermediation is most visible in healthcare and foodservice sanitation verticals where audit-ready supply-chain transparency has become a contractual requirement.
Diethanolamine (DEA) Market Segmentation
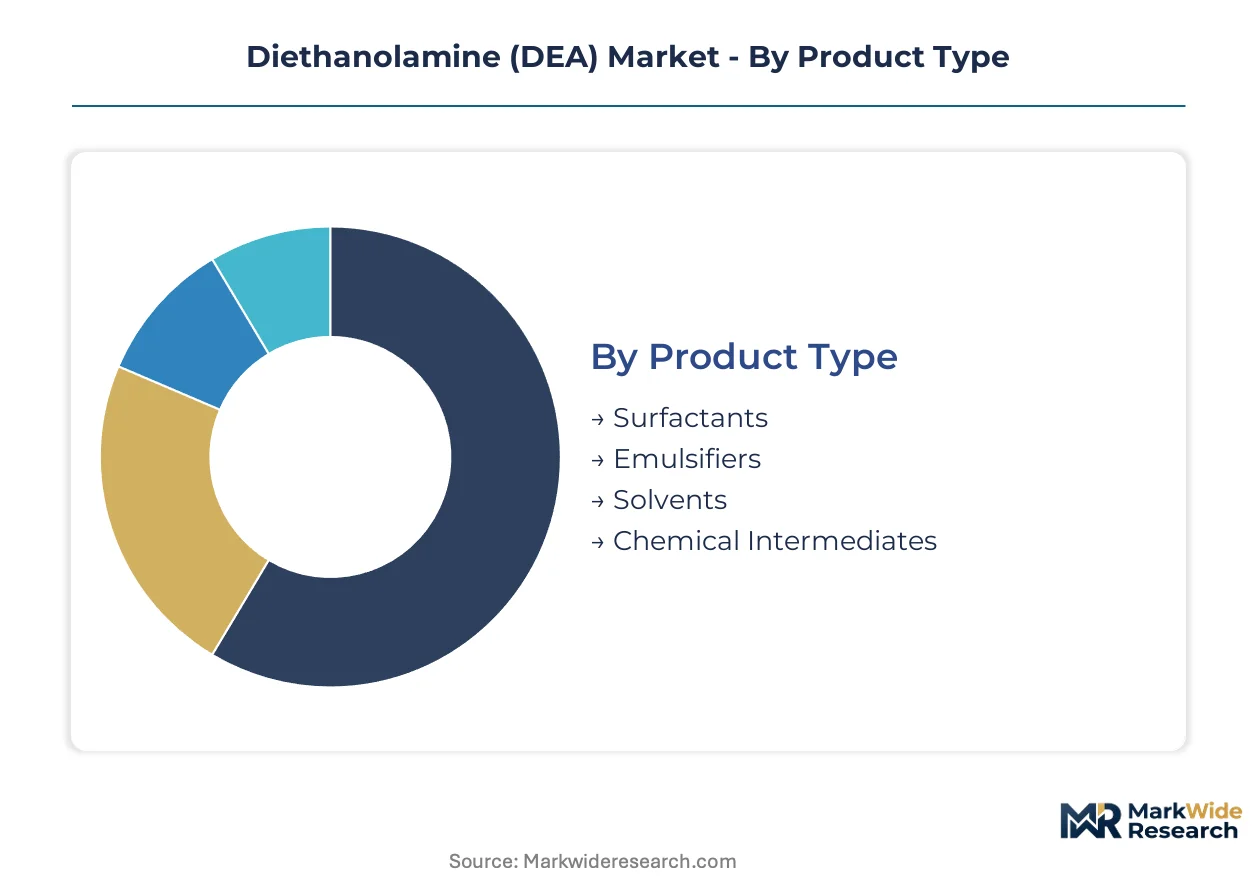
DEA's functional versatility across hydrophilic and alkalinity-driven applications creates distinct performance tiers that command different purity premiums. Segmentation reveals where substitution pressure from glycol ethers and bio-based alternatives concentrates most intensely.
Product Type:
Glycol ether substitution pressure falls unevenly across DEA product categories, with solvent applications bearing the brunt while surfactant and emulsifier grades retain structural demand.
- Surfactants:Alkanolamine-based anionic and non-ionic surfactants leverage DEA's dual hydroxyethyl structure for foaming and emulsification in institutional cleaning. Demand concentrates in industrial and healthcare sanitation verticals where REACH-registered supply chains have become mandatory for contract procurement.
- Emulsifiers:DEA-fatty acid condensates stabilize oil-in-water systems for agrochemical formulations and personal care products. Agricultural adjuvant demand in Brazil and the United States drives fastest volume expansion as pesticide formulators seek compatibility with tank-mix systems.
- Solvents:DEA serves as a neutralizing agent and co-solvent in waterborne coatings systems. Glycol ether alternatives from Dow and Eastman are displacing volume in architectural coatings where VOC regulations have tightened most aggressively.
- Chemical Intermediates:Morpholine and ethyleneamine derivatives consume DEA as a feedstock in captive chemical processes. Mature demand from corrosion inhibitor and rubber accelerator producers generates stable, specification-tight volume.
Surfactants anchors the volume base while emulsifiers gains share at the steepest rate.
End User:
Cost tier differentiation separates pharmaceutical-grade specifications from commodity industrial grades, with FDA indirect food-contact limits creating the steepest purity premiums.
- Personal Care:DEA functions as a pH adjuster and emulsion stabilizer in shampoos and skin cleansers. California's Proposition 65 labeling requirements and EU Cosmetic Regulation restrictions on nitrosamine precursors have compressed approved supplier lists to REACH-registered producers with validated purity documentation.
- Agriculture:Pesticide emulsifiers and tank-mix adjuvants represent the fastest-climbing application segment. Brazilian soybean and corn protection chemical formulators are expanding DEA consumption as spray application volumes intensify.
- Textile:Scouring agents and dye leveling assistants employ DEA for alkalinity control in fiber processing. Asian textile hubs in Vietnam and Bangladesh are absorbing volume as regional surfactant formulation capacity expands.
- Pharmaceuticals:Excipient-grade DEA meets USP-NF monograph specifications for parenteral and topical drug formulations. EMA and FDA dual-inspected manufacturing sites command 40-60% price premiums over industrial grades.
Agriculture anchors the volume base while pharmaceuticals gains share at the steepest rate.
Application:
Application maturity varies sharply, with cleaning products representing a consolidated, specification-tight segment while coatings applications face active chemistry substitution.
- Cleaning Products:Institutional and industrial degreasers, metal cleaners, and sanitation formulations consume the largest DEA volume. EPA Safer Choice program criteria and state-level aerosol precursor notifications in New York are elevating documentation burdens for formulators.
- Coatings:Waterborne architectural and industrial coatings use DEA for pH stability and pigment dispersion. Glycol ether and amine-neutralized alternatives are capturing share in low-VOC formulations where toxicity profiles drive specification changes.
- Pesticides:Herbicide and insecticide emulsifiable concentrates rely on DEA-based surfactant systems for field efficacy. Brazilian and US Midwest agricultural chemical producers are the dominant demand centers.
- Detergents:Laundry and dishwashing formulations employ DEA as a foam booster and soil anti-redeposition agent. Concentrated liquid detergent trends in European retail channels are shifting volume toward higher-activity surfactant grades.
Cleaning products anchors the volume base while pesticides gains share at the steepest rate.
Delivery Mode:
Supply chain configuration separates bulk pipeline deliveries to integrated formulators from packaged shipments to regional distributors, with liquid formats dominating total volume.
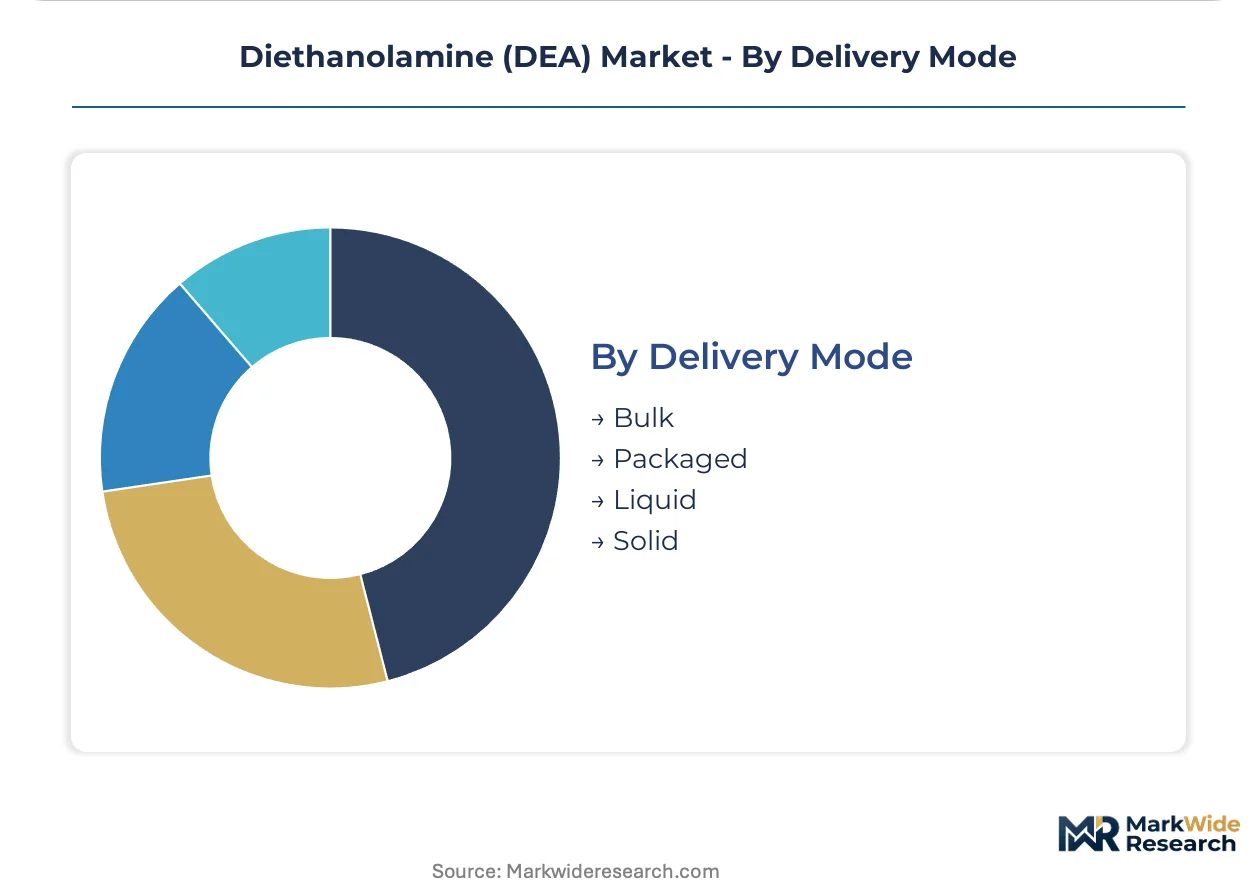
- Bulk:Tank truck and railcar deliveries serve large-scale surfactant and agrochemical producers with dedicated storage infrastructure. Coastal US and ARA-region terminals anchor intermodal distribution networks for REACH-registered material.
- Packaged:Drum and tote quantities reach mid-scale formulators and compounders without bulk handling capability. Distributor intermediaries are losing share to direct procurement contracts in healthcare and foodservice sanitation verticals.
- Liquid:Aqueous DEA solutions at 85-99% concentration represent the standard commercial format. Lower freezing points and handling convenience favor liquid over solid derivatives for most formulation applications.
- Solid:Flaked or prilled DEA serves specialty applications requiring extended shelf stability or reduced shipping weights. Limited volume concentrates in pharmaceutical excipient and remote-site industrial applications.
Liquid anchors the volume base while packaged gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated ethylene oxide pipelines cluster DEA manufacturing in Germany, China, and the United States, with each hub serving distinct regulatory and demand environments. Regional differentiation stems from feedstock access, purity specifications, and downstream formulation requirements.
United States
EPA Toxic Substances Control Act enforcement and OSHA exposure limits tighten handling protocols for industrial cleaning formulators. State-level precursor notification rules in California and New York outpace federal benchmarks. The Gulf Coast petrochemical corridor anchors production capacity serving agrochemical and coatings customers.
China
Proximity to expanding ethylene oxide capacity lowers input costs for domestic surfactant producers. MEE environmental standards and dual carbon goals pressure carbon intensity disclosures from chemical manufacturers. Yangtze River Delta integrated complexes supply Asian institutional cleaning and textile processing demand.
Germany
REACH registration deadlines and ECHA Substances of Very High Concern listings consolidate demand around validated suppliers. EU Green Deal chemical sustainability targets favor producers with lower Scope 3 emissions profiles. BASF's Ludwigshafen complex exemplifies integrated pipeline economics serving European pharmaceutical-grade specifications.
Saudi Arabia
Feedstock proximity to Saudi Aramco ethylene sources extends margin capture into Asian export markets. SAMR import registration requirements shape documentation burdens for Chinese and Indian buyers. Jubail Industrial City hosts SABIC production serving Middle Eastern gas-treatment and regional surfactant formulation.
Brazil
Soybean and corn protection chemical formulators expand DEA consumption as spray application volumes intensify. ANVISA agrochemical registration timelines influence formulation sourcing decisions. São Paulo state agrochemical clusters drive fastest emulsifier demand expansion in Latin America.
Diethanolamine (DEA) Market Competitive Environment
Concentration sits with integrated petrochemical majors possessing captive ethylene oxide supply. Three to five producers command bulk volume across major trade corridors, while specialty distributors serve fragmented mid-scale formulation demand. Archetypes divide between feedstock-integrated majors, regional purity specialists, and distribution-focused intermediaries. Competitive moves center on membrane purification technology licensing and direct procurement contract consolidation with institutional end-users.
Among feedstock-integrated majors, BASF SE, Dow, and SABIC exemplify divergent geographic anchoring strategies. BASF SE represents European integrated pipeline economics with REACH-registered supply chain documentation. Dow occupies North American production scale serving EPA-regulated industrial applications. SABIC sits within Middle Eastern feedstock advantage positioning for Asian export markets. Each anchors a distinct regulatory and logistics basin without overlapping core territories.
| Leading Market Players |
|---|
| BASF SE |
| Dow |
| SABIC |
| INEOS |
| HELM AG |
| Huntsman Corporation |
| AkzoNobel |
| Nippon Shokubai |
| Merck KGaA |
| Others |
Value Chain & Pricing Dynamics
Glycol ether displacement in waterborne coatings simultaneously redraws supply geography toward membrane-purification hubs and compresses pricing premiums for commodity-grade material. Buyers in California and New York now source REACH-registered pharmaceutical-grade DEA through direct contracts that bypass traditional distributor markups.
Pricing Analysis
REACH registration deadlines dictate the pricing tier structure across European supply chains. Three-tier pricing separates pharmaceutical-grade from industrial-grade from solvent-grade specifications, with FDA indirect food-contact certification commanding 40-60% premiums over commodity tiers. Cost compression in solvent applications is intensifying because glycol ether alternatives from Dow and Eastman capture share in low-VOC architectural coatings. Agricultural emulsifier buyers in Brazil exhibit highest price sensitivity, while pharmaceutical formulators demonstrate lowest sensitivity due to regulatory compliance requirements.
Supply Chain Analysis
Strait of Hormuz transit underwrites SABIC's margin capture into Asian export markets from Jubail Industrial City. Manufacturing concentrates in China, Germany, and the United States, with ethylene oxide feedstock proximity anchoring production economics. Raw material supply draws from Saudi Aramco ethylene sources, Yangtze River Delta petrochemical complexes, and Gulf Coast pipeline networks. Single-source vulnerability concentrates in membrane purification technology licensing held by German and US specialty producers. Distribution runs through bulk tank truck and railcar deliveries to integrated formulators, with drum and tote shipments declining as healthcare and foodservice verticals consolidate direct procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation across REACH, EPA, and state-level aerosol precursor rules fragments supplier lists and creates white-space opportunities for certified purity specialists. Demand-side shift toward audit-ready supply-chain transparency in healthcare and foodservice sanitation verticals rewards documentation-capable producers.
For Market Incumbents: Consolidate membrane purification technology licensing positions and secure direct procurement contracts with institutional cleaning end-users before distributor intermediaries lose further share. BASF's integrated Ludwigshafen pipeline and Dow's Gulf Coast captive ethylene oxide supply demonstrate how backward integration into feedstock sources defends margin position against Saudi and Chinese cost competitors. For New Entrants and Emerging Players: Lead with pharmaceutical-grade purity capabilities targeting Brazilian agrochemical formulators and US Midwest pesticide producers where ANVISA and EPA registration timelines constrain incumbent responsiveness. Agricultural emulsifiers represent the most penetrable segment, with tank-mix adjuvant demand climbing fastest. Pursue toll manufacturing arrangements with Yangtze River Delta ethylene oxide producers to bypass capital-intensive greenfield construction. For Investors and Strategic Acquirers: REACH Article 33 SCIP database obligations reshape the acquisition landscape toward registered suppliers with validated purity documentation and lower Scope 3 emissions profiles. Five-to-ten-year viability favors producers with integrated ethylene oxide pipelines serving dual pharmaceutical and industrial demand streams. Target membrane technology specialists in Germany and the United States with established EMA and FDA dual-inspected manufacturing sites. Monitor EU Green Deal chemical sustainability target enforcement as the signal indicating which certified suppliers will capture premium pricing.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Purification Technology Licensing | Enables pharmaceutical-grade DEA production with lower energy intensity than conventional distillation sequences. |
| Direct Procurement Contract Consolidation | Healthcare and foodservice sanitation verticals now require audit-ready supply-chain transparency as contractual terms. |
| Backward Integration into Ethylene Oxide | BASF's Ludwigshafen complex demonstrates captive feedstock economics that sustain cost leadership across European supply chains. |
| REACH Registration Completion | Validates supplier status for DEA imports above one tonne annually and secures access to institutional cleaning contract procurement. |
| Carbon Intensity Disclosure Investment | EU Green Deal chemical sustainability targets favor producers with documented lower Scope 3 emissions profiles. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with surfactant formulation chemists, institutional cleaning procurement managers, agrochemical adjuvant technical directors, and membrane separation technology licensors. Secondary validation incorporated customs and trade data, ECHA registration dossiers, EPA Toxic Substances Control Act filings, and SEC 10-K disclosures from integrated petrochemical majors. Bottom-up volume estimates from end-use application segments were triangulated against top-down ethylene oxide consumption proxies and regional production capacity assessments.
Across the analysis window, the analytical framework modeled segmentation dimensions spanning purity grade tier, end-use industry vertical, delivery mode format, and regional regulatory cluster. CAGRs were derived from slope analysis of historical consumption patterns projected through elasticity-adjusted demand curves. Forecast inputs incorporated ethylene oxide feedstock pricing volatility indices and REACH enforcement timeline assumptions.
Forecasts assume regulatory continuity in REACH, EPA, and state-level California and New York aerosol precursor regimes; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as glycol ether substitution rates and EU Green Deal carbon intensity disclosure requirements evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
Trichloroacetyl Chloride Market
Solvents
Methyl Diethanolamine Market
Solvents
Trifluoroethanol Market
Solvents
Ultra-Low-VOC Methacrylate Reactive Diluents Market
Solvents
2-Butanone Market
Solvents
Global Tert-Butanol Market
Solvents
Methyl Undecylenate Market
Solvents
2 - Ethyl Anthraquinone Market
Solvents
North America Acetonitrile Market
Solvents
Global Solvents Market
Solvents
GCC Acetonitrile Market
Solvents
6-Xylenol Market
Solvents
Dihydromyrcene Market
Solvents
Japan Acetonitrile Market
Solvents
Isopropylamine Market
Solvents
Hydrophobic Solvents Market