
 Aromatic Solvents Market | 2026-2036
Aromatic Solvents Market Size, Share, and Industry Trends Forecast 2026-2036
Aromatic Solvents Market Analysis
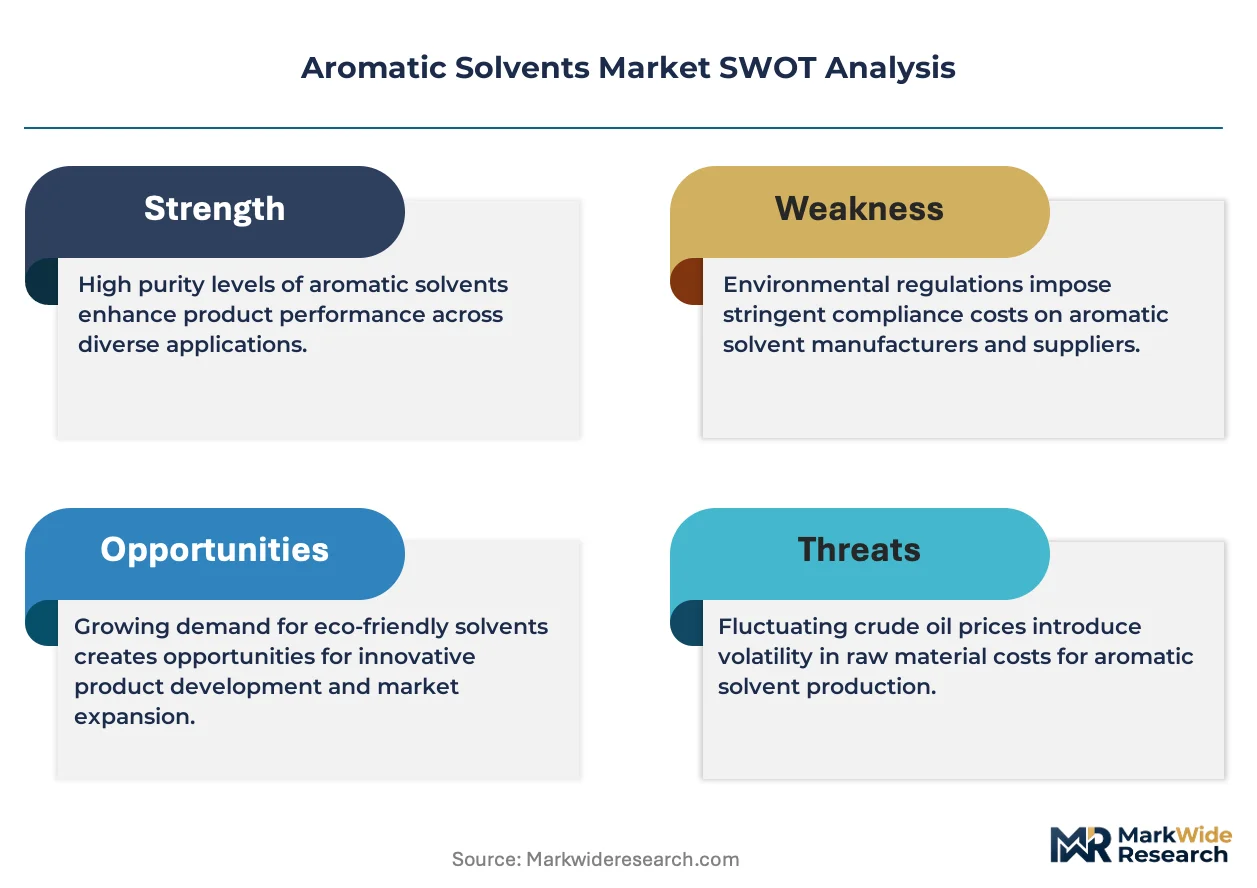
REACH is decoupling European aromatic solvent formulations from legacy high-VOC recipes. ExxonMobil Corporation leverages integrated refinery-petrochemical complexes to sustain cost-advantaged feedstock access. BASF SE anchors its position through specialty-grade xylene derivatives for coatings producers. Royal Dutch Shell PLC competes via global trading infrastructure that controls arbitrage flows between Asian and European markets.
Aromatic solvents are petroleum-derived hydrocarbon liquids containing benzene-ring structures, typically characterized by flash points ranging from 4°C to 30°C and evaporation rates that enable controlled film formation in industrial coatings. Toluene dominates volume consumption in paints and coatings applications where its intermediate evaporation rate balances flow and dry time. Xylene leads growth among product types as adhesives and sealant formulators favor its stronger solvency for synthetic resins. The automotive end-user segment concentrates margin pools around high-purity grades that meet OEM specification requirements.
The EPA enforces National Emission Standards for Hazardous Air Pollutants that limit benzene emissions from solvent production and use facilities across the United States. EMA and ECHA coordinate classification and restriction protocols that determine which aromatic solvent grades gain market access in European pharmaceutical and industrial applications. China's MEE implements dual carbon goals that tighten emission permits for toluene and xylene production clusters. Stakeholders must monitor regulatory divergence between jurisdictions to determine where reformulation investments yield durable competitive position.
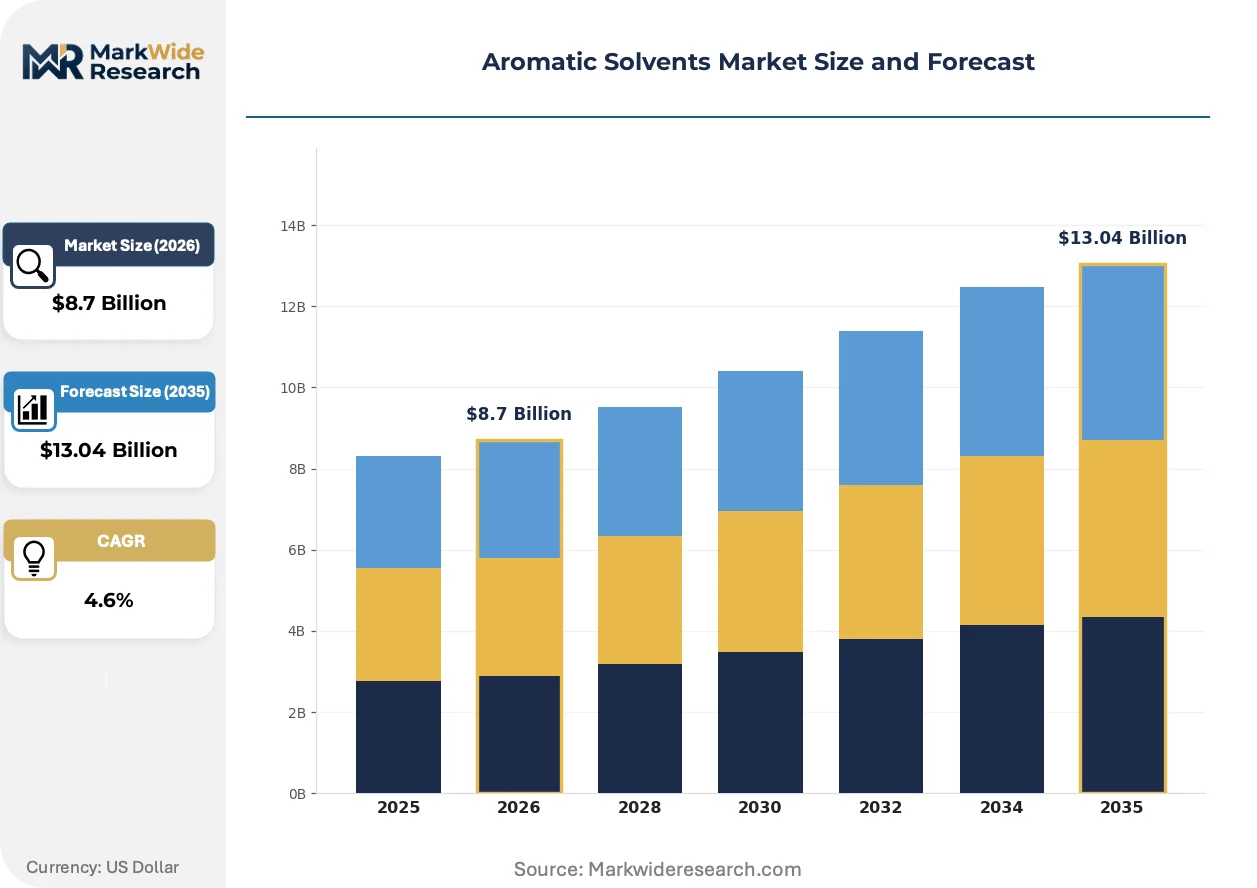
Market Dynamics
REACH restrictions on volatile organic compounds are fragmenting European formulation chemistry, forcing coatings manufacturers to reformulate away from legacy high-aromatic recipes while Asian petrochemical expansion floods adjacent markets with cost-advantaged supply.
Growth Catalysts
- Automotive refinishing demand:OEM specification requirements for high-purity toluene and xylene grades sustain volume pull from collision repair networks and vehicle assembly plants.
- China's petrochemical capacity expansion:Domestic solvent supply additions reduce import dependency and lower feedstock costs for regional coatings producers.
- Adhesives formulation shift:Synthetic resin solvency requirements in sealant manufacturing favor xylene's stronger dissolution properties over alternative hydrocarbons.
Market Restraints
- Crude oil price volatility:Naphtha feedstock cost swings compress blender margins and destabilize contract pricing for derivative aromatics.
- European regulatory friction:ECHA classification protocols restrict market access for certain benzene-containing solvent grades in pharmaceutical applications.
- Bio-based solvent substitution:Esters and terpenes gain formulation share in decorative paints where performance specifications permit lower solvency.
Strategic Opportunities
- Low-aromatic alternative development:REACH-driven reformulation creates white space for C9-C12 aliphatic blends that maintain evaporation control without VOC penalties.
- India industrial coatings penetration:Infrastructure investment and automotive assembly expansion generate unmet solvent demand outside established supply corridors.
- MEA pharmaceutical solvent demand:Saudi Arabia and UAE manufacturing zones require high-specification xylene for active pharmaceutical ingredient crystallization processes.
Industry Challenges
- Process safety certification timelines:Seveso III compliance for toluene storage and handling facilities extends project commissioning by 12-18 months in EU jurisdictions.
- Specialized logistics coordination:Flash point classifications between 4°C and 30°C mandate dedicated tanker fleets and terminal segregation that constrain distribution flexibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aromatic Solvents Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Toluene, Xylene, Benzene, Ethylbenzene Application: Paints, Adhesives, Coatings, Cleaners End User: Automotive, Construction, Chemical Manufacturing, Pharmaceuticals Packaging Type: Drums, Tanks, IBCs, Canisters |
| Companies Covered | Royal Dutch Shell PLC, LyondellBasell Industries Holdings B.V., ExxonMobil Corporation, China National Petroleum Corporation, Total S.A., China Petroleum & Chemical Corporation, Chevron Phillips Chemical Company, Reliance Industries Limited, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aromatic Solvents Market Emerging Trajectories
Formulation chemistry is pivoting toward controlled-evaporation systems that maintain film formation performance while satisfying tightening VOC ceilings across automotive and industrial coatings end-uses.
Hybrid solvent systems combining bio-derived esters with precision-cut aromatic fractions are overtaking conventional pure hydrocarbon blends in automotive OEM clearcoat applications. Tier-1 suppliers in Germany and Japan have adopted these formulations for 2024 model year production. The technology is compressing addressable volume for traditional xylene grades in premium coating segments.
EPA National Emission Standards for Hazardous Air Pollutants now mandate benzene capture technology at solvent production and use facilities across the United States. Equipment retrofit requirements have raised capital barriers for smaller blenders and terminal operators. Gulf Coast production clusters bear the heaviest compliance burden as they supply the largest concentration of downstream coatings manufacturers.
Buyer consolidation among multinational coatings producers has compressed supplier rosters and extended contract durations. Procurement teams at Sherwin-Williams, PPG, and Axalta now specify multi-year solvent supply agreements with embedded price adjustment mechanisms. This concentration is most visible in North America and Western Europe where top-five buyers command over sixty percent of aromatic solvent offtake.
Aromatic Solvents Market Segmentation
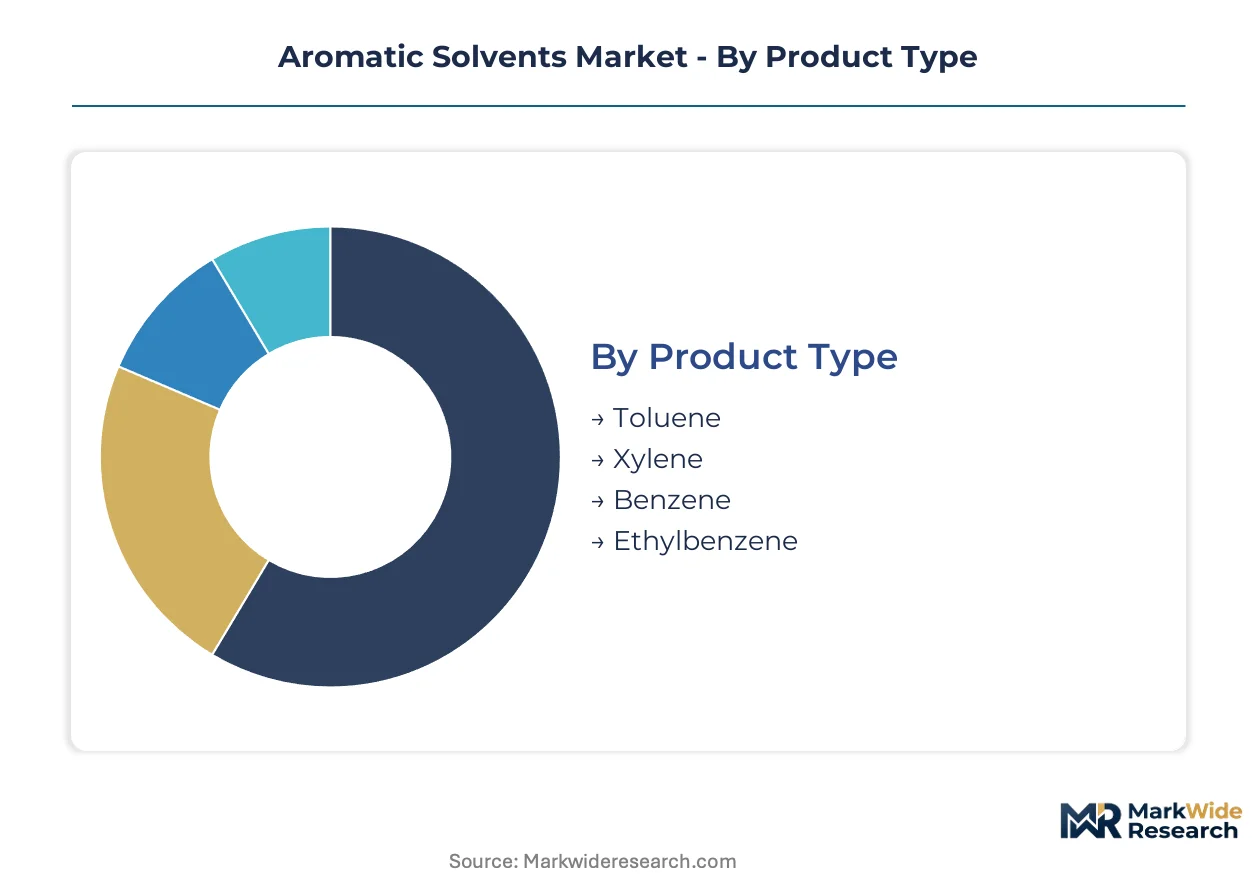
Aromatic solvent purchasing patterns diverge sharply across product grades and end-use specifications. Formulators select solvent types based on evaporation profiles, regulatory limits, and resin compatibility requirements that vary by application.
Product Type:
Replacement cycles for solvent systems accelerate as REACH and EPA emission ceilings force reformulation away from legacy high-benzene recipes toward controlled-aromatic alternatives.
- Toluene:A methyl-substituted benzene derivative with intermediate evaporation rates between 4°C and 30°C flash points. Collision repair networks and vehicle assembly plants in Germany, China, and the United States sustain volume pull for high-purity grades meeting OEM specifications. Toluene's balanced flow-and-dry characteristics preserve its position in automotive refinishing despite regulatory pressure.
- Xylene:Dimethylbenzene isomers offering stronger solvency for synthetic resins than toluene or aliphatic alternatives. Adhesives and sealant formulators in Japan and South Korea favor xylene for polyurethane and epoxy dissolution where faster evaporation would compromise open time. The grade commands premium pricing in pharmaceutical crystallization applications.
- Benzene:Unsubstituted aromatic ring with highest solvency power but strictest regulatory constraints under EPA National Emission Standards and REACH authorization requirements.
- Ethylbenzene:Single-alkyl benzene derivative primarily consumed as styrene feedstock with limited direct solvent applications in specialty coatings.
Volume placements concentrate in toluene; the faster expansion belongs to xylene as adhesives formulation shifts toward stronger-resin solvency.
Application:
Cost tier differentiation separates commodity coatings from specification-grade formulations where solvent purity directly determines film performance.
- Paints:Decorative and industrial coating systems consuming the largest aromatic solvent volumes across water-borne and solvent-borne technologies. Architectural formulators in India and Brazil blend toluene and xylene fractions to control viscosity and leveling in alkyd and acrylic systems. EPA VOC limits and China's MEE dual carbon goals are compressing allowable aromatic content per liter.
- Adhesives:Pressure-sensitive, structural, and sealant formulations where xylene's superior resin dissolution enables higher solids content and reduced solvent volume. Japanese automotive Tier-1 suppliers specify low-moisture xylene grades for polyurethane adhesive production. The segment gains share as lightweight bonding replaces mechanical fastening in vehicle assembly.
- Coatings:Protective and OEM finishes requiring precise evaporation control for appearance and durability. Automotive clearcoat applications in Germany and Japan are adopting hybrid bio-ester aromatic systems.
- Cleaners:Degreasing and equipment maintenance solvents where flash point and toxicity profiles determine workplace safety compliance.
Margin pools concentrate in coatings; adhesives are climbing the fastest as vehicle lightweighting accelerates bonding chemistry adoption.
End User:
Customer type fragmentation separates multinational OEMs with multi-year supply contracts from regional blenders purchasing spot volumes.
- Automotive:OEM assembly plants and collision repair networks specifying high-purity toluene and xylene grades with documented impurity profiles. Procurement teams at major coatings suppliers in the United States and Germany negotiate embedded price adjustment mechanisms spanning 24-36 months. The segment concentrates margin around certification and logistics compliance.
- Construction:Architectural coatings and waterproofing membrane producers consuming commodity-grade solvents where price sensitivity exceeds specification stringency. Indian and Indonesian infrastructure investment is expanding addressable volume for drum-packaged toluene deliveries.
- Chemical Manufacturing:Intermediate and derivative producers processing aromatic feedstocks into specialty chemicals, dyes, and agrochemical actives.
- Pharmaceuticals:Active pharmaceutical ingredient crystallization and extraction processes requiring high-specification xylene with documented residual solvent profiles meeting ICH Q3C guidelines.
Procurement scale concentrates in automotive; pharmaceuticals are expanding most quickly as Saudi Arabia and UAE manufacturing zones add API capacity.
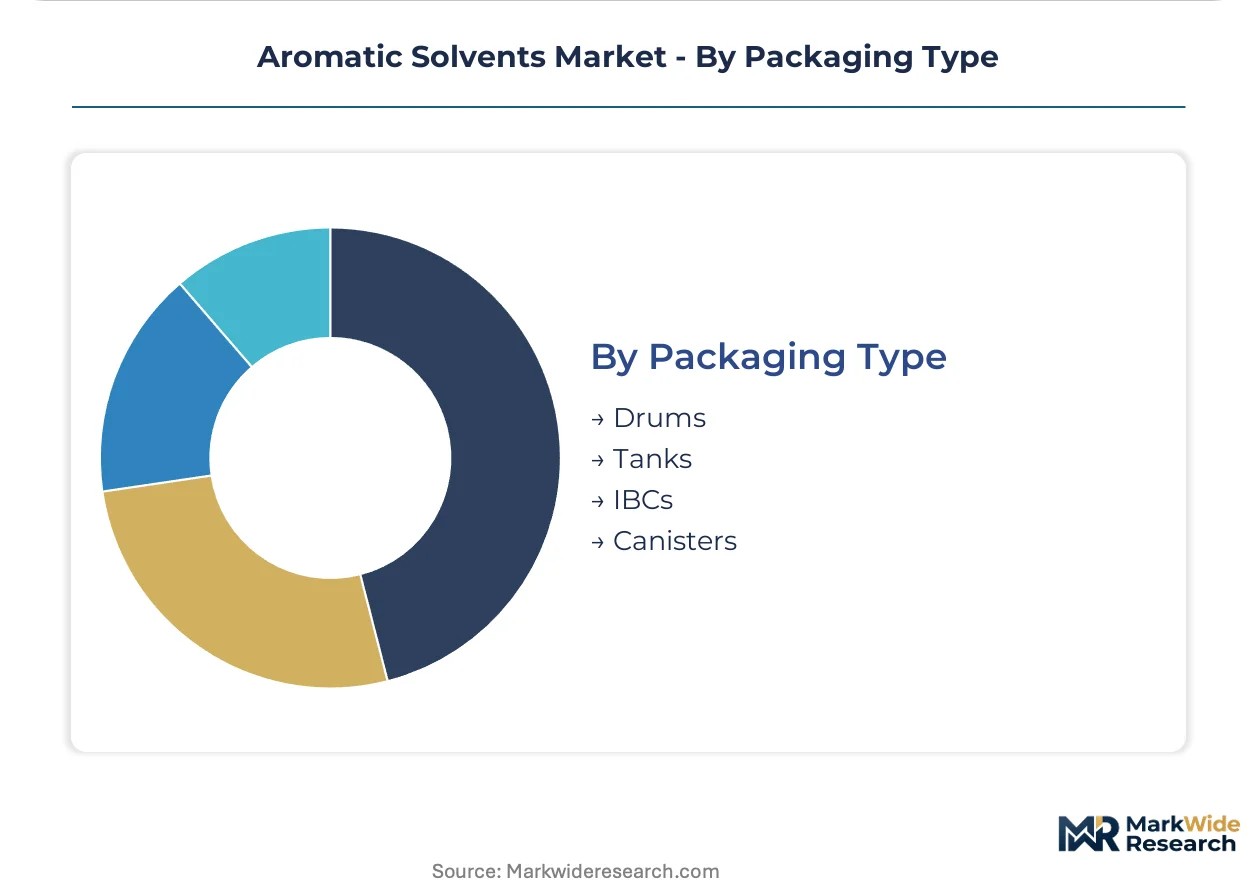
Packaging Type:
Supply concentration around coastal terminals and integrated refinery complexes dictates available packaging formats for regional buyers.
- Drums:Standard 200-liter steel containers serving small-to-medium coatings blenders and maintenance shops across fragmented distribution networks. Indian and Southeast Asian construction sector demand flows primarily through drum logistics.
- Tanks:Bulk railcar and tank truck deliveries to large-scale coatings manufacturers with dedicated solvent storage and vapor recovery systems. Gulf Coast and Rotterdam terminal clusters supply tank volumes to Sherwin-Williams, PPG, and Axalta facilities.
- IBCs:Intermediate bulk containers bridging drum and tank economies for mid-scale formulators requiring flexibility without capital investment in fixed tanks.
- Canisters:Small-format retail packaging for specialty cleaners and touch-up coatings in automotive aftermarket channels.
Shipment volume concentrates in tanks; IBCs are gaining share fastest as mid-tier formulators seek storage flexibility without Seveso III compliance burdens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Petrochemical special economic zones in China's coastal provinces concentrate the world's largest aromatic solvent production clusters. Integrated refinery complexes in Jiangsu and Zhejiang provinces supply domestic coatings manufacturers while exporting surplus volumes to Southeast Asian markets.
China
Automotive assembly plants in Shanghai and Guangzhou sustain high-purity toluene consumption for OEM clearcoat specifications. The Ministry of Ecology and Environment enforces dual carbon goals that tighten emission permits for xylene production clusters in Ningbo. Yangtze River Delta petrochemical zones are expanding solvent distillation capacity to serve domestic coatings formulators.
United States
Collision repair networks across Texas and California drive specification-grade xylene demand for automotive refinishing applications. The EPA enforces National Emission Standards for Hazardous Air Pollutants that mandate benzene capture technology at Gulf Coast production facilities. Houston Ship Channel terminal operators are retrofitting vapor recovery systems to maintain supply access to Sherwin-Williams and PPG distribution hubs.
Germany
Automotive Tier-1 suppliers in Bavaria specify low-moisture xylene grades for polyurethane adhesive production in vehicle lightweighting programs. ECHA classification protocols under REACH restrict benzene-containing solvent grades in pharmaceutical crystallization applications. Ludwigshafen and Cologne chemical clusters are reformulating coating systems toward hybrid bio-ester aromatic blends for 2024 model year production.
India
Infrastructure investment in Maharashtra and Gujarat generates drum-packaged toluene demand for architectural coatings and waterproofing membrane producers. The Bureau of Indian Standards implements labeling requirements for VOC content in decorative paints that compress allowable aromatic fractions. Mumbai-Pune industrial corridor blenders are expanding storage capacity to serve construction sector procurement teams.
Saudi Arabia
Active pharmaceutical ingredient manufacturers in Riyadh and Jubail require high-specification xylene for crystallization processes meeting ICH Q3C guidelines. The Saudi Food and Drug Authority coordinates with Gulf Cooperation Council regulators on residual solvent testing protocols. King Abdullah Economic City pharmaceutical zones are attracting solvent distributors to establish regional blending operations.
Aromatic Solvents Market Vendor Landscape
Gulf Coast and Rotterdam producers anchor one tier; Asian integrated petrochemical specialists hold feedstock-cost advantages in volume segments. The vendor base concentrates around refinery-integrated operators with captive naphtha supply and independent blenders purchasing spot feedstock. Three archetypes dominate: integrated oil majors with global trading infrastructure, national oil companies with domestic market protection, and regional specialists focused on specification-grade derivatives. Competitive moves center on backward integration into refinery assets and formulation partnerships with coatings manufacturers.
Within the integrated oil major tier, ExxonMobil Corporation and Royal Dutch Shell PLC exemplify global trading infrastructure that controls arbitrage flows between Asian and European markets. BASF SE occupies a position among specialty-grade derivative producers serving coatings formulators with documented impurity profiles. These three companies represent contrasting strategic anchors: feedstock integration, logistics control, and application-specific formulation expertise.
| Leading Market Players |
|---|
| Royal Dutch Shell PLC |
| LyondellBasell Industries Holdings B.V. |
| ExxonMobil Corporation |
| China National Petroleum Corporation |
| Total S.A. |
| China Petroleum & Chemical Corporation |
| Chevron Phillips Chemical Company |
| Reliance Industries Limited |
| BASF SE |
| Others |
Supply Flow & Price Mechanics
Naphtha price index movements on the Singapore and Rotterdam benchmarks cascade through aromatic solvent supply chains into three distinct pricing tiers. Feedstock cost pass-through mechanics favor integrated refinery operators with captive naphtha supply, while independent blenders absorb margin compression during volatility spikes.
Pricing Analysis
Short lead-time premiums of fifteen to twenty percent above contract baselines reward suppliers with available spot inventory near coastal terminal clusters. Three-tier pricing structure across pharmaceutical-grade, coatings-specification, and industrial-commodity levels separates customers by purity certification and documentation burden. Price differentiation hinges on Seveso III compliance documentation and vapor-recovery equipment certification. Margins are tightening in European commodity grades as REACH-driven reformulation shrinks addressable volume for high-benzene recipes. Construction sector buyers in India and Southeast Asia exhibit highest price sensitivity, while pharmaceutical crystallization customers in Saudi Arabia accept premium positioning for ICH Q3C-compliant xylene.
Supply Chain Analysis
ISO tank certification and Seveso III handling qualifications gate access to automotive OEM supply rosters, particularly for German and Japanese Tier-1 adhesive formulators. Production concentrates in China, the United States, and Germany where integrated petrochemical complexes anchor feedstock security. Raw material flows draw from refinery naphtha streams, pyrolysis gasoline, and catalytic reformate outputs. Single-source vulnerability persists around high-purity xylene distillation capacity in the Yangtze River Delta. Distribution runs through dedicated tanker fleets with flash-point segregation, railcar unit trains to Gulf Coast coatings clusters, and drum logistics serving fragmented Indian construction markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The aromatic solvents market has become a vertical-integration race where captive naphtha access and downstream formulation partnerships determine survival. Players without refinery integration or specialty-grade certification capabilities face systematic margin compression.
For Market Incumbents: Deploy backward integration into refinery-petrochemical complexes to secure cost-advantaged feedstock positions against Asian national oil companies. Expand high-purity xylene distillation capacity in King Abdullah Economic City to capture pharmaceutical crystallization demand growth. Lock multi-year offtake agreements with Sherwin-Williams, PPG, and Axalta procurement teams before buyer consolidation extends contract durations further. For New Entrants and Emerging Players: Launch via IBC-format distribution targeting mid-tier Indian coatings blenders seeking storage flexibility without Seveso III capital burdens. Penetrate the MEA pharmaceutical solvent segment where Saudi Arabia and UAE manufacturing zones lack established supply relationships. Develop low-aromatic C9-C12 aliphatic blends specifically formulated for REACH-compliant automotive refinishing applications in Germany. For Investors and Strategic Acquirers: Distressed-cycle entries favor specification-grade derivative specialists with documented impurity profiling capabilities in European jurisdictions. Long-term viability over the next decade rests on reformulation partnership depth with coatings OEMs rather than commodity volume scale. Watch for ECHA authorization list expansions targeting residual benzene content as the signal for accelerated substitution investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Refinery Assets | Captive naphtha supply insulates margin from Singapore benchmark volatility. |
| Pharmaceutical-Grade Certification Investment | ICH Q3C compliance documentation unlocks Saudi API crystallization demand. |
| Low-Aromatic Alternative Development | REACH-driven reformulation creates white space for C9-C12 aliphatic blends. |
| Multi-Year Supply Agreement Structuring | Embedded price adjustment mechanisms secure volume with consolidated coatings buyers. |
| Hybrid Solvent System Partnership | Bio-ester aromatic combinations address automotive OEM clearcoat specifications in Germany. |
Methodological Framework
Multi-period observation of naphtha price benchmarks, REACH authorization timelines, and automotive production schedules anchored the trend analysis, supplemented by interviews with refinery operations managers, coatings procurement leads at multinational OEMs, specialty chemical distribution partners, and pharmaceutical manufacturing executives. Secondary validation drew from customs trade data, ACC and Cefic industry reports, SEC 10-K filings of integrated oil majors, and ECHA substance registration databases. Bottom-up volume builds across product grades and end-use segments were cross-checked against top-down petrochemical capacity assessments.
Segment-weighting approaches applied differential growth assumptions across toluene, xylene, and benzene product categories, with further stratification by paints, adhesives, coatings, and cleaner applications. Automotive, construction, chemical manufacturing, and pharmaceutical end-user segments were modeled with distinct demand elasticities to crude oil price movements and regulatory phase-in schedules. CAGRs were derived from regression analysis of historical volume relationships with downstream industrial production indices, adjusted for identified structural breaks from REACH and EPA regulatory implementations.
Crude oil price collapse scenarios, accelerated REACH authorization restrictions, and Chinese petrochemical capacity utilization swings are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions regarding regulatory phase-in timelines and downstream substitution elasticities. A model refresh is warranted upon material change in ECHA substance evaluation priorities or MEE dual carbon goal enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
Ethane Market
Solvents
Asia Pacific Industrial Solvents Market
Solvents
Crotonaldehyde Market
Solvents
Methyl Isopropyl Ketone Market
Solvents
Green Solvents Market
Solvents
Fluorinated Solvents Market
Solvents
Acetone Market
Solvents
Glycerol Market
Solvents
Triacetin Market
Solvents
Pharmaceutical Solvent Market
Solvents
Global Dipropylene Glycol N-Butyl Ether Market
Solvents
5-Isopropyl-M-Xylene Market
Solvents
Toluene Derivatives Market
Solvents
Global Ink Solvents Market
Solvents
Reactive Diluents Market
Solvents
Global Green and Bio-Based Solvents Market