
 Patient Referral Management Software Market | 2026-2036
Patient Referral Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Patient Referral Management Software Market Intelligence
Market Context
Subscription-based SaaS delivery is restructuring how referral software monetizes, shifting perpetual licenses toward recurring revenue models with embedded analytics. Epic leverages its dominance in hospital electronic health records to control referral workflows within captive health system networks. Phreesia anchors outpatient intake and scheduling, extending its platform into referral coordination for ambulatory clinics. athenahealth competes on cloud-native architecture, sustaining network effects across its physician practice base.
Technical Definition and Segment Structure
Patient referral management software comprises digital platforms that automate the routing, tracking, and closure of clinical referrals between providers, incorporating HL7 FHIR interfaces, real-time status dashboards, and closed-loop analytics to ensure care continuity and reduce network leakage. Cloud-based platforms lead deployment preferences as health systems prioritize scalability and reduced IT infrastructure burden over on-premises installations. Integrated solutions capture expanding margin pools by bundling referral capabilities with existing electronic health record ecosystems, while standalone software occupies niche positions among independent specialists seeking modular interoperability.
Regulatory Environment and Outlook
The Office of the National Coordinator for Health IT enforces interoperability rules under the 21st Century Cures Act, penalizing information blocking and mandating standardized APIs that reshape product development roadmaps. HIPAA security requirements govern patient data exchange across referral networks, compelling vendors to maintain audit trails and encryption protocols. CMS value-based payment programs reinforce referral accountability by tying reimbursement to care coordination metrics. Stakeholders must monitor state-level all-payer claims database expansions and emerging FDA guidance on software-as-medical-device classifications that could redefine platform compliance obligations.
Market Dynamics
Cloud-native architecture is displacing legacy on-premise installations as health systems prioritize API-first interoperability and real-time care coordination dashboards.
Growth Catalysts
- 21st Century Cures Act:ONC interoperability mandates penalize information blocking and force standardized FHIR APIs, accelerating vendor platform upgrades.
- Value-based contracting:CMS accountable care organizations tie reimbursement to closed-loop referral metrics, creating direct financial pressure for adoption.
- Patient leakage reduction:Health system CFOs deploy referral analytics to capture revenue from out-of-network escapes, particularly in specialty care networks.
Market Restraints
- EHR vendor concentration:Epic and Cerner control hospital data architectures, creating integration friction for standalone referral platforms seeking connectivity.
- HIPAA compliance burden:Audit trail requirements and encryption protocols add implementation cost and legal review cycles for multi-tenant cloud deployments.
- Technical debt in legacy systems:HL7 v2 interfaces persist in older hospitals, forcing expensive middleware development for FHIR translation.
Strategic Opportunities
- Specialty pharmacy integration:Oncology and rare disease referral workflows lack embedded prior authorization automation, creating white space for vertical platforms.
- Behavioral health carve-ins:Medicare Advantage plans expanding mental health coverage generate demand for closed-loop psychiatric referral tracking.
- Medicaid managed care:State-level contracts in Texas and California reward care coordination, opening procurement channels for cloud-native vendors.
Industry Challenges
- Interoperability engineer scarcity:Health IT departments compete for talent versed in FHIR R4 and SMART on FHIR frameworks, delaying implementation timelines.
- Legacy system integration complexity:Custom EHR configurations in academic medical centers require bespoke API development, stretching vendor professional services capacity.
Report Scope
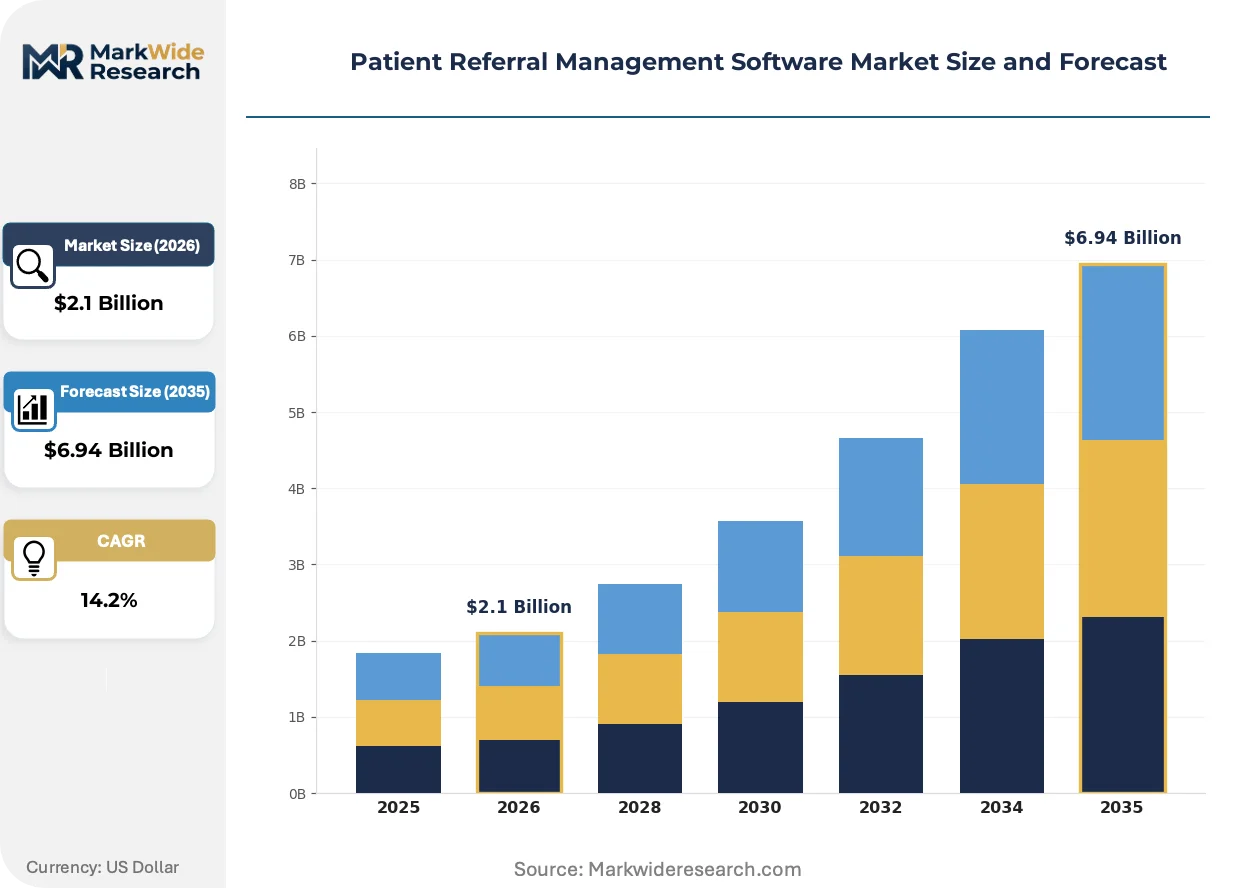
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Patient Referral Management Software Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $6.94 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone Software, Integrated Solutions, Cloud-Based Platforms, Mobile Applications End User: Hospitals, Clinics, Physicians, Group Practices Deployment Model: On-Premises, SaaS, Hybrid, Cloud Application: Patient Coordination, Reporting, Analytics, Care Pathway Management |
| Companies Covered | Luma Health, Phreesia, Epic, Blockit Health, Klara, Oracle Health, Linear Health, PointClickCare, athenahealth, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Patient Referral Management Software Market Strategic Shifts & Innovations
Artificial intelligence is embedding into referral workflows, automating prior authorization predictions and intelligent routing decisions that previously required manual clinical review.
Natural language processing is converging with referral intake systems, extracting clinical intent from unstructured physician notes and auto-populating structured referral forms. Large health systems in the United States are piloting these tools in high-volume specialties like cardiology and orthopedics. This convergence is compressing referral submission time from hours to minutes and reducing administrative FTE requirements.
CMS interoperability rules under the 21st Century Cures Act now require patient access APIs and provider directory transparency. This regulatory pressure forces vendors to expose real-time network availability and wait-time data. Standalone referral platforms serving independent physician associations face the steepest compliance cost increases.
Subscription pricing is displacing perpetual license models across ambulatory clinic procurement. Buyers now expect usage-based tiers bundled with analytics and patient engagement tools. This shift is most pronounced in multi-site specialty groups consolidating vendor relationships under single-platform contracts.
Patient Referral Management Software Market Segmentation
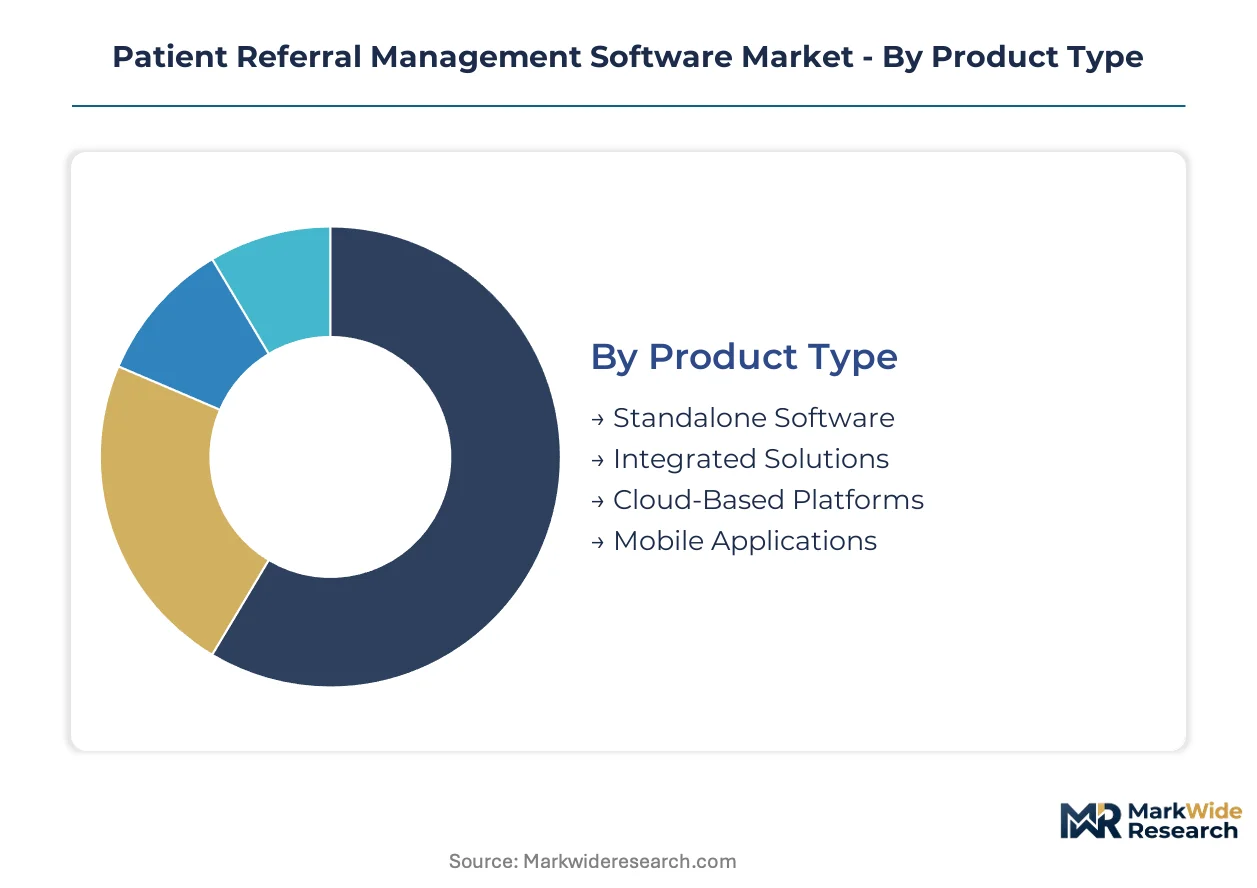
Referral software purchasing patterns diverge sharply between health systems seeking ecosystem control and independent practices prioritizing modular interoperability. Segmentation reveals how deployment architecture, user workflow, and care setting reshape vendor competitive positioning and margin structures.
Product Type:
Vendor supply concentrates around platform depth, with integrated solutions commanding premium pricing through EHR ecosystem lock-in while standalone alternatives compete on implementation speed.
- Integrated Solutions:Embedded within Epic, Cerner, or athenahealth architectures, these platforms leverage existing data repositories to eliminate interface development. Health systems in the United States prioritize these deployments to maintain unified patient records across inpatient and ambulatory settings, though switching costs create long-term vendor dependency.
- Cloud-Based Platforms:API-first architectures enable rapid scaling across multi-site specialty networks without on-premise infrastructure investment. Independent physician associations in Texas and California procurement channels favor these solutions for their subscription flexibility and reduced IT staffing requirements.
- Standalone Software:Modular systems targeting niche interoperability gaps in behavioral health and specialty pharmacy workflows. These platforms appeal to academic medical centers with custom EHR configurations requiring bespoke middleware development.
- Mobile Applications:Point solutions for referral status tracking and secure messaging, typically deployed as physician workflow extensions rather than primary coordination platforms.
Today's leader: Integrated Solutions. Tomorrow's challenger: Cloud-Based Platforms.
End User:
Customer scale determines feature complexity, with hospitals demanding enterprise analytics and small practices prioritizing ease of implementation over advanced reporting.
- Hospitals:Enterprise deployments require closed-loop analytics, real-time dashboards, and network leakage prevention tools. CFOs at these institutions justify investment through specialty care revenue capture metrics tied to value-based contracts.
- Physicians:Individual practitioners and small groups seek lightweight referral tracking with minimal training overhead. Mobile-first interfaces and automated prior authorization support drive purchasing decisions in this segment.
- Clinics:Multi-site ambulatory operations need patient engagement tools bundled with scheduling and intake workflows. Phreesia and similar platforms anchor these deployments through existing outpatient relationships.
- Group Practices:Consolidated specialty groups leverage single-platform contracts to standardize referral protocols across geographic footprints, particularly in cardiology and orthopedics networks.
Demand concentrates in hospitals for integrated platforms, while group practices represent the steepest expansion trajectory for cloud-native alternatives.
Deployment Model:
Technical debt and compliance burden reshape infrastructure choices, with SaaS models displacing legacy installations as HIPAA audit requirements intensify.
- SaaS:Subscription delivery eliminates capital expenditure and accelerates procurement cycles. ONC interoperability mandates under the 21st Century Cures Act favor these deployments for their embedded FHIR API maintenance and automatic security patching.
- Cloud:Dedicated or multi-tenant infrastructure serving health systems with hybrid workload requirements. These deployments balance scalability against data residency preferences in state Medicaid managed care contracts.
- On-Premises:Legacy installations persisting in academic medical centers with custom HL7 v2 interface investments. Migration friction and middleware replacement costs sustain this segment despite declining new sales.
- Hybrid:Split architectures routing sensitive patient data through on-premise nodes while leveraging cloud analytics. These configurations address HIPAA encryption protocol concerns for multi-state referral networks.
SaaS dominates new procurement, though hybrid deployments gain traction among organizations navigating state-level all-payer claims database expansions.
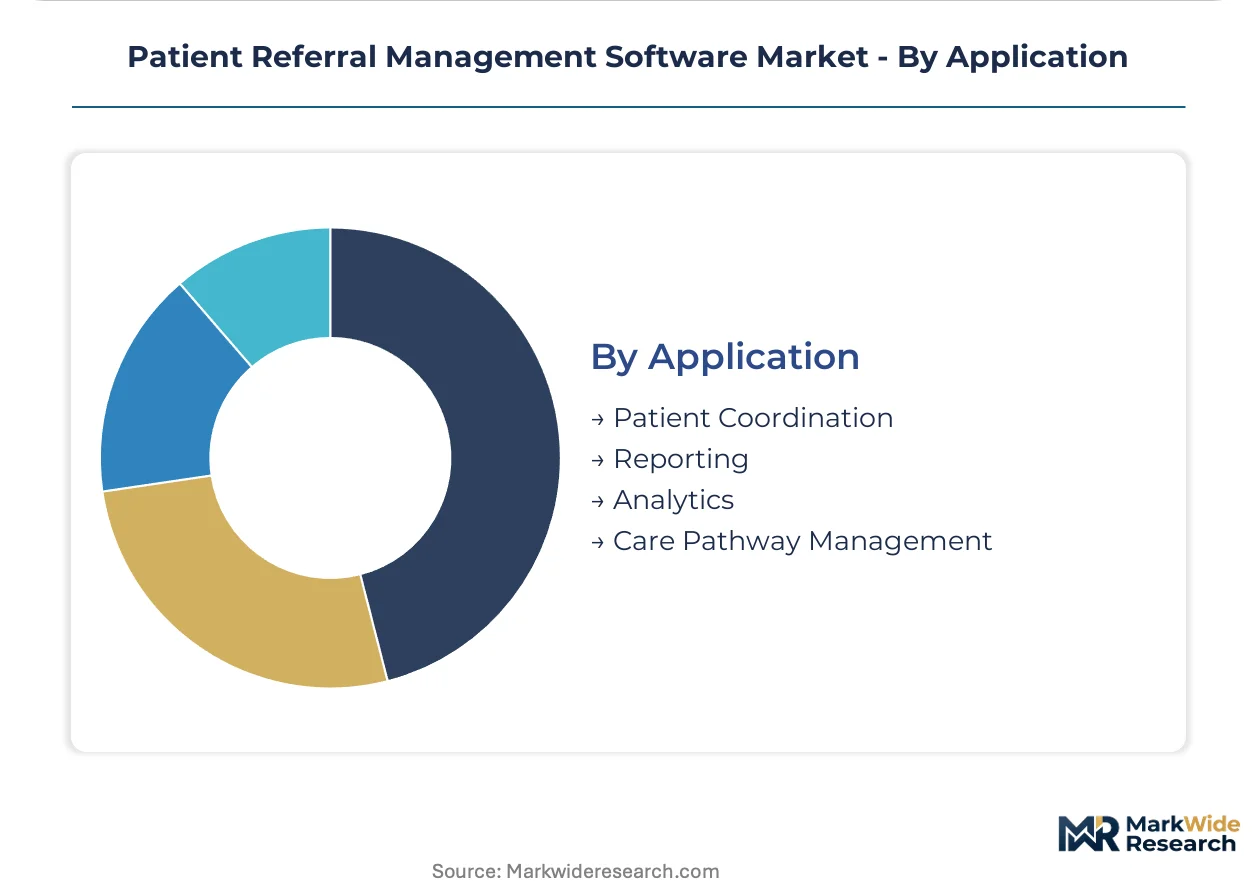
Application:
Workflow automation depth separates commodity coordination tools from premium analytics platforms that quantify care gap closure.
- Patient Coordination:Core routing and tracking functionality with real-time status updates between referring and receiving providers. CMS accountable care organization metrics elevate this application from administrative convenience to reimbursement-critical infrastructure.
- Analytics:Network leakage quantification, referral pattern visualization, and outcome correlation engines. Health system CFOs deploy these tools to demonstrate value-based contract performance to Medicare Advantage plans.
- Reporting:Compliance documentation for HIPAA audit trails and state Medicaid care coordination requirements. Automated report generation reduces administrative FTE overhead in high-volume referral specialties.
- Care Pathway Management:Clinical protocol enforcement and automated prior authorization integration, particularly in oncology and rare disease verticals where specialty pharmacy coordination creates workflow complexity.
Patient Coordination anchors current deployment, while Care Pathway Management applications are climbing the fastest as vertical platforms target specialty pharmacy automation gaps.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States deploys cloud-native referral platforms at triple the per-capita rate of Germany, reflecting divergent health system architectures and reimbursement incentives across these markets.
United States
Accountable care organizations and Medicare Advantage plans drive procurement of closed-loop analytics platforms that quantify network leakage. The 21st Century Cures Act mandates FHIR APIs through ONC enforcement, compelling vendor compliance investments. Texas and California Medicaid managed care contracts reward care coordination metrics, accelerating SaaS adoption among multi-site specialty groups in Dallas-Fort Worth and Los Angeles.
Germany
Hospital federations prioritize integrated EHR solutions to maintain unified patient records across inpatient and ambulatory networks. The EU AI Act and GDPR impose algorithmic transparency requirements on automated referral routing systems. Bavaria's university hospital clusters in Munich and Erlangen pilot hybrid cloud deployments balancing data residency preferences against scalability demands.
United Kingdom
NHS Integrated Care Systems consolidate vendor relationships under single-platform contracts spanning primary and secondary care interfaces. NHS Digital interoperability standards mandate HL7 FHIR compliance for all patient-facing applications. London's academic medical centers and Greater Manchester's devolved health economy represent contrasting procurement models for referral automation.
India
Corporate hospital chains and health tech startups deploy lightweight cloud platforms to coordinate referrals across fragmented provider networks. The Digital India mission and CDSCO software-as-medical-device guidance reshape platform compliance obligations for multi-tenant deployments. Karnataka's Bangalore cluster and Maharashtra's Mumbai-Pune corridor concentrate health IT engineering talent and venture capital flows.
Japan
Metropolitan hospital networks seek middleware solutions bridging legacy HL7 v2 installations with modern FHIR architectures. METI's Society 5.0 initiative and PMDA software guidance influence product roadmaps for AI-embedded referral tools. Tokyo's Keiyō industrial corridor and Osaka's Kansai medical district anchor enterprise deployment decisions for cloud-native coordination platforms.
Patient Referral Management Software Market Key Industry Players
Top-tier vendors anchor hospital EHR ecosystems, while mid-tier cloud-native specialists compete on implementation speed and subscription flexibility. Market structure tilts toward consolidation as health system procurement favors unified platforms over point solutions. Three archetypes dominate: EHR incumbents extending captive networks, ambulatory workflow platforms expanding into coordination, and standalone interoperability vendors targeting specialty verticals. Competitive moves concentrate on strategic partnerships with payer networks and API-first integration alliances.
Within the EHR-incumbent tier, Epic and Oracle Health occupy positions exemplifying ecosystem lock-in strategies that leverage existing data repository dominance. Among cloud-native specialists, athenahealth represents the archetype of network-effects-driven physician practice platforms, while Phreesia anchors ambulatory intake workflows extending into referral coordination. Luma Health and Klara sit within the patient-engagement-first segment, illustrating how communication-centric platforms wedge into coordination workflows through existing clinical relationships.
| Leading Market Players |
|---|
| Luma Health |
| Phreesia |
| Epic |
| Blockit Health |
| Klara |
| Oracle Health |
| Linear Health |
| PointClickCare |
| athenahealth |
| Others |
Cost & Logistics Intelligence
Cloud infrastructure pricing indices from hyperscalers cascade through SaaS delivery models into subscription tiers for health systems and ambulatory networks, compressing margins for vendors while expanding procurement flexibility for buyers.
Pricing Analysis
Capacity additions in cloud computing regions are reshaping price floors for multi-tenant referral platforms, forcing vendors toward usage-based subscription models. Pricing stratifies across enterprise, mid-market, and clinic tiers based on integration complexity and analytics depth. Cost compression in the mid-market tier is intensifying because Epic and Oracle Health bundle referral capabilities at marginal cost. Independent physician associations exhibit highest price sensitivity, while integrated delivery networks prioritize total cost of ownership over per-seat rates.
Supply Chain Analysis
FHIR R4 certification and HIPAA compliance audits gate vendor participation, filtering platform providers before procurement cycles begin. Engineering talent concentrates in the United States, India, and Israel, with Hyderabad and Bangalore clusters feeding offshore development centers. Cloud infrastructure draws from Amazon Web Services, Microsoft Azure, and Google Cloud Platform, creating single-source vulnerability for vendors locked to one hyperscaler. Distribution runs through direct enterprise sales teams and channel partnerships with EHR implementation specialists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in referral management hinges on automation density, where AI-embedded prior authorization and intelligent routing compress implementation costs while commanding premium subscription tiers.
For Market Incumbents: Cement ecosystem lock-in through deeper EHR workflow embedding and captive analytics layers that increase switching costs. Oracle Health and Epic should accelerate API-first partnerships with specialty pharmacy networks before cloud-native challengers gain FHIR interoperability footholds. Vertical integration into NLP engines for clinical note parsing offers a defensive moat against point-solution entrants. For New Entrants and Emerging Players: The 21st Century Cures Act in the United States opens a window for standalone platforms to penetrate independent physician associations in Texas and California Medicaid managed care corridors. Behavioral health carve-ins and specialty pharmacy prior authorization automation represent the most penetrable white spaces. A channel partnership strategy with regional health information exchanges accelerates credentialing and reduces direct sales cycle length. For Investors and Strategic Acquirers: Asymmetric upside sits with cloud-native vendors holding FHIR R4 certification and existing payer network integrations. Five-to-ten year viability favors platforms with recurring revenue above eighty percent and expanding gross margins from automation scale. Watch for CMS value-based payment program expansions into behavioral health as an inflection indicator for referral tracking demand.| Strategic Initiative | Industry Significance |
|---|---|
| FHIR API Certification | ONC interoperability mandates under the 21st Century Cures Act penalize information blocking, forcing vendor compliance investments. |
| Specialty Pharmacy Integration | Oncology and rare disease workflows lack embedded prior authorization automation, creating white space for vertical platforms. |
| Behavioral Health Expansion | Medicare Advantage plans expanding mental health coverage generate demand for closed-loop psychiatric referral tracking. |
| AI-Embedded Routing | Natural language processing convergence with referral intake compresses submission time from hours to minutes in cardiology networks. |
| Medicaid Managed Care Partnerships | State-level contracts in Texas and California reward care coordination, opening procurement channels for cloud-native vendors. |
Research Approach
Bottom-up health system deployment modeling reconciled against top-down vendor revenue tracking forms the analytical core of this study. Primary interviews with hospital CIOs, ambulatory clinic operations directors, EHR integration specialists, and payer care coordination executives combined with secondary validation from CMS Medicare data, ONC interoperability filings, and hospital procurement databases. Triangulation across stakeholder perspectives and documentary sources ensures segment-level accuracy.
Historical trendline analysis of cloud SaaS adoption in healthcare IT established baseline growth patterns across the projection horizon. The analytical framework models deployment model, organization size, care setting vertical, integration complexity, and regional regulatory cluster as segmentation dimensions. CAGRs derive from fitted growth curves adjusted for policy implementation timelines and health system capital cycle phasing. Forecast inputs include EHR vendor market concentration indices and value-based contract penetration rates by state.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated HIPAA enforcement or delays in FHIR API standardization across legacy systems. Model assumptions reflect documented regulatory schedules and health system procurement patterns. A model refresh is warranted upon material change in CMS reimbursement rulemaking or ONC information-blocking penalty implementation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare IT
Patient Registry Software Market
Healthcare IT
Neurosurgery Software Market
Healthcare IT
Epharmacy Market
Healthcare IT
Patient Self-Service Kiosks Market
Healthcare IT
Healthcare Ediscovery Market
Healthcare IT
Middle East and Africa Nurse Call Systems Market
Healthcare IT
Femtech Market
Healthcare IT
Dental Implantology Software Market
Healthcare IT
United States Pharmacy Management System Market
Healthcare IT
Commercial Pharmaceutical Analytics Market
Healthcare IT
North American Dental Software Market
Healthcare IT
ECG Management Systems Market
Healthcare IT
Global Telepharmacy Market
Healthcare IT
Digital Mhealth Solution Market
Healthcare IT
Healthcare IT Market
Healthcare IT
Prior Authorization Workflow Orchestration Market