
 Epharmacy Market | 2026-2036
Epharmacy Market Size, Share, and Industry Trends Forecast 2026-2036
Epharmacy Market Intelligence
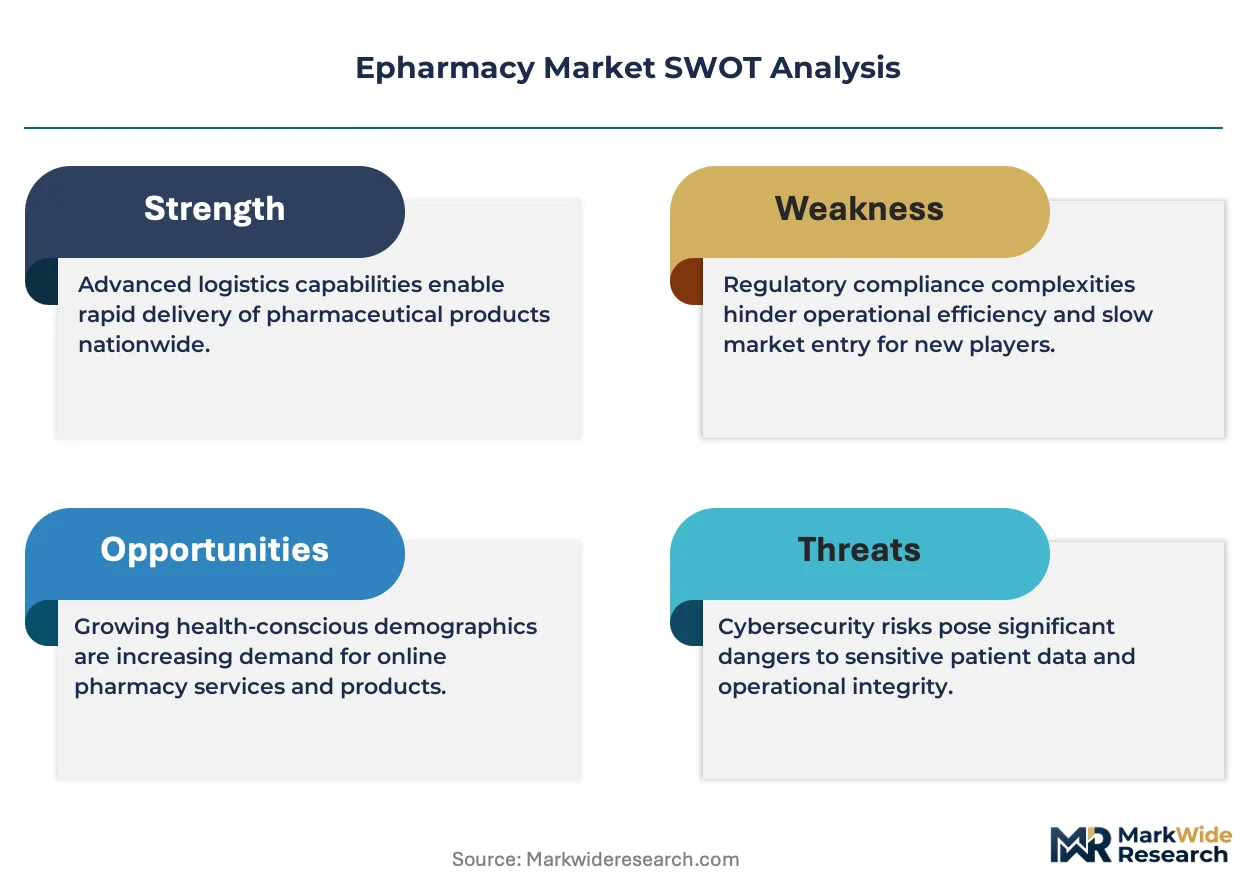
The EU F-Gas Regulation's phasedown of hydrofluorocarbon-based cold chain refrigerants is shifting temperature-controlled pharmaceutical logistics toward greener alternatives. CVS Health Corporation leverages its vertically integrated pharmacy benefits management platform to sustain nationwide same-day delivery coverage. Walgreen Co. anchors urban market share through dense brick-and-mortar networks that double as fulfillment nodes for digital orders. Walmart, Inc. competes on price transparency by extending its retail pharmacy infrastructure into rural epharmacy access.
An epharmacy constitutes a digitally operated pharmaceutical retail platform that processes prescriptions, dispenses medications, and delivers health products through web or mobile interfaces, typically integrating electronic health record verification and cold-chain logistics for biologics. Its primary commercial purpose eliminates geographic barriers between patients and licensed pharmacists while reducing fulfillment costs through centralized inventory and automated compliance checking. Prescription Medications dominate revenue pools due to recurring chronic therapy refills and insurance reimbursement structures, while Telehealth Services represent the fastest-expanding segment as synchronous video consultations become reimbursable events tied to prescription issuance. Over-the-Counter Products occupy mature margin territory where price comparison engines compress premiums.
The FDA enforces track-and-trace serialization under the Drug Supply Chain Security Act, compelling epharmacies to implement interoperable verification systems before dispensing. HIPAA privacy rules shape patient data architecture, restricting how platforms personalize medication adherence outreach. State boards of pharmacy impose varying teleprescribing licensure requirements that fragment operational compliance across jurisdictions. Stakeholders must monitor evolving state-level scope-of-practice expansions for pharmacists, as these permissions directly determine which clinical services epharmacies can monetize beyond product fulfillment.
Market Dynamics
The Drug Supply Chain Security Act's serialization mandates are forcing epharmacies to rebuild verification infrastructure before 2025 compliance deadlines, while chronic disease patients drive volume through recurring prescription automation.
Growth Catalysts
- Telehealth reimbursement expansion:Medicare Advantage plans in the United States now cover synchronous video consultations tied to prescription issuance, converting virtual visits into pharmacy revenue events.
- Cold-chain biologics demand:Temperature-sensitive specialty medications require precision logistics that centralized epharmacy fulfillment centers execute more reliably than fragmented retail networks.
- FDA track-and-trace mandates:The Drug Supply Chain Security Act compels interoperable verification systems that favor scaled platforms with capital to deploy serialization infrastructure.
Market Restraints
- State licensure fragmentation:Teleprescribing permissions vary across United States state boards of pharmacy, forcing redundant compliance architectures and limiting cross-border prescription fulfillment.
- Refrigerant supply constraints:The EU F-Gas Regulation's hydrofluorocarbon phasedown restricts cold-chain logistics capacity, raising costs for temperature-controlled pharmaceutical distribution.
- HIPAA data architecture limitations:Privacy rules restrict personalized medication adherence outreach, capping retention marketing effectiveness for chronic therapy patients.
Strategic Opportunities
- Rural access gaps:Underserved United States counties lack brick-and-mortar pharmacy density, creating white space for centralized fulfillment with last-mile delivery partnerships.
- Pharmacist scope-of-practice expansion:State-level clinical service permissions enable epharmacies to monetize vaccination administration and chronic disease management beyond product margins.
- Green cold-chain alternatives:Natural refrigerant technologies and passive thermal packaging are converging to replace hydrofluorocarbon-dependent logistics for biologics distribution.
Industry Challenges
- Interoperable system integration:EHR verification platforms must connect with disparate hospital and payer systems, creating legacy data migration complexity.
- Serialized inventory management:Item-level tracking requirements demand warehouse management system upgrades and staff retraining across fulfillment networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Epharmacy Market |
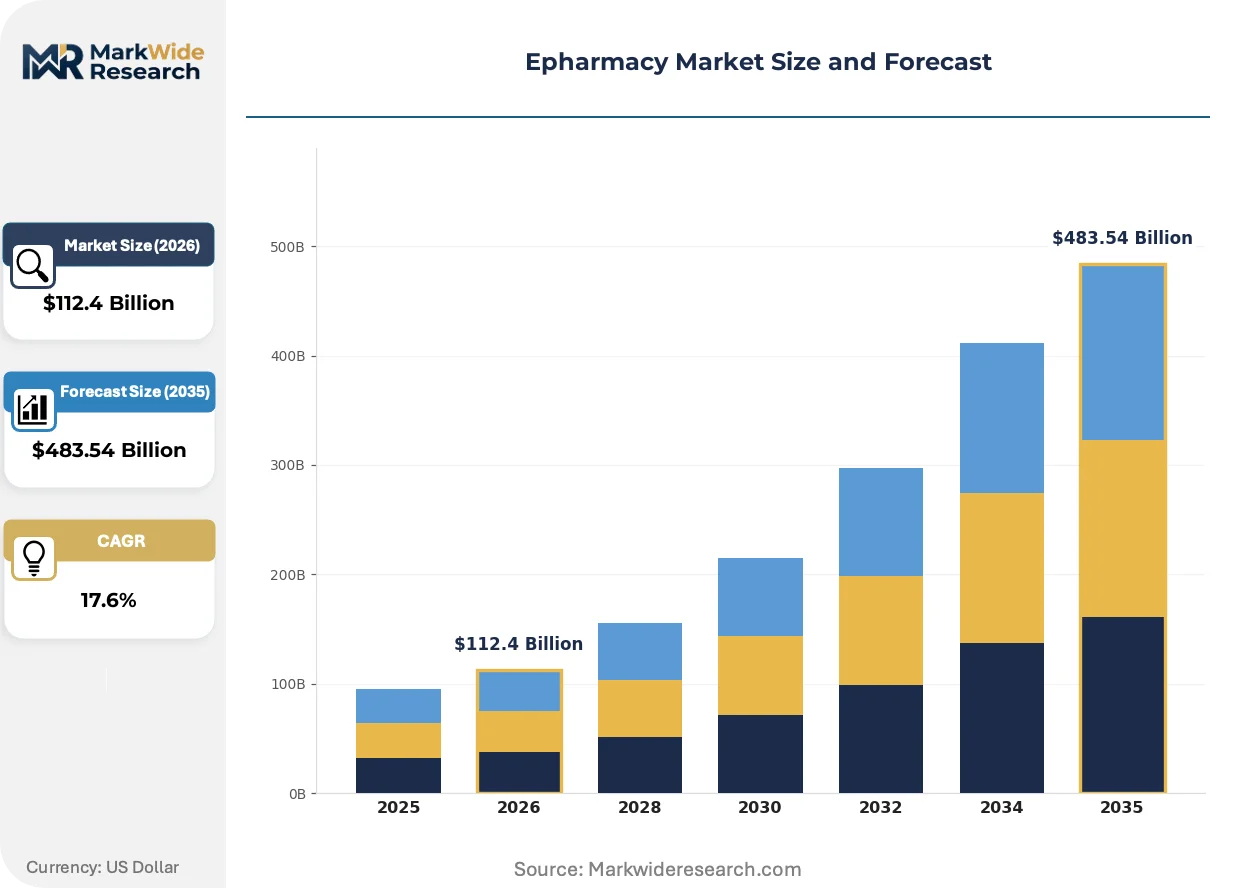
| Market Size in 2026 | $112.4 Billion |
| Market Size in 2035 | $483.54 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prescription Medications, Over-the-Counter Products, Personal Care Items, Nutraceuticals Delivery Method: Home Delivery, Click and Collect, Automated Dispensing Machines, Digital Prescriptions Customer Type: Individuals, Families, Seniors, Healthcare Providers Service Type: Pharmacy Services, Consultation Services, Health Monitoring, Telehealth Services |
| Companies Covered | CVS Health Corporation, Walgreen Co., DocMorris, Express Scripts Holding Company, The Kroger Co., Optum Rx, Inc., Walmart, Inc., Giant Eagle, Inc., Rowlands Pharmacy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Epharmacy Market Strategic Shifts & Innovations
Automation and regulatory compliance are reshaping how epharmacies architect fulfillment infrastructure, with three distinct shifts altering competitive requirements.
AI-powered prescription verification is absorbing pharmacist labor hours previously dedicated to manual drug interaction screening. Chronic disease management platforms deploy machine learning to flag adherence risks before refill lapses occur. This compression of clinical review time is absorbing margin pressure from reimbursement rate compression while maintaining safety standards.
The EU F-Gas Regulation is accelerating cold-chain refrigerant transitions across European pharmaceutical logistics networks. Temperature-controlled biologics distributors must retrofit fleet equipment or absorb penalty costs. German and French logistics hubs are responding fastest, with Nordic markets lagging due to smaller biologics volumes.
Subscription-based chronic therapy models are replacing episodic prescription fulfillment for diabetes, hypertension, and cardiovascular patients. United States Medicare Advantage plans now prefer automated 90-day refill programs over traditional 30-day retail pickups. This behavioral pivot concentrates volume with platforms capable of predictive inventory positioning and patient communication automation.
Epharmacy Market Segmentation
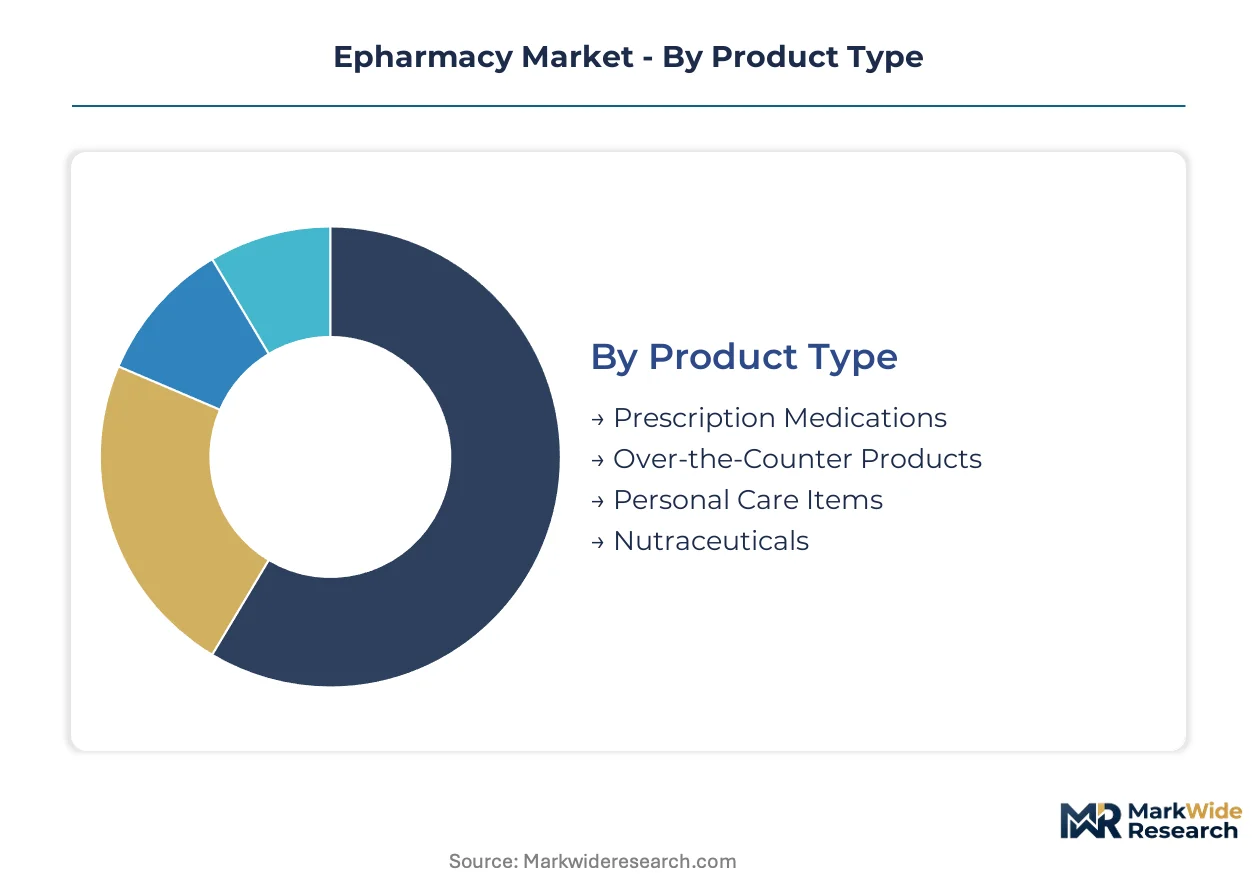
Segmentation in the epharmacy market reveals how platform architecture and fulfillment models must adapt to distinct product requirements, patient behaviors, and reimbursement pathways. Each dimension carries different margin profiles and regulatory exposure.
Product Type:
Standalone prescription fulfillment dominates platform revenue, while embedded wellness commerce creates cross-sell opportunities at checkout.
- Prescription Medications:These require electronic health record verification, insurance adjudication, and pharmacist review before dispensing. Chronic disease patients in the United States drive recurring refill automation through Medicare Advantage-covered home delivery programs.
- Over-the-Counter Products:Non-prescription health items carry lower regulatory burden but face price compression from comparison engines. Margin pressure concentrates in analgesics and cold remedies where generic substitution is routine.
- Personal Care Items:Skincare, hygiene, and cosmetic products extend basket size without prescription validation overhead.
- Nutraceuticals:Vitamins and supplements occupy a regulatory gray zone between food and drug classifications, requiring careful labeling compliance.
Prescription Medications leads volumes today; Telehealth-integrated dispensing is gaining share fastest.
Delivery Method:
Cost tier separation runs from premium same-day courier services to economy postal fulfillment, with cold-chain biologics commanding specialized logistics premiums.
- Home Delivery:Direct-to-patient shipping requires temperature-controlled infrastructure for biologics and signature verification for controlled substances. Rural United States counties lack pharmacy density, making this the default access mode.
- Click and Collect:Digital order with physical pickup merges online convenience with immediate product availability. Urban markets favor this hybrid where brick-and-mortar networks remain dense.
- Automated Dispensing Machines:Locker-based retrieval reduces last-mile labor costs for routine refills.
- Digital Prescriptions:Pure electronic transmission to patient-chosen pharmacies eliminates physical handling entirely.
Home Delivery captures the largest volume base; Click and Collect is expanding most quickly in metropolitan clusters.
Customer Type:
Application context varies from acute episodic needs to chronic disease management programs with embedded adherence monitoring.
- Individuals:Single-patient accounts generate the majority of transaction volume but lower per-account lifetime value without chronic conditions.
- Families:Multi-member household consolidation drives larger average order values and subscription attachment for pediatric and parental care needs.
- Seniors:Medicare-eligible patients require simplified interfaces and proactive refill management for polypharmacy regimens.
- Healthcare Providers:Institutional accounts including clinics and long-term care facilities purchase in bulk with formulary compliance requirements.
Individuals dominate transaction counts; Seniors show the steepest expansion trajectory as Medicare Advantage penetration deepens.
Service Type:
Maturity differentiation separates established dispensing operations from emerging clinical revenue streams that extend pharmacist scope-of-practice.
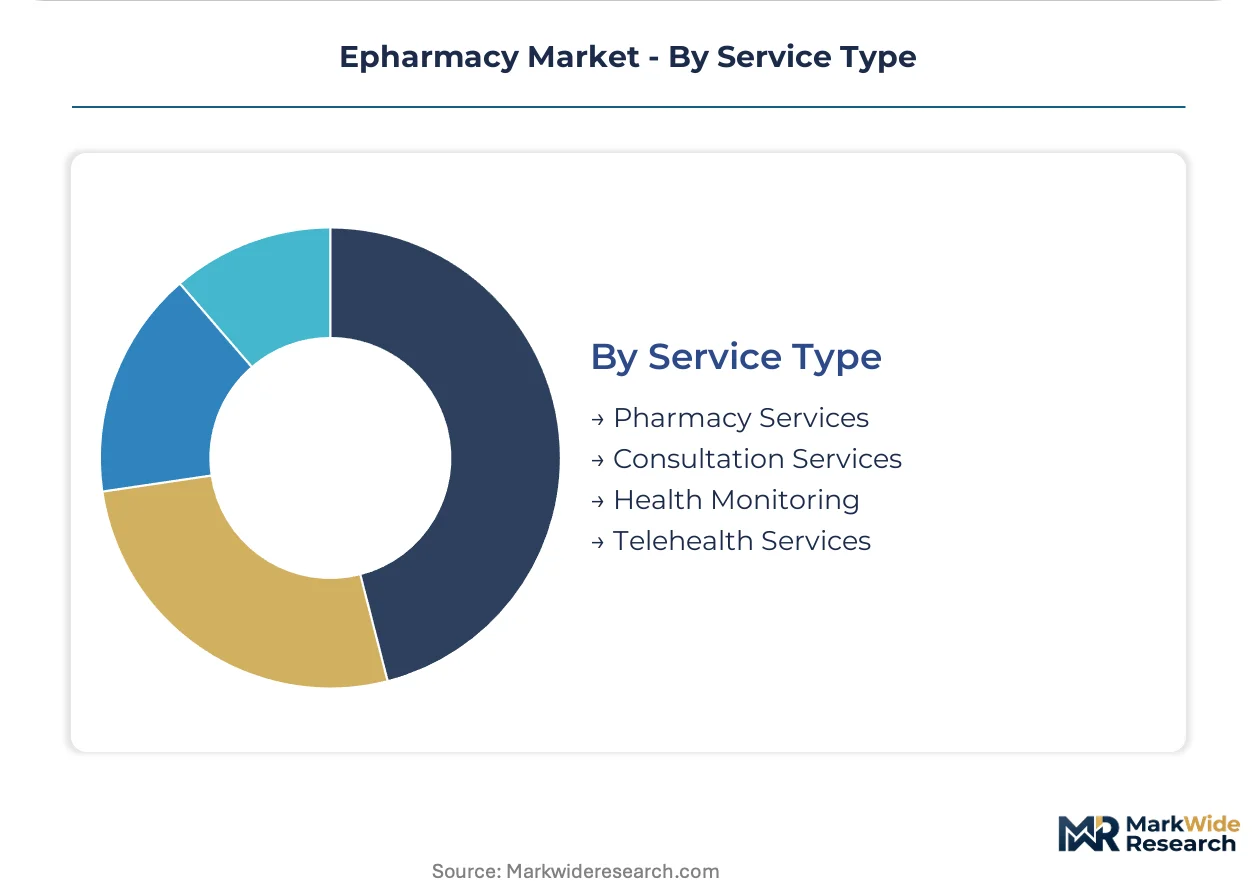
- Pharmacy Services:Core dispensing and medication therapy management remain the revenue foundation. FDA Drug Supply Chain Security Act serialization mandates are forcing verification infrastructure upgrades.
- Consultation Services:Asynchronous pharmacist counseling addresses drug interactions and dosing questions. State-level scope expansions determine reimbursement eligibility.
- Health Monitoring:Remote patient data collection for chronic conditions creates adherence insights but faces HIPAA architecture constraints on personalized outreach.
- Telehealth Services:Synchronous video consultations tied to prescription issuance convert clinical encounters into pharmacy revenue events. Medicare Advantage coverage expansion is accelerating adoption.
Pharmacy Services anchors revenue today; Telehealth Services is climbing the fastest as virtual visit reimbursement stabilizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Licensed pharmacists and pharmacy technicians concentrate in urban corridors where epharmacy fulfillment centers cluster near major hospital systems and insurance headquarters.
United States
Medicare Advantage penetration drives automated 90-day refill programs for chronic disease patients. The FDA's Drug Supply Chain Security Act mandates item-level serialization verification before dispensing. Boston and Minneapolis anchor major pharmacy benefit management operations with dense clinical pharmacist staffing.
Germany
DocMorris and other mail-order platforms capture statutory health insurance reimbursement for prescription delivery. The EU F-Gas Regulation accelerates cold-chain refrigerant retrofits for biologics distribution. The Rhine-Ruhr corridor hosts temperature-controlled pharmaceutical logistics hubs serving Benelux markets.
United Kingdom
Rowlands Pharmacy and competing chains integrate digital prescription routing with NHS Electronic Prescription Service infrastructure. The Medicines and Healthcare products Regulatory Agency enforces serialized tracking aligned with EU standards. Greater Manchester and Birmingham concentrate fulfillment automation investments for same-day urban delivery.
India
Urban middle-class expansion and smartphone penetration enable app-based pharmacy aggregation models. The Central Drugs Standard Control Organization requires cold-chain documentation for temperature-sensitive biologics. Bangalore and Hyderabad host venture-backed epharmacy platforms with integrated telehealth services.
China
Alibaba Health and JD Health process prescription orders through hospital-linked electronic medical record systems. The National Medical Products Administration enforces internet drug information service licenses for online pharmacies. Shanghai and Shenzhen anchor cross-border e-commerce pharmaceutical import zones.
Epharmacy Market Key Industry Players
Capital-heavy pharmacy benefit managers compete with asset-light telehealth-integrated platforms for prescription volume capture. The vendor base stratifies across three tiers: vertically integrated health insurers with captive pharmacy networks, standalone retail pharmacy chains with digital fulfillment overlays, and pure-play digital health platforms without physical infrastructure. Strategic archetypes include PBM-first consolidators, retail-digital hybrids, and telehealth-native dispensers. Dominant competitive moves encompass same-day delivery network expansion and pharmacist scope-of-practice monetization beyond product margins.
Among US-based integrated health systems, CVS Health Corporation and Walgreen Co. occupy positions as archetypal retail-digital hybrids with dense brick-and-mortar networks repurposed as fulfillment nodes. Walmart, Inc. exemplifies the mass-market price transparency vector, leveraging existing retail pharmacy infrastructure to extend rural epharmacy access where independent pharmacy density has declined.
| Leading Market Players |
|---|
| CVS Health Corporation |
| Walgreen Co. |
| DocMorris |
| Express Scripts Holding Company |
| The Kroger Co. |
| Optum Rx, Inc. |
| Walmart, Inc. |
| Giant Eagle, Inc. |
| Rowlands Pharmacy |
| Others |
Cost & Logistics Intelligence
Private-equity-rolled-up pharmacy benefit managers anchor pricing discipline through captive formulary control and centralized mail-order fulfillment, compressing margins for independent retail pharmacies while extracting rebates from manufacturers. Their ownership structure rewards volume consolidation over service differentiation, creating tiered access economics that favor Medicare Advantage enrollees with automated 90-day refill programs.
Pricing Analysis
Bundled prescription-adherence services versus unbundled per-fill transactions defines the dominant pricing split, with subscription-based chronic therapy models commanding premium positioning against episodic retail pickups. Price differentiation hinges on cold-chain logistics certification and synchronous telehealth integration, with temperature-controlled biologics carrying specialized handling premiums. Cost compression in routine generic dispensing intensifies as price comparison engines commoditize over-the-counter adjacencies. Individual cash-pay patients exhibit highest price sensitivity; Medicare Advantage-covered seniors show lowest elasticity due to fixed copay structures.
Supply Chain Analysis
Reverse-logistics flows for temperature-sensitive biologics require specialized returns handling and controlled destruction protocols that inflate operational overhead. Supply concentration centers on the United States, Germany, and India, with API sourcing drawing from Chinese and Indian chemical manufacturers. Serialized inventory tracking under FDA Drug Supply Chain Security Act mandates rests on interoperable verification infrastructure. Single-source vulnerability concentrates in cold-chain refrigerant supply chains constrained by EU F-Gas Regulation phasedowns. Distribution runs through centralized fulfillment centers with last-mile courier partnerships for controlled substances and biologics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The epharmacy market reads as a late-cycle quality story as chronic disease management demands shift toward premium cold-chain reliability and embedded telehealth coordination.
For Market Incumbents: Hedge against margin erosion in generic dispensing by deepening backward integration into specialty pharmacy services and pharmacist-led clinical programs. Consolidate redundant brick-and-mortar footprints into fulfillment nodes serving dense urban corridors. Defensive moves must address telehealth-native dispensers capturing Medicare Advantage volume through seamless video-to-prescription workflows. For New Entrants and Emerging Players: Launch via direct-to-senior subscription models targeting rural counties with pharmacy deserts and limited Medicare Advantage penetration. White-space opportunities concentrate in chronic disease management platforms with predictive adherence analytics. The most penetrable segment combines automated refill orchestration with remote patient monitoring for diabetes and cardiovascular patients. For Investors and Strategic Acquirers: Valuations sit cheapest among regional pharmacy chains with underutilized cold-chain infrastructure and untapped telehealth licensing. Long-term viability favors platforms with demonstrated FDA serialization compliance and established Medicare Advantage plan contracts. The signal to watch is state-level pharmacist scope-of-practice expansion enabling clinical service reimbursement beyond product margins.| Strategic Initiative | Industry Significance |
|---|---|
| Telehealth-Integrated Dispensing Platform | Medicare Advantage reimbursement rules now cover synchronous video consultations tied to prescription issuance. |
| Cold-Chain Refrigerant Retrofit Program | EU F-Gas Regulation compliance requires hydrofluorocarbon phaseout for temperature-controlled biologics distribution. |
| Serialized Inventory Management System | FDA Drug Supply Chain Security Act mandates item-level verification before dispensing across all fulfillment nodes. |
| Pharmacist Scope-of-Practice Expansion | State-level clinical service permissions enable vaccination administration and chronic disease management monetization. |
| Rural Last-Mile Delivery Partnership | Underserved counties lacking brick-and-mortar density create white space for centralized fulfillment with courier networks. |
Research Approach
Multiple input streams — pharmacy benefit manager formulary directors, cold-chain logistics operators, state board of pharmacy regulators, and telehealth platform architects — were reconciled against secondary validation from FDA Drug Supply Chain Security Act guidance documents, CMS Medicare Advantage plan filings, and EU F-Gas Regulation implementation notices. Primary fieldwork captured operational constraints in serialized inventory management and temperature-controlled distribution. Bottom-up prescription volume modeling and top-down healthcare expenditure triangulation anchored market sizing.
Data-stream reconciliation across product type, delivery method, customer segment, and service category dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from patient population growth, telehealth reimbursement expansion rates, and cold-chain infrastructure investment cycles. Chronic disease prevalence trajectories and Medicare Advantage penetration curves served as key forecast inputs alongside state-level teleprescribing licensure evolution.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated FDA enforcement actions or refrigerant supply disruptions. Periodic stress-testing of base assumptions is recommended given regulatory fragmentation across state pharmacy boards and evolving HIPAA constraints on personalized adherence outreach.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare IT
Operating Room Software Market
Healthcare IT
Global Patient Intake Software Market
Healthcare IT
US Practice Management Systems Market
Healthcare IT
Global Orthopedic Software Market
Healthcare IT
Ambulatory Surgical Centers IT Services Market
Healthcare IT
Healthcare Survey Software Market
Healthcare IT
Global Hospital Asset Tracking and Inventory Management Systems Market
Healthcare IT
Prior Authorization Software Market
Healthcare IT
Healthcare Business Collaboration Tools Market
Healthcare IT
Cognitive Assessment and Training in Healthcare Market
Healthcare IT
Patient Referral Management Software Market
Healthcare IT
North American Dental Software Market
Healthcare IT
Anatomic Pathology Track and Trace Solutions Market
Healthcare IT
Cancer Patient Registry Software Market
Healthcare IT
Global Pharma Knowledge Management Software Market
Healthcare IT
Pharma Management Software Market