
 Asia-Pacific Dental Practice Management Software Market | 2026-2036
Asia-Pacific Dental Practice Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Dental Practice Management Software Market Insights
Cloud-native certification tiers is bifurcating the competitive landscape into premium interoperability providers and cost-focused local vendors. Henry Schein Inc. leverages its distribution network across Australia and New Zealand to sustain installed-base loyalty. Carestream Dental anchors its position through imaging-software integration that reduces clinic workflow fragmentation. Curve Dental competes on subscription flexibility, while Centaur Software Development Co Pty Ltd dominates the Australian domestic market with localized compliance modules.
Asia-Pacific dental practice management software encompasses patient scheduling, electronic health records, billing, and clinical workflow tools delivered through cloud, on-premise, mobile, or integrated architectures with HL7 FHIR interoperability protocols and AES-256 encryption standards. Cloud-based solutions lead volume adoption due to lower capital barriers for small clinics, though on-premise deployments retain share among Japanese university hospitals with strict data-localization requirements. Multi-user deployment models capture the fastest expansion as dental groups consolidate, while technical support services generate recurring margin pools that exceed installation revenue by substantial multiples.
Australia's TGA cybersecurity framework for medical devices, India's CDSCO software-as-medical-device guidelines, and Japan's METI data governance standards collectively shape product certification requirements and cross-border market access protocols. India's BIS IT security standards and China's GB/T data-protection mandates add further compliance layers that favor vendors with dedicated regulatory affairs teams. Stakeholders must monitor evolving data-sovereignty rules across Southeast Asian jurisdictions to determine whether localized hosting partnerships or regional cloud hubs offer superior risk-adjusted returns.
Market Dynamics
Cloud migration among multi-location dental chains is compressing deployment timelines and forcing vendors to modularize their architectures around HL7 FHIR interoperability standards.
Growth Catalysts
- India's PLI scheme for healthcare IT infrastructure:Production-linked incentives reduce capital barriers for software vendors establishing local data centers, accelerating cloud adoption among tier-2 dental practitioners.
- Japan's METI interoperability guidelines:Mandatory electronic health record integration creates compliance-driven replacement cycles for legacy on-premise systems in university hospitals.
- Multi-location consolidation:Dental clinic chains across Australia and Southeast Asia standardize on unified scheduling and billing platforms to capture operational efficiencies.
Market Restraints
- Data-localization mandates:Japan's strict data-sovereignty requirements for university hospitals block pure SaaS models and force costly hybrid architectures.
- Cybersecurity certification costs:Australia's TGA framework for medical device software imposes multi-year compliance timelines that strain regional vendor balance sheets.
- Substitute workflow tools:Generic practice management platforms adapted from general medical practices compete on price against dental-specialized solutions.
Strategic Opportunities
- India's tier-2 cities:Unmet digitalization needs among independent practitioners in secondary metros outpace metropolitan market saturation.
- AI-powered diagnostic integration:Convergence of radiology AI modules with practice management platforms creates premium pricing tiers for early adopters.
- Mobile-first deployment:Smartphone-native interfaces unlock penetration among solo practitioners in Southeast Asian markets with limited desktop infrastructure.
Industry Challenges
- HL7 FHIR implementation expertise:Shortage of developers with healthcare interoperability certification delays product roadmaps for mid-tier vendors.
- Legacy system integration:Proprietary data formats in installed on-premise systems resist standardized migration tools, extending implementation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Dental Practice Management Software Market |
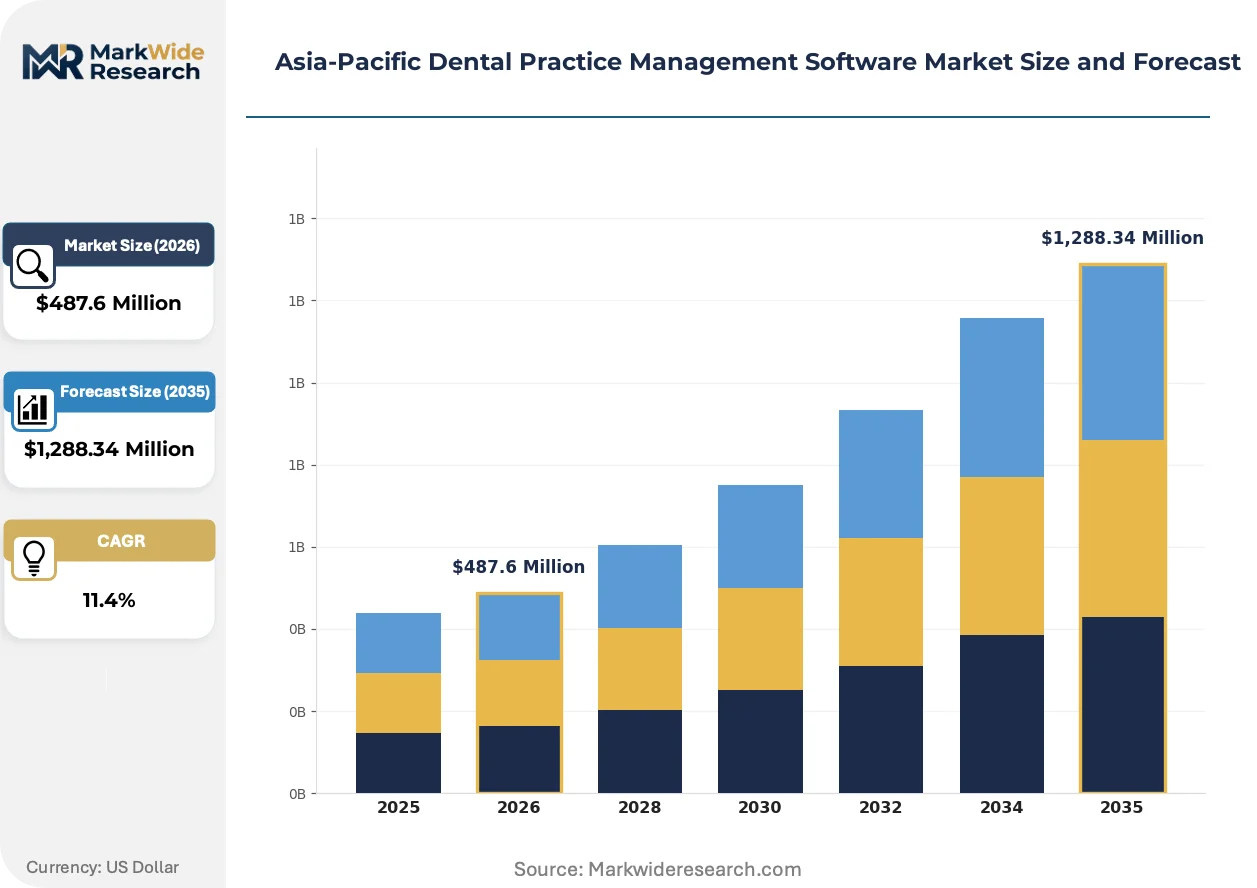
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,288.34 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-based Solutions, On-premise Solutions, Mobile Applications, Integrated Software End User: Private Dental Clinics, Dental Hospitals, Oral Surgeons, Dental Specialists Deployment: Single-user, Multi-user, Remote Access, Hybrid Solutions Service Type: Technical Support, Installation, Training, Consultation |
| Companies Covered | Henry Schein Inc., Carestream Dental, CareStack, Dentee, Centaur Software Development Co Pty Ltd, Curve Dental, NextGen Healthcare, Patterson Companies Inc., DentiMax, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Dental Practice Management Software Market Trends and Innovations
Modular software architectures are fragmenting the vendor landscape into specialized component providers and full-suite platforms, reshaping partnership strategies across the region.
Microservices-based practice management software is decomposing monolithic suites into interoperable scheduling, billing, and imaging modules. Multi-location dental groups in Australia and New Zealand are adopting these architectures fastest, compressing vendor switching costs and enabling best-of-breed procurement. This decomposition is eroding the lock-in advantages of legacy integrated suites.
India's CDSCO software-as-medical-device guidelines are formalizing cybersecurity documentation requirements for cloud-hosted patient data systems. Vendors must now submit penetration testing reports and encryption protocols before commercial deployment. Tier-2 city clinics are delaying purchases until preferred vendors complete certification, creating temporary demand pauses.
Subscription unbundling is separating technical support, implementation, and core platform access into independently priced components. Dental groups in Southeast Asia are selecting support tiers based on internal IT capability rather than defaulting to premium packages. Thailand and Vietnam show the fastest uptake of à-la-carte service contracts.
Asia-Pacific Dental Practice Management Software Market Segmentation
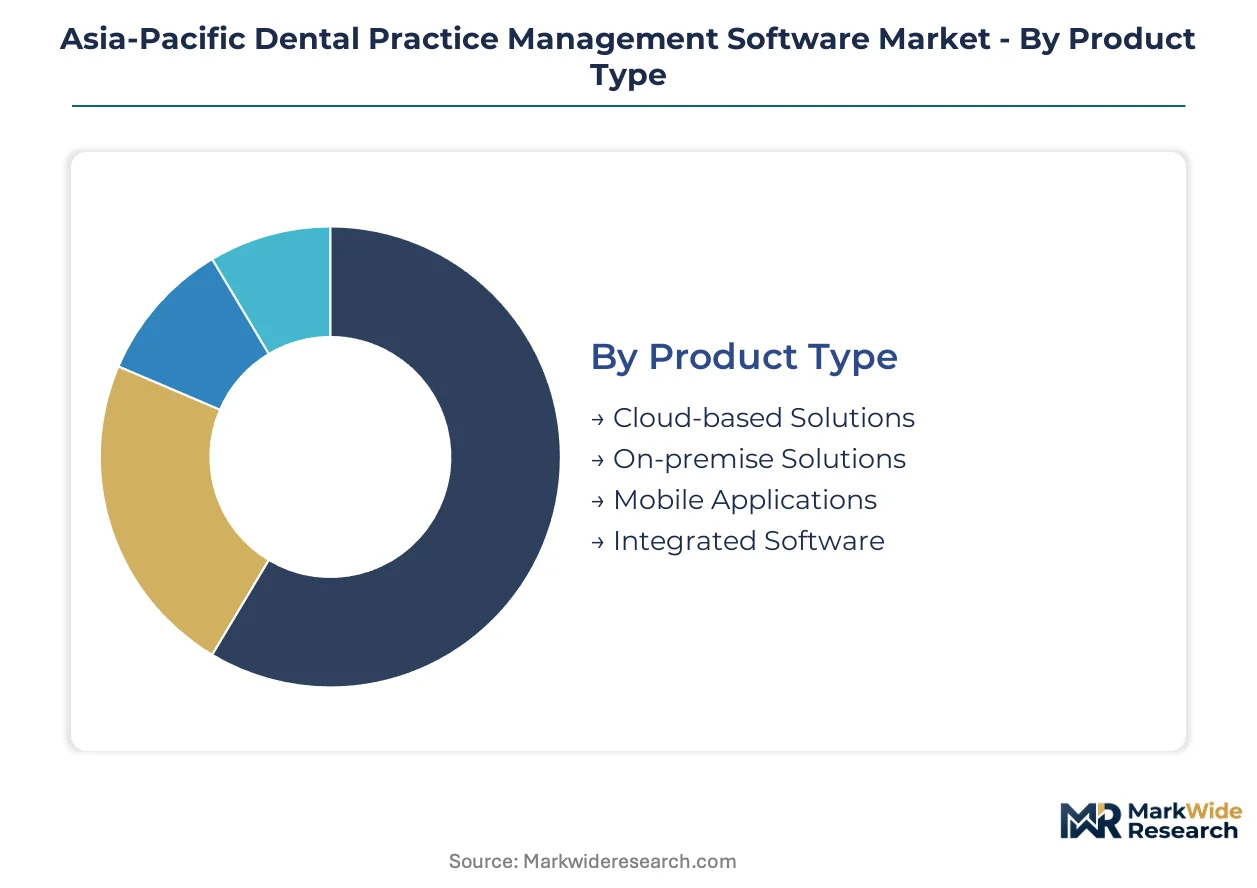
Segmentation in Asia-Pacific dental practice management software reveals how regulatory fragmentation and infrastructure heterogeneity fragment demand across deployment modes and service tiers. Each category reflects distinct compliance burdens, capital constraints, and interoperability requirements that shape vendor product roadmaps.
Product Type:
Australia's TGA cybersecurity framework for medical devices, India's CDSCO software-as-medical-device guidelines, and Japan's METI data governance standards each favor different architectural approaches based on data-localization stringency.
- Cloud-based Solutions:Browser-native architectures with AES-256 encryption and HL7 FHIR interoperability reduce upfront capital for small clinics. India's tier-2 cities concentrate demand here as PLI-subsidized local data centers address data-sovereignty concerns.
- On-premise Solutions:Locally installed servers with proprietary databases retain dominance in Japanese university hospitals where METI mandates strict physical data control. Compliance costs and extended implementation cycles limit expansion beyond institutional settings.
- Mobile Applications:Smartphone-native interfaces targeting solo practitioners in Southeast Asian markets with limited desktop infrastructure.
- Integrated Software:Unified suites combining scheduling, billing, imaging, and EHR modules for multi-location dental chains standardizing on single-vendor relationships.
Cloud-based Solutions handle the majority of throughput; Mobile Applications are gaining share fastest among independent practitioners.
End User:
Customer scale determines procurement sophistication, with large institutions demanding enterprise-grade interoperability while solo practitioners prioritize cost minimization.
- Private Dental Clinics:Independent and small-group practices representing the volume base across Australia, India, and Southeast Asia. Subscription flexibility and modular pricing drive vendor selection.
- Dental Hospitals:Institutional facilities with mandatory EHR integration requirements under Japan's METI guidelines and India's digital health mission. Compliance-driven replacement cycles sustain premium pricing.
- Oral Surgeons:Specialized practices requiring imaging-software integration and surgical workflow tools.
- Dental Specialists:Orthodontists, periodontists, and endodontists with procedure-specific documentation needs.
Private Dental Clinics absorb the largest deployment volume; Dental Hospitals show the steepest expansion trajectory as regulatory mandates accelerate system replacement.
Deployment:
User concurrency models align with organizational complexity, from solo practitioners to consolidated dental groups managing dozens of locations.
- Multi-user:Concurrent access architectures enabling centralized scheduling and billing across dental group networks. Australian and Southeast Asian chains adopt fastest to capture operational efficiencies from standardization.
- Single-user:Standalone licenses for solo practitioners with limited IT infrastructure. India's tier-2 independent dentists dominate this segment.
- Remote Access:VPN or zero-trust architectures supporting off-site administrative work.
- Hybrid Solutions:Mixed on-premise and cloud architectures for Japanese institutions navigating strict data-localization requirements.
Multi-user deployments command the highest revenue per account; Hybrid Solutions are climbing fastest as vendors architect around Japan's data-sovereignty constraints.
Service Type:
Recurring service margins now substantially exceed installation revenue, reshaping vendor business models toward long-term relationship economics.
- Technical Support:Tiered subscription packages spanning basic ticketing to dedicated account management. Southeast Asian dental groups increasingly select support levels à-la-carte based on internal IT capability.
- Training:Onboarding and continuing education for clinical and administrative staff.
- Installation:Initial deployment, data migration, and system configuration services.
- Consultation:Workflow optimization and regulatory compliance advisory.
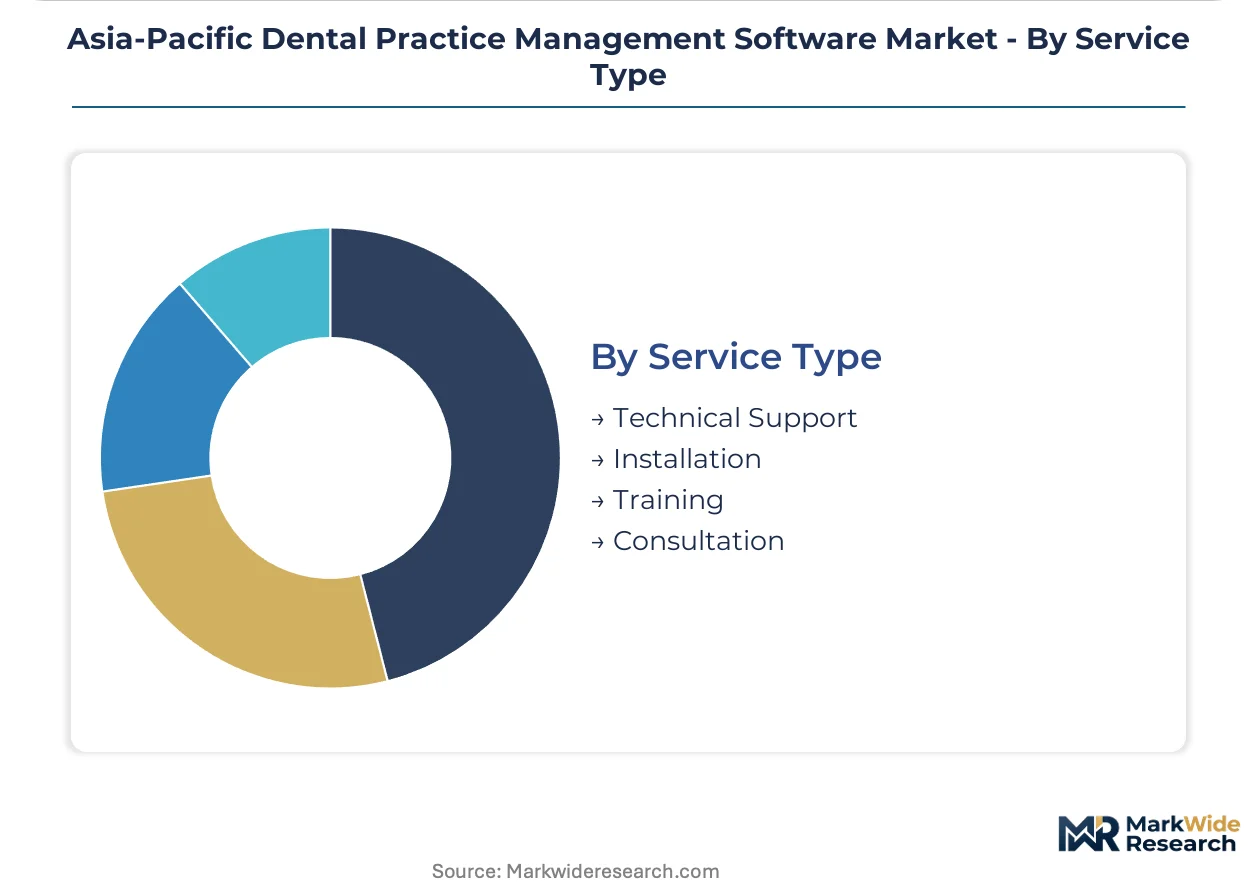
Technical Support generates the majority of recurring margin pools; Consultation is expanding most quickly as regulatory complexity deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across the Asia-Pacific region, with Indian tier-2 cities showing acute price sensitivity while Australian metropolitan markets absorb premium interoperability solutions without volume compression.
Australia
Multi-location dental chains in Sydney and Melbourne are standardizing on unified cloud platforms to capture operational efficiencies from centralized scheduling. The TGA cybersecurity framework for medical devices imposes multi-year compliance timelines that favor established vendors with dedicated regulatory affairs teams. Brisbane and Perth clusters concentrate demand among independent practitioners seeking modular subscription tiers.
India
Unmet digitalization needs among independent dentists in Lucknow, Jaipur, and Indore outpace metropolitan market saturation, creating concentrated demand pockets. The PLI scheme for healthcare IT infrastructure subsidizes local data center establishment, reducing capital barriers for cloud vendors targeting tier-2 practitioners. CDSCO software-as-medical-device guidelines formalize cybersecurity documentation requirements that delay purchases until certification completion.
Japan
University hospitals in Tokyo and Osaka retain dominance of on-premise deployments due to METI-mandated strict physical data control requirements. Mandatory electronic health record interoperability guidelines create compliance-driven replacement cycles for legacy systems. Nagoya and Fukuoka medical clusters show emerging hybrid architecture adoption as vendors architect around data-sovereignty constraints.
South Korea
MFDS medical device software regulations shape product certification pathways for vendors seeking hospital procurement contracts. Seoul's dense dental clinic networks drive multi-user deployment adoption for operational standardization. Busan and Daegu metropolitan areas concentrate independent practitioner demand for mobile-first solutions with smartphone-native interfaces.
Southeast Asia
Thailand and Vietnam show fastest uptake of à-la-carte technical support contracts as dental groups select service tiers based on internal IT capability. Singapore's regulatory alignment with international standards positions it as a regional cloud hub for vendors navigating fragmented data-sovereignty rules. Bangkok and Ho Chi Minh City clusters concentrate demand among emerging dental chains seeking subscription flexibility.
Asia-Pacific Dental Practice Management Software Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Asia-Pacific dental practice management software market. The vendor landscape bifurcates between premium interoperability providers with dedicated regulatory affairs teams and cost-focused local vendors serving price-sensitive independent practitioners. Three strategic archetypes dominate: distribution-leveraged incumbents, imaging-integrated specialists, and subscription-flexible challengers. Competitive intensity centers on M&A activity targeting regional compliance capabilities and strategic partnerships with local data center operators.
Within the distribution-leveraged tier, Henry Schein Inc. and Patterson Companies Inc. occupy positions sustained by installed-base loyalty across Australia and New Zealand. Carestream Dental exemplifies the imaging-integrated specialist archetype, while Curve Dental and Centaur Software Development Co Pty Ltd represent contrasting approaches to subscription flexibility and localized compliance modules respectively.
| Leading Market Players |
|---|
| Henry Schein Inc. |
| Carestream Dental |
| CareStack |
| Dentee |
| Centaur Software Development Co Pty Ltd |
| Curve Dental |
| NextGen Healthcare |
| Patterson Companies Inc. |
| DentiMax |
| Others |
Pricing and Supply Chain Analysis
Cloud-native modular architectures replacing monolithic on-premise suites are redrawing procurement geography across Australia, India, and Japan while compressing lifetime customer value into recurring subscription streams rather than perpetual license peaks.
Pricing Analysis
Technical support and implementation service tiers now generate lifetime value multiples exceeding core platform access across Asia-Pacific dental software contracts. Three-tier pricing structure across premium interoperability, standard compliance, and economy self-service levels stratifies by HL7 FHIR certification grade and data-localization capability. Pricing pressure stems from India's PLI-subsidized local data centers enabling aggressive SaaS entry by domestic vendors. Independent practitioners in tier-2 Indian cities exhibit acute price sensitivity, while Japanese university hospitals absorb premium hybrid architecture costs without volume compression.
Supply Chain Analysis
Inventory cycles for encryption hardware and localized server infrastructure stretch implementation timelines by 8-14 weeks across the region. Software development concentrates in India, Australia, and Singapore, with cloud hosting infrastructure drawing from AWS, Azure, and Alibaba Cloud regional data centers. Supply chain risk centers on single-source vulnerability for HL7 FHIR certification expertise, where qualified developers remain scarce. Distribution runs through direct vendor sales teams for enterprise dental groups and value-added resellers serving independent practitioners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific dental practice management software represents a high-growth disruption as Japan's METI interoperability mandates force compliance-driven replacement of legacy on-premise systems across university hospital networks.
For Market Incumbents: Secure installed-base loyalty by embedding AI-powered diagnostic modules into existing scheduling workflows before imaging-integrated specialists capture premium tier migration. Acquire regulatory affairs capabilities in India and Australia to compress CDSCO and TGA certification timelines that currently strain mid-tier vendor balance sheets. For New Entrants and Emerging Players: Anchor in India's tier-2 cities where unmet digitalization needs among independent dentists outpace metropolitan saturation. Target mobile-first deployment architectures for Southeast Asian solo practitioners lacking desktop infrastructure, using à-la-carte support pricing to undercut bundled incumbent offerings. For Investors and Strategic Acquirers: CDSCO software-as-medical-device guidelines reshape the acquisition landscape by formalizing cybersecurity documentation requirements that delay revenue recognition until certification completion. Vendors with completed penetration testing protocols and AES-256 encryption standards represent prime targets. Watch for temporary demand pauses in tier-2 Indian markets as preferred vendors clear regulatory hurdles—resumption signals execution capability.| Strategic Initiative | Industry Significance |
|---|---|
| HL7 FHIR Interoperability Certification | CDSCO and TGA frameworks mandate standardized data exchange, blocking non-compliant vendors from hospital procurement. |
| Local Data Center Partnership | India's PLI scheme subsidizes cloud infrastructure establishment, reducing capital barriers for tier-2 city penetration. |
| AI Diagnostic Module Integration | Convergence with radiology AI creates premium pricing tiers and defends against imaging-specialist competitors. |
| Mobile-Native Platform Launch | Smartphone-first interfaces unlock Southeast Asian solo practitioner segments with limited desktop infrastructure. |
| Regulatory Affairs Team Buildout | Dedicated compliance capabilities compress multi-year TGA and METI certification timelines that strain regional competitors. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of CDSCO certification databases, METI interoperability guidelines, TGA medical device registers, and dental group procurement disclosures across the analysis window. Interviews with practice management software CTOs, hospital biomedical engineers, dental group IT procurement officers, and HL7 FHIR integration specialists informed demand-side validation. SEC filings of listed healthcare IT vendors, hyperscaler cloud infrastructure disclosures, and Indian PLI scheme beneficiary lists supplied top-down market sizing anchors. Bottom-up clinic-by-clinic deployment estimates triangulated against macro-level healthcare IT spending trends.
Segmentation dimensions modeled span deployment architecture, end-user scale, user concurrency mode, and regional regulatory cluster across the projection horizon. CAGRs derive from regression analysis of historical adoption curves adjusted for policy inflection points including India's PLI scheme acceleration and Japan's METI mandate enforcement. Forecast inputs incorporate dental group consolidation velocity, cloud data center localization progress, and mobile penetration rates among independent practitioners.
Decision-makers should treat outputs as directional under assumptions of sustained PLI scheme funding, stable METI interoperability timelines, and continued cloud infrastructure investment by hyperscalers; material deviation in policy continuity or certification backlogs would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare IT
Healthcare IT Services Market
Healthcare IT
Pharmaceutical Quality Management Systems Market
Healthcare IT
Post-Acute Transition Care Coordination Platform Market
Healthcare IT
E-Prescribing Market
Healthcare IT
Europe Hospital Capacity Management Solutions Market
Healthcare IT
Global Accountable Care Solutions Market
Healthcare IT
North America Long-Term Care Software Market
Healthcare IT
Digital Mhealth Solution Market
Healthcare IT
Americas Healthcare Human Resources (HR) Software Market
Healthcare IT
Hospital Capacity Management Solutions Market
Healthcare IT
Healthcare Credentialing Software Market
Healthcare IT
Global Pharmacy Management System Market
Healthcare IT
Medical Specimen Tracking System Market
Healthcare IT
Global Orthopedic Software Market
Healthcare IT
ECG Management Systems Market
Healthcare IT
Healthcare Smart Card Reader Market