
 Global Orthopedic Software Market | 2026-2036
Global Orthopedic Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Orthopedic Software Market Foresight
Cloud-native architecture is tilting orthopedic software away from on-premise installations toward browser-based surgical planning platforms. Stryker leverages its implant portfolio to bundle proprietary planning tools with hardware sales. Materialise anchors its position through deep specialization in 3D-printed surgical guides and patient-specific implant design software. Brainlab competes by controlling the intraoperative navigation interface, extending its influence from preoperative planning into the operating room itself.
Orthopedic software encompasses digital platforms that process patient imaging data, generate three-dimensional anatomical reconstructions, and simulate surgical interventions prior to incision, with typical systems handling DICOM files at sub-millimeter resolution for preoperative planning. Preoperative Planning Software leads current revenue contribution as joint replacement workflows demand precise templating, while Artificial Intelligence segments show fastest expansion as machine learning models automate fracture classification and implant sizing recommendations. Cloud Computing deployment models are maturing rapidly among rehabilitation centers seeking remote patient monitoring capabilities without capital infrastructure investment.
FDA 510(k) premarket notification requirements govern software-as-medical-device classifications in the United States, while EU MDR and CE marking obligations enforce clinical evidence standards for algorithm-driven diagnostic outputs across European markets. Japan's PMDA imposes stringent quality management system audits on foreign orthopedic software vendors seeking market access. Stakeholders must monitor evolving FDA guidance on machine learning-enabled devices and determine whether adaptive algorithm architectures require new submission pathways or fall under existing predicate frameworks.
Market Dynamics
Cloud-native surgical planning platforms are compressing deployment cycles from months to days, forcing orthopedic software vendors to abandon perpetual licensing for subscription revenue models tied to procedure volume.
Growth Catalysts
- EU MDR software classification rules:Clearer pathways for algorithm-driven diagnostic tools are accelerating CE marking submissions across European markets.
- Ambulatory surgical centers:These facilities are expanding digital planning tool procurement as outpatient joint replacement volumes rise.
- Machine learning models:Automated fracture classification and implant sizing recommendations are reducing preoperative planning time.
Market Restraints
- Input cost volatility:Specialized graphics processing hardware for real-time 3D rendering faces supply concentration in Taiwan and South Korea.
- Technical limitation:Sub-millimeter DICOM reconstruction accuracy requires proprietary calibration protocols that lock customers into single-vendor ecosystems.
- Regulatory friction:FDA 510(k) predicate device requirements create bottlenecks for adaptive algorithm architectures that evolve post-clearance.
Strategic Opportunities
- Underpenetrated geography:Brazil's ANVISA digital health framework is opening pathways for orthopedic software vendors in Latin America's largest hospital market.
- Technology convergence:Integration of augmented reality visualization with haptic feedback systems is creating new intraoperative guidance categories.
- Distribution innovation:Direct-to-surgeon mobile applications are bypassing traditional hospital IT procurement committees.
Industry Challenges
- Skill gap in computational anatomy:Orthopedic surgeons require training in 3D modeling interfaces that most residency programs omit.
- Certification timeline compression:ISO 13485 quality management system audits for software-as-medical-device products demand 12-18 month preparation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Orthopedic Software Market |
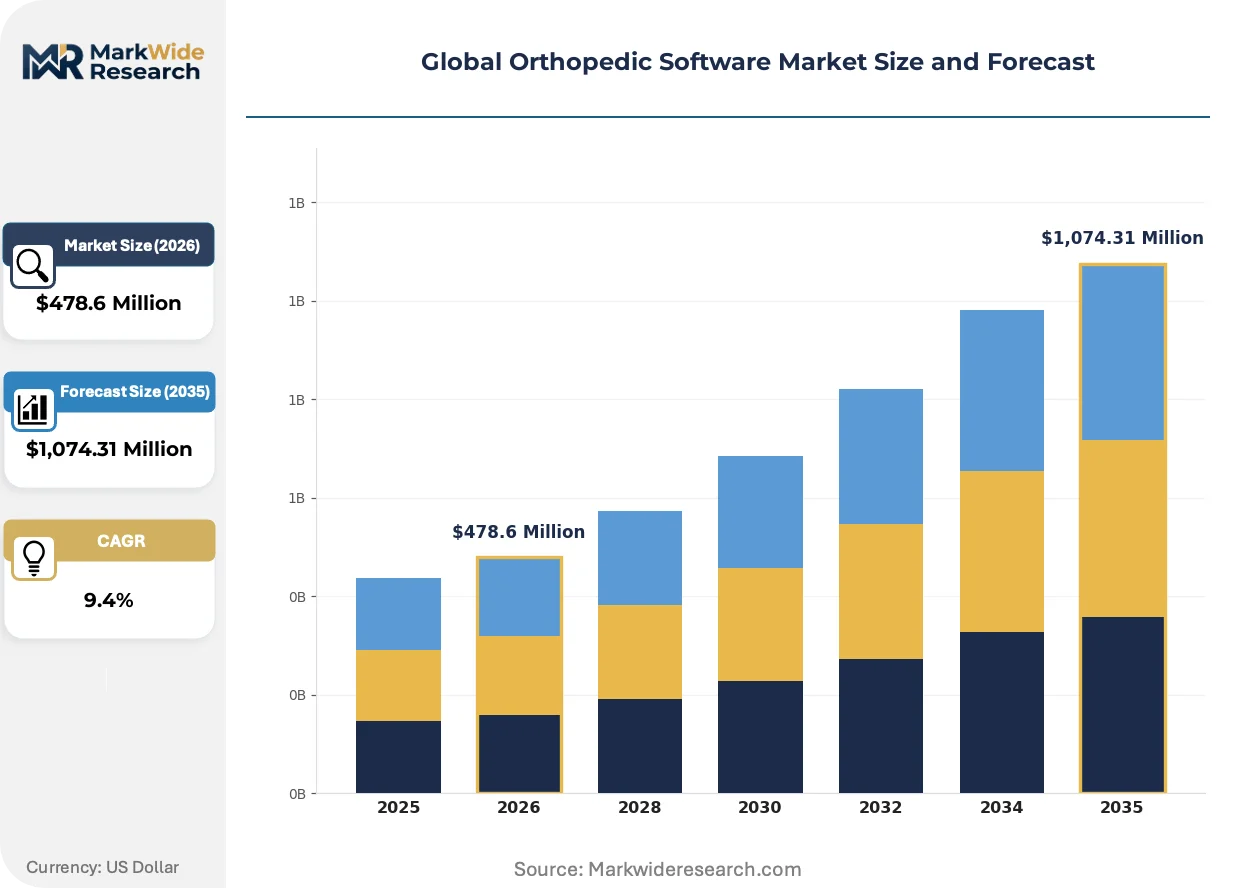
| Market Size in 2026 | $478.6 Million |
| Market Size in 2035 | $1,074.31 Million |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Preoperative Planning Software, Postoperative Management Software, Bone Density Analysis Tools, Rehabilitation Software, Implant Simulation Programs Technology: Artificial Intelligence, Machine Learning, 3D Imaging, Cloud Computing, Augmented Reality Application: Fracture Assessment, Joint Replacement, Spinal Correction, Sports Injury Management, Osteoporosis Monitoring End User: Orthopedic Surgeons, Physical Therapists, Rehabilitation Centers, Diagnostic Laboratories, Research Institutions |
| Companies Covered | Brainlab, Medstrat, Stryker, Zimmer Biomet, Materialise, IBM, CureMD Healthcare, GreenWay Health, NextGen Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Orthopedic Software Market Shifts & Advancements
Artificial intelligence is penetrating every layer of orthopedic workflow from image acquisition through postoperative monitoring, compressing decision timelines and elevating precision thresholds.
Generative adversarial networks are synthesizing high-resolution anatomical models from incomplete imaging data. Academic medical centers in Germany and Japan are deploying these tools for complex revision arthroplasty cases. This capability is digitizing preoperative planning for patients with metal artifact interference from prior implants.
FDA draft guidance on predetermined change control plans is reshaping how machine learning-enabled devices enter commerce. Manufacturers must lock algorithm modification protocols prior to clearance rather than seeking iterative approvals. Orthopedic software developers with locked architectures are accelerating submissions while adaptive systems face extended review timelines.
Hospital procurement committees are unbundling surgical planning software from implant contracts. Independent software vendors in the United States are winning standalone evaluations based on interoperability certifications. This pattern is most visible in integrated delivery networks seeking to standardize planning tools across multiple implant supplier relationships.
Global Orthopedic Software Market Segmentation
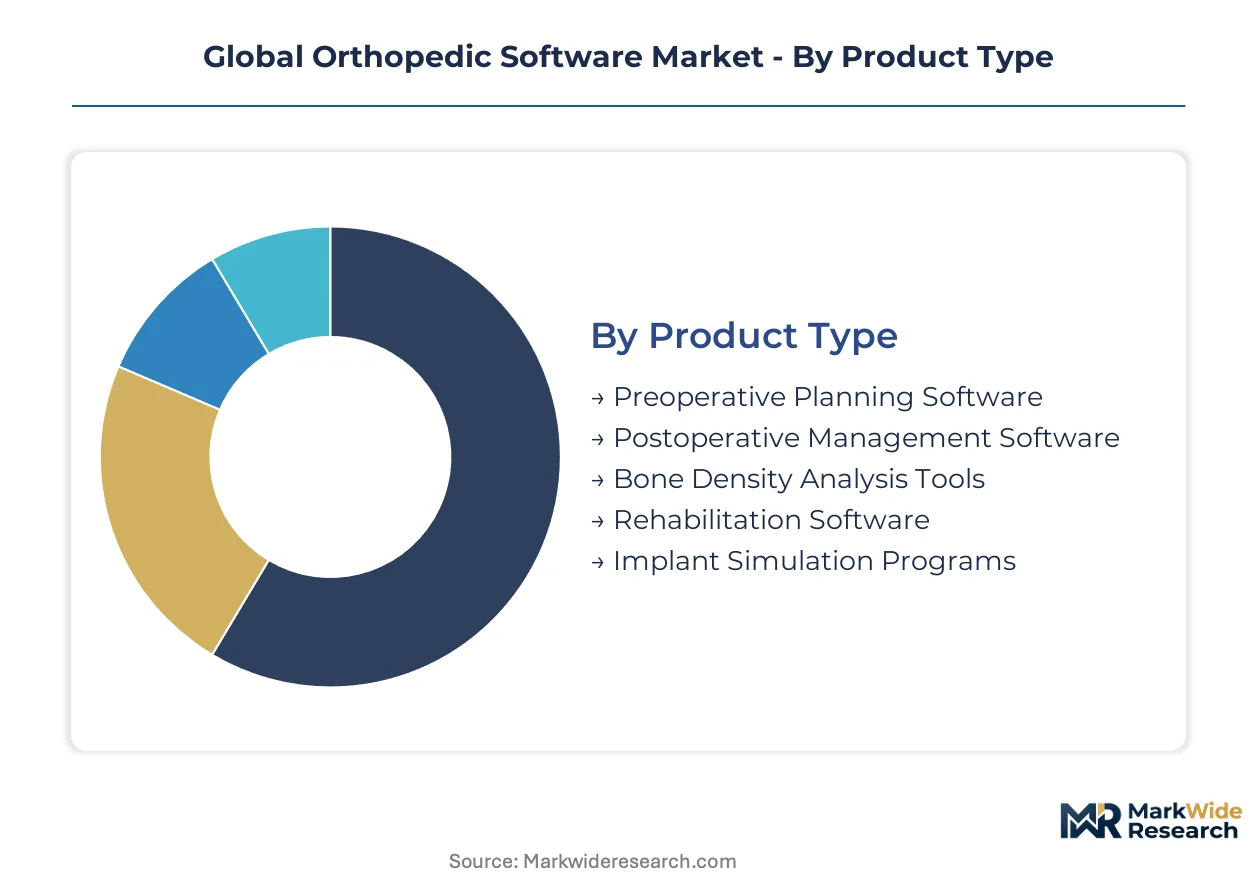
Orthopedic software segmentation reveals how clinical workflows, computational capabilities, and user expertise intersect to create distinct value pools. Vendors must align product architecture with the specific decision points each segment addresses.
Product Type:
Use-case spectrum spans surgical intervention planning through longitudinal patient monitoring, with software complexity escalating from templating tools to biomechanical simulation engines.
- Preoperative Planning Software:Digital templating platforms process DICOM imaging data to simulate implant positioning and bone resection parameters before incision. Demand concentrates among joint replacement surgeons in the United States and Germany where ambulatory surgical centers now mandate digital planning for outpatient arthroplasty procedures.
- Postoperative Management Software:Remote monitoring dashboards track patient-reported outcomes, wound healing metrics, and rehabilitation adherence through integrated mobile interfaces. Adoption accelerates in Japanese rehabilitation networks seeking to reduce readmission penalties under national insurance reimbursement reforms.
- Bone Density Analysis Tools:Quantitative computed tomography software automates trabecular bone scoring for osteoporosis screening protocols.
- Rehabilitation Software:Motion capture analytics and gamified exercise platforms guide physical therapy progression tracking.
- Implant Simulation Programs:Finite element modeling tools predict mechanical stress distribution across prosthetic-bone interfaces.
Established volume favors Preoperative Planning Software; emerging adoption favors Postoperative Management Software.
Technology:
Cost tier stratification separates capital-intensive on-premise deployments from lightweight cloud-native implementations accessible to smaller clinical practices.
- Artificial Intelligence:Deep learning architectures automate fracture classification, implant size prediction, and surgical outcome forecasting from radiological inputs. PMDA in Japan and FDA in the United States are tightening validation requirements for algorithm-driven diagnostic outputs, extending clearance timelines for adaptive model architectures.
- Cloud Computing:Browser-based platforms eliminate local infrastructure requirements while enabling real-time collaboration between surgeons and device manufacturers. Rehabilitation centers in Germany and Brazil's São Paulo hospital clusters are expanding procurement of cloud-native systems to support distributed care networks without dedicated IT departments.
- Machine Learning:Statistical pattern recognition tools refine implant selection algorithms through historical outcome database mining.
- 3D Imaging:Volumetric reconstruction engines generate patient-specific anatomical models from CT and MRI source data.
- Augmented Reality:Intraoperative visualization overlays project surgical plans onto live anatomy through head-mounted displays.
Capital intensity concentrates in 3D Imaging; accessibility gains favor Cloud Computing.
Application:
Customer type differentiation separates high-acuity surgical planning from screening and monitoring workflows with distinct reimbursement profiles.
- Joint Replacement:Software platforms for hip and knee arthroplasty integrate implant manufacturer catalogs with patient-specific templating algorithms. United States integrated delivery networks are unbundling planning tools from implant contracts, creating procurement openings for independent software vendors with interoperability certifications.
- Fracture Assessment:Automated classification systems reduce interpretation variability in emergency department settings. Demand is climbing fastest in Japanese trauma centers deploying machine learning models to address radiologist staffing constraints in regional hospitals.
- Spinal Correction:Deformity analysis tools measure Cobb angles and simulate pedicle screw trajectories.
- Sports Injury Management:Return-to-play assessment platforms track ligament healing progression through functional testing integration.
- Osteoporosis Monitoring:Longitudinal bone density tracking software manages pharmaceutical intervention timing.
Reimbursement stability favors Joint Replacement; volume expansion favors Fracture Assessment.
End User:
Maturity gradient separates digitally native hospital systems from community practices with uneven technical infrastructure.
- Orthopedic Surgeons:Primary decision-makers for preoperative planning tool selection, with purchasing authority increasingly consolidated in United States hospital value analysis committees. EU MDR software classification clarity is accelerating CE marking submissions for surgeon-facing diagnostic algorithms across German and Swiss hospital procurement frameworks.
- Rehabilitation Centers:Outpatient facilities pursuing remote patient monitoring capabilities without capital infrastructure investment. Cloud deployment models are penetrating fastest in Brazilian and Japanese rehabilitation networks seeking scalable subscription pricing tied to patient volume.
- Physical Therapists:Frontline users of motion analysis and exercise prescription software.
- Diagnostic Laboratories:Centralized imaging interpretation hubs for bone density and fracture screening.
- Research Institutions:Academic medical centers developing proprietary algorithms for complex revision cases.
Purchasing authority concentrates with Orthopedic Surgeons; deployment flexibility favors Rehabilitation Centers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German orthopedic software developers export planning platforms to Japanese hospital networks under METI procurement frameworks. United States integrated delivery networks import cloud-native surgical tools from Israeli digital health ventures. Swiss medical device clusters supply navigation software to German ambulatory surgical centers.
United States
FDA 510(k) premarket notification pathways govern software-as-medical-device classifications for algorithm-driven diagnostic tools. Hospital value analysis committees in integrated delivery networks are unbundling surgical planning software from implant contracts. Greater Boston medical technology corridors host digital health ventures developing machine learning-enabled fracture classification systems.
Germany
EU MDR software classification rules are accelerating CE marking submissions for algorithm-driven diagnostic outputs across Baden-Württemberg hospital procurement frameworks. The country's national pharmaceutical regulator enforces clinical evidence standards for adaptive algorithm architectures. Munich medical technology clusters concentrate development of patient-specific implant design software for revision arthroplasty cases.
Japan
PMDA quality management system audits impose stringent validation requirements on foreign orthopedic software vendors seeking market access. National insurance reimbursement reforms are driving rehabilitation center procurement of remote patient monitoring platforms. Tokyo metropolitan hospital networks deploy machine learning models to address radiologist staffing constraints in regional trauma centers.
Brazil
ANVISA digital health framework is opening regulatory pathways for orthopedic software vendors in Latin America's largest hospital market. São Paulo hospital clusters are expanding procurement of cloud-native systems to support distributed care networks without dedicated IT departments. Rehabilitation networks in the city pursue scalable subscription pricing tied to patient volume.
Switzerland
Swissmedic enforces medical device regulations for software products entering European commerce through Swiss distribution channels. Basel pharmaceutical-technology corridors host ventures developing intraoperative navigation interfaces. Zurich medical centers serve as reference sites for augmented reality visualization systems integrated with haptic feedback platforms.
Global Orthopedic Software Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered market positions. Implant manufacturers bundle proprietary planning tools with hardware sales, while independent software vendors win standalone evaluations based on interoperability certifications. Three archetypes dominate: hardware-integrated platform owners, pure-play surgical planning specialists, and cloud-native workflow disruptors. M&A activity concentrates on navigation interface acquisitions, while strategic partnerships link imaging software developers with rehabilitation platform operators.
Among implant-integrated platform owners, Stryker and Zimmer Biomet exemplify hardware-bundled software strategies. Materialise occupies a position within the patient-specific design specialist tier, anchoring its market presence through deep specialization in 3D-printed surgical guides. Brainlab sits within the intraoperative navigation category, extending influence from preoperative planning into operating room environments. These three companies represent distinct competitive vectors: hardware lock-in, manufacturing-design integration, and surgical workflow control.
| Leading Market Players |
|---|
| Brainlab |
| Medstrat |
| Stryker |
| Zimmer Biomet |
| Materialise |
| IBM |
| CureMD Healthcare |
| GreenWay Health |
| NextGen Healthcare |
| Others |
Supply & Pricing Matrix
Overcapacity in cloud-native platform development across United States medical technology corridors is compressing deployment timelines and forcing vendors toward subscription models tied to procedure volume rather than perpetual licensing. This utilization dynamic concentrates pricing power with ambulatory surgical centers and integrated delivery networks capable of consolidating procurement across multiple facilities.
Pricing Analysis
Current-generation cloud-native surgical planning platforms command premium positioning against prior-generation on-premise installations and emerging next-generation AI-augmented systems still navigating FDA clearance pathways. Pricing stratifies across enterprise-tier deployments with full interoperability certifications, mid-tier offerings with limited vendor integrations, and entry-level browser-based tools targeting independent orthopedic practices. Cost compression in the mid-tier segment is intensifying because rehabilitation centers in Brazil and Germany demand scalable subscription pricing without capital infrastructure commitment. Ambulatory surgical centers exhibit highest price sensitivity due to thin outpatient procedure margins, while academic medical centers in Japan and Switzerland demonstrate lowest sensitivity when acquiring patient-specific implant design capabilities.
Supply Chain Analysis
Export control restrictions on specialized graphics processing hardware from Taiwan and South Korea are constraining real-time 3D rendering capabilities for intraoperative navigation systems. Software development concentrates in the United States, Germany, and Israel, while specialized GPU manufacturing feeds from Taiwan Semiconductor and Samsung foundry operations. Supply chain risk centers on single-source vulnerability for high-performance computing components essential for sub-millimeter DICOM reconstruction accuracy. Distribution runs through hospital value analysis committees in integrated delivery networks, with direct-to-surgeon mobile applications emerging as an alternative channel bypassing traditional IT procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as hospital procurement committees unbundle surgical planning software from implant contracts, creating niches for independent vendors with interoperability certifications across multiple hardware ecosystems.
For Market Incumbents: Entrench market position by deepening backward integration into patient-specific implant design workflows and securing ISO 13485 quality management certifications ahead of EU MDR software classification enforcement. Threat from cloud-native disruptors with direct-to-surgeon distribution models demands accelerated navigation interface acquisitions to control intraoperative workflow touchpoints. Priority lever rests on locking proprietary calibration protocols that tether customers to single-vendor ecosystems through sub-millimeter reconstruction accuracy requirements. For New Entrants and Emerging Players: Build out presence in Brazil's ANVISA-regulated digital health framework, where São Paulo hospital clusters seek cloud-native systems without dedicated IT infrastructure. Underpenetrated rehabilitation networks in Japanese regional markets offer white-space expansion for remote patient monitoring platforms addressing national insurance reimbursement reforms. Go-to-market angle should emphasize browser-based deployment with subscription pricing tied to patient volume, bypassing capital expenditure approval cycles that delay traditional on-premise installations. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-native software-as-medical-device segments as browser-based platforms eliminate local infrastructure requirements. Long-term viability favors vendors with locked algorithm architectures compliant with FDA predetermined change control plans, as adaptive systems face extended regulatory timelines. Acquisition target archetype includes navigation interface specialists controlling intraoperative workflow integration. Signal to watch is FDA draft guidance finalization on machine learning-enabled device submissions, which will reshape competitive positioning between locked and adaptive algorithm architectures.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Acceleration | EU MDR software classification clarity is compressing submission timelines for algorithm-driven diagnostic tools across German hospital procurement frameworks. |
| Hospital System Partnership | Integrated delivery networks in the United States are unbundling planning tools from implant contracts, creating procurement openings for interoperable vendors. |
| Software Companion Development | FDA 510(k) clearance for mobile applications is enabling direct-to-surgeon distribution bypassing traditional IT procurement committees. |
| Reimbursement Strategy Alignment | Japan's national insurance reforms are driving rehabilitation center procurement of remote patient monitoring platforms with outcome-based pricing. |
| Strategic Partnership | Collaboration between imaging software developers and rehabilitation platform operators is creating integrated preoperative-to-postoperative workflow solutions. |
Research Methodology
Initial hypotheses were tested against primary input from orthopedic surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers and refined through secondary validation against FDA 510(k) filings, EU MDR submission databases, hospital procurement records, and CMS Medicare reimbursement data. Bottom-up modeling of procedure volumes and software penetration rates was triangulated with top-down market sizing derived from vendor revenue disclosures and trade flow analysis.
Demand-supply balance dynamics across the projection horizon were modeled through segmentation across deployment model, organization size, clinical application, integration complexity, and regional regulatory cluster. CAGRs were derived from procedure volume growth trajectories, digitization budget allocations, and software adoption curve analysis. Forecast inputs incorporated PMDA audit timelines, ANVISA digital health framework evolution, and cloud infrastructure capex disclosures from hyperscale providers.
The forecast holds incumbent behavior within observed patterns; aggressive moves by implant manufacturers to re-bundle software with hardware or cloud-native entrants to subsidize platform access would shift outcomes. Material shifts in FDA guidance on adaptive algorithm architectures or EU MDR software classification enforcement timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare IT
Medical IoT Software Market
Healthcare IT
Global Patient Flow Management Solutions Market
Healthcare IT
Global RFID in Healthcare Market
Healthcare IT
Healthcare Ediscovery Market
Healthcare IT
Healthcare Survey Software Market
Healthcare IT
Healthcare Business Collaboration Tools Market
Healthcare IT
Veterinary Practice Management Software Market
Healthcare IT
US Revenue Cycle Management Market
Healthcare IT
Asia-Pacific Dental Practice Management Software Market
Healthcare IT
US Practice Management Systems Market
Healthcare IT
Global Pharmacy Inventory Management Software Solutions and Cabinets Market
Healthcare IT
Epharmacy Market
Healthcare IT
Veterinary Dental Software Market
Healthcare IT
Femtech Market
Healthcare IT
Healthcare IT Consulting Services Market
Healthcare IT
Global Patient Intake Software Market