
 China Automotive Carbon Fiber Composites Market | 2026-2036
China Automotive Carbon Fiber Composites Market Size, Share, and Industry Trends Forecast 2026-2036
China Automotive Carbon Fiber Composites Market Outlook
Tow-grade carbon fiber precursor chemistry is reconfiguring how automotive structural parts achieve strength-to-weight ratios previously reserved for aerospace applications. Sinofibers Technology leverages domestic PAN precursor supply chains to reduce raw material dependence on imports. Weihai Guangwei Composite anchors Shandong province's marine-to-automotive manufacturing corridor with filament winding capabilities. Jiyan High-tech Fibers differentiates through high-modulus fiber grades targeting electric vehicle battery enclosures.
China automotive carbon fiber composites are fiber-reinforced polymer materials comprising polyacrylonitrile-derived carbon fibers embedded in thermoset or thermoplastic resin matrices, typically achieving tensile strengths exceeding 3,500 MPa with densities below 1.6 g/cm³, engineered primarily to reduce vehicle curb weight while maintaining crashworthiness and structural rigidity. Prepreg dominates current volume flows due to established autoclave processing infrastructure at domestic Tier-1 suppliers, while sheet molding compound is gaining fastest adoption as compression molding cycle times align with high-volume OEM throughput requirements. Structural components command the deepest margin pools given certification barriers and performance liability exposure in chassis and body-in-white applications.
MIIT enforces corporate average fuel consumption limits that effectively mandate lightweighting penetration rates across domestic OEM portfolios, while GB standards govern composite material qualification for automotive structural safety. SAMR administers market access certification that constrains which carbon fiber grades qualify for highway-legal vehicle applications. Stakeholders must monitor how NMPA-aligned automotive material testing protocols evolve to accommodate thermoplastic matrix systems that promise recyclability advantages over incumbent epoxy-based prepregs.
Market Dynamics
MIIT fuel-consumption mandates and China's dual carbon goals are forcing passenger vehicle OEMs to absorb carbon fiber structural components into high-volume platforms, compressing the traditional aerospace-to-automotive technology transfer timeline from decades to single-digit years.
Growth Catalysts
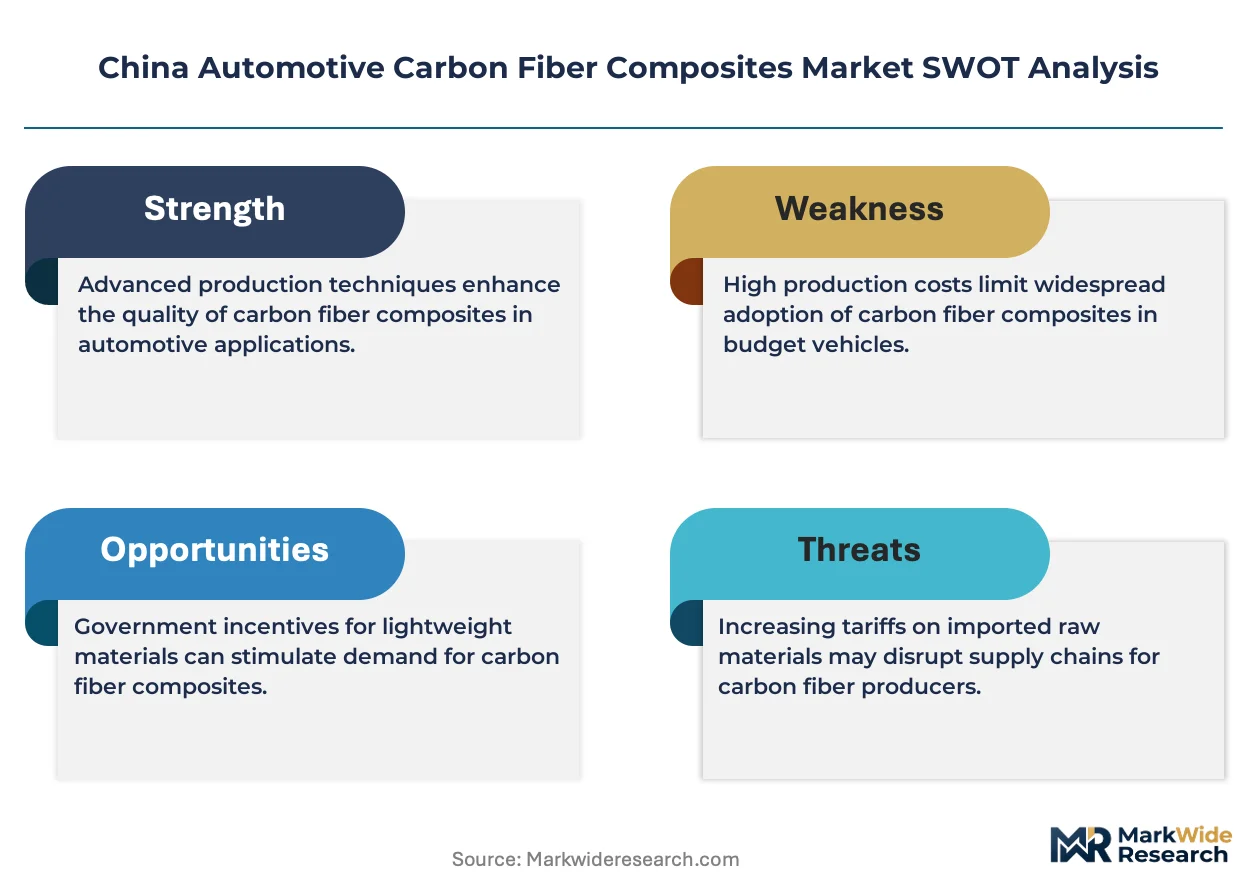
- MIIT Corporate Average Fuel Consumption Limits:Binding fleet-wide efficiency targets mandate lightweighting penetration across domestic OEM portfolios, creating regulatory pull for carbon fiber chassis and body-in-white applications.
- Thermoplastic matrix systems:Recyclable PEEK and PPA resins are displacing thermoset epoxies in battery enclosure designs, aligning with NMPA-aligned automotive material testing protocols and circular economy directives.
- Yangtze River Delta cluster concentration:Shanghai-Jiangsu-Zhejiang automotive corridor hosts integrated precursor-to-composite supply chains, reducing logistics friction for Tier-1 suppliers serving NIO and BYD electric vehicle platforms.
Market Restraints
- Polyacrylonitrile precursor cost volatility:Domestic PAN supply remains concentrated among state-controlled petrochemical complexes, exposing composite manufacturers to feedstock price swings and import dependency for aerospace-grade variants.
- Autoclave processing bottleneck:Established prepreg infrastructure requires 4-8 hour cure cycles incompatible with 60-second OEM assembly line takt times, constraining volume scalability for structural components.
- GB standards certification friction:Composite material qualification for automotive structural safety involves multi-year crashworthiness validation protocols that delay platform integration and tie up R&D capital.
Strategic Opportunities
- Sheet molding compound adoption:Compression molding cycle times under 3 minutes align with high-volume electric vehicle throughput requirements, opening margin pools previously locked by autoclave constraints.
- High-modulus fiber grades for battery enclosures:Thermal runaway protection standards are elevating demand for specialized carbon fiber grades targeting electric vehicle underbody shielding applications.
- Shandong marine-to-automotive corridor:Weihai Guangwei Composite's filament winding capabilities anchor a secondary manufacturing cluster with latent capacity for automotive component diversification.
Industry Challenges
- Composite repair technician scarcity:Automotive service networks lack trained personnel for carbon fiber damage assessment and bonded repair, creating aftermarket liability exposure and insurance underwriting complexity.
- Thermoset-to-thermoplastic requalification timelines:OEMs face 18-24 month material substitution validation cycles when switching from epoxy prepregs to recyclable matrices, compressing platform development windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Automotive Carbon Fiber Composites Market |
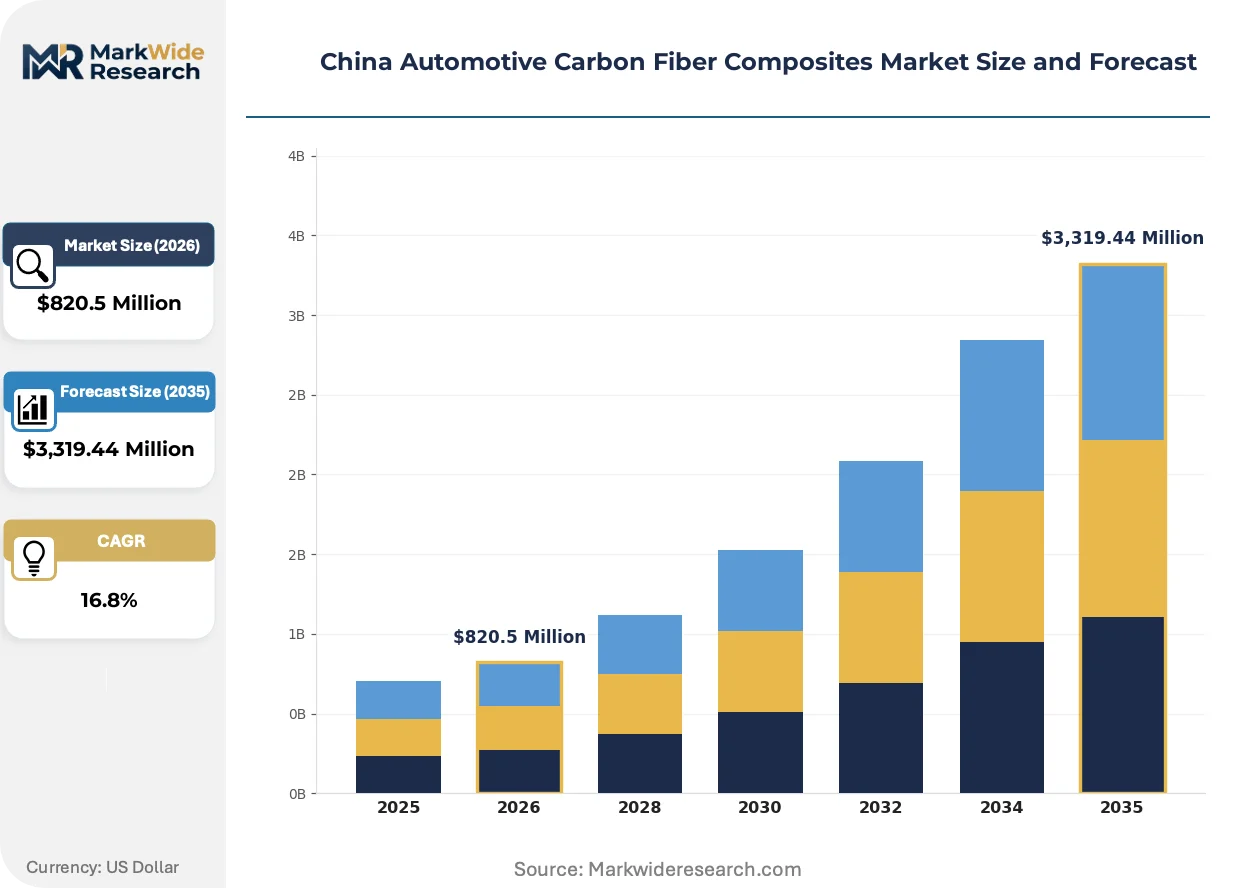
| Market Size in 2026 | $820.5 Million |
| Market Size in 2035 | $3,319.44 Million |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prepreg, Filament Wound, Pultruded, Sheet Molding Compound End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Tier-1 Suppliers Form: Continuous Fiber, Chopped Fiber, Fabric, Foam Application: Structural Components, Interior Parts, Exterior Panels, Crash Management |
| Companies Covered | Sinofibers Technology, Jiyan High-tech Fibers, Weihai Guangwei Composite, Beijing Kangde Xin Composite Material, Jiangsu Kangde Xin Composite Material, Jiangsu Tianniao High Technology, Jiangsu Hangke Composite Materials Technology, Jilin Tangu Carbon, Fangda Carbon New Material, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Automotive Carbon Fiber Composites Market Strategic Shifts
Automotive carbon fiber manufacturing is converging with electric vehicle platform architecture, forcing material suppliers to abandon aerospace-derived batch processes in favor of continuous-flow systems matched to million-unit annual volumes.
Hybrid thermoplastic-thermoset prepregs are hybridizing the performance gap between structural rigidity and recyclability. BYD's Seal platform and NIO's ET7 sedan integrate these intermediate-modulus systems into floor pans and A-pillars. The technology is hybridizing traditional aerospace supply chains with automotive stamping-press economics, collapsing the cost premium from 10x aluminum to 3x.
China's dual carbon goals and GB/T standards revisions are accelerating thermoplastic composite adoption in structural safety applications. MIIT's 2025 corporate average fuel consumption enforcement timeline compresses material qualification windows. Electric vehicle battery enclosure manufacturers face the tightest compliance pressure, driving co-development partnerships between fiber producers and resin compounders.
Long-term supply agreements are displacing spot purchasing for carbon fiber tow as OEMs secure 5-7 year precursor allocations. Tier-1 suppliers serving the Yangtze River Delta cluster now bundle fiber supply with processing equipment leases, transferring capex risk downstream. This contractual shift is most visible among NIO's supplier base, where fixed-price multi-year frameworks dominate procurement negotiations.
China Automotive Carbon Fiber Composites Market Segmentation
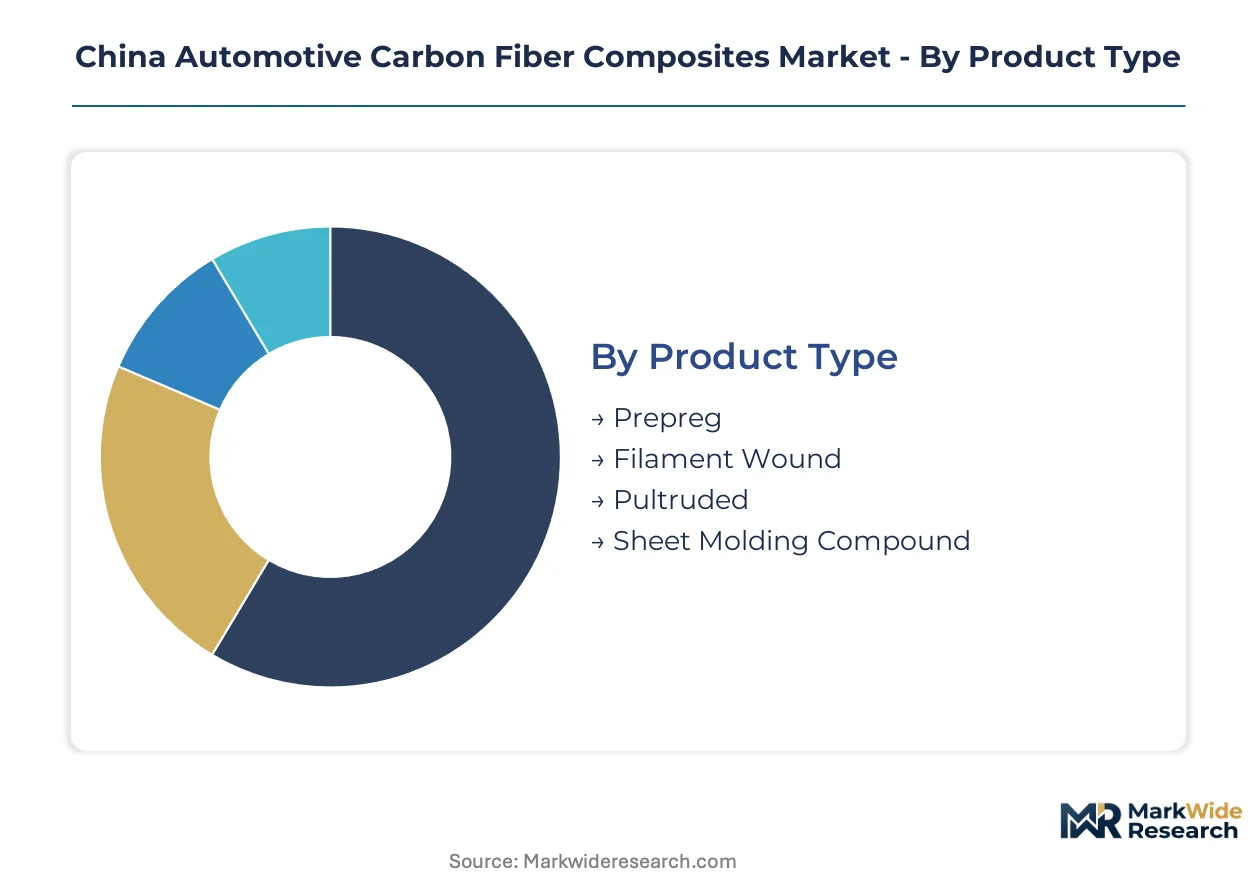
Carbon fiber composite segmentation in China's automotive sector tracks how processing economics and regulatory compliance reshape procurement patterns across electric vehicle platforms. Material form and manufacturing method determine which suppliers capture volume from NIO and BYD versus legacy internal combustion portfolios.
Product Type:
After-sales service intensity varies dramatically across processing methods, with thermoset prepregs demanding specialized repair protocols while thermoplastic alternatives enable conventional body shop workflows.
- Prepreg:Epoxy-impregnated unidirectional tapes and woven fabrics dominate structural safety applications requiring autoclave consolidation. MIIT fuel-consumption mandates pull demand toward Shanghai-Jiangsu-Zhejiang Tier-1 suppliers serving certified chassis programs, though 4-8 hour cure cycles constrain volume scalability.
- Sheet Molding Compound:Chopped fiber-thermoset charge compounds enable compression molding cycles under 3 minutes, aligning with BYD's million-unit annual throughput requirements. Yangtze River Delta electric vehicle platforms are displacing prepreg in non-structural body panels where crash certification thresholds are lower.
- Filament Wound:Continuous fiber wet winding produces hollow tubular sections for drive shafts and suspension links.
- Pultruded:Constant-profile linear sections serve bumper beams and door intrusion bars with minimal scrap rates.
By volume, prepreg leads. By growth pace, sheet molding compound is expanding most quickly.
End User:
Procurement authority concentrates differently across the value chain, with OEMs controlling strategic material qualifications while Tier-1 suppliers manage operational inventory risk.
- OEMs:BYD and NIO maintain direct carbon fiber tow purchasing agreements to secure 5-7 year precursor allocations, bypassing spot market volatility. Dual carbon goals force original equipment manufacturers to internalize lightweighting compliance liability rather than delegate to suppliers.
- Tier-1 Suppliers:Huayu Automotive Systems and Yanfeng Automotive Interiors bundle fiber supply with processing equipment leases, transferring capex exposure downstream while locking in multi-year platform contracts.
- Vehicle Assemblers:Joint venture partners execute MIIT-mandated fuel consumption calculations across imported and domestic brand portfolios.
- Aftermarket Providers:Composite repair technician scarcity limits addressable market for collision replacement panels.
Revenue margin pools favor OEM direct procurement. Contract velocity peaks among Tier-1 suppliers.
Form:
Material geometry dictates processing equipment compatibility and scrap economics across automotive stamping-press retrofits versus greenfield composite lines.
- Continuous Fiber:Unidirectional tow and woven fabrics deliver maximum specific strength for chassis and body-in-white applications, commanding premium qualification overhead.
- Chopped Fiber:25-50mm length discontinuous reinforcement enables injection and compression molding of complex geometries.
- Fabric:2D woven and multiaxial non-crimp fabrics balance drapeability with structural performance.
- Foam:Core materials for sandwich panel construction reduce weight in hood and decklid assemblies.
Continuous fiber commands highest unit value. Chopped fiber is gaining share fastest in battery enclosure applications.
Application:
Crashworthiness certification tiers separate structural from cosmetic applications, with GB standards validation timelines creating moats around safety-critical segments.
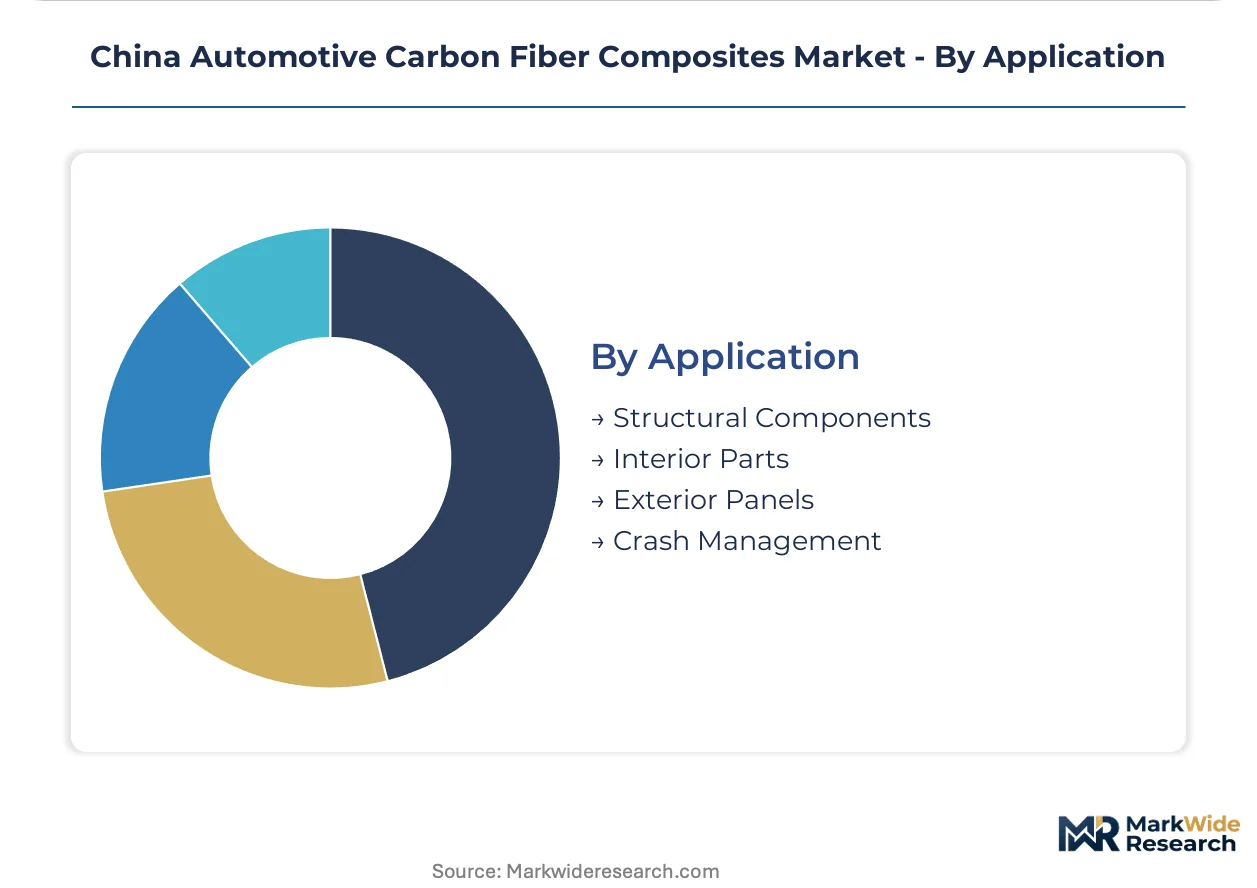
- Structural Components:Floor pans, A-pillars, and subframes require multi-year crashworthiness validation under GB/T protocols, tying up R&D capital but generating multi-platform annuity revenue.
- Crash Management:Front and rear crush structures absorb impact energy while protecting battery enclosures, with thermal runaway protection standards elevating demand for specialized high-modulus grades.
- Exterior Panels:Hoods, fenders, and roofs pursue Class A surface finish with reduced dent susceptibility versus aluminum.
- Interior Parts:Dashboard carriers and seat frames prioritize acoustic damping and mass reduction over structural load paths.
Structural components dominate margin capture. Crash management applications are climbing the fastest on electric vehicle platform proliferation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement authority concentrates among OEMs in the Yangtze River Delta, Shandong Peninsula, and Jilin industrial corridors, with MIIT fuel-consumption mandates driving lightweighting investments across domestic electric vehicle platforms.
Yangtze River Delta
Shanghai, Jiangsu, and Zhejiang provinces host integrated precursor-to-composite supply chains serving NIO and BYD platforms. MIIT corporate average fuel consumption limits bind OEMs to lightweighting timelines that compress material qualification cycles. Tier-1 suppliers in Suzhou and Ningbo bundle fiber supply with processing equipment leases, transferring capex risk downstream.
Shandong Peninsula
Weihai and Yantai anchor a marine-to-automotive manufacturing corridor with latent filament winding capacity for automotive diversification. GB standards govern composite material qualification for structural safety applications, creating multi-year validation protocols. Local processors are repurposing offshore wind blade manufacturing lines for electric vehicle battery enclosure components.
Jilin Province
Changchun and Jilin City concentrate PAN precursor production among state-controlled petrochemical complexes. Domestic feedstock supply reduces import dependency for standard-modulus grades, though aerospace-grade variants remain exposed to international price volatility. Regional fiber producers face pressure to align tow specifications with automotive stamping-press throughput requirements.
Beijing-Tianjin-Hebei
The capital region hosts SAMR market access certification bodies that constrain which carbon fiber grades qualify for highway-legal applications. NMPA-aligned automotive material testing protocols are evolving to accommodate thermoplastic matrix systems. Composite R&D facilities in Beijing's Zhongguancun corridor co-develop high-modulus grades with electric vehicle battery enclosure manufacturers.
Guangdong Province
Shenzhen and Guangzhou electric vehicle assemblers source carbon fiber structural components through Pearl River Delta logistics networks. Dual carbon goals force original equipment manufacturers to internalize lightweighting compliance liability. Local Tier-1 suppliers are retrofitting compression molding lines to match BYD's million-unit annual throughput requirements.
China Automotive Carbon Fiber Composites Market Competitive Environment
Channel-controlling players compete with product-specialist players across a market structure tiered by precursor integration depth and processing equipment ownership. State-controlled petrochemical complexes dominate upstream PAN supply, while mid-tier fabricators battle for OEM platform contracts through equipment-lease bundling. Two strategic archetypes anchor competitive positioning: vertically integrated fiber-to-composite producers and specialized Tier-1 component suppliers. Dominant competitive moves include multi-year precursor allocation agreements and compression molding capacity expansion for high-volume electric vehicle programs.
Among domestic fiber producers, Sinofibers Technology and Jiyan High-tech Fibers occupy positions within the integrated-manufacturer archetype, leveraging captive PAN supply chains to reduce raw material cost exposure. Weihai Guangwei Composite exemplifies the regional-specialist tier, anchoring Shandong province's secondary manufacturing cluster with filament winding capabilities that service both marine and automotive end-use diversification.
| Leading Market Players |
|---|
| Sinofibers Technology |
| Jiyan High-tech Fibers |
| Weihai Guangwei Composite |
| Beijing Kangde Xin Composite Material |
| Jiangsu Kangde Xin Composite Material |
| Jiangsu Tianniao High Technology |
| Jiangsu Hangke Composite Materials Technology |
| Jilin Tangu Carbon |
| Fangda Carbon New Material |
| Others |
Value Chain & Pricing Dynamics
PAN precursor import dependency for aerospace-grade variants determines both the spread between standard and high-modulus fiber pricing tiers and the geographic clustering of composite manufacturing capacity around state-controlled petrochemical complexes in Jilin Province.
Pricing Analysis
Cost-plus contracts with PAN precursor indexation dominate procurement between fiber producers and Tier-1 suppliers, with pricing stratifying across aerospace-grade, automotive-structural, and industrial-grade tiers based on modulus certification and tow consistency. Price differentiation hinges on GB standards qualification status and volume commitment scale, with unqualified entrants facing cost compression from established prepreg suppliers. BYD and NIO procurement teams exhibit lowest price sensitivity for battery enclosure grades due to thermal runaway compliance liability, while aftermarket panel distributors face acute margin pressure from composite repair technician scarcity.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from state-controlled petrochemical complexes in Jilin anchor upstream liquidity for domestic PAN precursor production, reducing working capital strain for fiber manufacturers. Geographic supply concentration centers on China for standard-modulus precursor, Japan and South Korea for aerospace-grade variants, and Germany for specialized thermoplastic resin compounding. Raw material dependencies span acrylonitrile monomer, dimethyl sulfoxide solvent, and epoxy resin hardeners. Single-source vulnerability for high-modulus fiber grades creates structural risk. Distribution runs through Yangtze River Delta Tier-1 supplier hubs serving NIO and BYD assembly plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where MIIT fuel-consumption mandates create regulatory entrenchment that locks incumbent fiber producers into multi-year platform contracts with switching costs exceeding 18-month requalification timelines.
For Market Incumbents: Pre-empt thermoplastic matrix substitution by securing co-development partnerships with NIO and BYD battery enclosure programs before epoxy prepreg contracts expire. Add compression molding capacity in the Shandong marine-to-automotive corridor to capture sheet molding compound volume from BYD's million-unit throughput requirements. Defensive positioning against emerging filament winding specialists from Weihai Guangwei's supplier base demands backward integration into PAN precursor production. For New Entrants and Emerging Players: Shandong Province's secondary manufacturing cluster offers the most penetrable geographic entry point, with latent filament winding capacity from offshore wind blade producers available for automotive component diversification. Target aftermarket collision repair networks where composite technician scarcity has suppressed incumbent service coverage. A go-to-market angle anchored in mobile repair unit partnerships with insurance underwriters bypasses established OEM-Tier-1 procurement chokepoints. For Investors and Strategic Acquirers: The market sits at a regulatory-enforcement phase that favors vertically integrated fiber-to-composite producers with captive PAN supply and GB standards certification in hand. Long-term viability over a multi-year window hinges on thermoplastic matrix qualification velocity rather than incumbent epoxy prepreg market share. The signal to watch is NMPA-aligned testing protocol evolution for recyclable PEEK and PPA resin systems, which would revalue acquisition targets with thermoplastic R&D pipelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into PAN Precursor | Jilin petrochemical complexes reduce import exposure for standard-modulus fiber grades serving BYD platforms. |
| Thermoplastic Matrix Qualification | PEEK and PPA resin validation under evolving NMPA protocols unlocks recyclable battery enclosure contracts with NIO. |
| Compression Molding Capacity Expansion | Sub-3-minute cycle times align with BYD's high-volume throughput and displace autoclave-constrained prepreg suppliers. |
| GB Standards Certification Investment | Multi-year crashworthiness validation creates moats around structural component revenue pools in chassis applications. |
| Equipment-Lease Bundling Programs | Yangtze River Delta Tier-1 suppliers transfer capex risk downstream while locking multi-year platform contracts. |
Study Parameters
A standing panel of OEM platform engineers, Tier-1 supplier procurement directors, carbon fiber plant managers, and MIIT regulatory affairs specialists provided ongoing calibration across primary interview cycles. Secondary validation drew from MIIT corporate average fuel consumption filings, SAMR market access certification records, GB standards revision drafts, and Yangtze River Delta automotive production databases. Bottom-up fiber demand modeling triangulated against top-down electric vehicle platform lightweighting penetration assumptions.
Scenario-bracketing framed low, base, and high cases across the projection horizon without discrete year anchoring. Segmentation dimensions modeled encompassed processing method, end-user procurement authority, fiber form geometry, and application crashworthiness tier. CAGRs derived from installed electric vehicle platform volume trajectories, content-per-vehicle assumptions for structural and non-structural components, and substitution elasticities between aluminum and carbon fiber. Industry-specific inputs included MIIT enforcement timeline scenarios and thermoplastic matrix adoption curves.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by state-controlled petrochemical complexes or accelerated NMPA protocol revision would shift outcomes beyond modeled ranges. Macroeconomic deviation, regulatory enforcement timing changes, or breakthrough thermoplastic processing cost reductions would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Industrial Gearbox Market
Vehicle Components
Latin America Automotive Connectors Market
Vehicle Components
Piston Market
Vehicle Components
Air Brake Reservoirs Market
Vehicle Components
Fuel Sensor Market
Vehicle Components
Snowplows Market
Vehicle Components
Trailer Landing Gear Market
Vehicle Components
Vehicle Trailer Hitch Market
Vehicle Components
Latin America Two-Wheeler Components Market
Vehicle Components
Vehicle Cargo Box Market
Vehicle Components
Brake Hoses Market
Vehicle Components
Cylindrical Roller Bearings Market
Vehicle Components
Global Automotive Carbon Fiber Composites Market
Vehicle Components
Global Bearings Market
Vehicle Components
Intake-Air Temperature Sensor Market
Vehicle Components
Driveline Systems for Electric Vehicle Market