
 Bicycle Components Aftermarket Market | 2026-2036
Bicycle Components Aftermarket Market Size, Share, and Industry Trends Forecast 2026-2036
Bicycle Components Aftermarket Market Analysis
Professional workshop and fleet-maintenance buyers is collapsing as the dominant revenue archetype, while enthusiast direct-to-consumer channels gain transaction volume. Shimano Inc. leverages its vertically integrated drivetrain ecosystem to lock in replacement-part compatibility across multiple bike generations. SRAM LLC anchors its aftermarket position through proprietary wireless shifting protocols that require brand-specific component swaps. DT Swiss competes on hub-service intervals and spoke-replacement programs that sustain dealer loyalty.
Bicycle components aftermarket encompasses replacement parts, upgrade kits, and wear items—brake pads, cassettes, chains, wheel rims, tires, and suspension seals—fabricated from aluminum alloys, carbon fiber prepregs, hardened steel, and rubber compounds, serving to restore or enhance bicycle performance after original-equipment failure or obsolescence. Drivetrain and brake categories command the largest replacement-frequency volumes, while carbon fiber wheel upgrades capture the highest margin pools among enthusiast purchasers. E-commerce distribution channels are displacing traditional specialty-shop fulfillment for standardized consumables such as tires and chains, though complex fitment categories remain concentrated in physical retail.
REACH in Europe, CPSC guidelines in the United States, and GB standards administered by SAMR in China each impose distinct material-composition and safety-testing requirements on brake systems and tire constructions, fragmenting certification burdens across supplier bases. ISO 4210 frame and component standards further shape product-design baselines that aftermarket manufacturers must match for interoperability. Stakeholders must monitor regulatory divergence on chemical content and e-bike-specific load ratings as these frameworks tighten and expand scope.
Market Dynamics
E-bike motor torque ratings and battery integration standards are forcing wholesale redesigns of drivetrain and braking architectures, compressing component lifecycles and accelerating replacement cadences across urban fleet and enthusiast segments alike.
Growth Catalysts
- REACH chemical restrictions:European regulations on brake pad and tire formulations are compelling manufacturers to reformulate with compliant compounds, creating replacement demand as older inventory phases out.
- Urban bike-share fleet operators:Municipal cycling infrastructure investments across Germany, the Netherlands, and Denmark are expanding commercial-grade component procurement volumes for scheduled maintenance programs.
- Lithium-ion battery thermal management:Higher-capacity e-bike powertrains require upgraded brake systems and reinforced wheel assemblies, pulling premium aftermarket upgrades.
Market Restraints
- Aluminum alloy price volatility:Wheel rim and frame component manufacturers face margin compression from primary metal input cost swings tied to energy-intensive smelting operations.
- Taiwanese hub and bearing supply concentration:Precision bearing assemblies for mid-to-high-end wheel systems source predominantly from Taichung-area suppliers, creating geographic single-point vulnerability.
- Interoperability fragmentation:Proprietary electronic shifting protocols from major drivetrain suppliers lock replacement part sourcing to brand-specific ecosystems, limiting consumer choice.
Strategic Opportunities
- Indian urban mobility expansion:Metro cycling infrastructure projects in Bangalore, Pune, and Delhi present untapped aftermarket service contracts for wear-item distributors.
- Subscription-based component refresh programs:Fleet operators in Copenhagen and Amsterdam are piloting all-inclusive maintenance subscriptions that bundle scheduled brake pad, chain, and tire replacements.
- ISO 4210 and e-bike load rating convergence:Harmonized frame and component testing standards across export markets are reducing certification duplication costs for multi-region suppliers.
Industry Challenges
- Carbon fiber repair technician scarcity:Wheel rim and frame damage assessment requires specialized composite layup skills that outpace vocational training program output.
- Multi-protocol diagnostic equipment capex:Service workshops must invest in proprietary software licenses and hardware interfaces to service wireless electronic shifting systems across competing brands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bicycle Components Aftermarket Market |
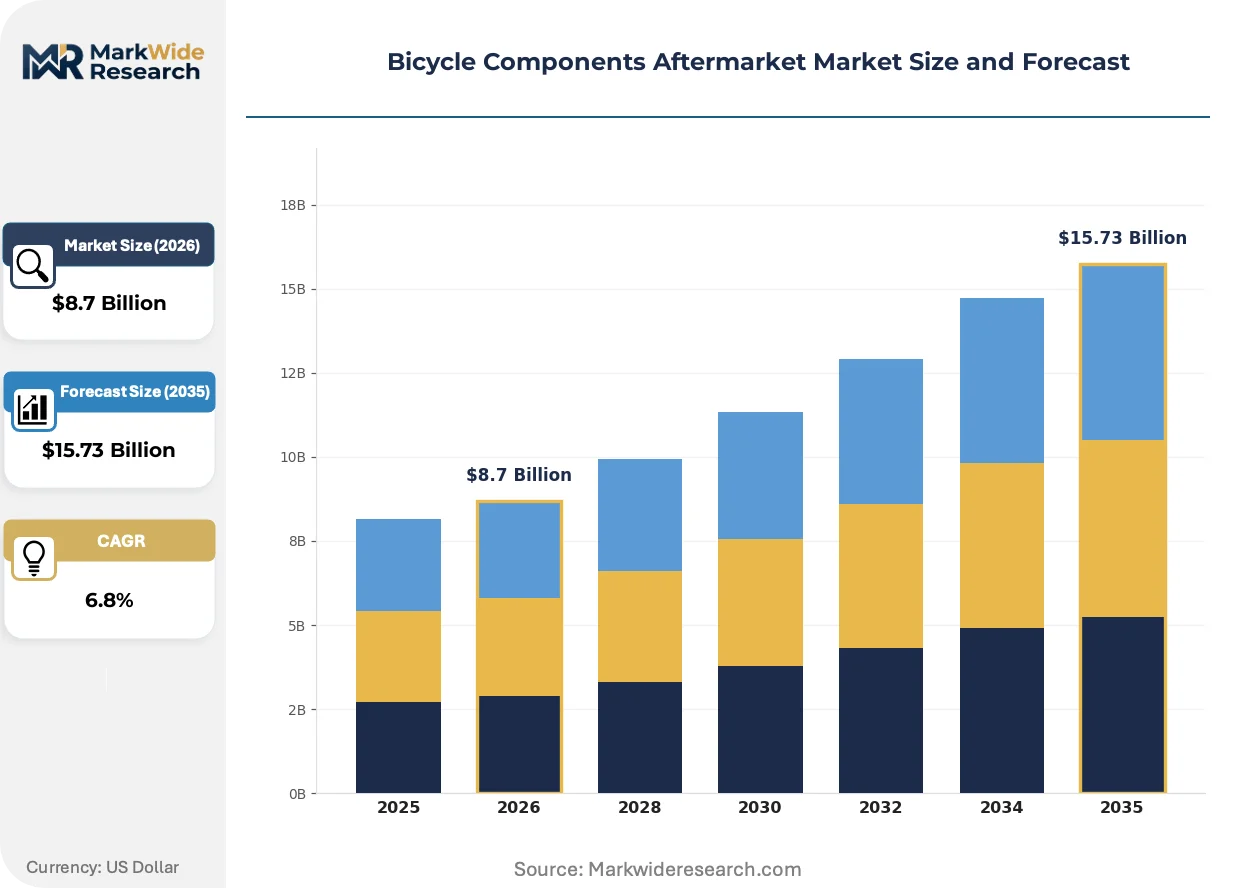
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Brakes, Drivetrains, Wheels, Tires Material: Aluminum, Carbon Fiber, Steel, Rubber End User: Retailers, Online Marketplaces, Aftermarket Providers, Enthusiasts Distribution Channel: Direct Sales, E-Commerce, Distributors, Specialty Shops |
| Companies Covered | Shimano Inc., SRAM LLC, Campagnolo S.r.l., Tektro Technology Corp., DT Swiss, Mavic, Full Speed Ahead, Hope Technology, Magura, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bicycle Components Aftermarket Market Emerging Trajectories
Wireless electronic shifting architectures and predictive maintenance algorithms are redefining component replacement triggers, moving the market from calendar-based to condition-based consumption models.
Integrated power-meter cranksets are miniaturizing strain gauge and accelerometer arrays into spider and spindle assemblies previously reserved for professional racing applications. Amateur endurance cyclists and gran fondo participants are adopting these units at accelerating rates. The technology is miniaturizing price barriers that once segmented power measurement into elite-only categories, expanding addressable market for precision drivetrain components.
REACH authorization requirements for rubber processing aids and vulcanization accelerators are tightening formulation disclosure obligations for tire manufacturers supplying European markets. Industrial consequence includes accelerated R&D spend on bio-based alternatives to traditional petroleum-derived plasticizers. Mountain bike and urban commuter tire categories face the steepest compliance timelines, with suppliers restructuring supply chains to segregate EU-bound from export-only production lines.
Direct-to-consumer wheel builders are capturing enthusiast transaction volume through online fitment configurators that bypass traditional specialty retail channel markup. Complex carbon rim builds and custom spoke tension specifications, once requiring physical consultation, now sell through digital interfaces with remote technical support. Germany and Switzerland demonstrate the most advanced channel migration, where established mail-order specialists have invested in localized spoke cutting and truing facilities to compress delivery windows.
Bicycle Components Aftermarket Market Segmentation
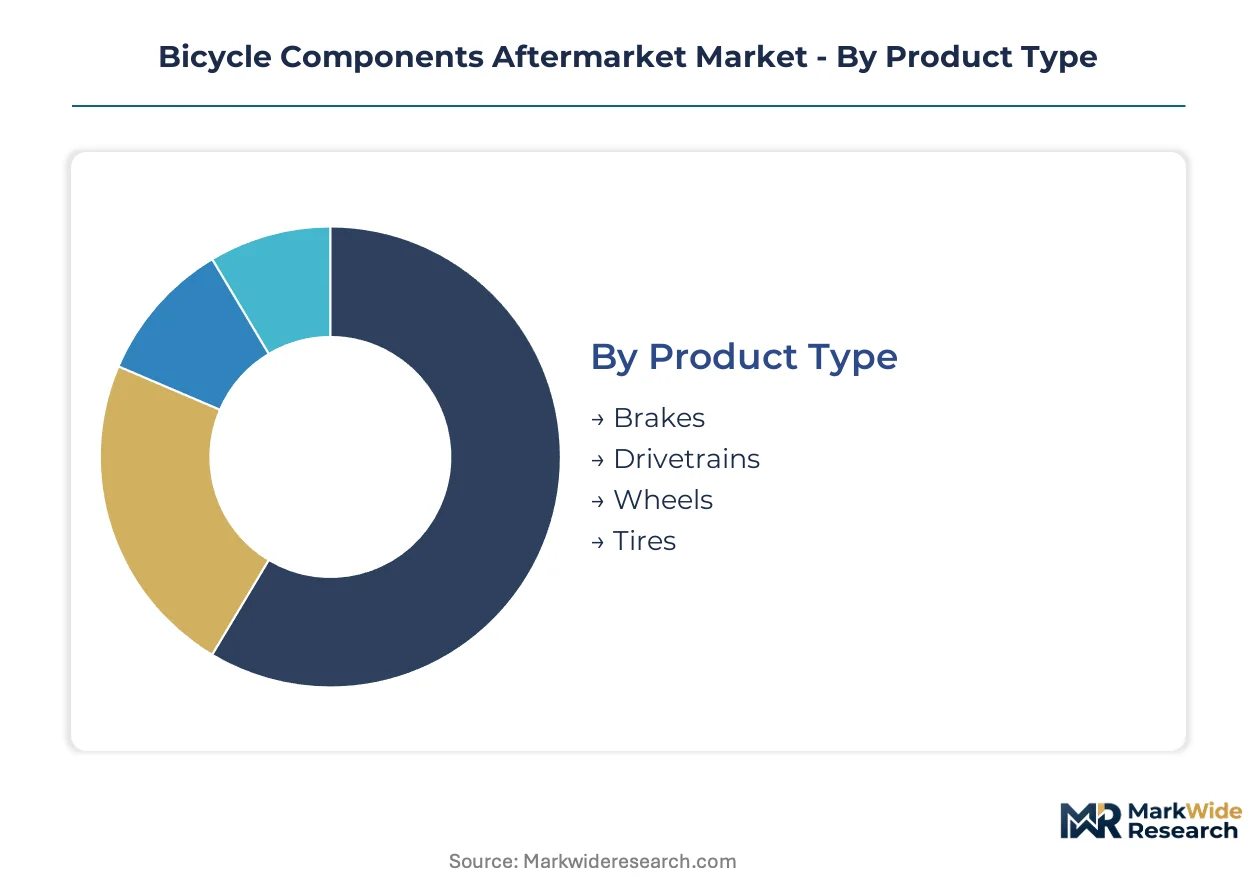
Component replacement cycles and upgrade purchasing patterns diverge sharply across product categories and buyer types in the bicycle components aftermarket. Channel strategy must align with technical complexity, as standardized consumables migrate online while fitment-critical assemblies retain physical retail dependency.
Product Type:
Channel mix varies by replacement frequency and technical complexity, with high-velocity consumables penetrating e-commerce fastest while precision assemblies sustain specialty shop concentration.
- Brakes:Hydraulic disc systems and rim brake calipers incorporate ceramic and metallic pad compounds, with thermal management specifications tightening under European REACH chemical restrictions. Fleet operators in Germany and Denmark are consolidating procurement of compliant brake pad formulations through direct distributor contracts, phasing out legacy inventory ahead of regulatory deadlines. By volume, Brakes leads. By growth pace, Drivetrains is ahead.
- Drivetrains:Cassette, chain, and crankset assemblies fabricated from hardened steel and aluminum alloys interface with proprietary electronic shifting protocols. E-bike motor torque ratings are compressing replacement intervals across urban commuter and cargo bike segments in the Netherlands and Belgium. Wireless electronic shifting compatibility requirements are locking replacement part sourcing to brand-specific ecosystems, limiting cross-shopping.
- Wheels:Rim and hub assemblies span aluminum extrusions to carbon fiber prepregs, with spoke tension specifications varying by rider weight and terrain application.
- Tires:Rubber compounds with varied durometer ratings and tread patterns serve mountain, road, and urban commuting disciplines, with REACH-compliant formulations restructuring European supply chains.
Replacement frequency concentrates in Brakes and Tires for fleet operators, while margin capture concentrates in Wheels and Drivetrains for enthusiast upgrade cycles.
Material:
Cost tier stratification separates premium performance upgrades from baseline replacement economics, with material selection directly determining channel markup and customer acquisition cost.
- Aluminum:Extruded and forged alloys dominate rim, frame, and drivetrain component fabrication, offering strength-to-weight ratios sufficient for mass-market and mid-tier enthusiast applications. Wheel rim manufacturers in Taiwan face margin compression from primary metal input cost volatility tied to energy-intensive smelting operations. By volume, Aluminum leads. By growth pace, Carbon Fiber is climbing fastest.
- Carbon Fiber:Prepreg layups with varying modulus ratings enable rim and component designs that shave rotational mass for competitive and endurance cycling segments. Repair technician scarcity for composite damage assessment is constraining aftermarket service capacity in Germany and Switzerland, where premium wheel adoption concentrates. Specialized layup skills outpace vocational training program output, creating service bottlenecks.
- Steel:Hardened alloys retain dominance in chain, cassette, and bearing race applications where fatigue resistance outweighs weight minimization priorities.
- Rubber:Natural and synthetic elastomer blends with petroleum-derived plasticizers face reformulation pressures under REACH authorization requirements for processing aids and vulcanization accelerators.
Carbon Fiber commands the steepest price premiums and slowest inventory turns, while Aluminum and Rubber drive transaction velocity through standardized consumable replacement.
End User:
Customer type determines technical support requirements and purchasing decision timelines, with commercial buyers prioritizing total cost of ownership and enthusiasts prioritizing performance optimization.
- Retailers:Independent bicycle dealers and multi-brand chains stock fast-moving consumables while outsourcing complex fitment to specialized distributors. German retailers are investing in localized spoke cutting and truing facilities to compress delivery windows for custom wheel builds. By volume, Retailers lead. By growth pace, Online Marketplaces is expanding most quickly.
- Online Marketplaces:Direct-to-consumer platforms capture enthusiast transaction volume through fitment configurators that bypass traditional channel markup. Germany and Switzerland demonstrate the most advanced channel migration, where established mail-order specialists have invested in technical support infrastructure for remote consultation.
- Aftermarket Providers:Fleet maintenance contractors and component refresh subscription services bundle scheduled replacement programs for urban bike-share operators in Copenhagen and Amsterdam.
- Enthusiasts:Amateur endurance cyclists and gran fondo participants are adopting integrated power-meter cranksets and wireless electronic shifting at accelerating rates, expanding addressable market for precision drivetrain components.
Procurement centralization among fleet operators is compressing margin capture for Retailers, while Enthusiast direct purchasing is fragmenting volume across digital channels.
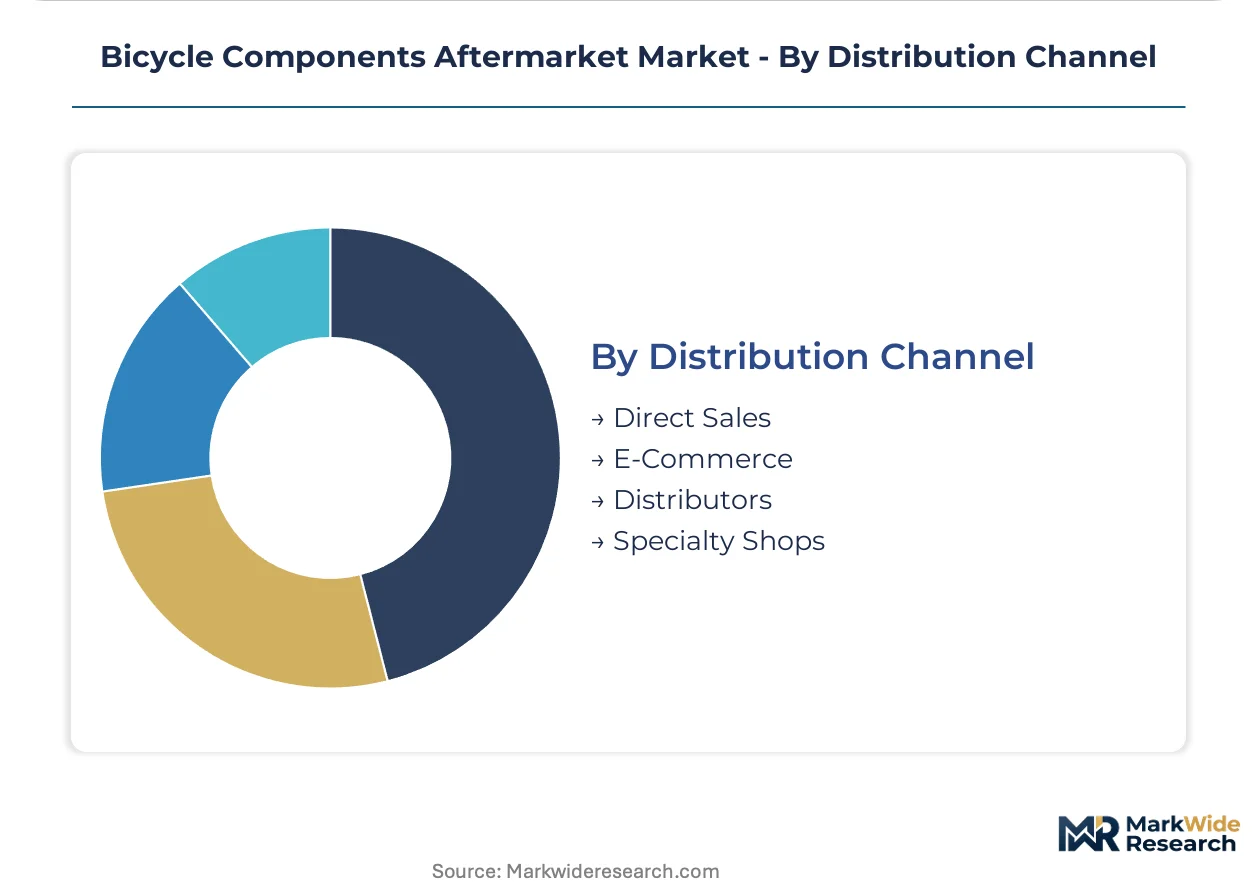
Distribution Channel:
Supply concentration and fulfillment speed requirements are reshaping channel economics, with inventory positioning and technical support capabilities determining competitive viability.
- Direct Sales:Manufacturer-owned channels bypass intermediary markups for proprietary electronic shifting components and brand-specific replacement parts. SRAM and Shimano leverage direct relationships to enforce ecosystem lock-in and capture margin that would otherwise flow to distributors. By volume, Direct Sales trails. By growth pace, E-Commerce is gaining share fastest.
- E-Commerce:Digital platforms displace specialty shop fulfillment for standardized consumables such as tires and chains, with predictive maintenance algorithms enabling condition-based replenishment triggers. Complex fitment categories remain concentrated in physical retail due to diagnostic equipment requirements.
- Distributors:Regional wholesalers aggregate procurement volumes for independent retailers and fleet operators, with inventory positioning determining delivery reliability for time-sensitive maintenance programs.
- Specialty Shops:Physical retailers retain concentration for complex fitment categories requiring proprietary diagnostic equipment and technician certification for wireless electronic shifting service.
E-Commerce penetration is deepest in consumable categories with standardized specifications, while Specialty Shops defend position in assembly and calibration services requiring physical presence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Taiwanese precision bearing and hub manufacturers export predominantly to German and Dutch fleet operators, anchoring a trade corridor that supplies urban bike-share maintenance programs across Northern Europe.
Germany
E-bike penetration rates exceed regional averages, compressing drivetrain and brake replacement cycles across commuter and cargo bike segments. REACH chemical restrictions on brake pad formulations are phasing out legacy inventory through fleet procurement mandates. The Taichung-to-Rotterdam supply corridor terminates in Hamburg and Berlin distribution hubs serving municipal maintenance contracts.
Netherlands
Urban cycling infrastructure density generates the highest per-capita component consumption rates in Europe. ECHA authorization requirements for rubber processing aids are restructuring tire supply chains serving Amsterdam and Rotterdam fleet operators. Subscription-based component refresh programs piloted in Copenhagen extend into Dutch municipal procurement frameworks.
United States
Enthusiast direct-to-consumer channels capture accelerating transaction volume for wheel and drivetrain upgrades. CPSC guidelines on brake system safety testing impose distinct certification burdens separate from European REACH frameworks. Colorado and California clusters concentrate specialty retailers investing in proprietary diagnostic equipment for wireless electronic shifting service.
China
GB standards administered by SAMR govern frame and component testing baselines for domestic production and export qualification. Yangtze River Delta manufacturing clusters supply aluminum rim extrusions and carbon fiber prepregs to Taiwanese hub assemblers. Dual carbon goals are pressuring energy-intensive smelting operations feeding primary metal inputs.
Switzerland
Premium wheel adoption concentrates among amateur endurance cyclists and gran fondo participants, expanding addressable market for integrated power-meter cranksets. Swissmedic-equivalent consumer safety frameworks align with EU REACH disclosure obligations for rubber compound formulations. Zurich and Geneva direct-to-consumer specialists have localized spoke cutting facilities to compress delivery windows.
Bicycle Components Aftermarket Market Vendor Landscape
Listed leaders compete with private specialists across ecosystem lock-in strategies, with public companies leveraging capital market access to fund proprietary protocol development while private fabricators defend niche positions through technical service relationships. The vendor base stratifies into three tiers: vertically integrated drivetrain architects, precision wheel system specialists, and regional brake component fabricators. Competitive moves concentrate on backward integration into carbon fiber prepreg supply and geographic expansion through distributor acquisition in Northern European fleet markets.
Within the drivetrain architect tier, Shimano Inc. and SRAM LLC occupy positions defined by ecosystem control strategies, while DT Swiss exemplifies the precision wheel specialist archetype competing on service interval programming and dealer loyalty mechanisms. Campagnolo S.r.l. represents the heritage European fabricator segment, maintaining positioning through mechanical shifting continuity amid wireless protocol transitions. These three anchors illustrate how competitive differentiation fragments across protocol ownership, service infrastructure, and brand heritage vectors.
| Leading Market Players |
|---|
| Shimano Inc. |
| SRAM LLC |
| Campagnolo S.r.l. |
| Tektro Technology Corp. |
| DT Swiss |
| Mavic |
| Full Speed Ahead |
| Hope Technology |
| Magura |
| Others |
Supply Flow & Price Mechanics
Long-term fleet maintenance contracts lock in both carbon fiber prepreg access and brake pad pricing visibility for German bike-share operators navigating REACH compliance deadlines. These multi-year service agreements tether component costs to raw material indices while guaranteeing supply priority from Taiwanese hub manufacturers.
Pricing Analysis
Current-generation wireless electronic shifting systems command 40-60% premiums over prior-generation mechanical groupsets, while next-generation integrated power-meter cranksets are climbing fastest in enthusiast price tiers. Three-tier pricing structure across premium, standard, and economy levels segments by certification grade and after-sales service bundling. Pricing pressure stems from aluminum alloy input cost volatility tied to energy-intensive smelting operations. Fleet operators exhibit highest price sensitivity due to total cost of ownership procurement mandates, while amateur endurance cyclists demonstrate lowest sensitivity for carbon fiber wheel upgrades.
Supply Chain Analysis
Taichung-area precision bearing manufacturing anchors a geographic chokepoint that constrains mid-to-high-end wheel system output for European and North American markets. Taiwan, China, and Germany concentrate supply for carbon fiber prepregs, aluminum rim extrusions, and drivetrain assembly respectively. Raw material dependencies center on petroleum-derived rubber plasticizers, lithium-ion battery thermal management compounds, and hardened steel alloys. Single-source vulnerability from Taiwanese hub concentration threatens delivery reliability for fleet maintenance programs. Distribution runs through Hamburg and Rotterdam distribution hubs serving municipal procurement frameworks across Northern Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as e-bike penetration accelerates component replacement cadences beyond traditional mechanical bicycle lifecycles. Urban fleet electrification across Northern European municipalities sustains above-average procurement growth.
For Market Incumbents: Fortify ecosystem lock-in through proprietary diagnostic software licensing and certified technician training programs. SRAM and Shimano already enforce wireless protocol compatibility requirements that limit cross-shopping. Carbon fiber repair technician scarcity threatens aftermarket service capacity; incumbents should deepen backward integration into composite layup training academies in Germany and Switzerland. For New Entrants and Emerging Players: Predictive maintenance algorithm deployment represents a service-layer gap where incumbents under-serve fleet operators still running calendar-based replacement schedules. New entrants should target Copenhagen and Amsterdam subscription-based component refresh pilots with IoT-enabled wear-item monitoring. Direct-to-consumer wheel builders have proven online fitment configurators penetrate enthusiast segments fastest. For Investors and Strategic Acquirers: Regional brake component fabricators with REACH-compliant formulation capabilities and established fleet distributor relationships represent the most defensible acquisition target archetype. Long-term viability hinges on regulatory compliance infrastructure rather than pure manufacturing scale. Watch for ECHA authorization timeline acceleration on rubber processing aids as the inflection signal for supply chain restructuring urgency.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Formulation Investment | ECHA authorization requirements on brake pad compounds force R&D spend ahead of legacy inventory phase-out deadlines. |
| Predictive Maintenance Platform Launch | Condition-based replacement triggers displace calendar-based consumption for Copenhagen fleet operators. |
| Carbon Fiber Repair Technician Academy | Specialized composite layup skills outpace vocational training output in Germany and Switzerland. |
| Direct-to-Consumer Wheel Configurator Expansion | Online fitment tools bypass specialty retail markup in markets with established mail-order infrastructure. |
| Subscription-Based Fleet Maintenance Contract | All-inclusive brake pad, chain, and tire replacements bundle procurement for Amsterdam bike-share operators. |
Methodological Framework
Two parallel data streams informed the analysis: primary field engagement with component manufacturers, fleet procurement managers, and independent bicycle dealer owners; and secondary validation through customs trade records, ISO 4210 certification databases, and ECHA authorization filings. Triangulation across bottom-up shipment data and top-down market sizing cross-checked volume estimates. Primary interviews captured replacement cycle compression effects from e-bike motor torque ratings. Secondary sources included SAMR GB standard publications, CPSC brake system safety guidelines, and trade flow data through Hamburg and Rotterdam distribution hubs.
Across the analysis window, forecasts model replacement frequency by component category, material cost tier, end-user procurement centralization, and channel migration velocity. Segmentation dimensions span product type, material composition, buyer archetype, and distribution channel. CAGRs derive from fitted growth curves applied to baseline replacement volumes adjusted for e-bike penetration rates. Industry-specific inputs incorporate REACH compliance phase-out schedules and lithium-ion battery thermal management upgrade pull-through.
Forecasts assume regulatory continuity in ECHA authorization timelines and SAMR GB standard enforcement; material policy shifts on chemical content or e-bike load ratings would require re-modeling. Practitioners should keep alternative scenarios live as Taiwan supply concentration and aluminum smelting energy costs evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Tailgate Chip Spreader Market
Vehicle Components
Car Sunshade Market
Vehicle Components
Towing Equipment Market
Vehicle Components
Automotive Battery Terminals Market
Vehicle Components
Tricycle Vending Cart Market
Vehicle Components
Automotive Displacement Sensor Market
Vehicle Components
Bus and Coach Suspension Bearing Components Market
Vehicle Components
Mechanical Control Cables Market
Vehicle Components
North America Forklift Rental Market
Vehicle Components
Bicycle Lights Market
Vehicle Components
Air Suspension Market
Vehicle Components
Refrigerated Trailer Hinges Market
Vehicle Components
Electric Brake Actuator Systems for Passenger Vehicles Market
Vehicle Components
Tipper Body Equipment Market
Vehicle Components
Car Diffuser Market
Vehicle Components
Hooklift Trailer Market