
 Portable Metal Detectors Market | 2026-2036
Portable Metal Detectors Market Size, Share, and Industry Trends Forecast 2026-2036
Portable Metal Detectors Market Outlook
Qualified electromagnetic sensor engineering talent is collapsing across North American and European manufacturing bases, constraining R&D throughput for next-generation discrimination algorithms. Garrett Metal Detectors sustains its foundry relationships and in-house coil winding capabilities in Texas, insulating it from component bottlenecks. Minelab leverages its Australian goldfield heritage to dominate ground-search sensitivity benchmarks, while C.E.I.A. S.p.A. anchors European airport security tenders through its Milan-area production campus and direct government contracting channels.
Portable metal detectors are electromagnetic induction instruments that transmit pulsed or continuous-wave signals through search coils and analyze eddy-current distortions to identify ferrous and non-ferrous metallic objects; operating frequencies typically range from 3 kHz to 100 kHz depending on target conductivity and soil mineralization requirements. These devices serve security screening, subsurface utility mapping, mineral prospecting, and archaeological survey applications where non-invasive metallic object location is essential. Walk-through installations command the largest revenue pool among product types due to institutional procurement scale and integration with access control infrastructure, while handheld units represent the fastest-growing segment driven by law enforcement patrol budgets and event-security mandates. Industrial applications attract expanding interest as food processors and textile manufacturers deploy utility-grade detectors for contaminant control, though mining and archaeology sustain steadier replacement cycles.
FAA directives on passenger checkpoint technology and TSA certification standards govern US market access, while CE marking under the EU Machinery Directive and emerging EU AI Act provisions for automated threat detection reshape European product development roadmaps. ISO 9001 quality frameworks and IEC 62368-1 safety standards provide baseline compliance thresholds for cross-border sales, with national regulators in Saudi Arabia and the UAE adding localized electromagnetic emissions testing. Stakeholders must monitor how AI-enabled threat-classification modules trigger new cybersecurity and algorithmic transparency requirements across jurisdictions.
Market Dynamics
Airport security procurement is intensifying as passenger throughput rebounds and terminal modernization accelerates, while the EU AI Act and CE marking requirements for security screening equipment are reshaping product certification pathways across manufacturing bases.
Growth Catalysts
- TSA Funding Cycles:Critical infrastructure protection mandates in the United States sustain replacement volumes for walk-through and handheld units at federal and municipal levels.
- EU AI Act Provisions:Automated threat detection modules are triggering new certification requirements that favor established electromagnetic sensor engineering capabilities in European tenders.
- Event-Security Mandates:Law enforcement patrol budgets are expanding handheld unit deployments for temporary perimeter screening at sporting venues and public gatherings.
Market Restraints
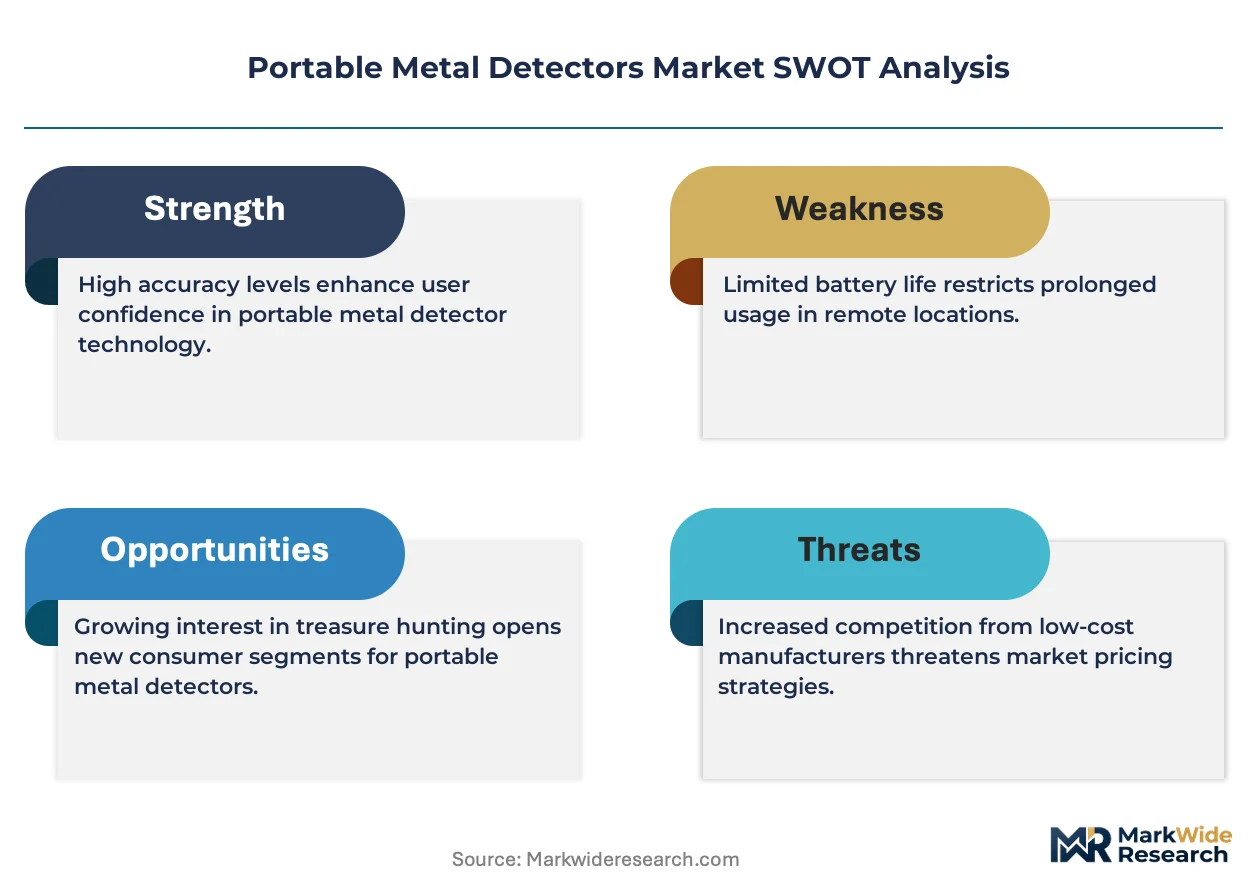
- Electromagnetic Sensor Engineering Talent Collapse:Qualified engineering talent is contracting across North American and European manufacturing bases, constraining R&D throughput for next-generation discrimination algorithms.
- Component Bottleneck Exposure:Manufacturers without captive coil winding capabilities or foundry relationships face supply concentration risk in Texas and Milan-area production clusters.
- ISO 9001 and IEC 62368-1 Compliance Burden:Cross-border sales require baseline quality and safety certifications that extend product development timelines and testing expenditures.
Strategic Opportunities
- Industrial Contaminant Control:Food processors and textile manufacturers are deploying utility-grade detectors for metallic contaminant detection, opening non-security revenue streams.
- Saudi Arabia and UAE Localized Testing:National regulators in these markets are adding electromagnetic emissions testing requirements that create first-mover advantages for compliant suppliers.
- AI-Enabled Threat Classification:Algorithmic transparency and cybersecurity requirements under emerging frameworks are creating differentiation opportunities for vendors with in-house software development.
Industry Challenges
- Algorithmic Certification Timelines:AI-enabled discrimination modules face extended validation periods under FAA directives and TSA certification standards, compressing product launch windows.
- Legacy System Integration Complexity:New handheld and walk-through units must interface with existing access control infrastructure at airports and critical facilities, requiring custom protocol adaptation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Portable Metal Detectors Market |
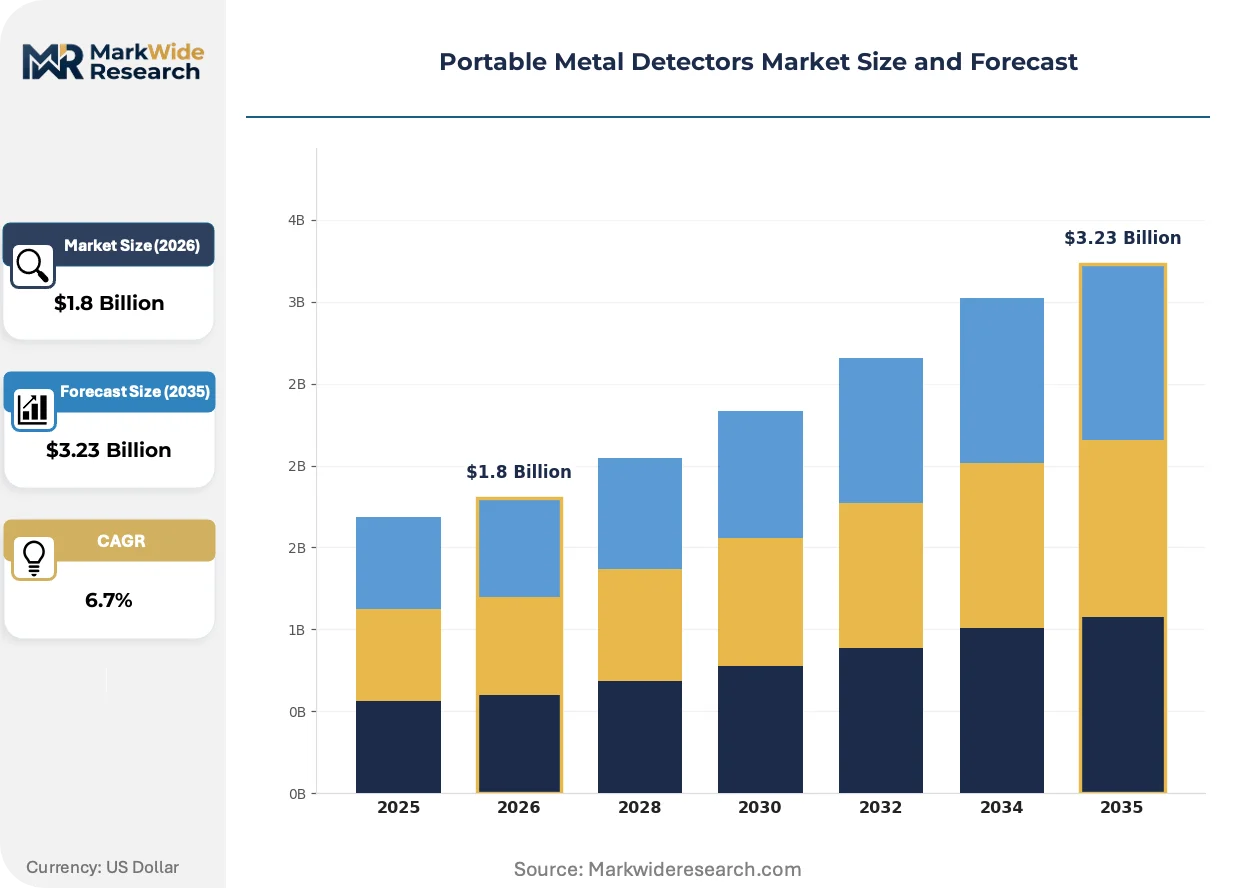
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld, Walk-through, Ground Search, Utility Application: Security, Mining, Archaeology, Industrial End User: Law Enforcement, Mining Companies, Museums, Airports Distribution Channel: Online Retail, Distributors, Direct Sales, Others |
| Companies Covered | Garrett Metal Detectors, C.E.I.A. S.p.A., Fisher Research Laboratory, Nokta Metal Detectors, Minelab, Range Security Detectors, Inc., White’s Electronics, SUNS International, LLC, OSI Systems, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Portable Metal Detectors Market Strategic Shifts
Pulsed induction architectures and multi-frequency discrimination algorithms are displacing single-frequency analog designs across professional-grade equipment, while regulatory frameworks governing automated threat detection are tightening certification requirements.
Multi-frequency electromagnetic induction systems are displacing legacy single-frequency detectors in professional security and prospecting applications. These architectures transmit simultaneous pulse trains across 3 kHz to 100 kHz bands, enabling real-time conductivity profiling that distinguishes ferrous debris from high-value non-ferrous targets. Mining operators and airport security directors are adopting these platforms to reduce false-positive rates and minimize manual secondary screening. The technology is displacing mid-tier analog competitors that lack firmware-upgradable discrimination libraries.
The EU AI Act's risk-classification framework for biometric and automated threat-detection systems is reshaping European product development roadmaps. Manufacturers must now document algorithmic decision pathways and maintain audit trails for threat-classification outputs, adding software engineering overhead to traditionally hardware-centric product lines. CE marking under the EU Machinery Directive now intersects with AI-specific conformity assessments, compressing timelines for vendors targeting German and French airport tenders.
Outcome-based service contracting is replacing transactional equipment sales in institutional security procurement. Municipal police departments and event-management firms are bundling detector maintenance, calibration, and operator training into multi-year agreements rather than capitalizing standalone hardware purchases. This shift is most visible in United States federal contracting channels, where TSA cooperative purchasing agreements now emphasize total cost of ownership over unit acquisition price.
Portable Metal Detectors Market Segmentation
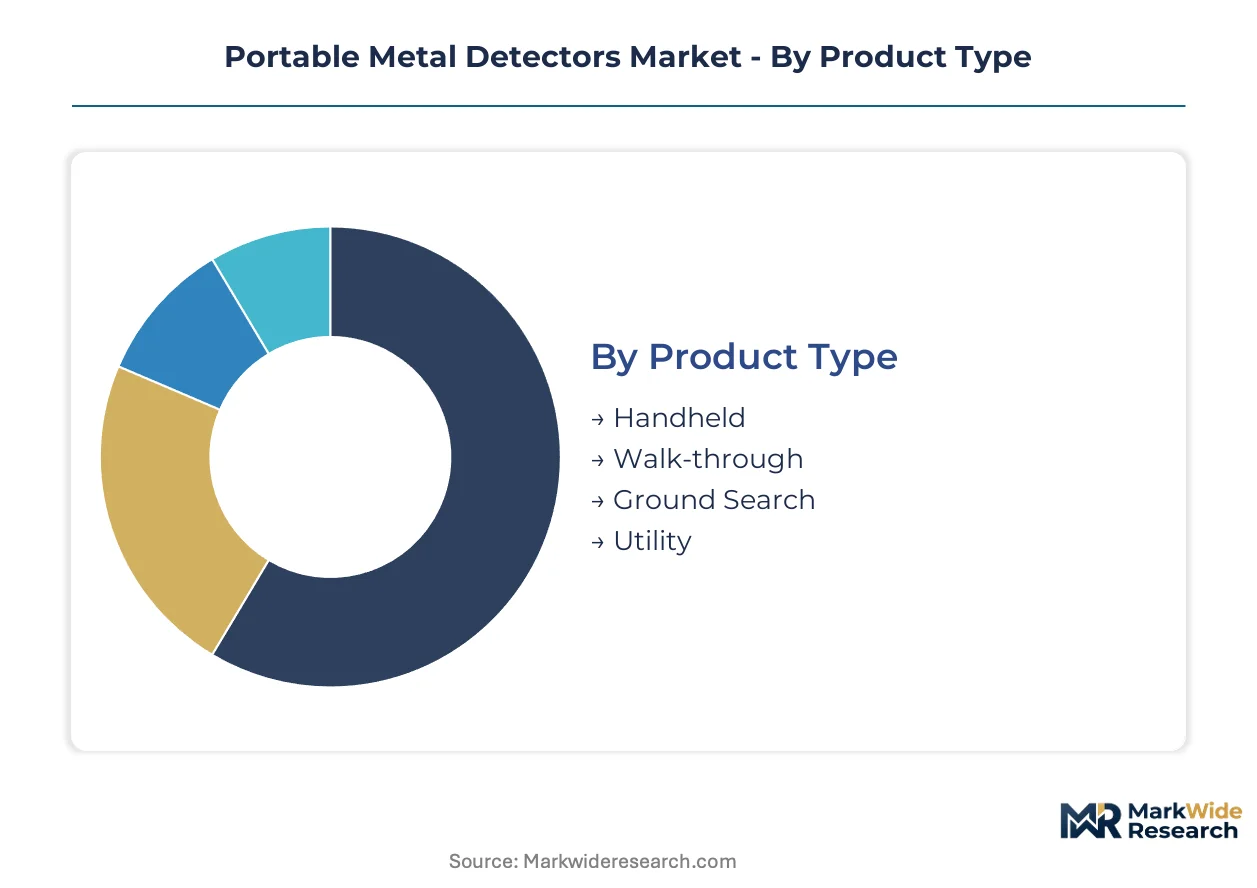
Portable metal detector procurement patterns diverge sharply across institutional, commercial, and consumer channels. Segment-level strategy requires matching electromagnetic performance specifications to end-use duty cycles and regulatory certification requirements.
Product Type:
Walk-through systems anchor domestic procurement in the United States and European Union member states, while handheld and ground-search units drive export volumes to resource economies and emerging security markets.
- Handheld:Battery-powered units operating at 3-100 kHz with adjustable discrimination thresholds. Law enforcement patrol budgets in the United States and event-security mandates across Germany and France are accelerating replacement cycles for firmware-upgradable models.
- Walk-through:Multi-coil portal architectures integrating with access control infrastructure. Airport terminal modernization in the United States, Italy, and the United Kingdom sustains institutional procurement at federal and municipal levels.
- Ground Search:Pulsed induction systems optimized for mineralized soil conditions. Australian mining operations and Saudi exploration concessions drive sensitivity benchmarking for deep-target detection.
- Utility:Fixed-installation detectors for food processing and textile manufacturing lines. Industrial contaminant control requirements in Japan and South Korea are opening non-security revenue channels.
Walk-through installations command the established base. The steepest expansion runs through handheld units.
Application:
Security applications concentrate manufacturing margins in certified equipment tiers, while mining and industrial segments reward sensitivity performance over compliance overhead.
- Security:Threat detection protocols requiring TSA certification or CE marking under EU Machinery Directive. Passenger checkpoint modernization at airports in the United States, France, and the United Arab Emirates is intensifying procurement.
- Mining:Mineral prospecting and subsurface utility mapping in geologically complex terrain. Australian goldfield operations and South African platinum belt surveys sustain replacement demand for ground-search platforms.
- Archaeology:Non-invasive metallic object location with minimal site disturbance. Mediterranean survey projects in Italy and Greece maintain steady equipment turnover.
- Industrial:Metallic contaminant detection in food processing and textile manufacturing. Japanese pharmaceutical packaging lines and South Korean electronics fabs are deploying utility-grade systems.
Security applications absorb the largest certification investment. Industrial deployment is climbing the fastest.
End User:
Airport authorities and law enforcement agencies dominate funded procurement cycles, while mining companies and museums operate on capital expenditure timelines sensitive to commodity prices and grant availability.
- Law Enforcement:Municipal police departments and federal agencies requiring patrol-grade handheld units. TSA cooperative purchasing agreements in the United States emphasize total cost of ownership over unit acquisition price.
- Mining Companies:Exploration divisions and contract surveyors operating in Australian, Canadian, and Saudi Arabian concessions. Sensitivity specifications for deep-target detection drive platform selection.
- Museums:Archaeological departments and cultural heritage agencies with constrained equipment budgets. European Union preservation grants in Italy and France support periodic technology upgrades.
- Airports:Terminal operators integrating walk-through portals with passenger processing infrastructure. FAA directives and TSA certification standards govern technology refresh timelines in the United States.
Airports and law enforcement anchor replacement demand. Mining companies are expanding most quickly in sensor performance requirements.
Distribution Channel:
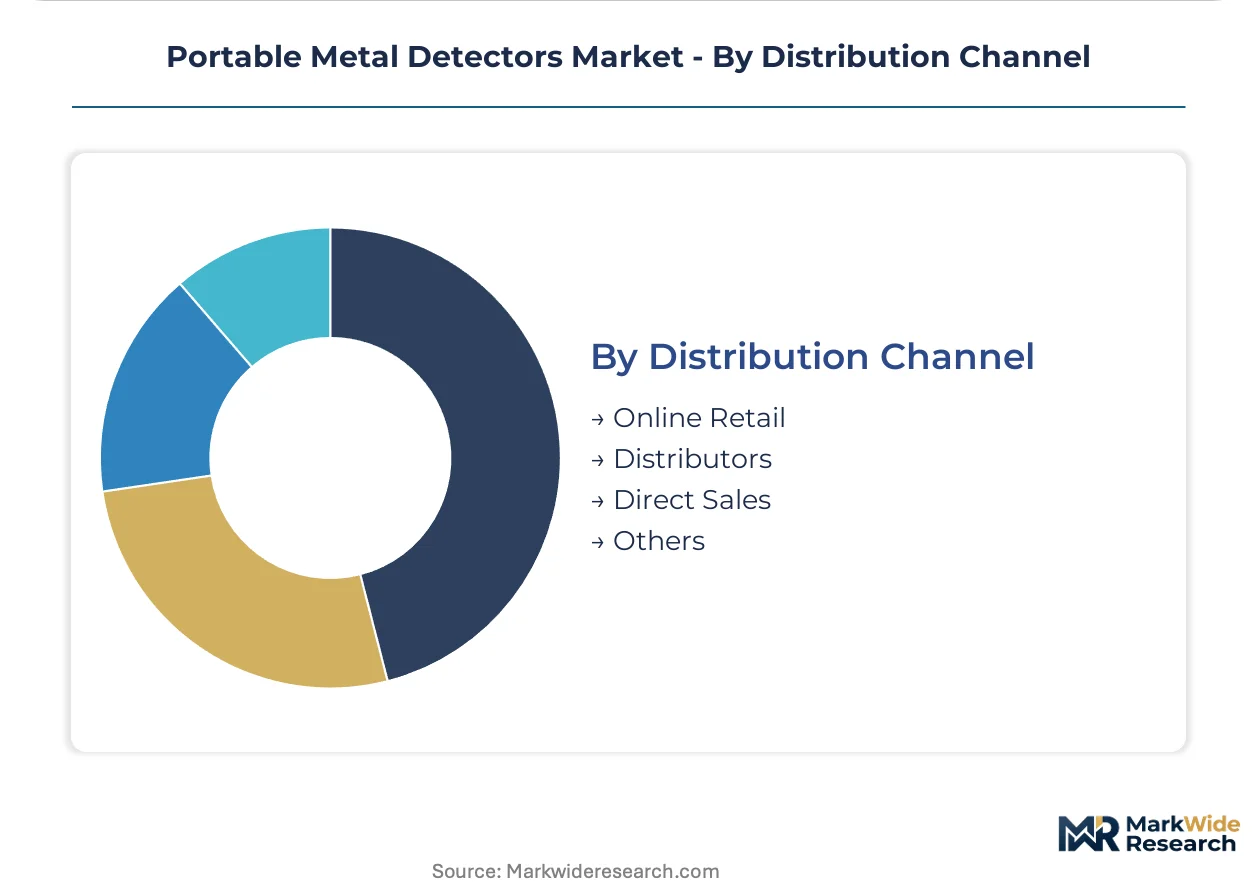
Direct sales capture institutional security contracts requiring customized protocol integration, while distributors and online retail serve price-sensitive commercial and consumer segments.
- Online Retail:E-commerce platforms serving hobbyist prospectors and small-scale security contractors. Consumer-grade handheld units with simplified discrimination interfaces dominate transaction volume.
- Distributors:Regional inventory and technical support networks for law enforcement and industrial accounts. German and French distributors maintain CE marking documentation for EU tender compliance.
- Direct Sales:Manufacturer-led contracting for airport authorities and critical infrastructure operators. TSA and EU AI Act certification requirements favor established vendor relationships.
- Others:Government procurement frameworks and cooperative purchasing agreements. United States federal supply schedules and European Union joint procurement mechanisms consolidate volume.
Direct sales secure the premium institutional tier. Distributor networks are gaining share fastest in mid-market commercial segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Portable metal detector deployment patterns diverge sharply across major economies, with security applications dominating procurement in the United States and European Union while mining and exploration drive demand in Australia and Saudi Arabia.
United States
TSA funding cycles and FAA directives on passenger checkpoint technology sustain replacement volumes for walk-through and handheld units at federal and municipal levels. Critical infrastructure protection mandates require ISO 9001 and IEC 62368-1 compliance for cross-border sales. Texas-based manufacturing clusters maintain captive coil winding capabilities that insulate domestic producers from component bottlenecks.
Germany
CE marking under the EU Machinery Directive and emerging EU AI Act provisions reshape product certification pathways for security screening equipment. German airport authorities emphasize total cost of ownership in multi-year service contracts rather than standalone hardware purchases. Bavaria and North Rhine-Westphalia host distributor networks maintaining documentation for EU tender compliance.
Australia
Goldfield operations and mineral prospecting in Western Australia and Queensland sustain replacement demand for ground-search platforms with deep-target detection sensitivity. Mining operators adopt multi-frequency electromagnetic induction systems to reduce false-positive rates in geologically complex terrain. Perth and Kalgoorlie anchor exploration equipment supply chains.
Saudi Arabia
National regulators add localized electromagnetic emissions testing requirements that create first-mover advantages for compliant suppliers in security and mining applications. Exploration concessions in the Eastern Province drive sensitivity benchmarking for subsurface utility mapping. Riyadh-based procurement channels consolidate volume for critical infrastructure protection.
Japan
Industrial contaminant control requirements in pharmaceutical packaging lines and electronics fabs deploy utility-grade detectors for metallic contaminant detection. METI standards govern electromagnetic emissions for food processing and textile manufacturing applications. Osaka and Nagoya manufacturing corridors concentrate non-security revenue channels.
Portable Metal Detectors Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with captive manufacturing capabilities and direct government contracting relationships determining competitive position. The structure rewards electromagnetic sensor engineering depth and foundry access over pure distribution scale. Three archetypes dominate: vertically integrated manufacturers with in-house coil winding, security-focused specialists with TSA and EU certification track records, and mining-heritage brands leveraging prospecting credibility. Capacity expansion in Texas and Milan-area production clusters and strategic partnerships for AI-enabled threat classification modules represent the dominant competitive moves.
Within the integrated manufacturing tier, Garrett Metal Detectors and C.E.I.A. S.p.A. exemplify archetypes built on geographic production concentration and direct institutional relationships. Garrett occupies a position tied to Texas-based foundry relationships, while C.E.I.A. S.p.A. anchors European airport security tenders through its Milan-area presence. Minelab represents the mining-heritage specialist archetype, leveraging Australian goldfield credibility to dominate ground-search sensitivity benchmarks.
| Leading Market Players |
|---|
| Garrett Metal Detectors |
| C.E.I.A. S.p.A. |
| Fisher Research Laboratory |
| Nokta Metal Detectors |
| Minelab |
| Range Security Detectors, Inc. |
| White's Electronics |
| SUNS International, LLC |
| OSI Systems, Inc. |
| Others |
Value Chain & Pricing Dynamics
CE marking under the EU Machinery Directive and FAA certification standards gate both supplier qualification and price differentiation simultaneously, compressing margins for uncertified entrants while allowing established electromagnetic sensor manufacturers to command service-contract premiums in institutional procurement channels.
Pricing Analysis
Long-term outcome-based service contracts now dominate institutional procurement in the United States and European Union, displacing transactional equipment sales. Three-tier pricing structure across premium certified, standard compliant, and economy uncertified levels tracks directly to TSA and CE certification tiers. Cost compression in the economy handheld segment is intensifying because Chinese manufacturers without captive coil winding capabilities face component bottleneck exposure. Law enforcement patrol budgets exhibit highest price sensitivity, while airport authorities prioritize total cost of ownership over unit acquisition price.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes are elevating inbound logistics costs for ferrite core and copper coil imports. Manufacturing gravity centers on Texas, Italy, and Australia, with Garrett Metal Detectors maintaining captive foundry relationships in the former and C.E.I.A. S.p.A. anchoring Milan-area production. Raw material dependencies draw from Chinese rare earth processing, German precision electronics, and Japanese ferrite suppliers. Single-source vulnerability in Texas-based coil winding creates concentration risk. Distribution runs through direct sales for airport authorities and distributor networks for law enforcement accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Portable metal detector adoption sits in early-cycle expansion as AI-enabled threat classification modules trigger replacement demand across airport security infrastructure and law enforcement patrol budgets.
For Market Incumbents: Compound defensive positioning through backward integration into captive coil winding capabilities and accelerated EU AI Act certification investment. Algorithmic transparency requirements favor established electromagnetic sensor engineering depth over emerging software-only entrants. Capacity addition in Texas and Milan-area production clusters insulates against component bottleneck exposure. For New Entrants and Emerging Players: Anchor in industrial contaminant control applications in Japan and South Korea, where METI standards govern food processing and textile manufacturing deployments with lower certification overhead than security applications. The utility-grade detector segment offers the most penetrable entry point. Pursue distributor partnerships with German and French networks maintaining CE marking documentation. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across AI-enabled discrimination algorithm development, favoring targets with in-house firmware capabilities and direct government contracting relationships. Viable acquisition archetypes combine Australian ground-search heritage with European airport security certification track records. Watch for FAA directive acceleration on passenger checkpoint technology as inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Certification Investment | CE marking intersection with algorithmic transparency requirements compresses timelines for German and French airport tenders. |
| Captive Coil Winding Expansion | Texas and Milan-area production clusters insulate Garrett and C.E.I.A. from ferrite core supply concentration risk. |
| Industrial Contaminant Control Entry | Japanese pharmaceutical packaging lines and South Korean electronics fabs open non-security revenue channels with lower compliance burden. |
| Outcome-Based Service Contracting | TSA cooperative purchasing agreements now emphasize total cost of ownership, locking in multi-year maintenance and calibration revenue. |
| Multi-Frequency Architecture Migration | Pulsed induction systems transmitting across 3-100 kHz bands displace single-frequency analog competitors lacking firmware-upgradable libraries. |
Study Parameters
A spread of perspectives from airport security directors, electromagnetic sensor engineers, law enforcement procurement officers, and industrial maintenance directors converged on the working assumptions. Primary interviews combined with secondary validation from FAA directive filings, TSA procurement databases, EU Machinery Directive conformity assessments, and customs records on ferrite core trade flows. Bottom-up unit shipment modeling and top-down revenue triangulation anchored the analytical framework.
Segmentation dimensions modeled include product type architecture, application certification tier, end-user procurement channel, and regional regulatory cluster across the analysis window. CAGRs derived from replacement cycle analysis, infrastructure investment pipelines, and technology displacement curves. Forecast inputs incorporated passenger throughput recovery trajectories and EU AI Act implementation timelines.
Decision-makers should treat outputs as directional under base assumptions of sustained TSA funding cycles and CE marking continuity; material deviation would warrant model refresh. Specific risks include electromagnetic sensor engineering talent collapse constraining R&D throughput and algorithmic certification timeline extensions compressing product launch windows. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Detection and Regulation Devices
Betavoltaic Device Market
Detection and Regulation Devices
Ultra Low Dropout Regulator (LDO) Market
Detection and Regulation Devices
Global Surge Protection Devices Market
Detection and Regulation Devices
Signaling Devices Market
Detection and Regulation Devices
Photoionization Detectors Market
Detection and Regulation Devices
Radar Detector Market
Detection and Regulation Devices
Neutron Detector Market
Detection and Regulation Devices
ESD Suppressors Market
Detection and Regulation Devices
Digital Metal Detector Market
Detection and Regulation Devices
Active Buzzer Market
Detection and Regulation Devices
Carbon Monoxide (Co) Detector Market
Detection and Regulation Devices
Null Detector Market
Detection and Regulation Devices
IR Detector Market
Detection and Regulation Devices
Arc Fault Detection Devices Market
Detection and Regulation Devices
Semiconductor Inspection System Market
Detection and Regulation Devices
Walk Through Metal Detector Market