
 IR Detector Market | 2026-2036
IR Detector Market Size, Share, and Industry Trends Forecast 2026-2036
IR Detector Market Outlook
Aftermarket sensor calibration and refurbishment revenue is fragmenting across regional service networks as original equipment margins compress. Excelitas Technologies Corp. leverages its vertically integrated quartz MEMS fabrication to sustain premium positioning in pyroelectric detector supply. Hamamatsu Photonics K.K. anchors the quantum IR detector segment through proprietary InGaAs photodiode architectures. Teledyne Technologies competes in cooled HgCdTe focal plane arrays for defense applications, occupying a narrow but defensible technology tier.
An IR detector is a solid-state transducer that converts infrared electromagnetic radiation, typically within wavelengths of 0.75 to 14 micrometers, into measurable electrical signals through thermal or photonic mechanisms, with responsivity and noise-equivalent temperature difference serving as critical performance parameters. These devices enable non-contact temperature measurement, thermal imaging, and spectral analysis across industrial process control, military targeting, and medical diagnostics. Thermal IR sensors lead unit shipments in building automation and consumer motion detection where cost minimization dominates procurement criteria. Cooled technology concentrates value capture in satellite payloads and long-range surveillance where quantum efficiency and frame rate requirements exclude uncooled alternatives. Quantum IR detectors represent the fastest-growing architecture in spectroscopic environmental monitoring applications.
FDA 21 CFR Part 1020 governs medical imaging equipment incorporating IR detectors for thermal breast screening and vascular mapping, mandating radiation safety performance standards that shape product development cycles. EU RoHS and REACH directives restrict cadmium, mercury, and lead content in detector materials, forcing suppliers to reformulate HgCdTe epitaxy processes or substitute alternative semiconductor compounds. The EU AI Act introduces conformity requirements for automated decision systems in surveillance applications, directly affecting thermal camera deployments in public spaces. Stakeholders must monitor evolving dual-use export control classifications under Wassenaar Arrangement guidelines that govern cooled detector cross-border transfers.
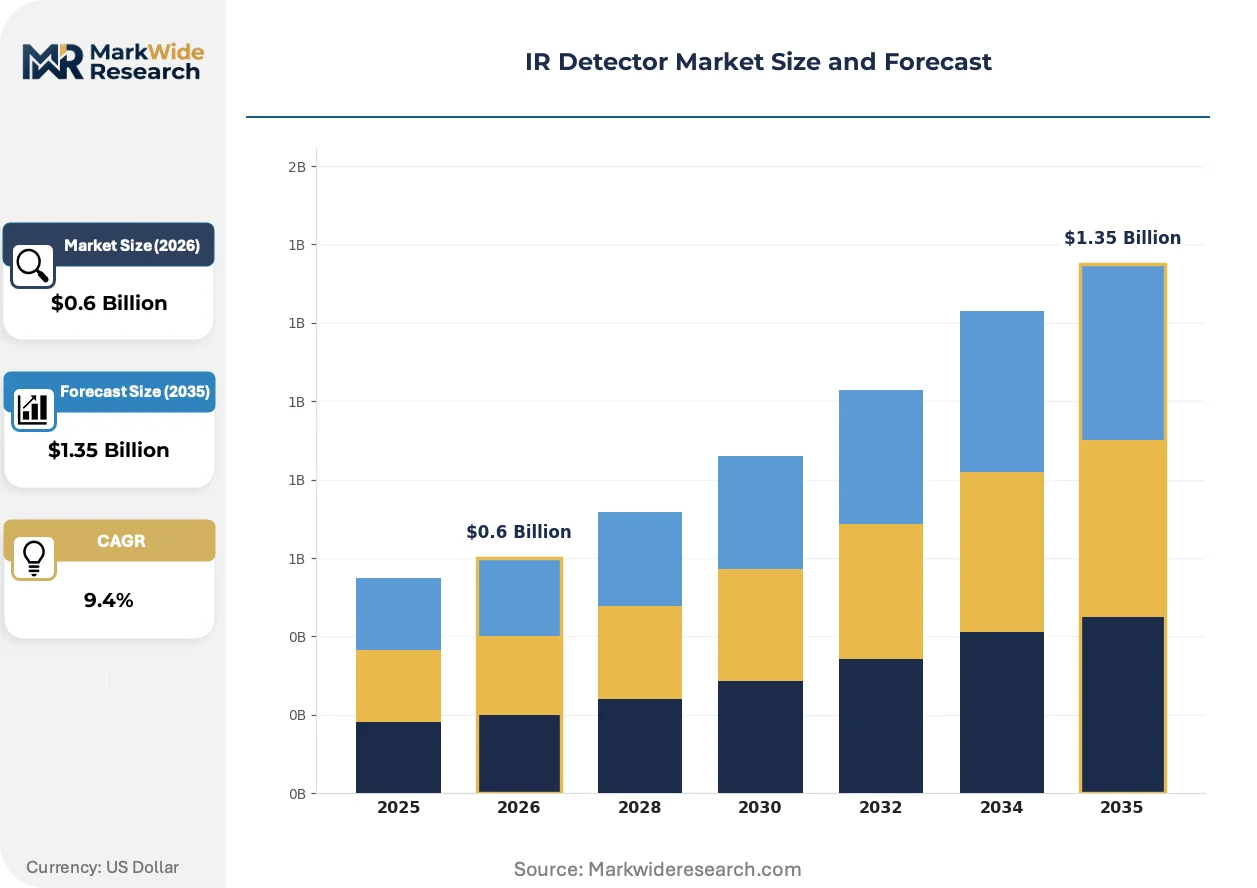
Market Dynamics
Uncooled microbolometer technology is collapsing cost structures across thermal imaging applications, enabling volume deployment in automotive safety and building automation while compressing margins for legacy cooled detector suppliers.
Growth Catalysts
- Automotive Night Vision Mandates:OEMs in Germany and Japan integrate thermal sensing for pedestrian detection, with NHTSA testing protocols accelerating North American adoption timelines.
- EU AI Act Surveillance Rules:Automated decision system conformity requirements create certified product demand for thermal camera deployments in public infrastructure monitoring.
- RoHS Material Exemptions:Restrictions on cadmium and mercury in detector materials force HgCdTe reformulation, opening substitution pathways for alternative semiconductor compounds.
Market Restraints
- Indium Antimonide Supply Concentration:Limited foundry capacity for InSb substrates concentrates sourcing risk among three specialized Japanese and US suppliers.
- Dual-Use Export Controls:Wassenaar Arrangement classifications impose licensing friction on cooled focal plane array transfers to non-member states.
- Quantum Efficiency Trade-offs:Uncooled microbolometers sacrifice responsivity at wavelengths beyond 14 micrometers, excluding long-wave infrared spectroscopy applications.
Strategic Opportunities
- India Industrial Automation:BIS certification requirements and PLI scheme incentives create localized assembly demand for pyroelectric motion sensors in smart manufacturing.
- Medical Thermal Imaging:FDA 21 CFR Part 1020 radiation safety standards for breast screening equipment open reimbursement pathways for vascular mapping diagnostics.
- AI-Edge Convergence:On-chip neural processing integration with microbolometer arrays enables real-time threat classification without external compute.
Industry Challenges
- MEMS Fabrication Talent Scarcity:Specialized cleanroom process engineers command premium compensation, constraining capacity expansion at quartz micromachining facilities.
- Cross-Border Certification Delays:Divergent electromagnetic compatibility testing between FCC and CE marking regimes extends product launch timelines by 8-14 months.
- Legacy System Integration:Analog-output detector replacement in existing thermal camera installations requires signal conditioning retrofit engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | IR Detector Market |
| Market Size in 2026 | $0.6 Billion |
| Market Size in 2035 | $1.35 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermal IR Sensors, Quantum IR Detectors, Photoconductive Detectors, Pyroelectric Detectors Technology: Uncooled, Cooled, Fabry-Pérot, Photonic Crystal Application: Surveillance, Medical Imaging, Automotive Safety, Environmental Monitoring End User: Defense, Aerospace, Healthcare, Industrial |
| Companies Covered | Excelitas Technologies Corp., Hamamatsu Photonics K.K., Murata Manufacturing Co., Ltd., Texas Instruments Incorporated, Teledyne Technologies, Lynred, InfraTec GmbH, Nippon Ceramic Co., Ltd., OMRON Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
IR Detector Market Strategic Shifts
Thermal sensing architectures are fragmenting across performance tiers, with quantum efficiency requirements dictating technology selection while manufacturing scale drives unit economics divergence.
Wafer-level vacuum packaging is collapsing cost curves for uncooled microbolometer production. Automotive Tier-1 suppliers in Germany and Japan adopt these devices for night vision modules at 40% lower bill-of-materials than ceramic-packaged alternatives. The structural compression enables thermal camera standardization in economy vehicle segments previously served only by premium brands.
REACH substance restrictions are forcing HgCdTe epitaxy process redesigns across European detector foundries. ECHA authorization requirements for cadmium compounds extend qualification timelines for new focal plane array designs. Defense contractors in France and Germany accelerate indium gallium arsenide photodiode development as RoHS-compliant alternatives for short-wave infrared applications.
Service unbundling is separating hardware procurement from calibration maintenance in industrial thermal imaging. End-users in US process control sectors now contract regional metrology laboratories for annual detector responsivity verification rather than manufacturer service agreements. This channel fragmentation concentrates aftermarket revenue among third-party ISO 17025-accredited facilities in Texas, Ohio, and California industrial corridors.
IR Detector Market Segmentation
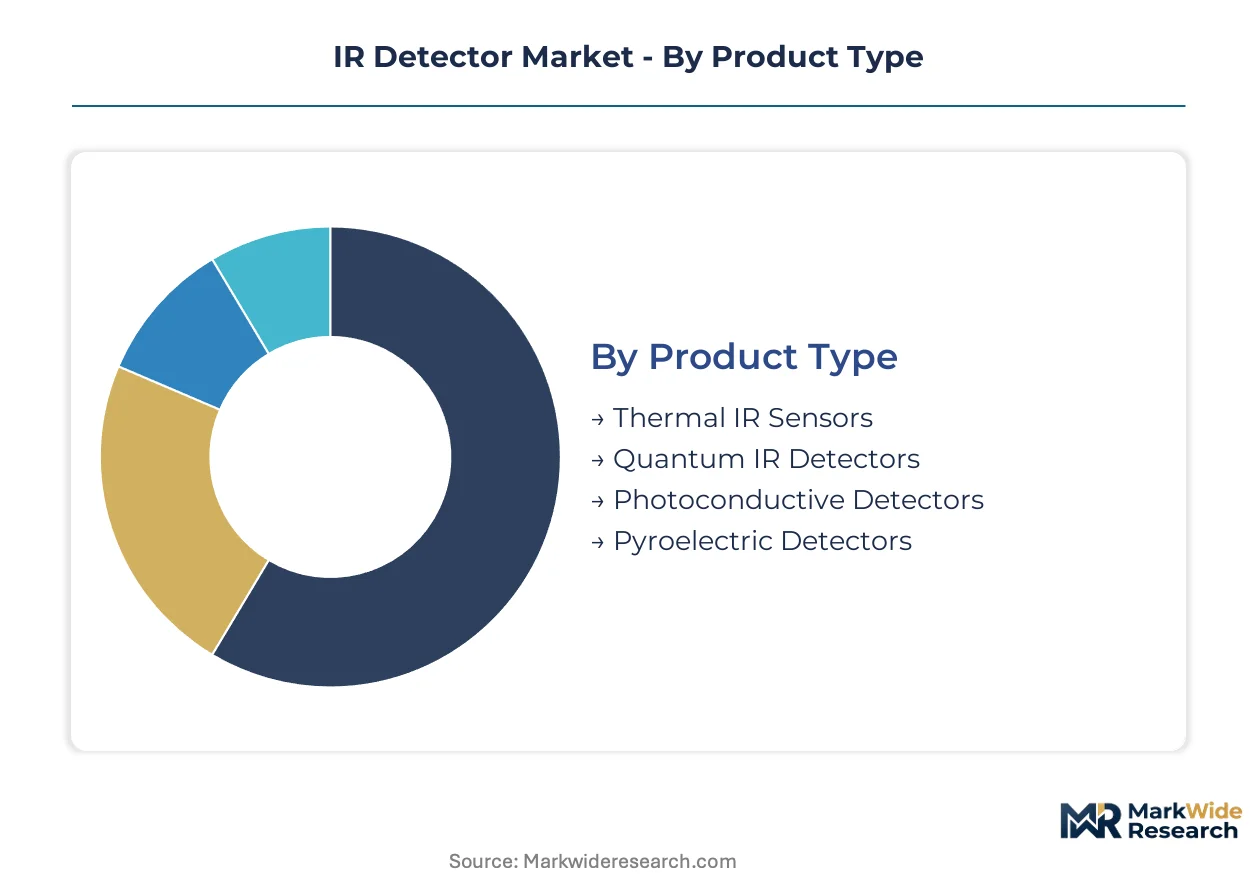
IR detector procurement patterns diverge sharply across product architectures and cooling requirements, with aftermarket service intensity varying from minimal calibration for consumer pyroelectric units to complex vacuum maintenance for cooled focal plane arrays in satellite payloads.
Product Type:
After-sales service intensity escalates from passive thermal sensors requiring only periodic responsivity checks to quantum detectors demanding cryogenic system refurbishment and hermetic seal replacement.
- Thermal IR Sensors:Microbolometer and thermopile architectures convert infrared radiation into temperature differentials through resistive or thermoelectric mechanisms. Building automation installers in Germany and Japan specify these for occupancy detection where 10-year calibration intervals minimize lifetime ownership costs. By volume, thermal IR sensors lead. By growth pace, quantum IR detectors are expanding most quickly.
- Quantum IR Detectors:Photodiode and photoconductor designs exploit the photoelectric effect across InGaAs, HgCdTe, and InSb semiconductor junctions. Spectroscopic environmental monitoring stations in the United States deploy these for methane leak detection where quantum efficiency above 70% at 3-5 micrometers enables parts-per-billion sensitivity.
- Photoconductive Detectors:PbS and PbSe thin-film elements modulate conductivity under infrared illumination for legacy process control instrumentation.
- Pyroelectric Detectors:Lithium tantalate and PZT ceramic crystals generate surface charge from temperature fluctuations in passive infrared motion sensors.
Service revenue concentrates in cooled quantum architectures where cryogenic compressor maintenance generates recurring manufacturer attachment rates.
Technology:
Cost tier stratification separates volume applications tolerating reduced responsivity from premium segments demanding shot-noise-limited performance.
- Uncooled:Microbolometer focal plane arrays operate at ambient temperature through vacuum-packaged thermistor matrices. Automotive Tier-1 suppliers in Germany integrate these into night vision modules where wafer-level packaging has compressed unit costs below ceramic-packaged alternatives. By volume, uncooled technology leads. By growth pace, photonic crystal architectures are gaining share fastest.
- Cooled:Stirling-cycle or thermoelectric cooling maintains HgCdTe and InSb arrays at 77 Kelvin to suppress thermal noise for long-range surveillance. Defense procurement in the United States sustains this segment despite 40% higher bill-of-materials than uncooled equivalents.
- Fabry-Pérot:Tunable optical cavity structures enable wavelength-selective detection without dispersive elements in compact gas analyzers.
- Photonic Crystal:Nanostructured silicon or germanium lattices engineer artificial optical bandgaps for enhanced absorption in silicon-compatible infrared detection.
Manufacturing scale favors uncooled production while cooled systems retain pricing power in export-controlled defense applications.
Application:
Customer maturity varies from standardized automotive safety specifications to evolving medical reimbursement pathways for thermal diagnostics.
- Surveillance:Thermal camera networks for perimeter security and public infrastructure monitoring. EU AI Act conformity requirements in France and Germany now mandate certified automated decision systems for thermal analytics in public spaces.
- Medical Imaging:FDA 21 CFR Part 1020 governs thermal breast screening and vascular mapping equipment, with radiation safety performance standards shaping product development cycles for US manufacturers.
- Automotive Safety:Night vision and pedestrian detection systems integrate thermal sensing alongside visible cameras. NHTSA testing protocols in the United States accelerate validation timelines for OEM deployment.
- Environmental Monitoring:Spectroscopic detection of greenhouse gases and industrial emissions. Quantum detector architectures dominate this segment where wavelength resolution requirements exclude thermal alternatives.
Regulatory complexity is highest in medical and surveillance applications where multi-jurisdictional certification extends commercialization timelines.
End User:
Procurement authority concentrates in defense agencies with long-term supply agreements, while industrial buyers fragment across regional system integrators.
- Defense:Cooled focal plane arrays for targeting pods, missile seekers, and long-range reconnaissance. Wassenaar Arrangement export controls constrain cross-border transfers to non-member states.
- Aerospace:Satellite payloads and unmanned aerial vehicle gimbals demand radiation-hardened detectors with proven orbital reliability.
- Healthcare:Thermal imaging for fever screening, wound assessment, and oncology diagnostics. Reimbursement coding in the United States determines clinical adoption velocity.
- Industrial:Process control, predictive maintenance, and quality inspection across manufacturing facilities. BIS certification requirements in India and PLI scheme incentives are localizing assembly demand for pyroelectric motion sensors.
Defense and aerospace segments capture value through technology access restrictions, while industrial volume scales through distributor networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial automation buyers in Germany exhibit the lowest price elasticity, absorbing premium cooled detector costs for precision manufacturing, while building automation procurement in India operates at extreme cost sensitivity where uncooled pyroelectric sensors dominate.
United States
Defense procurement sustains demand for HgCdTe focal plane arrays in targeting pods and satellite payloads. NHTSA testing protocols for automotive night vision accelerate OEM validation cycles. Detector assembly concentrates in Texas and California industrial corridors where regional metrology laboratories capture aftermarket calibration revenue.
Germany
Automotive Tier-1 suppliers integrate wafer-level packaged microbolometers into night vision modules for pedestrian detection. EU AI Act conformity requirements mandate certified automated decision systems for thermal surveillance in public infrastructure. Bavaria hosts precision MEMS fabrication clusters serving both automotive and industrial automation end-users.
Japan
Limited foundry capacity for InSb substrates concentrates sourcing risk among specialized domestic suppliers. METI industrial policy supports quantum detector development for spectroscopic environmental monitoring. Nagoya and Osaka metropolitan areas anchor pyroelectric sensor production for consumer motion detection applications.
India
BIS certification requirements and PLI scheme incentives localize assembly demand for pyroelectric motion sensors in smart manufacturing. Extreme cost sensitivity in building automation procurement favors uncooled thermal architectures over quantum alternatives. Gujarat and Maharashtra industrial corridors attract component sourcing for process control instrumentation.
China
Dual carbon goals drive spectroscopic methane leak detection deployments requiring quantum efficiency above 70% at 3-5 micrometers. MIIT standards govern electromagnetic compatibility testing for thermal camera exports. Yangtze River Delta manufacturing clusters scale wafer-level vacuum packaging for microbolometer cost reduction.
IR Detector Market Competitive Environment
Capability concentration sits with specialized cooled detector foundries serving defense and aerospace; scale advantage sits with semiconductor houses leveraging consumer electronics fabrication infrastructure. The vendor base stratifies across three tiers: vertically integrated MEMS fabricators, photonics specialists with compound semiconductor expertise, and diversified electronics conglomerates with sensor division operations. Dominant competitive moves include backward integration into quartz micromachining capacity and strategic partnerships with automotive Tier-1 suppliers for night vision module co-development.
Among established detector specialists, Excelitas Technologies Corp., Hamamatsu Photonics K.K., and Teledyne Technologies occupy positions across distinct technology tiers. Excelitas exemplifies the vertically integrated archetype through captive quartz MEMS fabrication. Hamamatsu anchors the quantum detector segment with compound semiconductor photodiode expertise. Teledyne represents the defense-focused tier where export-controlled cooled focal plane arrays sustain pricing power despite higher bill-of-materials.
| Leading Market Players |
|---|
| Excelitas Technologies Corp. |
| Hamamatsu Photonics K.K. |
| Murata Manufacturing Co., Ltd. |
| Texas Instruments Incorporated |
| Teledyne Technologies |
| Lynred |
| InfraTec GmbH |
| Nippon Ceramic Co., Ltd. |
| OMRON Corporation |
| Others |
Value Chain & Pricing Dynamics
InSb substrate foundry capacity in Japan and the United States concentrates among three specialized suppliers, anchoring pricing power for cooled quantum detectors while compressing margins for downstream integrators dependent on these inputs. This upstream concentration funnels margin capture toward cryogenic system refurbishment and hermetic seal replacement services, where manufacturers sustain recurring revenue attachment rates.
Pricing Analysis
After-sales service contracts for cryogenic compressor maintenance drive lifetime value in cooled detector architectures. Three-tier pricing structure across defense-grade, industrial-grade, and commercial-grade certification levels segments procurement tiers. Cost compression in wafer-level packaged microbolometers intensifies pricing pressure from automotive Tier-1 suppliers. Building automation buyers in India exhibit extreme price sensitivity, while German industrial automation buyers absorb premium cooled detector costs with minimal elasticity.
Supply Chain Analysis
Contract manufacturing for vacuum packaging concentrates in Yangtze River Delta facilities and Bavarian MEMS clusters. Raw material flows draw from germanium substrates, indium antimonide boules, and lithium tantalate crystals. Single-source vulnerability in InSb substrate supply creates structural risk for defense contractors. Distribution runs through regional metrology laboratories in Texas, Ohio, and California for aftermarket calibration, alongside direct OEM supply agreements for automotive night vision modules.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Defense procurement cycles and automotive safety mandate rollouts position this market for cyclical recovery, with NHTSA testing protocols and EU AI Act conformity timelines providing synchronized demand triggers.
For Market Incumbents: Pre-empt margin erosion in uncooled microbolometers by securing captive quartz MEMS fabrication capacity and accelerating wafer-level packaging qualification with German automotive Tier-1 suppliers. Defend against emerging Chinese cost competitors through BIS certification partnerships in India and PLI scheme-aligned local assembly investments. For New Entrants and Emerging Players: Establish a beachhead in pyroelectric motion sensors for Indian smart manufacturing, where BIS requirements and PLI incentives create qualified demand with limited incumbent saturation. Target environmental monitoring spectroscopy applications with RoHS-compliant InGaAs photodiode alternatives, leveraging REACH-driven HgCdTe substitution pathways as the go-to-market angle. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed defense electronics platforms holding export-controlled cooled focal plane array capabilities. Long-term viability over a multi-year horizon hinges on Wassenaar Arrangement classification stability and dual-use technology access restrictions. Monitor indium antimonide foundry capacity utilization as the inflection signal for supply-constrained pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| Wafer-Level Vacuum Packaging Scale-Up | Yangtze River Delta and Bavarian clusters compress microbolometer costs for automotive night vision standardization. |
| RoHS-Compliant Compound Semiconductor Development | InGaAs photodiode architectures from Hamamatsu and European foundries substitute restricted HgCdTe in spectroscopic applications. |
| AI-Edge Neural Processing Integration | On-chip inference with microbolometer arrays enables real-time threat classification without external compute infrastructure. |
| Regional Metrology Laboratory Certification | ISO 17025-accredited facilities in Texas and Ohio capture aftermarket calibration revenue from fragmented industrial buyers. |
| Dual-Use Export Control Compliance Investment | Wassenaar Arrangement licensing infrastructure sustains pricing power for cooled focal plane arrays in defense applications. |
Study Parameters
Desk research of customs trade databases, SEC 10-K filings from detector manufacturers, and ECHA REACH authorization records preceded structured interviews with MEMS fabrication engineers, automotive Tier-1 procurement leads, defense contractor program managers, and regional metrology laboratory directors. Bottom-up unit shipment estimates across uncooled and cooled technology tiers were triangulated against top-down defense procurement budget allocations and automotive safety system content forecasts.
Assumptions regarding Wassenaar Arrangement classification stability, EU AI Act enforcement timelines, and NHTSA mandate adoption curves were held fixed across scenarios, while indium antimonide supply elasticity and wafer-level packaging yield trajectories were varied. The analytical framework modeled product type, cooling requirement, application, and end-user segmentation dimensions across the projection horizon. CAGR derivation incorporated automotive night vision penetration rates, industrial automation sensor density trends, and spectroscopic environmental monitoring deployment schedules.
Stress conditions across InSb substrate supply disruption, REACH substance restriction acceleration, and automotive OEM insourcing decisions were modeled; outcomes outside those bands fall beyond the analytical envelope. Quarterly review of defense procurement award announcements, BIS certification issuance rates, and automotive Tier-1 supplier contract awards is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Detection and Regulation Devices
Temperature Detection Screen Market
Detection and Regulation Devices
Europe Trace Detection Market
Detection and Regulation Devices
Infrared Detection Chip Market
Detection and Regulation Devices
Handheld Optical Gas Imaging Camera Market
Detection and Regulation Devices
Microwave Leakage Detector Market
Detection and Regulation Devices
Temperature Modulation Devices Market
Detection and Regulation Devices
Leak Detection Equipment Market
Detection and Regulation Devices
Volatile Organic Compound (VOC) Detector Market
Detection and Regulation Devices
Explosive Detectors Market
Detection and Regulation Devices
Global Tunnel Diode Detectors Market
Detection and Regulation Devices
Pin and Sleeve Devices Market
Detection and Regulation Devices
Semiconductor Leak Detectors Market
Detection and Regulation Devices
X-Ray Detectors Market
Detection and Regulation Devices
Europe Gas Detectors Market
Detection and Regulation Devices
South East Asia Gas Detection Device Market
Detection and Regulation Devices
Smart Water Leak Detector Market