
 Neutron Detector Market | 2026-2036
Neutron Detector Market Size, Share, and Industry Trends Forecast 2026-2036
Neutron Detector Market Foresight
The specialized nuclear engineering workforce is rotating toward solid-state and semiconductor-based detection architectures, pulling investment away from legacy gas-filled systems. Thermo Fisher Scientific leverages its analytical instrumentation footprint to sustain R&D intensity across scintillation and activation platforms. Kromek Group anchors its position through cadmium zinc telluride crystal growth capabilities that differentiate its solid-state offerings. Ametek competes via its precision electronics manufacturing scale, supplying signal processing chains to multiple detector OEMs.
A neutron detector converts neutron flux into measurable electrical signals through interactions with sensitive materials such as helium-3, boron-10, or lithium-6, achieving thermal neutron detection efficiencies ranging from 60% to over 90% depending on converter geometry and fill gas pressure. These instruments serve critical functions in reactor control, nuclear safeguards verification, and radiation portal monitoring for fissile material interdiction. Helium-3 detectors retain established positions in safeguards applications despite supply constraints from tritium decay production, while solid-state detectors capture expanding share in portable and distributed deployments where size and power budgets tighten. Homeland security procurement concentrates margin pools in ruggedized, network-ready systems, whereas research institutions drive specification innovation through custom neutron spectroscopy requirements.
The US Nuclear Regulatory Commission enforces 10 CFR Part 50 and Part 73 standards that mandate redundant neutron monitoring in commercial reactors, directly shaping product certification requirements and procurement cycles. France's Autorité de Sûreté Nucléaire and Japan's Nuclear Regulation Authority impose comparable instrumentation standards, creating a multi-jurisdictional compliance landscape for vendors. The International Atomic Energy Agency safeguards protocols further standardize detector performance benchmarks for export-controlled installations. Stakeholders must monitor helium-3 stockpile depletion timelines and alternative converter material qualification progress to align product roadmaps with supply chain realities.
Market Dynamics
Helium-3 depletion is forcing a wholesale technology migration toward boron-10 and lithium-6 converter materials, reshaping R&D priorities across safeguards and reactor instrumentation supply chains.
Growth Catalysts
- 10 CFR Part 50 mandates:The US Nuclear Regulatory Commission requires redundant neutron monitoring in commercial reactors, compelling utilities to refresh detector fleets on predictable procurement cycles.
- Decommissioning waste characterization:France's simultaneous reactor construction and decommissioning programs create dual demand streams for portable and fixed neutron detection systems.
- Cadmium zinc telluride maturation:Solid-state crystal growth advances are extending detector lifespans while reducing maintenance intervals in distributed monitoring networks.
Market Restraints
- Helium-3 supply concentration:US tritium stockpile decay remains the dominant production pathway, creating single-source dependency for safeguards-grade fill gas.
- Converter material qualification timelines:Alternative boron-10 and lithium-6 architectures face multi-year certification delays under IAEA safeguards protocols.
- Specialized workforce scarcity:Nuclear engineering talent pools are thinning as universities redirect resources toward semiconductor and renewable energy programs.
Strategic Opportunities
- Radiation portal modernization:Homeland security agencies in the United States are unbundling after-sales service contracts, opening recurring revenue streams for detector OEMs.
- Small modular reactor instrumentation:Emerging reactor designs in China require compact, network-ready neutron monitoring systems with reduced cabling infrastructure.
- Research spectroscopy customization:National laboratories in France are commissioning bespoke neutron spectrometers with application-specific converter geometries.
Industry Challenges
- Legacy system integration friction:Utilities operating 1970s-era reactor instrumentation face signal compatibility hurdles when retrofitting solid-state detectors into analog control chains.
- Cross-jurisdictional certification complexity:Vendors must simultaneously satisfy 10 CFR Part 73, ASN instrumentation standards, and NRA technical specifications for multi-country reactor deployments.
- IP fragmentation in solid-state architectures:Cadmium zinc telluride growth patents are distributed across national laboratory and commercial holders, complicating licensing negotiations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Neutron Detector Market |
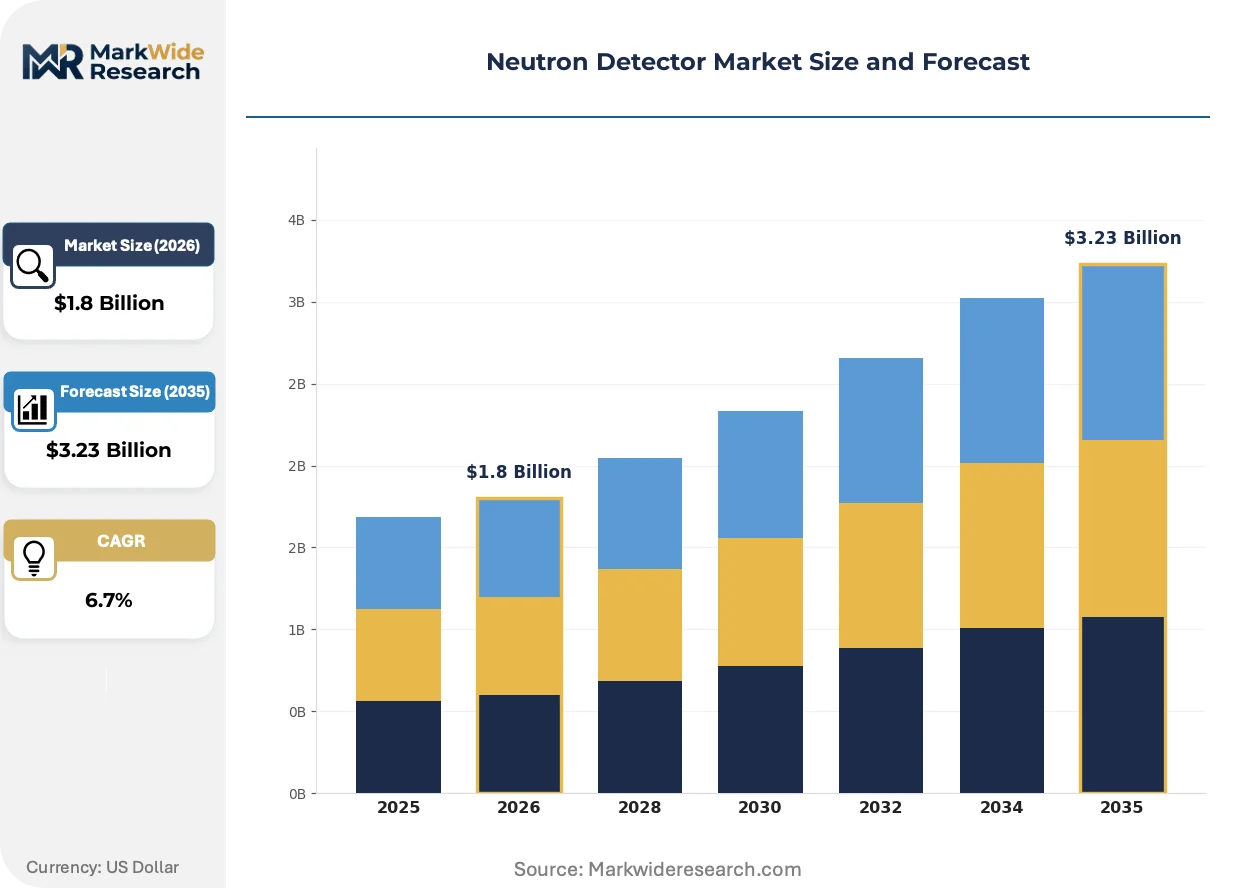
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Helium-3 Detectors, Boron Trifluoride Detectors, Organic Liquid Scintillators, Thermal Neutron Detectors Application: Nuclear Power Plants, Research Institutions, Homeland Security, Industrial Radiography Technology: Solid-State Detectors, Gas-Filled Detectors, Liquid Scintillation Detectors, Neutron Activation Analysis End User: Defense Organizations, Environmental Monitoring Agencies, Healthcare Facilities, Academic Research Centers |
| Companies Covered | Silverside Detectors, Kromek Group, Thermo Fisher Scientific, Ametek, Ludlum Measurements, Mirion Technologies, Leidos, Scionix Holland, Arktis Radiation Detectors, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Neutron Detector Market Shifts & Advancements
Solid-state detection architectures are compressing form factors and power budgets while regulatory agencies harmonize performance benchmarks across safeguards and reactor safety applications.
Semiconductor-based neutron detection is decomposing the traditional gas-filled detector value chain. Research institutions in France are piloting lithium-6-doped silicon arrays for compact spectroscopy applications. This technology is decomposing established supplier relationships by enabling in-house detector assembly at national laboratories.
IAEA safeguards protocols are tightening performance documentation requirements for export-controlled installations. Detector vendors must now submit thermal neutron efficiency certifications to multiple national regulators simultaneously. Small modular reactor developers in China are responding by pre-qualifying instrumentation packages against US, French, and Japanese standards in parallel.
Service unbundling is altering procurement patterns across utilities and homeland security agencies. Buyers are separating hardware acquisition from calibration and maintenance contracts, pressuring OEM margins while opening specialist service provider niches. This shift is most visible in US radiation portal deployments, where network management contracts now route through cybersecurity-focused vendors distinct from detector manufacturers.
Neutron Detector Market Segmentation
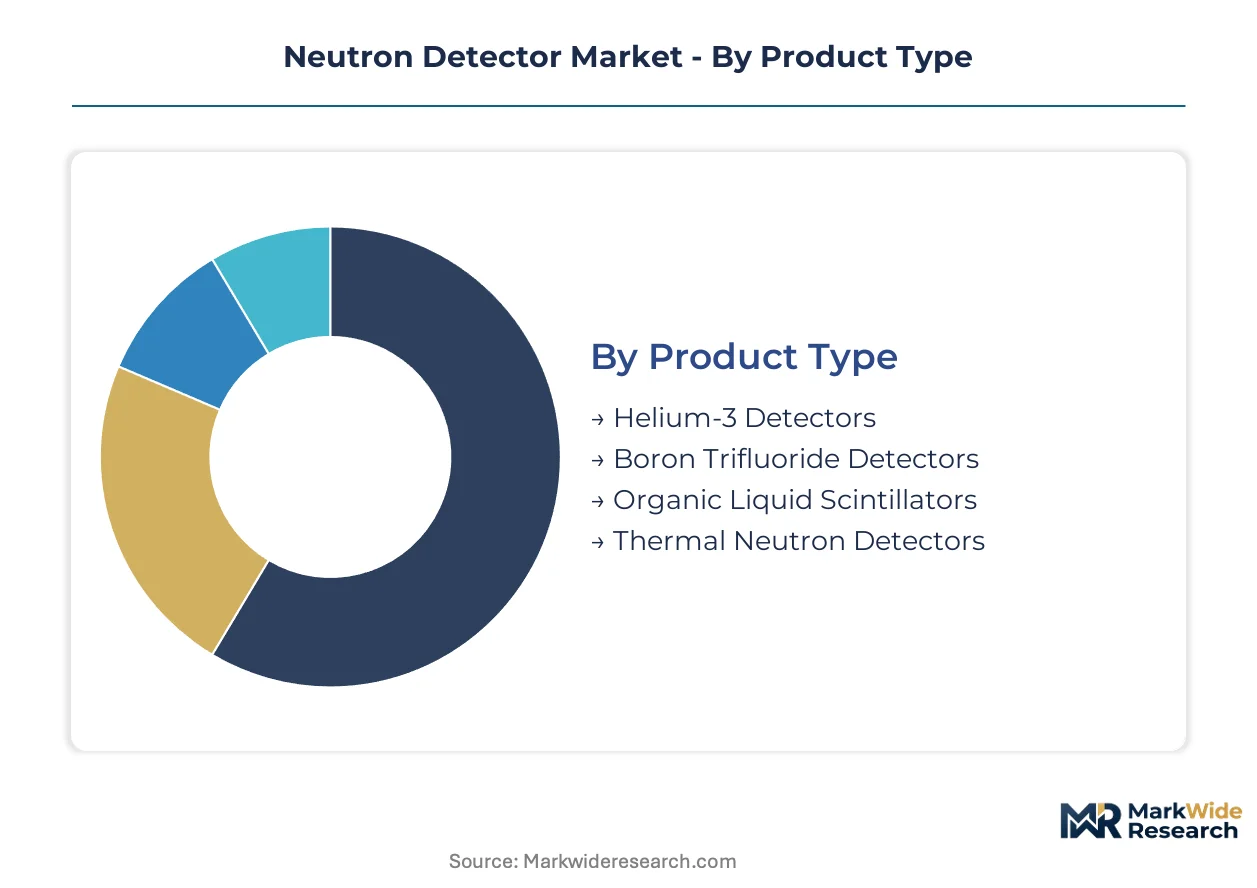
Neutron detector procurement splits sharply across converter chemistry, deployment environment, and certification tier, with margin concentration shifting as helium-3 scarcity forces material substitutions. Vendors align product portfolios to capture value pools in safeguards-grade instrumentation versus commoditized industrial monitoring.
Product Type:
Premium pricing concentrates in detectors qualified for IAEA safeguards protocols, where fill gas purity and converter geometry tolerances create certification barriers.
- Helium-3 Detectors:These gas-filled tubes exploit the high thermal neutron cross-section of helium-3 isotope, achieving detection efficiencies exceeding 80% in proportional counter configurations. US national laboratories and French safeguards agencies anchor demand despite supply constraints from tritium decay production pathways.
- Boron Trifluoride Detectors:BF3-filled proportional counters operate at lower voltages than helium-3 alternatives, with boron-10 converter layers deposited on internal cathode surfaces. China's reactor construction programs are absorbing expanded BF3 production capacity as utilities pre-position against helium-3 depletion timelines.
- Organic Liquid Scintillators:Pulse-shape discrimination capabilities enable simultaneous neutron-gamma detection in compact form factors.
- Thermal Neutron Detectors:Optimized converter geometries target specific neutron energy spectra for reactor control applications.
The dominant share belongs to Helium-3 Detectors, while Boron Trifluoride Detectors is closing the gap fastest.
Application:
Procurement volume concentrates in reactor instrumentation refresh cycles tied to regulatory compliance deadlines rather than greenfield deployment.
- Nuclear Power Plants:Redundant neutron monitoring channels satisfy 10 CFR Part 50 mandates in US commercial reactors, with detector replacement cycles averaging 10-15 years based on radiation damage accumulation. French and Japanese utilities are synchronizing fleet upgrades to ASN and NRA technical specification revisions.
- Homeland Security:Radiation portal monitors at US ports of entry require ruggedized, network-ready systems with tamper-evident enclosures. Customs and Border Protection procurement is unbundling hardware from calibration service contracts, opening recurring revenue streams for specialist providers.
- Research Institutions:National laboratories commission bespoke neutron spectrometers with application-specific converter geometries.
- Industrial Radiography:Non-destructive testing applications prioritize portability and battery operation over spectroscopic resolution.
Nuclear Power Plants commands the largest installed base, though Homeland Security is expanding most quickly as border infrastructure modernization accelerates.
Technology:
Investment intensity is rotating toward semiconductor architectures as solid-state crystal growth advances compress form factors and maintenance intervals.
- Solid-State Detectors:Cadmium zinc telluride and lithium-6-doped silicon arrays eliminate fill gas dependencies while extending operational lifespans in distributed monitoring networks. France's CEA is piloting compact spectroscopy platforms that decompose traditional supplier relationships through in-house assembly capabilities.
- Gas-Filled Detectors:Proportional counter and ionization chamber architectures retain established positions in high-flux reactor instrumentation where radiation tolerance exceeds solid-state alternatives. Legacy system integration friction complicates retrofit programs at 1970s-era US facilities.
- Liquid Scintillation Detectors:Organic scintillator cocktails enable neutron-gamma discrimination through pulse-shape analysis.
- Neutron Activation Analysis:Activation-based techniques serve specialized materials characterization requirements in geological and forensic applications.
Gas-Filled Detectors retains dominant share, while Solid-State Detectors is climbing the fastest as helium-3 scarcity accelerates substitution timelines.
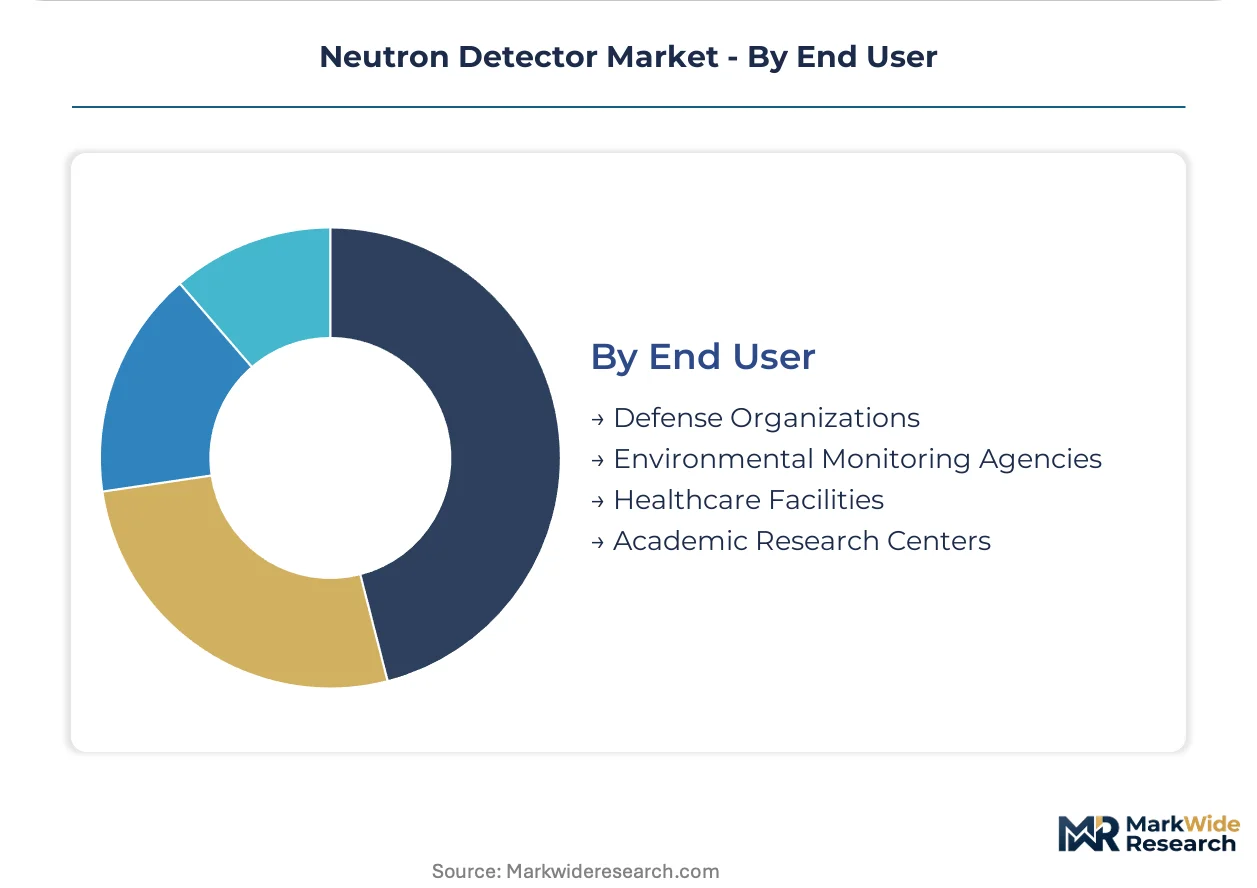
End User:
Specification authority fragments across procurement officers, nuclear safety regulators, and research principal investigators with divergent performance priorities.
- Defense Organizations:Military specifications emphasize ruggedization, electromagnetic hardening, and rapid deployment packaging for fieldable nuclear verification teams. US National Nuclear Security Administration stockpiling programs create demand spikes aligned with treaty monitoring obligations.
- Academic Research Centers:University-based neutron scattering facilities drive innovation in converter geometry and signal processing algorithms, with custom fabrication requirements that strain standard product margins. Oak Ridge and ILL Grenoble anchor specialized procurement volumes.
- Environmental Monitoring Agencies:Atmospheric radionuclide tracking networks prioritize sensitivity and long-term stability over portability.
- Healthcare Facilities:Boron neutron capture therapy applications require precise thermal neutron flux mapping for treatment planning.
Defense Organizations holds the largest contract values, while Academic Research Centers is gaining share fastest through national laboratory instrumentation budgets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Nuclear Regulatory Commission anchors the dominant geography through 10 CFR Part 50 and Part 73 mandates that compel reactor operators to maintain redundant neutron monitoring systems on predictable refresh cycles.
United States
Commercial reactor fleet upgrades and homeland security portal modernization drive procurement volume. The US Nuclear Regulatory Commission enforces redundant channel requirements under 10 CFR Part 50. Oak Ridge National Laboratory anchors specialized spectroscopy demand through custom instrumentation programs for materials characterization.
France
Simultaneous reactor construction and decommissioning programs create dual demand streams for portable and fixed detection systems. The Autorité de Sûreté Nucléaire imposes instrumentation standards comparable to US benchmarks. CEA facilities around Grenoble pilot lithium-6-doped silicon arrays that enable in-house detector assembly capabilities.
China
Small modular reactor construction and expanding nuclear capacity propel compact instrumentation requirements. The National Nuclear Safety Administration aligns technical specifications with international safeguards protocols. Yangtze River Delta manufacturing clusters scale boron trifluoride detector production to pre-position against helium-3 depletion timelines.
Japan
Post-Fukushima reactor restarts and stricter accountability rules compel detector fleet refreshes. The Nuclear Regulation Authority mandates enhanced monitoring under revised technical specifications. Tokyo-based utilities synchronize procurement with NRA compliance deadlines while Kansai region facilities upgrade aging instrumentation.
United Kingdom
New nuclear build programs at Hinkley Point C and Sizewell C stimulate safeguards-grade detector demand. The Office for Nuclear Regulation enforces instrumentation standards through site license conditions. Culham Centre for Fusion Energy drives research spectroscopy requirements through bespoke neutron diagnostic procurement.
Neutron Detector Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the neutron detector supply base. The market structure concentrates safeguards-grade certification among specialized nuclear instrumentation vendors while precision electronics manufacturers capture signal processing value pools. Three archetypes dominate: solid-state crystal growth specialists, analytical instrumentation conglomerates with nuclear divisions, and precision electronics suppliers serving multiple OEMs. Competitive moves center on alternative converter material qualification and unbundling of service contracts from hardware sales.
Within the solid-state specialization tier, Kromek Group exemplifies cadmium zinc telluride crystal growth capabilities that differentiate semiconductor-based offerings. Thermo Fisher Scientific occupies a position representing analytical instrumentation scale applied across scintillation and activation platforms. Ametek sits within the precision electronics archetype, supplying signal processing chains to detector OEMs without direct converter material exposure.
| Leading Market Players |
|---|
| Silverside Detectors |
| Kromek Group |
| Thermo Fisher Scientific |
| Ametek |
| Ludlum Measurements |
| Mirion Technologies |
| Leidos |
| Scionix Holland |
| Arktis Radiation Detectors |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts for helium-3 stockpiles lock in supply access and price visibility for safeguards-grade detector manufacturers, while simultaneously exposing utilities to cost escalation as tritium decay production pathways tighten. US national laboratories and French safeguards agencies anchor procurement through multi-year agreements that transfer inventory risk upstream.
Pricing Analysis
US radiation portal deployments command 15-25% premiums over comparable European installations due to cybersecurity hardening and network integration requirements. Pricing stratifies across IAEA-certified safeguards tiers, with boron-10 converter systems undercutting legacy helium-3 configurations as qualification timelines compress. Cost compression in solid-state architectures is intensifying because cadmium zinc telluride crystal growth yields are improving. Homeland security agencies exhibit lowest price sensitivity, prioritizing tamper-evident enclosures and rapid deployment packaging over unit economics.
Supply Chain Analysis
US tritium stockpile decay underwrites the dominant helium-3 production pathway, creating single-source chokepoint vulnerability for safeguards-grade fill gas. Manufacturing concentrates in the United States, France, and China, with Yangtze River Delta clusters scaling boron trifluoride detector output. Converter materials draw from lithium-6 enrichment facilities, boron-10 isotope separation plants, and helium-3 recovery operations. Tariff exposure runs through rare earth processing dependencies for scintillator dopants. Distribution runs through direct OEM relationships with reactor operators and tiered distributor networks for industrial radiography applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The neutron detector market is entering a cyclical upswing as reactor construction and decommissioning programs in France, China, and the United Kingdom synchronize procurement waves. Regulatory compliance deadlines under 10 CFR Part 50, ASN technical specifications, and NRA mandates are compressing replacement cycles.
For Market Incumbents: Compound certification advantages by accelerating boron-10 and lithium-6 converter qualifications ahead of IAEA protocol revisions. Deepen backward integration into cadmium zinc telluride crystal growth to capture margin pools migrating from gas-filled architectures. Lock in multi-year service contracts as US Customs and Border Protection unbundles hardware from calibration agreements, defending against specialist cybersecurity vendors encroaching on network management revenue. For New Entrants and Emerging Players: Differentiate on compact solid-state form factors targeting China's small modular reactor instrumentation requirements, where reduced cabling infrastructure specifications remain underpenetrated by legacy suppliers. Target radiation portal modernization programs in US homeland security as aftermarket service contracts fragment, enabling specialist positioning without competing head-to-head against Thermo Fisher Scientific's analytical instrumentation scale. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among detector OEMs with unbundled calibration and network management contracts, particularly those serving US radiation portal deployments. Long-term viability hinges on converter material diversification away from helium-3 dependencies. Acquisition focus should center on solid-state crystal growth specialists with cadmium zinc telluride capabilities and established IAEA safeguards certifications. The signal to monitor is lithium-6-doped silicon array qualification progress at France's CEA, which would accelerate technology substitution timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Converter Material Qualification Acceleration | IAEA safeguards protocol alignment enables market access for boron-10 and lithium-6 architectures. |
| Backward Integration into Crystal Growth | Cadmium zinc telluride captive supply secures margin pools migrating from gas-filled detector value chains. |
| Service Contract Unbundling | US Customs and Border Protection procurement patterns open recurring revenue streams separate from hardware sales. |
| Multi-Jurisdictional Certification Parallel Processing | Pre-qualification against 10 CFR Part 73, ASN, and NRA standards captures China SMR instrumentation demand. |
| Research Spectroscopy Customization Capability | Oak Ridge and ILL Grenoble bespoke procurement volumes anchor premium pricing in national laboratory segments. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with reactor control system engineers, nuclear safeguards inspectors, homeland security procurement officers, and detector OEM product managers. Secondary validation drew from US Nuclear Regulatory Commission 10 CFR filings, IAEA safeguards protocol documentation, French ASN technical specifications, and Japan NRA regulatory updates. Bottom-up unit economics triangulated against top-down market sizing across converter chemistry, deployment environment, and certification tier segments.
Across the analysis window, the forecasting framework modeled product type substitution dynamics, application-specific procurement cycles, technology migration timelines, and end-user specification authority fragmentation. CAGRs were derived from reactor construction and decommissioning program pipelines, regulatory compliance deadline clustering, and helium-3 stockpile depletion trajectory assessments. Converter material qualification progress and solid-state crystal growth yield improvements served as key industry-specific forecast inputs.
Material uncertainties — helium-3 supply disruption, IAEA protocol revision timing, and small modular reactor deployment acceleration — sit outside the modeled envelope. Forecasts reflect assumptions regarding converter material certification timelines and cross-jurisdictional regulatory harmonization progress. Practitioners should keep alternative scenarios live as lithium-6 enrichment capacity expansion and boron-10 isotope separation technology maturation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Detection and Regulation Devices
Global Gas Sensors Market
Detection and Regulation Devices
Pedestrian Detection System Market
Detection and Regulation Devices
Ultraviolet Currency Detector Market
Detection and Regulation Devices
Digital Attenuators Market
Detection and Regulation Devices
ESD Suppressors Market
Detection and Regulation Devices
Global a-Si X-Ray Flat Panel Detectors Market
Detection and Regulation Devices
Filter Panels Market
Detection and Regulation Devices
Hydrogen Detection Transmitters Market
Detection and Regulation Devices
Duct Smoke Detectors Market
Detection and Regulation Devices
Europe Gas Detectors Market
Detection and Regulation Devices
Voltage Detector Market
Detection and Regulation Devices
Betavoltaic Device Market
Detection and Regulation Devices
Vacuum Leak Detectors Market
Detection and Regulation Devices
Pin and Sleeve Devices Market
Detection and Regulation Devices
Global Counterfeit Money Detection Market
Detection and Regulation Devices
Underwater Signaling Devices Market