
 Pea Protein Processing Equipment Market | 2026-2036
Pea Protein Processing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Pea Protein Processing Equipment Market Insights
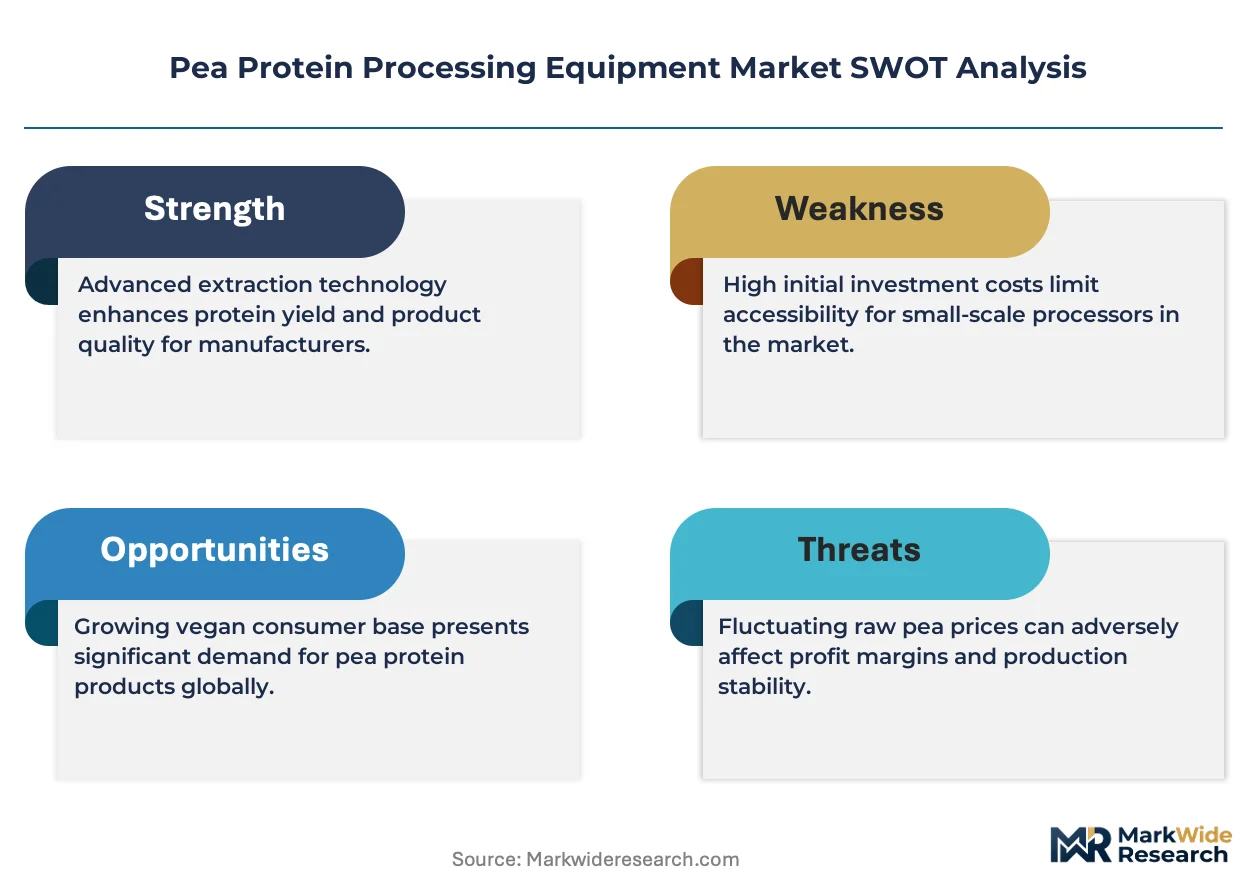
REACH is rebalancing capital allocation toward closed-loop wet fractionation systems that reduce solvent discharge liabilities. Alfa Laval AB leverages its decanter centrifuge portfolio to dominate high-capacity protein recovery lines for European isolates. Bühler AG sustains integrated extrusion-to-drying workflows that cut downstream handling costs for meat alternative manufacturers. Hosokawa Micron Corp. specializes in precision air classification systems that target the sub-20 micron protein fractions favored by nutraceutical formulators.
Pea protein processing equipment encompasses mechanical, thermal, and enzymatic systems engineered to extract, concentrate, and dry protein fractions from yellow and green pea cultivars, typically achieving isolate purities above 85 percent protein by dry weight for food-grade output. Separators and extruders anchor current revenue pools where wet fractionation capacity expansions command premium pricing from food manufacturers scaling meat alternative operations. Enzymatic processing lines represent the fastest-growing technology segment as hydrolysis protocols improve digestibility scores for nutraceutical and senior nutrition applications, while thermal processing retains margin strength in regions with lower energy costs.
The EU Green Deal and REACH compliance frameworks are mandating solvent recovery rates above 95 percent in European pea fractionation facilities, while FDA nutrition labeling rules push protein quality claims toward PDCAAS-validated isolates in the United States. EFSA novel food consultations and USDA process-verified programs add parallel compliance layers that equipment vendors must embed in control system architectures. Stakeholders should monitor regulatory divergence between enzymatic processing approvals in Europe and mechanical processing preferences in North America when configuring regional product portfolios.
Market Dynamics
Wet fractionation capacity expansions are compressing equipment procurement cycles as food manufacturers race to lock in isolate supply before EU Green Deal solvent-recovery mandates take full effect. This structural pressure favors vendors with integrated closed-loop systems over modular point solutions.
Growth Catalysts
- EU Green Deal solvent mandates:Equipment buyers in Germany and the Netherlands accelerate wet fractionation investments to preempt REACH compliance deadlines for 95 percent solvent recovery rates.
- Plant-based meat scaling:Meat alternative manufacturers in Canada expand extrusion-to-drying workflows, pulling demand for continuous processing lines that reduce downstream handling steps.
- Enzymatic hydrolysis protocols:Nutraceutical formulators drive adoption of precision-controlled hydrolysis systems to achieve digestibility scores required for senior nutrition applications.
Market Restraints
- Energy cost differentials:Thermal processing lines face margin compression in regions with elevated electricity tariffs, pushing capacity toward jurisdictions with subsidized industrial power.
- Pea cultivar supply concentration:Yellow pea procurement concentrates in the Canadian prairies and northern France, creating feedstock vulnerability for European processors dependent on cross-Atlantic shipments.
- Isolate purity ceiling:Mechanical fractionation systems hit technical limits near 85 percent protein by dry weight, forcing costly enzymatic upgrades for nutraceutical-grade output.
Strategic Opportunities
- India FSSAI plant protein recognition:Pending regulatory clarity on pulse protein isolates opens equipment deployment pathways for domestic food manufacturers seeking import substitution.
- Precision fermentation integration:Hybrid facilities combining pea protein extraction with microbial protein production create demand for flexible processing architectures.
- Direct-to-manufacturer digital channels:Equipment vendors bypass traditional distributor networks in the Netherlands through cloud-based process simulation tools that accelerate specification cycles.
Industry Challenges
- Control systems integration:Legacy SCADA architectures in North American facilities resist seamless incorporation of EFSA-mandated traceability modules, extending commissioning timelines.
- Skilled process engineering scarcity:Wet fractionation expertise concentrates among specialists trained at Wageningen University and the University of Saskatchewan, creating recruitment bottlenecks for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pea Protein Processing Equipment Market |
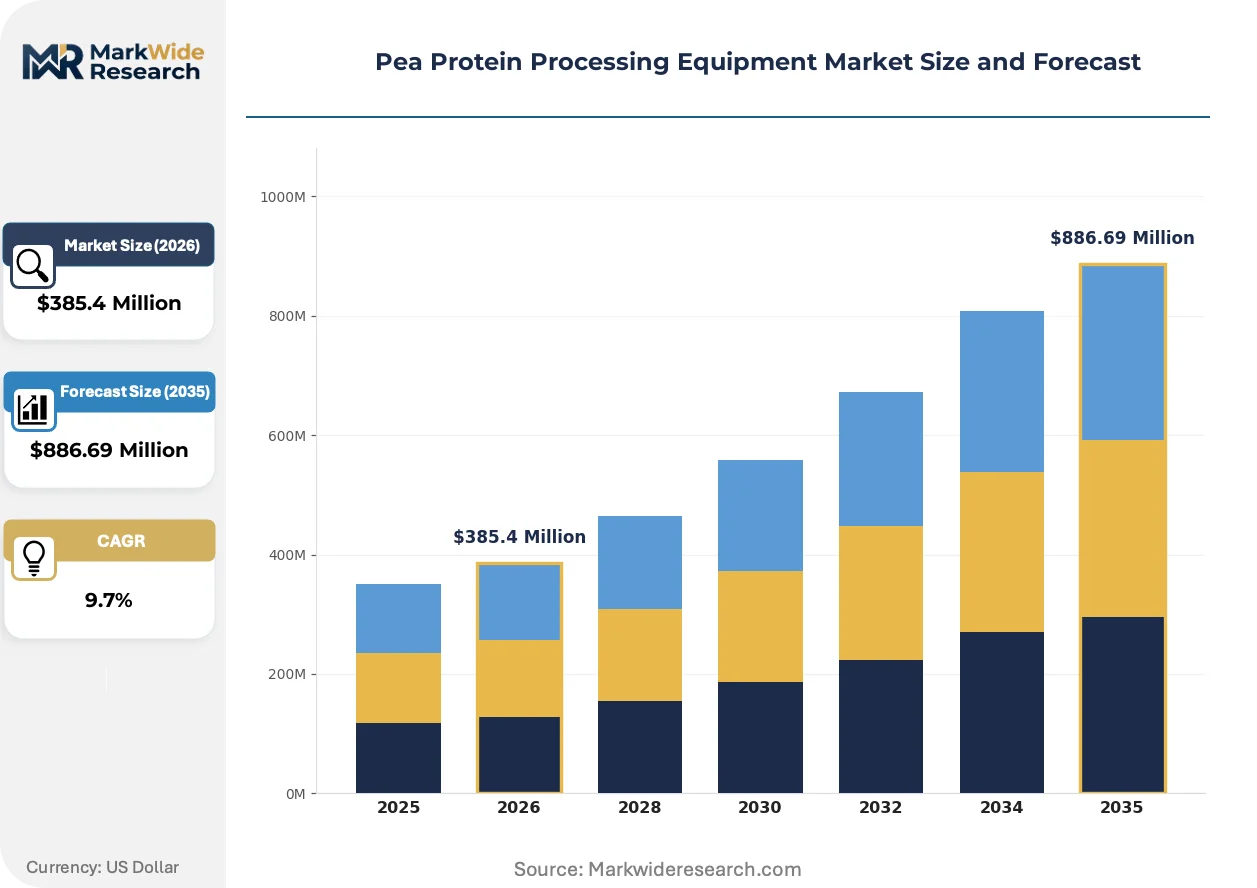
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $886.69 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Extruders, Separators, Dryers, Mixers Technology: Mechanical Processing, Chemical Processing, Thermal Processing, Enzymatic Processing End User: Food Manufacturers, Nutraceutical Companies, Animal Feed Producers, Beverage Industries Application: Meat Alternatives, Protein Enrichment, Food Formulations, Bakery Products |
| Companies Covered | Alfa Laval AB, Bühler AG, GEA Group AG, Andritz AG, Flottweg SE, Hosokawa Micron Corp., Coperion GmbH, Netzsch-Feinmahltechnik GmbH, SiccaDania, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pea Protein Processing Equipment Market Trends and Innovations
Processing architectures are pivoting from batch-oriented extraction toward continuous flow systems that compress cycle times and reduce solvent inventory. This shift demands synchronized advances in inline sensing, automated separation, and real-time quality verification.
Membrane filtration technology is converging with enzymatic hydrolysis control systems to enable simultaneous protein concentration and molecular weight fractionation in a single pass. Nutraceutical manufacturers in Germany adopt these hybrid lines to produce targeted peptide profiles for functional food applications. The convergence is compressing capital deployment timelines by eliminating redundant drying and rehydration stages previously required between discrete unit operations.
REACH authorization requirements for hexane and ethanol recovery are forcing equipment redesigns across European installations. Vendors must now engineer closed-loop solvent loops with integrated distillation and condensation stages to meet the 95 percent recovery threshold. Wet fractionation facilities in the Netherlands and Belgium face the steepest retrofit obligations, driving replacement demand for legacy open-system centrifuges.
Buyer consolidation among meat alternative manufacturers is compressing equipment specification cycles and elevating vendor qualification thresholds. Large-scale producers in Canada now demand turnkey performance guarantees spanning extraction through final drying, displacing the historical preference for best-of-breed component sourcing. This bundling pressure concentrates procurement authority with integrated solution providers capable of single-source accountability.
Pea Protein Processing Equipment Market Segmentation
Equipment specification cycles in pea protein processing diverge sharply across buyer sophistication tiers, with multinational food manufacturers demanding integrated turnkey systems while regional processors prioritize modular point solutions. Understanding these segmentation fault lines enables vendors to align R&D roadmaps with procurement authority concentration and margin capture potential.
Product Type:
Capital deployment intensity separates buyers in this category, with meat alternative manufacturers prioritizing continuous throughput over discrete batch flexibility.
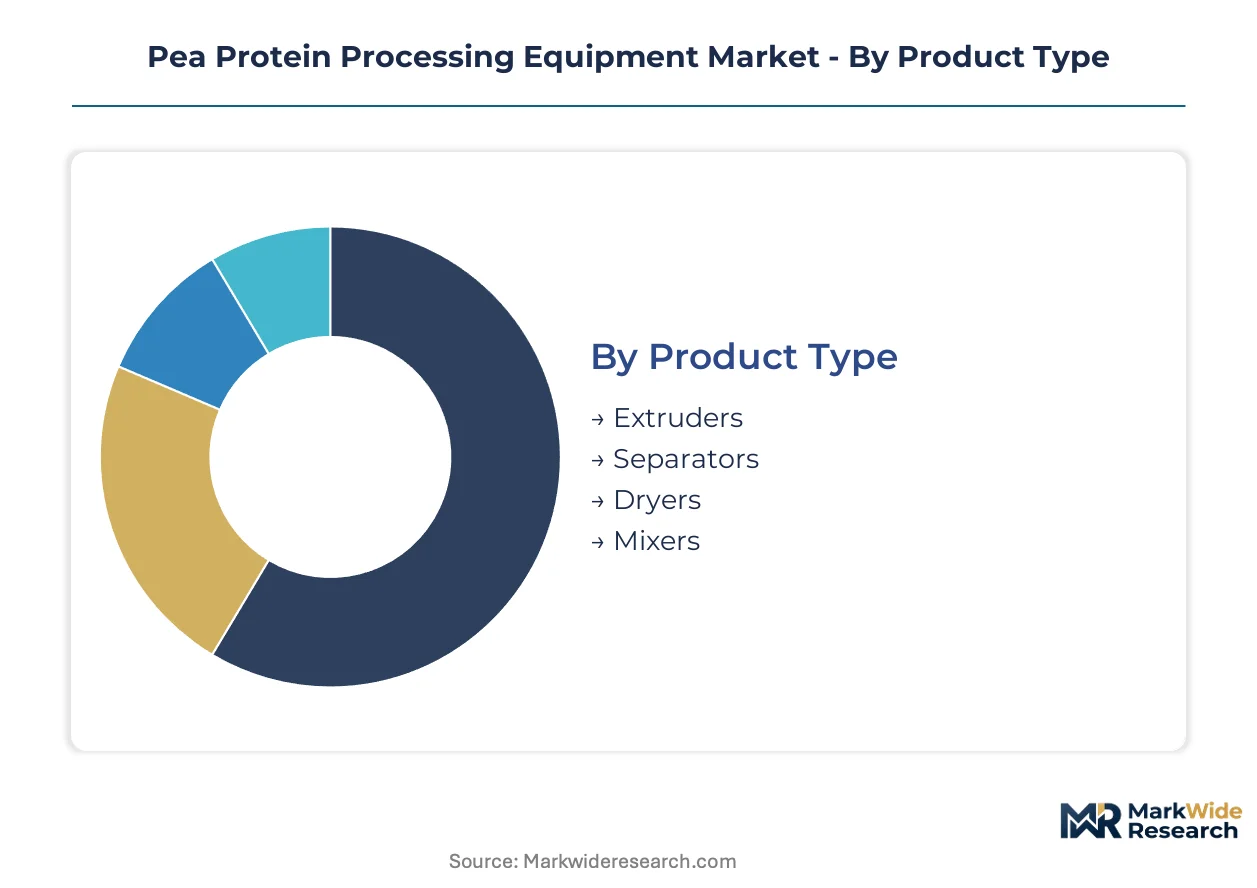
- Extruders:Twin-screw configurations dominate high-capacity lines for texturized protein production, with die design specialization determining final fiber structure in meat alternative applications. Demand concentrates in Canada where plant-based meat scaling pulls investment toward integrated extrusion-to-drying workflows that eliminate intermediate handling.
- Separators:Decanter centrifuges anchor wet fractionation capacity, achieving protein recovery rates above 90 percent from pea flour slurries through differential sedimentation. German processors lead procurement volumes as EU Green Deal solvent mandates accelerate replacement of legacy open-system units with closed-loop configurations.
- Dryers:Spray drying systems handle protein concentrate-to-isolate conversion with inlet temperatures calibrated to preserve functional properties.
- Mixers:High-shear blenders support downstream formulation integration for beverage and bakery applications.
Volume sits with Separators; growth tilts toward Extruders.
Technology:
Regulatory geography dictates technology preference, with European facilities absorbing enzymatic upgrade costs for REACH compliance while North American operators exploit mechanical processing cost advantages.
- Mechanical Processing:Wet milling and air classification systems achieve isolate purities near 85 percent protein by dry weight without solvent intervention, preserving native protein functionality for food applications. This segment retains margin strength in regions with subsidized industrial electricity where thermal drying costs remain manageable.
- Enzymatic Processing:Controlled hydrolysis protocols cleave peptide bonds to improve PDCAAS digestibility scores and enable molecular weight fractionation for nutraceutical targeting. German and Dutch facilities drive adoption as senior nutrition formulators demand validated protein quality claims.
- Chemical Processing:Alkaline extraction and isoelectric precipitation remain standard for high-volume isolate production.
- Thermal Processing:Heat treatment systems denature antinutritional factors and extend shelf stability in finished ingredients.
Mechanical Processing commands current installed base; enzymatic configurations are climbing the fastest.
End User:
Application complexity and certification requirements fragment procurement specifications across buyer categories, with nutraceutical formulators driving precision engineering premiums.
- Food Manufacturers:Meat alternative producers specify continuous processing architectures with single-source accountability spanning extraction through final drying, compressing vendor qualification cycles and elevating performance guarantee thresholds.
- Nutraceutical Companies:Peptide-targeted hydrolysis systems with inline molecular weight monitoring support functional food and senior nutrition applications requiring digestibility validation.
- Animal Feed Producers:Protein concentrate buyers prioritize throughput economics over isolate purity specifications.
- Beverage Industries:Solubility-optimized isolates demand specialized drying protocols to prevent agglomeration in liquid matrices.
Food Manufacturers anchor procurement volume; nutraceutical buyers deliver steepest expansion trajectory.
Application:
End-product positioning determines equipment configuration, with premium meat alternatives requiring texturization capabilities absent from commodity protein enrichment applications.
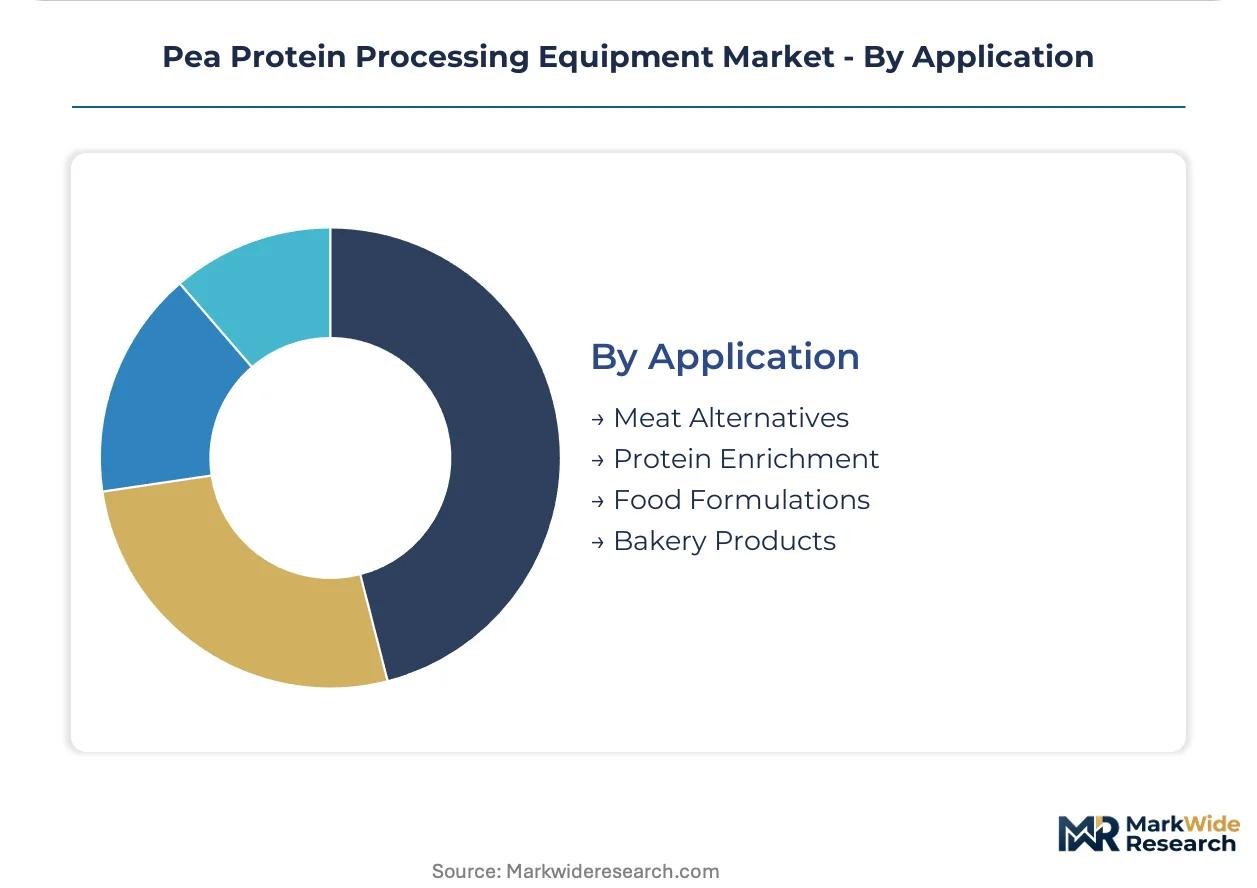
- Meat Alternatives:High-moisture extrusion systems with cooling die technology generate fibrous structures mimicking animal muscle tissue, with Canadian and Dutch facilities leading capacity installation.
- Protein Enrichment:Standard isolate production for fortification applications leverages conventional wet fractionation without specialized downstream texturization.
- Food Formulations:Emulsion stability requirements drive specification of protein fractions with specific solubility profiles.
- Bakery Products:Dough functionality demands partial denaturation control through thermal processing parameter optimization.
Meat Alternatives concentrate current investment; protein enrichment maintains steady replacement demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Saskatchewan Enterprise Innovation Incentive anchors wet fractionation capacity concentration in Canada, drawing equipment procurement toward prairie processing clusters. German industrial zones absorb REACH-mandated solvent recovery retrofits, while Dutch facilities scale enzymatic hydrolysis lines for nutraceutical peptide targeting.
Germany
Meat alternative manufacturers in North Rhine-Westphalia drive demand for integrated extrusion-to-drying workflows. ECHA REACH authorization requirements for hexane recovery above 95 percent force replacement of legacy open-system centrifuges. Cologne-Düsseldorf corridor facilities lead procurement of closed-loop wet fractionation systems ahead of compliance deadlines.
Canada
Yellow pea procurement concentration in Saskatchewan and Manitoba pulls equipment investment toward prairie processing hubs. Health Canada process-verified programs elevate vendor qualification thresholds for isolate purity claims. Saskatoon-based facilities anchor North American capacity expansion for plant-based meat ingredient supply.
Netherlands
Precision fermentation hybrid facilities in Brabant create demand for flexible processing architectures combining pea extraction with microbial protein production. EU Green Deal solvent discharge mandates accelerate wet fractionation retrofit cycles. Eindhoven region vendors deploy cloud-based process simulation tools that compress equipment specification timelines.
United States
FDA nutrition labeling updates push protein quality claims toward PDCAAS-validated isolates, favoring enzymatic upgrade investments. Midwest food manufacturers in Illinois and Iowa scale mechanical processing lines where subsidized industrial electricity preserves thermal drying margins. Chicago-area procurement offices consolidate vendor qualification authority for turnkey system contracts.
India
FSSAI pending recognition of pulse protein isolates positions domestic equipment deployment for import substitution strategies. Gujarat and Maharashtra food processors pilot wet fractionation capacity ahead of regulatory clarity. Mumbai-Pune industrial corridor facilities evaluate modular point solutions for regional protein concentrate supply.
Pea Protein Processing Equipment Market Competitive Landscape
Swiss and German producers anchor one tier; Japanese and Nordic specialists hold differentiated positions in precision subsystems. The vendor base concentrates around integrated solution providers capable of single-source accountability across extraction-to-drying workflows, displacing historical preference for best-of-breed component sourcing. Three archetypes dominate: full-line system integrators, precision separation specialists, and modular point-solution fabricators. Competitive moves center on capacity expansion for turnkey performance guarantees and technology licensing partnerships that accelerate regional market entry.
Within the full-line system integrator tier, Alfa Laval AB and Bühler AG exemplify European-based providers capable of spanning wet fractionation through final drying. Hosokawa Micron Corp. occupies a distinct position among precision subsystem specialists, representing Japanese engineering concentration in air classification technology. These three anchors illustrate the geographic split between continental European integrated providers and Asia-Pacific precision equipment developers.
| Leading Market Players |
|---|
| Alfa Laval AB |
| Bühler AG |
| GEA Group AG |
| Andritz AG |
| Flottweg SE |
| Hosokawa Micron Corp. |
| Coperion GmbH |
| Netzsch-Feinmahltechnik GmbH |
| SiccaDania |
| Others |
Pricing and Supply Chain Analysis
Continuous flow processing architectures are compressing capital deployment timelines while simultaneously concentrating procurement authority with vendors capable of integrated solvent recovery guarantees. This technological pivot elevates pricing power for closed-loop wet fractionation specialists and penalizes modular point-solution providers facing retrofit obsolescence in European jurisdictions.
Pricing Analysis
Short lead-time premiums of fifteen to twenty percent apply to closed-loop centrifuge systems as German processors accelerate procurement ahead of ECHA REACH authorization deadlines. Three-tier pricing structure across premium, standard, and economy levels separates REACH-compliant integrated lines from mechanical-only configurations and refurbished legacy units. Cost compression in standard-tier thermal drying equipment is intensifying because subsidized industrial electricity in the North American Midwest preserves margin pressure on European vendors. Regional processors in India exhibit highest price sensitivity due to pending FSSAI regulatory clarity, while multinational meat alternative manufacturers absorb premium pricing for single-source performance guarantees.
Supply Chain Analysis
Freight cost differentials between Canadian prairie yellow pea origins and European processing hubs add twelve to eighteen percent to landed input costs for Dutch and German facilities. Manufacturing concentration centers on Germany, Switzerland, and Japan for precision separation and drying equipment, while stainless steel fabrication and control system components draw from Chinese and South Korean supplier networks. Single-source vulnerability concentrates in decanter centrifuge bowl casting capabilities anchored at specialized foundries in northern Italy. Distribution runs through OEM-direct channels for turnkey systems and regional distributor networks for modular components, with cloud-based process simulation tools compressing specification cycles in the Netherlands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vendor consolidation is accelerating as REACH compliance costs and turnkey performance guarantee demands force sub-scale modular fabricators toward exit or acquisition. Buyers increasingly refuse multi-vendor integration risk, concentrating procurement authority with full-line system integrators.
For Market Incumbents: Deepen captive control over enzymatic hydrolysis control system engineering to defend against precision fermentation hybrid facilities eroding pea protein equipment demand. Add wet fractionation capacity in Saskatchewan prairie clusters to anchor proximity to Canadian yellow pea supply concentration. Invest in Wageningen University recruitment pipelines to secure scarce process engineering talent before competitor poaching intensifies.
For New Entrants and Emerging Players: Capture modular point-solution white space in Indian Gujarat and Maharashtra processing corridors ahead of FSSAI regulatory clarity on pulse protein isolates. Target beverage industry solubility-optimized drying configurations underserved by meat-alternative-focused incumbents. Deploy cloud-based specification tools to bypass entrenched distributor relationships in European markets.
For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to full-line system integrators seeking enzymatic processing capabilities or regional market access. Five-to-ten year viability favors vendors with closed-loop solvent recovery architectures validated under EU Green Deal mandates. Watch for inflection signals in India FSSAI regulatory finalization triggering domestic capacity deployment acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Solvent Recovery Systems | REACH-mandated recovery rates above ninety-five percent elevate closed-loop engineering premiums. |
| Capacity Expansion in Prairie Processing Clusters | Saskatchewan yellow pea procurement concentration pulls equipment investment toward Canadian hubs. |
| Technology Licensing for Enzymatic Hydrolysis | German nutraceutical formulators drive adoption of precision-controlled peptide targeting systems. |
| Joint Venture with Precision Fermentation Facilities | Brabant hybrid architectures create demand for flexible extraction-microbial protein processing lines. |
| Geographic Expansion via Cloud-Based Specification Tools | Eindhoven vendors compress procurement cycles by bypassing traditional distributor networks. |
Research Methodology
Trade association filings, ECHA REACH authorization databases, and customs equipment import records formed the secondary backbone for market sizing and vendor share estimation. Primary interviews with wet fractionation plant engineers, OEM procurement managers at meat alternative manufacturers, aftermarket service directors, and regulatory compliance officers at Dutch and German processing facilities validated secondary findings. Bottom-up triangulation against top-down macroeconomic drivers anchored volume and value estimates.
Bottom-up modeling segmented demand across mechanical, enzymatic, chemical, and thermal processing technologies, further disaggregated by extruder, separator, dryer, and mixer product categories. End-use splits across food manufacturers, nutraceutical companies, animal feed producers, and beverage industries informed application-level growth rates. CAGRs derived from equipment procurement cycle analysis and capacity expansion announcements across the analysis window. Energy cost differentials and regulatory compliance timelines served as key forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to India FSSAI regulatory finalization and precision fermentation technology maturation. Forecasts reflect documented assumptions regarding REACH implementation timelines and yellow pea cultivar supply stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Dough Processing System Market
Food Processing Equipment
Corn Puff Making Machine Market
Food Processing Equipment
Fish Processing Equipment Market
Food Processing Equipment
Fish Feed Pellet Making Machine Market
Food Processing Equipment
Food Ultrasound Market
Food Processing Equipment
Deep Fryer Market
Food Processing Equipment
High Speed Oven Market
Food Processing Equipment
Water Pod Soluble Machines Market
Food Processing Equipment
Freezers Market
Food Processing Equipment
Food Sorting Machines Market
Food Processing Equipment
Cider Brewing Equipment Market
Food Processing Equipment
Spray Drying Equipment Market
Food Processing Equipment
Soda Production Machine Market
Food Processing Equipment
Food Processing Equipment Market
Food Processing Equipment
Food Sterilization Equipment Market
Food Processing Equipment
Dehydrators Market