
 Global Food Sterilization Machines Market | 2026-2036
Global Food Sterilization Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Global Food Sterilization Machines Market Analysis
Remote monitoring subscriptions is realigning how food sterilization machines generate lifetime value for vendors. JBT Corporation leverages its cloud-connected retort fleet to sustain recurring revenue streams beyond hardware sales. GEA Group anchors European dairy and beverage sterilization through proprietary clean-in-place integration. ALLPAX Products LLC specializes in batch retort systems for mid-sized canneries, competing on configurability rather than scale.
Food sterilization machines are enclosed pressure vessels that apply saturated steam, superheated water, or chemical media to eliminate pathogenic microorganisms in sealed containers, typically operating at temperatures between 115°C and 140°C with F-value validation to ensure commercial sterility. Steam sterilizers dominate installed capacity across canning and aseptic filling lines, while continuous processing technology captures expanding margin pools in high-volume beverage and dairy applications where throughput economics override capital intensity. Microwave processing remains nascent but occupies a growing niche in pouch-based ready meals where rapid heating preserves sensory quality.
The FDA enforces 21 CFR Part 113 and Part 114 for low-acid and acidified foods, mandating process filing and equipment calibration that directly shapes sterilizer design and validation service demand. EFSA and national EU regulators under the EU Hygiene Package (EC 852/2004) impose HACCP-aligned equipment standards that filter market access for non-CE-compliant machinery. China's NMPA and GB standards for food contact materials add parallel certification layers for imported retort systems. Stakeholders must weigh regulatory divergence against platform standardization when configuring regional product portfolios and service architectures.
Market Dynamics
Remote monitoring subscriptions are consolidating vendor revenue models away from one-time equipment sales toward recurring service architectures. Thermal processing validation requirements under FDA 21 CFR Part 113 are forcing capital deployment toward digitally integrated retort systems with automated F-value logging.
Growth Catalysts
- Ready-to-eat food manufacturers:Extended shelf stability demands are pulling batch retort capacity into pouch-based meal production lines.
- China's GB standards for food contact materials:Domestic certification requirements are accelerating localized production of automated sterilization equipment.
- Low-acid canned food regulations:FDA process filing mandates are expanding the addressable market for validation services attached to thermal processing equipment.
Market Restraints
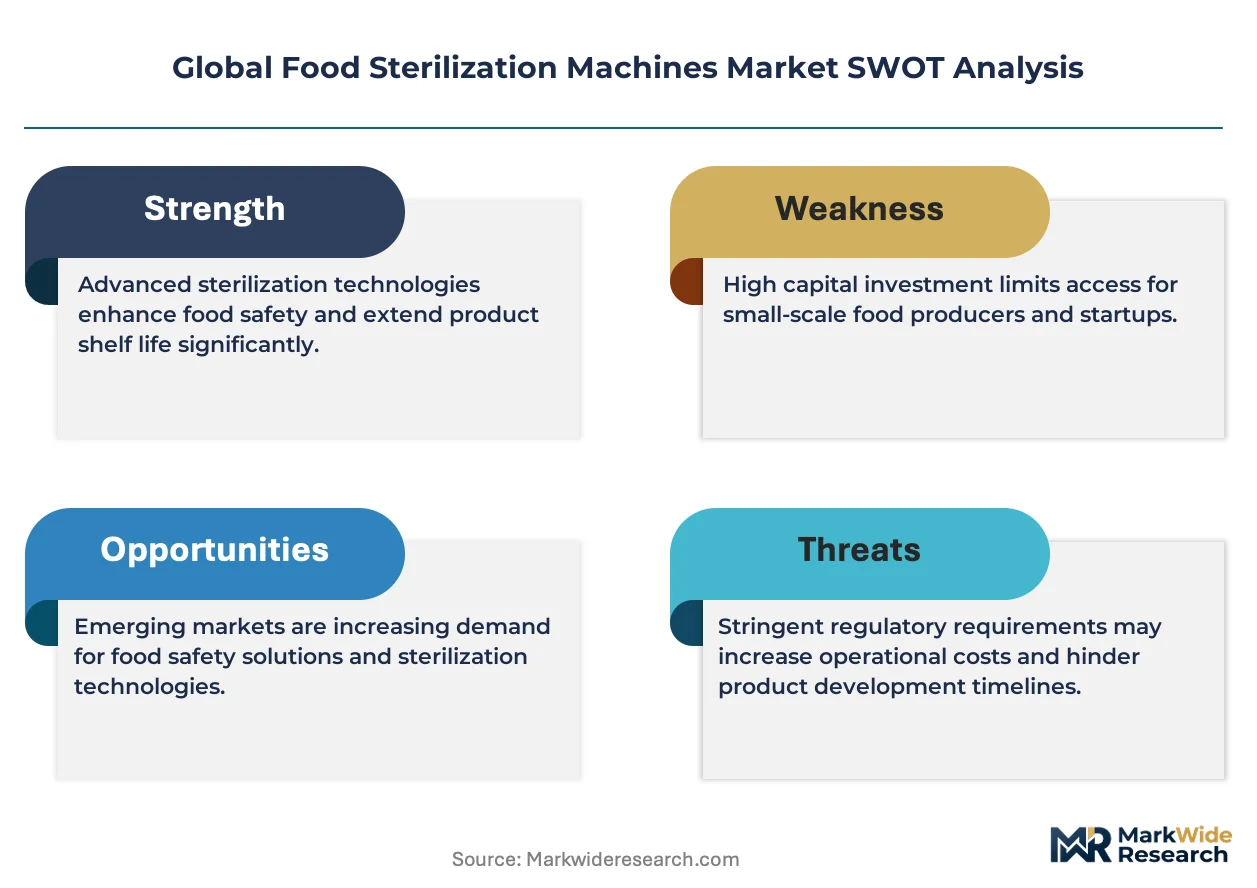
- Stainless steel input volatility:Pressure vessel fabrication costs fluctuate with nickel and chromium price swings, compressing OEM margins on fixed-price contracts.
- Steam sterilizer supply concentration:European and Japanese incumbents dominate high-pressure vessel certification, limiting new entrant access to CE-marked component supply.
- High-throughput continuous systems:Capital intensity above batch alternatives restricts adoption to beverage and dairy processors with volume certainty.
Strategic Opportunities
- Microwave-assisted thermal sterilization:Convergence of 915 MHz magnetron arrays with conventional steam retorts opens shelf-stable pouch applications without sensory degradation.
- India's FSSAI modernization:Centralized food safety infrastructure investment is creating first-mover advantage for automated retort vendors in nascent canning clusters.
- Cloud-connected validation platforms:Equipment-as-a-service models are penetrating mid-sized canneries previously priced out of enterprise-tier digital infrastructure.
Industry Challenges
- Process authority talent scarcity:Qualified thermal processing specialists capable of filing scheduled processes with FDA are concentrated among retiring industry veterans.
- Legacy control system integration:Retrofitting digital monitoring onto 1990s-era retort installations requires custom PLC bridging that extends commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Food Sterilization Machines Market |
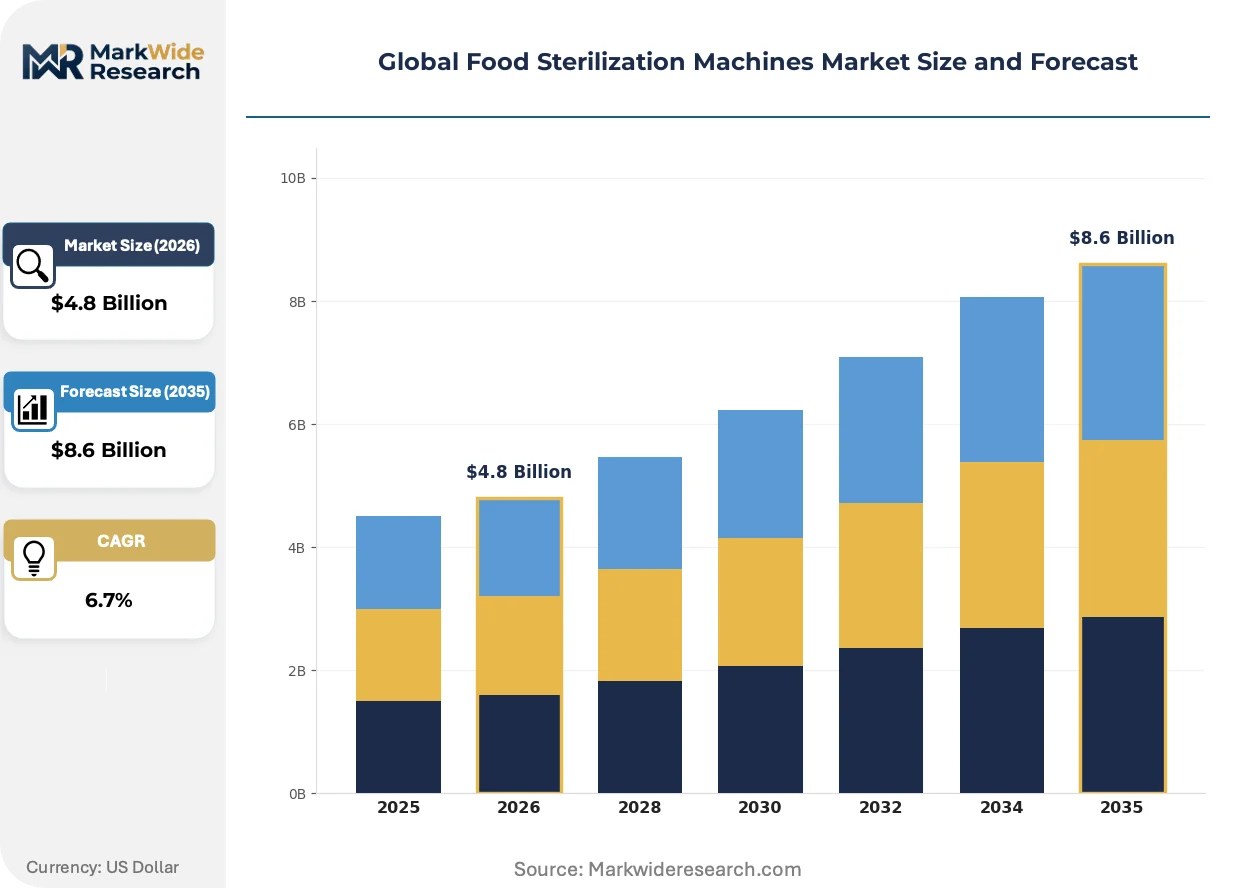
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steam Sterilizers, Chemical Sterilizers, Dry Heat Sterilizers, Radiation Sterilizers Technology: Batch Processing, Continuous Processing, Microwave Processing, Indirect Heating End User: Food Manufacturers, Restaurants, Catering Services, Retail Chains Packaging Type: Flexible Packaging, Rigid Packaging, Vacuum Packaging, Others |
| Companies Covered | JBT Corporation, ALLPAX Products LLC, Cosmed Group, DE LAMA S.p.A, Surdry S.L., Ventilex B.V., Steriflow, Bühler Group, GEA Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Food Sterilization Machines Market Emerging Trajectories
Equipment intelligence and energy recovery systems are compressing operating cost structures while regulatory digitization mandates reshape validation workflows. These forces are converging to favor vendors with integrated software-hardware platforms over pure hardware suppliers.
Continuous flow sterilization using scraped-surface heat exchangers is consolidating market share in high-volume dairy and beverage applications. Major processors in Western Europe and North America are replacing batch retort farms with single-line continuous systems capable of 20,000+ liters per hour throughput. This technology is consolidating margin pools around throughput economics rather than capital efficiency, favoring scale-specialized OEMs with dedicated clean-in-place integration.
EFSA's evolving guidance on novel processing technologies is tightening equivalence demonstration requirements for non-thermal and advanced thermal methods. Equipment vendors must now generate microbial inactivation data packages comparable to conventional thermal references before commercial deployment. Aseptic filling lines and extended-shelf-life dairy operations face the steepest compliance burdens, driving consolidation of validation capabilities among full-service engineering firms.
Buyer procurement patterns are compressing equipment specification cycles as ready-to-eat brands accelerate product development timelines. Traditional 18-month sterilizer procurement processes are collapsing to 6-9 months through pre-engineered modular retort configurations. This behavioral shift is most visible in China's Yangtze River Delta food manufacturing clusters, where domestic brands demand rapid line commissioning to capture seasonal consumption windows.
Global Food Sterilization Machines Market Segmentation
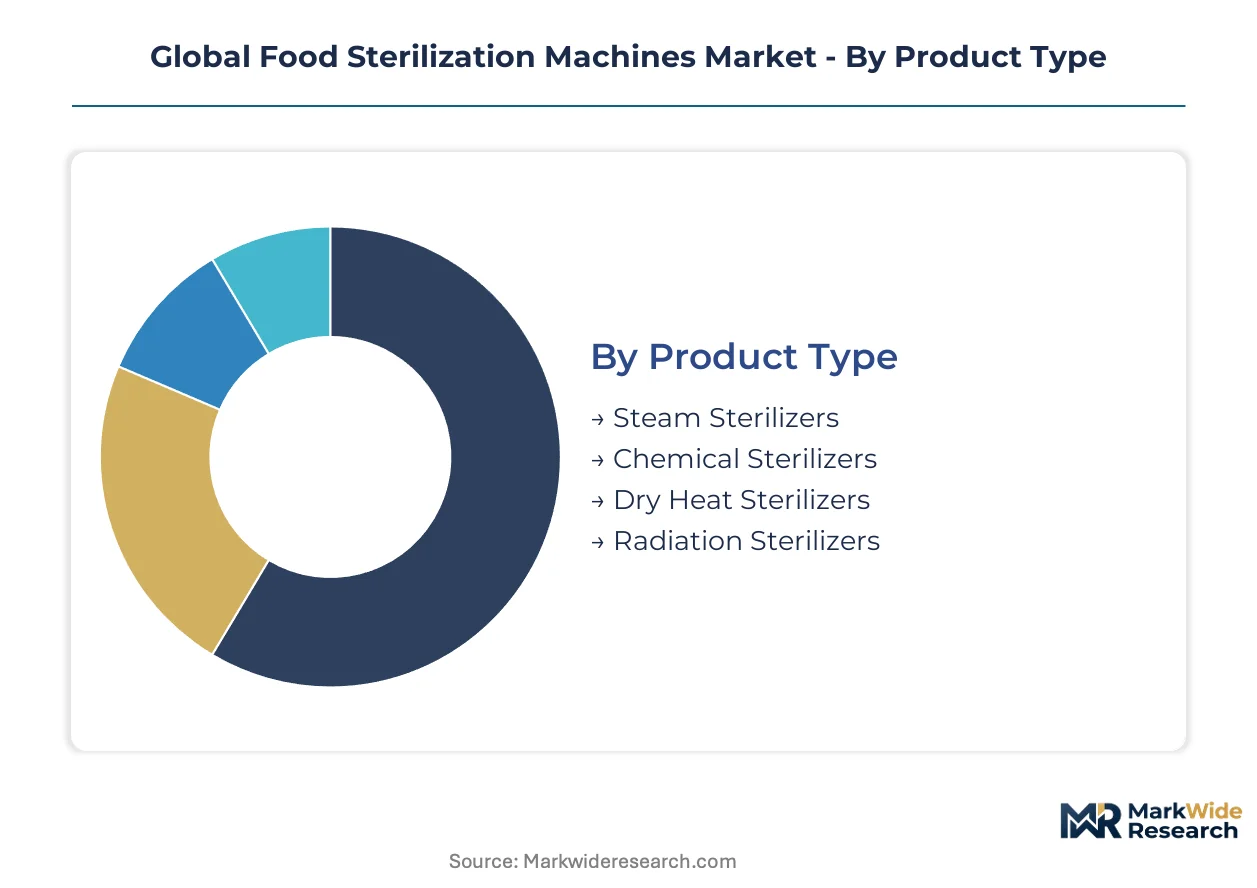
Food sterilization machine buyers navigate a complex trade-off between standardized equipment platforms and application-specific configurations. Procurement patterns diverge sharply across end-use verticals, with high-volume processors prioritizing throughput economics while specialty food brands demand modular retort systems for rapid product changeovers.
Product Type:
Customization intensity varies from fully standardized pressure vessel designs to highly engineered chemical delivery systems requiring site-specific integration.
- Steam Sterilizers:Saturated steam retorts dominate installed base across canning operations, operating at 115-140°C with automated F-value validation. Demand concentrates in China's Yangtze River Delta as domestic food brands scale automated lines for middle-class consumption expansion.
- Chemical Sterilizers:Ethylene oxide and peracetic acid systems serve temperature-sensitive packaging formats where thermal degradation risks product integrity. European aseptic dairy processors under EFSA's EU Hygiene Package drive specification for clean-in-place integrated chemical sterilization loops.
- Dry Heat Sterilizers:Hot air ovens address moisture-restricted applications in dehydrated food and spice processing with extended cycle times.
- Radiation Sterilizers:Gamma and electron beam systems occupy niche pharmaceutical-food crossover applications requiring cold sterilization.
Leading the category by volume: Steam Sterilizers. Expanding most quickly: Chemical Sterilizers.
Technology:
Capital deployment thresholds separate batch-based entry points from continuous systems demanding volume certainty.
- Batch Processing:Static retort configurations serve mid-sized canneries with production flexibility across SKU portfolios. ALLPAX Products LLC anchors this tier through configurable vessel designs competing on adaptability rather than scale.
- Continuous Processing:Scraped-surface heat exchangers and hydrostatic sterilizers deliver 20,000+ liters per hour throughput for beverage and dairy applications. Western European majors are consolidating batch retort farms into single-line continuous systems where throughput economics override capital intensity.
- Microwave Processing:915 MHz magnetron arrays converge with conventional steam for rapid pouch-based ready meal sterilization without sensory degradation.
- Indirect Heating:Plate and tubular heat exchangers serve acidified foods and high-viscosity products where direct steam contact risks dilution.
Batch Processing retains dominant installed share. Microwave Processing gains share fastest in ready-to-eat applications.
End User:
Facility scale and regulatory exposure determine whether buyers prioritize validation services or capital efficiency.
- Food Manufacturers:Integrated processors under FDA 21 CFR Part 113 and China's NMPA GB standards drive demand for digitally integrated retort systems with automated process filing capabilities.
- Restaurants:Central kitchen operations and ghost kitchen chains adopt compact batch sterilizers for extended shelf-life sauce and prepared component production.
- Catering Services:Institutional foodservice operators specify mobile retort units for field-based meal production in remote mining and military contracts.
- Retail Chains:Private-label ready meal programs pull sterilization capacity in-house as grocers verticalize prepared food manufacturing.
Food Manufacturers command the largest equipment procurement volume. Retail Chains represent the steepest expansion trajectory as private-label verticalization accelerates.
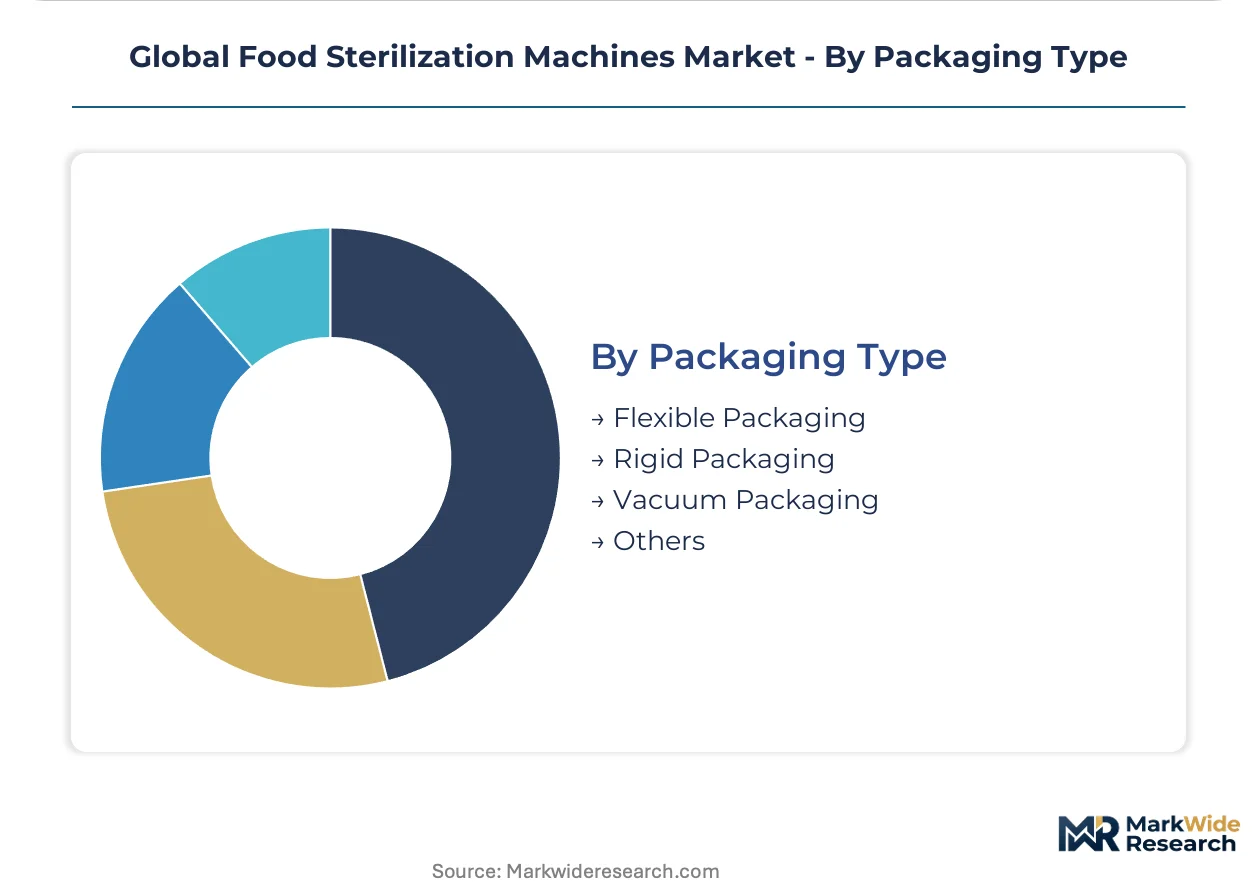
Packaging Type:
Material thermal tolerance constraints dictate sterilization medium selection and cycle parameter windows.
- Flexible Packaging:Retort pouches and laminated films enable rapid heat penetration for ready meals, driving microwave-assisted thermal sterilization adoption where rapid heating preserves sensory quality.
- Rigid Packaging:Metal cans and glass jars retain dominance in low-acid shelf-stable foods, anchoring steam sterilizer demand across traditional canning clusters.
- Vacuum Packaging:Modified atmosphere formats extend chilled shelf life but require specialized pressure control during thermal processing.
- Others:Aseptic cartons and composite containers serve high-acid beverages and dairy with distinct validation requirements under FDA Part 114.
Rigid Packaging leads by historical installed base. Flexible Packaging climbs fastest as pouch-based ready meals displace canned alternatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the majority of installed food sterilization capacity while the United States and Western Europe consume the most validation-intensive processing equipment. Production clusters concentrate in industrial zones with stainless steel fabrication heritage and pressure vessel certification infrastructure.
United States
Low-acid canned food processors under FDA 21 CFR Part 113 drive demand for digitally integrated retort systems with automated F-value logging. The FDA's updated thermal processing validation requirements are forcing capital deployment toward equipment with embedded compliance documentation. Chicago and central California canning clusters anchor domestic demand for batch retort capacity serving private-label ready meal programs.
China
Domestic food brands scaling automated retort lines pull capacity expansion in the Yangtze River Delta manufacturing corridor. NMPA GB standards for food contact materials and sterilization equipment certification are accelerating localized production over imported systems. Shanghai and Jiangsu province industrial zones concentrate domestic OEM fabrication serving middle-class consumption growth in shelf-stable prepared foods.
Germany
Dairy and beverage processors under EFSA's EU Hygiene Package specifications anchor European demand for continuous flow sterilization with clean-in-place integration. CE-marked pressure vessel certification requirements filter market access for non-European machinery suppliers. Bavarian and North Rhine-Westphalia food technology clusters house engineering firms specializing in scraped-surface heat exchanger systems for high-volume applications.
India
FSSAI modernization and centralized food safety infrastructure investment are creating first-mover opportunity for automated retort vendors in nascent canning clusters. The country's national food regulator is tightening equipment standards for commercial sterilization operations. Maharashtra and Gujarat industrial corridors concentrate emerging demand as domestic food brands verticalize processing capacity for extended shelf-life products.
Japan
Ready-to-eat pouch meal manufacturers pull microwave-assisted thermal sterilization adoption where rapid heating preserves sensory quality. METI industrial standards and JIS certification requirements shape equipment procurement specifications for domestic processors. Kansai and Chubu regional manufacturing bases concentrate precision retort fabrication serving premium convenience food export markets.
Global Food Sterilization Machines Market Vendor Landscape
Top-tier vendors anchor the premium continuous processing segment, while mid-tier specialists compete on batch retort configurability for regional canneries. European and Japanese incumbents dominate high-pressure vessel certification, limiting new entrant access to CE-marked component supply. Three archetypes define competitive positioning: scale-driven continuous system OEMs, modular batch retort specialists, and validation-integrated platform vendors. M&A activity concentrates on digital monitoring capabilities, while geographic expansion targets India's emerging canning infrastructure.
Within the premium-tier vector, GEA Group and JBT Corporation exemplify full-service engineering firms with integrated software-hardware platforms. ALLPAX Products LLC occupies a position among North American batch retort specialists competing on adaptability rather than throughput scale. These three anchors represent distinct strategic postures: European clean-in-place integration dominance, cloud-connected validation platform expansion, and mid-sized cannery configurability focus.
| Leading Market Players |
|---|
| JBT Corporation |
| ALLPAX Products LLC |
| Cosmed Group |
| DE LAMA S.p.A |
| Surdry S.L. |
| Ventilex B.V. |
| Steriflow |
| Bühler Group |
| GEA Group |
| Others |
Supply Flow & Price Mechanics
Nickel and chromium price swings cascade from stainless steel mills through pressure vessel fabrication costs, compressing OEM margins on fixed-price contracts and forcing tiered pricing stratification across premium CE-certified systems, standard regional equipment, and economy-grade batch retorts for emerging markets.
Pricing Analysis
Margin tightening in mid-tier batch retorts reflects stainless steel input volatility and concentrated European-Japanese certification control over high-pressure vessel supply. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated continuous systems with cloud logging from basic steam retorts and unbundled validation services. Pricing pressure accelerates in standard-tier equipment as Chinese domestic OEMs scale localized production under NMPA GB standards. Small-scale canneries exhibit highest price sensitivity, while multinational dairy processors under EFSA compliance show lowest elasticity due to throughput economics.
Supply Chain Analysis
Freight cost escalation from Shanghai and Rotterdam ports amplifies landed cost differentials between Chinese domestic OEMs and European-Japanese incumbents serving Southeast Asian and Latin American markets. Component fabrication concentrates in China, Germany, and Japan, drawing from nickel ore processing in Indonesia and chromium refining in South Africa. Single-source vulnerability pervades CE-marked pressure vessel certification controlled by European notified bodies. Distribution runs through regional engineering firms providing installation and validation services rather than direct OEM sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pressure vessel certification scarcity props pricing power for incumbent OEMs, constraining supply expansion and sustaining margin structures despite Chinese manufacturing scale.
For Market Incumbents: Lock in certification moats by deepening backward integration into stainless steel fabrication and expanding validation service subscriptions. Threat from microwave-assisted thermal sterilization substitutes demands R&D investment in hybrid steam-magnetron platforms. Priority lever rests on cloud-connected fleet management to capture recurring revenue from installed base.
For New Entrants and Emerging Players: Enter via India's FSSAI modernization wave in Maharashtra and Gujarat canning clusters where automated retort penetration remains nascent. Most penetrable segment comprises mid-sized pouch-based ready meal manufacturers seeking configurability over throughput scale. Go-to-market angle emphasizes rapid commissioning cycles through pre-engineered modular configurations.
For Investors and Strategic Acquirers: Distressed-cycle entries favor validation-integrated platform vendors in Western Europe where EFSA equivalence demonstration requirements consolidate service demand. Long-term viability hinges on software-hardware convergence over pure equipment manufacturing. Acquisition target archetype includes digital monitoring specialists with FDA filing capabilities. Signal to watch is FSSAI equipment standard enforcement timeline in Indian canning infrastructure.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Connected Validation Platform | JBT Corporation's subscription model captures recurring revenue beyond hardware sales. |
| Backward Integration into Pressure Vessel Fabrication | GEA Group secures CE-marked component supply against stainless steel price volatility. |
| Microwave-Assisted Thermal Sterilization R&D | 915 MHz magnetron convergence opens shelf-stable pouch applications without sensory degradation. |
| Localized Production under NMPA GB Standards | Domestic Chinese OEMs bypass import certification layers serving Yangtze River Delta clusters. |
| Validation Service Expansion | ALLPAX Products LLC attaches process filing capabilities to batch retort sales for mid-sized canneries. |
Methodological Framework
Document review covered FDA 21 CFR Part 113 filings, EFSA guidance documents, NMPA GB standards, and EU pressure equipment directives, complemented by interviews with thermal processing specialists, retort OEM procurement teams, plant engineers at ready-to-eat manufacturers, and aftermarket service heads. Secondary validation drew from customs trade data, stainless steel price indices, and equipment certification registries. Bottom-up installed base estimates triangulated against top-down market sizing across technology and end-use segments.
Segment-level outputs across the projection horizon reflect modeled deployment of batch versus continuous systems, steam versus chemical sterilization media, and validation service attachment rates. CAGRs were derived from elasticity-adjusted demand curves incorporating regulatory filing volume trends and regional capacity expansion announcements. Industry-specific inputs included F-value validation automation adoption curves and microwave processing technology maturation timelines.
Revisions become necessary when FDA process filing mandates accelerate, China's NMPA enforcement tightens import barriers, or stainless steel price volatility exceeds historical bands. Forecasts reflect documented assumptions about regulatory digitization pace and certification body capacity constraints. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Dry Ice Market
Food Processing Equipment
Bread Slicer Market
Food Processing Equipment
Global Food Deaerators Market
Food Processing Equipment
Cook Processor Market
Food Processing Equipment
Spiral Cooler Market
Food Processing Equipment
Smart Bread Maker Market
Food Processing Equipment
Magnetic Grill Market
Food Processing Equipment
Aseptic Processing Equipment Market
Food Processing Equipment
Industrial Graters Market
Food Processing Equipment
Flake Ice Machines Market
Food Processing Equipment
High Speed Oven Market
Food Processing Equipment
Milk Sterilizer Machine Market
Food Processing Equipment
Batter Mixer Machines Market
Food Processing Equipment
Salmon Fish Scaling Machine Market
Food Processing Equipment
Shrimp Peeling Machine Market
Food Processing Equipment
Hand Blender Market