
 Global Powder Processing Equipment Market | 2026-2036
Global Powder Processing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Powder Processing Equipment Market Intelligence
Contract pharmaceutical manufacturers are redrawing procurement priorities for powder processing equipment as specialty chemical producers scale back capital commitments. Hosokawa Micron Corporation dominates precision jet milling systems for inhalable drug formulations. Buhler Group extends its installed base across food-grade grinding lines with integrated hygienic design. GEA Group anchors European demand through pharmaceutical freeze-drying and containment solutions.
Powder processing equipment encompasses mechanical systems that reduce, classify, dry, or blend particulate solids to controlled particle size distributions, typically operating at throughput rates from kilograms to multiple tons per hour and achieving fineness levels below ten microns for specialized applications. Ball mills retain the largest installed base across mining and construction material operations due to their tolerance for abrasive feedstocks and lower capital intensity. Jet mills capture premium margin pools in pharmaceutical and cosmetic applications where contamination-free processing and narrow particle size distribution justify higher equipment costs. Wet grinding technology leads chemical manufacturing installations where solvent-based systems prevent dust explosion hazards and enable finer end-product specifications.
FDA process validation guidelines and EMA GMP Annex 15 requirements compel pharmaceutical buyers to demand documented equipment qualification protocols and material traceability from suppliers. EPA air emission standards and OSHA combustible dust regulations in the United States restrict dryer and mill configurations, pushing end users toward closed-system designs with integrated dust collection. Stakeholders must weigh regional regulatory divergence against platform standardization strategies when configuring global equipment portfolios.
Market Dynamics
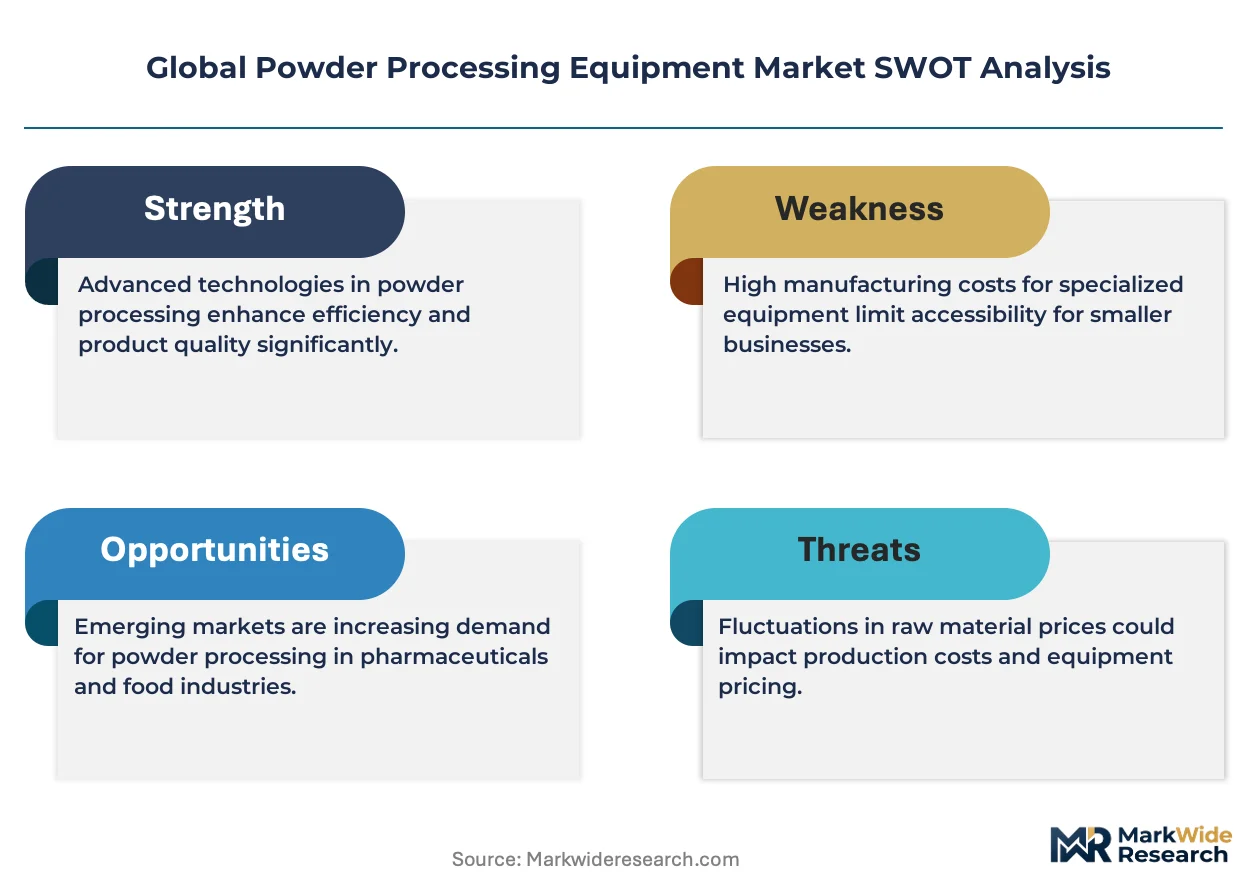
Pharmaceutical contract manufacturers are consolidating procurement around qualified equipment platforms as REACH and FDA validation requirements harden qualification protocols into binding commercial terms.
Growth Catalysts
- Active ingredient micronization:Inhalable drug formulators demand sub-ten-micron particle distributions, pulling precision jet milling capacity into dedicated production lines.
- REACH compliance deadlines:European chemical processors must retrofit containment systems, creating replacement demand for closed-loop drying and grinding equipment.
- India's pharmaceutical expansion:Domestic API manufacturers are installing integrated grinding-classification systems to reduce import dependence on processed intermediates.
Market Restraints
- Stainless steel price volatility:Pharmaceutical-grade 316L and specialty alloys constitute forty to sixty percent of equipment bill-of-materials, compressing margins when commodity markets spike.
- Precision component supplier concentration:High-speed classifier wheels and ceramic grinding media rely on German and Japanese specialty manufacturers, exposing lead time risk.
- Wet grinding solvent recovery costs:EPA air emission standards and OSHA combustible dust rules push chemical processors toward solvent-based systems with capital-intensive recovery infrastructure.
Strategic Opportunities
- Brazil's pharmaceutical localization:ANVISA import substitution policies incentivize domestic powder processing capacity for generic API production.
- Battery material processing:Cathode precursor manufacturers require controlled atmosphere milling for lithium nickel manganese cobalt oxides, opening non-pharmaceutical revenue pools.
- Continuous manufacturing adoption:FDA Quality by Design frameworks reward integrated powder-to-tablet lines with abbreviated approval pathways.
Industry Challenges
- Equipment qualification specialist scarcity:Pharmaceutical buyers require suppliers to deliver documented IQ/OQ/PQ protocols, but qualified validation engineers remain concentrated among incumbent vendors.
- Legacy control system integration:Brownfield chemical plants operate decades-old distributed control architectures that resist seamless connection to modern powder processing telemetry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Powder Processing Equipment Market |
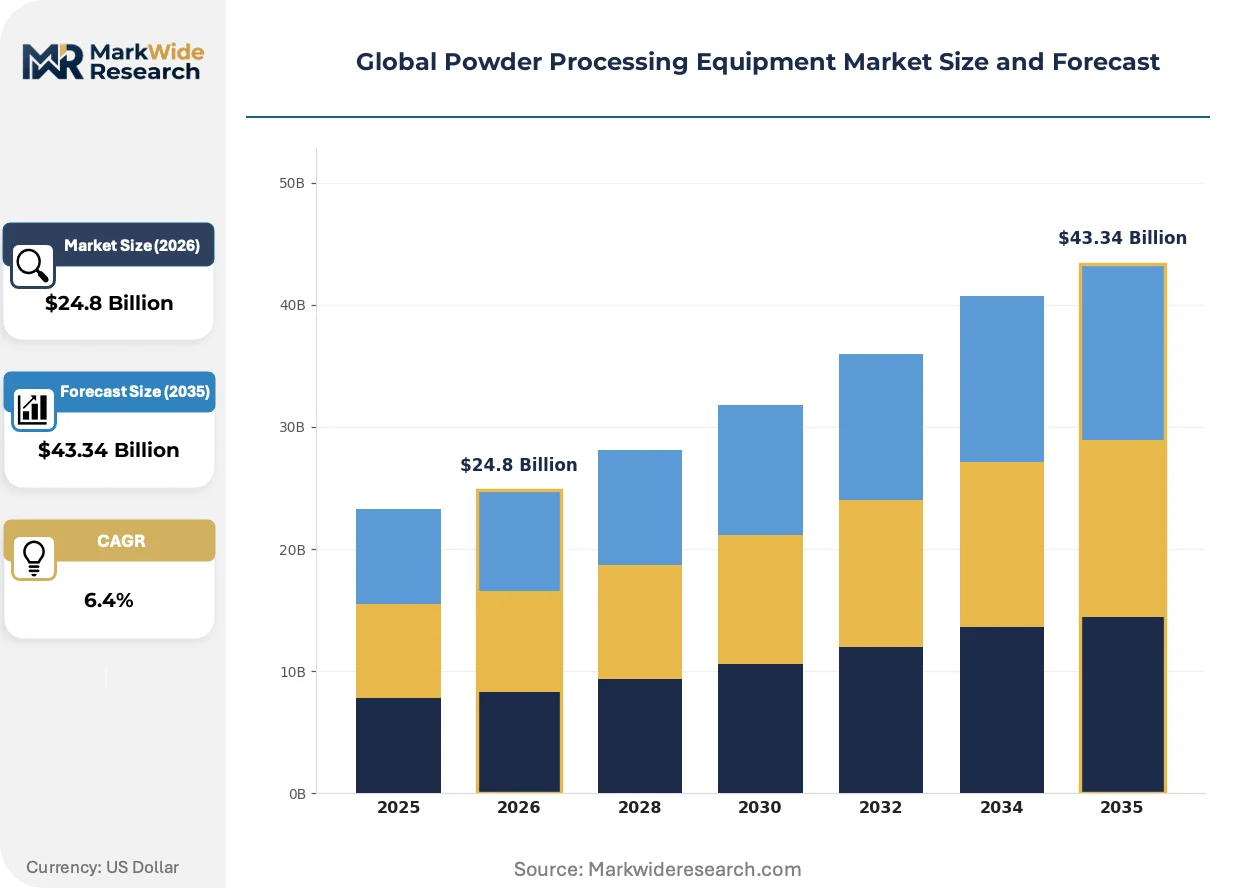
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $43.34 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
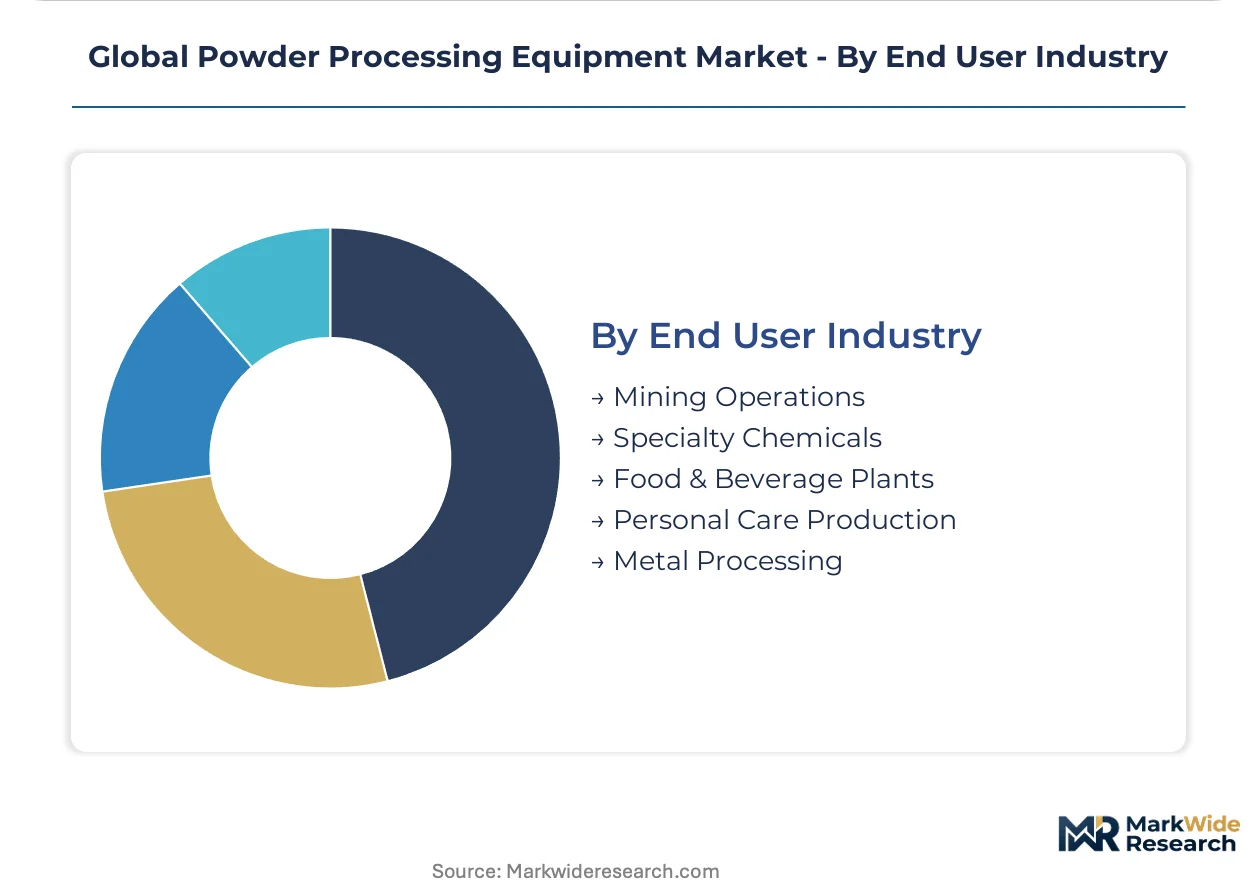
| Segmentation | Product Type: Ball Mills, Jet Mills, Hammer Mills, Fluidized Bed Dryers, Pin Mills Technology: Wet Grinding, Dry Grinding, Cryogenic Grinding, Air Classification, Vibratory Processing Application: Pharmaceuticals, Food Processing, Chemical Manufacturing, Construction Materials, Cosmetics End User Industry: Mining Operations, Specialty Chemicals, Food & Beverage Plants, Personal Care Production, Metal Processing |
| Companies Covered | Bepex International LLC, Charles Ross & Son Company, Hosokawa Micron Corporation, Baker Perkins Limited, Hänsel Processing GmbH, Syntegon Technology GmbH, Dongsun Powder Processing Equipment Co. Ltd, Buhler Group, GEA Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Powder Processing Equipment Market Strategic Shifts & Innovations
Equipment architecture is pivoting from batch-centric mechanical systems toward continuous processing platforms with embedded process analytical technology, compressing validation timelines and enabling real-time release.
Electromagnetic grinding mills with variable frequency drives are supplanting fixed-speed mechanical mills in pharmaceutical applications. Contract manufacturers operating multi-product suites adopt these systems to reduce changeover cleaning validation burden. The technology is compressing equipment footprint requirements while expanding the range of APIs that can be processed without cross-contamination risk.
EMA GMP Annex 15 revisions now mandate continuous process verification for sterile powder operations, compelling equipment suppliers to embed PAT sensors as standard rather than optional configurations. European pharmaceutical manufacturers are retrofitting existing lines with Raman spectroscopy and particle size analyzers. This regulatory pressure is accelerating supplier consolidation around platforms with native data integrity architecture.
After-sales service unbundling is fragmenting the traditional equipment procurement model. Large pharmaceutical buyers now separate hardware acquisition from validation support, maintenance contracts, and spare parts provisioning, negotiating each element with specialized providers. This behavior is most pronounced in North American and Western European markets where procurement functions have matured category-management capabilities.
Global Powder Processing Equipment Market Segmentation
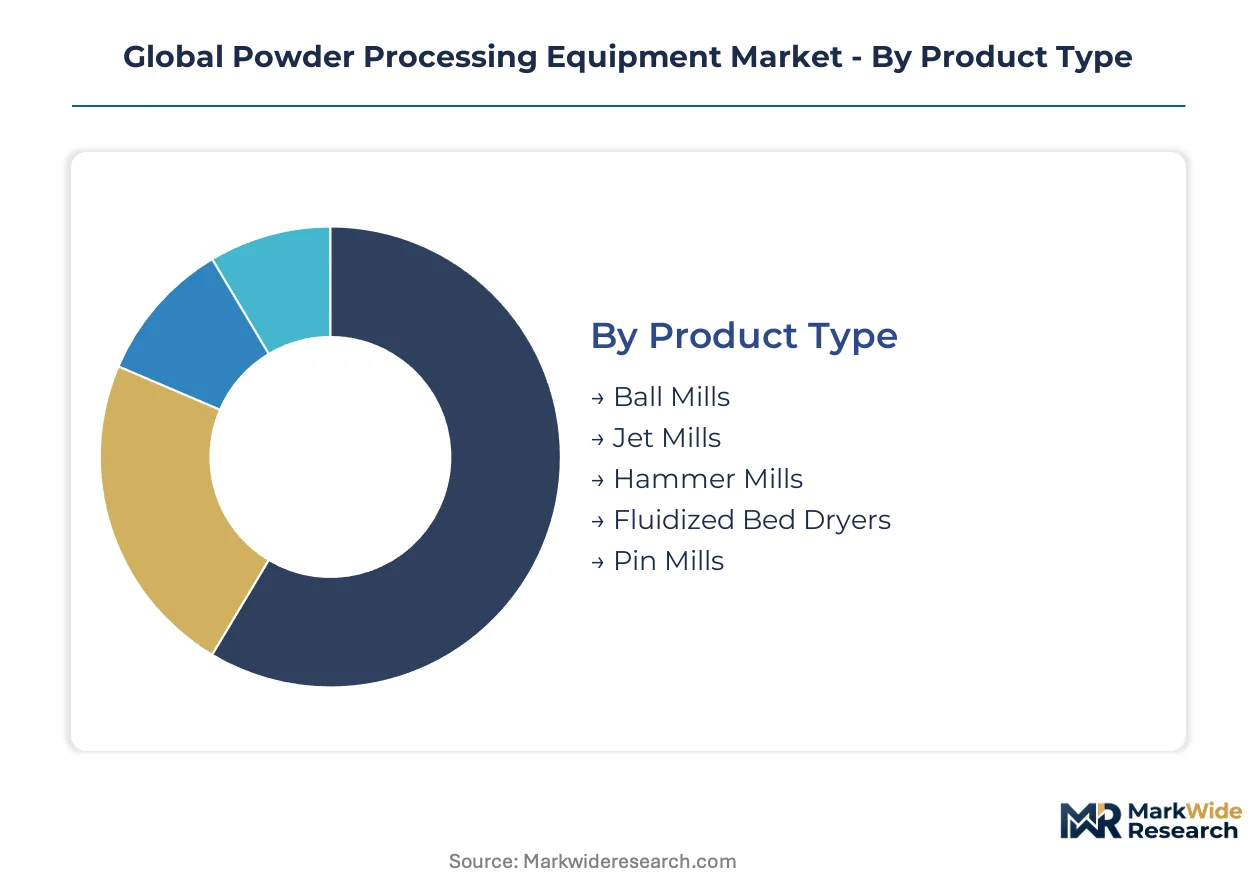
Powder processing equipment procurement varies sharply by operational scale and regulatory exposure. Segment boundaries increasingly blur as pharmaceutical-grade specifications migrate into food and cosmetic applications.
Product Type:
Domestic installations dominate ball mill and hammer mill demand across mining and construction sectors, while jet mills and fluidized bed dryers flow heavily through export channels serving pharmaceutical and specialty chemical markets in Germany, Switzerland, and Japan.
- Ball Mills:Abrasion-resistant steel or ceramic-lined rotating cylinders grind mineral feedstocks through cascading media action. Mining operations in Australia and Brazil absorb the bulk of new capacity for iron ore and cement clinker processing, though capital intensity limits replacement frequency.
- Jet Mills:Compressed gas streams accelerate particles into collision zones, achieving sub-five-micron distributions without mechanical contamination. Inhalable drug manufacturers in Switzerland and the United States deploy these systems in dedicated containment suites to satisfy FDA and Swissmedic validation protocols.
- Hammer Mills:High-speed rotating hammers shatter friable materials through impact fracture. Domestic grain processing and construction aggregate operations in India and China represent the core installed base.
- Fluidized Bed Dryers:Hot air suspends particulate solids in turbulent beds for uniform moisture removal. European chemical processors retrofit these with closed-loop solvent recovery to meet REACH emission thresholds.
- Pin Mills:Counter-rotating pin discs generate shear forces for fine grinding of heat-sensitive materials. Cosmetic pigment producers in France and Italy favor these for controlled temperature rise.
Ball mills command the established base. The steepest expansion runs through jet mills.
Technology:
Cost tier separation drives technology selection, with wet grinding systems commanding premium capital outlays for solvent infrastructure while dry grinding dominates volume applications with simpler footprint requirements.
- Wet Grinding:Slurry-based processing eliminates dust explosion hazards and enables sub-micron particle sizes through extended residence times. Battery cathode precursor manufacturers in South Korea and Japan specify wet attritor mills for lithium nickel manganese cobalt oxide production.
- Dry Grinding:Mechanical mills reduce moisture-free feedstocks without solvent handling infrastructure. Cement and construction material plants across China and India deploy vertical roller mills for clinker grinding at throughput rates exceeding 100 tons per hour.
- Cryogenic Grinding:Liquid nitrogen or carbon dioxide cools heat-sensitive materials below glass transition temperatures. Polymer and spice processors in Germany and the Netherlands use these systems to preserve volatile aromatic compounds.
- Air Classification:Centrifugal and gravitational separation sorts particles by size without liquid media. Talc and calcium carbonate producers in Italy and Spain integrate these with roller mills for precise cut-point control.
- Vibratory Processing:Eccentric drives impart three-dimensional motion for gentle blending and surface modification. Pharmaceutical granulation operations in Ireland and Denmark employ these for uniform coating of active ingredients.
Dry grinding anchors volume throughput. Wet grinding is climbing the fastest as battery material specifications tighten.
Application:
Customer type fragmentation separates commodity processors seeking lowest capital cost from validated manufacturers requiring documented qualification protocols and material traceability.
- Pharmaceuticals:Containment-grade milling and drying systems process active ingredients under FDA, EMA, and PMDA oversight. Swiss and Singaporean contract manufacturers drive demand for isolator-integrated jet mills with continuous process verification.
- Food Processing:Hygienic design standards from EFSA and national regulators govern equipment surface finishes and cleanability. Dairy powder and infant formula producers in New Zealand and the Netherlands specify 316L stainless construction with automated CIP systems.
- Chemical Manufacturing:Explosion-proof configurations and solvent recovery integration dominate procurement criteria. German and Japanese specialty chemical producers prioritize ATEX-certified mills with nitrogen inerting.
- Construction Materials:Abrasion-resistant designs tolerate silica and clinker feedstocks with minimal maintenance intervals. Chinese and Vietnamese cement producers favor vertical roller mills with ceramic grinding elements.
- Cosmetics:Narrow particle size distributions enhance texture and coverage in pigment and powder formulations. French and Italian luxury cosmetic houses demand micronization to sub-ten-micron specifications for premium product lines.
Construction materials anchor the installed base. Pharmaceuticals is gaining share fastest on validation-intensive replacement cycles.
End User Industry:
Maturity gradients separate legacy sectors with decades-old equipment from emerging applications requiring novel processing architectures.
- Mining Operations:Semi-autogenous and ball mill circuits grind ore to flotation feed sizes. Chilean and Peruvian copper concentrators represent the largest regional concentration of new mill installations.
- Specialty Chemicals:Multi-product batch facilities demand rapid changeover capability and cross-contamination prevention. German and Swiss agrochemical and electronic materials producers specify modular skidded systems.
- Food & Beverage Plants:Spray drying and agglomeration systems convert liquid feeds into free-flowing powders. Irish and Danish dairy cooperatives dominate whey and lactose processing capacity.
- Personal Care Production:Talc, mica, and mineral sunscreen active processing requires cosmetic-grade contamination control. Brazilian and Mexican manufacturers serving Latin American markets expand micronization capacity.
- Metal Processing:Atomization and mechanical alloying produce powder metallurgy feedstocks. Swedish and Austrian tool steel and titanium powder producers serve additive manufacturing qualification pipelines.
Mining operations command the established base. Specialty chemicals shows the steepest expansion trajectory on continuous manufacturing adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized grinding media and precision classifier wheels concentrate in German and Japanese manufacturing clusters, creating supply dependencies that shape procurement timelines across pharmaceutical and battery material installations worldwide.
United States
Contract pharmaceutical manufacturers in New Jersey and Massachusetts expand micronization capacity for inhalable drug programs. FDA process validation guidelines and OSHA combustible dust regulations compel documented IQ/OQ/PQ protocols and closed-system designs. The Boston-Cambridge biotech corridor drives demand for isolator-integrated jet mills with continuous process verification.
Germany
Specialty chemical producers in North Rhine-Westphalia retrofit containment systems ahead of REACH compliance deadlines. ECHA enforcement of Annex XV restrictions on hazardous substance emissions accelerates replacement demand for closed-loop drying equipment. The Leverkusen-Düsseldorf chemical belt anchors European demand for ATEX-certified mills with nitrogen inerting.
China
Domestic API manufacturers in Jiangsu and Zhejiang provinces install integrated grinding-classification systems to reduce import dependence on processed intermediates. NMPA alignment with ICH Q7 guidelines tightens equipment qualification standards for export-oriented facilities. The Yangtze River Delta battery cluster demands controlled atmosphere milling for lithium nickel manganese cobalt oxide precursors.
India
Pharmaceutical manufacturers in Gujarat and Telangana scale active ingredient micronization capacity for generic API exports. CDSCO harmonization with FDA process validation requirements drives documented equipment qualification protocols from suppliers. The Hyderabad-Visakhapatnam corridor concentrates new fluidized bed dryer installations for domestic formulation fill-finish.
Switzerland
Precision jet milling systems for inhalable drug formulations concentrate around Basel and Zurich pharmaceutical clusters. Swissmedic validation protocols and EMA GMP Annex 15 requirements mandate embedded process analytical technology as standard configuration. The Basel biopharma hub leads European adoption of continuous manufacturing platforms with real-time release capability.
Global Powder Processing Equipment Market Key Industry Players
Concentration sits with diversified industrial technology conglomerates that anchor premium pharmaceutical and food-grade segments through integrated hygienic design and validation support capabilities. The vendor base spans three functional tiers: precision specialists commanding margins in sub-ten-micron pharmaceutical applications, diversified process equipment houses leveraging cross-sector platform economics, and regional fabricators serving commodity mining and construction material processing. M&A activity targets PAT-embedded continuous manufacturing platforms, while capacity expansion concentrates in India and China to serve localization mandates.
Within the precision specialist tier, Hosokawa Micron Corporation and Hänsel Processing GmbH exemplify archetypes that occupy positions defined by micronization expertise and German engineering lineage respectively. Among diversified technology houses, GEA Group and Buhler Group anchor European and Swiss market presence through pharmaceutical containment and food-grade grinding integration. Syntegon Technology GmbH represents the packaging-to-processing vertical extension model. These named entities sit within competitive positions shaped by regulatory qualification depth and aftermarket service architecture rather than unit cost alone.
| Leading Market Players |
|---|
| Bepex International LLC |
| Charles Ross & Son Company |
| Hosokawa Micron Corporation |
| Baker Perkins Limited |
| Hänsel Processing GmbH |
| Syntegon Technology GmbH |
| Dongsun Powder Processing Equipment Co. Ltd |
| Buhler Group |
| GEA Group |
| Others |
Cost & Logistics Intelligence
Ninety-day lead times for precision ceramic grinding media and high-speed classifier wheels concentrate pricing power among German and Japanese specialty manufacturers, compressing margins for equipment assemblers while amplifying cost pass-through to pharmaceutical buyers seeking FDA-validated systems.
Pricing Analysis
FDA process validation guidelines and EMA GMP Annex 15 requirements dictate the pricing tier structure across pharmaceutical-grade equipment procurement. Three-tier pricing structure across premium containment-integrated, standard hygienic-design, and economy industrial-grade levels separates buyers by qualification depth and material traceability requirements. Cost compression in standard-tier grinding systems is intensifying because stainless steel price volatility and precision component supplier concentration squeeze assembler margins. Mining and construction material processors exhibit highest price sensitivity, while Swiss and Singaporean contract manufacturers absorb premium tiers without volume negotiation.
Supply Chain Analysis
Precision ceramic grinding media manufacturing concentrates in Germany and Japan, creating single-source vulnerability for pharmaceutical-grade jet mill configurations. Equipment bill-of-materials draws from 316L stainless steel, specialty alloys, and ceramic grinding elements, with German and Japanese suppliers controlling high-speed classifier wheel production. Tariff exposure runs through precision component import dependencies, particularly for battery material processing equipment serving South Korean cathode precursor manufacturers. Distribution runs through direct OEM sales for pharmaceutical containment systems and regional distributor networks for mining and construction material processing equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Continuous manufacturing platform economics are displacing batch-centric procurement models, with FDA Quality by Design frameworks rewarding integrated powder-to-tablet lines that compress validation timelines and enable real-time release.
For Market Incumbents: Compound validation support capabilities through captive engineering services and documented IQ/OQ/PQ protocol libraries, insulating against emerging PAT-embedded continuous manufacturing specialists threatening premium positioning. Backward integration into precision ceramic grinding media production in Germany or Japan reduces lead time vulnerability and secures margin control. For New Entrants and Emerging Players: Lead with battery material processing equipment for lithium nickel manganese cobalt oxide precursors, where cathode manufacturers demand controlled atmosphere milling without incumbent pharmaceutical validation overhead. Brazil's ANVISA import substitution policies create the most penetrable geography for generic API processing equipment, with modular skidded system architecture enabling rapid commissioning. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underperforming powder processing divisions lacking pharmaceutical qualification depth. Long-term viability centers on PAT-embedded continuous manufacturing platforms with native data integrity architecture. Watch FDA draft guidance on real-time release testing as the inflection signal for platform consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Components | German and Japanese ceramic grinding media supply anchors pharmaceutical equipment margins against volatility. |
| PAT-Embedded Platform Development | Raman spectroscopy and particle size analyzer integration satisfies EMA GMP Annex 15 continuous verification mandates. |
| Battery Material Processing Capacity | South Korean and Chinese cathode precursor specifications drive non-pharmaceutical revenue pool expansion. |
| Validation Support Unbundling | North American pharmaceutical procurement functions now negotiate hardware, validation, and maintenance separately. |
| Brazil Localization Partnership | ANVISA import substitution policies incentivize domestic powder processing capacity for generic API production. |
Research Approach
Operator-level perspectives from plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads anchored the qualitative base, cross-referenced with customs trade data, SEC equipment manufacturer filings, EMA GMP inspection reports, and pharmaceutical facility qualification databases. Bottom-up equipment shipment tracking and top-down end-use industry capacity expansion analysis provided triangulation across volume and value estimates.
Sensitivity analysis tested forecast robustness across stainless steel price volatility bands, REACH compliance deadline acceleration scenarios, and battery material specification tightening trajectories. Segmentation modeling spanned product type, technology, application, and end-use industry dimensions, with regional regulatory cluster and qualification protocol depth as cross-cutting variables. CAGRs derived from equipment replacement cycle analysis, capacity expansion announcements, and continuous manufacturing adoption curve positioning.
The analysis sits within stated boundaries; outcomes outside sustained pharmaceutical capital expenditure commitment or battery material specification stability would require recalibration. Forecasts reflect documented assumptions regarding regulatory timeline adherence and precision component supply continuity. Practitioners should keep alternative scenarios live as FDA real-time release guidance and EMA GMP Annex 15 enforcement intensity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Planetary Mixer Market
Food Processing Equipment
Non-Thermal Food Processing Market
Food Processing Equipment
Fluidized Bed Dryer Market
Food Processing Equipment
Global Electrodialysis Equipment Market
Food Processing Equipment
Convection Ovens Market
Food Processing Equipment
Glass Processing Equipment Market
Food Processing Equipment
Automatic Evisceration System Market
Food Processing Equipment
Canning Machine Market
Food Processing Equipment
De-Agglomerating Equipment Market
Food Processing Equipment
Hot Food Processing Equipment Market
Food Processing Equipment
Beer Brewing Equipment Market
Food Processing Equipment
Brining Systems Market
Food Processing Equipment
Countertop Convection Oven Market
Food Processing Equipment
Global Food Deaerators Market
Food Processing Equipment
Plastic Processing Machinery Market
Food Processing Equipment
Shawarma Grill Machine Market