
 Plastic Processing Equipment Market | 2026-2036
Plastic Processing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Plastic Processing Equipment Market Outlook
China is tilting the competitive map through state-backed capacity additions in all-electric injection molding and large-tonnage extrusion systems. Haitian International Holdings Limited leverages mass production economics to dominate mid-market machine deliveries across Asia and emerging economies. Engel Austria GmbH sustains premium positioning through intensive R&D in tie-bar-less architectures and process-integrated quality systems. Arburg GmbH & Co KG specializes in medical-grade micro-molding platforms that command narrow-tolerance applications.
Plastic processing equipment comprises machinery that shapes thermoplastic and thermoset resins through controlled heat, pressure, and forming cycles, typically operating at clamp forces from 50 to 5,000+ metric tons and barrel temperatures up to 400°C depending on polymer viscosity. Its primary purpose is to convert raw polymer pellets into dimensionally precise finished or semi-finished components for industrial assembly and consumer use. Injection molding machines anchor the highest value pool due to their ubiquity in automotive and medical device production, where cavity complexity and repeatability justify capital intensity. Electric technology segments are capturing margin expansion as energy efficiency and servo precision displace hydraulic platforms in regulated end uses. Packaging applications sustain volume throughput demand, particularly for thin-wall containers and closure systems running on high-speed hybrid systems.
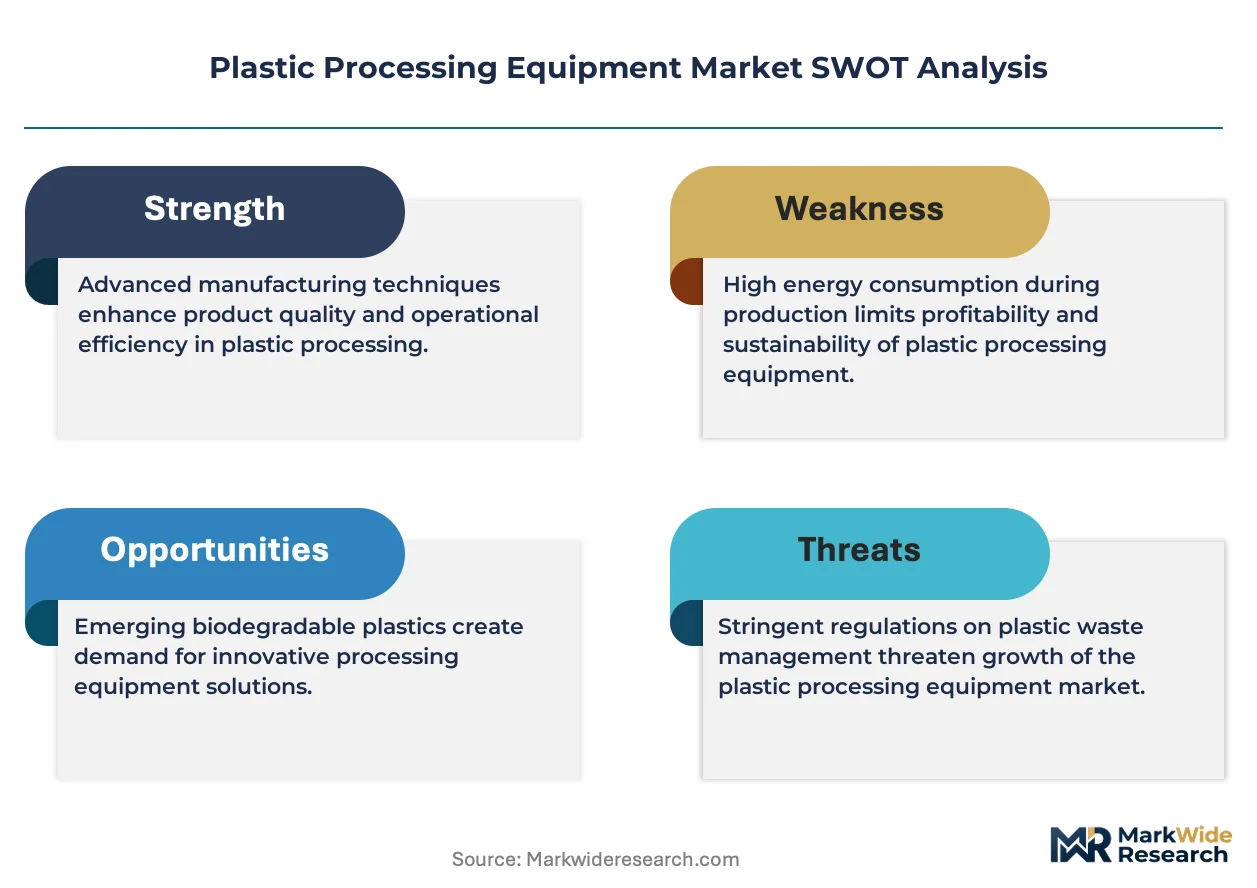
The US EPA and OSHA frameworks govern emissions and workplace exposure limits that shape machine enclosure and ventilation specifications, while the EU F-Gas Regulation and REACH directly constrain hydraulic fluid chemistries and refrigerant choices in cooling circuits. China's GB energy efficiency standards and SAMR certification requirements create divergent compliance pathways that fragment equipment specification sheets across export markets. Stakeholders must weigh regulatory trajectory against technology refresh cycles when committing to platform architectures that will operate across multiple jurisdictions.
Market Dynamics
The transition from hydraulic to all-electric and hybrid machine architectures constitutes the dominant structural force reshaping capital allocation across plastic processing equipment, as energy efficiency mandates and precision requirements compress technology refresh cycles.
Growth Catalysts
- EU F-Gas Regulation:The phase-down of fluorinated greenhouse gases in cooling circuits accelerates electric machine adoption among European automotive molders seeking compliant process-integrated quality systems.
- Medical device cleanroom expansion:Sterile manufacturing requirements for drug-delivery devices and surgical instruments pull high-cavitation, tie-bar-less platforms into pharmaceutical supply chains.
- China's dual carbon goals:GB energy efficiency standards and provincial carbon intensity targets force domestic processors toward servo-driven injection systems with regenerative braking.
Market Restraints
- Specialized steel and servo motor cost volatility:Precision ball screws and rare-earth magnet supply concentration in China inflates electric machine bill-of-materials unpredictability.
- REACH compliance friction:ECHA restrictions on hydraulic fluid additives and metalworking lubricants extend equipment qualification timelines for converters serving EU export markets.
- Technical limitation in large-tonnage electric platforms:Clamping force economics above 1,000 metric tons still favor hybrid architectures, fragmenting fleet standardization for automotive structural component producers.
Strategic Opportunities
- India's PLI scheme for medical devices:Domestic manufacturing incentives create white space for micro-molding platforms serving contract manufacturers qualifying under CDSCO and BIS standards.
- Biopolymer process convergence:Equipment retrofits integrating temperature-controlled venting and shear-rate management capture emerging PLA and PHA packaging demand.
- Outcome-based service contracting:Availability-guarantee and pay-per-part models displace traditional maintenance agreements among mid-market processors in Southeast Asia.
Industry Challenges
- Controls software integration complexity:Legacy hydraulic press fleets resist seamless retrofit with Industry 4.0 data architectures, forcing parallel SCADA overlay investments.
- Multi-jurisdiction certification timelines:SAMR, CE marking, and OSHA variance requirements for a single machine platform extend commercialization cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plastic Processing Equipment Market |
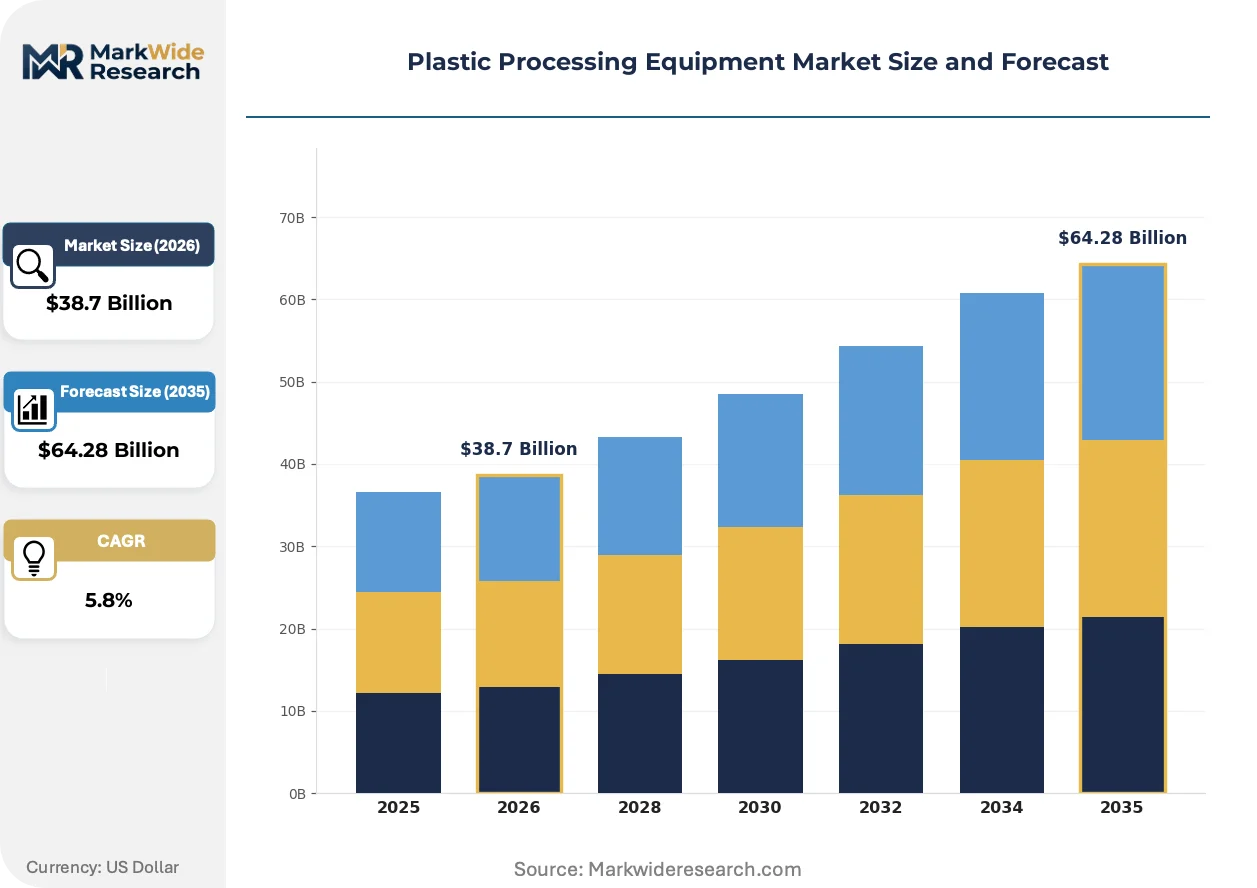
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $64.28 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injection Molding Machines, Extruders, Blow Molding Machines, Thermoforming Machines Technology: Electric, Hydraulic, Hybrid, Pneumatic End User: Automotive, Consumer Goods, Packaging, Medical Devices Size: Small Scale, Medium Scale, Large Scale, Customized Solutions |
| Companies Covered | KraussMaffei Corporation, Husky Injection Molding Systems Ltd., Engel Austria GmbH, Nissei Plastic Industrial Co Ltd., Sumitomo Heavy Industries Ltd., Haitian International Holdings Limited, Milacron LLC, Shibaura Machine Co Ltd., Arburg GmbH & Co KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plastic Processing Equipment Market Strategic Shifts
Digital twin technology and closed-loop process control are compressing setup times and scrap rates simultaneously, while regulatory chemistry constraints and circular economy mandates rewrite equipment specification priorities across buyer segments.
Digital twin software for injection molding is virtualizing machine behavior, material flow, and thermal dynamics prior to physical commissioning. Tier-one automotive suppliers in Germany and Japan deploy these platforms to reduce mold trial iterations by half. The technology is virtualizing traditional equipment supplier relationships as molders bring simulation capability in-house.
The EU F-Gas Regulation's refrigerant phase-down is forcing cooling circuit redesigns across hydraulic and hybrid platforms. Equipment manufacturers now specify propane-based chillers and adiabatic cooling towers to maintain process temperature stability. Medical device producers in Ireland and Switzerland face the tightest compliance windows, accelerating electric platform procurement.
Consolidated buying by multinational packaging groups is compressing supplier negotiation cycles and unbundling after-sales service contracts. Regional equipment distributors in Brazil and Mexico lose margin to direct manufacturer relationships as buyers centralize procurement through corporate engineering teams. This concentration is most visible in thin-wall food container and closure system segments.
Plastic Processing Equipment Market Segmentation
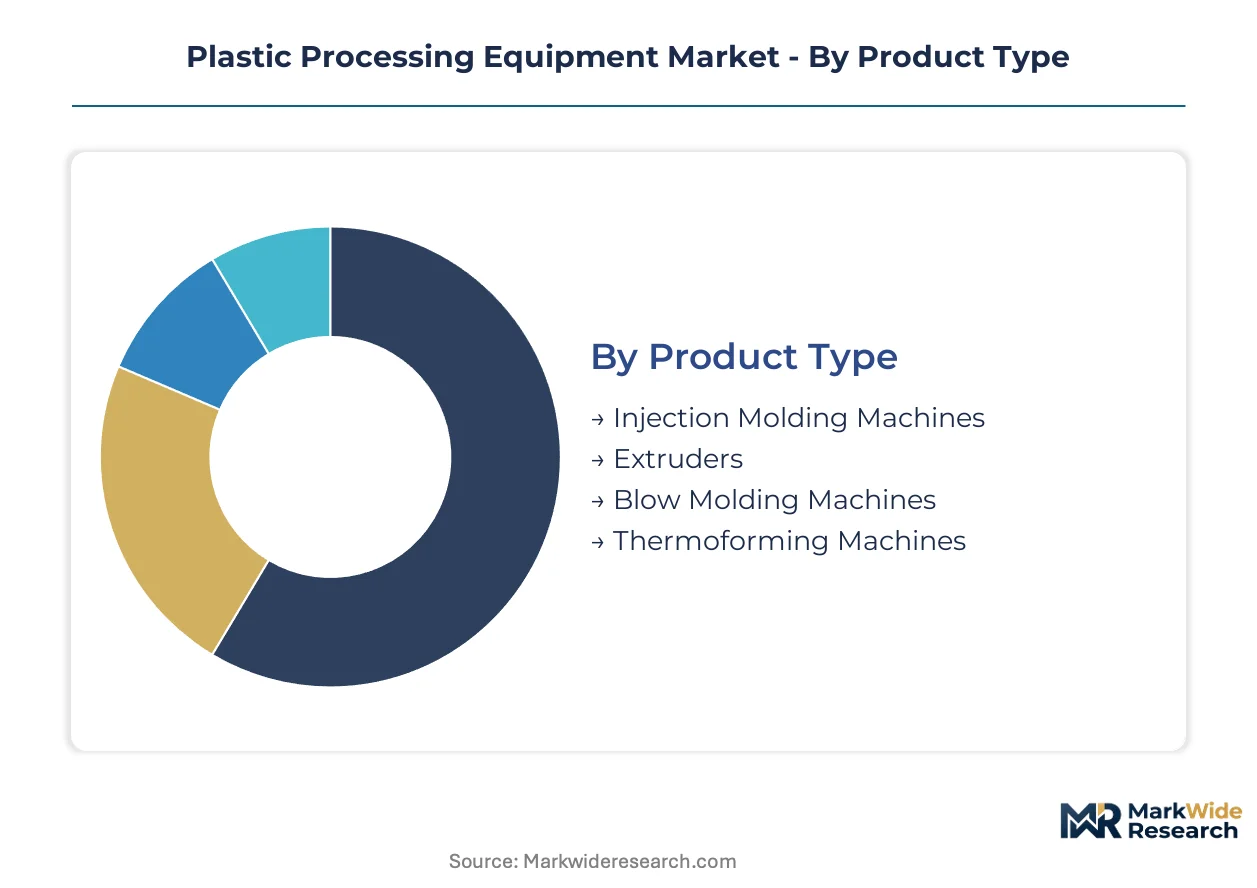
Plastic processing equipment segments by product type, technology, end user, and operational scale. Each dimension carries distinct margin profiles, certification requirements, and technology refresh cycles that shape procurement behavior across automotive, medical, and packaging verticals.
Product Type:
Mature hydraulic platforms dominate legacy installed bases while emerging electric architectures capture replacement demand in precision end uses.
- Injection Molding Machines:These systems apply clamp forces from 50 to 5,000+ metric tons to shape thermoplastics into dimensionally precise components. Automotive OEMs in Germany and medical device manufacturers in Switzerland anchor demand for high-cavitation, tie-bar-less configurations that reduce cycle times and improve repeatability.
- Extruders:Continuous screw-driven systems melt and form polymer into profiles, films, or pellets at throughputs exceeding multiple tons per hour. China's state-backed capacity additions in large-tonnage extrusion systems are tilting competitive economics toward domestic suppliers serving Asia-Pacific infrastructure and packaging markets.
- Blow Molding Machines:Parison-based forming systems produce hollow containers from pharmaceutical bottles to automotive fuel tanks. FDA and EMA compliance requirements for drug-contact surfaces constrain supplier qualification in North American and European pharmaceutical supply chains.
- Thermoforming Machines:Sheet-fed systems heat and vacuum-form polymer into trays, cups, and clamshell packaging. Thin-wall food container producers in Mexico and Brazil concentrate procurement through corporate engineering teams, compressing distributor margins.
Injection molding machines handle the majority of throughput; extruders are gaining share fastest among replacement investments.
Technology:
Cost tier stratification separates premium electric platforms from standard hydraulic fleets and mid-market hybrid alternatives.
- Electric:Servo-driven architectures eliminate hydraulic fluid circuits, delivering precision positioning and energy recovery through regenerative braking. EU F-Gas Regulation compliance windows and China's GB energy efficiency standards are accelerating displacement of hydraulic platforms in regulated automotive and medical end uses.
- Hydraulic:Conventional oil-pressure systems maintain cost advantages in large-tonnage applications above 1,000 metric tons where electric clamping economics fragment. REACH restrictions on hydraulic fluid additives extend equipment qualification timelines for converters serving EU export markets.
- Hybrid:Combined electric servo and hydraulic power units balance precision with force economics in mid-tonnage packaging and consumer goods applications. Southeast Asian processors favor these platforms for availability-guarantee service contracting models.
- Pneumatic:Compressed-air actuation serves specialized low-force forming and trimming operations in secondary processing stations. Limited to niche auxiliary equipment as primary forming demands higher pressure capabilities.
Electric platforms command the steepest expansion trajectory; hybrid systems retain the largest installed base pending refresh cycles.
End User:
Application-specific requirements fragment equipment specification priorities across volume-driven and precision-critical segments.
- Automotive:Structural component producers require clamping forces above 1,000 metric tons for bumper beams, dashboards, and under-hood modules. Germany's precision molders supply high-cavitation tooling to OEMs demanding process-integrated quality systems and ISO/TS certification alignment.
- Medical Devices:Cleanroom-capable processing lines for drug-delivery devices and surgical instruments pull tie-bar-less platforms into pharmaceutical supply chains. CDSCO and BIS standards in India are creating white space for micro-molding platforms under domestic manufacturing incentives.
- Packaging:Thin-wall container and closure system production runs on high-speed hybrid systems with sub-second cycle times. Consolidated multinational buying compresses supplier negotiation cycles and unbundles after-sales service contracts.
- Consumer Goods:Durable and disposable product molding spans commodity resins to engineering polymers with less stringent tolerance requirements than medical or automotive segments. Price sensitivity favors refurbished hydraulic fleets and regional equipment distributors.
Automotive absorbs the highest capital intensity per machine; medical devices show the fastest share climb from cleanroom expansion.
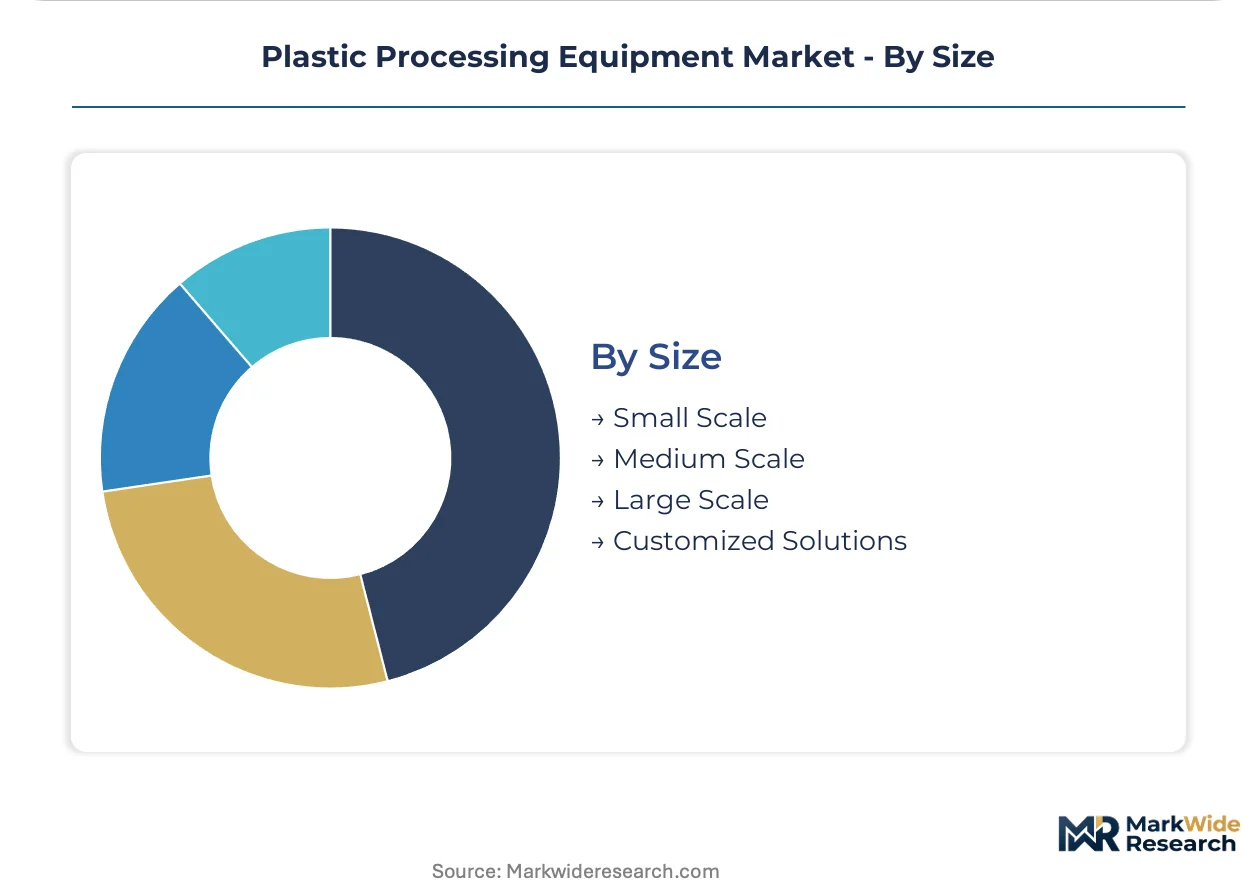
Size:
Customer type differentiation separates mass-production processors from specialized job shops and captive manufacturing operations.
- Small Scale:Benchtop and entry-level machines serve prototyping, short-run molding, and educational applications. Job shops in Brazil and Mexico lose margin to direct manufacturer relationships as buyers centralize procurement.
- Medium Scale:General-purpose platforms from 100-500 metric tons clamp force anchor contract manufacturing and mid-volume component supply. These systems face the steepest technology refresh pressure from energy efficiency mandates.
- Large Scale:High-tonnage systems for automotive structural parts and bulk packaging command dedicated installation infrastructure and extended commissioning timelines. SAMR, CE marking, and OSHA variance requirements extend commercialization cycles by 8-14 months for single platforms.
- Customized Solutions:Application-engineered configurations integrate specialized controls, multi-material capability, or in-mold decoration for differentiated product requirements. Medical-grade micro-molding and biopolymer processing retrofits concentrate in this tier.
Medium scale carries the broadest installed base; customized solutions expand most quickly from medical and biopolymer process convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Machine builders cluster in Germany, Japan, and China, each commanding distinct technology tiers. Precision molders in southern Germany supply automotive OEMs with high-cavitation tooling. Chinese state-backed capacity additions in all-electric platforms compress mid-market pricing across Asia.
United States
Medical device cleanroom expansion in Minnesota and Massachusetts pulls tie-bar-less platforms into pharmaceutical supply chains. The EPA and OSHA frameworks govern emissions and workplace exposure limits that shape machine enclosure specifications. Precision molders in the Great Lakes region serve automotive OEMs with process-integrated quality systems.
Germany
Automotive structural component producers demand clamping forces above 1,000 metric tons for bumper beams and under-hood modules. The EU F-Gas Regulation and REACH compliance push converters toward electric and hybrid machine platforms. Bavarian precision molders anchor high-cavitation tooling supply to premium automotive OEMs.
China
Provincial carbon intensity targets under dual carbon goals force domestic processors toward servo-driven injection systems. GB energy efficiency standards and SAMR certification requirements create divergent compliance pathways that fragment equipment specification sheets. Yangtze River Delta manufacturers dominate mass production economics in mid-market machine deliveries.
Japan
Automotive and electronics OEMs require sub-micron repeatability for connector and housing production. METI efficiency standards and JIS certification frameworks shape equipment procurement specifications. Chubu region machinery builders specialize in compact electric platforms for precision component molding.
India
The PLI scheme for medical devices creates white space for micro-molding platforms serving contract manufacturers. CDSCO and BIS standards govern equipment qualification timelines for pharmaceutical supply chains. Gujarat and Maharashtra industrial corridors concentrate new capacity additions in packaging and consumer goods segments.
Plastic Processing Equipment Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in precision drive and control modules. The vendor base stratifies across three tiers: premium European builders with intensive R&D programs, Asian mass-production specialists leveraging scale economics, and mid-market hybrid-platform providers serving regional contract manufacturers. Strategic moves concentrate on technology licensing for electric architectures and backward integration into servo motor production.
Among Austrian and German precision machinery builders, Engel Austria GmbH and Arburg GmbH & Co KG exemplify the premium-tier archetype through tie-bar-less architectures and medical-grade platform specialization. Haitian International Holdings Limited occupies a position at the scale-driven end, representing mass-production economics in mid-market all-electric and hybrid system deliveries across Asia and emerging economies. These three entities anchor the competitive spectrum from precision-critical to volume-optimized equipment supply.
| Leading Market Players |
|---|
| KraussMaffei Corporation |
| Husky Injection Molding Systems Ltd. |
| Engel Austria GmbH |
| Nissei Plastic Industrial Co Ltd. |
| Sumitomo Heavy Industries Ltd. |
| Haitian International Holdings Limited |
| Milacron LLC |
| Shibaura Machine Co Ltd. |
| Arburg GmbH & Co KG |
| Others |
Value Chain & Pricing Dynamics
The Yangtze River Delta's concentrated all-electric injection molding capacity feeds pricing power downstream to mid-market machine buyers across Southeast Asia, compressing margins for regional distributors unable to match mass-production economics.
Pricing Analysis
EU F-Gas Regulation dictates the pricing tier structure across European automotive and medical end uses, forcing premium positioning for electric platforms with compliant cooling circuits while hybrid systems capture mid-market packaging demand. Price differentiation hinges on certification grade—CE-marked medical-grade configurations command substantial premiums over standard industrial variants—and volume scale, with multinational packaging groups extracting fleet discounts unavailable to job shops. Pricing pressure intensifies in the mid-tonnage segment as Haitian International and domestic Chinese suppliers flood Asia-Pacific markets with servo-driven alternatives. Contract manufacturers in India and Brazil exhibit the highest price sensitivity, while Swiss and German precision molders prioritize repeatability and cleanroom compatibility over capital cost.
Supply Chain Analysis
Export controls on servo motor technology and rare-earth magnet processing constrain component flows from China to European and North American machine builders, fragmenting supply security across tier-one manufacturers. Precision ball screws and high-torque servo motors draw from concentrated production in China, Japan, and Germany, with secondary sourcing for specialized hydraulic valves anchored in Italy and the United States. Single-source vulnerability in rare-earth magnet supply creates acute exposure for electric platform assemblers dependent on Chinese processed neodymium. Distribution runs through direct manufacturer relationships with multinational OEMs, bypassing traditional regional distributors in Mexico, Brazil, and Southeast Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Medical device cleanroom expansion fragments demand into specialized micro-molding niches, creating entry points for equipment specialists outside the dominant automotive supply chain.
For Market Incumbents: Harden defensive positions by deepening captive production of servo motors and precision drive components to offset rare-earth supply volatility. Accelerate certification investments for CDSCO and BIS compliance to lock in India's PLI-driven medical device manufacturing wave before regional competitors qualify. Tie-bar-less architecture R&D at Engel and Arburg must extend into sub-50-ton medical micro-molding to defend premium positioning against emerging Asian specialists. For New Entrants and Emerging Players: India's Gujarat and Maharashtra industrial corridors offer underpenetrated white space for mid-scale electric platforms serving packaging and consumer goods segments outside the automotive shadow of German and Japanese incumbents. Biopolymer processing retrofits—temperature-controlled venting and shear-rate management modules—present a second entry vector as PLA and PHA packaging demand outruns incumbent equipment adaptation cycles. Partner with contract manufacturers qualifying under CDSCO standards to bypass direct competition with established medical-grade suppliers. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with neglected plastics machinery divisions lacking electric platform roadmaps. Five-to-ten-year viability favors precision component specialists with backward integration into control software and process simulation capability. Monitor SAMR certification timelines for foreign equipment platforms as an inflection signal—accelerated approvals for European builders would indicate regulatory alignment favoring premium-tier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Servo Motor Production | Captive rare-earth magnet supply secures electric platform margins against Chinese export volatility. |
| Medical-Grade Micro-Molding Platform Launch | CDSCO and BIS certification alignment captures India's PLI scheme contract manufacturing demand. |
| Biopolymer Process Retrofit Development | Shear-rate management modules capture emerging PLA and PHA packaging converter requirements. |
| Direct Manufacturer Relationship Expansion | Bypassing Brazilian and Mexican distributors recaptures margin from multinational packaging procurement centralization. |
| Outcome-Based Service Contracting | Availability-guarantee models displace traditional maintenance agreements among Southeast Asian mid-market processors. |
Study Parameters
A spread of perspectives from plant engineers at automotive Tier 1 suppliers, medical device manufacturing directors, packaging procurement leads, and aftermarket service heads converged on the working assumptions shaping demand trajectories. Primary fieldwork across Germany, China, Japan, and the United States supplemented secondary validation through SEC filings, customs and trade data, SAMR certification registries, and EU F-Gas Regulation compliance disclosures. Bottom-up equipment shipment analysis and top-down polymer consumption modeling triangulated volume estimates across the projection horizon.
Demand-supply balance dynamics anchored the analytical framework, with segmentation modeling across technology tier, end-use vertical, and operational scale throughout the forecast period. Injection molding machine configurations were further disaggregated by clamp force range and cleanroom compatibility to capture medical device demand divergence. CAGRs derived from replacement cycle analysis and energy efficiency mandate compliance timelines, with cross-referencing against provincial carbon intensity targets in China and GB standard enforcement trajectories.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by Chinese state-backed manufacturers or accelerated REACH restrictions on hydraulic fluids would shift outcomes. Material shifts in rare-earth magnet export controls, EU F-Gas Regulation phase-down timelines, or India's PLI scheme disbursement rates would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Commercial Mixer Market
Food Processing Equipment
Global Carbonated Beverage Processing Equipment Market
Food Processing Equipment
North America Walk-In Refrigerators and Freezers Market
Food Processing Equipment
Non-Thermal Food Processing Market
Food Processing Equipment
Reach-In Freezers Market
Food Processing Equipment
Food Extrusion Market
Food Processing Equipment
Shrimp Peeling Machine Market
Food Processing Equipment
Smart Meat Thermometer Market
Food Processing Equipment
UHT Systems Market
Food Processing Equipment
Cider Brewing Equipment Market
Food Processing Equipment
Fish Filleting Machine Market
Food Processing Equipment
Tangyuan Machine Market
Food Processing Equipment
High Speed Oven Market
Food Processing Equipment
Smart Food Machine Market
Food Processing Equipment
Deep Fryer Machine Market
Food Processing Equipment
Pet Food Processing Market