
 Hygienic Easy to Clean Food Processing Equipment Market | 2026-2036
Hygienic Easy to Clean Food Processing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Hygienic Easy to Clean Food Processing Equipment Market Analysis
Contract food manufacturers is unwinding share from in-house plant operators as private-label production scales across North America and Western Europe. GEA Group leverages its dairy processing heritage to dominate clean-in-place system integration. Tetra Pak sustains technology leadership through aseptic filling architectures that minimize contamination vectors. Alfa Laval AB anchors European demand with heat exchanger designs optimized for rapid disassembly and visual inspection protocols.
Hygienic easy to clean food processing equipment encompasses machinery engineered with smooth surface finishes, minimal crevices, and tool-free disassembly to eliminate microbial harborage points during sanitation cycles. Stainless steel construction with sub-micron Ra surface roughness dominates regulatory-compliant installations, while electropolished welds and sealed bearing housings prevent biofilm accumulation in dairy and meat processing environments. Conveyor systems lead material handling installations due to modular belt designs that permit single-person washdown routines without production line shutdown. Stainless steel commands the material hierarchy given its corrosion resistance under caustic cleaning chemistries, though composite panels are gaining traction in bakery applications where thermal cycling demands differ. Dairy processing represents the most specification-intensive application segment, with clean-in-place validation protocols driving equipment replacement decisions.
The FDA Food Safety Modernization Act mandates preventive controls for human food, compelling processors to document equipment cleanability in hazard analyses. EFSA hygiene guidelines and EU Regulation 852/2004 establish equivalent cleanability benchmarks across member states, while 3-A Sanitary Standards in North America certify equipment designs for dairy and meat contact surfaces. Stakeholders must monitor evolving ISO 14159 machinery safety standards, which increasingly incorporate hygienic design requirements alongside traditional operator protection protocols.
Market Dynamics
Clean-in-place validation protocols are compressing equipment replacement cycles across dairy and ready-to-eat segments, forcing processors to prioritize hygienic design certification over capital cost minimization in procurement decisions.
Growth Catalysts
- FSMA preventive controls mandate:FDA documentation requirements for equipment cleanability in hazard analyses compel processors to upgrade to validated hygienic designs.
- Ready-to-eat meal manufacturing expansion:Private-label production scaling across North America accelerates demand for rapid-sanitation conveyor and filling systems.
- German dairy cooperative consolidation:Large processing footprint mergers in Bavaria and Lower Saxony drive centralized equipment standardization programs.
Market Restraints
- Electropolished stainless steel supply concentration:Specialty surface finish capacity clusters in Nordic and German metallurgical suppliers, creating input bottlenecks.
- 3-A Sanitary Standards certification timeline:Dairy contact surface validation protocols extend equipment commissioning by four to eight months.
- Composite panel thermal cycling limitations:Bakery applications face material degradation under repeated steam sanitation above 120°C.
Strategic Opportunities
- Modular clean-in-place system integration:Convergence of IoT sensor networks with automated chemical dosing enables real-time biofilm detection.
- Contract manufacturer channel expansion:Toll processing growth in Netherlands and Belgium creates demand for flexible, multi-product line equipment.
- EU Green Deal industrial decarbonization incentives:Heat recovery heat exchanger upgrades qualify for national efficiency grants in Denmark and Sweden.
Industry Challenges
- Sanitary welding technician scarcity:Certified orbital welders for sub-micron Ra finish specifications command 40% wage premiums in tight labor markets.
- Legacy equipment integration complexity:Retrofitting 1990s-era production lines with tool-free disassembly protocols requires custom mechanical adapters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hygienic Easy to Clean Food Processing Equipment Market |
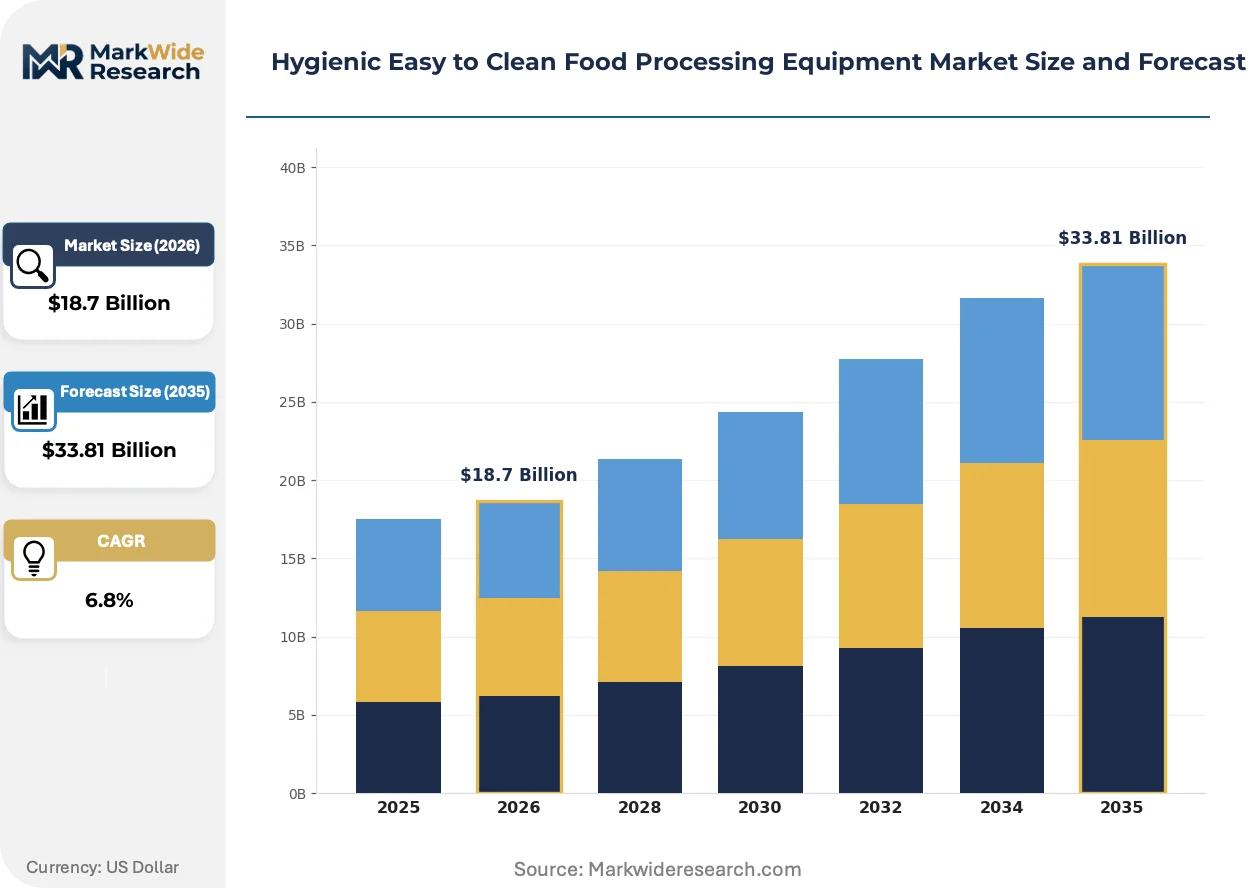
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conveyor Systems, Mixers, Blenders, Food Grinders Material: Stainless Steel, Plastic, Glass, Composite Application: Dairy Processing, Meat Processing, Beverage Production, Bakery End User: Food Manufacturers, Restaurants, Catering Services, Supermarkets |
| Companies Covered | Tetra Pak, GEA Group, Buhler AG, SPX Corporation, Middleby Corporation, Heat and Control Inc., Rheon Automatic, Alfa Laval AB, Marel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hygienic Easy to Clean Food Processing Equipment Market Emerging Trajectories
Equipment architecture is splitting between maximal-automation aseptic systems and simplified manual-clean designs, with specification intensity diverging sharply by end-use contamination risk tolerance.
Electropolished 316L stainless steel with sub-micron surface roughness is bifurcating equipment procurement into two tiers. High-risk dairy and infant formula processors specify Ra 0.4 micrometer finishes with full material traceability. Mid-risk bakery and beverage operators accept Ra 0.8 micrometer mechanical polishing at 30% lower unit cost. This surface finish stratification is compressing supplier margins on intermediate-grade offerings.
EFSA hygiene guideline updates and EU Regulation 852/2004 enforcement harmonization are mandating visual inspection access points on all food contact equipment. Member state food safety authorities now require documented disassembly times under 15 minutes for validation compliance. Dairy processors in France and Italy are responding by specifying hinged bearing housings and quick-release clamp architectures in new tenders.
Buyer consolidation among contract manufacturers is concentrating procurement authority with technical specification teams rather than plant engineering departments. Equipment selection now flows through centralized hygiene validation committees at firms operating multiple toll processing sites. This committee-driven purchasing is most visible in Netherlands-based ready-to-eal specialists scaling private-label output for German retailers.
Hygienic Easy to Clean Food Processing Equipment Market Segmentation
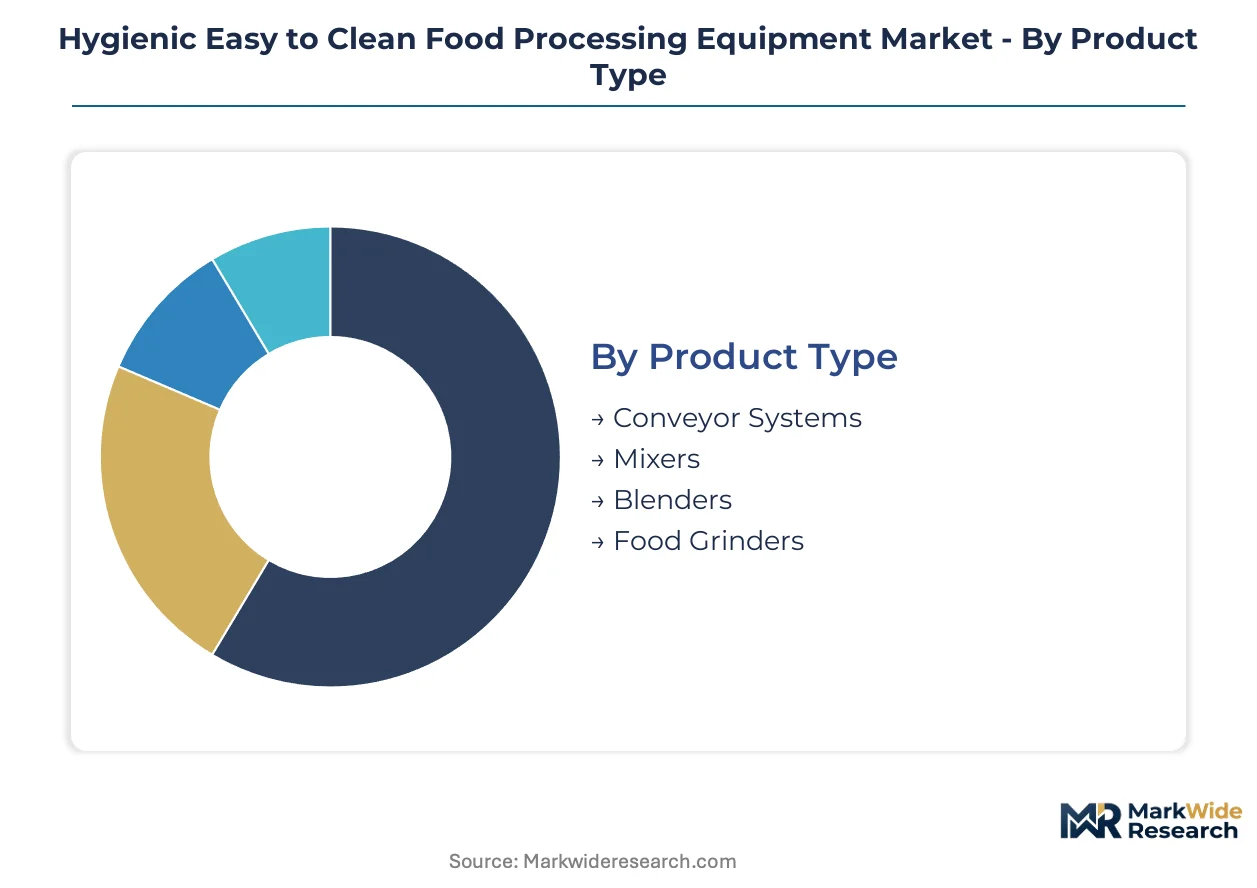
Equipment specification intensity varies sharply across contamination risk profiles and sanitation chemistry exposure. Regulatory validation protocols drive material selection and architectural complexity in high-risk dairy and meat applications.
Product Type:
FSMA preventive controls and EFSA hygiene guidelines mandate documented cleanability for each equipment class, with conveyor systems facing the most stringent validation timelines.
- Conveyor Systems:Modular belt architectures with tool-free disassembly enable single-operator washdown without line shutdown. Ready-to-eat manufacturers in Germany and the Netherlands specify quick-release clamp designs to meet EFSA visual inspection access mandates.
- Mixers:Sealed bearing housings and electropolished 316L contact surfaces prevent biofilm accumulation in high-viscosity dairy applications. French and Italian processors now require hinged access panels permitting sub-15-minute disassembly for compliance documentation.
- Blenders:High-shear designs with polished Ra 0.4 micrometer finishes dominate infant formula specifications.
- Food Grinders:Removable auger assemblies and polished grinding heads address meat processing sanitation cycles.
Established volume favors Conveyor Systems; emerging adoption favors Mixers as dairy cooperative consolidation accelerates centralized specification programs.
Material:
Cost tier stratification separates premium electropolished grades from mechanically polished alternatives, with thermal cycling demands driving composite experimentation in lower-risk segments.
- Stainless Steel:Electropolished 316L with sub-micron Ra surface roughness commands regulatory-compliant installations across dairy and meat contact surfaces. Nordic and German metallurgical suppliers concentrate specialty finish capacity, creating input bottlenecks for validated grades.
- Composite:Glass-reinforced polymer panels reduce thermal mass in bakery proofing and cooling applications. Material degradation above 120°C steam sanitation limits penetration in high-temperature clean-in-place protocols.
- Plastic:UHMW-PE and PTFE components serve low-temperature beverage handling where thermal cycling is minimal.
- Glass:Borosilicate sight glasses and inspection windows provide visual access points for EFSA-mandated hygiene verification.
Stainless Steel captures specification-critical revenue; Composite gains share fastest in thermal-moderate bakery environments.
Application:
Customer type concentration determines architectural complexity, with contract manufacturers driving multi-product flexibility requirements.
- Dairy Processing:Clean-in-place validation protocols and 3-A Sanitary Standards certification compress equipment replacement cycles. Bavarian and Lower Saxony cooperative mergers demand centralized standardization across expanded processing footprints.
- Meat Processing:USDA-FSIS sanitation performance standards and EU Regulation 853/2004 specific hygiene rules mandate daily disassembly for visual inspection. Tool-free bearing housings and quick-release clamp architectures dominate tender specifications.
- Beverage Production:Aseptic filling architectures minimize contamination vectors in extended-shelf-life packaging.
- Bakery:Moderate contamination risk permits simplified manual-clean designs with reduced surface finish requirements.
Dairy Processing anchors premium equipment investment; Meat Processing shows steepest expansion trajectory as FSIS enforcement tightens.
End User:
Procurement authority concentration shifts technical specification control from plant engineering to centralized hygiene validation committees.
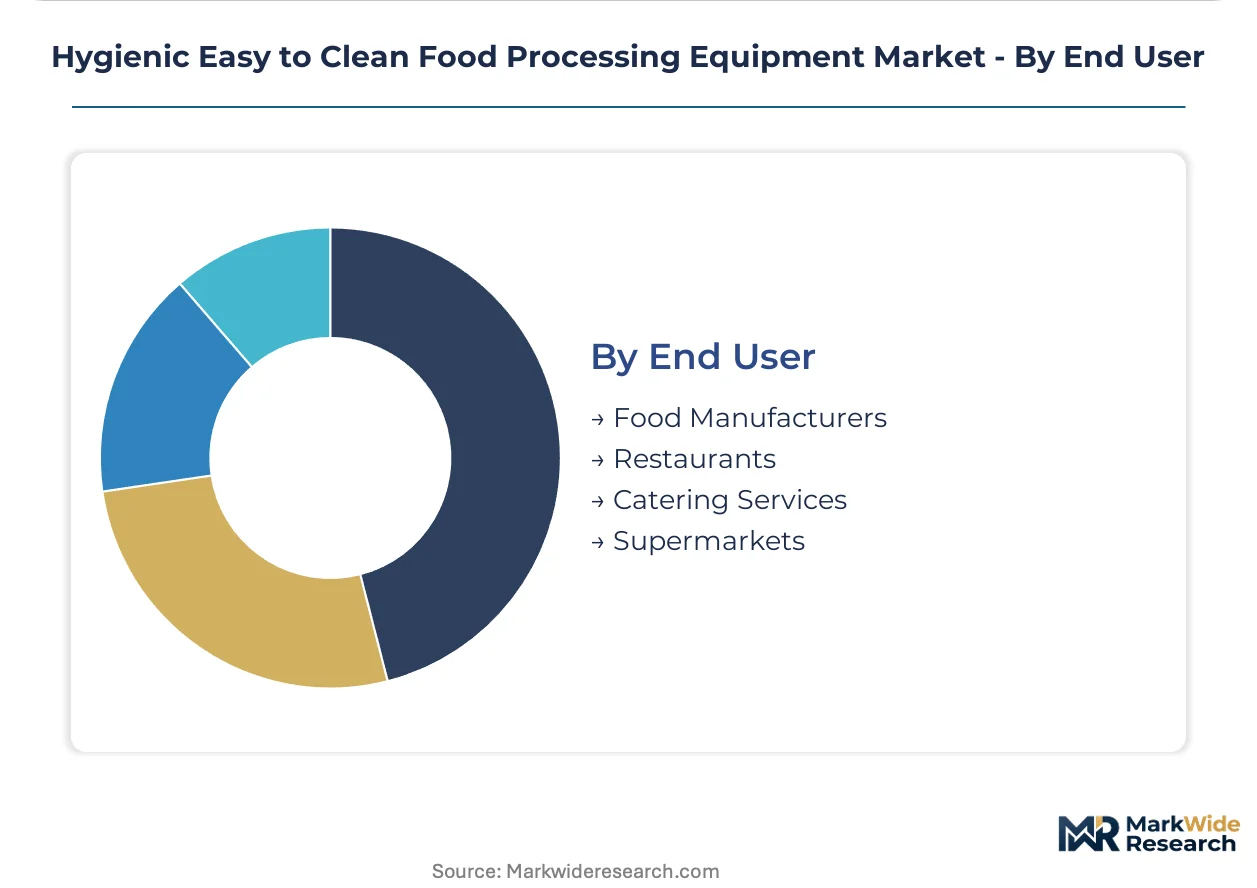
- Food Manufacturers:Private-label production scaling across North America and Western Europe drives toll processing growth. Netherlands-based ready-to-eat specialists now route equipment selection through multi-site hygiene committees rather than individual plant engineers.
- Restaurants:Commercial kitchen operators prioritize compact footprint and rapid sanitation turnaround for high-throughput service environments.
- Catering Services:Mobile and temporary food service operations demand lightweight, modular equipment with simplified disassembly protocols.
- Supermarkets:In-store prepared food departments require equipment bridging retail space constraints with regulatory cleanability documentation.
Food Manufacturers dominate capital equipment procurement; Supermarkets represent the fastest-climbing adoption curve as prepared food retail expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German dairy equipment exports flow into French and Italian processing facilities as cooperative consolidation reshapes procurement patterns across the continent.
United States
Private-label ready-to-eat production scaling drives conveyor system replacement cycles. FDA FSMA preventive controls mandate documented equipment cleanability in hazard analyses. Chicago and Minneapolis processing clusters concentrate toll manufacturing capacity for national retail chains.
Germany
Bavarian and Lower Saxony dairy cooperative mergers demand centralized equipment standardization across expanded footprints. EU Regulation 852/2004 hygiene benchmarks shape tender specifications. Munich-area engineering clusters supply electropolished stainless steel components to dairy contact surface fabricators.
France
Infant formula processors specify Ra 0.4 micrometer surface finishes with full material traceability. EFSA hygiene guideline updates mandate visual inspection access points. Lyon and Rennes dairy processing zones drive hinged bearing housing and quick-release clamp architectures.
Netherlands
Contract manufacturer procurement authority concentrates with centralized hygiene validation committees. EU Green Deal industrial decarbonization incentives support heat recovery heat exchanger upgrades. Amsterdam-Rotterdam corridor hosts ready-to-eat specialists scaling private-label output for German retailers.
Italy
Meat processing sanitation performance standards tighten daily disassembly requirements for visual inspection. EU Regulation 853/2004 specific hygiene rules dominate tender specifications. Emilia-Romagna protein processing clusters adopt tool-free bearing housings to compress sanitation cycle times.
Hygienic Easy to Clean Food Processing Equipment Market Vendor Landscape
Player mix skews toward diversified industrial conglomerates with heritage dairy processing expertise. Market structure concentrates around integrated system providers capable of delivering validated clean-in-place architectures. Strategic archetypes include electropolished stainless steel specialists, modular conveyor fabricators, and heat exchanger designers optimized for rapid disassembly. Dominant competitive moves encompass portfolio diversification into adjacent food contact equipment categories and strategic partnerships with metallurgical suppliers for specialty surface finish capacity.
Among Nordic and German engineering groups, Alfa Laval AB and GEA Group exemplify the heritage-dairy-processing archetype with deep integration into heat transfer and clean-in-place system architectures. Tetra Pak occupies a distinct position at the aseptic-filling vector, representing the maximal-automation tier where contamination vector minimization drives specification intensity. These three anchors demonstrate how geographic clustering around metallurgical supply bases and dairy processing heritage shapes competitive positioning.
| Leading Market Players |
|---|
| Tetra Pak |
| GEA Group |
| Buhler AG |
| SPX Corporation |
| Middleby Corporation |
| Heat and Control Inc. |
| Rheon Automatic |
| Alfa Laval AB |
| Marel |
| Others |
Supply Flow & Price Mechanics
Electropolished stainless steel capacity utilization above 85 percent in Nordic and German metallurgical clusters concentrates supplier pricing power and establishes hard price floors for validated surface finishes. This scale concentration forces equipment fabricators to absorb margin compression or pass through input costs to dairy processors with limited substitution alternatives.
Pricing Analysis
Next-generation IoT-integrated clean-in-place systems command 40-50 percent premiums over current-generation automated units, while prior-generation manual-clean designs trade at 60 percent discounts in secondary markets. Three-tier pricing structure across premium, standard, and economy levels separates Ra 0.4 micrometer electropolished systems with full traceability from Ra 0.8 micrometer mechanical polish alternatives and unvalidated legacy equipment. Cost compression in mid-grade offerings is intensifying because surface finish stratification eliminates demand for intermediate specifications. Contract manufacturers with centralized hygiene committees exhibit lowest price sensitivity; independent bakery operators demonstrate highest.
Supply Chain Analysis
Strait of Malacca transit congestion threatens just-in-time delivery of electropolished 316L stainless steel from Swedish and Finnish mills to Southeast Asian fabricators. Geographic supply concentration centers on Germany, Sweden, and Finland for specialty metallurgical finishes; Italy and Denmark for precision machining; and Netherlands for modular conveyor assembly. Raw material dependencies draw from nickel ore, chromium alloys, and specialized chemical polishing agents. Single-source vulnerability in orbital welding technician certification creates bottleneck risk. Distribution runs through direct OEM channels for large dairy cooperatives and regional distributor networks for mid-size processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equipment specification fragmentation accelerates as buyer consolidation among contract manufacturers fragments procurement authority across hygiene validation committees, technical specification teams, and plant engineering departments. This demand-side shift creates niches for specialized fabricators targeting committee-driven purchasing protocols.
For Market Incumbents: Secure captive capacity in electropolished stainless steel through backward integration into Nordic metallurgical suppliers or long-term offtake agreements with Ra 0.4 micrometer finish specialists. Defend against emerging IoT-native entrants by embedding sensor networks into existing clean-in-place architectures and locking in dairy cooperative standardization programs across merged Bavarian and Lower Saxony footprints. For New Entrants and Emerging Players: Lead with simplified manual-clean designs targeting bakery and beverage segments where contamination risk tolerance permits lower surface finish specifications and faster sales cycles. White-space opportunities concentrate in Netherlands-based toll processors scaling private-label output for German retailers, and in Italian meat processing clusters adopting tool-free bearing housings under tightened EU Regulation 853/2004 enforcement. Go-to-market angle: sub-15-minute disassembly documentation support for EFSA compliance. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors electropolished stainless steel specialists with validated 3-A Sanitary Standards certification pipelines and established relationships with dairy cooperative procurement committees. Long-term viability rests on defensible metallurgical expertise and regulatory validation capabilities rather than assembly scale. Acquisition target archetype: mid-cap orbital welding shops with certified technician benches and existing dairy contact surface portfolios. Signal to watch: German cooperative merger velocity and subsequent centralized tender issuance.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Electropolished Steel Supply | Captive Ra 0.4 micrometer finish capacity insulates margin from Nordic supplier concentration. |
| IoT Sensor Network Integration | Real-time biofilm detection in clean-in-place systems differentiates offerings for FSMA-compliant processors. |
| Orbital Welding Technician Certification Programs | Proprietary certified bench capacity addresses 40 percent wage premium scarcity in tight labor markets. |
| EU Green Deal Heat Recovery Upgrades | Heat exchanger efficiency improvements qualify for Danish and Swedish national decarbonization grants. |
| Contract Manufacturer Channel Partnerships | Centralized hygiene committee relationships unlock multi-site equipment standardization programs. |
Methodological Framework
Two parallel data streams informed the analysis: primary intelligence gathering and secondary source validation. Primary interviews engaged equipment engineering directors at dairy cooperatives, hygiene validation committee leads at Netherlands-based contract manufacturers, plant engineers at ready-to-eat specialists, orbital welding technicians, and procurement officers at metallurgical suppliers. Secondary sources drew from FDA FSMA guidance documents, EFSA hygiene guideline updates, 3-A Sanitary Standards certification records, EU Regulation 852/2004 enforcement bulletins, and SEC filings of listed processing equipment manufacturers. Bottom-up equipment shipment tallies triangulated against top-down dairy processing capacity expansion estimates.
Across the projection horizon, the analytical framework modeled demand across equipment type, surface finish grade, application contamination risk tier, and end-user procurement authority concentration. CAGRs were derived from replacement cycle compression rates, regulatory mandate implementation timelines, and cooperative merger-driven standardization program adoption curves. Industry-specific forecast inputs incorporated clean-in-place validation protocol evolution and electropolished stainless steel capacity expansion schedules.
The analysis sits within stated boundaries; outcomes outside sustained FSMA enforcement intensity, stable Nordic metallurgical supply, and continued dairy cooperative consolidation would require recalibration. Forecasts reflect documented assumptions regarding regulatory compliance cost pass-through and technician certification pipeline expansion. Practitioners should keep alternative scenarios live as EU hygiene guideline harmonization and German cooperative merger completion rates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Vacuum Cooling Equipment Market
Food Processing Equipment
Food Extruder Market
Food Processing Equipment
Commercial Winery Equipment Market
Food Processing Equipment
Pasteuriser Market
Food Processing Equipment
Chewing Gum Machine Market
Food Processing Equipment
Industrial Graters Market
Food Processing Equipment
Milk Sterilizer Machine Market
Food Processing Equipment
Global Snack Pellet Equipment Market
Food Processing Equipment
Residential Food Waste Disposer Market
Food Processing Equipment
Tortilla Machine Market
Food Processing Equipment
Commercial Oven for Bakery Market
Food Processing Equipment
Global Commercial Food Dehydrators Market
Food Processing Equipment
Cook Processor Market
Food Processing Equipment
Food Ultrasound Market
Food Processing Equipment
Soda Production Machine Market
Food Processing Equipment
Food Disinfection Equipment Market