
 Dual-Ovenable Cook Trays Market | 2026-2036
Dual-Ovenable Cook Trays Market Size, Share, and Industry Trends Forecast 2026-2036
Dual-Ovenable Cook Trays Market Foresight
The premium-commodity split in dual-ovenable cook trays is rebalancing as temperature tolerance thresholds and sustainability certifications separate high-performance aluminum and fiber grades from basic plastic alternatives. Sealed Air Corporation leverages its barrier film expertise to dominate temperature-stable lidding systems for premium trays. Sonoco Products Company anchors North American supply through integrated paperboard and fiber manufacturing. Huhtamaki Oyj competes across European retail channels with molded fiber ovenable formats.
Dual-ovenable cook trays are rigid or semi-rigid containers engineered to withstand both conventional and microwave oven temperatures without deformation, typically constructed from aluminum alloys, crystallized polyethylene terephthalate, or pressed natural fibers with silicone or polyester coatings to prevent moisture loss and structural failure during thermal cycling. Aluminum sheet and pre-formed product forms command the highest margin pools due to superior heat conductivity and established recycling infrastructure, while fiber-based rigid trays represent the fastest-growing category as food service operators eliminate per- and polyfluoroalkyl substance coatings under tightening chemical regulations. Plastic flexible formats retain volume in industrial baking applications where cost minimization outweighs sustainability mandates.
The U.S. FDA maintains strict migration limits for substances contacting food under thermal stress, while the EU REACH regulation and F-Gas Framework constrain fluorinated coating chemistries that historically enabled paperboard ovenability. China's SAMR enforces GB standards for composite food contact materials that dual-ovenable imports must satisfy for market access. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions across multiple jurisdictions to determine whether reformulation investments or material substitutions offer superior returns.
Market Dynamics
The European Union's Single-Use Plastics Directive is forcing rapid material migration across the dual-ovenable cook trays sector, compressing demand for crystallized polyethylene terephthalate while accelerating aluminum and fiber-based format adoption. Ready-to-eat meal manufacturers are requalifying entire packaging portfolios under tighter chemical compliance timelines.
Growth Catalysts
- EU F-Gas Framework:The regulation constrains fluorinated coating chemistries historically enabling paperboard ovenability, creating immediate substitution demand for silicone and polyester barrier alternatives in Germany and France.
- Centralized kitchen expansion:Industrial bakeries across Germany are consolidating procurement into high-volume dual-ovenable formats, pulling capacity toward temperature-tolerant aluminum sheet products.
- Per- and polyfluoroalkyl substance bans:REACH restrictions on PFAS coatings are eliminating incumbent fiber tray chemistries, forcing reformulation investments that favor suppliers with integrated barrier film capabilities.
Market Restraints
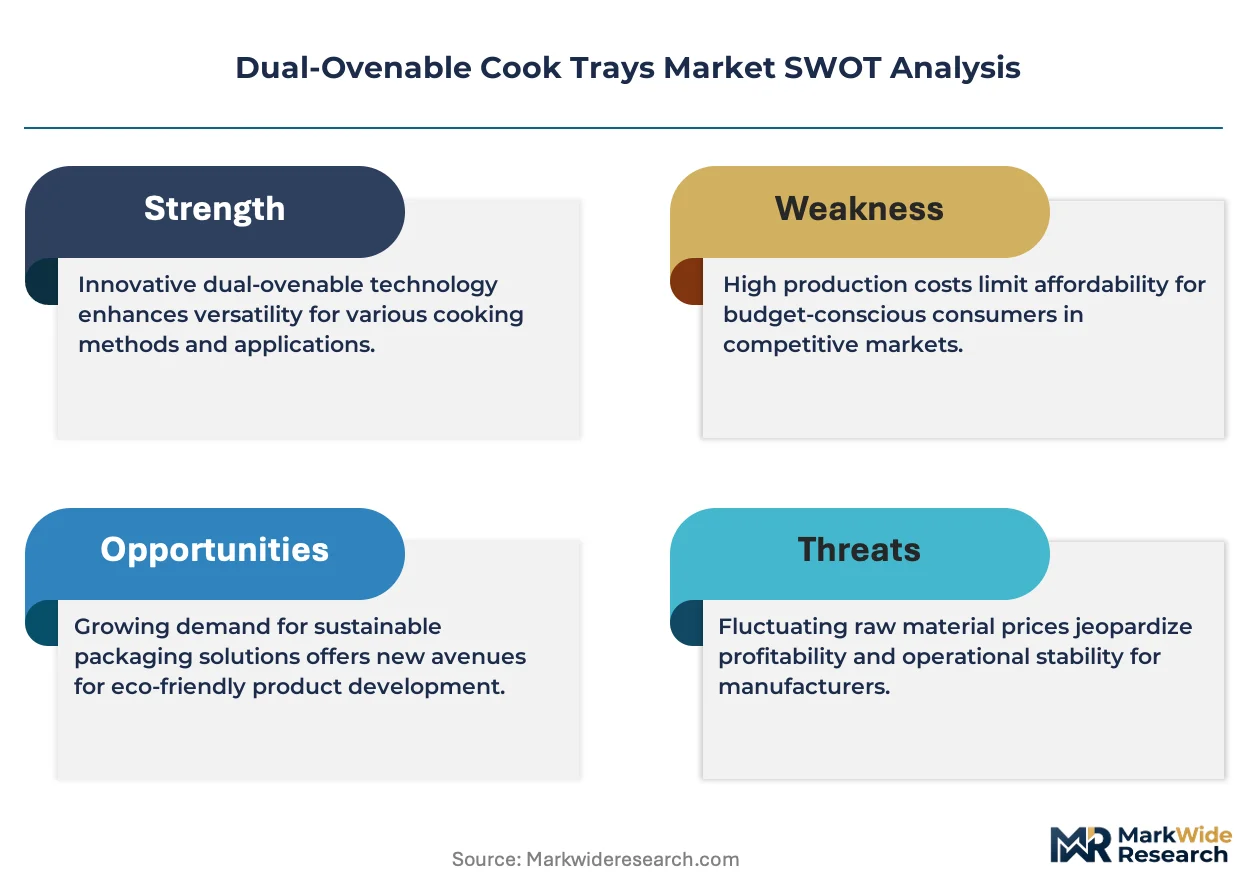
- Aluminum input volatility:Primary aluminum ingot pricing fluctuations compress margin pools for pre-formed tray manufacturers dependent on spot metal markets.
- German supply concentration:Industrial bakery demand clusters in Bavaria and Baden-Württemberg, creating geographic dependency risk for format suppliers without distributed molding assets.
- Technical limitation in fiber heat tolerance:Pressed natural fiber trays with silicone coatings fail above 220°C, excluding them from high-temperature convection applications where aluminum dominates.
Strategic Opportunities
- Underpenetrated France:Retail channel penetration of molded fiber ovenable formats remains below German levels, creating white space for barrier-integrated product launches.
- Regulatory tailwind from EU Green Deal:Packaging waste reduction targets incentivize fiber-based rigid tray adoption in food service channels seeking circular material credentials.
- Technology convergence:Barrier film expertise is integrating with pressed fiber molding, enabling moisture-retentive ovenable formats without fluorinated chemistries.
Industry Challenges
- Thermal cycling certification timelines:GB standards enforcement by China's SAMR requires extended migration testing for composite food contact materials, delaying market entry for European exporters.
- Coating reformulation capex:Eliminating per- and polyfluoroalkyl substances demands new silicone and polyester application lines, straining mid-cap fiber tray producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dual-Ovenable Cook Trays Market |
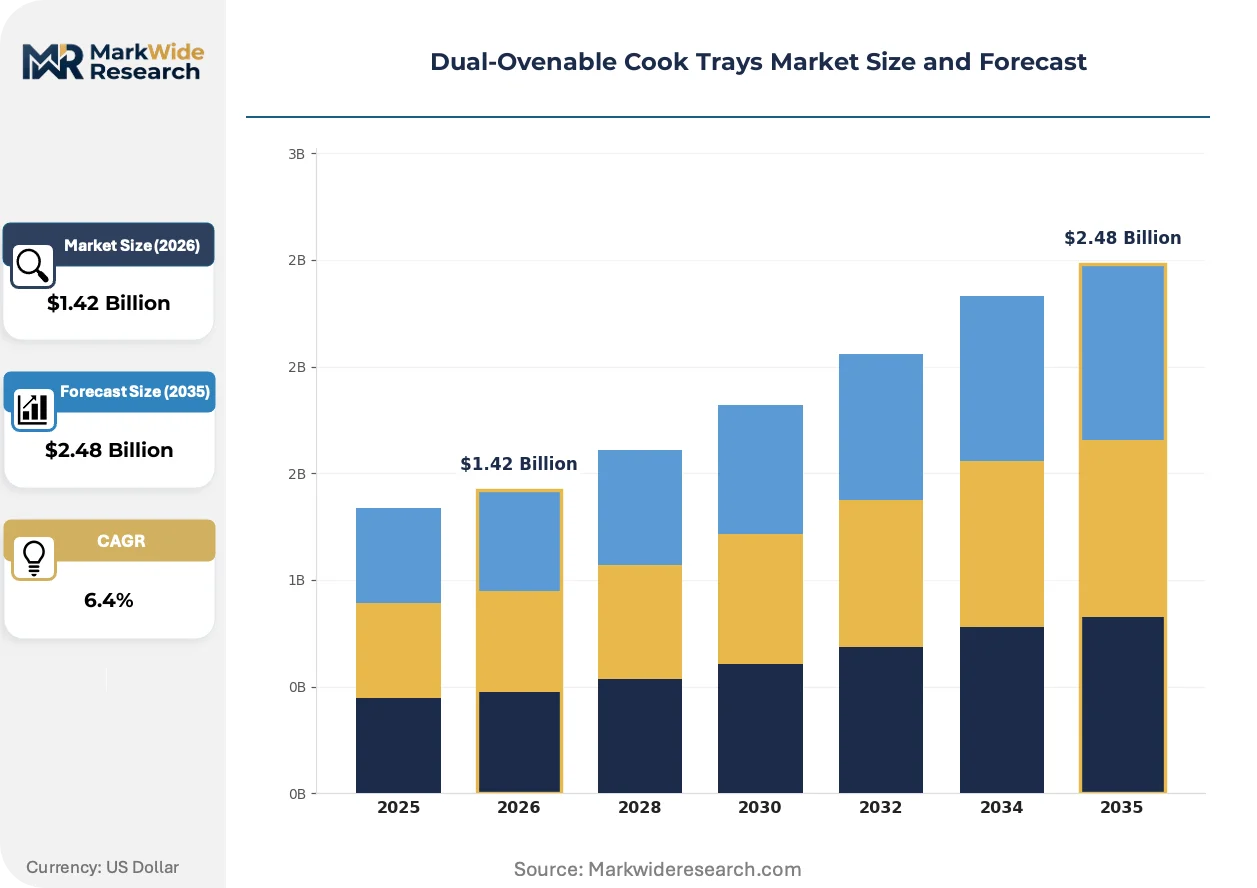
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.48 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Aluminum, Plastic, Paperboard, Fiber Product Form: Sheet, Pre-formed, Flexible, Rigid Target Application: Food Packaging, Industrial Baking, Retail Sales, Catering Distribution Channel: Wholesale, Retail, Online Sales, Direct Supply |
| Companies Covered | Sealed Air Corporation, Sonoco Products Company, Pactiv LLC, Amcor Plc, Sabert Corporation, Genpak LLC, Huhtamaki Oyj, DuPont Teijin Films U.S. Limited Partnership, Evergreen Packaging, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dual-Ovenable Cook Trays Market Shifts & Advancements
Material science advances and regulatory chemistry constraints are converging to reshape competitive positioning in dual-ovenable formats. Suppliers are racing to deliver temperature-stable barriers without legacy fluorinated coatings.
Silicone-polyester hybrid coatings are integrating into pressed natural fiber substrates to replace per- and polyfluoroalkyl substance barriers eliminated under REACH. German industrial bakeries are piloting these reformulated trays for ready-to-eat meal applications. The technology is integrating moisture retention performance with established recycling infrastructure, compressing the premium-commodity split in fiber-based formats.
REACH and the EU F-Gas Framework are systematically constraining fluorinated coating chemistries across food contact applications. Industrial consequences include accelerated R&D timelines for silicone and polyester alternatives and requalification costs for incumbent tray portfolios. Centralized kitchen operators in Germany are most affected, responding by consolidating procurement around suppliers with certified barrier film integration.
Ready-to-eat meal manufacturers are compressing supplier qualification cycles from 18 months to 9 months as sustainability mandates accelerate packaging portfolio overhauls. Direct procurement relationships with molded fiber specialists are displacing distributor-mediated sourcing in European retail channels. France and the Netherlands show the most visible demand rotation, with food service operators eliminating plastic alternatives ahead of regulatory deadlines.
Dual-Ovenable Cook Trays Market Segmentation
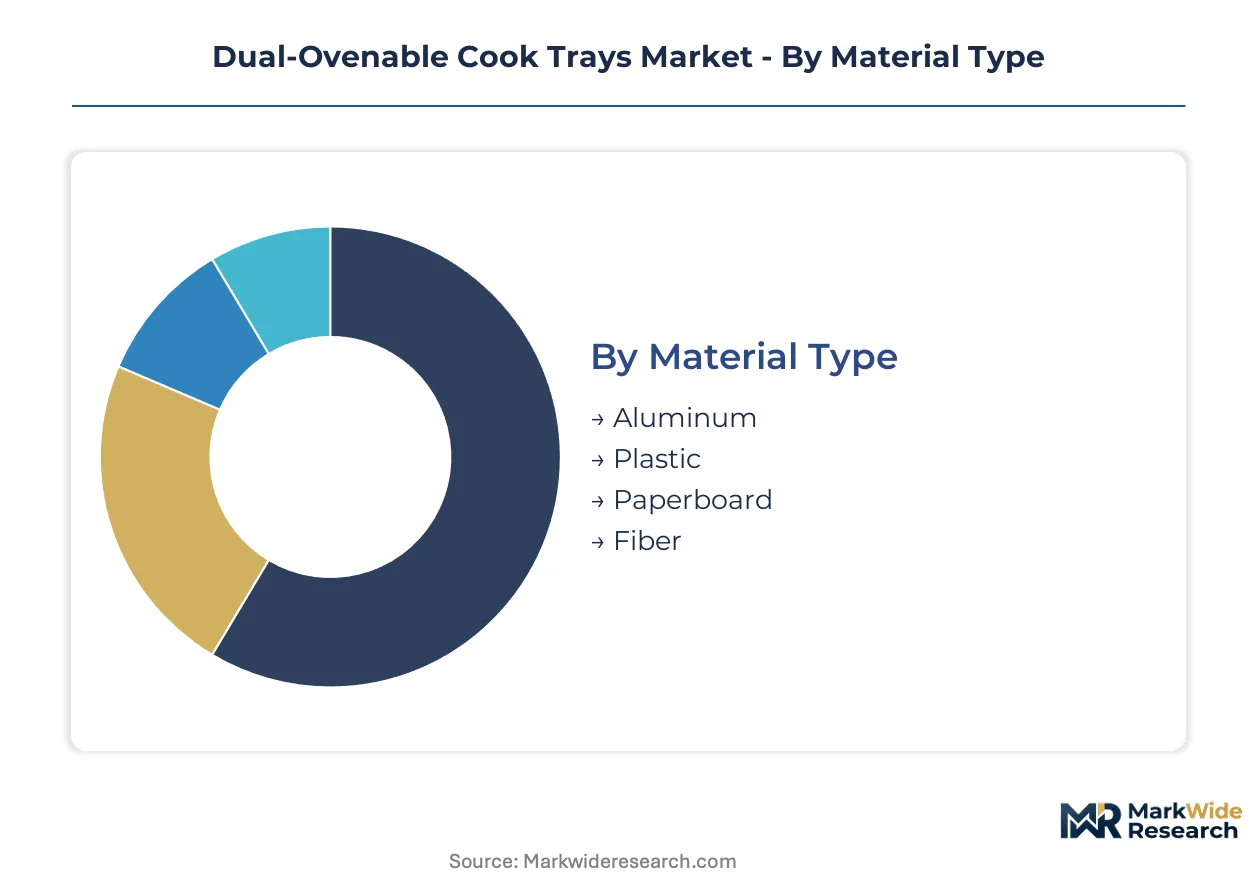
Material chemistry and thermal tolerance thresholds partition the dual-ovenable cook trays market into distinct compliance tiers. Each segment carries specific certification burdens from FDA migration limits, EU REACH restrictions, and China's GB standards for composite food contact materials.
Material Type:
Certification complexity escalates from metallic substrates to fiber-based alternatives, with aluminum requiring thermal conductivity validation while fiber demands barrier coating requalification under REACH PFAS constraints.
- Aluminum:Aluminum alloys deliver superior heat conductivity and withstand temperatures exceeding 400°C in convection applications. German industrial bakeries in Bavaria consolidate procurement around pre-formed aluminum sheet products for centralized kitchen operations. Leading the category by volume: Aluminum. Growing fastest: Fiber.
- Fiber:Pressed natural fibers with silicone or polyester coatings replace eliminated PFAS barriers under EU F-Gas Framework timelines. France and the Netherlands show accelerating food service adoption ahead of regulatory deadlines.
- Plastic:Crystallized polyethylene terephthalate retains industrial baking volume where cost minimization outweighs sustainability mandates.
- Paperboard:Paperboard substrates with barrier laminations serve retail ready-to-eat meal segments requiring moderate temperature tolerance.
Margin pools concentrate in aluminum due to established recycling infrastructure and premium pricing power in high-temperature applications.
Product Form:
Manufacturing scale and capital intensity separate sheet-based production from molded formats, with pre-formed trays requiring die tooling investment while flexible formats leverage existing extrusion assets.
- Pre-formed:Die-cut and stamped aluminum configurations command premium positioning in industrial bakery supply chains. German procurement consolidation favors suppliers with distributed molding assets across Baden-Württemberg and Bavaria.
- Sheet:Flat aluminum stock serves custom fabrication requirements in catering and food service channels with lower volume thresholds.
- Rigid:Molded fiber and aluminum trays integrate barrier film lidding systems for moisture-retentive ready-to-eat meal packaging.
- Flexible:Plastic films retain cost-sensitive industrial baking segments where thermal cycling demands remain below 180°C.
Pre-formed configurations dominate revenue contribution. Rigid fiber formats are expanding most quickly as PFAS elimination accelerates format substitution.
Target Application:
End-use thermal profiles and regulatory exposure determine format selection, with industrial baking demanding maximum temperature tolerance while retail channels prioritize circular material credentials.
- Industrial Baking:High-volume centralized kitchen operations in Germany require aluminum sheet and pre-formed products for convection oven compatibility above 220°C.
- Food Packaging:Ready-to-eat meal manufacturers compress supplier qualification cycles from 18 months to 9 months under sustainability mandate pressure.
- Retail Sales:Molded fiber ovenable formats penetrate French retail channels below German saturation levels, creating white space for barrier-integrated launches.
- Catering:Food service operators eliminate plastic alternatives ahead of EU Single-Use Plastics Directive enforcement timelines.
Industrial baking generates the highest absolute volume. Food packaging applications are climbing the fastest as ready-to-eat meal portfolios requalify under compressed timelines.
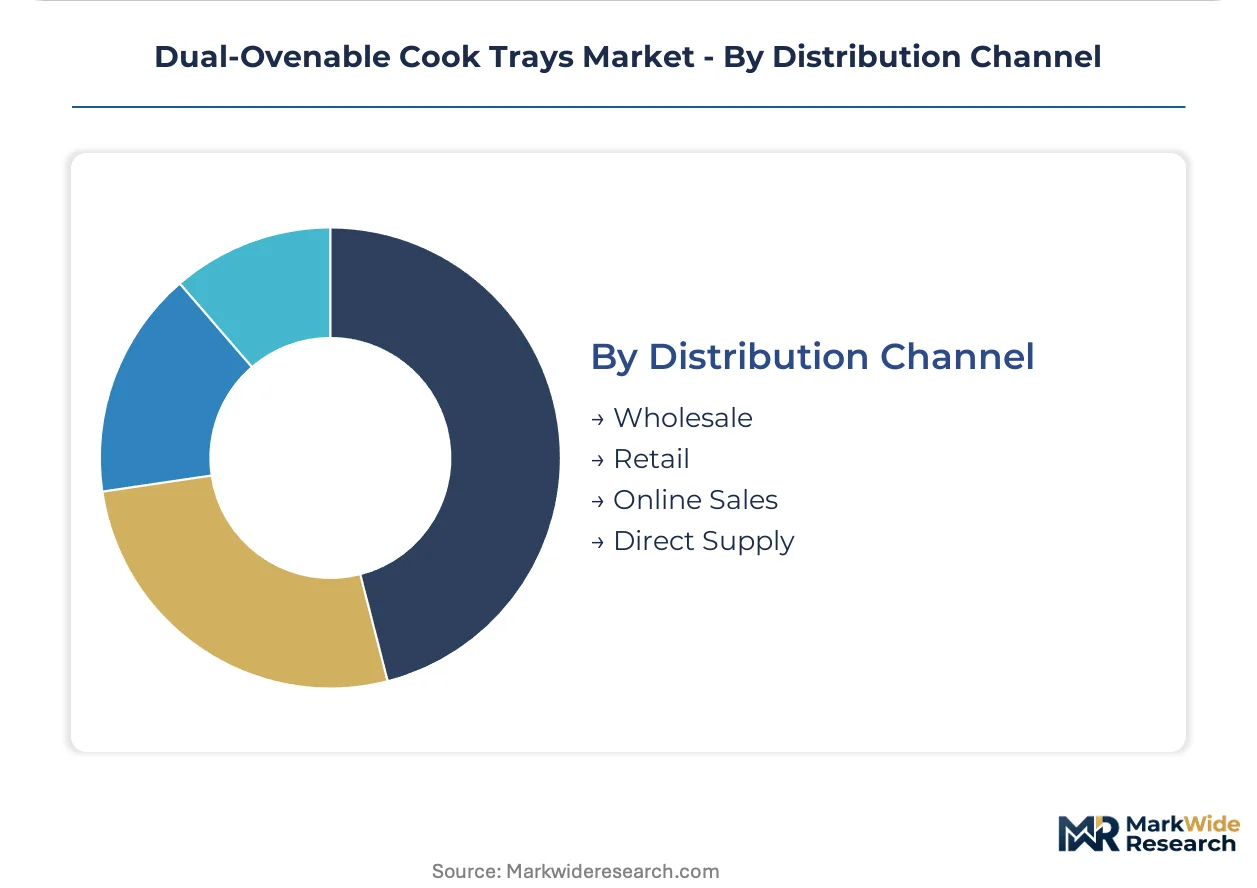
Distribution Channel:
Procurement consolidation patterns separate high-volume direct relationships from fragmented distributor-mediated sourcing, with sustainability mandates accelerating channel restructuring.
- Direct Supply:Ready-to-eat meal manufacturers establish direct procurement relationships with molded fiber specialists, displacing traditional distribution in European retail channels.
- Wholesale:Industrial bakery procurement consolidation in Germany concentrates volume through specialized foodservice distributors with temperature-certified inventory capabilities.
- Retail:Supermarket private label programs demand certified barrier film integration and established recycling infrastructure documentation.
- Online Sales:E-commerce channels serve small-format catering and specialty food producers with lower minimum order quantities.
Direct supply relationships are gaining share fastest as qualification timelines compress. Wholesale retains the largest volume position through industrial bakery concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bavaria's industrial bakery corridor anchors European demand for high-temperature dual-ovenable formats. Centralized kitchen operators in Munich and Nuremberg consolidate procurement around aluminum sheet products certified for convection applications exceeding 220°C.
Germany
Industrial bakeries in Bavaria and Baden-Württemberg drive volume concentration for pre-formed aluminum trays. The EU F-Gas Framework constrains fluorinated coating chemistries, forcing rapid requalification of fiber-based alternatives. Procurement consolidation in Stuttgart and Mannheim favors suppliers with distributed molding assets and REACH-compliant barrier film integration.
France
Food service operators in Paris and Lyon accelerate molded fiber adoption ahead of Single-Use Plastics Directive deadlines. ECHA restrictions on per- and polyfluoroalkyl substances eliminate incumbent paperboard chemistries. Retail channel penetration remains below German saturation levels, creating white space for silicone-polyester hybrid coating launches in the Île-de-France region.
United States
Ready-to-eat meal manufacturers compress supplier qualification cycles under sustainability mandate pressure. FDA migration limits for thermally stressed food contact materials constrain format selection. Flexible plastic formats retain volume in Chicago and Dallas industrial baking clusters where cost minimization outweighs circular material requirements.
China
SAMR enforcement of GB standards for composite food contact materials delays European exporter market entry. Extended migration testing timelines affect Shanghai and Guangzhou import channels. Domestic producers in the Yangtze River Delta leverage local supply chains to capture food packaging demand from centralized kitchen expansion.
Netherlands
Food service operators in Amsterdam and Rotterdam eliminate plastic alternatives ahead of regulatory enforcement. The EU Green Deal packaging waste reduction targets incentivize fiber-based rigid tray adoption. Rotterdam's port infrastructure supports aluminum sheet import flows serving Benelux industrial bakery networks.
Dual-Ovenable Cook Trays Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the dual-ovenable cook trays sector. The market structure fragments between integrated material manufacturers and specialized format converters. Three archetypes dominate: aluminum sheet specialists with captive smelter relationships, molded fiber innovators with barrier film integration capabilities, and diversified packaging conglomerates with multi-material portfolios. Competitive moves concentrate on coating reformulation partnerships and geographic capacity repositioning toward German industrial bakery clusters.
Within the barrier-integrated tier, Sealed Air Corporation and Huhtamaki Oyj exemplify divergent strategic positions. Sealed Air leverages film expertise to anchor temperature-stable lidding systems for premium tray applications. Huhtamaki competes across European retail channels with molded fiber ovenable formats. Sonoco Products Company represents the North American integrated paperboard archetype, anchoring supply through captive fiber manufacturing assets.
| Leading Market Players |
|---|
| Sealed Air Corporation |
| Sonoco Products Company |
| Pactiv LLC |
| Amcor Plc |
| Sabert Corporation |
| Genpak LLC |
| Huhtamaki Oyj |
| DuPont Teijin Films U.S. Limited Partnership |
| Evergreen Packaging |
| Others |
Supply & Pricing Matrix
Primary aluminum ingot pricing volatility cascades through pre-formed tray manufacturing tiers, compressing margin pools for converters dependent on spot metal markets while pushing industrial bakeries toward contract-based sheet procurement anchored in German supply clusters.
Pricing Analysis
Throughput-based pricing for high-temperature convection applications anchors value capture in aluminum sheet products, with German industrial bakeries paying premiums for certified 400°C tolerance. Price differentiation separates REACH-compliant silicone-polyester barrier coatings from legacy PFAS chemistries facing reformulation cost pass-through. Pricing pressure stems from aluminum input volatility and compressed qualification timelines. Food service operators in France and the Netherlands show highest price sensitivity, while centralized kitchen operators in Bavaria prioritize temperature certification over unit cost.
Supply Chain Analysis
REACH and FDA migration certification gates market entry for European exporters targeting US retail channels, forcing dual-qualification investments across barrier coating chemistries. Supply concentrates in Germany, China, and the United States, with German aluminum sheet production feeding Bavarian industrial bakery clusters. Raw material dependencies center on primary aluminum ingot, pressed natural fiber substrates, and silicone-polyester coating resins. Single-source vulnerability runs through fluorinated coating elimination timelines. Distribution runs through specialized foodservice distributors with temperature-certified inventory capabilities serving wholesale procurement consolidation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Silicone-polyester hybrid barrier coatings are displacing legacy PFAS chemistries across European fiber tray manufacturing, compressing supplier requalification windows and reshaping competitive positioning in temperature-stable formats.
For Market Incumbents: Acquire barrier film integration capabilities to defend margin pools against REACH-driven coating reformulation costs. Consolidate molding assets across Baden-Württemberg and Bavaria to match German procurement concentration. Prioritize silicone-polyester R&D partnerships over fluorinated chemistry retention as ECHA restrictions tighten. For New Entrants and Emerging Players: Technology-first barrier coating certification offers entry into underpenetrated French retail channels below German saturation levels. Target food service operators in Amsterdam and Rotterdam eliminating plastic alternatives ahead of EU Single-Use Plastics Directive enforcement. Pursue direct supply relationships with ready-to-eat meal manufacturers compressing qualification cycles. For Investors and Strategic Acquirers: ECHA's accelerated PFAS restriction timeline is the leading indicator that barrier-integrated fiber specialists will command acquisition premiums over commodity tray converters. Frame long-term viability around circular material credentials and established recycling infrastructure documentation. Watch for SAMR GB standard enforcement delays affecting European exporter market entry as the signal for domestic Chinese producer capture.| Strategic Initiative | Industry Significance |
|---|---|
| Barrier Coating Reformulation Partnership | REACH-compliant silicone-polyester integration replaces eliminated PFAS chemistries in German industrial bakery supply. |
| Geographic Capacity Repositioning | Distributed molding assets across Bavaria and Baden-Württemberg match centralized kitchen procurement consolidation patterns. |
| Direct Supply Relationship Establishment | Ready-to-eat meal manufacturers in France and the Netherlands displace distributor-mediated sourcing under compressed timelines. |
| Certification Investment Acceleration | FDA migration limits and SAMR GB standards require dual-qualification for US and China market access. |
| Circular Material Credential Development | EU Green Deal packaging waste targets incentivize fiber-based rigid tray adoption in food service channels. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across plant managers at aluminum sheet producers, procurement leads at German industrial bakeries, barrier coating R&D directors, food service distribution channel partners, and regulatory affairs specialists at packaging converters. Secondary sources included ECHA restriction dossiers, FDA food contact substance notifications, SAMR GB standard publications, EU F-Gas Framework implementation guidance, and trade flow databases. Bottom-up volume modeling triangulated against top-down market sizing.
Data-stream reconciliation across material type, product form, target application, and distribution channel dimensions shaped the analytical framework over the projection horizon. CAGRs derived from segment-level volume trajectories weighted by aluminum price elasticity, fiber substitution rates under PFAS elimination timelines, and food service channel penetration curves. Industry-specific inputs included REACH compliance cost pass-through assumptions and centralized kitchen capacity expansion pipelines.
Several conditions sit outside the modeled scope, including speculative aluminum tariff regimes, breakthrough high-temperature fiber formulations exceeding 220°C thresholds, and abrupt SAMR enforcement acceleration. Forecasts reflect documented assumptions about regulatory phase-in schedules and coating technology maturation curves. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Food Preservation Equipment Market
Food Processing Equipment
Magnetic Grill Market
Food Processing Equipment
Ice Cream Machine Market
Food Processing Equipment
Frozen Food Processing Machinery Market
Food Processing Equipment
Food Processing Blades Market
Food Processing Equipment
Steam Blanching Equipment Market
Food Processing Equipment
Global Conveyor Oven Market
Food Processing Equipment
Wine Bottling Machine Market
Food Processing Equipment
Mushroom Fermenter Market
Food Processing Equipment
Sandwich Preparation Refrigerators Market
Food Processing Equipment
Ribbon Blenders Market
Food Processing Equipment
Industrial Food and Beverages Filtration System Market
Food Processing Equipment
Vacuum Frying Machine Market
Food Processing Equipment
Edible Oil Extracting Machine Market
Food Processing Equipment
De-Agglomerating Equipment Market
Food Processing Equipment
Global Food Dehydrators Market