
 Food Processing Blades Market | 2026-2036
Food Processing Blades Market Size, Share, and Industry Trends Forecast 2026-2036
Food Processing Blades Market Intelligence
The gap between premium coated blades and commodity carbon steel replacements is expanding across food manufacturing procurement departments. Baucor leverages its precision grinding capabilities to anchor European bakery and slicing applications. Hyde Industrial Blade Solutions sustains dominant positions in North American meat processing through captive heat-treatment facilities. Simonds International competes on scale in fruit and vegetable cutting installations across industrial peeling lines.
Food processing blades are precision cutting implements manufactured from hardened stainless steel, carbon steel, ceramic, or titanium alloys with edge angles typically ground between 15 and 40 degrees depending on product abrasiveness and required cut geometry; these tools perform size reduction, portioning, or surface-texturing operations across protein, produce, and grain-based food matrices. Slicer and dicer blade categories command the widest installed base, while ceramic and titanium material segments capture disproportionate margin pools from allergen-sensitive and high-wear dairy applications. Meat processing and fruit and vegetable cutting applications generate the highest replacement frequency, with frozen food producers driving standardization toward quick-change blade systems.
FDA food contact surface regulations, USDA FSIS sanitation performance standards, and EU MDR-equivalent hygiene frameworks for food processing equipment collectively enforce material traceability and surface roughness thresholds that elevate replacement costs for non-compliant suppliers. China's SAMR national food safety standards and GB specifications for stainless steel food machinery impose parallel metallurgical testing burdens on blade imports. Stakeholders must monitor divergence between regional certification reciprocity and emerging national testing regimes when configuring supply chain footprints.
Market Dynamics
Automated blade replacement programs in German meat processing facilities are compressing replacement cycles and forcing suppliers to reconfigure service architectures around predictive maintenance contracts rather than transactional sales.
Growth Catalysts
- USDA FSIS Sanitation Performance Standards:Tightening surface-finish requirements for food-contact cutting tools are mandating premium-grade blade upgrades across US protein processing plants.
- Ceramic blade adoption in dairy:Allergen-sensitive production lines are specifying zirconia and alumina ceramic edges to eliminate metallic contamination risks in cheese and yogurt cutting operations.
- China's coastal manufacturing clusters:Integrated protein processing consolidation in Shandong and Jiangsu provinces is standardizing procurement around quick-change blade systems from single-source suppliers.
Market Restraints
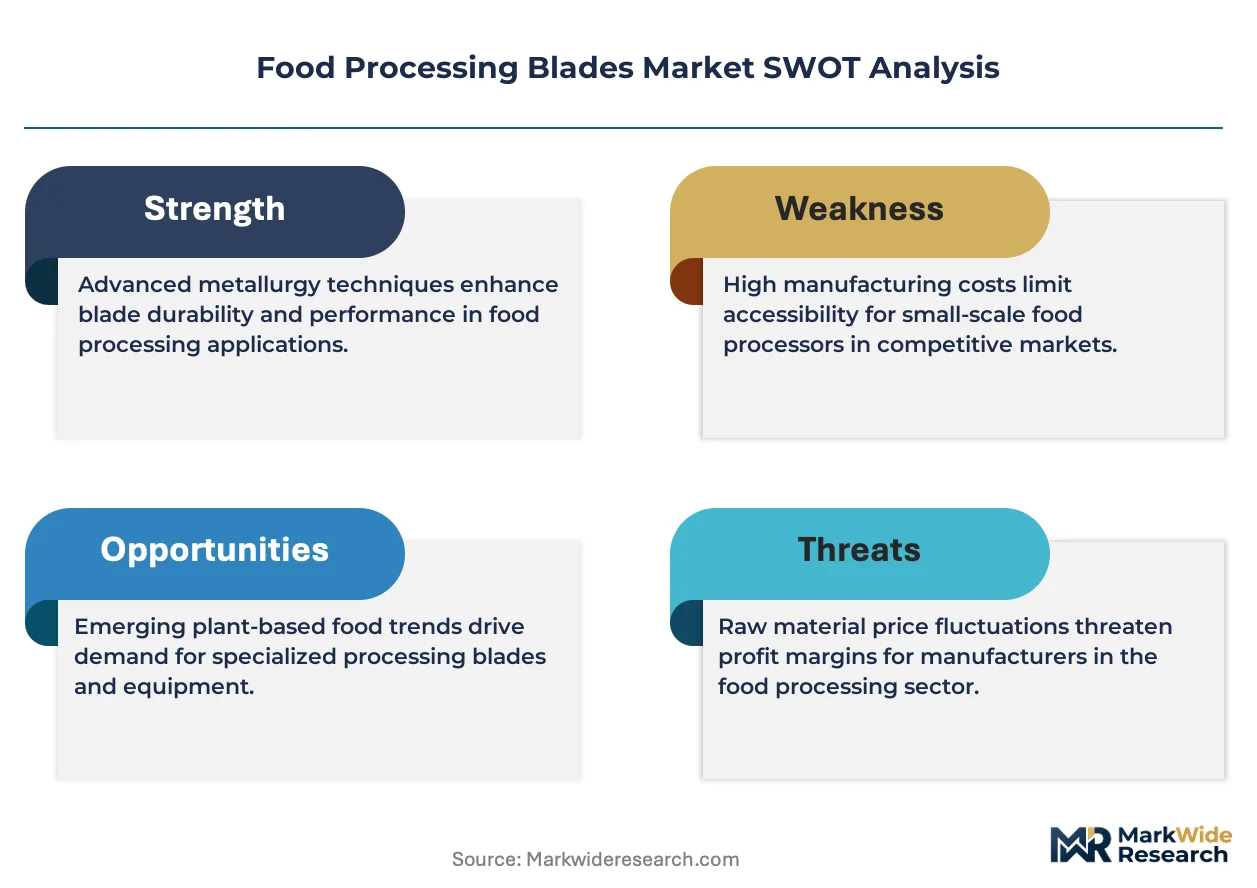
- Nickel and cobalt alloy volatility:Aerospace-grade titanium and superalloy input costs fluctuate with defense sector demand, squeezing margin on corrosion-resistant blade grades.
- Heat-treatment capacity concentration:Captive heat-treatment facilities in Germany and the United States create supply bottlenecks for independent blade manufacturers lacking in-house metallurgical capabilities.
- Laser cutting substitution:Waterjet and fiber laser systems are displacing mechanical blades in portioning applications above 50mm thickness, capping addressable market expansion.
Strategic Opportunities
- Plant-based protein processing:Extruded texturized vegetable protein cutting requires novel edge geometries that incumbent suppliers have not optimized, creating white space for specialized entrants.
- EU MDR-equivalent hygiene frameworks:Material traceability mandates are disqualifying non-compliant Asian imports, opening replacement volume for certified European producers.
- Direct-to-processor digital channels:E-procurement platforms are disintermediating traditional industrial distribution in mid-sized bakery and produce operations.
Industry Challenges
- Precision grinding technician scarcity:Master grinders capable of maintaining 15-40 degree edge tolerances on hardened stainless are retiring faster than apprenticeship programs replenish the workforce.
- Multi-certification compliance timelines:Simultaneous FDA, USDA, and EU MDR-equivalent approvals extend product launch cycles by 18-24 months for new blade geometries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Processing Blades Market |
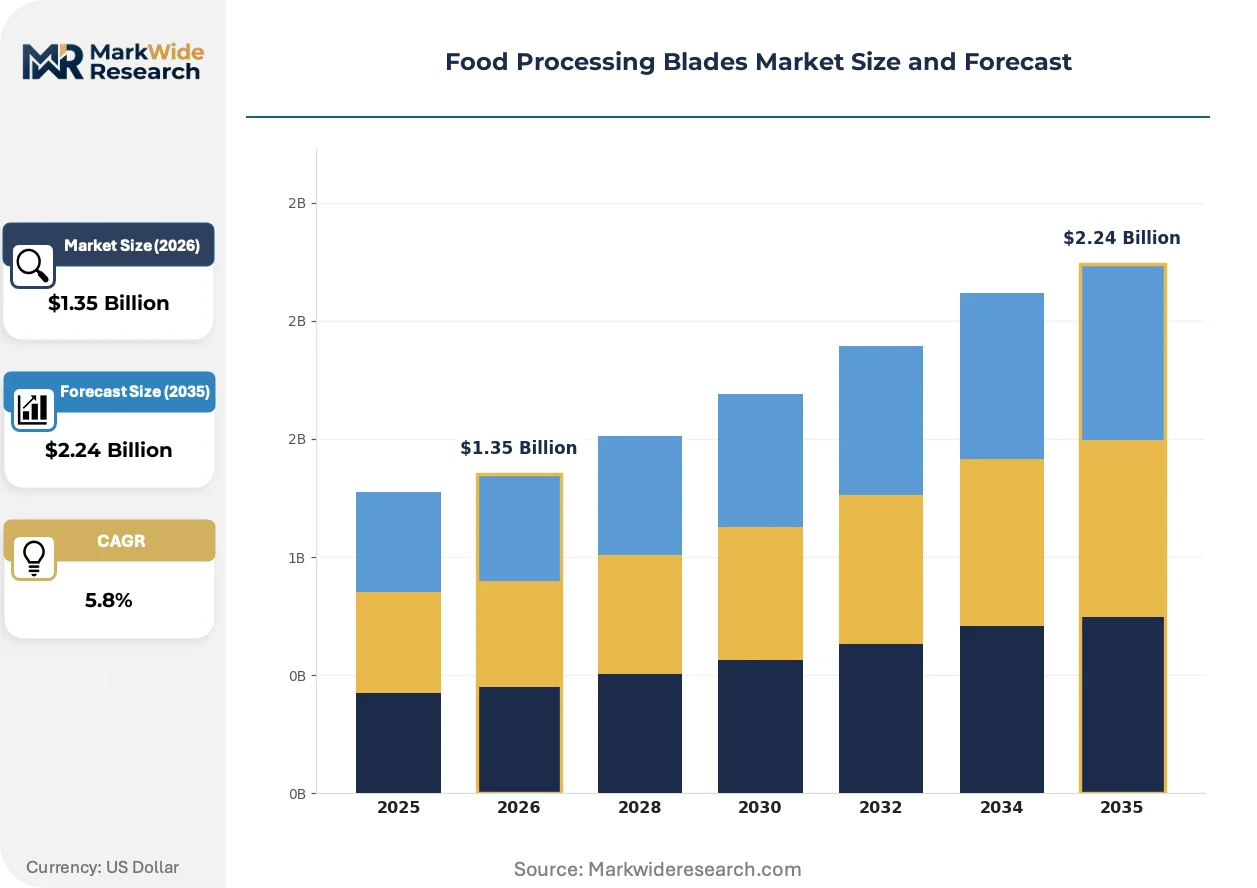
| Market Size in 2026 | $1.35 Billion |
| Market Size in 2035 | $2.24 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Blade Type: Slicer, Dicer, Chopper, Grater, Shredder, Peeler Material: Stainless Steel, Carbon Steel, Ceramic, Titanium, High-Speed Steel Application: Meat Processing, Bakery, Fruit & Vegetable Cutting, Dairy, Seafood Preparation End User: Food Manufacturers, Catering Services, Commercial Kitchens, Butcheries, Frozen Food Producers |
| Companies Covered | Hyde Industrial Blade Solutions, Baucor, Simonds International, Fortifi Food Processing Solutions, Norwood Commercial Products, Urschel Laboratories, Inc., Hamilton Knife Company, Grote Company, Dexter Russell, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Processing Blades Market Strategic Shifts & Innovations
Coating technologies and quick-change mounting systems are redefining blade lifecycle economics, while regulatory divergence between major markets fragments certification requirements.
Physical vapor deposition and diamond-like carbon coatings are extending edge retention in high-abrasion applications such as frozen meat and crusty bread slicing. Major bakery chains in France and Germany are specifying coated blades for 10,000+ hour service intervals. This performance tier is consolidating procurement decisions around total cost of ownership models rather than unit price.
EU MDR-equivalent hygiene frameworks for food processing equipment now enforce surface roughness thresholds below Ra 0.8 micrometers on all food-contact cutting tools. Blade manufacturers serving European meat and dairy processors must maintain batch-level material traceability from melt source to finished edge. German and Dutch protein processors are responding by qualifying only suppliers with integrated metallurgical testing laboratories.
Integrated procurement by protein processing clusters in China's coastal provinces is consolidating equipment decisions under single technical directors. Traditional distributor networks in Shandong and Jiangsu are losing access to plant-level specification authority. This concentration is most visible in automated slicing line deployments where blade selection is bundled with OEM maintenance contracts.
Food Processing Blades Market Segmentation
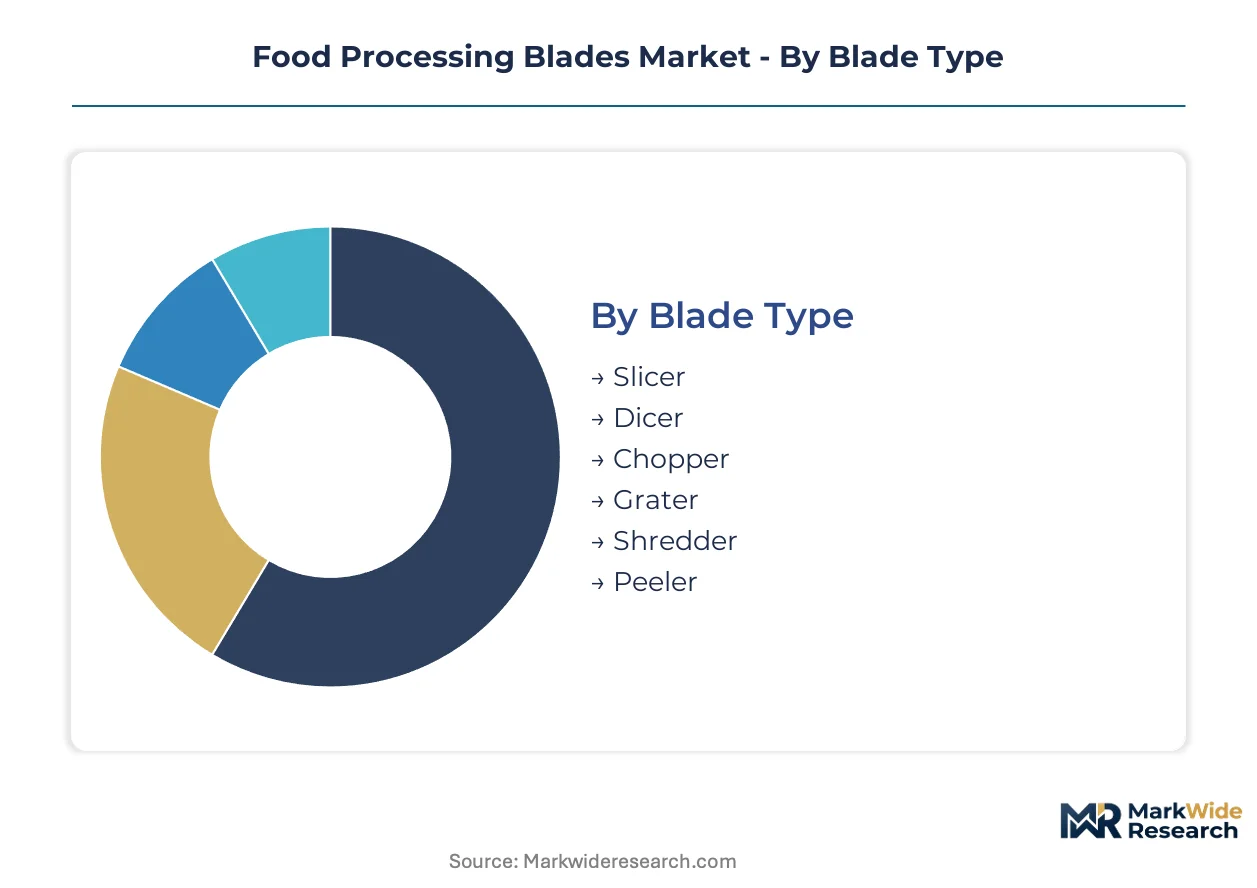
Blade specification in food processing hinges on three interlocking variables: the mechanical demands of the food matrix, the regulatory environment governing surface contact, and the replacement economics of automated versus manual changeout systems. Procurement departments now segment suppliers across these axes rather than treating blades as interchangeable commodities.
Blade Type:
Operational tempo and cut geometry separate high-volume automated facilities from batch-oriented processors.
- Slicer:Straight-edge and serrated configurations dominate portioning operations for deli meats and baked goods. German meat processors specify quick-change slicer mounts compatible with predictive maintenance platforms.
- Dicer:Grid and strip assemblies handle high-throughput vegetable and protein cube production. China's Shandong protein clusters are standardizing dicer blade procurement through single technical directors.
- Chopper:Curved and straight cleaver profiles serve coarse reduction in butcher shops and mid-scale catering operations.
- Grater:Rotary and planar drum designs target cheese and root vegetable surface-texturing in dairy and produce applications.
- Shredder:Fine and coarse julienne edges support coleslaw, cheese, and prepared salad manufacturing lines.
- Peeler:Scalloped and straight profiles remove skins from tubers and fruits in industrial peeling installations.
Volume sits with Slicer; growth tilts toward Dicer.
Material:
Surface-finish mandates and allergen protocols are fragmenting material selection across regulatory jurisdictions.
- Stainless Steel:Austenitic grades dominate food-contact applications with Ra 0.8 micrometer surface roughness compliance. FDA and USDA FSIS sanitation standards enforce batch-level traceability for stainless melt sources.
- Ceramic:Zirconia and alumina compositions eliminate metallic contamination risks in allergen-sensitive dairy cutting. EU MDR-equivalent hygiene frameworks accelerate ceramic specification for cheese and yogurt operations.
- Carbon Steel:High-carbon grades retain sharpness in low-corrosion bakery and dry goods applications.
- Titanium:Aerospace-grade alloys command premium positioning in high-chloride seafood environments.
- High-Speed Steel:Cobalt-enhanced formulations serve frozen product cutting where abrasion resistance trumps corrosion concerns.
Procurement weight rests with Stainless Steel; margin expansion clusters around Ceramic.
Application:
Replacement frequency and edge geometry complexity vary sharply across food matrices.
- Meat Processing:Automated replacement programs in German facilities compress blade cycles. USDA FSIS surface-finish tightening mandates premium-grade upgrades across US protein plants.
- Fruit & Vegetable Cutting:Abrasive silica content in produce accelerates edge degradation. Industrial peeling lines in the Netherlands specify coated blades for extended service intervals.
- Bakery:Crusty bread slicing demands coated edges with 10,000+ hour durability. French bakery chains are consolidating procurement around total cost of ownership models.
- Dairy:Allergen-sensitive production lines specify ceramic edges to eliminate metallic contamination.
- Seafood Preparation:High-chloride environments drive titanium and superalloy specification despite input cost volatility.
Replacement volume concentrates in Meat Processing; specification complexity expands fastest in Dairy.
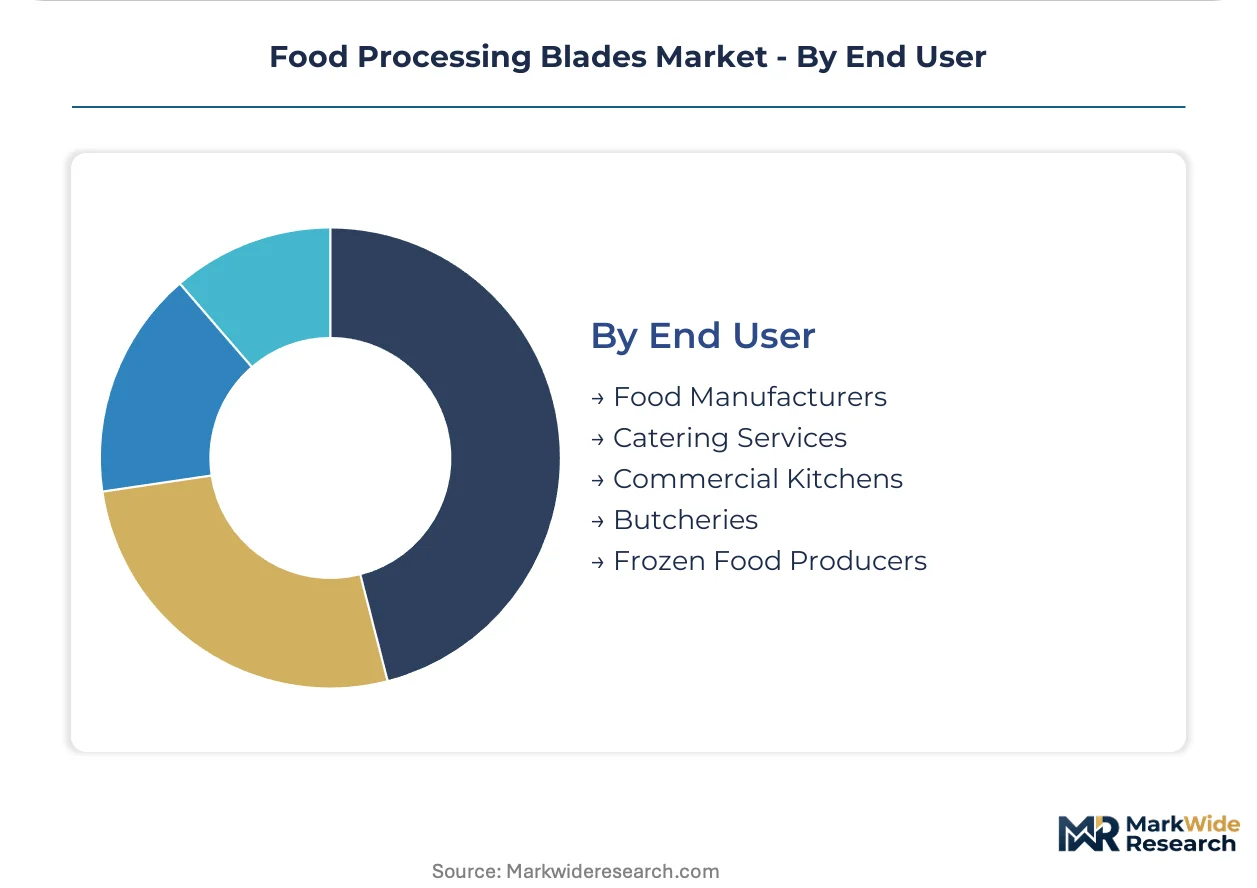
End User:
Scale and technical staffing determine whether buyers prioritize unit economics or lifecycle contracting.
- Food Manufacturers:Integrated coastal clusters in Jiangsu province bundle blade selection with OEM maintenance contracts. E-procurement platforms are disintermediating traditional distribution in mid-scale operations.
- Frozen Food Producers:Standardization toward quick-change blade systems reduces line downtime in high-volume portioning.
- Catering Services:Batch-oriented operations favor economical carbon steel replacement over coated premium tiers.
- Commercial Kitchens:Mixed-use facilities require versatile blade geometries across protein, produce, and grain applications.
- Butcheries:Manual changeout systems persist where automated infrastructure investment is uneconomical.
Contract value aggregates with Food Manufacturers; service intensity peaks with Frozen Food Producers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shandong and Jiangsu provinces anchor blade demand through integrated protein processing clusters that bundle equipment procurement under single technical directors. Coastal manufacturing consolidation in these provinces is standardizing specifications around quick-change blade systems. This concentration pattern repeats across four additional national markets with distinct regulatory and industrial drivers.
United States
USDA FSIS sanitation performance standards are tightening surface-finish requirements for food-contact cutting tools in protein processing plants. FDA food contact surface regulations enforce batch-level material traceability from melt source to finished edge. Midwest meatpacking corridors in Nebraska and Iowa are mandating premium-grade blade upgrades to maintain compliance.
Germany
Automated blade replacement programs in Bavarian and North Rhine-Westphalian meat processing facilities are compressing replacement cycles toward predictive maintenance contracts. EU MDR-equivalent hygiene frameworks enforce surface roughness thresholds below Ra 0.8 micrometers on all food-contact cutting tools. Stuttgart-area protein processors are qualifying only suppliers with integrated metallurgical testing laboratories.
China
SAMR national food safety standards and GB specifications for stainless steel food machinery impose metallurgical testing burdens on blade imports. Integrated coastal clusters in Shandong and Jiangsu provinces are consolidating equipment decisions under single technical directors. Qingdao and Yantai protein processing hubs are standardizing procurement around quick-change blade systems from single-source suppliers.
France
Major bakery chains in Île-de-France and Auvergne-Rhône-Alpes are specifying coated blades for extended service intervals exceeding 10,000 hours. EU MDR-equivalent hygiene frameworks accelerate ceramic specification for cheese and yogurt cutting operations in allergen-sensitive production lines. Lyon-area dairy processors are consolidating procurement around total cost of ownership models rather than unit price.
Netherlands
Industrial peeling lines in Noord-Brabant and Zuid-Holland are specifying coated blades for extended service intervals in abrasive produce applications. EU hygiene frameworks enforce material traceability mandates that disqualify non-compliant Asian imports. Rotterdam-port logistics clusters are opening replacement volume for certified European producers with integrated testing capabilities.
Food Processing Blades Market Key Industry Players
Premium-margin players sit above commodity-margin players across coating technology and metallurgical certification tiers. The vendor base organizes into three functional tiers: precision grinding specialists with captive heat-treatment facilities, scale-driven fabricators competing on volume in fruit and vegetable installations, and ceramic-edge innovators serving allergen-sensitive dairy applications. Consolidation pressure is intensifying through backward integration into metallurgical testing and geographic expansion into China's coastal manufacturing clusters.
Within the precision grinding tier, Baucor and Hyde Industrial Blade Solutions occupy positions anchored by European and North American manufacturing footprints respectively. Simonds International exemplifies the scale-driven archetype competing across industrial peeling and portioning lines. These three entities represent the dominant competitive positioning vectors: metallurgical certification depth, regional manufacturing proximity, and volume-scale production economics.
| Leading Market Players |
|---|
| Hyde Industrial Blade Solutions |
| Baucor |
| Simonds International |
| Fortifi Food Processing Solutions |
| Norwood Commercial Products |
| Urschel Laboratories, Inc. |
| Hamilton Knife Company |
| Grote Company |
| Dexter Russell |
| Others |
Cost & Logistics Intelligence
Master precision grinders concentrated in Stuttgart and Solingen anchor labor-cost differentials that widen pricing-tier spreads between European-certified premium blades and commodity carbon steel replacements. This workforce scarcity forces buyers into total-cost-of-ownership calculations that privilege predictive maintenance contracts over transactional procurement.
Pricing Analysis
Value-based pricing anchored to line uptime and yield throughput dominates automated meat processing contracts in Germany and the United States. Three-tier pricing structure across premium, standard, and economy levels separates FDA-compliant coated blades from uncertified Asian imports and carbon steel bakery knives. Cost compression in the economy tier is intensifying because Chinese coastal clusters bundle blade selection with OEM maintenance contracts. Frozen food producers exhibit lowest price sensitivity due to downtime costs, while mid-scale catering services gravitate toward commodity replacements.
Supply Chain Analysis
Single-source vulnerability sits with aerospace-grade titanium suppliers in the United States and Germany facing defense sector demand spikes. Raw material sourcing draws from Swedish stainless steel melt shops, Chinese rare earth processors for ceramic zirconia, and Japanese cobalt-enhanced high-speed steel foundries. Tariff exposure on Chinese ceramic imports creates supply uncertainty for dairy processors specifying allergen-free edges. Distribution runs through OEM maintenance contracts in coastal Chinese clusters and industrial distributors in European bakery markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where EU MDR-equivalent hygiene frameworks erect barrier-to-entry moats favoring certified European producers with integrated metallurgical laboratories.
For Market Incumbents: Deepen backward integration into captive heat-treatment facilities to defend against laser cutting substitution in portioning applications above 50mm thickness. Fortify certification depth across FDA, USDA FSIS, and EU hygiene frameworks to disqualify non-compliant Asian imports from European dairy contracts. For New Entrants and Emerging Players: Capture white space in plant-based protein processing where extruded texturized vegetable protein cutting demands novel edge geometries incumbent suppliers have not optimized. Penetrate China's Shandong and Jiangsu coastal clusters through direct e-procurement platforms disintermediating traditional distributor networks. For Investors and Strategic Acquirers: The window for entry favors precision grinding specialists with metallurgical certification depth and regional manufacturing proximity to protein processing hubs. Long-term viability hinges on consolidation plays targeting European producers with integrated testing capabilities. Watch ceramic blade adoption rates in allergen-sensitive dairy lines as inflection signal for margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Heat-Treatment | Captive metallurgical capabilities satisfy EU MDR-equivalent traceability mandates for German meat processors. |
| Ceramic Edge Technology Investment | Zirconia and alumina compositions capture premium positioning in allergen-sensitive cheese and yogurt operations. |
| Predictive Maintenance Platform Launch | Service-contract economics displace transactional blade sales in Bavarian automated replacement programs. |
| Direct E-Procurement Channel Expansion | Digital disintermediation accesses mid-scale bakery and produce operations bypassing traditional distributors. |
| Multi-Certification Compliance Investment | Simultaneous FDA, USDA, and EU approvals extend addressable market for new blade geometries. |
Research Approach
Document review covered FDA food contact surface regulations, USDA FSIS sanitation performance standards, EU MDR-equivalent hygiene frameworks, and SAMR national food safety standards, complemented by interviews with maintenance directors at protein processing facilities, procurement leads at bakery chains, OEM blade specification engineers, and aftermarket service heads. Secondary validation drew from customs trade data, SEC filings of listed industrial blade manufacturers, and equipment procurement databases. Bottom-up blade unit demand estimates triangulated against top-down market value reconstructions.
Cross-referencing historical replacement cycle data against expert panel inputs on predictive maintenance adoption shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include blade type, material grade, application matrix, and end-user scale tier. CAGRs derived from regression analysis of replacement frequency trends and premium material penetration curves. Industry-specific inputs encompassed laser cutting substitution rates in thick portioning and ceramic specification velocity in dairy allergen protocols.
The model holds under stable regulatory reciprocity between FDA, USDA, and EU hygiene frameworks; deviation in national testing regime divergence or aerospace alloy demand spikes would shift replacement cost assumptions. Forecasts reflect documented assumptions about automation adoption and certification compliance timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Wine Crusher Market
Food Processing Equipment
Global Powder Processing Equipment Market
Food Processing Equipment
Decanter Centrifuge Market
Food Processing Equipment
Global Meat Mixer Market
Food Processing Equipment
Brewery Equipment Market
Food Processing Equipment
Bottling Machinery Market
Food Processing Equipment
Pet Food Extrusion Market
Food Processing Equipment
Mushroom Fermenter Market
Food Processing Equipment
Food Slicer and Dicer Market
Food Processing Equipment
China Industrial Food and Beverages Filtration System Market
Food Processing Equipment
Craft Brewery Equipment Market
Food Processing Equipment
Commercial Winery Equipment Market
Food Processing Equipment
Sous Vide Cooking Appliances Market
Food Processing Equipment
Global Commercial Refrigeration Market
Food Processing Equipment
Pizza Preparation Refrigerator Market
Food Processing Equipment
Tunnel Oven Market