
 Fish Deboning Machine Market | 2026-2036
Fish Deboning Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Fish Deboning Machine Market Foresight
Aftermarket service revenue is rewriting profitability expectations for original equipment makers. Marel leverages its integrated software-hardware ecosystem to capture recurring diagnostics contracts across Nordic processing hubs. Baader anchors its position through captive spare-part networks that reduce client downtime during peak salmon seasons. Kroma competes via specialized refurbishment programs that extend machine life cycles for mid-scale fishery cooperatives.
A fish deboning machine mechanically separates edible flesh from skeletal structure using precision blade arrays, conveyor-fed pressure rollers, or ultrasonic oscillation systems operating at frequencies between 20-40 kHz to minimize tissue damage while maximizing yield recovery. Electromechanical systems dominate installed bases due to proven reliability in high-throughput salmon and whitefish operations, though ultrasonic configurations are gaining traction where premium fillet integrity commands price premiums. Pneumatic technology occupies a mature niche in smaller processing factories where compressed-air infrastructure already exists, while vacuum-assisted deboning is emerging in specialty seafood retailers seeking minimal-waste portioning for direct consumer sales.
EU F-Gas Regulation compliance costs are redirecting R&D budgets toward refrigerant-free cooling architectures in integrated processing lines. FDA HACCP protocols and EFSA hygiene standards mandate stainless-steel contact surfaces with clean-in-place capability, effectively filtering out non-compliant entrants from transatlantic supply chains. Stakeholders must monitor how Norway's dual carbon goals and Iceland's fishery cooperative consolidation reshape equipment procurement cycles and service contract structures.
Market Dynamics
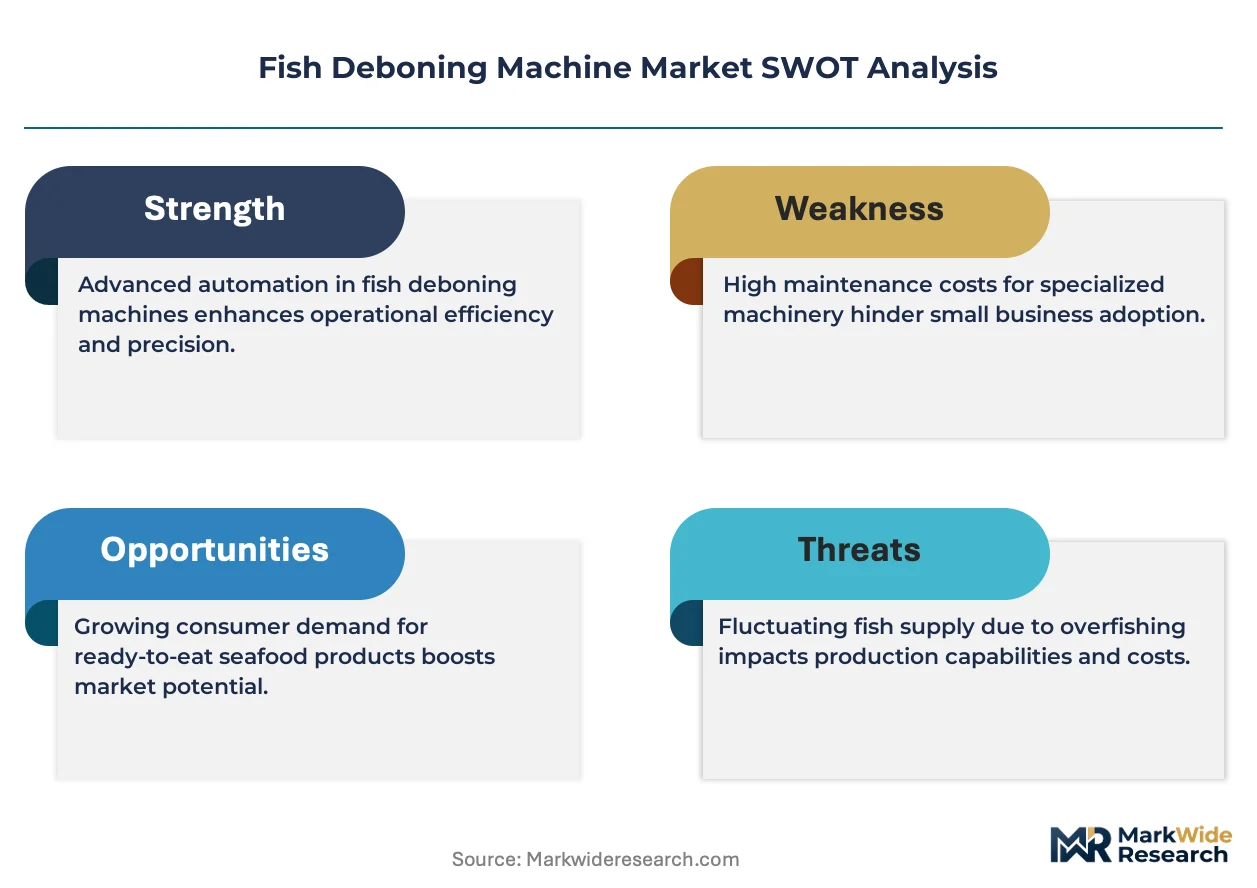
EU F-Gas Regulation compliance is forcing equipment manufacturers to redesign refrigerant-dependent cooling systems integrated with deboning lines, redirecting capital toward alternative thermal management architectures while compressing development timelines for integrated processing solutions.
Growth Catalysts
- Atlantic salmon processing concentration:Norway's fishery cooperatives are modernizing shore facilities in tandem with fleet upgrades, creating synchronized demand windows for automated deboning installations.
- REACH chemical safety protocols:Stainless-steel contact surface mandates under EFSA hygiene standards are filtering non-compliant entrants from transatlantic supply chains, consolidating procurement toward certified equipment vendors.
- Ultrasonic oscillation adoption:Frequencies between 20-40 kHz are minimizing tissue damage in premium fillet operations, commanding price premiums that justify equipment replacement cycles.
Market Restraints
- Refrigerant transition costs:EU F-Gas Regulation phase-down schedules are imposing R&D budget reallocations that extend payback periods for integrated cooling-deboning system investments.
- Pneumatic infrastructure lock-in:Smaller processing factories with existing compressed-air systems face technical debt barriers when evaluating electromechanical system upgrades.
- Yield rate volatility:Species-specific bone density variations in whitefish versus salmon limit universal machine configurations, constraining equipment utilization rates across seasonal catch rotations.
Strategic Opportunities
- Refurbishment program expansion:Specialized machine life-cycle extension services for mid-scale fishery cooperatives are capturing margin pools that original equipment sales cannot access.
- Vacuum-assisted deboning emergence:Specialty seafood retailers seeking minimal-waste portioning for direct consumer sales represent an underpenetrated channel requiring compact footprint configurations.
- Icelandic cooperative consolidation:Fishery merger activity is restructuring procurement authority toward centralized technical specifications that favor integrated service contracts over transactional equipment sales.
Industry Challenges
- Clean-in-place engineering complexity:FDA HACCP protocol compliance for stainless-steel contact surfaces demands specialized sanitation system integration that extends commissioning timelines.
- Diagnostics talent scarcity:Recurring service contract profitability depends on field technician availability for software-hardware ecosystem maintenance across remote Nordic processing hubs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fish Deboning Machine Market |
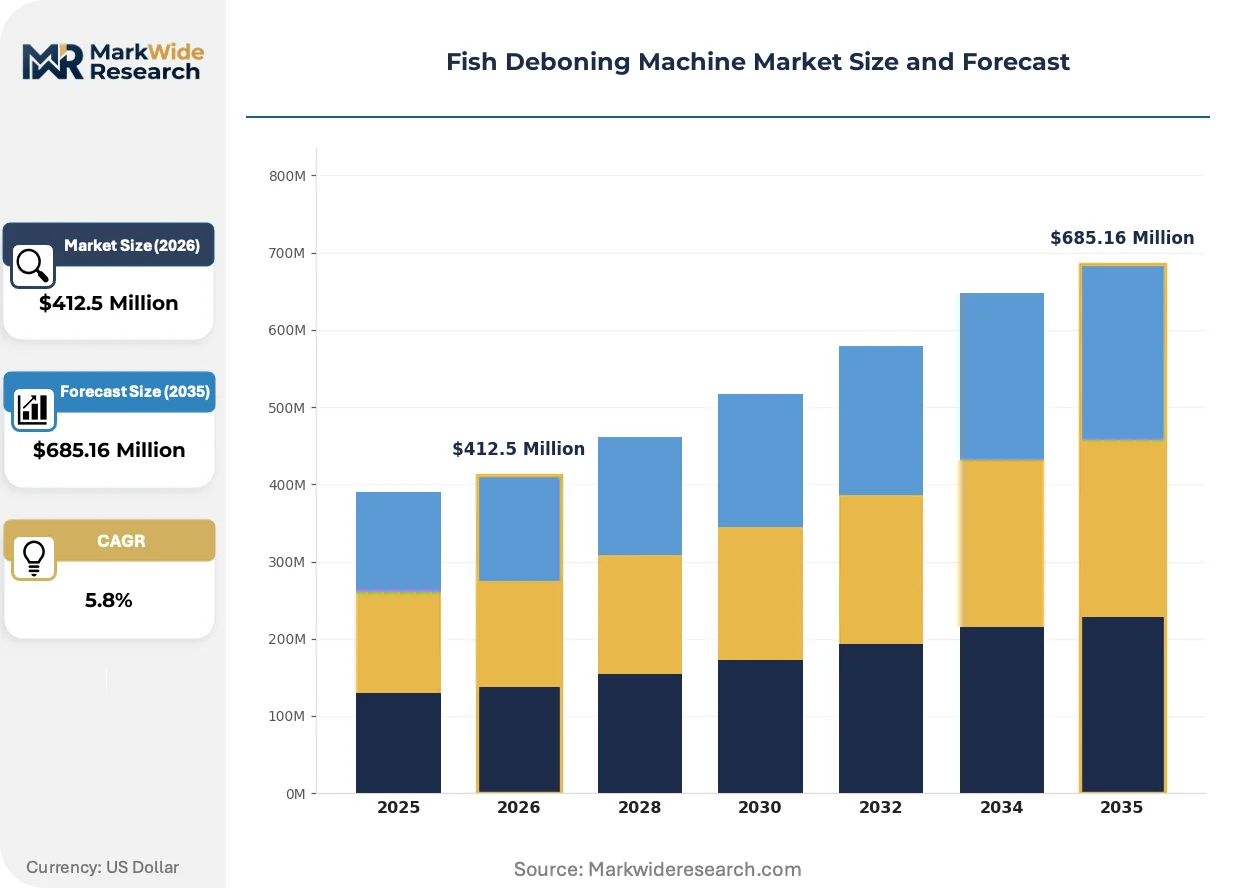
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $685.16 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic Deboning Machine, Semi-Automatic Deboning Machine, Manual Deboning Machine, Portable Deboning Unit Technology: Electromechanical, Pneumatic, Hydraulic, Ultrasonic, Vacuum Assisted Application: Fish Processing Plants, Seafood Packaging, Foodservice Industry, Specialty Seafood Retailers, Culinary Schools End User: Cold Storage Operators, Fishery Cooperatives, Processing Factories, Frozen Food Manufacturers |
| Companies Covered | Arenco, Kroma, Marel, Cretel, Ryco Equipment, Baader, Norbech, Cabinplant, JBT FoodTech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fish Deboning Machine Market Shifts & Advancements
Equipment architecture is converging around yield optimization and thermal management integration, with regulatory pressure and buyer consolidation accelerating technology substitution cycles beyond traditional replacement timelines.
Ultrasonic oscillation systems operating at 20-40 kHz are collapsing the tissue damage trade-off that previously forced processors to choose between throughput volume and fillet integrity. Premium salmon and whitefish operations in Norway's Atlantic processing corridor are adopting these configurations at compressed implementation schedules. The structural consequence is collapsing the price premium window that electromechanical systems previously commanded in mid-tier operations.
EU F-Gas Regulation phase-down mandates are prohibiting hydrofluorocarbon refrigerants in integrated cooling-deboning lines, forcing equipment makers toward ammonia or CO2-based thermal architectures. Industrial consequence includes extended validation periods for new cooling system integrations. Norwegian and Icelandic processing facilities face the most acute compliance deadlines, with cooperatives accelerating procurement of refrigerant-free configurations ahead of regulatory enforcement dates.
Buyer concentration within fishery cooperatives is compressing vendor negotiation cycles from multi-year equipment evaluations to consolidated technical specification rounds. Integrated diagnostics and spare-part availability are displacing standalone equipment pricing as primary selection criteria. This pattern is most visible across Nordic processing hubs where cooperative mergers have centralized procurement authority.
Fish Deboning Machine Market Segmentation
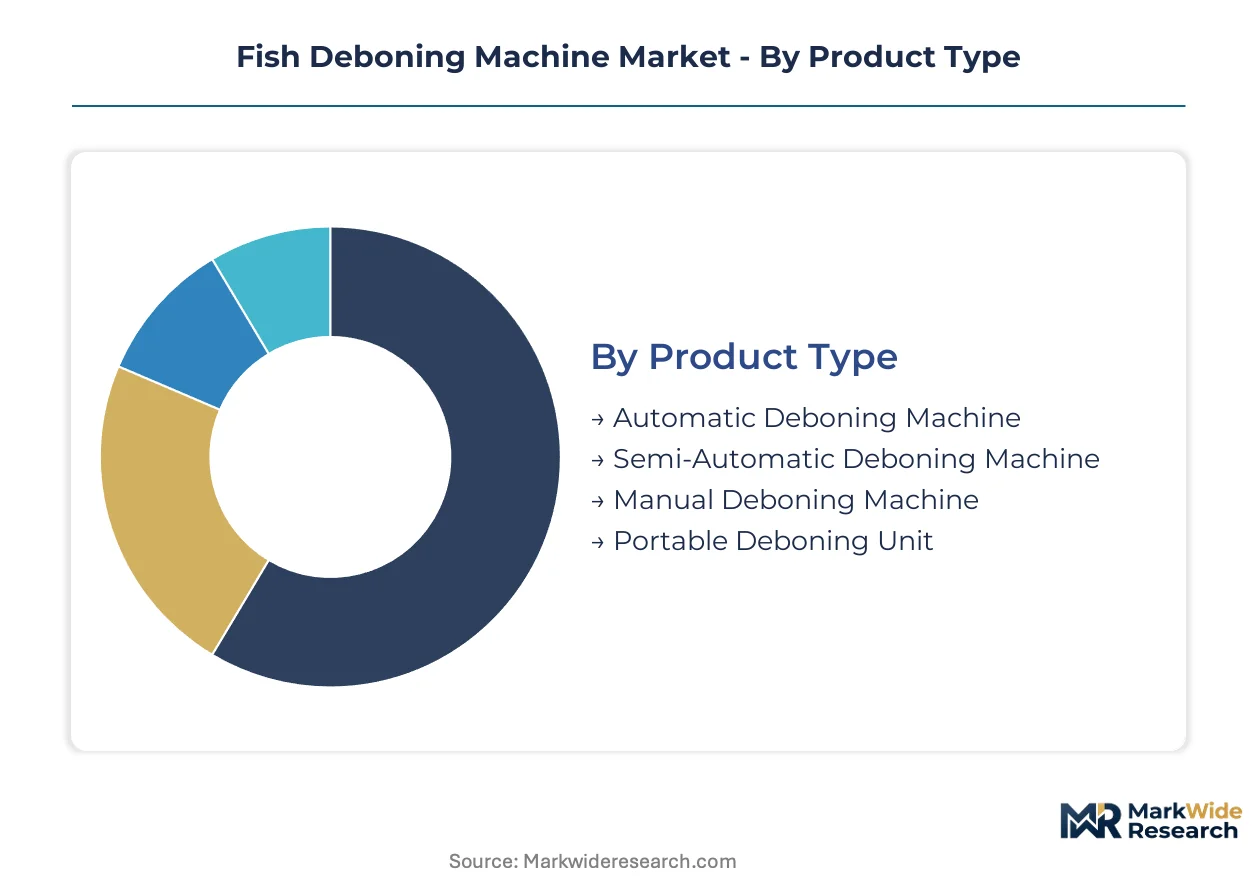
Equipment configuration directly shapes service contract economics across the fish deboning machine market. Procurement patterns diverge sharply between high-volume automated installations demanding integrated diagnostics and smaller pneumatic units requiring episodic maintenance.
Product Type:
After-sales intensity varies dramatically across automation tiers, with fully automated systems generating recurring software-hardware service revenue while manual units rely on sporadic parts replacement.
- Automatic Deboning Machine:Continuous-feed systems with precision blade arrays and integrated conveyor networks dominate salmon and whitefish operations in Norway's Atlantic processing corridor. Frozen food manufacturers anchor demand through synchronized fleet-shore modernization programs that bundle equipment with multi-year diagnostics contracts.
- Semi-Automatic Deboning Machine:Hybrid configurations blending mechanized feeding with operator-supervised portioning occupy the mid-tier where fishery cooperatives balance labor flexibility with yield consistency. Iceland's cooperative consolidation is compressing procurement cycles toward these intermediate automation levels.
- Manual Deboning Machine:Hand-fed bench units persist in specialty seafood retailers and culinary schools where batch sizes and species variety defy standardization.
- Portable Deboning Unit:Compact mobile configurations serve remote landing sites and seasonal processing camps with limited fixed infrastructure.
Automatic deboning machines hold the largest share; momentum sits with semi-automatic configurations as mid-scale cooperatives prioritize capital flexibility.
Technology:
Yield recovery rates and tissue integrity specifications are fragmenting technology procurement across species-specific processing economics.
- Electromechanical:Blade-array and pressure-roller systems constitute the installed base majority, proven across high-throughput salmon operations where reliability metrics outweigh marginal yield gains.
- Pneumatic:Compressed-air actuation occupies legacy factories with existing infrastructure, though technical debt barriers constrain upgrade paths to electromechanical alternatives.
- Hydraulic:High-force configurations serve dense-bone species where mechanical advantage exceeds precision requirements.
- Ultrasonic:Oscillation systems at 20-40 kHz frequencies command premium positioning in Norway's fillet-integrity-focused operations, collapsing the historical throughput-versus-quality trade-off.
- Vacuum Assisted:Emerging configurations target minimal-waste portioning for direct-to-consumer specialty retailers seeking compact footprint solutions.
Electromechanical systems retain dominant installed base; ultrasonic configurations are climbing the fastest as premium salmon processors absorb compressed implementation schedules.
Application:
Regulatory compliance intensity scales with production volume, concentrating certified stainless-steel configurations in mass-processing channels while niche applications tolerate simpler sanitation architectures.
- Fish Processing Plants:Industrial-scale facilities under FDA HACCP and EFSA hygiene mandates drive demand for clean-in-place capable stainless-steel contact surfaces.
- Seafood Packaging:Downstream integration requirements favor deboning-packing line synchronization with refrigerant-free cooling architectures responding to EU F-Gas Regulation deadlines.
- Foodservice Industry:High-volume restaurant and institutional chains prioritize throughput consistency over premium fillet integrity.
- Specialty Seafood Retailers:Direct consumer sales channels are adopting vacuum-assisted minimal-waste configurations for portion-controlled offerings.
- Culinary Schools:Training environments sustain demand for manual and semi-automatic units where pedagogical visibility matters.
Fish processing plants command the dominant application share; specialty seafood retailers represent the steepest expansion trajectory as channel fragmentation accelerates.
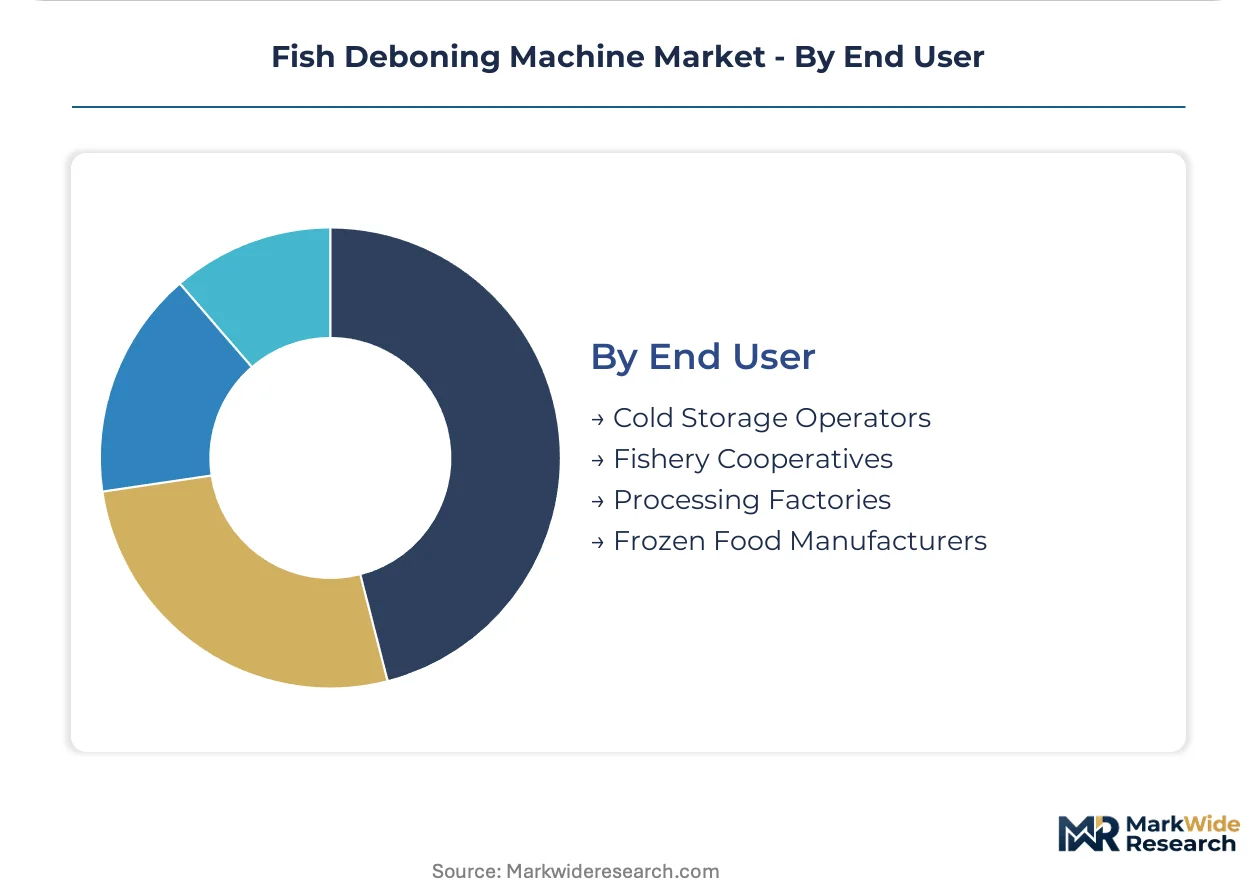
End User:
Procurement authority concentration is restructuring vendor relationships from transactional equipment sales toward integrated service contracts with captive spare-part guarantees.
- Cold Storage Operators:Integrated cooling-deboning line investments face acute EU F-Gas Regulation compliance deadlines, accelerating refrigerant-free thermal architecture adoption.
- Fishery Cooperatives:Norwegian and Icelandic merger activity is centralizing technical specifications and favoring vendors with Nordic diagnostics networks.
- Processing Factories:Mid-scale operations balance electromechanical reliability against ultrasonic yield premiums across seasonal catch rotations.
- Frozen Food Manufacturers:Automated deboning investments secure consistent yield rates and labor efficiency across scaled production commitments.
Fishery cooperatives hold the largest end-user share; frozen food manufacturers are gaining share fastest as yield-rate automation becomes non-negotiable.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Norwegian fishery cooperatives and Atlantic processing hubs concentrate equipment procurement authority, while regulatory pressure from Brussels reshapes cooling system architectures across Nordic shore facilities.
Norway
Atlantic salmon processing corridors drive synchronized fleet-shore modernization, with fishery cooperatives bundling automated deboning with multi-year service contracts. EU F-Gas Regulation phase-down deadlines accelerate refrigerant-free thermal architecture adoption. Bergen and Stavanger processing clusters absorb compressed implementation schedules for ultrasonic configurations.
Iceland
Fishery cooperative consolidation is centralizing technical specifications toward integrated diagnostics networks. EFSA hygiene standards mandate stainless-steel contact surfaces with clean-in-place capability. Reykjavik-based processing authorities favor vendors with captive spare-part guarantees over transactional equipment sales.
United States
Frozen food manufacturers anchor demand through yield-rate automation investments securing labor efficiency. FDA HACCP protocols filter non-compliant entrants from transatlantic supply chains. Seattle and Boston seafood processing hubs prioritize throughput consistency in high-volume institutional channels.
Denmark
Specialty seafood retailers adopt vacuum-assisted minimal-waste configurations for direct-to-consumer portioning. REACH chemical safety protocols reinforce stainless-steel surface mandates. Copenhagen processing facilities represent emerging compact-footprint demand outside industrial-scale channels.
Japan
Premium fillet integrity specifications command price premiums justifying ultrasonic oscillation adoption at 20-40 kHz frequencies. METI industrial standards shape equipment validation timelines. Tokyo and Osaka seafood processing districts balance electromechanical reliability against yield optimization technologies.
Fish Deboning Machine Market Competitive Landscape
Integrated solution providers and specialized component fabricators split the market along service-contract versus equipment-transaction lines. Nordic-origin vendors leverage proximity to Atlantic processing corridors for diagnostics network density. Competitive dynamics center on captive spare-part availability and software-hardware ecosystem integration rather than standalone machine pricing.
Among Nordic equipment specialists, Marel, Baader, and Kroma exemplify contrasting strategic archetypes. Marel represents the integrated diagnostics ecosystem model with recurring revenue capture across software-hardware maintenance contracts. Baader anchors the captive spare-part network approach, reducing client downtime exposure during peak salmon seasons. Kroma occupies the refurbishment program specialization, extending machine life cycles for mid-scale fishery cooperatives outside premium-tier procurement budgets.
| Leading Market Players |
|---|
| Arenco |
| Kroma |
| Marel |
| Cretel |
| Ryco Equipment |
| Baader |
| Norbech |
| Cabinplant |
| JBT FoodTech |
| Others |
Supply & Pricing Matrix
Bergen and Stavanger processing clusters concentrate procurement authority for automated deboning installations, translating fleet-shore modernization synchronization into vendor pricing leverage during peak salmon seasons.
Pricing Analysis
EU F-Gas Regulation dictates the pricing tier structure across integrated cooling-deboning configurations, separating refrigerant-free thermal architectures from legacy hydrofluorocarbon-dependent systems. Premium-mid-economy pricing differentiation tracks clean-in-place certification levels under FDA HACCP and EFSA hygiene mandates. Cost compression in mid-tier electromechanical units is intensifying because ultrasonic yield optimization collapses historical throughput-versus-quality trade-offs. Frozen food manufacturers exhibit lowest price sensitivity due to yield-rate automation imperatives, while specialty seafood retailers remain most price-sensitive given compact-footprint constraints.
Supply Chain Analysis
Contract manufacturing for precision blade arrays and ultrasonic transducer assemblies concentrates in Germany, Denmark, and Japan, with Nordic-origin vendors maintaining captive fabrication for conveyor networks and stainless-steel contact surfaces. Component sourcing draws from marine-grade stainless suppliers in Sweden, high-frequency oscillator specialists in Japan, and refrigerant-free cooling system fabricators in Germany. Single-source vulnerability sits with 20-40 kHz transducer suppliers serving premium fillet operations. Distribution runs through fishery cooperative procurement consortia in Norway and Iceland, with aftermarket service networks anchored by regional diagnostics hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ultrasonic oscillation adoption represents early-cycle expansion potential as premium salmon processors absorb compressed implementation schedules that collapse traditional replacement timelines.
For Market Incumbents: Pre-empt ultrasonic technology substitution by accelerating refrigerant-free thermal architecture R&D ahead of EU F-Gas enforcement deadlines. Defend service contract profitability through captive spare-part network density across Nordic processing hubs, countering emerging refurbishment specialists. Vertical integration into software-hardware diagnostics ecosystems captures recurring revenue as procurement authority concentrates within merged fishery cooperatives. For New Entrants and Emerging Players: Build out vacuum-assisted minimal-waste configurations targeting specialty seafood retailers in Denmark and Japan, where direct-to-consumer channel fragmentation outpaces incumbent coverage. The most penetrable white-space sits with compact-footprint portable units for remote landing sites lacking fixed infrastructure. A go-to-market angle emphasizing life-cycle extension services for mid-scale cooperatives outside Marel-Baader-Kroma coverage zones bypasses capital-intensive equipment sales barriers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated diagnostics ecosystem providers with Nordic field technician networks, positioning these archetypes for sustained cash flow quality across multi-year service contracts. Long-term viability favors vendors with refrigerant-free cooling integration capabilities as regulatory compliance hardens into procurement screening criteria. The signal to watch is Icelandic cooperative merger velocity, which accelerates centralized technical specification adoption and integrated contract favorability.| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant-Free Cooling Integration | EU F-Gas Regulation compliance secures eligibility for Norwegian and Icelandic cooperative procurement cycles. |
| Ultrasonic Configuration Expansion | 20-40 kHz oscillation systems command premium positioning in Bergen and Stavanger salmon processing corridors. |
| Captive Spare-Part Network Buildout | Regional inventory positioning reduces client downtime exposure during peak Atlantic salmon seasons. |
| Refurbishment Program Development | Life-cycle extension services capture margin pools from mid-scale cooperatives outside premium-tier budgets. |
| Software-Hardware Diagnostics Ecosystem | Recurring maintenance contracts displace transactional equipment sales as primary revenue anchor. |
Research Methodology
Cross-validation between primary interviews with fishery cooperative procurement directors, plant engineers at Atlantic processing facilities, and aftermarket service heads anchors the qualitative findings against secondary validation from EFSA hygiene standard filings, EU F-Gas Regulation implementation timelines, and Norwegian fishery modernization program disclosures. Bottom-up equipment installation tracking across Bergen, Stavanger, and Reykjavik processing clusters triangulates with top-down revenue estimates derived from vendor service contract disclosures.
Calibration against historical replacement cycles in salmon and whitefish operations shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include automation tier, technology configuration, application channel, and end-user procurement authority concentration. CAGRs derive from yield-rate automation imperatives among frozen food manufacturers and regulatory compliance deadlines compressing implementation schedules. Species-specific bone density variations and seasonal catch rotation patterns inform utilization rate assumptions.
The forecast holds incumbent behavior within observed patterns; aggressive refrigerant-free cooling integration moves by electromechanical specialists or ultrasonic technology leapfrogging by emerging entrants would shift outcomes beyond modeled ranges. Quarterly review of Icelandic cooperative merger velocity, EU F-Gas enforcement milestone adherence, and ultrasonic configuration adoption rates across Norway's Atlantic processing corridor is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Mixing Vessels Market
Food Processing Equipment
Asia-Pacific Walk-In Refrigerators and Freezers Market
Food Processing Equipment
Automatic Fish Scaling Machine Market
Food Processing Equipment
Cereal Rolling Machine Market
Food Processing Equipment
North America Commercial Sous Vide Machine Market
Food Processing Equipment
Cook Processor Market
Food Processing Equipment
Alternative Protein Processing Equipment Market
Food Processing Equipment
Food Processing Machinery Market
Food Processing Equipment
UHT Systems Market
Food Processing Equipment
Industrial Steam Peeler Market
Food Processing Equipment
Fish Processing Equipment Market
Food Processing Equipment
Conveyor Ovens and Impinger Ovens Market
Food Processing Equipment
Portable Clean-In-Place Market
Food Processing Equipment
Plastic Processing Machinery Market
Food Processing Equipment
Global Meat Mixer Market
Food Processing Equipment
Industrial Food and Beverages Filtration System Market