
 Pasteuriser Market | 2026-2036
Pasteuriser Market Size, Share, and Industry Trends Forecast 2026-2036
Pasteuriser Market Analytics
The capability gap between integrated system builders and component assemblers is reorganizing competitive tiers in pasteuriser supply. GEA Group Aktiengesellschaft leverages its heat-exchanger manufacturing depth to anchor long-term dairy contracts across Northern Europe. Tetra Pak International S.A. competes through end-to-line integration, bundling pasteurisers with aseptic filling systems. Alfa Laval differentiates on plate heat-exchanger efficiency, sustaining premium positioning in energy-intensive beverage applications.
A pasteuriser is a thermal processing unit that heats liquid or semi-liquid food products to a defined temperature—typically between 60°C and 85°C—for a controlled duration before rapid cooling, thereby eliminating pathogenic microorganisms while preserving sensory and nutritional properties. Continuous pasteurisers dominate volume throughput in large-scale dairy operations, whereas high-temperature short-time pasteurisers capture expanding share in juice and functional beverage lines where minimal thermal degradation preserves vitamin stability. Batch pasteurisers retain structural relevance in craft alcoholic beverage production and small-scale sauce manufacturing, where recipe flexibility outweighs unit-economy constraints.
FDA pasteurisation standards under the Pasteurized Milk Ordinance shape equipment specifications for US dairy exports, while EFSA hygiene criteria and EU MDR pressure-vessel directives govern European market access. In India, BIS certification and FSSAI thermal-process norms compel domestic processors to upgrade from unregulated boiling methods to instrumented pasteurisation systems. Stakeholders must monitor regulatory divergence between pathogen-reduction performance standards and energy-efficiency mandates when configuring equipment portfolios for multi-territory deployment.
Market Dynamics
Regulatory divergence between pathogen-reduction mandates and energy-efficiency standards is fragmenting equipment specifications across export corridors, forcing manufacturers to engineer modular platforms that reconfigure for FDA, EFSA, or NMPA compliance without full redesign.
Growth Catalysts
- EFSA hygiene benchmarks:Dairy processors in Germany and France are expanding batch and HTST capacity to meet these standards, pulling demand for instrumented continuous systems.
- China's NMPA-aligned dairy safety protocols:These rules are accelerating equipment replacement cycles among domestic processors upgrading from manual thermal methods.
- India's cooperative dairy sector:AMUL-linked processing plants are converting from manual to continuous pasteurisation systems, concentrating demand in this channel.
Market Restraints
- Stainless steel price volatility:Heat-exchanger fabrication depends on 316L and 304 grades, with input cost swings compressing margin visibility for system builders.
- Specialized valve and pump supplier concentration:Precision sanitary components for aseptic pasteuriser lines concentrate among German and Italian component houses, creating single-source vulnerability.
- EU MDR pressure-vessel certification timelines:Extended conformity assessment periods for high-capacity continuous units delay revenue recognition on large dairy contracts.
Strategic Opportunities
- India's unpenetrated artisanal dairy segment:Thousands of small-scale milk collection centers lack instrumented pasteurisation, presenting retrofit potential for skid-mounted batch units.
- Functional beverage aseptic integration:Probiotic and plant-based drink lines require pasteuriser-filler block integration that legacy dairy equipment suppliers have not addressed.
- FSSAI thermal-process enforcement:India's mandatory instrumented pasteurisation for interstate milk trade creates regulatory tailwind for certified system imports and domestic assembly partnerships.
Industry Challenges
- Sanitary welding certification scarcity:Qualified orbital welders for dairy-grade stainless pipework command premium wages and extend fabrication lead times.
- Legacy control system integration:Continuous pasteuriser retrofits into 1990s-era dairy plants require protocol bridging between modern PLCs and obsolete SCADA architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pasteuriser Market |
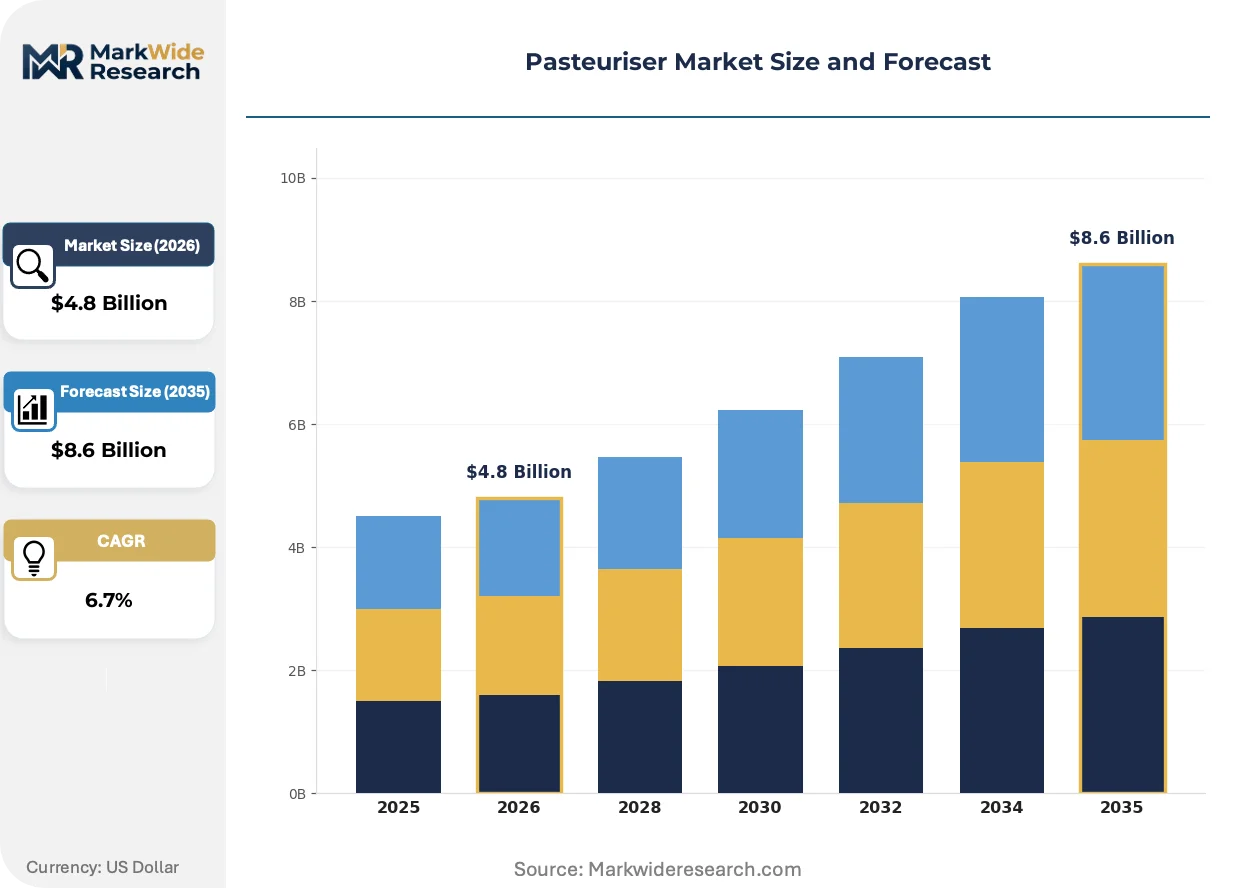
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Batch Pasteurisers, Continuous Pasteurisers, Mobile Pasteurisers, High-Temperature Short-Time Pasteurisers Technology: Steam Pasteurisation, Hot Water Pasteurisation, Plate Pasteurisation, Microwave Pasteurisation Application: Dairy Products, Juices, Alcoholic Beverages, Sauces End User: Food Processing Plants, Beverage Manufacturers, Research Institutions, Restaurants |
| Companies Covered | Tetra Pak International S.A., GEA Group Aktiengesellschaft, Alfa Laval, SPX FLOW, Inc., Krones AG, IDMC Limited, Feldmeier Equipment, Inc., JBT Corporation, Scherjon Dairy Equipment Holland B.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pasteuriser Market Evolving Landscape
Equipment architecture is pivoting from fixed-line configurations toward modular, reconfigurable platforms that accommodate shorter product runs and faster format changeovers in dairy and beverage processing.
Plate heat-exchanger technology is miniaturizing. Micro-channel plate designs with enhanced corrugation patterns now deliver equivalent thermal transfer in 40% less footprint than conventional units. Craft breweries and small-batch sauce manufacturers are adopting these compact pasteurisers to reclaim floor space in urban production facilities. This compression is miniaturizing the minimum viable scale for automated thermal processing, eroding the historical cost barrier that protected manual batch methods in sub-million-liter operations.
REACH restrictions on perfluorinated compounds are eliminating legacy gasket materials from European food-contact equipment. Manufacturers must qualify hydrogenated nitrile and platinum-cured silicone alternatives that withstand CIP thermal cycling without leaching. Dairy pasteuriser lines with extended run times between maintenance windows face the steepest reformulation burden, with some processors accelerating replacement cycles to avoid compliance-driven retrofit costs on installed base.
Service unbundling is fragmenting vendor-customer relationships. Large dairy cooperatives are separating pasteuriser hardware procurement from aftermarket maintenance, awarding service contracts to independent specialists or in-house engineering teams. Equipment OEMs respond with remote monitoring subscriptions and predictive analytics layers to retain attach rates. This disintermediation is most pronounced in Northern European markets where cooperative buying power concentrates procurement leverage.
Pasteuriser Market Segmentation
Pasteuriser procurement patterns diverge sharply between domestic food processing and export-oriented beverage manufacturing, with equipment specifications tracking regulatory requirements in destination markets. Understanding these segment boundaries clarifies where modular platform investments yield cross-border compliance advantages versus single-market optimization.
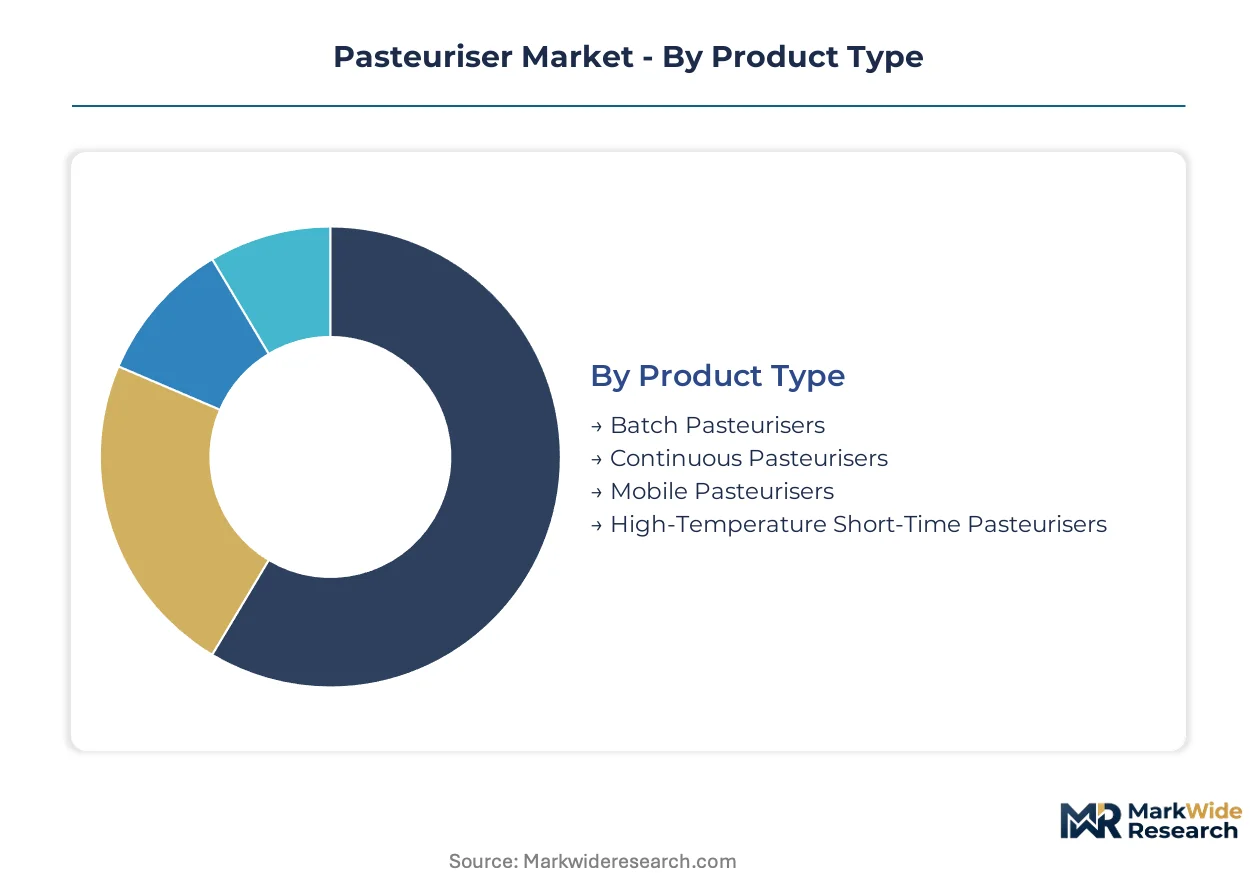
Product Type:
Batch pasteurisers concentrate in domestic craft production where recipe flexibility outweighs throughput economics, while continuous systems dominate export corridors serving multinational dairy and juice brands.
- Continuous Pasteurisers:These systems integrate plate heat-exchangers with automated CIP cycles to sustain 24-hour production runs. Demand clusters in Germany and France where EFSA hygiene benchmarks mandate instrumented thermal control for interstate dairy trade. Dairy processors expanding HTST capacity pull these units for standardized milk and cream lines.
- High-Temperature Short-Time Pasteurisers:Operating at 72°C for 15 seconds, HTST units minimize vitamin degradation in heat-sensitive functional beverages. China's NMPA-aligned dairy safety protocols accelerate replacement of manual vat systems with automated HTST lines among domestic juice processors seeking export certification.
- Batch Pasteurisers:Vat-style units with programmable temperature ramps serve craft breweries and artisanal sauce manufacturers in India and Europe where production volumes fall below continuous system thresholds.
- Mobile Pasteurisers:Skid-mounted trailer units enable on-farm processing for India's unpenetrated artisanal dairy segment, bypassing infrastructure gaps at collection centers.
Continuous pasteurisers hold the largest share; momentum sits with HTST systems as functional beverage lines proliferate.
Technology:
Steam and hot water systems split along energy cost gradients, with steam dominating where natural gas prices favor thermal efficiency and hot water penetrating markets with electricity subsidies or renewable mandates.
- Plate Pasteurisation:Corrugated stainless-steel plates create turbulent flow for heat transfer coefficients exceeding 6000 W/m²K. India's AMUL-linked cooperative plants specify plate systems for energy recovery between raw and pasteurised milk streams, cutting thermal loads by 40% versus tubular alternatives.
- Hot Water Pasteurisation:Closed-loop glycol-water systems eliminate steam boiler infrastructure, appealing to small-scale beverage manufacturers in urban European facilities where space constraints and safety codes restrict high-pressure steam installation.
- Steam Pasteurisation:Direct steam injection delivers rapid temperature ramping for high-viscosity sauces and dairy concentrates where fouling risks complicate plate heat-exchanger maintenance.
- Microwave Pasteurisation:Electromagnetic volumetric heating reduces thermal degradation in premium juices and probiotic beverages, though capital costs limit penetration to niche functional drink lines.
Plate pasteurisation dominates installed capacity; microwave systems are climbing the fastest as aseptic functional beverage lines expand.
Application:
Dairy and juice applications anchor equipment standardization, while alcoholic beverages and sauces fragment specifications around alcohol tolerance and particulate handling.
- Dairy Products:Milk, cream, and yogurt processing demands 3A sanitary standards with full CIP compatibility. FDA Pasteurized Milk Ordinance specifications shape equipment procurement for US export-oriented plants in Europe and Oceania.
- Juices:Citrus and tropical fruit lines require enzyme deactivation without pectin degradation, driving plate pasteuriser selection with precise temperature control bands.
- Alcoholic Beverages:Craft breweries and wineries utilize batch pasteurisers for stabilization before bottling, with flash pasteurisation gaining share in kegged beer distribution.
- Sauces:High-viscosity tomato and cream-based products necessitate scraped-surface or tubular heat-exchangers where plate designs would foul.
Dairy applications command the greatest equipment value; juice processing is gaining share fastest on functional beverage proliferation.
End User:
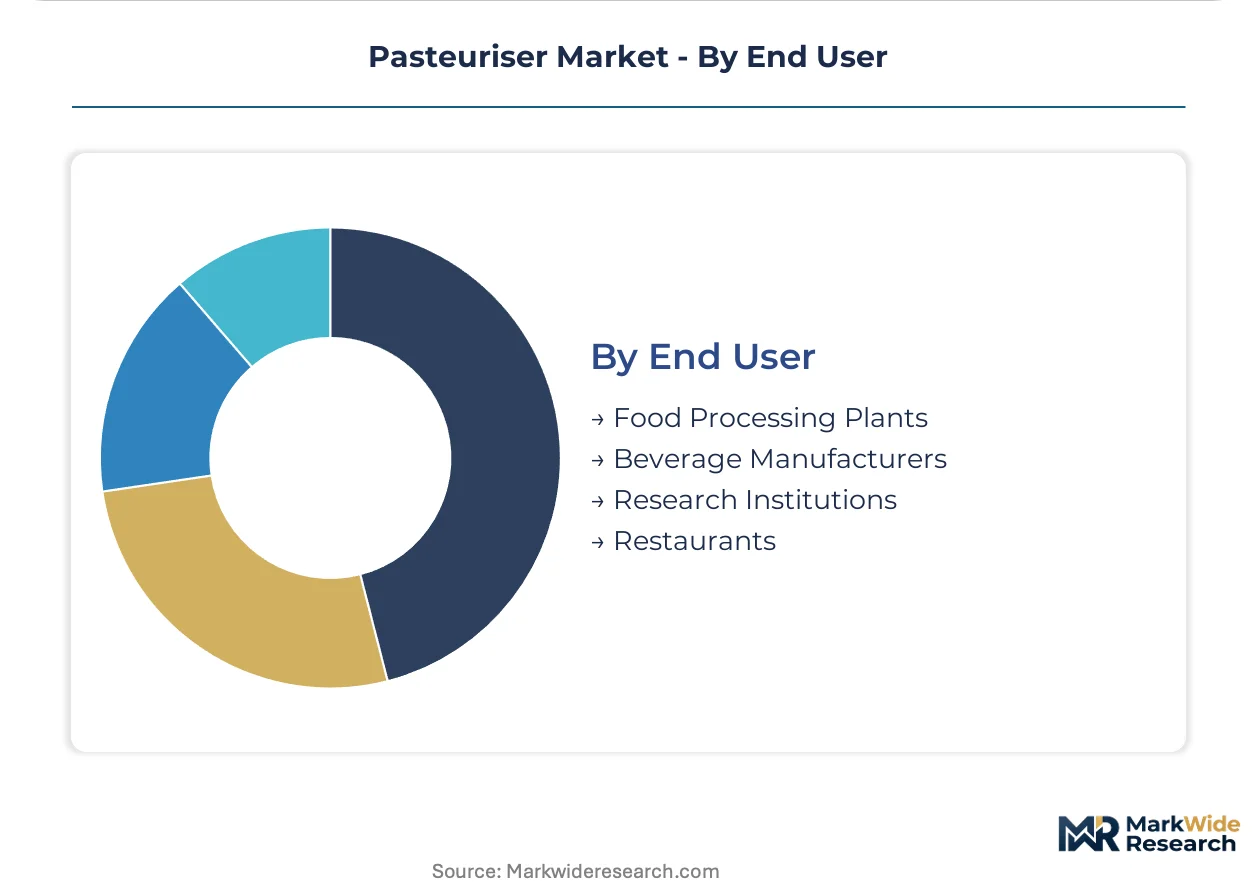
Food processing plants and beverage manufacturers drive capital expenditure cycles, while research institutions and restaurants represent sporadic, specification-driven demand.
- Food Processing Plants:Integrated dairy and sauce manufacturers specify pasteurisers as central process units with upstream homogenization and downstream aseptic filling integration. India's FSSAI thermal-process enforcement compels interstate milk traders to upgrade from unregulated boiling to instrumented systems.
- Beverage Manufacturers:Juice and functional drink specialists prioritize HTST and microwave systems for vitamin retention, with aseptic pasteuriser-filler block integration emerging as a competitive differentiator.
- Research Institutions:Pilot-scale batch units with data logging support process development for novel probiotic and plant-based formulations.
- Restaurants:Countertop batch pasteurisers serve high-volume commercial kitchens producing house-made sauces and dairy bases under local health department oversight.
Food processing plants represent the dominant procurement channel; beverage manufacturers are expanding most quickly on functional drink capacity builds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in India's cooperative dairy sector exhibit the highest price elasticity, prioritizing low-capital batch units over continuous systems, while German and French processors absorb premium pricing for EFSA-compliant HTST capacity without volume contraction.
United States
Dairy export-oriented processors in Wisconsin and California drive HTST system procurement to maintain FDA Pasteurized Milk Ordinance compliance for international shipment eligibility. The USDA enforces Grade A standards that mandate instrumented thermal control for interstate milk distribution. Chicago-area equipment distributors report accelerating replacement cycles as legacy vat systems reach end-of-life.
Germany
Bavarian dairy cooperatives expand continuous pasteuriser capacity to meet EFSA hygiene benchmarks for extended-shelf-life milk production. The EU MDR pressure-vessel directive extends certification timelines for high-capacity units, delaying some capital deployments. Stuttgart-based system integrators specialize in retrofitting 1990s-era plants with modern PLC architectures.
France
Normandy cheese processors specify batch pasteurisers for recipe-flexible cream and specialty milk production alongside HTST lines for standardized fluid milk. ANSM oversight of food-contact materials drives gasket material transitions away from perfluorinated compounds. Lyon-area stainless fabricators concentrate sanitary welding capacity for dairy-grade pipework.
China
Domestic juice processors in Shandong and Guangdong provinces replace manual thermal methods with automated HTST lines to secure NMPA-aligned export certification. The MIIT promotes equipment modernization through technical standards harmonization with Codex Alimentarius. Shanghai-based dairy groups accelerate pasteuriser-filler block integration for probiotic beverage capacity.
India
AMUL-linked cooperatives in Gujarat and Maharashtra convert from manual boiling to continuous plate pasteurisation systems under FSSAI interstate trade enforcement. The BIS certification regime compels instrumented thermal-process documentation for formal sector participation. Anand-based processing clusters concentrate demand for skid-mounted batch units serving unpenetrated artisanal collection centers.
Pasteuriser Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with heat-exchanger specialists commanding premium positioning through energy-efficiency differentiation while regional fabricators compete on capital-light delivery timelines. The vendor base organizes into three strategic tiers: integrated system builders bundling pasteurisation with downstream filling equipment, component specialists anchoring supply relationships through heat-exchanger manufacturing depth, and regional assemblers serving price-sensitive domestic markets. Dominant competitive moves include geographic expansion through local assembly partnerships and portfolio diversification into aseptic integration for functional beverage lines.
Among European-integrated system builders, Tetra Pak International S.A. and GEA Group Aktiengesellschaft exemplify divergent positioning archetypes—one competing through end-to-line bundling strength, the other through captive heat-exchanger manufacturing depth. Alfa Laval occupies a position within the component-specialist tier, with its corporate identity signaling Swedish engineering origins and plate heat-exchanger concentration. These three anchors demonstrate how competitive advantage fragments across integration strategies rather than concentrating in a single dominant model.
| Leading Market Players |
|---|
| Tetra Pak International S.A. |
| GEA Group Aktiengesellschaft |
| Alfa Laval |
| SPX FLOW, Inc. |
| Krones AG |
| IDMC Limited |
| Feldmeier Equipment, Inc. |
| JBT Corporation |
| Scherjon Dairy Equipment Holland B.V. |
| Others |
Value Network & Pricing Analysis
EU MDR pressure-vessel certification timelines gate both supplier qualification and price differentiation simultaneously, extending revenue recognition cycles for high-capacity continuous units while compressing margins for fabricators awaiting conformity assessments. This regulatory bottleneck concentrates pricing power among incumbent system builders with established notified-body relationships, forcing regional assemblers to absorb longer working-capital cycles or exit the formal sector.
Pricing Analysis
After-sales service contracts and predictive maintenance subscriptions now drive lifetime value capture, with large dairy cooperatives in Northern Europe unbundling hardware procurement from ongoing support. Three-tier pricing structure across premium, standard, and economy levels segments by certification grade and automation depth, with EFSA-compliant HTST systems commanding substantial premiums over manual batch alternatives. Cost compression in economy-tier skid-mounted units is intensifying because stainless steel price volatility feeds directly into heat-exchanger fabrication costs. India's cooperative dairy sector exhibits highest price elasticity, while German processors absorb premium positioning without volume contraction.
Supply Chain Analysis
Port congestion on Asia-Europe trade lanes and container availability constraints in Hamburg and Rotterdam are elevating inbound logistics costs for precision sanitary components sourced from Italian and German valve houses. Heat-exchanger fabrication draws from stainless steel mills in Germany, Sweden, and China, with 316L and 304 grade dependencies creating margin vulnerability when commodity cycles spike. Single-source concentration among specialized pump suppliers for aseptic lines presents structural vulnerability. Distribution runs through regional system integrators in Stuttgart, Lyon, and Anand who configure skid-mounted platforms for local dairy infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated dairy cooperatives with centralized procurement functions, fragmenting vendor-customer relationships as AMUL-linked plants and Northern European collectives separate equipment buying from aftermarket service awards.
For Market Incumbents: Shield installed-base relationships by embedding predictive analytics layers and remote monitoring subscriptions that retain attach rates against independent service specialists. Deepen backward integration into plate heat-exchanger manufacturing to anchor cost structures when stainless input volatility spikes, while accelerating CE marking and FDA dual-certification investments to capture cross-border dairy export corridors before regional assemblers qualify. For New Entrants and Emerging Players: Predictive maintenance capability gaps among legacy equipment OEMs present white-space entry points, particularly where 1990s-era dairy plants require protocol bridging between modern PLCs and obsolete SCADA architectures. India's unpenetrated artisanal dairy segment offers most penetrable geography, with thousands of small-scale milk collection centers lacking instrumented pasteurisation. Pursue skid-mounted batch unit partnerships with Anand-based processing clusters to establish reference installations before FSSAI enforcement hardens. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across aseptic pasteuriser-filler block integration for functional beverage lines, as probiotic and plant-based drink capacity builds demand bundled thermal-processing solutions. Target acquisition candidates with captive heat-exchanger manufacturing depth and established notified-body relationships for EU MDR compliance. Monitor stainless steel price volatility indices and EFSA hygiene benchmark enforcement timelines as inflection indicators for margin compression or demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Aseptic Integration Development | Bundled pasteuriser-filler blocks capture functional beverage lines in Shanghai and Guangdong provinces. |
| Modular Platform Engineering | Reconfigurable systems accommodate FDA, EFSA, and NMPA compliance without full redesign for export corridors. |
| Service Unbundling Response | Remote monitoring subscriptions retain attach rates as dairy cooperatives separate procurement from maintenance. |
| Regional Assembly Partnerships | Local skid-mount configuration in Gujarat and Maharashtra reduces delivery timelines for price-sensitive cooperatives. |
| Gasket Material Transition | REACH-compliant hydrogenated nitrile and platinum-cured silicone alternatives secure European food-contact equipment access. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, trade customs data, and equipment certification databases, combining structured interviews with dairy processing engineers, aftermarket service directors, and cooperative procurement leads with validation across EFSA guidance documents, FDA Pasteurized Milk Ordinance specifications, and BIS thermal-process standards. Bottom-up capacity assessments triangulate against top-down market sizing through equipment shipment tracking and capital expenditure disclosure analysis.
Segmentation dimensions modeled span product type, technology architecture, application category, and end-user channel across the projection horizon, with CAGRs derived from regression analysis of historical replacement cycles and regulatory enforcement trajectories. Forecast inputs incorporate stainless steel price elasticity coefficients, dairy sector consolidation patterns, and FSSAI interstate trade compliance timelines.
Underlying assumptions cover sustained EFSA hygiene benchmark enforcement, continued NMPA alignment with Codex Alimentarius, and stable cooperative procurement concentration in India and Northern Europe, with deviation risk concentrated in EU MDR certification timeline extensions and REACH material restriction accelerations. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Tomato Processing Machine Market
Food Processing Equipment
Food Waste Disposal Equipment Market
Food Processing Equipment
Pizza Scissors Market
Food Processing Equipment
Fish Deboning Machine Market
Food Processing Equipment
North America Walk-In Refrigerators and Freezers Market
Food Processing Equipment
Brining Systems Market
Food Processing Equipment
Fluidized Bed Dryer Market
Food Processing Equipment
Europe Household Food Waste Composting Machine Market
Food Processing Equipment
Hydrostatic Steam Blancher Market
Food Processing Equipment
De-Agglomerating Equipment Market
Food Processing Equipment
Global Fermenters Market
Food Processing Equipment
Used Commercial Freezer Market
Food Processing Equipment
Multi Ovens Market
Food Processing Equipment
Smart Food Machine Market
Food Processing Equipment
Cereal Rolling Machine Market
Food Processing Equipment
Food Processing Equipment Market