
 Frozen Food Processing Machinery Market | 2026-2036
Frozen Food Processing Machinery Market Size, Share, and Industry Trends Forecast 2026-2036
Frozen Food Processing Machinery Market Foresight
A capital-intensity divergence between integrated turnkey providers and component specialists is rotating competitive dynamics across the frozen food processing machinery sector. GEA Group leverages its end-to-end refrigeration and processing integration to command premium positioning in large-scale protein and dairy installations. JBT Corporation anchors its footprint through freezing tunnel and coating system specialization for prepared foods. Marel competes with sensor-driven automation that reduces yield loss in poultry and seafood IQF lines.
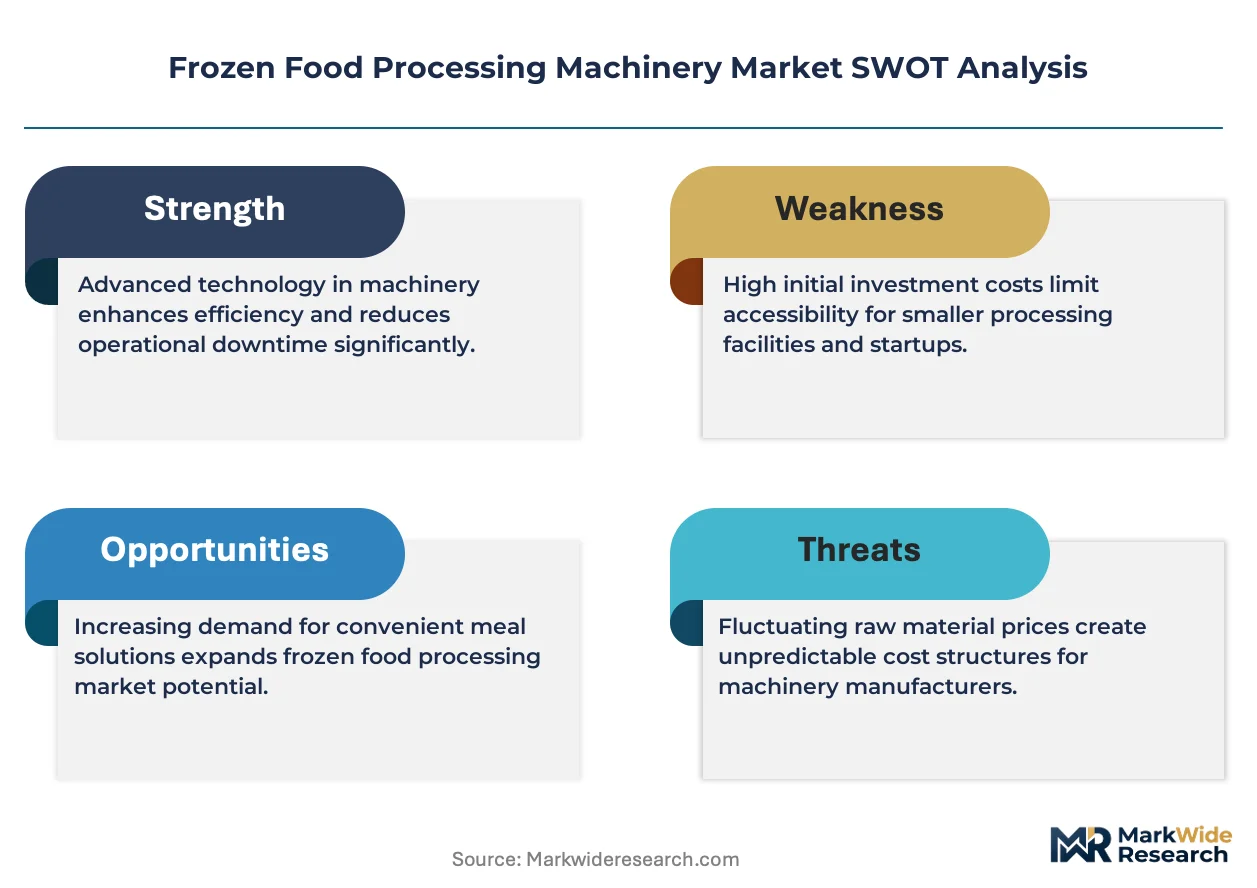
Frozen food processing machinery encompasses industrial equipment engineered to reduce food product temperatures rapidly to preserve cellular structure, nutritional content, and sensory quality, typically achieving core temperatures below minus eighteen degrees Celsius through mechanical compression, cryogenic injection, or hybrid thermal transfer methods. Blast freezers and IQF systems dominate capital deployment due to their centrality in seafood and vegetable processing workflows where individual quick freezing prevents clumping and moisture loss. Cryogenic freezers using liquid nitrogen represent the fastest-expanding technology segment as processors seek to eliminate hydrofluorocarbon refrigerant compliance burdens while cutting freezing cycle times.
The EU F-Gas Regulation and REACH framework constrain refrigerant selection and equipment design standards across European installations, while the FDA's Hazard Analysis and Critical Control Points mandates shape sanitary design requirements for machinery serving US export-bound facilities. China's GB standards and NMPA food contact material rules add certification complexity for multinational suppliers deploying hybrid freezing platforms across Asia-Pacific manufacturing networks. Stakeholders must monitor refrigerant phase-down schedules and energy efficiency benchmarking protocols to align capital allocation with tightening environmental compliance trajectories.
Market Dynamics
The EU F-Gas Regulation is compressing refrigerant choice sets across European installations, forcing capital reallocation toward cryogenic nitrogen systems and hybrid thermal platforms that sidestep hydrofluorocarbon phase-down schedules while preserving freezing throughput.
Growth Catalysts
- Protein processing automation:Large-scale poultry and seafood facilities in Germany are retrofitting IQF lines to meet retail shelf-life specifications, pulling demand for sensor-integrated freezing tunnels.
- REACH compliance burden:Equipment manufacturers redesigning heat exchangers and seals to eliminate restricted substances are capturing preferential placement in EU-bound export contracts.
- Cryogenic nitrogen injection:Liquid nitrogen freezers are penetrating prepared foods segments where rapid crust-freezing preserves texture in coated and battered products.
Market Restraints
- Stainless steel input volatility:Grade 304 and 316 price swings compress margin visibility for fabricators of sanitary-grade freezing chambers and conveyor frameworks.
- Specialized compressor supply concentration:Precision refrigeration compressors for sub-zero mechanical systems concentrate among a narrow supplier base in northern Italy and southern Germany.
- Energy intensity ceilings:Grid capacity constraints at rural protein processing clusters in northern Germany limit simultaneous deployment of multiple high-draw blast freezing units.
Strategic Opportunities
- Plant-based protein freezing:Dedicated IQF lines for pea and soy protein isolates remain undersupplied relative to capacity expansion timelines at Dutch and German alternative protein facilities.
- Service contract unbundling:Predictive maintenance subscriptions using vibration and thermal sensors are displacing traditional break-fix arrangements in Scandinavian dairy freezing operations.
- EU Green Deal capital access:Machinery upgrades qualifying for NextGenerationEU facility modernization grants are accelerating replacement cycles in Spanish and Italian vegetable processing cooperatives.
Industry Challenges
- Refrigeration technician scarcity:Qualified service personnel for ammonia and CO2 cascade systems are concentrating near legacy industrial clusters, leaving peripheral installations with extended downtime exposure.
- Legacy control system integration:Retrofitting IoT-enabled freezing tunnels into 1990s-era SCADA architectures demands custom protocol bridging that extends commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Frozen Food Processing Machinery Market |
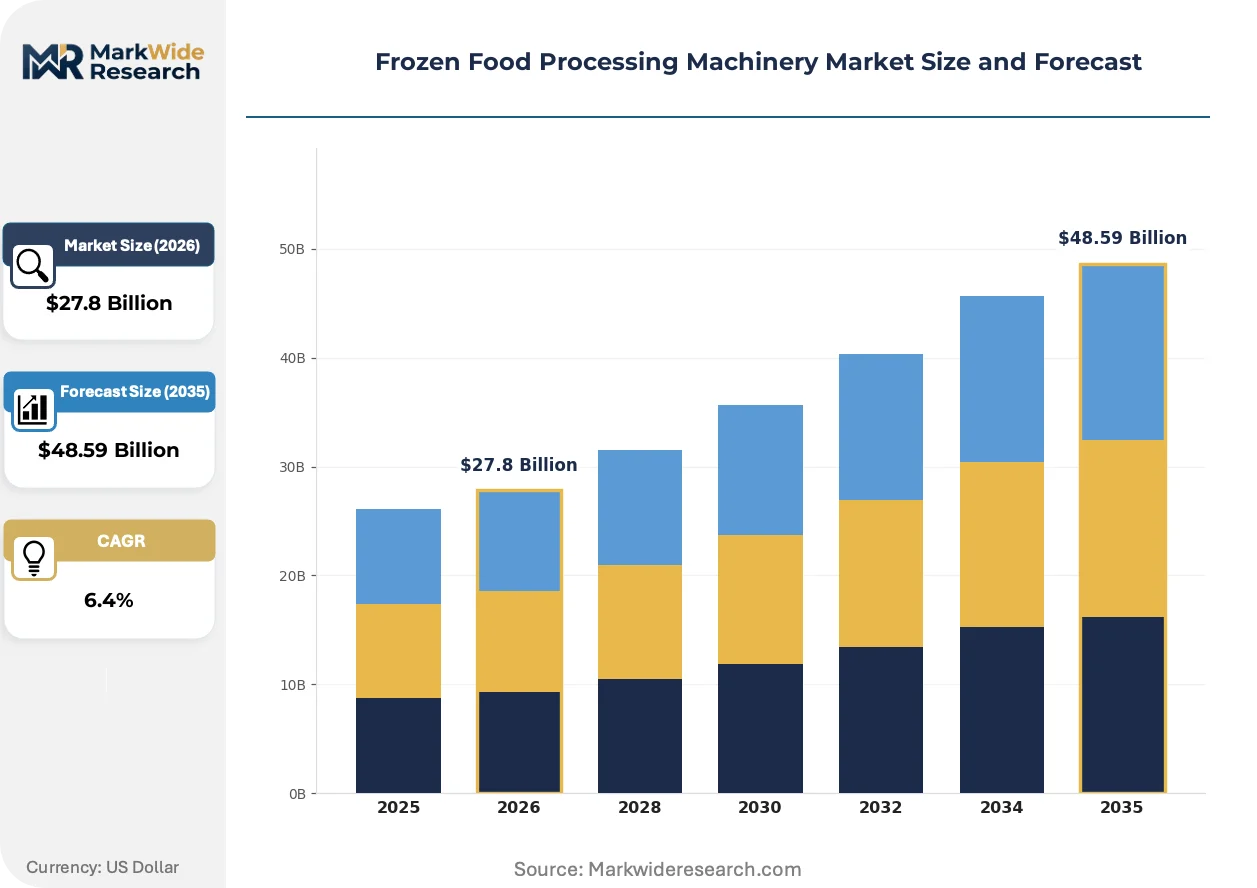
| Market Size in 2026 | $27.8 Billion |
| Market Size in 2035 | $48.59 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blast Freezers, IQF Systems, Freezing Tunnels, Cryogenic Freezers, Plate Freezers, Spiral Freezers Technology: Mechanical Compression, Cryogenic, Liquid Nitrogen, Liquid Carbon Dioxide, Hybrid Freezing, Vacuum Freezing Application: Seafood Processing, Meat Preparation, Vegetables Treatment, Ready Meals Manufacturing, Dairy Products Handling, Fruit Preservation End User: Food Processing Plants, Cold Storage Facilities, Packaged Foods Manufacturers, Catering Services, Institutional Kitchens, Food Exporters |
| Companies Covered | GEA Group, JBT Corporation, Marel, Alfa Laval, Tetra Pak, FRIGOGLASS, OctoFrost Group, Starfrost, FEMIA Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Frozen Food Processing Machinery Market Shifts & Advancements
Equipment architectures are pivoting from mechanical compression dominance toward hybrid and cryogenic platforms, driven by refrigerant compliance pressure and energy efficiency benchmarking across European protein and dairy installations.
Hybrid freezing systems combining mechanical pre-cooling with liquid nitrogen finishing is supplanting pure mechanical compression in high-throughput seafood operations. Norwegian salmon processors are adopting these configurations to eliminate hydrofluorocarbon refrigerant inventories entirely. The shift is compressing capital deployment timelines for conventional two-stage ammonia plants while expanding the addressable market for nitrogen supply infrastructure.
REACH substance restrictions and the EU F-Gas Regulation are tightening material specifications for seals, lubricants, and heat transfer fluids in freezing equipment. Manufacturers are reformulating compressor lubricants to eliminate PFAS content ahead of anticipated broader restrictions. German and Dutch equipment fabricators are most exposed, with redesign cycles compressing from five-year to eighteen-month intervals.
Buyer concentration among pan-European retail chains is consolidating procurement leverage over freezing line specifications. Prepared foods contractors serving Aldi, Lidl, and Carrefour central kitchens face unified technical audits that favor suppliers with pan-continental service networks. This consolidation is most visible in the Benelux corridor, where co-manufacturing facilities are standardizing on single-source freezing platform providers to simplify compliance documentation.
Frozen Food Processing Machinery Market Segmentation
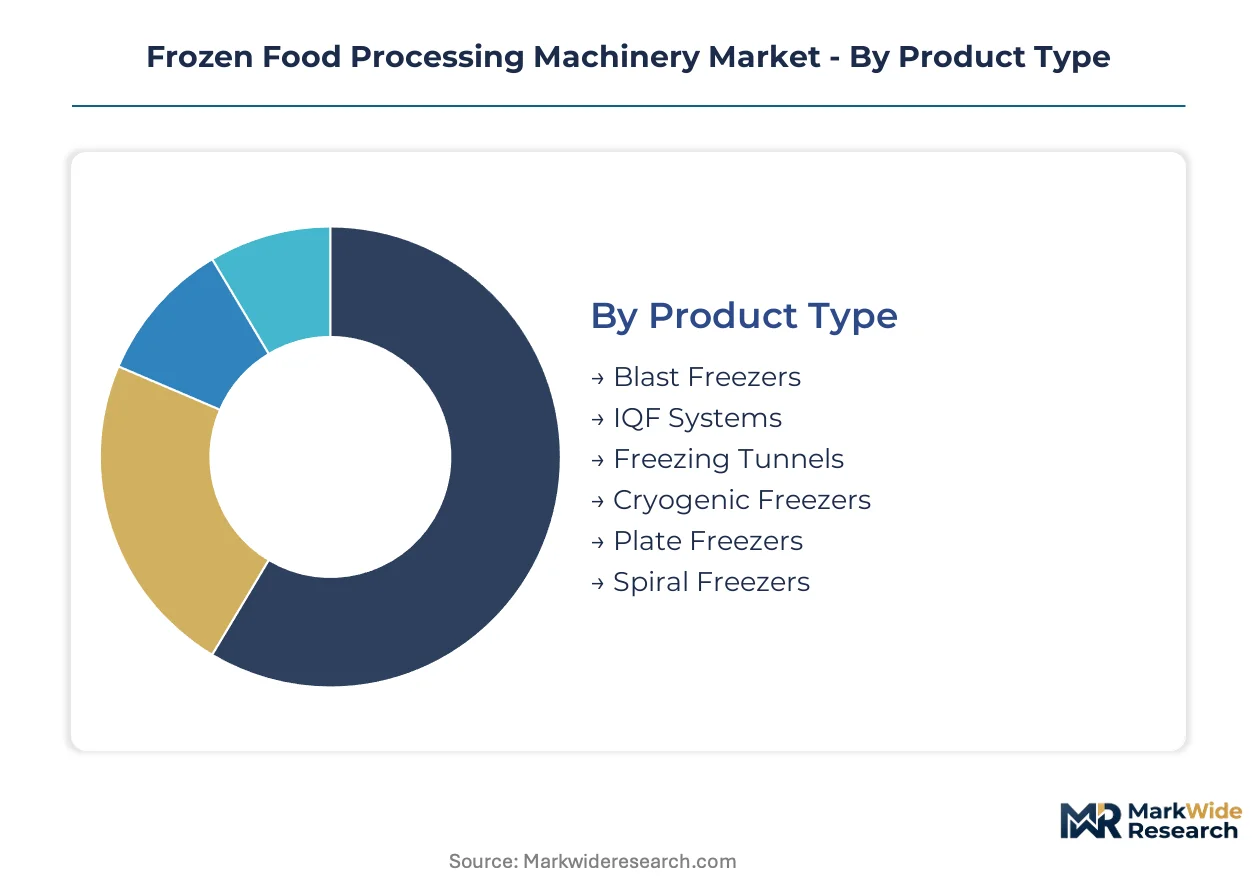
Equipment segmentation in frozen food processing machinery determines capital allocation priorities, refrigerant compliance pathways, and integration complexity for protein and prepared foods facilities. Distinct technology-product combinations carry divergent energy profiles, throughput ceilings, and regulatory exposure across European installations.
Product Type:
REACH substance restrictions and the EU F-Gas Regulation differentiate equipment categories by refrigerant inventory requirements and heat exchanger material specifications, compressing redesign cycles for manufacturers serving EU-bound contracts.
- Blast Freezers:High-velocity air circulation systems achieve rapid temperature reduction through forced convection across product surfaces. German poultry processors in Lower Saxony are retrofitting blast lines to meet Aldi and Lidl shelf-life specifications, pulling demand for stainless steel chambers rated for continuous sub-thirty-degree Celsius operation.
- IQF Systems:Individual quick freezing platforms fluidize products through vibrating conveyors or air impingement to prevent clumping. Norwegian salmon processors deploy IQF tunnels at Bergen-area facilities to preserve cellular structure for export-grade fillets, with sensor-integrated yield optimization reducing moisture loss below three percent.
- Freezing Tunnels:Continuous belt systems for high-volume throughput in prepared foods manufacturing.
- Cryogenic Freezers:Direct liquid nitrogen or carbon dioxide injection systems eliminating hydrofluorocarbon refrigerant compliance burdens.
- Plate Freezers:Contact freezing platforms for flat product geometries in seafood block operations.
- Spiral Freezers:Vertical belt configurations maximizing floor space efficiency in constrained Dutch dairy facilities.
Blast freezers handle the majority of throughput across European protein installations; cryogenic freezers are gaining share fastest as F-Gas phase-down schedules accelerate capital reallocation.
Technology:
Cost tier differentiation separates established mechanical infrastructure from emerging cryogenic and hybrid platforms, with upfront capital intensity and operating energy profiles driving buyer selection across facility scale categories.
- Mechanical Compression:Two-stage ammonia or hydrofluorocarbon systems utilizing vapor compression refrigeration cycles. Large-scale German meat clusters in North Rhine-Westphalia retain mechanical dominance where existing compressor infrastructure and technician concentration support maintenance economies.
- Cryogenic:Direct expansion systems using liquid nitrogen or carbon dioxide as primary refrigerants. Benelux prepared foods contractors adopt cryogenic crust-freezing for coated products, eliminating F-Gas inventory compliance while cutting cycle times by forty percent versus mechanical alternatives.
- Liquid Nitrogen:Sub-segment of cryogenic systems with highest freezing rate capability for premium texture preservation.
- Liquid Carbon Dioxide:Alternative cryogenic medium with lower unit cost but reduced thermal capacity versus nitrogen.
- Hybrid Freezing:Combined mechanical pre-cooling with cryogenic finishing for optimized energy-refrigerant tradeoffs.
- Vacuum Freezing:Pressure-reduced sublimation systems for specialized high-value applications with minimal thermal damage tolerance.
Mechanical compression retains installed base dominance; hybrid configurations are expanding most quickly as processors balance compliance elimination against nitrogen supply infrastructure requirements.
Application:
Volume concentration in protein processing rotates technology selection toward high-throughput IQF and blast configurations, while prepared foods diversification pulls cryogenic adoption for texture-critical coated products.
- Seafood Processing:Rapid freezing requirements for enzymatic activity arrest in high-value marine species. Norwegian and Scottish salmon facilities prioritize IQF and plate freezing to maintain export-grade cellular integrity through extended cold chain distribution.
- Meat Preparation:Poultry and red protein operations in Germany and Poland driving blast freezer and spiral system deployment for portion-controlled retail packaging.
- Vegetables Treatment:Seasonal harvest concentration requiring flexible capacity scaling in Spanish and Italian cooperative processing networks.
- Ready Meals Manufacturing:Complex multi-component freezing with texture preservation demands for pasta, rice, and sauce matrices.
- Dairy Products Handling:Ice cream and cheese freezing with strict temperature control for crystal structure management.
- Fruit Preservation:Berry and tropical fruit IQF applications where clumping prevention preserves retail presentation value.
Meat preparation commands the largest equipment installed base; ready meals manufacturing is climbing the fastest as co-manufacturing consolidation standardizes freezing line specifications across central kitchen networks.
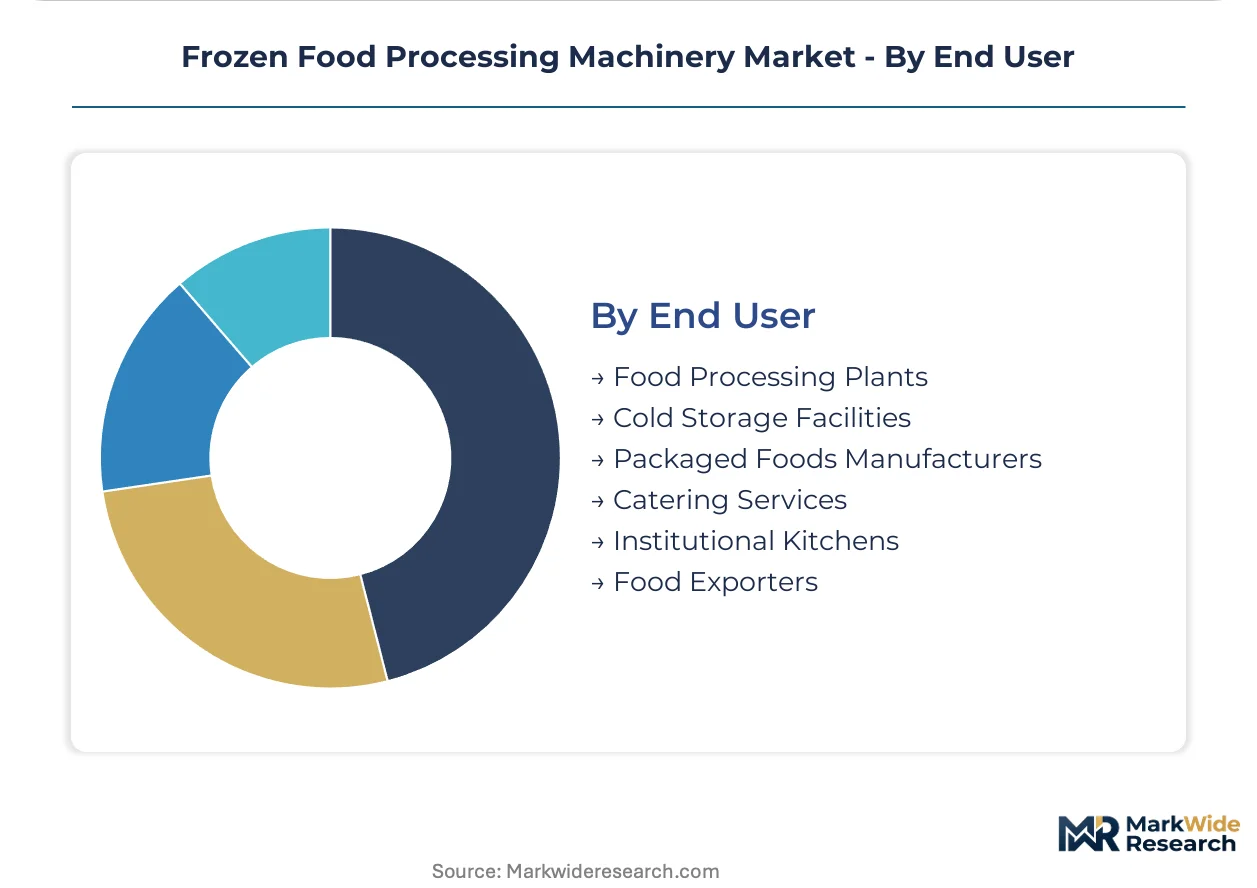
End User:
Customer type segmentation differentiates procurement authority, with packaged foods manufacturers holding specification-setting power over equipment fabricators versus captive cold storage operators following processor-directed configurations.
- Food Processing Plants:Integrated protein and prepared foods facilities with direct capital allocation authority. Large German poultry processors in Bavaria and Lower Saxony specify turnkey freezing lines with predictive maintenance integration, consolidating supplier relationships to simplify compliance documentation.
- Packaged Foods Manufacturers:Co-manufacturing and branded goods producers serving retail chain central kitchens. Benelux contractors standardize on single-source freezing platforms to meet unified technical audits from Aldi, Lidl, and Carrefour procurement teams.
- Cold Storage Facilities:Third-party logistics operators with equipment selection constrained by shipper requirements.
- Catering Services:Institutional and commercial foodservice with batch-scale freezing needs.
- Institutional Kitchens:Hospital, education, and government facility food preparation with regulatory compliance priorities.
- Food Exporters:Trade-oriented processors with destination-country certification requirements shaping equipment specifications.
Food processing plants account for the dominant share of capital deployment; packaged foods manufacturers are expanding fastest as retail chain consolidation concentrates procurement leverage over freezing line standards.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German protein processing clusters while Italian fabricators absorb margin compression from stainless steel volatility. Equipment specification authority tilts toward northern European retail chains over southern European cooperatives.
Germany
Lower Saxony poultry processors retrofit IQF lines to meet Aldi and Lidl shelf-life mandates. The EU F-Gas Regulation accelerates cryogenic adoption at facilities in North Rhine-Westphalia. Bavarian meat clusters deploy predictive maintenance subscriptions to minimize ammonia system downtime.
Netherlands
Benelux co-manufacturers standardize on single-source freezing platforms for Carrefour central kitchen compliance. REACH substance restrictions force eighteen-month redesign cycles for compressor lubricants. Rotterdam-area vegetable cooperatives access NextGenerationEU grants for hybrid freezing upgrades.
Norway
Bergen salmon processors eliminate hydrofluorocarbon inventories through hybrid mechanical-cryogenic configurations. ECHA PFAS restrictions drive seal and gasket reformulation across equipment fleets. Trondheim seafood facilities prioritize IQF yield optimization to maintain export-grade cellular integrity.
Spain
Andalusian vegetable processing networks expand seasonal capacity through modular blast freezer deployment. EU Green Deal facility modernization grants accelerate replacement cycles in Murcia agricultural cooperatives. Barcelona-area prepared foods contractors adopt nitrogen crust-freezing for coated product texture preservation.
Poland
Poultry processing automation pulls demand for spiral freezers in Silesian manufacturing zones. The EU F-Gas phase-down compresses refrigerant choice sets for Warsaw-area protein facilities. Poznan equipment distributors report extended commissioning timelines from legacy SCADA integration demands.
Frozen Food Processing Machinery Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the frozen food processing machinery sector. Integrated turnkey providers command premium positioning through end-to-end refrigeration and processing integration, while component specialists compete on fabrication flexibility and shorter delivery cycles. The market structure segments into three strategic archetypes: full-system integrators, freezing technology specialists, and regional fabrication houses. Competitive moves concentrate on strategic partnerships for nitrogen supply infrastructure and portfolio diversification into predictive maintenance services.
Among European-integrated conglomerates, GEA Group and Alfa Laval occupy positions exemplifying the full-system archetype through their refrigeration and processing integration capabilities. JBT Corporation represents the freezing technology specialist tier, anchoring market presence through tunnel and coating system focus. Tetra Pak sits within the packaging-processing convergence segment, leveraging beverage industry adjacencies into frozen dairy applications.
| Leading Market Players |
|---|
| GEA Group |
| JBT Corporation |
| Marel |
| Alfa Laval |
| Tetra Pak |
| FRIGOGLASS |
| OctoFrost Group |
| Starfrost |
| FEMIA Industries |
| Others |
Supply & Pricing Matrix
Liquid nitrogen infrastructure substitution for hydrofluorocarbon refrigerant systems simultaneously redraws supply geography toward industrial gas production clusters and compresses pricing economics for equipment fabricators absorbing stainless steel volatility. German and Dutch manufacturers face margin pressure from shortened redesign cycles driven by REACH compliance, while buyers in protein processing clusters leverage standardization mandates from retail chains to consolidate procurement leverage.
Pricing Analysis
Configured-to-order pricing for turnkey freezing lines commands premiums of thirty to fifty percent above standard blast freezer configurations, with differentiation driven by sensor integration density and predictive maintenance bundling. Stainless steel grade certification tiers separate premium sanitary-grade chambers from economy fabrications, while nitrogen supply contract structures increasingly influence total cost of ownership calculations. Pricing pressure intensifies in standard mechanical compression equipment as F-Gas phase-down schedules accelerate replacement demand and compress delivery timelines. Packaged foods manufacturers exhibit highest price sensitivity due to centralized procurement audits, whereas integrated protein processors prioritize uptime guarantees over capital expenditure minimization.
Supply Chain Analysis
Precision refrigeration compressor manufacturing concentrates in northern Italy and southern Germany, creating single-source vulnerability for sub-zero mechanical systems deployed across European protein facilities. Equipment fabrication draws from stainless steel mills in Spain and Poland, with Grade 304 and 316 supply subject to commodity price swings that propagate through sanitary-grade chamber production. Tariff exposure on Chinese-sourced control electronics and sensors threatens margin stability for mid-tier fabricators. Distribution runs through regional equipment distributors with captive service networks, extending from fabricator plants in Bavaria and Veneto to end-user facilities in Lower Saxony and Silesia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Frozen food processing machinery sits at an early-cycle expansion phase as cryogenic and hybrid platform adoption accelerates ahead of regulatory phase-down deadlines, with nitrogen supply infrastructure buildout creating downstream pull-through for equipment upgrades.
For Market Incumbents: Secure predictive maintenance service contract penetration in Scandinavian dairy operations before independent IoT platform providers establish footholds. Deepen backward integration into compressor remanufacturing capabilities to offset technician scarcity risks in peripheral installations. Prioritize REACH-compliant lubricant and seal reformulation investments to capture preferential placement in EU-bound export contracts. For New Entrants and Emerging Players: Anchor in plant-based protein freezing applications where dedicated IQF lines for pea and soy isolates remain undersupplied relative to Dutch and German capacity expansion timelines. Target modular blast freezer configurations for Spanish and Italian vegetable cooperatives accessing NextGenerationEU modernization grants. Pursue equipment-as-a-service pricing models to bypass capital expenditure barriers at mid-scale prepared foods contractors. For Investors and Strategic Acquirers: The market sits at a technology substitution phase that favors cryogenic infrastructure specialists and hybrid system integrators over pure mechanical compression legacy players. Long-term viability over the next decade hinges on nitrogen supply chain control and predictive maintenance platform ownership. Acquisition candidates with captive industrial gas partnerships and sensor-integrated yield optimization software represent priority targets. Watch nitrogen terminal capacity expansion announcements as the signal for equipment demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Compressor Remanufacturing | Captive refurbishment capacity mitigates technician scarcity and extends service revenue capture in ammonia systems. |
| Hybrid Freezing Platform Launch | Mechanical-cryogenic configurations eliminate F-Gas compliance burdens while preserving throughput for Norwegian salmon processors. |
| Predictive Maintenance Subscription Rollout | Vibration and thermal sensor packages displace break-fix arrangements in Bavarian meat clusters. |
| REACH-Compliant Material Reformulation | PFAS-free lubricant and seal redesign secures preferential placement in EU-bound export contracts ahead of broader restrictions. |
| Nitrogen Supply Infrastructure Partnership | Industrial gas terminal access agreements anchor equipment placement at Benelux prepared foods central kitchens. |
Research Methodology
The analysis maps blast freezer, IQF system, cryogenic freezer, and hybrid platform sub-sectors, each validated through maintenance directors at protein processing facilities, plant engineers at dairy cooperatives, OEM procurement teams at equipment fabricators, and aftermarket service heads at regional distributors. Primary interview findings triangulated against customs data for stainless steel equipment imports, SEC filings of listed machinery manufacturers, EU F-Gas Regulation implementation reports, and industrial gas supply databases. Bottom-up equipment deployment estimates cross-checked with top-down protein processing capacity expansion projections across the analysis window.
Consistency checks validated volume and value outputs against external benchmarks including nitrogen consumption data from industrial gas suppliers and refrigeration equipment trade association shipment reports. Segmentation modeling incorporated product type, technology platform, application category, and end-user procurement authority dimensions across the projection horizon. CAGRs derived from equipment replacement cycle analysis and regulatory compliance deadline clustering, with nitrogen terminal capacity buildout schedules and F-Gas phase-down milestones serving as key forecast inputs.
Material uncertainties — refrigerant technology substitution rates, stainless steel price volatility, and nitrogen supply infrastructure completion delays — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory enforcement consistency and retail chain standardization timelines. Practitioners should keep alternative scenarios live as EU Green Deal grant disbursement patterns and ECHA PFAS restriction scope evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Sheet Metal Processing Equipment Market
Food Processing Equipment
Commercial Food Processors Market
Food Processing Equipment
Global Industrial Bakery Processing Equipment Market
Food Processing Equipment
Brewing Boiler Market
Food Processing Equipment
Asia-Pacific Commercial Sous Vide Machine Market
Food Processing Equipment
Tea Processing Equipment Market
Food Processing Equipment
Wine Bottling Machine Market
Food Processing Equipment
Reflow Oven Market
Food Processing Equipment
Vee Bee Consistometer Market
Food Processing Equipment
Global Conveyor Oven Market
Food Processing Equipment
Air Cooled Cube Ice Machines Market
Food Processing Equipment
Homogenizers Market
Food Processing Equipment
Flake Ice Machines Market
Food Processing Equipment
Filleting Machines Market
Food Processing Equipment
Mobile Bottling Line Market
Food Processing Equipment
Food Processor Market