
 Contact and Convective Dryers Market | 2026-2036
Contact and Convective Dryers Market Size, Share, and Industry Trends Forecast 2026-2036
Contact and Convective Dryers Market Outlook
REACH compliance is expanding capital requirements for European dryer installations. GEA Group leverages its process engineering portfolio to serve dairy and pharmaceutical clients with integrated thermal solutions. Andritz AG anchors its position through heavy investment in pulp and paper drying systems. Bühler Group competes aggressively in food processing with custom-configured belt dryer lines.
Contact and convective dryers remove moisture from solids, slurries, and pastes through direct heat transfer at temperatures typically ranging from 40°C to 300°C depending on material sensitivity and thermal degradation thresholds; conduction dryers transfer heat through a heated surface while convection dryers force heated air across the product bed, with hybrid systems combining both mechanisms for heat-sensitive pharmaceuticals and nutraceuticals. Drum dryers dominate mature bulk chemical applications where throughput economics override energy precision, while flash dryers capture the fastest expansion in instant food and starch processing due to sub-second residence times that preserve volatile flavor compounds. Belt dryers concentrate margin pools in premium food segments where gentle dehydration at controlled humidity preserves cellular structure and rehydration performance.
FDA cGMP guidelines and EPA emissions standards shape equipment specifications across US pharmaceutical and chemical installations, while EU F-Gas Regulation and CE marking requirements constrain refrigerant-based dehumidification integrations in European systems. India's BIS energy performance standards and China's GB standards on industrial thermal efficiency are redirecting procurement toward heat-recovery configurations and variable-frequency drive systems. Stakeholders must monitor evolving carbon border adjustment mechanisms and regional efficiency benchmarks to align capital deployment with compliance timelines that outpace current product certification cycles.
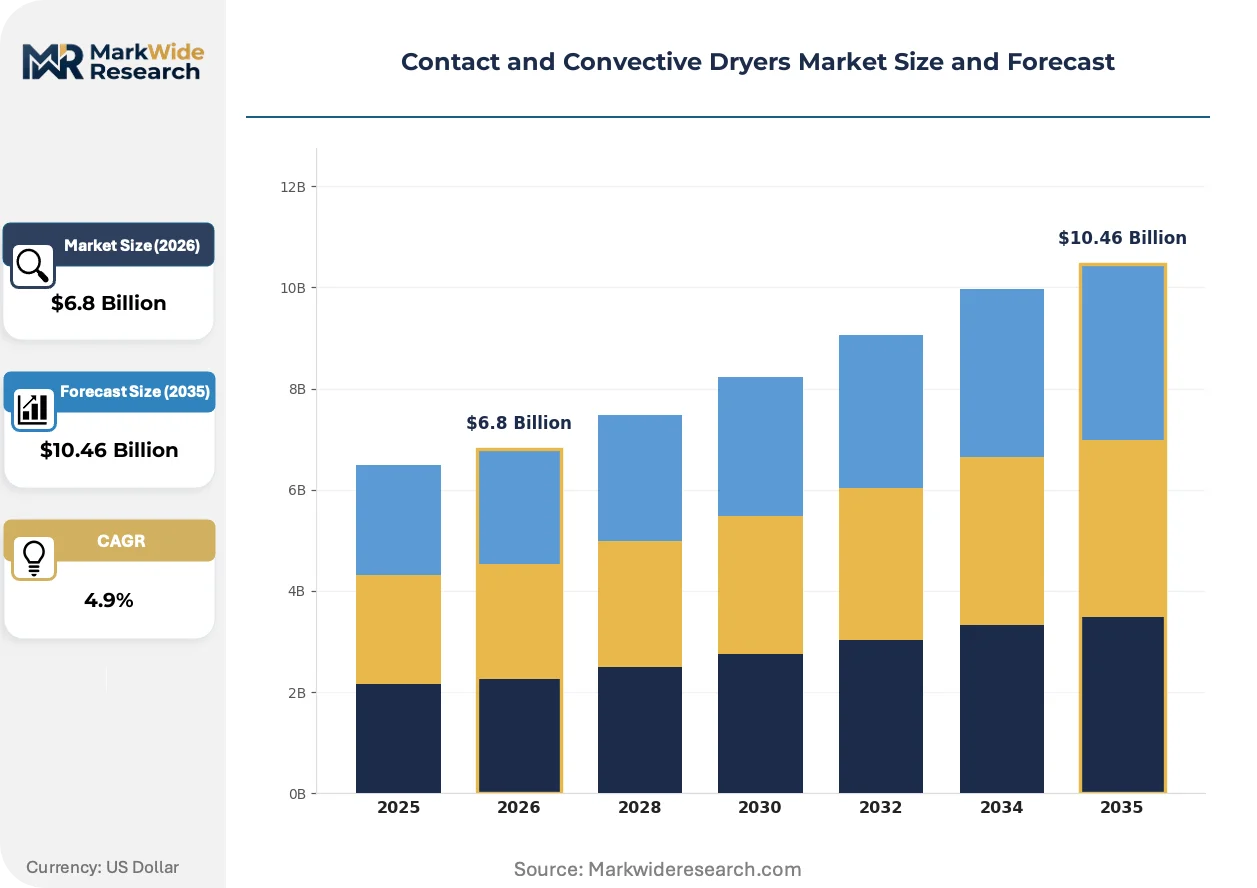
Market Dynamics
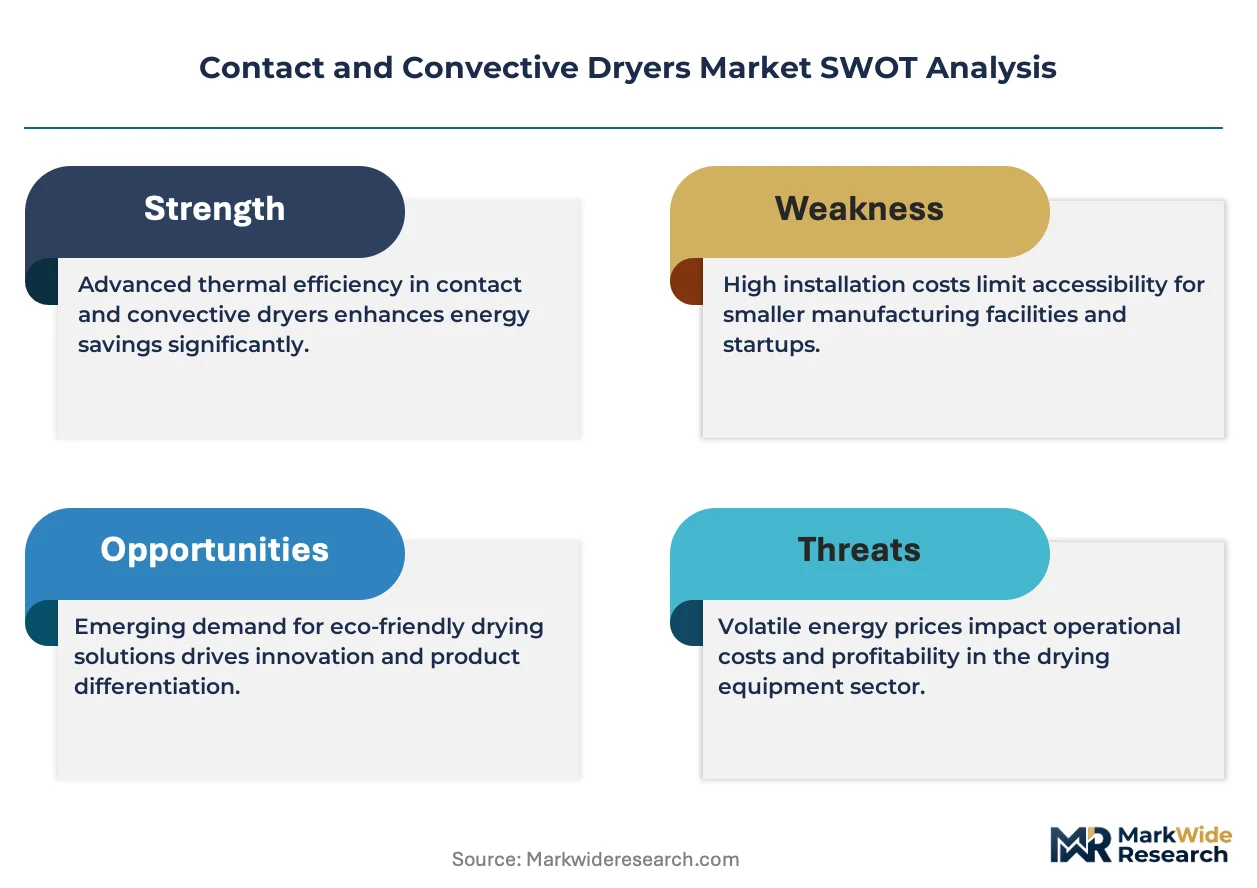
Energy-efficiency mandates across major manufacturing jurisdictions are compressing equipment replacement cycles and redirecting capital toward heat-recovery configurations and hybrid thermal systems.
Growth Catalysts
- EU F-Gas Regulation:Refrigerant phase-down requirements are accelerating upgrades to closed-loop convective systems with non-fluorinated heat transfer fluids in pharmaceutical and dairy processing facilities.
- Instant food manufacturing:Flash dryer installations are expanding in starch and flavor compound preservation lines where sub-second residence times protect volatile organoleptic properties.
- Hyderabad pharmaceutical corridor:India's PLI scheme for active pharmaceutical ingredients is driving demand for cGMP-compliant conduction dryers with integrated clean-in-place protocols.
Market Restraints
- Stainless steel price volatility:Drum and belt dryer fabrication costs swing with nickel and chromium input markets, compressing margins on fixed-price installation contracts.
- REACH compliance capital burden:European chemical processors face extended certification timelines for thermal equipment with refrigerant-based dehumidification, delaying procurement decisions.
- Heat pump substitution:Low-temperature drying below 80°C is migrating to vapor-compression heat pump systems in food applications, displacing conventional gas-fired convection units.
Strategic Opportunities
- Indonesia palm kernel processing:Belt dryer retrofits in Sumatra and Kalimantan facilities present untapped demand for gentle dehydration preserving cellular structure in oleochemical feedstocks.
- CE marking convergence with ISO 14001:Unified environmental and safety certification pathways are reducing compliance friction for European equipment vendors exporting to Middle Eastern food processors.
- AI-driven moisture control:Machine vision and near-infrared sensing integration with variable-frequency drive systems is enabling real-time residence time adjustment in hybrid dryer configurations.
Industry Challenges
- Thermal process engineering talent scarcity:Design of heat-and-mass transfer systems for heat-sensitive nutraceuticals requires specialized expertise concentrated in German and Swiss technical universities.
- Legacy DCS integration complexity:Brownfield pharmaceutical facilities running Siemens or Rockwell distributed control systems face protocol mismatches with modern dryer automation architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Contact and Convective Dryers Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.46 Billion |
| CAGR (2026 – 2036) | 4.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Drum Dryers, Belt Dryers, Tray Dryers, Flash Dryers Application: Food Processing, Pharmaceuticals, Chemicals, Textiles End User: Manufacturers, Laboratories, Research Institutions, Food Industry Technology: Conduction, Convection, Radiation, Hybrid |
| Companies Covered | GEA Group, Andritz AG, Bühler Group, SPX FLOW, FLSmidth & Co. A/S, Hosokawa Micron Group, SaintyCo, Thyssenkrupp AG, JBT Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Contact and Convective Dryers Market Strategic Shifts
Digitalization of thermal process control and modular equipment architectures are compressing commissioning timelines and enabling rapid reconfiguration between product campaigns.
Hybrid conduction-convection dryer platforms are modularizing around standardized heat exchanger cartridges and interchangeable air handling units. Pharmaceutical contract manufacturers in Ireland and Singapore are adopting these configurable systems to switch between API drying and nutraceutical dehydration within single shifts. This architecture is compressing vendor engineering hours and enabling faster geographic deployment without site-specific fabrication.
REACH authorization requirements for chromium trioxide in surface treatments are forcing migration to alternative coatings for drum dryer rolls in European chemical installations. Stainless steel plasma nitriding and ceramic thermal spray processes are displacing hard chrome plating in food-contact applications. Dairy processors in Denmark and the Netherlands are absorbing 15-20% capital premiums to secure compliant equipment ahead of sunset dates.
Equipment-as-a-service contracting is displacing traditional capital purchase models in mid-scale food processing. Brazilian soybean meal processors and Thai tapioca starch manufacturers are adopting throughput-based pricing with vendor-retained ownership of dryer assets. This transfers energy efficiency risk to OEMs and accelerates technology refresh cycles beyond typical 15-year depreciation schedules.
Contact and Convective Dryers Market Segmentation
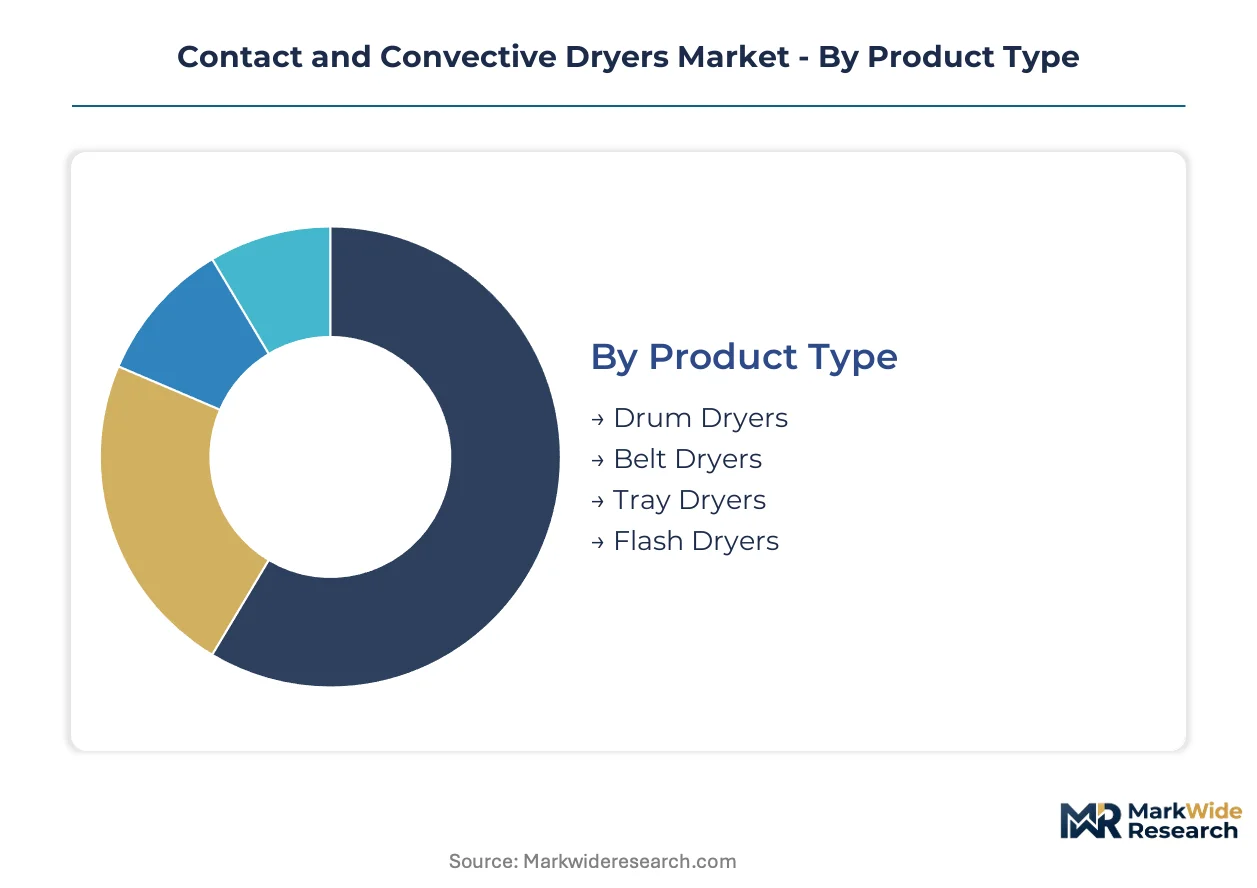
Dryer selection cascades through thermal sensitivity, throughput requirements, and regulatory exposure. Procurement teams map product specifications against end-use constraints and energy mandates to optimize capital deployment.
Product Type:
Standalone drum and belt configurations dominate process lines with continuous throughput requirements, while tray and flash systems embed into batch operations and instant processing lines respectively.
- Drum Dryers:Heated cylindrical shells rotate through slurry baths to deposit thin films that dry in single revolutions. Bulk chemical processors in Germany favor these for mature applications where throughput economics override energy precision, though nickel price volatility compresses fabrication margins.
- Belt Dryers:Perforated conveyor systems force conditioned air through product beds at controlled humidity. Premium food segments in Denmark concentrate demand here, as gentle dehydration preserves cellular structure and rehydration performance in specialty ingredients.
- Tray Dryers:Static batch chambers with recirculated air suit low-volume pharmaceutical intermediates. Swiss contract manufacturers deploy these for heat-sensitive API campaigns requiring precise temperature profiling.
- Flash Dryers:Pneumatic conveyance through heated gas streams achieves sub-second residence times. Starch and flavor compound preservation lines in Thailand expand installations to protect volatile organoleptic properties.
Drum dryers lead volumes today; flash dryers are gaining share fastest.
Application:
Margin pools concentrate where thermal degradation thresholds intersect with regulatory stringency, creating tiered value capture across end-use verticals.
- Food Processing:Belt and flash configurations handle everything from vegetable dehydration to instant coffee production. Indonesian palm kernel processors in Sumatra and Kalimantan present untapped retrofit demand for gentle cellular preservation in oleochemical feedstocks.
- Pharmaceuticals:cGMP-compliant conduction dryers with clean-in-place protocols dominate active ingredient manufacturing. India's Hyderabad corridor drives equipment upgrades as PLI scheme incentives expand API production capacity.
- Chemicals:Drum dryers anchor mature bulk operations. REACH authorization timelines for chromium trioxide surface treatments are forcing European installations toward plasma-nitrided stainless steel alternatives at 15-20% capital premiums.
- Textiles:Convective tunnel systems handle fiber conditioning and finishing. Brazilian manufacturers are adopting throughput-based equipment-as-a-service contracts that transfer energy efficiency risk to OEMs.
Food processing leads volumes today; pharmaceuticals are expanding most quickly.
End User:
Scale and certification requirements split procurement patterns between commercial production and validation-focused operations.
- Manufacturers:Continuous processing lines demand integrated thermal solutions with heat recovery and variable-frequency drive systems. Dairy processors across the Netherlands prioritize energy-efficiency configurations to meet tightening EU F-Gas compliance deadlines.
- Laboratories:Bench-scale tray and fluidized bed units support formulation development. Singaporean pharmaceutical contract manufacturers specify modular platforms that reconfigure between API drying and nutraceutical dehydration within single shifts.
- Research Institutions:Pilot-scale hybrid systems enable process parameter mapping before commercial scale-up. German technical universities concentrate specialized thermal process engineering expertise for heat-sensitive nutraceutical design.
- Food Industry:Mid-scale processors in Thailand and Brazil are migrating from capital purchase models to vendor-retained ownership with throughput-based pricing, accelerating technology refresh beyond typical depreciation schedules.
Manufacturers lead volumes today; food industry adopters are climbing the fastest.
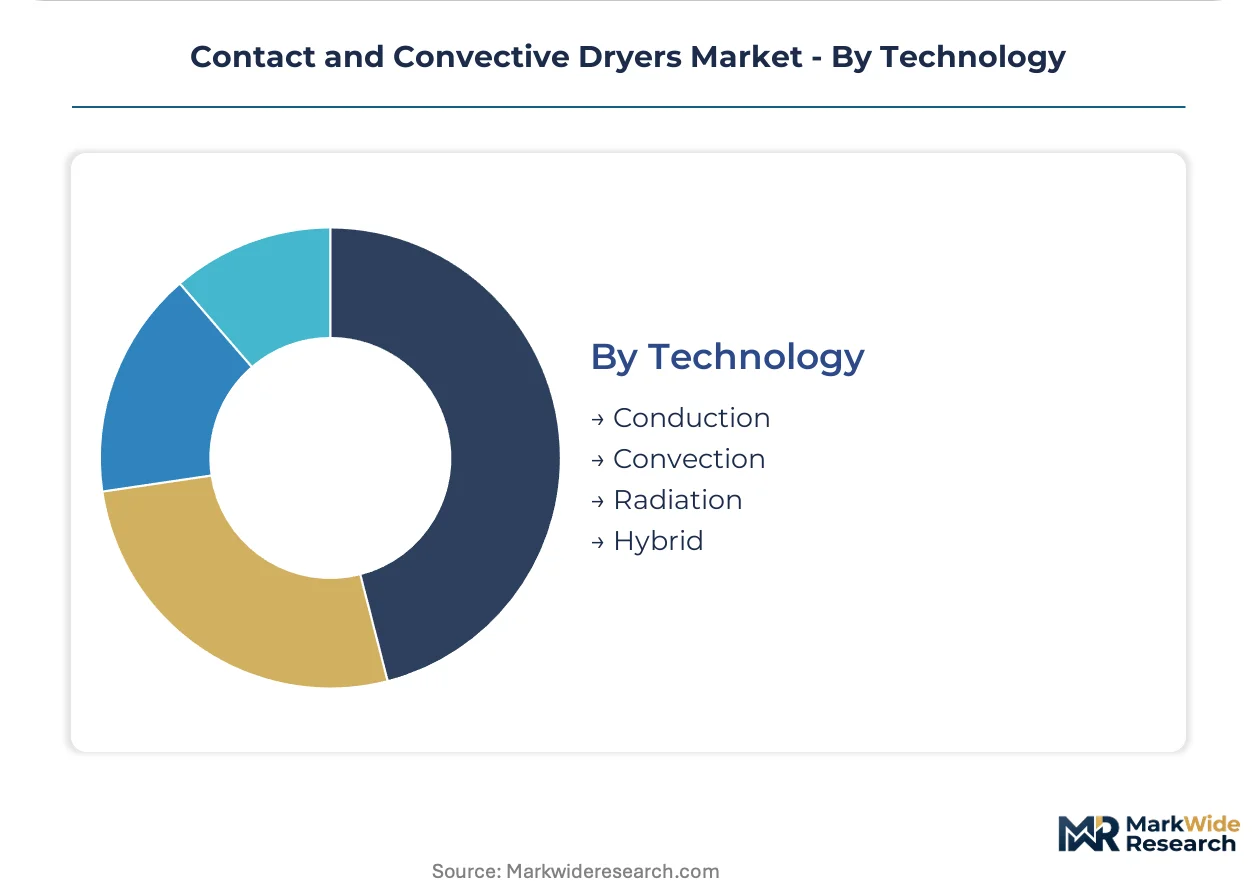
Technology:
Heat transfer mechanism selection hinges on product sensitivity, energy source availability, and dehumidification integration constraints.
- Conduction:Heated surface contact delivers precise temperature control for heat-sensitive materials. Pharmaceutical installations near Hyderabad specify these for cGMP compliance with integrated clean-in-place protocols.
- Convection:Forced hot air systems dominate food applications with moderate thermal sensitivity. EU F-Gas refrigerant phase-down requirements are accelerating upgrades to closed-loop configurations with non-fluorinated heat transfer fluids.
- Radiation:Infrared and microwave systems target surface moisture in specialized coatings and thin-film applications. Limited penetration constrains adoption to niche segments.
- Hybrid:Combined conduction-convection platforms optimize residence time and temperature profiling. Irish pharmaceutical contract manufacturers adopt these configurable systems for rapid campaign switching without site-specific fabrication.
Convection leads volumes today; hybrid systems show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered industrial drying technology through its chemical and pharmaceutical machinery heritage, establishing engineering standards that still shape equipment specifications worldwide. The sector's geographic footprint now reflects energy policy divergence and food processing migration toward tropical feedstock sources.
Germany
Drum dryer fabrication for bulk chemical processors anchors demand in the Ruhr industrial corridor. REACH authorization timelines for chromium trioxide surface treatments are forcing migration toward plasma-nitrided stainless steel alternatives. Equipment vendors in North Rhine-Westphalia absorb 15-20% capital premiums to secure compliant machinery ahead of regulatory sunset dates.
United States
FDA cGMP guidelines and EPA emissions standards shape pharmaceutical and chemical installation specifications across the Great Lakes manufacturing belt. Flash dryer deployments are expanding in Wisconsin and Iowa starch processing facilities. Corn belt processors prioritize sub-second residence times to preserve volatile flavor compounds in instant food lines.
India
The PLI scheme for active pharmaceutical ingredients is driving cGMP-compliant conduction dryer demand in Telangana's Hyderabad pharmaceutical corridor. BIS energy performance standards redirect procurement toward heat-recovery configurations. Contract manufacturers near Genome Valley specify integrated clean-in-place protocols for API drying campaigns.
Indonesia
Palm kernel processing in Sumatra and Kalimantan presents untapped retrofit demand for belt dryer systems. Gentle dehydration preserving cellular structure in oleochemical feedstocks commands premium pricing. Sumatran facilities are upgrading legacy equipment to meet European oleochemical import specifications.
Denmark
Dairy processors across Jutland prioritize energy-efficiency configurations to meet tightening EU F-Gas compliance deadlines. Belt dryers concentrate margin pools in premium food segments where controlled humidity preserves rehydration performance. Arla Foods' supplier network drives specification standards for gentle dehydration technology.
Contact and Convective Dryers Market Competitive Environment
The competitive structure tilts toward diversified process engineering conglomerates with thermal system integration capabilities. Market positions stratify across three tiers: full-line thermal solution providers, specialized drying equipment fabricators, and regional batch-system suppliers. Consolidation pressure is mounting as energy-efficiency mandates raise R&D thresholds. Strategic moves center on modular platform development and equipment-as-a-service contracting models that transfer operational risk to OEMs.
Among diversified European engineering groups, GEA Group and Andritz AG exemplify the full-line integration archetype, while Bühler Group occupies a position within the food-processing specialization tier. These anchors demonstrate how process engineering heritage translates into thermal system specification authority across pharmaceutical, dairy, and bulk chemical verticals. Their geographic footprint and certification breadth create defensive positioning against emerging Asian fabricators.
| Leading Market Players |
|---|
| GEA Group |
| Andritz AG |
| Bühler Group |
| SPX FLOW |
| FLSmidth & Co. A/S |
| Hosokawa Micron Group |
| SaintyCo |
| Thyssenkrupp AG |
| JBT Corporation |
| Others |
Value Chain & Pricing Dynamics
Nickel and chromium price indices on the London Metal Exchange cascade through stainless steel fabrication costs into three-tier pricing structures across premium, standard, and economy equipment tiers. Pharmaceutical processors in Hyderabad absorb 15-20% capital premiums for cGMP-compliant conduction dryers, while Indonesian palm kernel facilities negotiate standard-tier belt configurations amid volatile alloy input markets.
Pricing Analysis
Project-based equipment contracting with throughput-based performance guarantees dominates procurement for mid-scale food processors in Thailand and Brazil. Price differentiation separates FDA-validated pharmaceutical tiers from standard food-grade configurations, with certification level and customization depth as primary drivers. Cost compression in standard-tier drum dryers is intensifying because nickel price volatility squeezes fabrication margins on fixed-price installation contracts. Contract manufacturers exhibit highest price sensitivity; dairy multinationals in Denmark demonstrate lowest sensitivity due to energy-efficiency compliance deadlines.
Supply Chain Analysis
Container freight rates from German and Swiss engineering hubs to Southeast Asian installation sites feed into landed cost calculations for modular hybrid systems. Manufacturing concentrates in Germany, Switzerland, and India, with stainless steel rolls and heat exchanger cartridges drawing from Italian and Chinese component suppliers. Single-source vulnerability in specialized thermal spray coating capacity for REACH-compliant drum surfaces threatens European delivery timelines. Distribution runs through OEM-direct channels for pharmaceutical installations and regional equipment distributors for food processing retrofits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU F-Gas refrigerant phase-down deadlines and India's BIS energy performance standards are compressing replacement cycles and redirecting capital toward heat-recovery configurations.
For Market Incumbents: Hedge against heat pump substitution in low-temperature food applications by accelerating hybrid conduction-convection platform development. Secure captive supply of plasma-nitrided stainless steel coating capacity before REACH chromium trioxide sunset dates eliminate competing drum fabrication methods. Vertical integration into modular heat exchanger cartridge production in India reduces exposure to European alloy price volatility.
For New Entrants and Emerging Players: Mid-scale Indonesian palm kernel processors represent an underserved buyer archetype requiring gentle dehydration technology for oleochemical feedstock cellular preservation. Target equipment-as-a-service contracting in Brazilian soybean meal processing where vendor-retained ownership transfers energy efficiency risk and accelerates refresh cycles. Lead with AI-driven moisture control integration as a differentiated go-to-market angle against legacy DCS-dependent incumbents.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized thermal process engineering firms holding concentrated expertise in German and Swiss technical universities. Long-term viability over a multi-year horizon favors acquisition targets with modular platform architectures enabling rapid geographic deployment without site-specific fabrication. Monitor CE marking convergence with ISO 14001 certification pathway simplification as an inflection indicator for European vendor export competitiveness into Middle Eastern food processing markets.
| Strategic Initiative | Industry Significance |
|---|---|
| Modular Platform Standardization | Compresses vendor engineering hours for Irish pharmaceutical contract manufacturers switching between API and nutraceutical campaigns. |
| Backward Integration into Coating Technology | Secures REACH-compliant plasma nitriding capacity ahead of chromium trioxide authorization sunset in European chemical installations. |
| Equipment-as-a-Service Contracting | Transfers energy efficiency risk to OEMs while accelerating technology refresh beyond 15-year depreciation schedules in Thai starch processing. |
| AI-Driven Moisture Control Integration | Enables real-time residence time adjustment through machine vision and near-infrared sensing in hybrid dryer configurations. |
| Geographic Manufacturing Footprint Expansion | Positions fabrication capacity near India's Hyderabad pharmaceutical corridor to capture PLI scheme-driven API production growth. |
Study Parameters
Coverage spans Germany, Switzerland, India, Indonesia, and the United States, with primary inputs from each market informing demand calibration. The research combines structured interviews with plant engineers, OEM procurement teams, aftermarket service heads, and thermal process engineering directors at pharmaceutical and food processing facilities with secondary validation from SEC filings, customs and trade data, BIS and GB standard documentation, and EU regulatory authorization timelines. Bottom-up equipment shipment data triangulates against top-down capital expenditure patterns across end-use verticals.
Granularity-level modeling disaggregates volume and value outputs by product type, application, technology, and end user across the projection horizon. The analytical framework derives expansion rates from historical replacement cycle compression, regulatory mandate phase-in schedules, and energy price trajectory assumptions. Industry-specific forecast inputs include stainless steel price volatility coefficients and pharmaceutical PLI scheme capacity addition pipelines.
Underlying measurement precision varies by segment; flash dryer and hybrid system forecasts carry tighter precision than mature drum dryer categories given technology transition uncertainty. Forecasts reflect documented assumptions regarding regulatory enforcement timing and commodity price stabilization. A model refresh is warranted upon material change in EU F-Gas refrigerant phase-down implementation schedules or nickel market structural shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Industrial Steam Peeler Market
Food Processing Equipment
Global Powder Processing Equipment Market
Food Processing Equipment
Pet Food Extrusion Market
Food Processing Equipment
Food Industry Vacuum Cooling Equipment Market
Food Processing Equipment
Canada Industrial Food and Beverages Filtration System Market
Food Processing Equipment
Brewing Equipment Market
Food Processing Equipment
Europe Commercial Sous Vide Machine Market
Food Processing Equipment
Conveyor Ovens and Impinger Ovens Market
Food Processing Equipment
Oceania Commercial Ice Machine Market
Food Processing Equipment
Commercial Tunnel Oven Market
Food Processing Equipment
Food Ultrasound Market
Food Processing Equipment
Vee Bee Consistometer Market
Food Processing Equipment
Bottling Line Machinery Market
Food Processing Equipment
Non-Thermal Food Processing Market
Food Processing Equipment
Food Waste Disposers Market
Food Processing Equipment
India Household Flour Milling Machines Market