
 Food Thermos Market | 2026-2036
Food Thermos Market Size, Share, and Industry Trends Forecast 2026-2036
Food Thermos Market Analytics
EU REACH compliance is expanding the cost-of-entry calculus for food thermos manufacturers importing into Europe. Thermos L.L.C leverages its century-old brand heritage and Japanese engineering partnerships to sustain premium positioning across North American retail channels. Zojirushi America Corporation anchors its competitive stance through proprietary vacuum insulation technology and direct control over Asian manufacturing assets. Tiger Corporation specializes in compact-capacity designs that dominate Japanese commuter markets and extend into Southeast Asian expansion.
A food thermos is a double-walled, thermally insulated vessel engineered to maintain food temperature through vacuum-sealed or foam-insulated construction, typically fabricated from 18/8 stainless steel with copper-plated inner walls to minimize radiative heat loss. Its primary commercial purpose is safe, portable food storage for institutional meal programs, outdoor recreation, and daily commuting. Stainless steel vacuum flasks command the dominant margin pool due to durability premiums and replacement-cycle economics, while plastic variants compete on entry-price positioning in school-lunch procurement. The 500ml to 750ml capacity band leads volume shipments, though 1000ml+ formats are gaining fastest in outdoor activities and construction-site meal delivery.
FDA food-contact material standards govern US market access, while EU REACH and RoHS directives restrict heavy-metal content in coatings and sealing gaskets. Japan's Ministry of Economy, Trade and Industry (METI) enforces JIS standards for thermal retention performance that shape product development priorities for export-oriented manufacturers. China's National Medical Products Administration (NMPA) and Ministry of Ecology and Environment (MEE) jointly regulate food-contact safety and environmental compliance for domestic production. Stakeholders must monitor evolving PFAS restrictions in Europe and North America, as fluoropolymer-based nonstick interior coatings face phased elimination that will force material substitutions across the supply base.
Market Dynamics
Vacuum insulation technology is consolidating manufacturing footprints as hydrofluorocarbon phase-out mandates under EU F-Gas Regulation force retooling investments across the supply base.
Growth Catalysts
- EU F-Gas Regulation:The phased elimination of hydrofluorocarbon blowing agents accelerates adoption of vacuum-sealed double-wall construction, redirecting R&D budgets toward copper-plated stainless steel architectures.
- School lunch procurement:Institutional meal programs in the United States and China specify thermal retention performance standards that favor durable 18/8 stainless steel vessels over disposable alternatives.
- Urban commuting culture:Dense metropolitan transport networks in China normalize portable meal consumption, sustaining replacement-cycle demand for 500ml to 750ml capacity formats.
Market Restraints
- Nickel price volatility:18/8 stainless steel input costs fluctuate with nickel futures traded on the London Metal Exchange, compressing margin pools for mid-tier fabricators.
- Guangdong-Zhejiang supply concentration:Over two-thirds of vacuum flask manufacturing clusters within a 300-kilometer corridor along China's eastern seaboard creates logistics vulnerability and labor competition.
- Thermal retention ceiling:Vacuum insulation physics limits practical heat retention duration to 12-24 hours, constraining premium pricing differentiation beyond material finishes.
Strategic Opportunities
- India institutional catering:Midday meal schemes under the National Food Security Act generate bulk procurement volumes underserved by current import-dependent supply chains.
- PFAS-free coating chemistry:Fluoropolymer interior lining bans in Europe and North America create first-mover advantage for ceramic-based or uncoated stainless steel interior solutions.
- Direct-to-institution channels:Construction site meal delivery and outdoor recreation rental programs bypass retail markup structures, capturing full margin on 1000ml+ capacity formats.
Industry Challenges
- Vacuum seal integrity testing:Mass production lines require helium leak detection equipment with 24-month depreciation schedules, elevating breakeven volumes for new entrants.
- Multi-jurisdiction certification:Simultaneous FDA, EU REACH, and JIS compliance creates documentation burden and testing timeline conflicts for export-oriented manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Thermos Market |
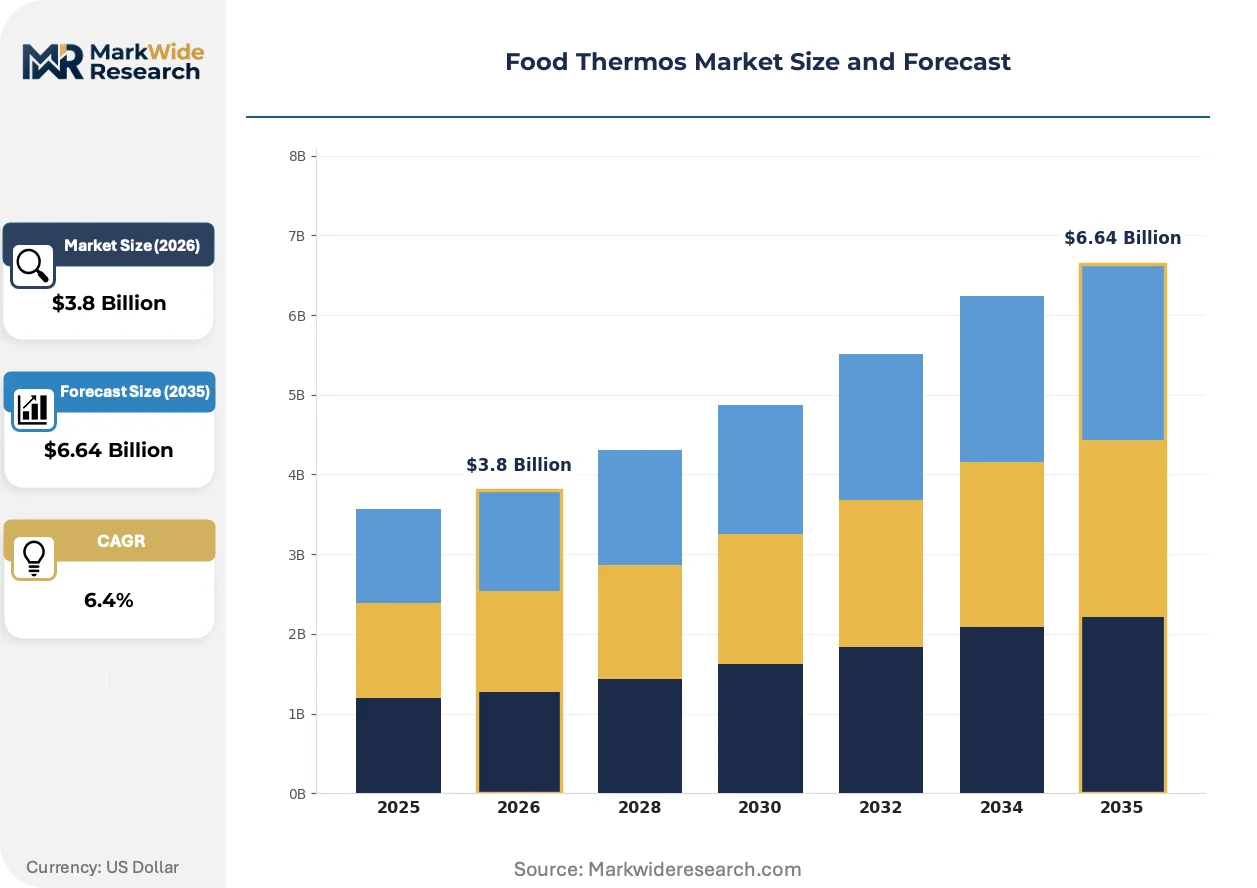
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulated Containers, Vacuum Flasks, Food Jars, Soup Thermoses Material: Stainless Steel, Plastic, Glass, Aluminum Capacity: 500ml, 750ml, 1000ml, 1500ml Application: Outdoor Activities, School Lunches, Travel, Daily Use |
| Companies Covered | Thermos L.L.C, Zojirushi America Corporation, Cambro Foodservice Equipment and Supplies, Stanley Black & Decker, Newell Brands, Carlisle FoodService Products, Huhtamaki, TokyoPlast, Tiger Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Thermos Market Evolving Landscape
Material substitution and regulatory chemistry restrictions are compressing traditional coating supply chains while redirecting competitive advantage toward metallurgical engineering capabilities.
Copper-plated inner wall construction is consolidating quality tiers across the stainless steel vacuum flask segment. Premium positioning now requires demonstrable radiative heat loss minimization through electroplated copper layers 0.3-0.5 microns thick. Japanese commuter markets and North American outdoor recreation buyers specify this architecture in procurement tenders, forcing mid-tier Chinese fabricators to license plating technology or retreat to uncoated entry-price positioning.
REACH Annex XVII PFAS restrictions are eliminating fluoropolymer-based nonstick interior coatings from European market access. ECHA enforcement timelines compress reformulation windows to 18-24 months for incumbent suppliers. Ceramic-based and electropolished bare steel alternatives capture shelf space previously dominated by coated products, with German and French retail buyers leading preference shifts ahead of formal deadline dates.
Construction site meal delivery programs are aggregating demand into specification-driven procurement. Contractors in the United States and Australia issue thermal retention performance bonds that require third-party JIS or ISO certification, displacing retail brand loyalty with documented test results. This pattern concentrates volume with manufacturers maintaining captive testing laboratories, fragmenting remaining demand across price-competitive unverified suppliers.
Food Thermos Market Segmentation
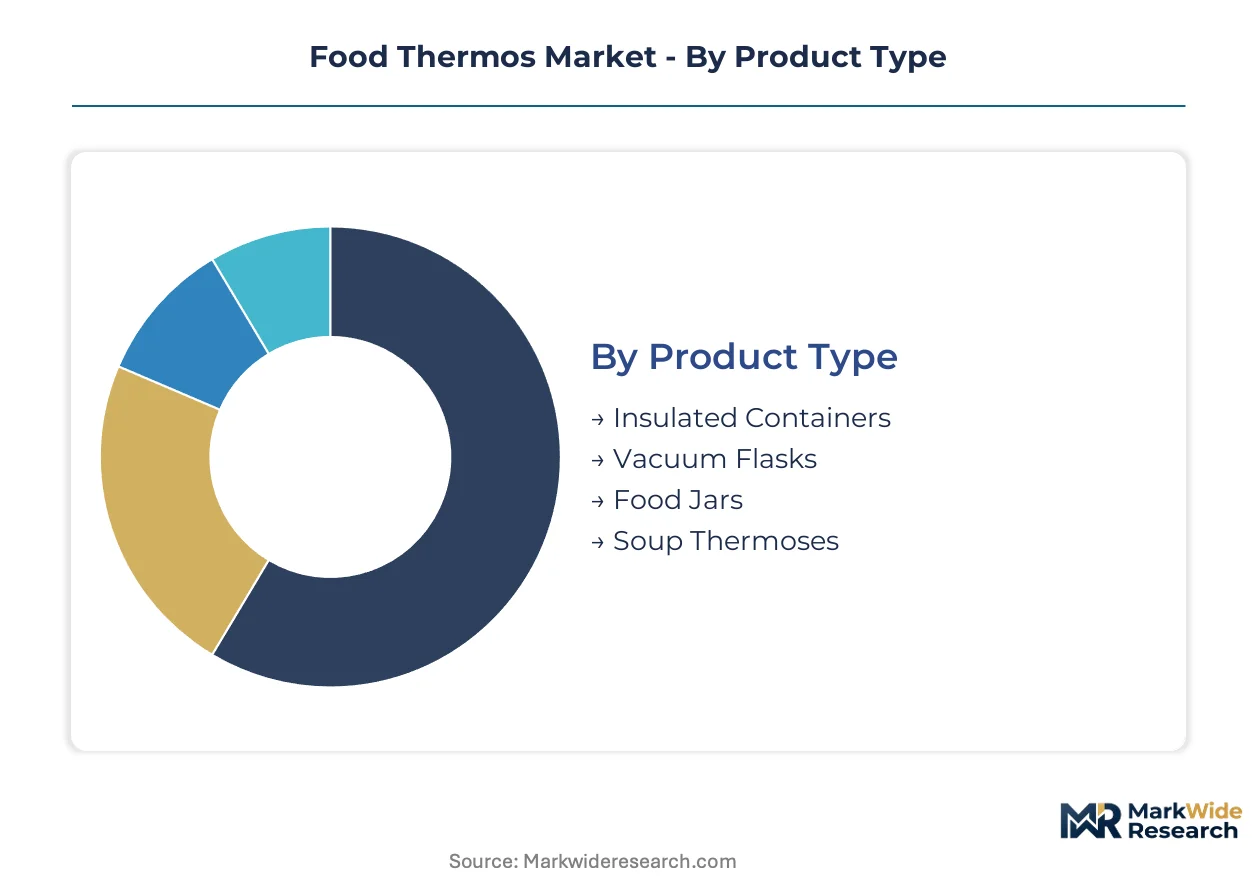
Food thermos segmentation reveals how manufacturing capabilities align with distinct performance requirements across institutional and consumer channels. Product architecture, material selection, and capacity specifications each create divergent margin structures and certification burdens.
Product Type:
Vacuum flask assembly lines cluster in China's eastern seaboard manufacturing belt, where helium leak detection infrastructure and copper plating capacity determine competitive tier.
- Vacuum Flasks:Double-walled stainless steel construction with vacuum-sealed air gaps and copper-plated inner walls minimizes radiative heat loss. Japanese commuter markets and North American outdoor recreation procurement specify this architecture, requiring third-party JIS thermal retention certification.
- Food Jars:Wide-mouth cylindrical designs optimize for solid food access and institutional meal program portion control. China's urban commuting culture sustains replacement-cycle demand for 500ml to 750ml formats, while school lunch programs in the United States specify thermal performance bonds.
- Insulated Containers:Foam-insulated plastic or composite bodies compete on entry-price positioning in mass retail channels.
- Soup Thermoses:Narrow-neck designs prioritize liquid retention and spill prevention for single-serve consumption.
Vacuum flasks absorb the bulk of installed capacity; food jars are expanding most quickly.
Material:
Raw material cost tiers stratify competitive positioning, with nickel price volatility on the London Metal Exchange compressing margin pools for mid-tier fabricators.
- Stainless Steel:18/8 grade with 18% chromium and 8% nickel content dominates premium positioning. EU REACH and RoHS compliance requirements restrict heavy-metal content in coatings and sealing gaskets, elevating documentation burdens for export-oriented manufacturers.
- Plastic:Polypropylene and Tritan copolyester variants serve school-lunch procurement at entry-price tiers, though PFAS restrictions in Europe and North America force fluoropolymer coating substitutions.
- Glass:Borosilicate inner liners with protective silicone sleeves occupy niche health-conscious segments.
- Aluminum:Lightweight anodized exteriors support outdoor recreation weight-sensitive applications.
Stainless steel commands the dominant margin pool; plastic maintains volume leadership in institutional procurement.
Capacity:
Volume specifications map directly to end-use replacement economics and logistics optimization in construction site meal delivery.
- 500ml:Single-serve formats align with Japanese commuter market norms and dense metropolitan transport networks in China. Urban rail-dependent workers normalize portable meal consumption, sustaining consistent replacement-cycle demand.
- 750ml:Mid-capacity designs balance portion flexibility with transport convenience across daily use and travel applications.
- 1000ml:Family-size and high-activity formats gain share in outdoor recreation and construction-site meal delivery, where contractors issue thermal retention performance bonds requiring documented test results.
- 1500ml:Bulk institutional formats serve midday meal schemes and catering aggregation with extended heat retention requirements.
500ml formats anchor volume shipments; 1000ml+ capacities are gaining share fastest in specification-driven procurement channels.
Application:
End-use concentration determines channel structure, with institutional bypass of retail markup creating divergent margin capture opportunities.
- School Lunches:Institutional meal programs in the United States and China specify thermal retention performance standards that favor durable 18/8 stainless steel vessels. FDA food-contact material standards and EU REACH compliance create multi-jurisdiction certification burdens for suppliers.
- Outdoor Activities:Camping, hiking, and recreation rental programs aggregate demand into 1000ml+ capacity formats with third-party certification requirements, concentrating volume with manufacturers maintaining captive testing laboratories.
- Daily Use:Commuter-driven replacement cycles in Chinese metropolitan areas sustain mid-capacity format demand.
- Travel:Airline-compatible and leak-proof specifications serve international mobility requirements with compact form factors.
School lunches absorb the bulk of institutional procurement volume; outdoor activities are climbing the fastest in specification-driven premium tiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China absorbs the dominant share of food thermos procurement volume through urban commuter replacement cycles and institutional meal aggregation. Manufacturing gravity concentrates in the Yangtze River Delta and Pearl River Delta corridors, where vacuum insulation assembly lines cluster within 300 kilometers of raw steel suppliers.
China
Metropolitan rail networks in Shanghai, Beijing, and Guangzhou normalize daily portable meal consumption across 500ml to 750ml formats. NMPA food-contact safety standards and MEE environmental compliance jointly regulate domestic production certification. Zhejiang and Guangdong provinces host over two-thirds of global vacuum flask manufacturing capacity, with Ningbo and Dongguan serving as export-oriented fabrication hubs.
United States
School lunch procurement programs specify thermal retention performance bonds that favor 18/8 stainless steel vessels over disposable alternatives. FDA food-contact material standards govern market access for imported and domestic manufacturers. Construction site meal delivery contractors in Texas and California aggregate demand into 1000ml+ capacity formats with third-party certification requirements.
Japan
Dense commuter rail corridors in Tokyo and Osaka sustain replacement-cycle demand for compact-capacity designs optimized for bento-style meal transport. METI enforces JIS thermal retention performance standards that shape product development priorities for export-oriented manufacturers. Kansai and Chubu industrial regions maintain captive testing laboratories serving both domestic and overseas certification requirements.
Germany
EU F-Gas Regulation mandates hydrofluorocarbon phase-out, accelerating vacuum-sealed double-wall construction adoption across institutional and consumer channels. ECHA REACH Annex XVII PFAS restrictions eliminate fluoropolymer interior coatings, forcing ceramic-based material substitutions. Bavaria and North Rhine-Westphalia host distribution infrastructure serving cross-border procurement into France and the Netherlands.
India
Midday meal schemes under the National Food Security Act generate bulk procurement volumes for stainless steel food jars in 500ml to 1000ml capacities. FSSAI food safety standards and BIS certification requirements create multi-layer compliance burdens for import-dependent supply chains. Maharashtra and Gujarat manufacturing clusters are developing domestic vacuum insulation assembly capacity to reduce reliance on Chinese imports.
Food Thermos Market Competitive Landscape
Chinese producers anchor the scale-driven tier; Japanese specialists hold premium positioning through proprietary vacuum insulation technology. The vendor base fragments across three competitive strata: century-old heritage brands with retail channel control, Asian fabricators with captive manufacturing assets, and institutional suppliers with specification-driven procurement relationships. Dominant competitive moves include backward integration into steel plating capacity and technology licensing agreements for helium leak detection systems.
Among heritage-positioned manufacturers, Thermos L.L.C and Zojirushi America Corporation exemplify brand-equity-driven competitive architecture. Tiger Corporation occupies a position within the compact-capacity specialization tier. These three entities represent distinct geographic anchoring—American brand management, Japanese engineering partnerships, and domestic Asian market focus—without implying specific strategic coordination or market share claims.
| Leading Market Players |
|---|
| Thermos L.L.C |
| Zojirushi America Corporation |
| Cambro Foodservice Equipment and Supplies |
| Stanley Black & Decker |
| Newell Brands |
| Carlisle FoodService Products |
| Huhtamaki |
| TokyoPlast |
| Tiger Corporation |
| Others |
Value Network & Pricing Analysis
Helium leak detection technicians in Ningbo and Dongguan command wage premiums that compress margin spreads between premium vacuum flasks and standard uncoated variants. Labor-cost differentials across China's eastern seaboard manufacturing belt translate directly into pricing-tier stratification, with copper-plated JIS-certified products absorbing skilled-worker premiums while entry-price plastic alternatives exploit lower-skill assembly economics.
Pricing Analysis
Volume concentrates in 500ml plastic food jars for school-lunch procurement, while margin pools accrue to 1000ml+ vacuum flasks with third-party thermal retention certification. Pricing stratifies across premium copper-plated stainless steel, standard uncoated 18/8 vessels, and economy polypropylene formats, with JIS certification and FDA compliance tiers driving spreads. Cost compression in mid-tier stainless steel is intensifying because nickel futures volatility on the London Metal Exchange feeds directly into input costs. Institutional buyers in construction-site meal delivery exhibit lowest price sensitivity due to thermal performance bond requirements, while mass retail channels in Southeast Asia show highest sensitivity.
Supply Chain Analysis
Direct-to-institution channels handle specification-driven demand from contractors and midday meal schemes, bypassing retail markup structures. Manufacturing concentrates in China, Japan, and emerging clusters in India, with Zhejiang and Guangdong provinces hosting over two-thirds of global vacuum flask capacity. Raw material dependencies rest on nickel for 18/8 stainless steel, copper for radiative heat-loss plating, and helium for leak detection calibration. Single-source vulnerability in Guangdong-Zhejiang corridor logistics creates exposure to regional labor competition and port congestion. Distribution runs through OEM-direct contracts for institutional buyers and layered distributor networks for retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU F-Gas Regulation and REACH Annex XVII PFAS restrictions are consolidating manufacturing footprints, forcing retooling investments that weaker fabricators cannot absorb. This regulatory compression creates a consolidation play as compliance burdens eliminate sub-scale competitors.
For Market Incumbents: Hedge nickel price exposure through long-term offtake agreements with stainless steel mills or backward integration into plating capacity. Capture channel control by deepening direct-to-institution relationships with construction-site contractors and school-lunch procurement officers, insulating against retail price erosion. Prioritize captive helium leak detection laboratories to maintain third-party certification velocity as testing timeline conflicts multiply across FDA, REACH, and JIS jurisdictions.
For New Entrants and Emerging Players: REACH Annex XVII PFAS restrictions in Europe open a window for ceramic-based and electropolished bare steel interior solutions, displacing fluoropolymer-coated incumbents with 18-24 month reformulation windows. Target India's midday meal schemes under the National Food Security Act, where bulk procurement volumes remain underserved by import-dependent supply chains. Lead with direct-to-institution go-to-market models that bypass retail slotting fees and capture full margin on specification-driven tenders.
For Investors and Strategic Acquirers: The window for entry favors manufacturers with captive testing infrastructure and copper-plating technology licenses. Long-term viability hinges on regulatory compliance velocity rather than brand equity alone. Target acquisition profiles should emphasize firms with JIS-certified production lines and established contractor relationships in construction-site meal delivery. Watch helium leak detection equipment utilization rates as an inflection indicator for quality-tier capacity constraints.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Copper Plating | Captures margin from electroplated inner wall premiums demanded by Japanese commuter markets. |
| PFAS-Free Coating Transition | Positions ceramic-based interiors ahead of ECHA enforcement timelines in European retail channels. |
| Direct-to-Institution Channel Expansion | Bypasses retail markup structures for construction-site contractors issuing thermal retention bonds. |
| Helium Leak Detection Laboratory Investment | Accelerates JIS and ISO certification velocity for specification-driven procurement tenders. |
| India Manufacturing Footprint Establishment | Reduces tariff exposure and logistics vulnerability for National Food Security Act midday meal schemes. |
Research Methodology
Independent corroboration across procurement officers at institutional meal programs, quality directors at vacuum flask fabricators, and regulatory compliance leads at export-oriented manufacturers underwrites the qualitative findings. Primary interviews with school-lunch program administrators, construction-site catering contractors, and retail category buyers combined with secondary validation from FDA food-contact material filings, EU ECHA REACH registration databases, and METI JIS standard documentation. Bottom-up shipment data from Chinese customs records and top-down demand modeling across commuter replacement cycles triangulate volume estimates.
Rate-of-change decomposition separates volume growth from mix-shift effects across the projection horizon. Segmentation dimensions modeled include product architecture, material grade tier, capacity specification, and end-use application with regulatory compliance cluster overlays. CAGRs derive from regression against commuter rail ridership trends, nickel futures correlation analysis, and institutional procurement tender aggregation. Industry-specific forecast inputs incorporate helium leak detection equipment depreciation schedules and copper plating capacity utilization rates.
The model assumes a particular technology adoption path; alternative pathways for vacuum insulation versus foam-insulated construction would alter the outlook. Forecasts reflect documented assumptions regarding EU F-Gas Regulation phase-out timing and PFAS restriction enforcement calendars, with nickel price volatility and logistics corridor concentration representing material revision risks. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service Equipment
Culinary Torch Market
Food Service Equipment
Multi Cooker Market
Food Service Equipment
Commercial Refrigerated Display Cabinet Market
Food Service Equipment
Commercial Stainless Steel Cooking Equipment Market
Food Service Equipment
900 Series Cooking Equipment Market
Food Service Equipment
North America Countertop Ice Makers Market
Food Service Equipment
Sheet Pan Racks Market
Food Service Equipment
Draught Beer Chiller Market
Food Service Equipment
Gas Smoker Market
Food Service Equipment
Global QSR Food Service Equipment Market
Food Service Equipment
US and Canada Hot Food Vending Machine Market
Food Service Equipment
Restaurant Fryers Market
Food Service Equipment
Food Holding Equipment Market
Food Service Equipment
Commercial Convection Ovens Market
Food Service Equipment
North America Fountain Dispenser Equipment Market
Food Service Equipment
North America and Europe Vending Machine Market