
 Popcorn Market | 2026-2036
Popcorn Market Size, Share, and Industry Trends Forecast 2026-2036
Popcorn Market Intelligence
The rise of asset-light contract manufacturing for private label brands is reconfiguring competitive entry barriers. Large incumbents like ConAgra Brands leverage extensive distribution networks to maintain shelf space dominance. PepsiCo (Frito-Lay) competes through its massive brand equity and marketing scale in the broader snack category. Meanwhile, specialists such as Weaver Popcorn Company focus on bulk kernel supply and co-packing services for other brands.
Popcorn is a snack food produced from a specific strain of corn, Zea mays everta. The kernel's hard, moisture-sealed hull allows internal steam pressure to build upon heating, causing it to rupture and expand into an edible puff. Within product types, classic Butter and Cheese flavors command the largest share, while Kettle Corn and other sweet-savory combinations show high growth potential. Supermarkets constitute the core distribution channel, though online retail is gaining traction rapidly through direct-to-consumer models.
Market access and product formulation are governed by food safety regulations. In the United States, the FDA mandates strict nutritional labeling and allergen declarations. Similarly, the European Food Safety Authority (EFSA) sets limits on flavorings and additives used in ready-to-eat products. Navigating shifting consumer demands for clean-label ingredients and sustainable packaging will be critical for future brand differentiation.
Market Dynamics
The core dynamic shaping the popcorn market is the conflict between health-driven clean-label demands and the expansion of indulgence-focused snacking occasions. This tension directly influences product formulation, from kernel sourcing to the additives used in ready-to-eat varieties.
Growth Catalysts
- Modern Retail Expansion:The proliferation of supermarkets and hypermarkets in developing economies, particularly in India, is increasing the availability and visibility of packaged popcorn products, capturing new consumer segments.
- Health and Wellness Positioning:Popcorn's inherent qualities as a whole-grain, high-fiber, and naturally low-calorie snack are being leveraged by brands to appeal to health-conscious consumers seeking permissible indulgences.
- Cinema and Entertainment Growth:The expansion and premiumization of cinemas globally, especially within the Asia-Pacific region, directly stimulates high-margin, on-premise sales of freshly prepared popcorn, a cornerstone of the movie-going experience.
Market Restraints
- Input Price Volatility:The market is sensitive to price fluctuations of key raw materials, especially the specialized Zea mays everta corn variety, which is subject to agricultural yields, climate conditions, and competing crop economics.
- Intense Snack Category Competition:Popcorn faces significant substitution threats from a vast array of alternative snack products, including potato chips, pretzels, nuts, and extruded snacks, which compete for the same shelf space and consumer spending.
- Regulatory Scrutiny on Additives:Food safety authorities like the European Food Safety Authority (EFSA) impose strict regulations on flavorings, colorings, and preservatives, which can complicate formulation and limit the use of certain cost-effective ingredients.
Strategic Opportunities
- Functional Ingredient Infusion:There is a clear opportunity to develop popcorn products fortified with functional ingredients such as protein, probiotics, or vitamins, catering to consumer demand for snacks that offer specific health benefits.
- Gourmet and Ethnic Flavor Profiles:Introducing novel, region-specific flavor combinations beyond traditional butter and cheese, such as spicy, umami, or ethnic-inspired seasonings, can attract new demographics and create premium product tiers.
- Sustainable Packaging Solutions:Investing in compostable, biodegradable, or recycled packaging materials offers a powerful point of differentiation, appealing to environmentally conscious consumers and aligning with corporate sustainability goals.
Industry Challenges
- Supply Chain Consistency:Maintaining a consistent supply of high-quality popping corn with optimal moisture content and expansion ratios across different geographic regions and harvest seasons presents a significant logistical challenge.
- Navigating Divergent Labeling Laws:Brands operating globally must contend with a complex web of nutritional labeling mandates, such as the FDA's requirements in the United States and the FSSAI's rules in India, increasing compliance costs.
- Shelf-Life Management:Ensuring the freshness and crispness of ready-to-eat popcorn, particularly for "clean label" products with minimal preservatives, requires sophisticated packaging technology and careful inventory management to prevent spoilage.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Popcorn Market |
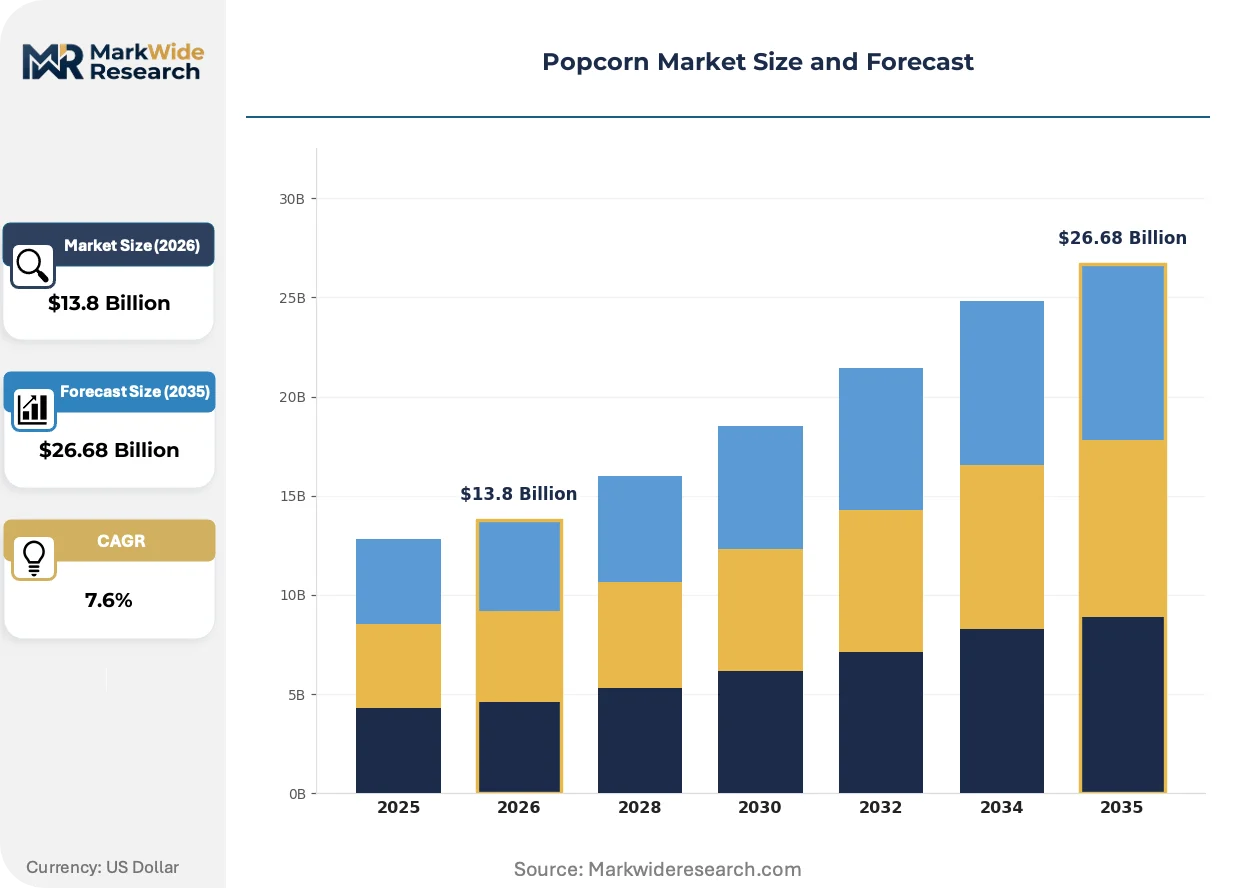
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $26.68 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Butter, Cheese, Caramel, Kettle Corn Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Specialty Shops Packaging Type: Bags, Boxes, Tubs, Bulk End User: Households, Cinemas, Cafes, Events |
| Companies Covered | Campbell Soup Company, Amplify Snack Brands, ConAgra Brands, Quinn Foods, Snyder's-Lance, PepsiCo (Frito-Lay), Weaver Popcorn Company, Garrett Popcorn Shops, The Hershey Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Popcorn Market Strategic Shifts & Innovations
Product innovation in the popcorn market is being defined by the intersection of flavor science and health-conscious reformulation. Manufacturers are using new technologies to create novel taste experiences while simultaneously adhering to stricter nutritional guidelines and consumer demands for simpler ingredients.
Flavor Development Technology
Advanced computational tools and AI-driven platforms are being used to map flavor compounds and predict successful new taste combinations. Artisanal and large-scale producers alike adopt these systems to accelerate research and development for complex profiles like sweet-umami or savory-floral. This technology is virtualizing the traditionally slow and trial-and-error-based process of flavor creation, significantly shortening the time to market for novel products.
Front-of-Pack Labeling
Mandatory front-of-pack nutrition labeling (FOPL) systems, such as the Nutri-Score in several European countries, are becoming more prevalent. These policies compel manufacturers to reformulate products by reducing sodium, sugar, and saturated fats to avoid negative ratings. The ready-to-eat popcorn segment is most impacted, pushing brands to innovate healthier versions of classic indulgent flavors like caramel and extra butter.
Shifting Consumption Formats
Consumer purchasing behavior is moving away from large, family-sized bags toward single-serving packages and multi-flavor variety packs. This trend disrupts the economics of traditional supermarket channels while boosting sales in convenience stores and through direct-to-consumer online models. The shift is most pronounced in North American markets, driven by consumer interest in portion control and the desire to sample multiple gourmet flavors.
Popcorn Market Segmentation
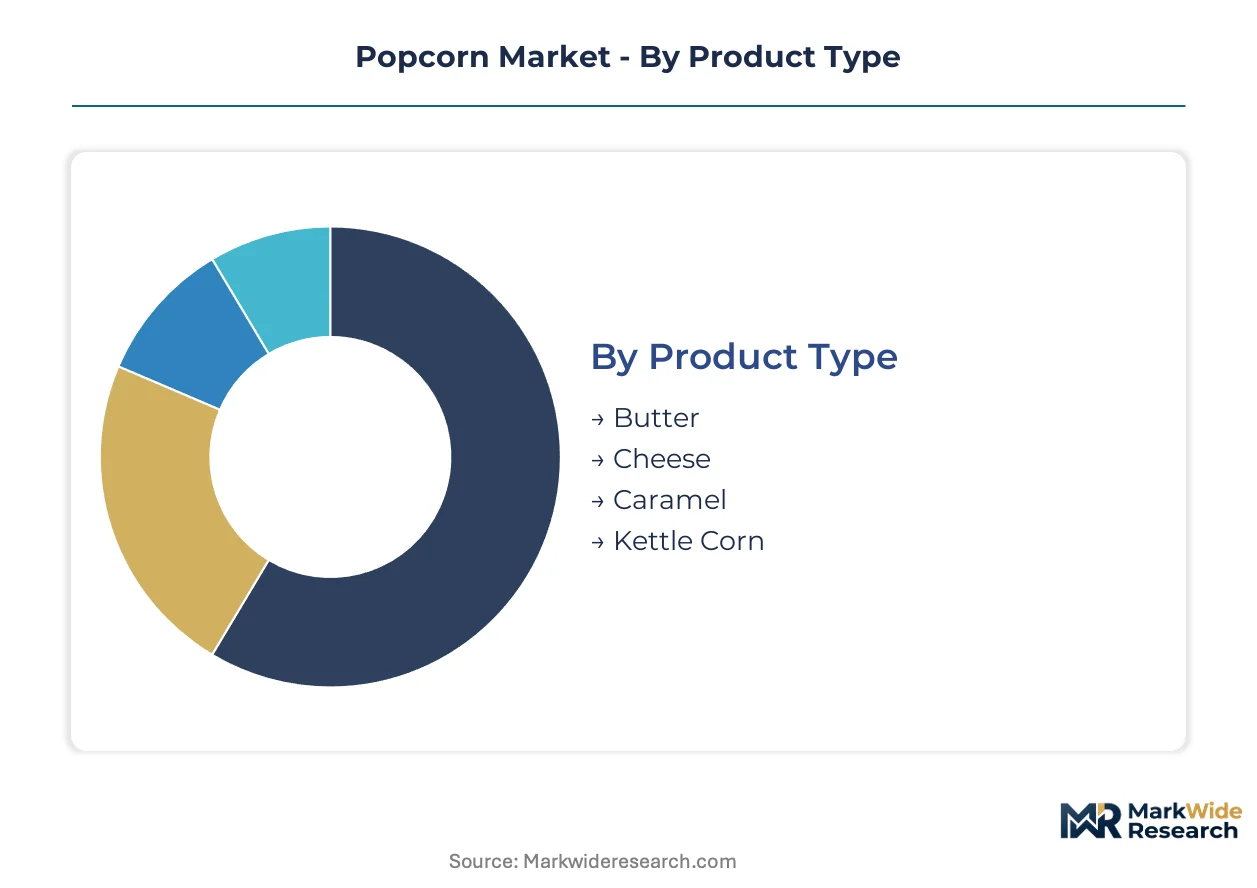
Understanding the varied segments within the popcorn market allows stakeholders to pinpoint specific consumer preferences and operational efficiencies. This granular view reveals where consumption patterns are most concentrated and where innovation can yield the highest returns.
Product Type:
The product type segment illustrates the varying stages of maturity within flavor preferences, from established classics to rapidly expanding novel combinations.
- Butter:This traditional flavor consists of popcorn kernels seasoned with butter or butter-flavored oil, providing a rich, savory profile. Demand for butter popcorn remains consistently high across households and cinemas, particularly in North American markets, driven by its enduring appeal as a classic snack.
- Kettle Corn:Characterized by its unique sweet and savory balance, kettle corn is typically prepared with sugar, salt, and oil. This segment shows high growth potential, attracting consumers seeking more complex flavor experiences, especially through online retail channels and gourmet snack offerings.
- Cheese:This savory category includes popcorn coated or seasoned with various cheese powders, offering a distinct umami taste. Cheese popcorn maintains strong popularity in supermarkets for at-home consumption.
- Caramel:Caramel popcorn features a sweet, crunchy coating, often made from melted sugar and butter. This indulgent variety is popular in specialty shops and as a treat for specific occasions.
Butter handles the majority of throughput; Kettle Corn is the fastest mover on share.
Distribution Channel:
Distribution channels dictate market reach and consumer accessibility, with traditional retail still dominant but digital platforms gaining significant ground.
- Supermarkets:These large retail outlets serve as the primary distribution channel for packaged popcorn products, offering extensive shelf space and variety. Supermarkets cater to bulk household purchases, driven by convenient access and competitive pricing.
- Online Retail:This channel encompasses e-commerce platforms and direct-to-consumer websites, providing convenience and access to niche or gourmet popcorn brands. Online retail is gaining traction rapidly, particularly in North American markets, for its ability to offer diverse flavor profiles and subscription models.
- Convenience Stores:Smaller retail formats focus on immediate consumption and impulse purchases, stocking single-serving popcorn bags. Convenience stores capture on-the-go snackers.
- Specialty Shops:These outlets often feature artisanal, gourmet, or unique popcorn flavors, catering to consumers seeking premium or differentiated products. Specialty shops emphasize product quality and unique branding.
Supermarkets continue to drive the largest volume; Online Retail is expanding most quickly.
Packaging Type:
Packaging type reflects consumer usage patterns and logistical considerations, from individual servings to bulk purchases.
- Bags:Flexible pouches and bags are the most common packaging format for ready-to-eat popcorn, available in various sizes from single-serve to family packs. This type supports portion control and multi-flavor variety packs, particularly in North American markets.
- Bulk:Large containers or sacks of unpopped kernels or pre-popped popcorn cater to industrial users, co-packing services, and commercial establishments like cinemas. Bulk packaging is crucial for maintaining supply chain consistency for large-scale operations.
- Boxes:Typically used for microwave popcorn, boxes offer convenience for at-home preparation. This format emphasizes ease of use.
- Tubs:Larger, rigid containers are frequently utilized in cinema settings or for larger family-sized portions of ready-to-eat popcorn. Tubs facilitate sharing among consumers.
Bags dominate consumer-facing sales; Bulk sales are climbing the fastest for B2B applications.
End User:
End-user segments highlight the diverse consumption occasions, from daily snacking at home to event-driven indulgence.
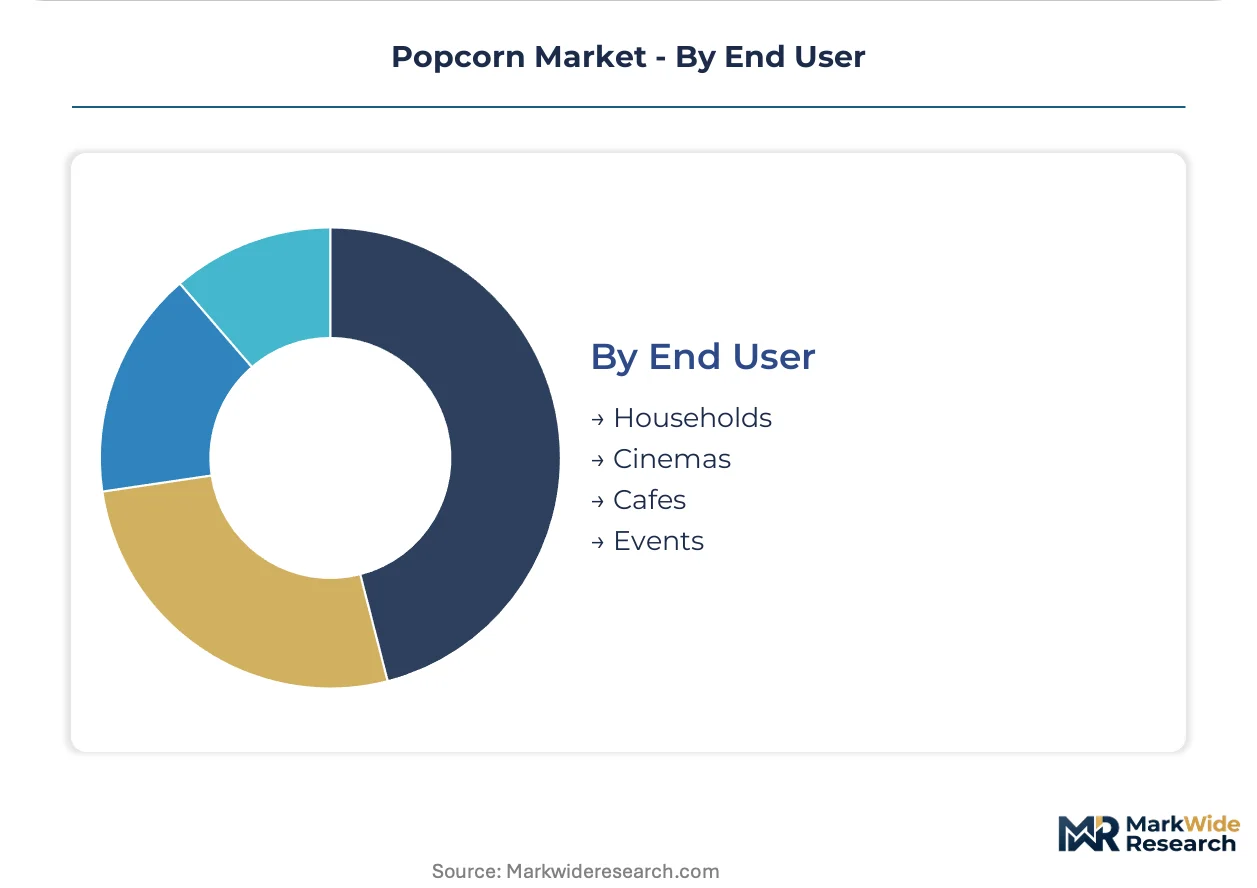
- Households:This segment includes consumers purchasing popcorn for at-home consumption, either as a snack or for movie nights. Households drive demand for both microwave and ready-to-eat varieties, often influenced by clean-label ingredient trends.
- Cinemas:Movie theaters represent a significant high-margin end-user segment, with freshly popped popcorn being an integral part of the entertainment experience. The expansion and premiumization of cinemas, especially within the Asia-Pacific region, directly stimulate these sales.
- Cafes:Coffee shops and cafes offer popcorn as a complementary snack alongside beverages, often featuring gourmet or artisanal flavors. Cafes cater to casual snacking occasions.
- Events:This category encompasses sports arenas, concerts, fairs, and other large gatherings where popcorn is sold as a popular concession item. Events contribute to seasonal demand.
Households represent the largest consumption base; Cinemas are gaining share fastest due to premiumization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory frameworks, such as the FDA's nutritional labeling requirements in the United States and EFSA's guidance on additives in Europe, significantly influence product formulation across global popcorn markets. These policies drive innovation in healthier snack options and clean-label ingredients. Diverse consumer preferences and retail expansion further shape regional demand dynamics.
United States
Consumer demand in the United States increasingly favors convenience and diverse, gourmet flavor profiles, driving innovation in ready-to-eat popcorn. The FDA mandates strict nutritional labeling and allergen declarations. Major urban centers like Los Angeles and New York City exhibit high consumption of premium and artisanal popcorn varieties.
India
India's popcorn market expands rapidly due to modern retail proliferation and a burgeoning snacking culture among its growing middle class. The FSSAI imposes food safety and labeling regulations, ensuring product quality. Tier-1 and Tier-2 cities such as Mumbai and Delhi are experiencing significant growth in packaged popcorn sales.
Germany
Health and wellness positioning drives demand in Germany, with consumers seeking whole-grain, low-calorie popcorn options as permissible indulgences. The European Food Safety Authority (EFSA) sets stringent limits on flavorings and additives. Cities like Berlin and Munich show strong interest in organic and sustainably packaged popcorn products.
China
China's market benefits from cinema expansion and rising disposable incomes, boosting both on-premise and at-home popcorn consumption. Regulations from the State Administration for Market Regulation (SAMR) govern food safety and ingredient transparency. Major metropolitan areas like Shanghai and Beijing lead in cinema attendance and packaged snack consumption.
Brazil
Brazilian consumers are increasingly adopting packaged snack foods, with popcorn gaining traction as a convenient and versatile option in urban areas. ANVISA, the national health surveillance agency, regulates food additives and labeling. São Paulo and Rio de Janeiro are key hubs for modern retail expansion and increased popcorn availability.
Popcorn Market Key Industry Players
On the supply side, the industry is characterized by a tiered structure, encompassing large food conglomerates, specialized popcorn manufacturers, and smaller artisanal producers. This market configuration includes incumbents leveraging extensive distribution networks and specialists focusing on bulk ingredient supply. Dominant competitive moves involve portfolio diversification into adjacent snack categories and strategic partnerships for market access.
At the scale-driven end, major food companies like ConAgra Brands and PepsiCo (Frito-Lay) exemplify broad market penetration through their established brand equity and expansive retail presence. These incumbents leverage their vast marketing resources and distribution networks to maintain shelf space dominance across global markets. Meanwhile, specialists such as Weaver Popcorn Company represent the core bulk kernel supply and co-packing service providers for numerous other brands. These entities collectively shape the competitive dynamics across various product types and distribution channels, influencing both raw material sourcing and finished product availability.
| Leading Market Players |
|---|
| Campbell Soup Company |
| Amplify Snack Brands |
| ConAgra Brands |
| Quinn Foods |
| Snyder's-Lance |
| PepsiCo (Frito-Lay) |
| Weaver Popcorn Company |
| Garrett Popcorn Shops |
| The Hershey Company |
| Others |
Cost & Logistics Intelligence
The corn belt region of the United States, a primary source for Zea mays everta, directly influences global popcorn kernel pricing due to its production capacity and export volumes. This concentration of specialized agricultural output significantly impacts raw material costs for manufacturers worldwide.
Pricing Analysis
Quality grade (expansion ratio) creates the primary spread in popcorn pricing. The market operates on a hybrid model, combining commodity spot pricing for bulk kernels with value-based pricing for branded, ready-to-eat products. Price differentiation stems from brand premium, unique flavor profiles, and packaging innovation. Pricing softness reflects intense competition from alternative snack categories. Households procuring basic kernels or ready-to-eat bags are most price-sensitive, while cinemas and specialty shops purchasing premium varieties show lower sensitivity.
Supply Chain Analysis
Commodity price volatility for Zea mays everta corn dominates the popcorn supply chain. Supply concentration for specialized popping corn primarily rests in the United States, with significant contributions from Brazil and Argentina. Raw material dependencies include specialized corn kernels, various flavorings, and sustainable packaging solutions. Regulatory restrictions on additives by bodies like the European Food Safety Authority (EFSA) represent a structural risk. Distribution runs through a diverse model encompassing supermarkets for packaged goods, online retail for niche products, and direct bulk supply to cinemas.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The popcorn market is experiencing a platform-economics inflection, driven by the expanding digital retail ecosystem and direct-to-consumer models.
For Market Incumbents: Entrench existing distribution channels by optimizing shelf space and leveraging brand equity in supermarkets. Diversify product portfolios into adjacent snack categories to mitigate substitution threats from competing products. Invest in advanced flavor development technologies to create novel taste experiences, counteracting clean-label demands with innovative formulations. Focus R&D on sustainable packaging solutions to meet evolving consumer preferences and regulatory pressures.
For New Entrants and Emerging Players: India's rapidly expanding modern retail landscape offers significant geographic underpenetration for packaged popcorn products. Target the growing demand for functional ingredients, such as protein-fortified popcorn, appealing to health-conscious consumers. A direct-to-consumer online model provides a penetrable go-to-market angle for unique gourmet or ethnic-inspired flavor profiles. Focus on niche segments seeking clean-label ingredients and transparent sourcing.
For Investors and Strategic Acquirers: Long-term, this sits as a resilient consumer staple play because of popcorn's enduring appeal as an affordable indulgence and its whole-grain health halo. Target acquisition candidates include specialized co-packing service providers with robust supply chain consistency. Strategic interest also extends to innovative flavor houses developing proprietary taste technologies. The signal to watch is the increasing market share of online retail, indicating a shift in consumer purchasing habits.
| Strategic Initiative | Industry Significance |
|---|---|
| Flavor Portfolio Diversification | Expands consumer appeal beyond traditional tastes and captures new demographics. |
| Sustainable Packaging Adoption | Aligns with environmental consumer values and enhances brand differentiation. |
| Direct-to-Consumer Channel Expansion | Increases market reach for niche products and offers higher margin opportunities. |
| Functional Ingredient Fortification | Addresses health and wellness trends by adding specific nutritional benefits. |
| Regional Market Entry (e.g., India) | Taps into high-growth developing economies with expanding snacking cultures. |
Research Approach
Initial hypotheses were tested against primary input from brand managers, cinema operators, retail category buyers, and food scientists and refined through iterative feedback. This involved combining insights from in-depth interviews with industry stakeholders with extensive secondary validation. Secondary data sources included regulatory filings from the FDA and EFSA, retail sales data, and agricultural commodity reports. Bottom-up and top-down triangulation ensured data consistency and accuracy.
The analytical framework focused on the demand-supply balance across the analysis window, modeling market dynamics. Segmentation dimensions included product type, distribution channel, packaging type, end user, and regional consumption patterns. Compound annual growth rates were derived through regression analysis of historical trends and projected market drivers. Key forecast inputs included raw material price forecasts for Zea mays everta and consumer spending patterns across various income brackets.
Practitioners should monitor geopolitical events impacting commodity prices, rapid shifts in dietary trends, and unforeseen regulatory changes for early signals of market inflection. Forecasts reflect assumptions documented throughout the study. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Protein Bars Market
Snacks
North America Snack Pellets Market
Snacks
Europe Frozen Snacks Market
Snacks
Middle East and North Africa Extruded Snack Food Market
Snacks
United Kingdom Energy Bar Market
Snacks
Low Sugar Fruit Snacks Market
Snacks
Fat Free Meals and Snacks Market
Snacks
Southeast Asia Savory Snacks Market
Snacks
Cheese Snacks Market
Snacks
Low-Calorie Savoury Snacks Market
Snacks
Energy Balls Market
Snacks
Spicy Sticks (Chinese Snack) Market
Snacks
Italy Snack Bar Market
Snacks
Europe Snack Bar Market
Snacks
China Snack Bar Market
Snacks
South Africa Snack Bar Market