
 Autonomous One-Pot Cooking System Market | 2026-2036
Autonomous One-Pot Cooking System Market Size, Share, and Industry Trends Forecast 2026-2036
Autonomous One-Pot Cooking System Market Analysis
Premium connectivity specifications with integrated recipe libraries and remote monitoring capabilities is bifurcating the competitive landscape into appliance-grade and robotics-grade tiers. Samsung Electronics Co Ltd leverages its SmartThings ecosystem to anchor kitchen automation within broader home IoT architectures. Thermomix (Vorwerk) sustains exceptionally high replacement-cycle loyalty through proprietary recipe content and guided cooking workflows. Moley Robotics differentiates on full robotic arm manipulation, occupying a narrow but defensible position in fully hands-free meal preparation.
An autonomous one-pot cooking system integrates thermal management, precision dispensing, and programmable motion control within a single vessel to execute complete recipes without human intervention during the cooking phase. These systems typically operate between 40°C and 250°C with ±1°C temperature stability, employing load cells and optical sensors to monitor ingredient state transitions in real time. Multi-cookers with automated stirring and ingredient-adding sequences currently lead volume shipments, while integrated solutions with built-in refrigeration modules capture the highest margin pools. Smart sensors and IoT connectivity represent the fastest-expanding technology layer, though voice control adoption remains concentrated in North American and Western European households where digital assistant penetration is deepest.
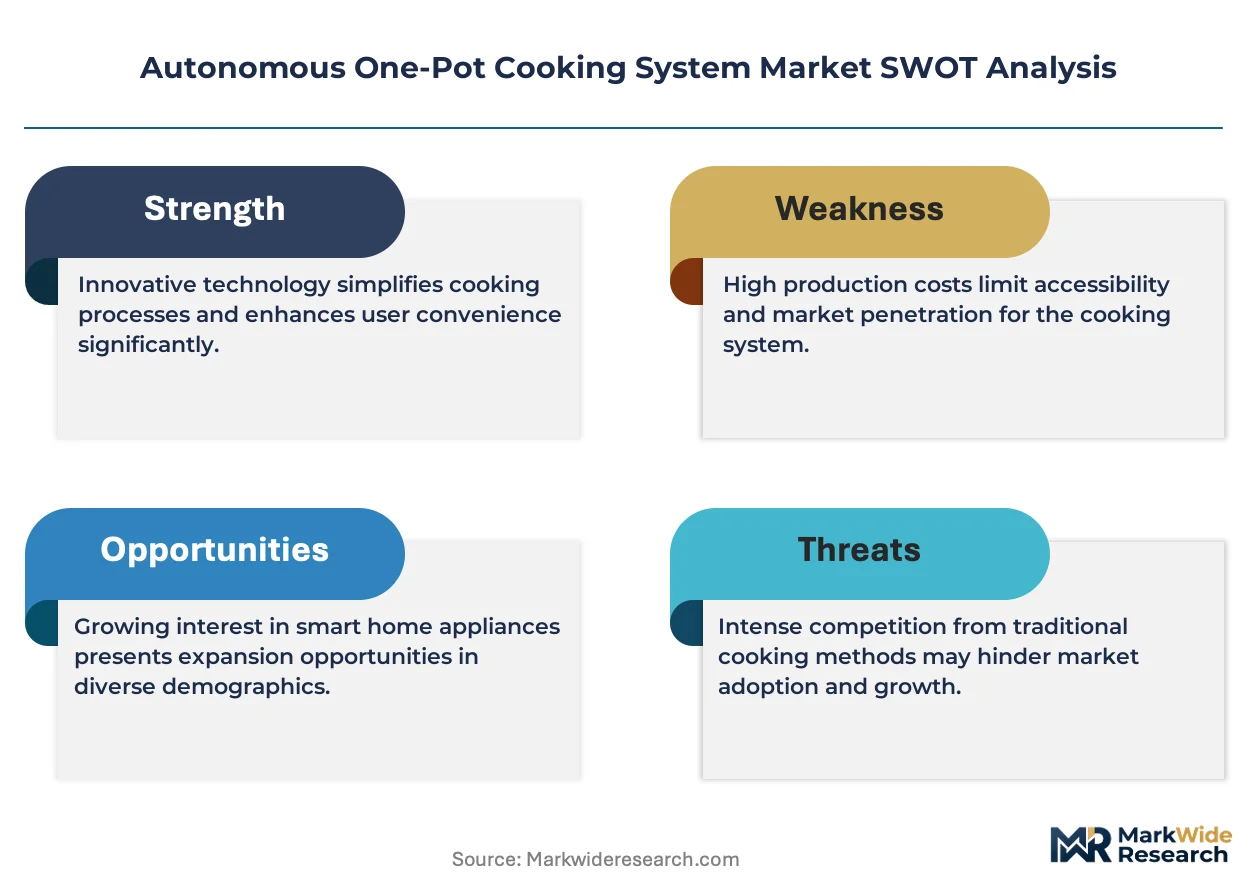
FDA food-contact material regulations and FCC wireless equipment certifications constrain hardware design choices for systems sold in the United States, while the EU's Ecodesign Directive and CE marking requirements enforce energy consumption labeling and electromagnetic compatibility standards across member states. Japan's METI has initiated consultations on robotics safety standards for domestic kitchen environments, signaling forthcoming compliance obligations for vendors targeting that market. Stakeholders must weigh the capital intensity of robotics-grade engineering against the faster payback cycles of sensor-augmented conventional appliances as they allocate development resources across product architectures.
Market Dynamics
Labor scarcity across North American restaurant chains is accelerating deployment of robotic kitchen stations, while the EU's Ecodesign Directive tightens energy thresholds for connected appliances, compressing margins for conventional multi-cooker manufacturers.
Growth Catalysts
- Energy efficiency mandates:The EU's Ecodesign Directive forces appliance-grade manufacturers toward sensor-augmented thermal management systems that reduce power consumption during idle cycles.
- Commercial kitchen automation:Quick-service restaurants facing persistent staffing gaps are expanding pilot programs with integrated refrigeration modules that extend unmanned operational windows.
- IoT sensor proliferation:Optical state-detection and load-cell arrays enable real-time ingredient monitoring, unlocking subscription revenue from guided cooking content libraries.
Market Restraints
- Robotics-grade capex intensity:Precision dispensing and programmable motion control systems require specialized servo motor suppliers concentrated in Germany and Japan, inflating bill-of-materials costs.
- Wireless certification friction:FCC equipment authorization timelines for Wi-Fi-enabled cooking systems extend hardware release cycles by 8-14 months versus non-connected alternatives.
- Conventional appliance substitution:Premium multi-cookers with automated stirring sequences satisfy price-sensitive households, capping robotics-grade penetration in the residential segment.
Strategic Opportunities
- Institutional kitchen penetration:German hospital and university foodservice operators are piloting commercial Thermomix variants to standardize meal preparation across distributed sites.
- Voice control convergence:Integration with Alexa and Google Assistant ecosystems creates channel partnerships with smart home installers in North American metropolitan markets.
- Robotics safety standardization:Japan's METI consultation process signals forthcoming domestic kitchen automation guidelines, opening compliance-first market entry for arm-manipulation systems.
Industry Challenges
- Cross-functional talent scarcity:Mechatronics engineers with simultaneous thermal management and food-safety expertise command premium compensation, constraining R&D velocity for mid-tier vendors.
- FDA material compliance timelines:Food-contact substance notifications for novel polymer coatings add 12-18 months to product development schedules for US-bound systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Autonomous One-Pot Cooking System Market |
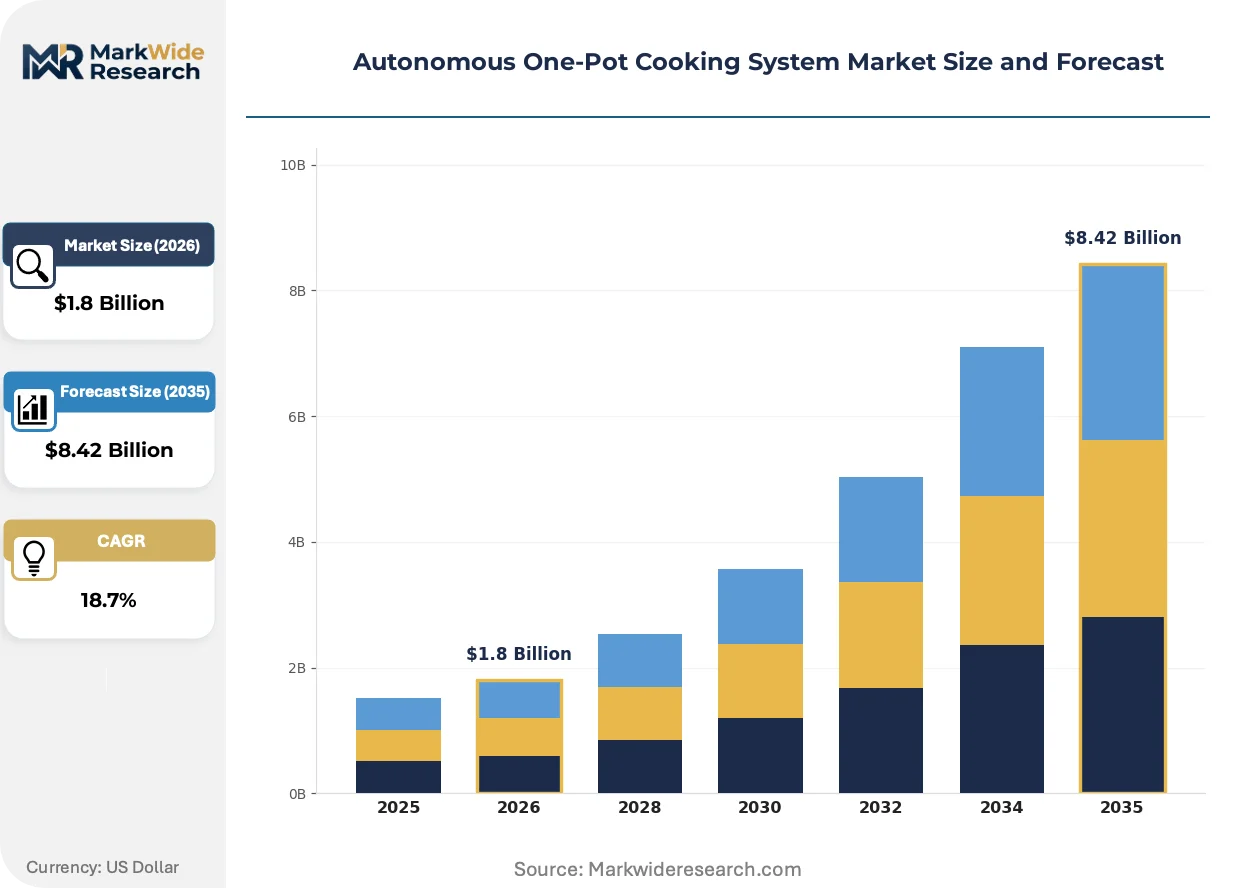
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.42 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Cookers, Multi-Cookers, Slow Cookers, Pressure Cookers Technology: Smart Sensors, IoT Connectivity, Voice Control, Automated Cooking Programs End User: Households, Restaurants, Catering Services, Institutional Kitchens Installation: Built-in Appliances, Countertop Models, Portable Units, Integrated Solutions |
| Companies Covered | Samsung Electronics Co Ltd, Electrolux AB, Haier Group, Panasonic Corporation, Philips Domestic Appliances, Instant Brands, Thermomix (Vorwerk), Moley Robotics, Nala Robotics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Autonomous One-Pot Cooking System Market Emerging Trajectories
Connectivity specifications are bifurcating hardware architectures, with premium tiers integrating cloud recipe ecosystems while value tiers strip remote monitoring to hit price points. This divergence is reshaping vendor R&D allocation and partnership strategies.
Precision dispensing mechanisms with gravimetric feedback loops are fragmenting the competitive landscape between appliance-grade and robotics-grade tiers. Quick-service restaurant chains are adopting these systems fastest, compressing the performance gap between mid-tier multi-cookers and fully automated stations. The technology is fragmenting procurement committees into separate capital committees for conventional equipment versus robotics infrastructure.
The EU's Ecodesign Directive is tightening energy efficiency thresholds for connected cooking appliances sold across member states. Manufacturers must redesign thermal management subsystems to meet standby power limits, redirecting engineering resources from feature development to compliance. Commercial variants with integrated refrigeration modules face the steepest redesign costs due to dual-circuit energy accounting requirements.
Subscription revenue from proprietary recipe content is displacing hardware margin as the primary profit pool for residential-focused vendors. Smart home installers in Germany and the United States are bundling guided cooking workflows with ecosystem configuration services, capturing recurring commissions. This shift concentrates customer lifetime value in content libraries rather than replacement cycles, favoring incumbents with established culinary databases.
Autonomous One-Pot Cooking System Market Segmentation
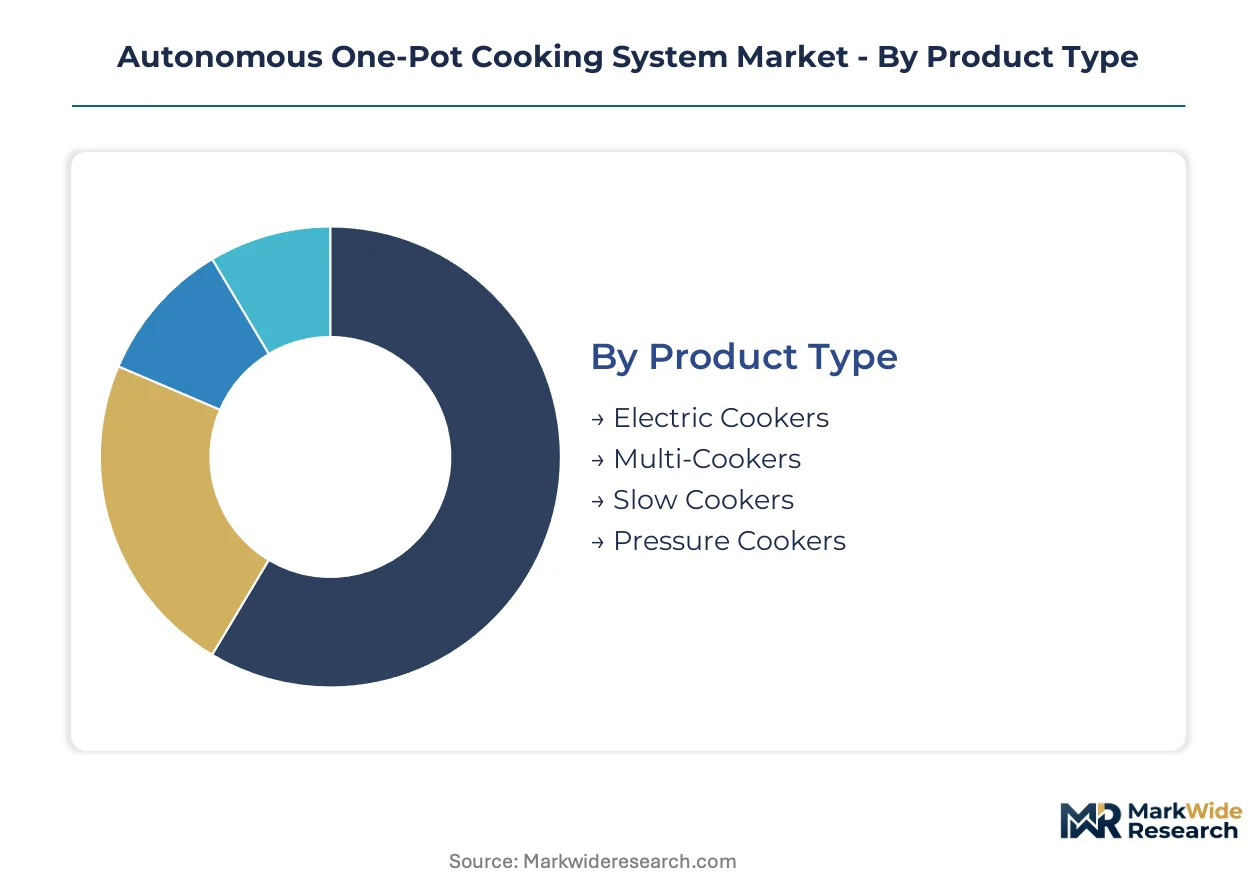
Segmentation in autonomous one-pot cooking systems reveals how thermal management sophistication and connectivity architecture map to distinct compliance obligations and margin structures across residential and commercial deployments.
Product Type:
FDA food-contact material regulations and EU Ecodesign Directive thresholds apply differentially across thermal vessel designs, with sealed pressure systems facing stricter safety certifications than open-vessel alternatives.
- Electric Cookers:Base heating elements with single-point temperature control dominate entry-level residential penetration. German households favor these for energy-label compliance under Ecodesign standby power limits.
- Multi-Cookers:Modular thermal platforms combine pressure, slow-cook, and sauté functions with programmable sequencing. Quick-service restaurants in the United States deploy these for cross-menu flexibility during labor shortages.
- Slow Cookers:Low-wattage thermal maintenance systems with minimal sensor integration.
- Pressure Cookers:Sealed-vessel designs requiring pressure relief certification and enhanced liability coverage.
Multi-cookers handle the majority of throughput; electric cookers are gaining share fastest among price-sensitive European households.
Technology:
Cost tier stratification separates sensor-augmented appliance-grade systems from robotics-grade platforms with precision dispensing and motion control, with FCC certification timelines adding 8-14 months for Wi-Fi-enabled variants.
- Smart Sensors:Optical state-detection and load-cell arrays monitor ingredient transitions in real time. Commercial kitchens in Japan are piloting these for METI robotics safety pre-compliance.
- IoT Connectivity:Cloud-integrated platforms enable remote monitoring and subscription recipe access. North American metropolitan markets show deepest penetration where digital assistant ecosystems anchor smart home bundles.
- Voice Control:Alexa and Google Assistant integration concentrated in US and Western European households.
- Automated Cooking Programs:Preloaded thermal sequences with minimal user intervention during execution.
Smart sensors anchor the largest installed base; IoT connectivity is climbing the fastest on recurring revenue potential from content libraries.
End User:
Application-specific thermal demands and operational duty cycles create divergent procurement patterns, with institutional buyers prioritizing standardization across distributed sites.
- Households:Residential users prioritize countertop footprint and guided cooking workflows. German household penetration of premium guided systems remains the deepest globally, sustaining replacement-cycle loyalty.
- Restaurants:Quick-service chains face persistent staffing gaps. These operators are expanding robotic kitchen station pilots with integrated refrigeration modules to extend unmanned operational windows.
- Catering Services:Mobile foodservice operators requiring portable thermal platforms with rapid cycle times.
- Institutional Kitchens:Hospital and university foodservice operators in Germany are piloting commercial variants to standardize meal preparation across distributed sites.
Households represent the broadest addressable base; institutional kitchens are expanding most quickly on procurement consolidation.
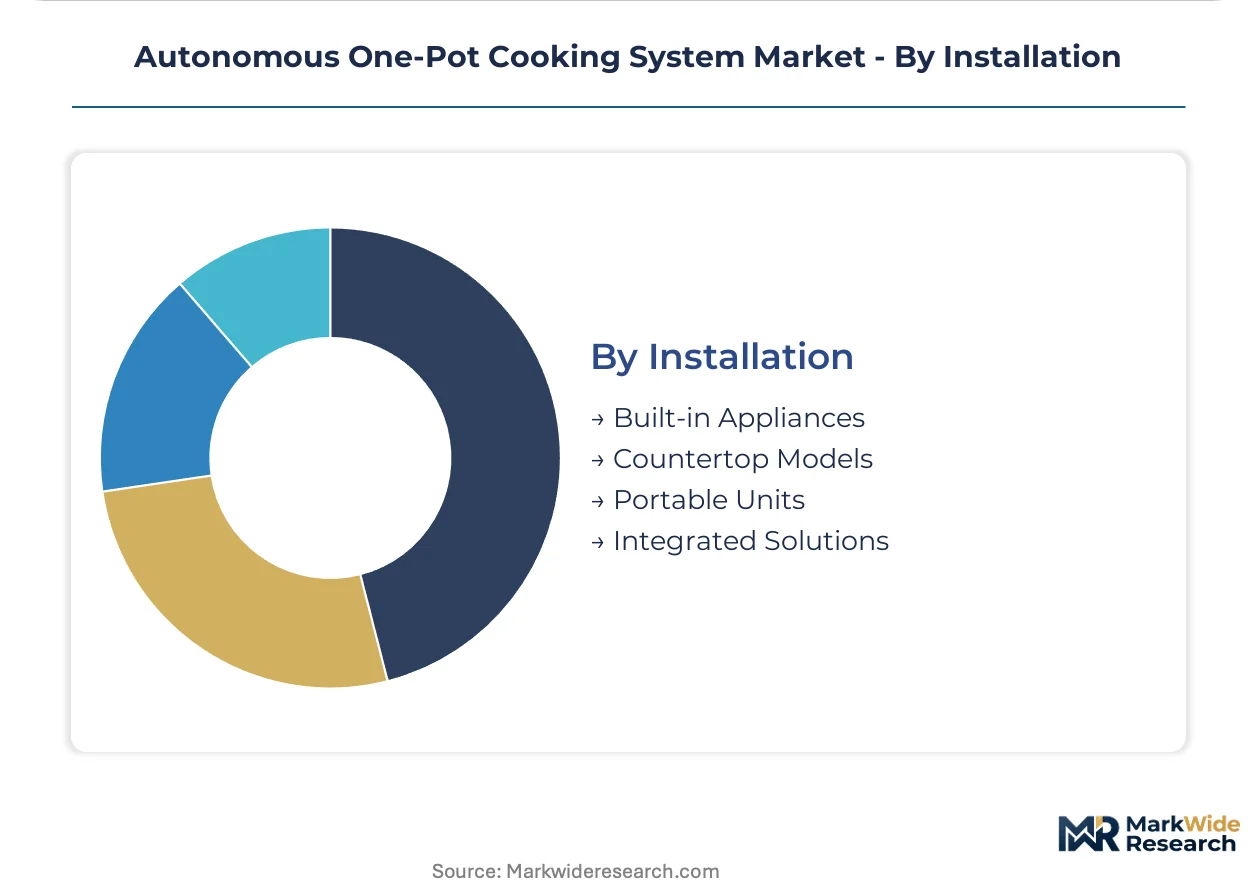
Installation:
Physical integration depth determines capital intensity and regulatory exposure, with built-in and integrated solutions facing dual-circuit energy accounting under EU Ecodesign.
- Built-in Appliances:Cabinet-integrated thermal systems with fixed electrical connections. These face the steepest redesign costs from Ecodesign standby power limits due to hardwired idle-state consumption.
- Countertop Models:Plug-in units with modular positioning flexibility dominate residential volume. US and German markets favor these for kitchen renovation cost control.
- Portable Units:Battery or low-voltage thermal platforms for field and mobile deployment.
- Integrated Solutions:Combined cooking and refrigeration modules with unified control architecture. Quick-service restaurants adopt these fastest for extended unmanned operation.
Countertop models move the highest unit volumes; integrated solutions command the steepest expansion trajectory on commercial automation demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized servo motor suppliers cluster in Germany and Japan, creating dual-source dependencies for precision dispensing mechanisms. Component concentration forces vendors to navigate extended procurement timelines and currency exposure across these manufacturing hubs.
United States
Quick-service restaurant chains deploy robotic kitchen stations fastest, driven by persistent staffing gaps in metropolitan foodservice operations. FCC wireless equipment certification extends hardware release cycles by 8-14 months for Wi-Fi-enabled cooking systems. Smart home installers in California and Texas metropolitan markets bundle guided cooking workflows with Alexa and Google Assistant ecosystem configurations.
Germany
Household penetration of premium guided cooking systems remains deepest globally, sustaining replacement-cycle loyalty through proprietary content libraries. The EU's Ecodesign Directive enforces standby power limits that force thermal management subsystem redesigns. Hospital and university foodservice operators in Bavaria and North Rhine-Westphalia pilot commercial variants to standardize meal preparation across distributed institutional sites.
Japan
METI has initiated consultations on robotics safety standards for domestic kitchen environments, signaling forthcoming compliance obligations for arm-manipulation system vendors. Commercial kitchens in Tokyo and Osaka prefectures pilot optical state-detection sensors for pre-compliance positioning. Precision servo motor suppliers in Nagoya industrial clusters supply motion control subsystems to robotics-grade manufacturers.
China
MIIT and SAMR oversight of connected appliance standards shapes IoT integration requirements for kitchen automation platforms. Yangtze River Delta manufacturing hubs produce base heating elements and sensor arrays for entry-level electric cookers. Domestic appliance brands leverage cost-optimized thermal management platforms to capture price-sensitive household segments across tier-one cities.
United Kingdom
London and Southeast England metropolitan markets show concentrated voice control adoption where digital assistant penetration anchors smart home bundles. CE marking requirements and post-Brexit UKCA conformity assessment procedures create dual certification burdens for connected cooking appliances. Midlands-based foodservice operators evaluate multi-cooker platforms for cross-menu flexibility in contract catering operations.
Autonomous One-Pot Cooking System Market Vendor Landscape
Concentration sits with diversified appliance conglomerates and specialized robotics developers, creating a bifurcated structure where sensor-augmented conventional platforms compete alongside full robotic manipulation systems. Appliance-grade manufacturers leverage existing distribution networks and brand recognition to defend volume positions, while robotics-grade developers occupy narrow defensible positions in hands-free meal preparation. Two strategic archetypes dominate: ecosystem-anchored conglomerates with smart home integration capabilities, and pure-play robotics specialists with precision motion control expertise. Competitive moves center on strategic partnerships with smart home installers and technology licensing agreements for thermal management subsystems.
Among diversified appliance conglomerates, Samsung Electronics Co Ltd and Electrolux AB exemplify ecosystem-anchored positioning, while Thermomix (Vorwerk) represents the premium guided-cooking archetype with proprietary content libraries. Moley Robotics occupies a position within the robotics-grade tier as a pure-play automation specialist. These three companies span distinct competitive vectors: smart home ecosystem integration, recipe-content-driven customer lifetime value, and full robotic arm manipulation for unmanned operation.
| Leading Market Players |
|---|
| Samsung Electronics Co Ltd |
| Electrolux AB |
| Haier Group |
| Panasonic Corporation |
| Philips Domestic Appliances |
| Instant Brands |
| Thermomix (Vorwerk) |
| Moley Robotics |
| Nala Robotics |
| Others |
Supply Flow & Price Mechanics
Sixty-to-ninety-day procurement cycles for precision servo motors from Nagoya and Stuttgart clusters concentrate pricing power with dual-source suppliers, while FCC certification delays extend inventory carrying costs for Wi-Fi-enabled platforms destined for North American quick-service restaurant chains.
Pricing Analysis
The EU's Ecodesign Directive dictates the pricing tier structure across autonomous one-pot cooking systems, separating appliance-grade units with basic sensor augmentation from robotics-grade platforms with precision dispensing and motion control. Price differentiation stems from certification grade—CE marking for basic connectivity versus METI pre-compliance for arm-manipulation systems—and from vertical integration depth in thermal management subsystems. Cost compression in the appliance-grade tier intensifies as German and Chinese manufacturers compete for European household volume. Quick-service restaurant chains show least price sensitivity due to labor substitution payback calculations, while residential buyers in tier-two Chinese cities remain most price-sensitive.
Supply Chain Analysis
Strategic stockpiling of precision servo motors and optical sensor arrays dominates inventory strategy over just-in-time approaches, given eight-to-fourteen-month FCC certification timelines that freeze hardware configurations early. Component supply concentrates in Germany, Japan, and China's Yangtze River Delta, with specialized load-cell arrays and gravimetric feedback mechanisms drawing from Nagoya industrial clusters. Single-source vulnerability runs through German suppliers of high-temperature polymer coatings subject to FDA food-contact notification delays. Distribution runs through smart home installer networks in North American metropolitan markets and institutional procurement consortia in German hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mechatronics engineers commanding premium compensation for simultaneous thermal management and food-safety expertise constrain R&D velocity, concentrating competitive advantage with vendors who have already built these cross-functional teams.
For Market Incumbents: Compound defensive positioning by deepening proprietary recipe content libraries that sustain replacement-cycle loyalty against emerging robotics-grade entrants, while accelerating FDA food-contact substance notifications to compress twelve-to-eighteen-month compliance timelines that currently disadvantage US market entry. For New Entrants and Emerging Players: METI robotics safety standard fast-tracks offer entry into Japanese commercial kitchen pilots before compliance obligations harden, with voice control integration for Alexa and Google Assistant ecosystems providing the most penetrable go-to-market angle in North American smart home installer channels. For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue play because subscription content libraries are displacing hardware margin as the primary profit pool, with acquisition target archetypes being pure-play robotics specialists with precision motion control expertise; the signal to watch is Japan's METI consultation conclusion triggering compliance-first market entry windows.| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Recipe Content Expansion | Thermomix's guided cooking workflows demonstrate how culinary databases sustain replacement-cycle loyalty against hardware competitors. |
| Robotics Safety Certification Fast-Track | METI pre-compliance positioning in Tokyo commercial kitchens creates first-mover advantage before domestic kitchen standards finalize. |
| Smart Home Ecosystem Integration | Samsung's SmartThings anchoring demonstrates how kitchen automation capture expands through broader home IoT architectures. |
| Institutional Procurement Consolidation | German hospital and university foodservice pilots show how distributed site standardization drives commercial variant adoption. |
| Precision Dispensing Mechanism Development | Gravimetric feedback loops in quick-service robotic stations compress performance gaps between multi-cookers and full automation. |
Methodological Framework
Cross-validation between primary interviews with commercial kitchen operators, smart home installation specialists, and thermal management subsystem engineers and secondary validation through FDA food-contact substance notification databases, FCC equipment authorization filings, and EU Ecodesign Directive compliance registries anchors the qualitative findings. Bottom-up triangulation from component supplier interviews in Nagoya and Stuttgart clusters converges with top-down analysis of institutional procurement patterns across German hospital systems.
Sensitivity analysis across thermal management sophistication tiers, connectivity architecture levels, and end-user application segments shapes the analytical framework over the projection horizon. CAGRs derive from segment-level adoption curves weighted by regulatory compliance timelines and labor substitution economics. Modeled inputs include Ecodesign standby power limit redesign costs and METI robotics safety consultation progress indicators.
Underlying assumptions cover sustained labor scarcity in North American foodservice, EU energy efficiency mandate enforcement, and Japan's robotics standardization trajectory, with deviation risk concentrated in FDA material compliance timeline extensions and servo motor supply disruptions. Revision becomes warranted when METI consultation conclusions or Ecodesign threshold adjustments cross implementation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service Equipment
Commercial Rotisserie Oven Market
Food Service Equipment
Food Display Cabinet Market
Food Service Equipment
Prepared Food Equipment Market
Food Service Equipment
Food and Beverage Vending Machine Market
Food Service Equipment
Portable Cooler Market
Food Service Equipment
United States Commercial Dishwasher Market
Food Service Equipment
Digital Menu Boards Market
Food Service Equipment
Commercial Food Warming and Holding Equipment Market
Food Service Equipment
North America Fountain Dispenser Equipment Market
Food Service Equipment
Food Warmer Machines Market
Food Service Equipment
Commercial Refrigerator Market
Food Service Equipment
Combi Cooler Market
Food Service Equipment
Commercial Kitchen Knife Market
Food Service Equipment
Freestanding Large Cooking Appliance Market
Food Service Equipment
Beverage Refrigeration Market
Food Service Equipment
Commercial Catering Equipment Market