
 Global Commercial Cooking Equipment Market | 2026-2036
Global Commercial Cooking Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Commercial Cooking Equipment Market Analysis
Energy Star and EN 60335 certification tiers is bifurcating procurement patterns across the Global Commercial Cooking Equipment Market. Electrolux Professional leverages its European manufacturing base to sustain premium positioning in induction systems. The Middleby Corporation anchors its portfolio through vertical control over conveyor oven technology. RATIONAL differentiates via combi-steamer engineering leadership that commands specification-driven channel access.
Commercial cooking equipment encompasses heavy-duty appliances engineered for continuous food production in professional settings, typically constructed from 304-grade stainless steel with burner outputs exceeding 25,000 BTU and operating temperatures ranging from 150°F to 550°F depending on application. Ovens and fryers represent the highest-margin product categories where replacement cycles compress under intensive-use conditions. End-user demand tilts toward restaurants and catering services as ghost-kitchen formats proliferate, while modular installation configurations gain preference for space-optimized layouts in urban food halls. Electric and induction technologies capture specification share as gas infrastructure restrictions expand across municipalities.
EPA Energy Star certification, EU Ecodesign Directive requirements, and NSF International sanitation standards collectively shape product development roadmaps and market access conditions for equipment manufacturers. FDA Food Code provisions and OSHA ventilation mandates further constrain kitchen system design, elevating total installed cost but protecting incumbents with compliance infrastructure. Stakeholders must monitor evolving electrification mandates in California, Germany, and South Korea to anticipate shifts in technology mix and capital allocation priorities.
Market Dynamics
Electrification mandates across California, Germany, and South Korea are compressing replacement cycles for gas-fired equipment while forcing manufacturers to reconfigure thermal engineering roadmaps around induction and battery-compatible architectures.
Growth Catalysts
- EU Ecodesign Directive:Energy-efficiency mandates accelerate equipment turnover in full-service restaurant chains across France, Italy, and Spain.
- Ghost-kitchen proliferation:Delivery-optimized formats in São Paulo, Dubai, and Jakarta demand compact, high-throughput fryer and oven systems.
- Induction technology maturation:Precision temperature control and reduced ventilation requirements drive specification in Singapore's premium hotel kitchens.
Market Restraints
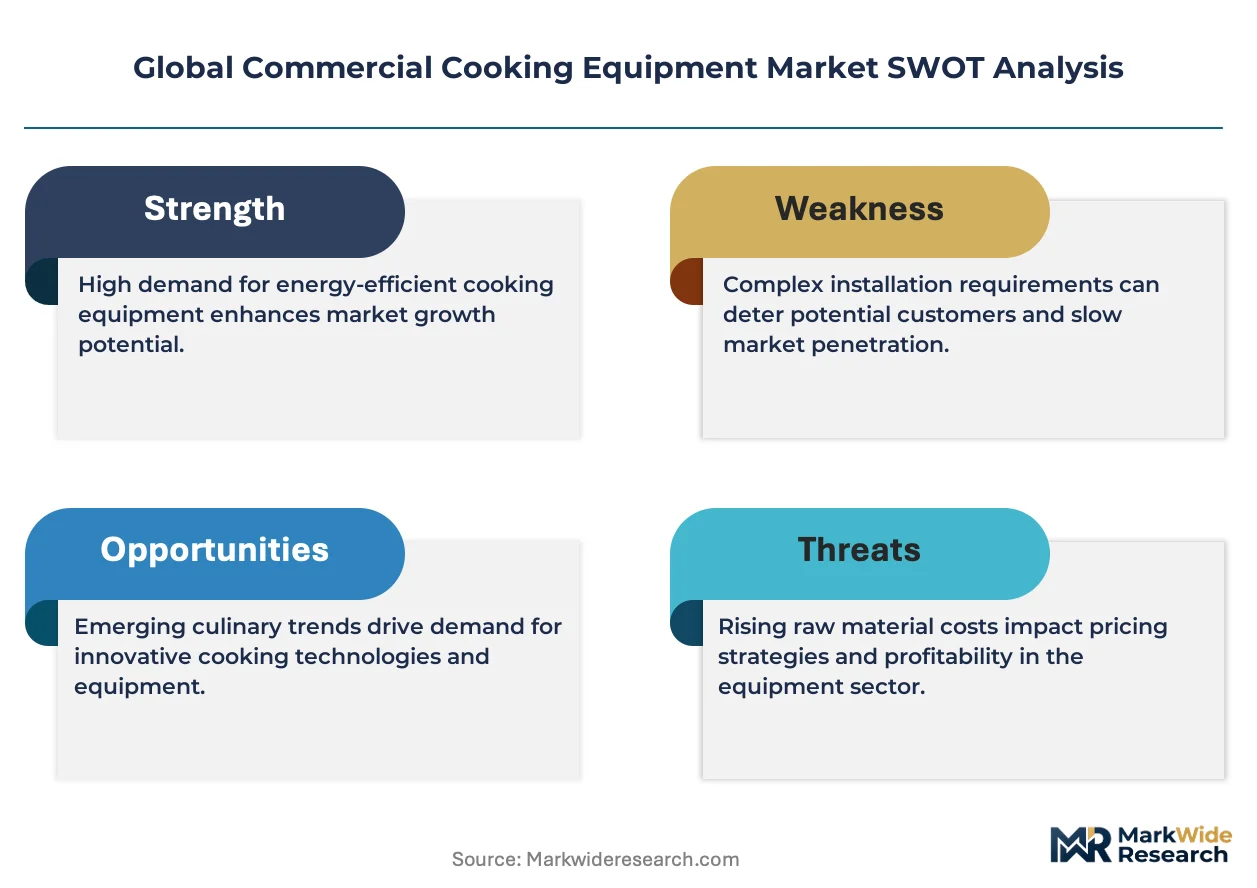
- 304-grade stainless steel volatility:Nickel price swings compress margin visibility for European and North American fabricators.
- Gas infrastructure lock-in:Existing kitchen ventilation and utility configurations in older US urban districts delay electric conversion timelines.
- Combustion equipment substitution:Rapid electrification in South Korean municipalities threatens fryer and range manufacturers with stranded product lines.
Strategic Opportunities
- India's tier-two city expansion:Domestic hotel brands in Jaipur, Lucknow, and Indore underinvest in premium foodservice infrastructure.
- Combi-steamer and battery convergence:Integration with mobile power systems enables off-grid catering and event foodservice in remote Australian and Canadian markets.
- California Title 24 electrification:New construction mandates create captive demand for all-electric kitchen specifications through 2030.
Industry Challenges
- EPA Energy Star certification timelines:Testing backlogs delay product launches by 8-14 months for induction equipment categories.
- Integration complexity:Legacy ventilation and fire suppression systems in existing US restaurant chains resist retrofit for high-BTU electric alternatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Commercial Cooking Equipment Market |
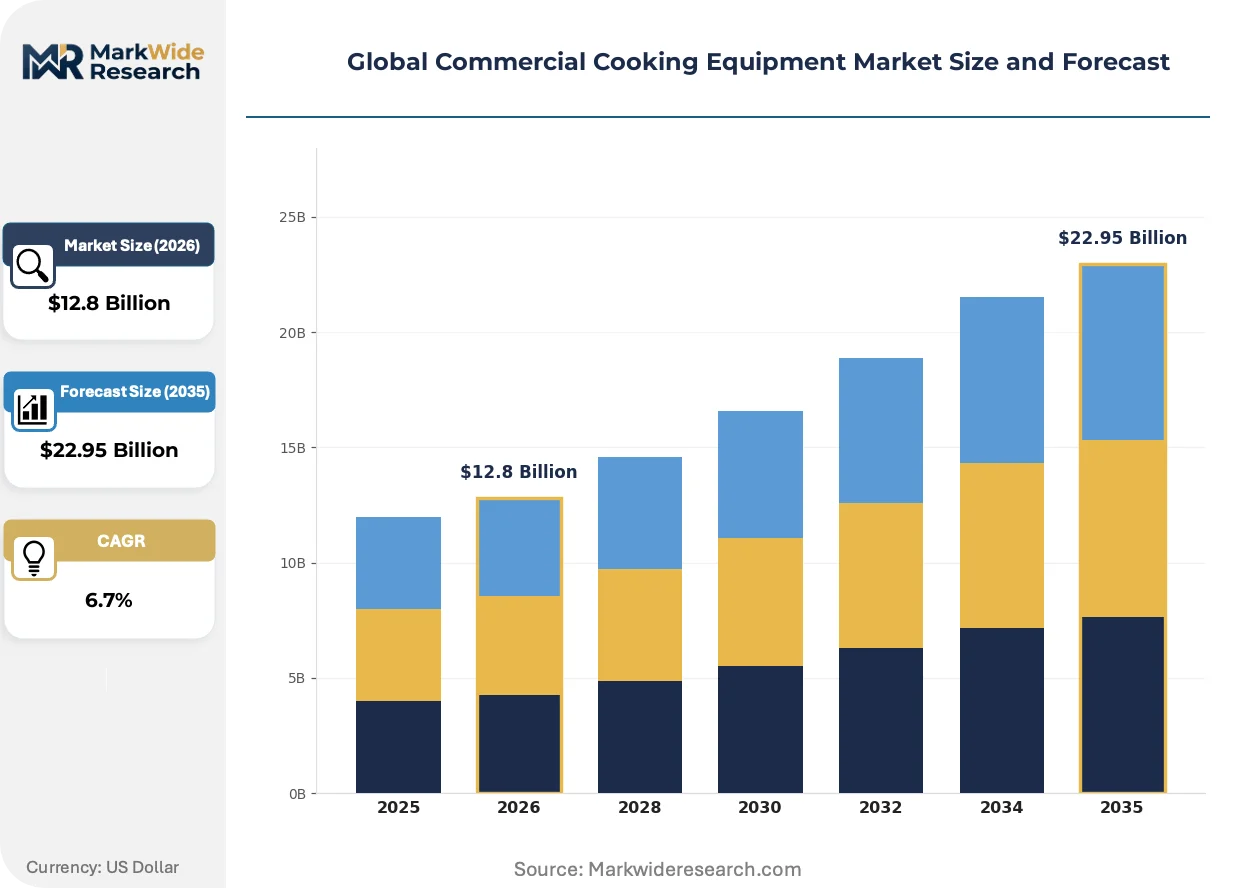
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.95 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
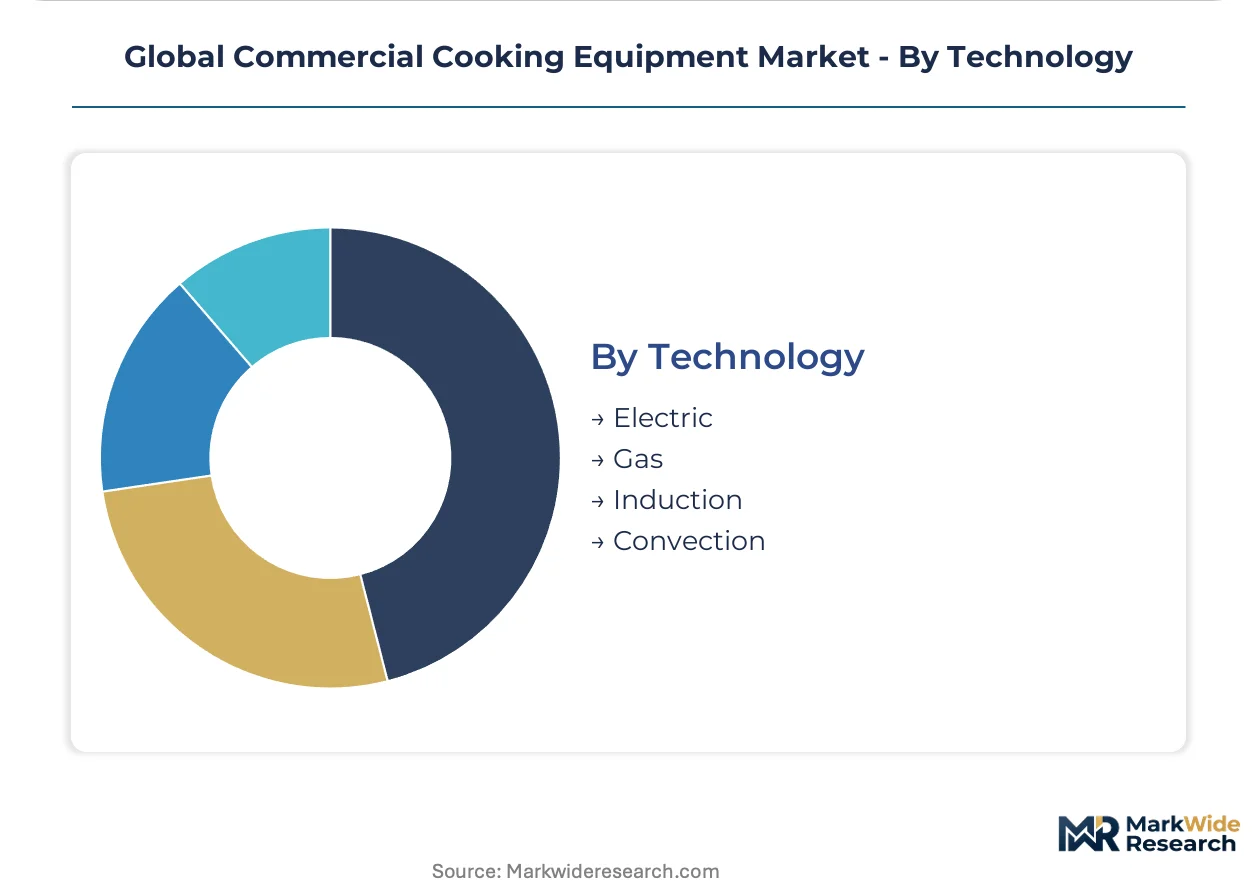
| Segmentation | Product Type: Ovens, Grills, Fryers, Ranges End User: Restaurants, Hotels, Catering Services, Institutions Installation: Built-in, Countertop, Freestanding, Modular Technology: Electric, Gas, Induction, Convection |
| Companies Covered | Electrolux Professional, Duke Manufacturing, The Middleby Corporation, Ali Group, ITW Food Equipment, RATIONAL, Henny Penny Corporation, Hobart Corporation, Alto-Shaam, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Commercial Cooking Equipment Market Emerging Trajectories
Equipment form factors and control architectures are converging around space-constrained urban food halls and battery-dependent mobile operations. Thermal efficiency and connectivity specifications now dominate buyer evaluation criteria.
Induction burner modules are miniaturizing. These solid-state heating elements eliminate open flame and reduce ventilation load. Ghost-kitchen operators in London, Berlin, and Mexico City specify them for 40-60% kitchen footprint reduction. The technology is miniaturizing traditional range configurations into countertop and under-counter formats.
REACH restrictions on per- and polyfluoroalkyl substances (PFAS) are eliminating traditional non-stick coatings from fryer and griddle surfaces. European manufacturers reformulate ceramic and diamond-like carbon alternatives. High-volume fast-casual chains in Germany and the Netherlands face accelerated retooling costs.
Specification decisions now flow through centralized procurement functions rather than individual chef preferences. Large US and UK restaurant groups consolidate vendor panels and demand outcome-based performance guarantees. This consolidation is most visible in contract catering and institutional foodservice segments.
Global Commercial Cooking Equipment Market Segmentation
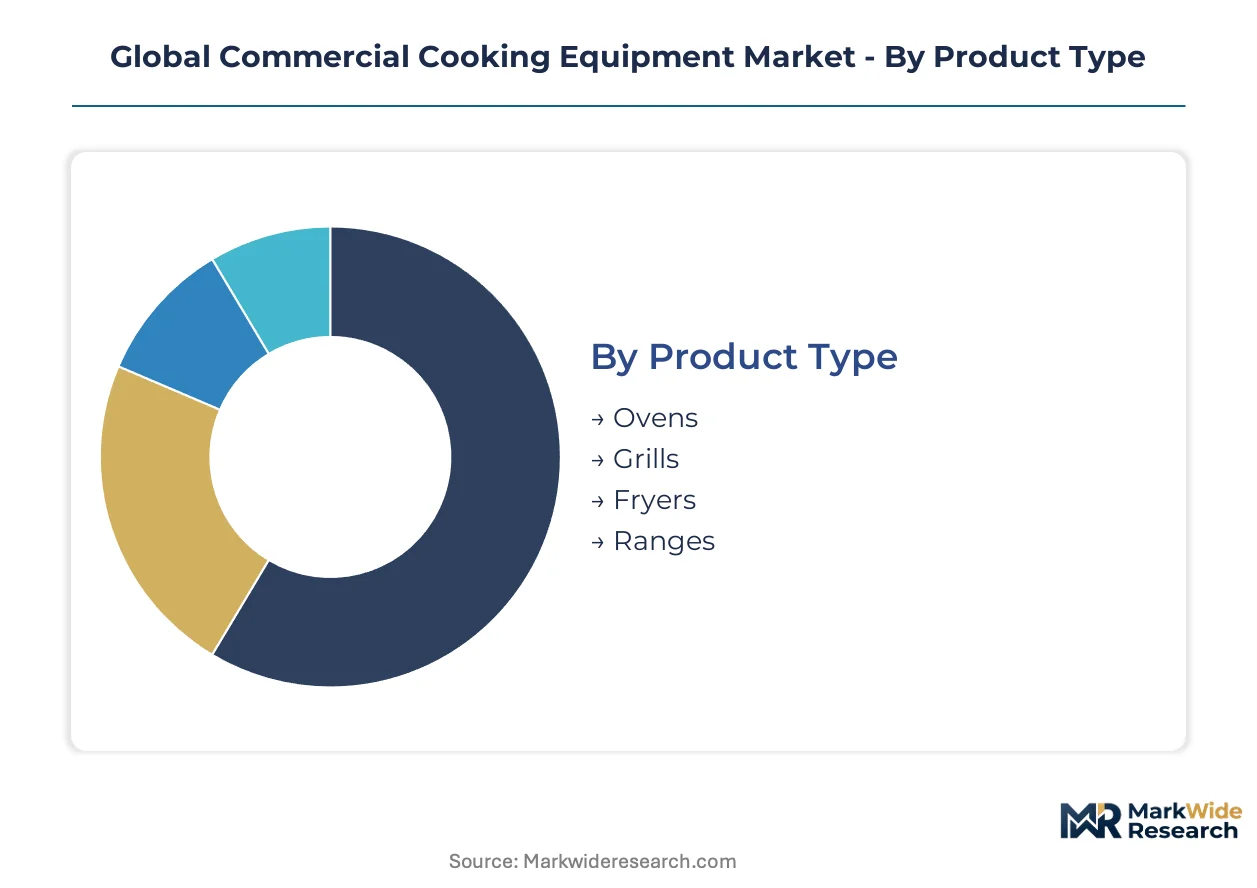
Equipment specification in commercial kitchens diverges sharply across regulatory jurisdictions and operational formats. Segmentation reveals how electrification mandates, space constraints, and certification tiers reshape procurement priorities across product categories and end-use environments.
Product Type:
EPA Energy Star and EU Ecodesign Directive standards create tiered efficiency requirements that favor precision-controlled thermal systems over legacy combustion designs.
- Ovens:Convection and combi-steamer configurations dominate premium specifications in Singapore's hotel kitchens and California's ghost-kitchen clusters. RATIONAL and Electrolux Professional anchor specification channels through programmable humidity control and connected diagnostics that satisfy EU Ecodesign verification protocols.
- Fryers:High-BTU gas and electric immersion systems command margins in fast-casual chains across Germany and the Netherlands, though REACH restrictions on PFAS coatings force ceramic and diamond-like carbon surface reformulation that elevates retooling costs for manufacturers.
- Grills:Radiant and lava-rock configurations persist in traditional steakhouse formats across Texas and Argentina despite electrification pressure.
- Ranges:Open-burner gas systems face replacement compression in South Korean municipalities with aggressive decarbonization timelines.
Established volume favors Ovens; emerging adoption favors Fryers as ghost-kitchen formats prioritize compact, high-throughput oil management systems.
End User:
Procurement centralization in large-format operators is displacing chef-driven specification autonomy.
- Restaurants:Full-service chains across France, Italy, and Spain accelerate equipment turnover under EU Ecodesign mandates, while ghost-kitchen operators in São Paulo, Dubai, and Jakarta demand 40-60% footprint reduction through induction and countertop configurations.
- Hotels:Domestic brand expansion in China's tier-one cities and premium positioning in Singapore drive combi-steamer and induction specification for banquet and à la carte operations.
- Catering Services:Mobile and off-grid formats in remote Australian and Canadian markets explore battery-integrated thermal systems.
- Institutions:Contract catering consolidation across the US and UK demands outcome-based performance guarantees and consolidated vendor panels.
Restaurants command the steepest expansion trajectory; Institutions impose the most rigorous total-cost-of-ownership evaluation frameworks.
Installation:
Urban real estate economics and ventilation infrastructure dictate configuration selection.
- Modular:Space-optimized layouts in London, Berlin, and Mexico City food halls specify interchangeable burner, oven, and refrigeration units that adapt to menu rotation and lease term volatility.
- Countertop:Miniaturized induction modules eliminate hood requirements and enable 24-hour operational flexibility in delivery-only kitchens.
- Built-in:Permanent exhaust integration in legacy US urban districts delays electric conversion where gas infrastructure lock-in persists.
- Freestanding:Traditional casters and utility-flexible connections remain standard in catering and event foodservice for rapid redeployment.
Modular systems gain specification fastest; Freestanding configurations defend installed base in mobile operations.
Technology:
Electrification mandates in California, Germany, and South Korea force thermal engineering roadmaps away from open-flame architectures.
- Induction:Solid-state heating eliminates combustion ventilation load and enables precision temperature control that satisfies Singapore's premium hotel procurement standards. Testing backlogs for EPA Energy Star certification delay product launches by 8-14 months.
- Electric:Resistance-element ovens and fryers capture share where gas infrastructure restrictions expand, though legacy ventilation and fire suppression systems in older US restaurant chains resist retrofit for high-BTU alternatives.
- Gas:Existing kitchen configurations in US urban districts and Latin American markets sustain replacement demand despite regulatory pressure.
- Convection:Forced-air circulation technology integrates across electric and gas platforms for uniform heat distribution in high-volume baking operations.
Induction climbs the fastest among new specifications; Gas defends replacement cycles in infrastructure-constrained geographies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export precision-engineered thermal systems to Southeast Asian hotel chains and North American ghost-kitchen operators. Italian fabricators supply premium combi-steamers to French and Spanish restaurant groups under EU Ecodesign compliance timelines.
United States
Full-service restaurant chains accelerate equipment turnover under California Title 24 electrification mandates and EPA Energy Star certification requirements. Ghost-kitchen clusters in Los Angeles, Chicago, and New York City specify compact induction modules for 40-60% footprint reduction. Gas infrastructure lock-in across older urban districts delays electric conversion timelines despite regulatory pressure.
Germany
REACH restrictions on PFAS coatings force ceramic and diamond-like carbon surface reformulation for fryer manufacturers serving fast-casual chains. The EU Ecodesign Directive compresses replacement cycles for convection and combi-steamer equipment. Industrial fabricators in Baden-Württemberg and North Rhine-Westphalia anchor supply to French, Italian, and Spanish restaurant markets.
China
Domestic hotel brands in Shanghai, Beijing, and Shenzhen scale premium foodservice operations with induction and combi-steamer specifications. Tier-one city procurement concentrates in banquet and à la carte kitchen expansions. Local manufacturing clusters supply cost-optimized electric fryers and ovens to Southeast Asian export markets.
South Korea
Aggressive municipal decarbonization timelines in Seoul and Busan compress replacement cycles for open-burner gas ranges. Induction technology captures specification share in premium hotel and institutional kitchens. Battery-compatible thermal architectures emerge for mobile catering operations in remote mountain and coastal regions.
Australia
Off-grid catering demand in Western Australia and Queensland drives exploration of battery-integrated combi-steamer systems. Remote mining camp foodservice and event catering operations prioritize mobile, ventilation-independent configurations. Sydney and Melbourne ghost-kitchen operators specify compact countertop induction for urban density constraints.
Global Commercial Cooking Equipment Market Vendor Landscape
Listed leaders compete with private specialists across certification infrastructure and thermal engineering capabilities. The vendor base clusters around three tiers: multinational diversified equipment houses, regional stainless-steel fabricators, and precision-control technology specialists. Two strategic archetypes dominate: European manufacturers leveraging regulatory compliance as specification moats, and North American players capturing scale through conveyor and fryer system standardization. Competitive moves concentrate on M&A for induction technology access and vertical control over burner module supply.
Within the premium engineering tier, RATIONAL and Electrolux Professional exemplify specification-driven positioning through European manufacturing bases and Ecodesign verification protocols. The Middleby Corporation anchors a scale-driven archetype with North American operational density. Among diversified equipment houses, ITW Food Equipment and Hobart Corporation occupy positions spanning institutional and commercial end-use segments.
| Leading Market Players |
|---|
| Electrolux Professional |
| Duke Manufacturing |
| The Middleby Corporation |
| Ali Group |
| ITW Food Equipment |
| RATIONAL |
| Henny Penny Corporation |
| Hobart Corporation |
| Alto-Shaam, Inc. |
| Others |
Supply Flow & Price Mechanics
EPA Energy Star certification tiers gate both supply qualification and price differentiation simultaneously, creating procurement bifurcation where verified manufacturers command specification premiums while uncertified competitors compete on transactional cost. This regulatory scaffolding concentrates pricing power with incumbent fabricators who have absorbed compliance infrastructure costs.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation separates NSF-verified stainless fabricators from commodity Asian suppliers and from European precision-engineering houses. Pricing pressure stems from nickel volatility in 304-grade stainless feedstock. Fast-casual chains exhibit highest price sensitivity; premium hotel groups prioritize total-cost-of-ownership over unit economics.
Supply Chain Analysis
Strategic stockpiling of nickel and chromium dominates inventory strategy among European and North American fabricators facing commodity volatility. Supply concentrates in China, Germany, and Italy for thermal system assembly. Component dependencies include 304-grade stainless steel, solid-state induction modules, and ceramic PFAS-free coatings. Single-source vulnerability runs through Indonesian nickel refining. Distribution runs through manufacturer-direct specification channels and foodservice equipment distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Connected diagnostics and predictive maintenance subscriptions expand faster than hardware sales, transforming capital equipment into service-attach platforms with recurring revenue streams.
For Market Incumbents: Fortify specification moats through accelerated EPA Energy Star and EU Ecodesign certification pipelines before testing backlogs widen. Deepen captive supply of induction burner modules to defend margin position against Asian component imports. Electrification mandates in California and Germany compress replacement cycles for gas-fired portfolios. For New Entrants and Emerging Players: NSF International fast-track certification unlocks institutional procurement panels in US contract catering. India's tier-two cities present penetrable white space where domestic hotel brands underinvest in premium infrastructure. Target battery-integrated thermal architectures for Australian and Canadian off-grid catering segments. For Investors and Strategic Acquirers: California Title 24 electrification milestones reshape the acquisition landscape toward all-electric specification capabilities. Long-term viability favors targets with induction engineering depth and Ecodesign verification infrastructure. Watch EPA Energy Star testing backlog resolution as inflection indicator for product launch velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Induction Technology Acquisition | Secures thermal engineering capabilities for electrification mandates in California and Germany. |
| Connected Diagnostics Platform Launch | Enables predictive maintenance subscriptions that attach recurring revenue to hardware sales. |
| Battery Integration Partnership | Opens off-grid catering and remote event foodservice in Australian and Canadian markets. |
| PFAS-Free Coating Reformulation | Addresses REACH restrictions and qualifies equipment for European fast-casual procurement panels. |
| Ghost-Kitchen Configuration Development | Captures compact footprint demand in São Paulo, Dubai, and Jakarta delivery-only formats. |
Methodological Framework
Two parallel data streams informed the analysis: primary interviews with foodservice equipment procurement directors, kitchen design consultants, and aftermarket service heads; and secondary validation through NSF International certification databases, EPA Energy Star product listings, and EU Ecodesign compliance registries. Bottom-up equipment shipment data triangulated against top-down foodservice construction spending estimates.
Across the projection horizon, the analytical framework modeled segmentation across product type, end-user format, installation configuration, and thermal technology platform. CAGRs derived from equipment replacement cycle compression under regulatory mandates and from electrification adoption curves in specified municipalities. Forecast inputs included nickel price volatility scenarios and ghost-kitchen format proliferation rates.
Underlying assumptions cover regulatory enforcement continuity and stainless steel supply stability, with deviation risk concentrated in EPA certification timeline delays and accelerated municipal gas bans. Revision becomes warranted when electrification mandate adoption crosses threshold penetration in tier-one urban markets.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service Equipment
Autonomous One-Pot Cooking System Market
Food Service Equipment
Europe Commercial Dishwashers Market
Food Service Equipment
Global Commercial Dishwashers Market
Food Service Equipment
Electric Commercial Deep Fryers Market
Food Service Equipment
Automatic Popcorn Machine Market
Food Service Equipment
Hot Food Display Cabinet Market
Food Service Equipment
Remote Cooled Cube Ice Machines Market
Food Service Equipment
Gas Smoker Market
Food Service Equipment
Multi Cooker Market
Food Service Equipment
UK Countertop Ice Makers Market
Food Service Equipment
Prepared Food Equipment Market
Food Service Equipment
Commercial Ice Equipment and Supplies Market
Food Service Equipment
Warewashing Equipment Market
Food Service Equipment
Commercial Rotisserie Equipment Market
Food Service Equipment
North America Fountain Dispenser Equipment Market
Food Service Equipment
Food and Beverage Vending Machine Market