
 Back Bar Coolers Market | 2026-2036
Back Bar Coolers Market Size, Share, and Industry Trends Forecast 2026-2036
Back Bar Coolers Market Outlook
Craft cocktail lounges and microbrewery taprooms is bifurcating demand away from traditional hotel banquet buyers who once dominated procurement volumes. True Manufacturing leverages captive metal fabrication to control cabinet lead times across North American distribution. Hoshizaki Corporation anchors its position through ice-making adjacencies that create bundled specification relationships with bar designers. Turbo Air competes aggressively on compressor warranty terms that reduce total cost of ownership calculations for independent operators.
Back bar coolers are forced-air refrigeration cabinets engineered to maintain beverage temperatures between 33°F and 38°F while accommodating standard 330ml to 750ml bottle formats within depths rarely exceeding 24 inches, purpose-built for service-speed access in high-traffic alcohol service environments. Glass-front coolers command specification preference in open-kitchen and visible-bar concepts where bottle display drives menu storytelling and per-seat revenue. Compressor-based cooling technology dominates installed base economics despite thermoelectric advances in compact countertop formats where noise and vibration constraints matter most.
The US Department of Energy commercial refrigeration standards and the EPA SNAP program governing hydrofluorocarbon phase-down jointly determine compressor refrigerant selection and insulation panel specifications for products sold into American foodservice channels. European access requires CE marking conformity with Ecodesign regulations on energy labeling and the F-Gas Regulation's tightening GWP thresholds for blowing agents and refrigerant charges. Stakeholders must decide whether to engineer separate regional product families or pursue unified platforms that satisfy the most stringent efficiency denominator.
Market Dynamics
Variable-speed compressor architectures are forcing a wholesale redesign of back bar cooler supply chains as US DOE efficiency standards eliminate fixed-speed models from American foodservice channels. Manufacturers must retool fabrication lines while independent craft breweries and gastropubs accelerate replacement cycles ahead of compliance deadlines.
Growth Catalysts
- EPA SNAP Phase-Down:Hydrofluorocarbon refrigerant restrictions are compressing replacement demand into 2024-2026 windows as operators pre-empt obsolescence.
- Craft Beverage Expansion:Taproom buildouts in Texas, Florida, and California are generating specification volume for glass-front display units that support menu storytelling.
- Forced-Air Engineering Advances:Improved evaporator coil geometries are extending compressor service intervals, reducing total cost of ownership calculations for independent operators.
Market Restraints
- Copper and Aluminum Volatility:Input cost swings for heat exchanger materials are compressing margin predictability for cabinet fabricators.
- Compressor Supply Concentration:Sourcing dependency on Asian motor manufacturers creates lead time vulnerability for North American assembly plants.
- Thermoelectric Performance Ceiling:Peltier cooling efficiency limitations block adoption beyond compact countertop formats in noise-sensitive installations.
Strategic Opportunities
- Underpenetrated Secondary Markets:Austin, Nashville, and Denver hospitality construction permits indicate refrigerated display capacity expansion ahead of national saturation.
- Bundle Specification Relationships:Ice-making equipment adjacencies create integrated bar design opportunities with consulting specifiers.
- CE Marking Convergence:Unified platform engineering for Ecodesign and F-Gas Regulation compliance opens European gastropub and hotel channels without regional SKU duplication.
Industry Challenges
- Refrigeration Technician Scarcity:Variable-speed diagnostic competency gaps are extending service call resolution times in distributed independent operator networks.
- Legacy Control System Integration:Building management system compatibility requirements complicate specification for hotel chain retrofit programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Back Bar Coolers Market |
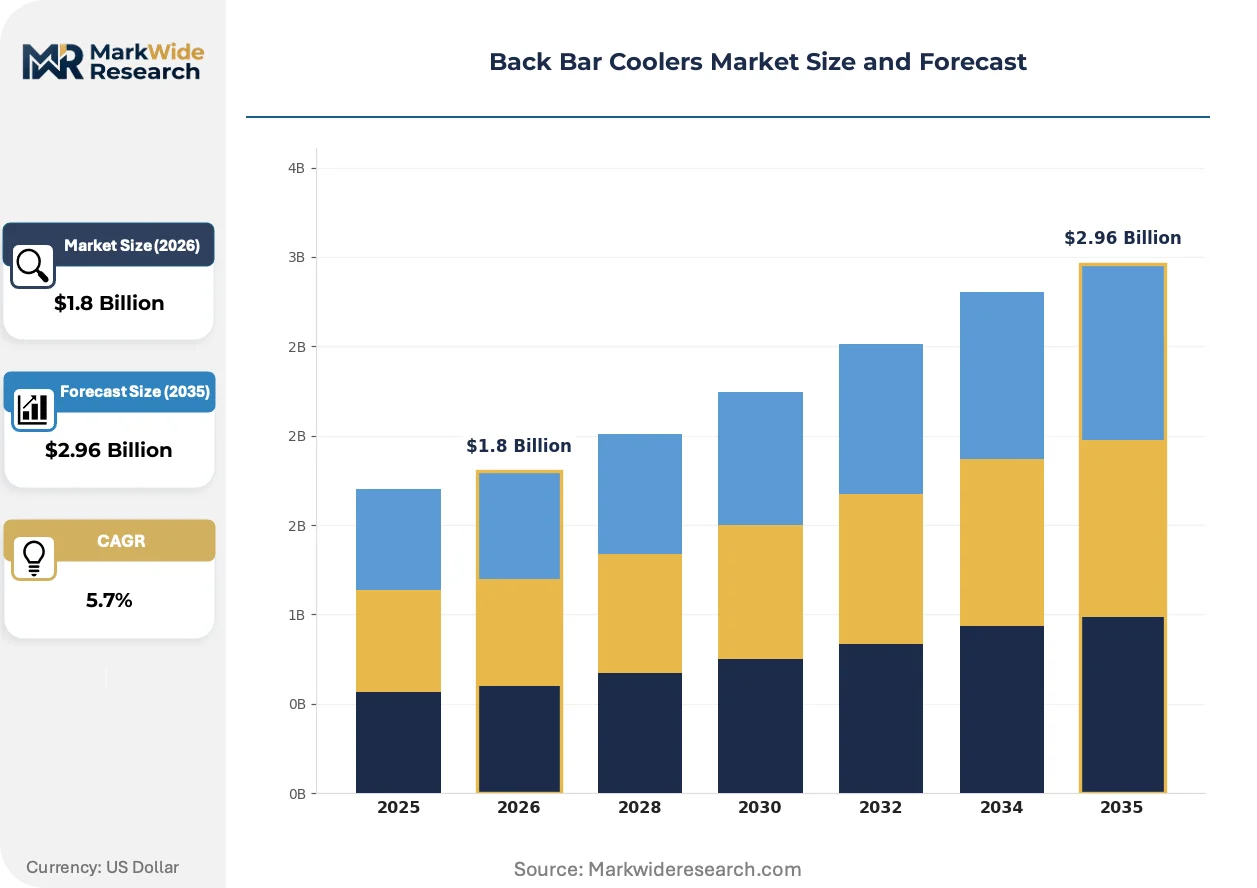
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Door Coolers, Double-Door Coolers, Multi-Door Coolers, Glass-Front Coolers End User: Pubs, Restaurants, Hotels, Nightclubs Installation Type: Built-In, Free-Standing, Countertop, Commercial Cooling Technology: Thermoelectric, Compressor, Absorption, Cascade |
| Companies Covered | True Manufacturing, Hoshizaki Corporation, Turbo Air, Hussmann Corporation, Beverage-Air Corporation, Perlick Corporation, Liebherr USA, Procool, Everest Refrigeration, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Back Bar Coolers Market Strategic Shifts
Refrigeration engineering is pivoting toward modularity and connectivity as bar operators demand flexible capacity configurations and remote monitoring capabilities. Equipment specification now prioritizes adaptive compressor control and data visibility over static capacity ratings.
Thermoelectric cooling modules are miniaturizing for under-counter and mobile bar applications where compressor vibration compromises wine and craft beer service quality. Boutique cocktail lounges in Manhattan and Brooklyn are specifying these units for front-of-house installations where acoustic performance outweighs energy efficiency tradeoffs. The technology is miniaturizing cabinet footprints to 18-inch depths previously unreachable with forced-air systems, enabling bar designers to reclaim floor space for seating revenue.
The US Department of Energy commercial refrigeration standards and EPA SNAP program are jointly eliminating R-404A and R-507A refrigerants from new equipment sales. Manufacturers are engineering R-448A and R-449A drop-in replacements while redesigning insulation panels to maintain thermal performance with reduced blowing agent volumes. California and New York operators face the most compressed compliance timelines as state-level accelerations precede federal mandates.
Specification authority is migrating from hotel procurement departments to independent bar designers and consulting chefs who prioritize aesthetic integration over brand loyalty. Design-build firms in Miami, Los Angeles, and Chicago are bundling cooler selection with millwork and lighting specifications, displacing traditional equipment distributor relationships. This channel consolidation concentrates volume with specifiers who cross-reference ice-making, refrigeration, and display requirements across single-project contracts.
Back Bar Coolers Market Segmentation
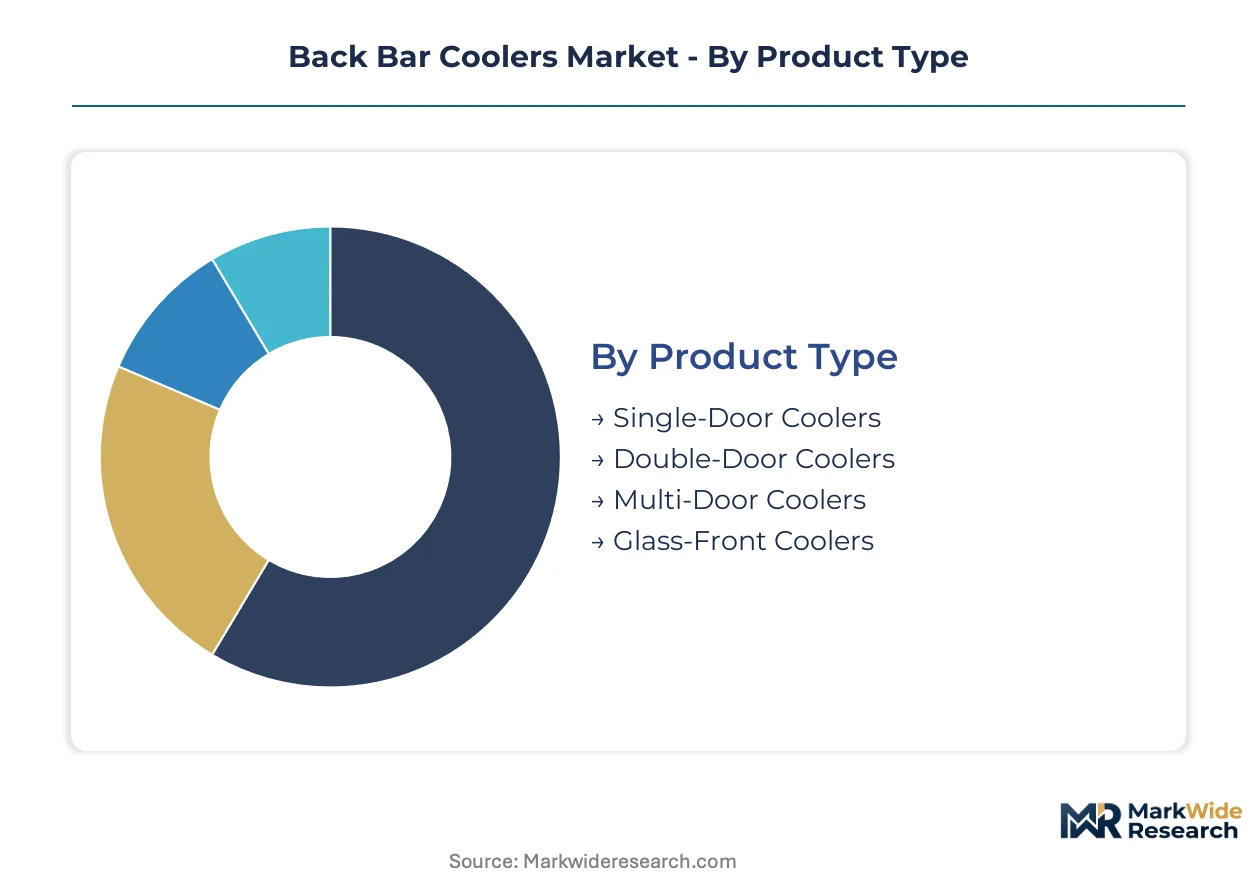
Back bar cooler procurement patterns diverge sharply between independent hospitality operators and institutional buyers, with specification authority migrating toward design-build firms who bundle refrigeration with millwork. Understanding segment boundaries clarifies why glass-front units command premium positioning in craft beverage channels while compressor reliability dominates hotel procurement criteria.
Product Type:
Glass-front and multi-door variants drive export volume to European gastropub channels, while single-door and double-door units concentrate in domestic replacement cycles across Texas, Florida, and California.
- Glass-Front Coolers:Forced-air cabinets with LED-illuminated display interiors maintain 33°F to 38°F while enabling bottle visibility for menu storytelling. Demand concentrates in Austin, Nashville, and Denver craft cocktail lounges where aesthetic integration drives per-seat revenue calculations.
- Multi-Door Coolers:Modular three-to-four-door configurations accommodate variable bottle formats across craft beer, wine, and spirits SKUs. Independent gastropubs in Brooklyn and Manhattan specify these units for high-SKU-count back bars where service speed outweighs floor space constraints.
- Single-Door Coolers:Compact 18-inch to 24-inch depth units serve countertop and under-bar installations in space-constrained urban locations.
- Double-Door Coolers:Mid-capacity workhorses balance storage density with service accessibility for mid-volume independent operators.
Glass-front coolers hold the largest share; momentum sits with multi-door configurations as craft beverage SKU proliferation accelerates.
End User:
Pubs and nightclubs prioritize acoustic performance and rapid temperature recovery, while hotels and restaurants weight energy efficiency certifications and warranty terms more heavily in total cost of ownership models.
- Pubs:Independent craft brewery taprooms generate specification volume for variable-speed compressor architectures ahead of EPA SNAP compliance deadlines. Texas and Florida permit data indicates refrigerated display capacity expansion outpacing legacy hotel chain procurement.
- Nightclubs:High-traffic alcohol service environments demand forced-air systems with rapid door-recovery performance. Manhattan and Miami operators specify thermoelectric modules for VIP areas where compressor vibration compromises premium wine service.
- Restaurants:Open-kitchen concepts drive glass-front penetration as consulting chefs prioritize visible bottle display for menu narrative integration.
- Hotels:Procurement departments face legacy building management system integration constraints that complicate variable-speed control specification for retrofit programs.
Pubs dominate current procurement volume; nightclubs represent the steepest expansion trajectory as experiential hospitality concepts proliferate.
Installation Type:
Built-in and countertop formats concentrate specification with design-build firms in coastal metropolitan markets, while free-standing and commercial installations persist in value-oriented independent operator channels.
- Built-In:Flush-mount millwork integration requires precise 24-inch depth compliance and custom panel-ready exteriors. Los Angeles and Chicago design-build firms bundle these specifications with lighting and bar surface materials.
- Countertop:Thermoelectric miniaturization enables 18-inch depth footprints previously unreachable with forced-air systems. Brooklyn boutique cocktail lounges specify these for front-of-house acoustic performance.
- Free-Standing:Roll-in mobility supports temporary and seasonal bar configurations in event hospitality and festival circuits.
- Commercial:Heavy-duty framing and reinforced shelving accommodate high-volume bottle turnover in airport and stadium concessions.
Built-in installations command the specification premium; countertop formats are gaining share fastest as urban floor space economics intensify.
Cooling Technology:
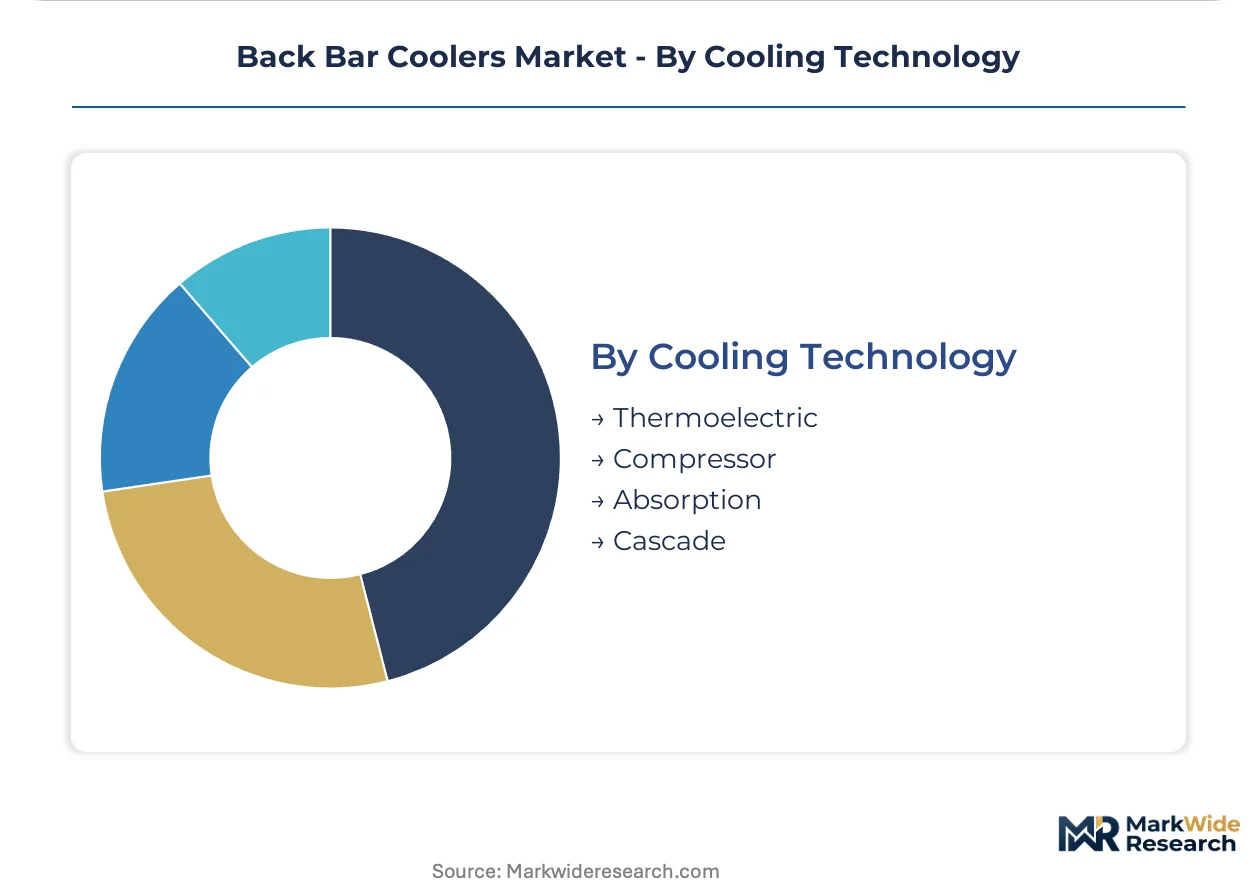
Compressor architectures face regulatory pressure from US DOE efficiency standards, while thermoelectric and absorption alternatives capture niche applications where noise constraints or off-grid operation justify efficiency tradeoffs.
- Compressor:Variable-speed scroll and reciprocating systems dominate installed base economics through superior coefficient of performance. US DOE commercial refrigeration standards are eliminating fixed-speed models from American foodservice channels.
- Thermoelectric:Peltier modules eliminate vibration and audible cycling for wine and craft beer quality preservation. Manhattan and Brooklyn front-of-house installations accept energy penalties for acoustic performance.
- Absorption:Ammonia-based systems serve off-grid and mobile bar applications where electrical infrastructure is unavailable or unreliable.
- Cascade:Dual-refrigerant architectures enable ultra-low temperature spirits service in premium cocktail programs requiring precise thermal zones.
Compressor technology holds the largest share; thermoelectric formats show the strongest momentum as craft beverage quality sensitivity expands beyond traditional wine service.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Assembly plants for forced-air refrigeration cabinets cluster in the United States, Germany, China, and Japan where component ecosystems for compressor systems and metal fabrication have matured. Regulatory divergence between EPA SNAP phase-down timelines and EU F-Gas Regulation thresholds is forcing manufacturers to engineer region-specific product families or pursue unified compliance platforms.
United States
Texas, Florida, and California hospitality construction permits are driving refrigerated display capacity expansion faster than legacy hotel chain procurement. The EPA SNAP program and US Department of Energy commercial refrigeration standards are eliminating R-404A and R-507A refrigerants while mandating variable-speed compressor architectures. Austin craft brewery taprooms and Miami design-build firms are specifying glass-front units that bundle millwork integration with LED-illuminated bottle display.
Germany
Gastropub and hotel channel procurement in Bavaria and North Rhine-Westphalia is accelerating specification of CE-marked units conforming to Ecodesign energy labeling requirements. The EU F-Gas Regulation's tightening GWP thresholds for blowing agents and refrigerant charges are determining insulation panel specifications for products sold into German foodservice channels. Berlin-Brandenburg consulting specifiers are bundling cooler selection with bar surface materials and lighting design.
China
Domestic hospitality construction in the Yangtze River Delta and Pearl River Delta is generating demand for compact under-counter formats in space-constrained urban bar concepts. The country's national commercial refrigeration efficiency standards and dual carbon goals are pressuring manufacturers toward improved evaporator coil geometries. Shanghai boutique cocktail lounges are specifying thermoelectric modules for front-of-house installations where acoustic performance outweighs energy efficiency tradeoffs.
Japan
Kanto and Kansai region taproom buildouts are creating specification volume for modular multi-door configurations accommodating craft beer, wine, and spirits SKUs. METI efficiency standards and JIS certification requirements are shaping compressor refrigerant selection for products sold into Japanese foodservice channels. Tokyo bar designers are prioritizing aesthetic integration and millwork compatibility over brand loyalty in equipment procurement.
Back Bar Coolers Market Competitive Environment
Concentration sits with diversified refrigeration equipment manufacturers who leverage captive metal fabrication and compressor sourcing relationships to control cabinet lead times. The vendor base spans North American metal fabrication specialists, Japanese ice-making equipment providers, and Asian assembly operations serving value-oriented independent operators. Two strategic archetypes dominate: vertically integrated fabricators with in-house compressor specification authority, and design-build bundlers who cross-reference refrigeration with millwork and lighting requirements. Competitive moves center on warranty term extension to reduce total cost of ownership calculations, and geographic expansion through CE marking convergence for unified platform engineering.
Among North American metal fabrication specialists, True Manufacturing exemplifies the vertically integrated archetype through captive cabinet production, while Hussmann Corporation and Beverage-Air Corporation occupy positions within the diversified refrigeration equipment tier. Japanese providers represented by Hoshizaki Corporation anchor specification relationships through ice-making equipment adjacencies. Turbo Air sits within the value-oriented independent operator channel where aggressive compressor warranty terms influence procurement decisions. These named entities represent the competitive structure without exhaustively cataloging market participants.
| Leading Market Players |
|---|
| True Manufacturing |
| Hoshizaki Corporation |
| Turbo Air |
| Hussmann Corporation |
| Beverage-Air Corporation |
| Perlick Corporation |
| Liebherr USA |
| Procool |
| Everest Refrigeration |
| Others |
Value Chain & Pricing Dynamics
EPA SNAP phase-down timelines and US DOE efficiency standards simultaneously gate supplier qualification and stratify price tiers across the back bar cooler market. Manufacturers must absorb variable-speed compressor retooling costs while design-build specifiers bundle premium glass-front units with millwork integration.
Pricing Analysis
US DOE commercial refrigeration standards dictate the pricing tier structure by eliminating fixed-speed models and forcing R-448A/R-449A refrigerant transitions. Three-tier pricing structure across premium, standard, and economy levels separates CE-marked European export units from domestic compliance SKUs and value-oriented Asian assembly. Cost compression in mid-tier configurations is intensifying because copper and aluminum volatility compresses heat exchanger margins. Independent craft brewery taprooms exhibit highest price sensitivity while Miami design-build firms prioritize aesthetic integration over unit economics.
Supply Chain Analysis
Container availability fluctuations on Asia-North America trade lanes are extending compressor lead times for assembly plants in the United States and Germany. Sourcing concentrates in China for scroll compressor motors, in Germany for precision coil fabrication, and in Japan for ice-making adjacency components. Raw material dependencies span copper tubing, aluminum heat exchanger fins, and polyurethane blowing agents. Single-source vulnerability sits with Asian motor manufacturers. Distribution runs through design-build bundlers in coastal metropolitan markets and traditional equipment distributors in secondary cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The back bar cooler market is approaching a platform-economics inflection as remote monitoring capabilities and variable-speed diagnostic data create equipment-as-a-service monetization. Interoperability between refrigeration telemetry and building management systems is reshaping specification authority.
For Market Incumbents: Secure captive compressor sourcing relationships to buffer against Asian motor manufacturer lead time volatility. Extend warranty terms on variable-speed scroll systems to defend against Turbo Air's total cost of ownership positioning. Invest in CE marking convergence engineering to preempt regional SKU duplication costs from divergent EPA SNAP and EU F-Gas Regulation timelines. For New Entrants and Emerging Players: Lead with thermoelectric miniaturization for Manhattan and Brooklyn front-of-house installations where acoustic performance commands premium positioning. Target underpenetrated Austin, Nashville, and Denver craft cocktail lounges with 18-inch depth countertop formats. Bundle specification relationships with consulting bar designers who cross-reference lighting and millwork requirements. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified refrigeration equipment parents seeking to monetize non-core back bar portfolios. Five-to-ten year viability hinges on unified platform engineering capabilities spanning EPA SNAP, EU F-Gas, and METI efficiency standards. Watch for state-level refrigerant accelerations in California and New York as inflection indicators compressing replacement demand windows.| Strategic Initiative | Industry Significance |
|---|---|
| Variable-Speed Compressor Platform Migration | US DOE efficiency standards mandate forced transition eliminating fixed-speed model revenue streams. |
| CE Marking Convergence Engineering | Unified Ecodesign and F-Gas compliance opens German gastropub channels without regional SKU duplication. |
| Design-Build Bundler Partnership | Miami and Los Angeles specifiers cross-reference refrigeration with millwork and lighting procurement. |
| Thermoelectric Acoustic Performance Tier | Brooklyn boutique lounges accept energy penalties for front-of-house vibration elimination. |
| Remote Monitoring Capability Integration | Telemetry interoperability with building management systems addresses hotel chain retrofit constraints. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with bar designers, consulting chefs, hotel procurement directors, craft brewery operations managers, and refrigeration service technicians. Secondary validation drew from EPA SNAP program filings, US DOE efficiency standard dockets, EU Ecodesign energy labeling databases, and hospitality construction permit records. Bottom-up unit shipment estimates triangulated against top-down value chain analysis across the projection horizon.
Across the modeling period, forecasts segmented by cooling technology, installation type, end-user channel, and regional regulatory cluster. CAGRs derived from replacement cycle acceleration patterns, SKU proliferation trajectories, and compliance deadline clustering. Model inputs included compressor supply lead time indices, copper and aluminum price volatility bands, and state-level refrigerant acceleration schedules.
Forecasts assume regulatory continuity in EPA SNAP phase-down timelines and EU F-Gas Regulation thresholds; material policy shifts would require re-modeling. Commodity price volatility, compressor supply concentration events, or hospitality construction permit collapses in Texas, Florida, or California could revise trajectory. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service Equipment
Commercial Ventless Cooking Equipment Market
Food Service Equipment
Sheet Pan Racks Market
Food Service Equipment
Ice Maker Market
Food Service Equipment
Global Refrigerated Display Cases and Chilled Rooms Market
Food Service Equipment
Commercial Gas Restaurant Ranges Market
Food Service Equipment
Instant Pot Market
Food Service Equipment
Commercial Kitchen Knife Market
Food Service Equipment
Commercial Rotisserie Equipment Market
Food Service Equipment
Low-Sugar Rice Cooker Market
Food Service Equipment
Used Restaurant Equipment Market
Food Service Equipment
United States Commercial Dishwasher Market
Food Service Equipment
North America Countertop Ice Makers Market
Food Service Equipment
US and Canada Hot Food Vending Machine Market
Food Service Equipment
Automatic Popcorn Machine Market
Food Service Equipment
Food Holding Equipment Market
Food Service Equipment
Hospital Foodservice Equipment Market