
 Yeast and Yeast Extract Market | 2026-2036
Yeast and Yeast Extract Market Size, Share, and Industry Trends Forecast 2026-2036
Yeast and Yeast Extract Market Outlook
European baker's yeast producers is realigning capacity toward specialty extract lines. Lesaffre Group leverages vertical integration from fermentation to finished extract, sustaining margin control across the value chain. Angel Yeast Co., Ltd. anchors Asia-Pacific supply with large-scale molasses-based fermentation complexes. Lallemand Inc. differentiates through strain banking capabilities that serve both food and animal nutrition customers.
Yeast and yeast extract comprises single-celled fungi of the Saccharomyces genus cultivated on carbohydrate substrates, then processed through autolysis or plasmolysis to release intracellular proteins, nucleotides, and B-vitamins for flavor enhancement and nutritional fortification. Baker's yeast occupies the mature volume core, while nutritional yeast extracts command premium positioning in clean-label savory formulations. The food industry end-user segment channels the bulk of procurement, though nutraceutical applications are pulling higher-margin instant yeast derivatives for supplement fortification.
EFSA novel food assessments, FDA GRAS self-affirmation pathways, and EU organic processing standards collectively govern strain approval, labeling claims, and substrate sourcing across jurisdictions. These frameworks elevate compliance costs for new entrants while rewarding incumbent investments in documentation and certification infrastructure. Stakeholders must monitor evolving strain-level transparency requirements as procurement criteria tighten across European and North American buyer specifications.
Market Dynamics
Fermentation biotechnology clusters in Germany are consolidating regional supply chains while EFSA clean-label mandates force disclosure reformulation across European savory applications.
Growth Catalysts
- Molasses substrate optimization:Carbohydrate feedstock refinement is lowering unit production costs for baker's yeast volume leaders.
- EFSA novel food pathways:Streamlined strain approval mechanisms are accelerating Saccharomyces cerevisiae derivative launches in fortified foods.
- Nutraceutical pull:Supplement manufacturers are expanding instant yeast procurement for B-vitamin fortification matrices.
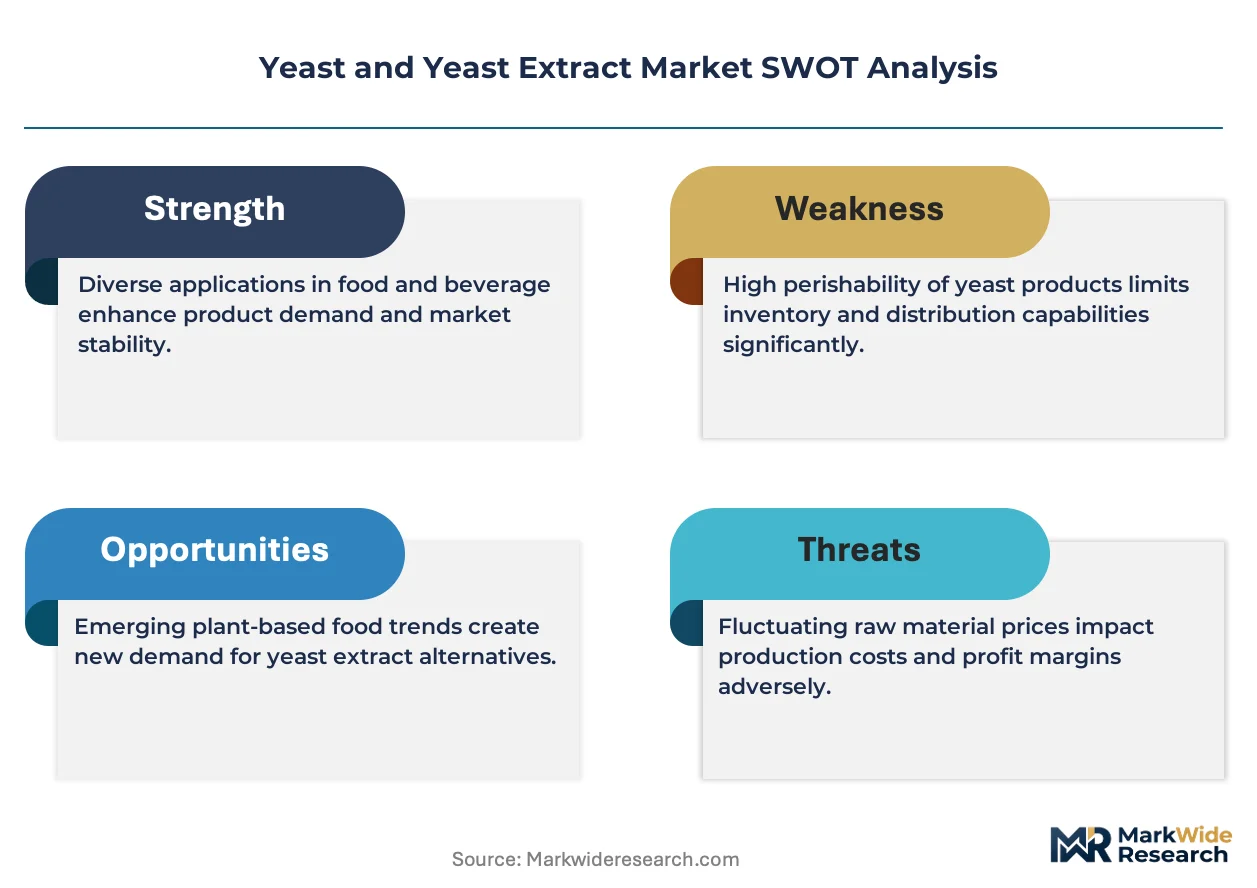
Market Restraints
- Input cost volatility:Molasses pricing swings tied to sugar beet harvest variability compress margin predictability for fermentation operators.
- Supply concentration risk:European extract capacity clusters heavily in German Rhineland biotechnology corridors, creating single-point vulnerability.
- Substitution pressure:Hydrolyzed vegetable proteins and mushroom-derived umami compounds are capturing clean-label savory share.
Strategic Opportunities
- Asia-Pacific capacity expansion:India's FSSAI regulatory harmonization is opening import pathways for standardized yeast extract grades.
- Precision fermentation convergence:Cell-culture technology hybridization with traditional autolysis is enabling novel bioactive peptide streams.
- EU organic processing tailwinds:Certified organic substrate sourcing mandates are rewarding early certification investments with premium positioning.
Industry Challenges
- Strain banking capex intensity:Cryopreservation infrastructure and genomic characterization facilities demand sustained capital deployment.
- Documentation timeline compression:FDA GRAS self-affirmation dossier preparation is extending product launch cycles for new entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Yeast and Yeast Extract Market |
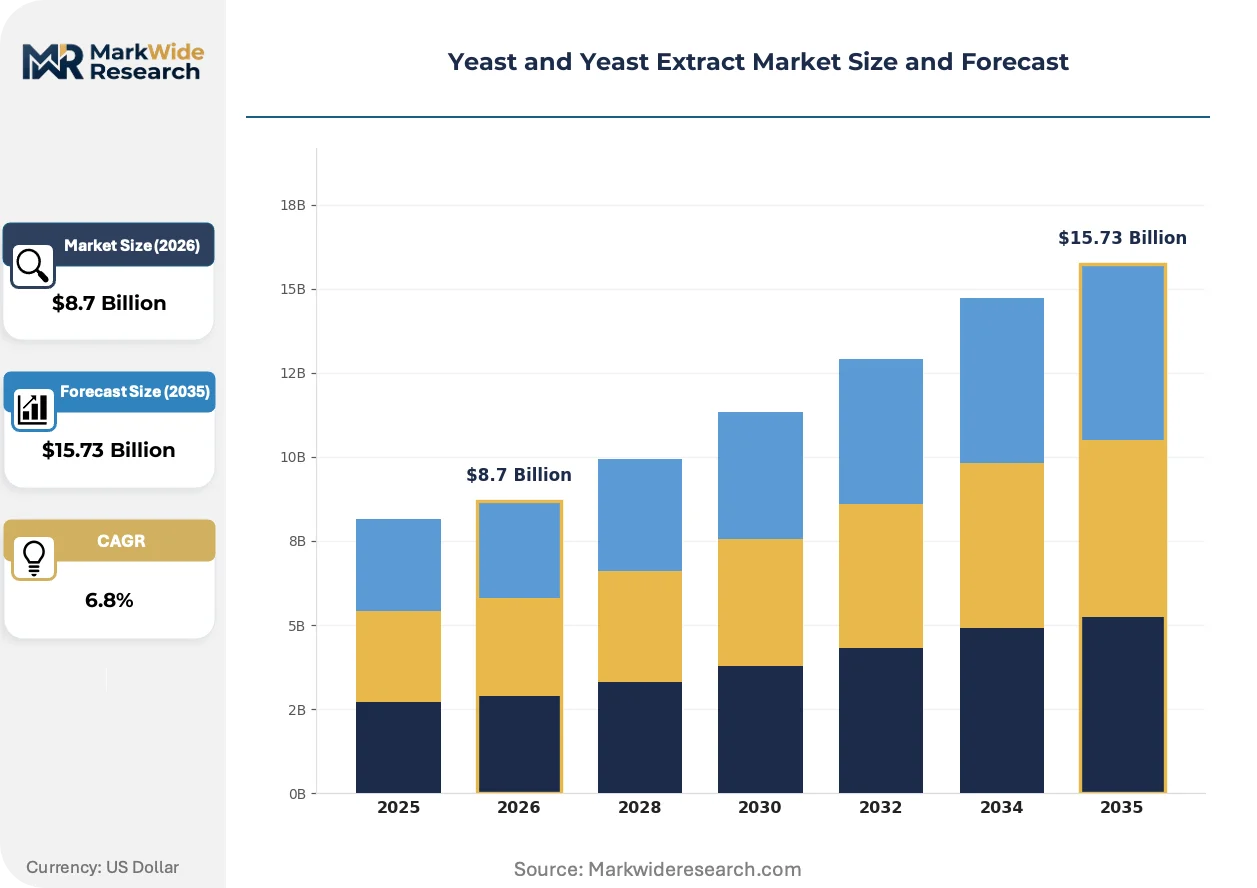
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Baker's Yeast, Brewer's Yeast, Nutritional Yeast, Instant Yeast Application: Baking, Brewing, Fermentation, Food Preservation End User: Food Industry, Beverage Industry, Nutraceuticals, Animal Feed Form: Dry, Liquid, Paste, Granulated |
| Companies Covered | Lesaffre Group, Angel Yeast Co., Ltd., Lallemand Inc., Kerry Group plc, Koninklijke DSM N.V., Associated British Foods plc, Biorigin, Ohly, Synergy Flavors, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Yeast and Yeast Extract Market Strategic Shifts
Clean-label disclosure requirements and precision fermentation advances are restructuring how yeast derivatives reach food and nutraceutical formulators.
Continuous fermentation systems are overtaking batch processing in high-volume baker's yeast production. Industrial bakeries and contract manufacturers are adopting these systems to reduce downtime and improve metabolic yield consistency. This shift is compressing capital recovery timelines for facility upgrades while raising technical barriers for smaller operators.
EFSA's evolving strain-level transparency requirements are mandating full genomic disclosure for novel Saccharomyces derivatives. Food manufacturers must now document substrate provenance and processing aids across their supply chains. European savory formulation houses are responding by consolidating supplier relationships with vertically integrated fermentation partners.
Direct procurement from fermentation facilities is displacing traditional ingredient distributor networks among large-scale nutraceutical compounders. Volume buyers are negotiating captive supply arrangements that bypass regional wholesale channels. This pattern is most visible in North American supplement manufacturing corridors where buyer concentration enables contract restructuring.
Yeast and Yeast Extract Market Segmentation
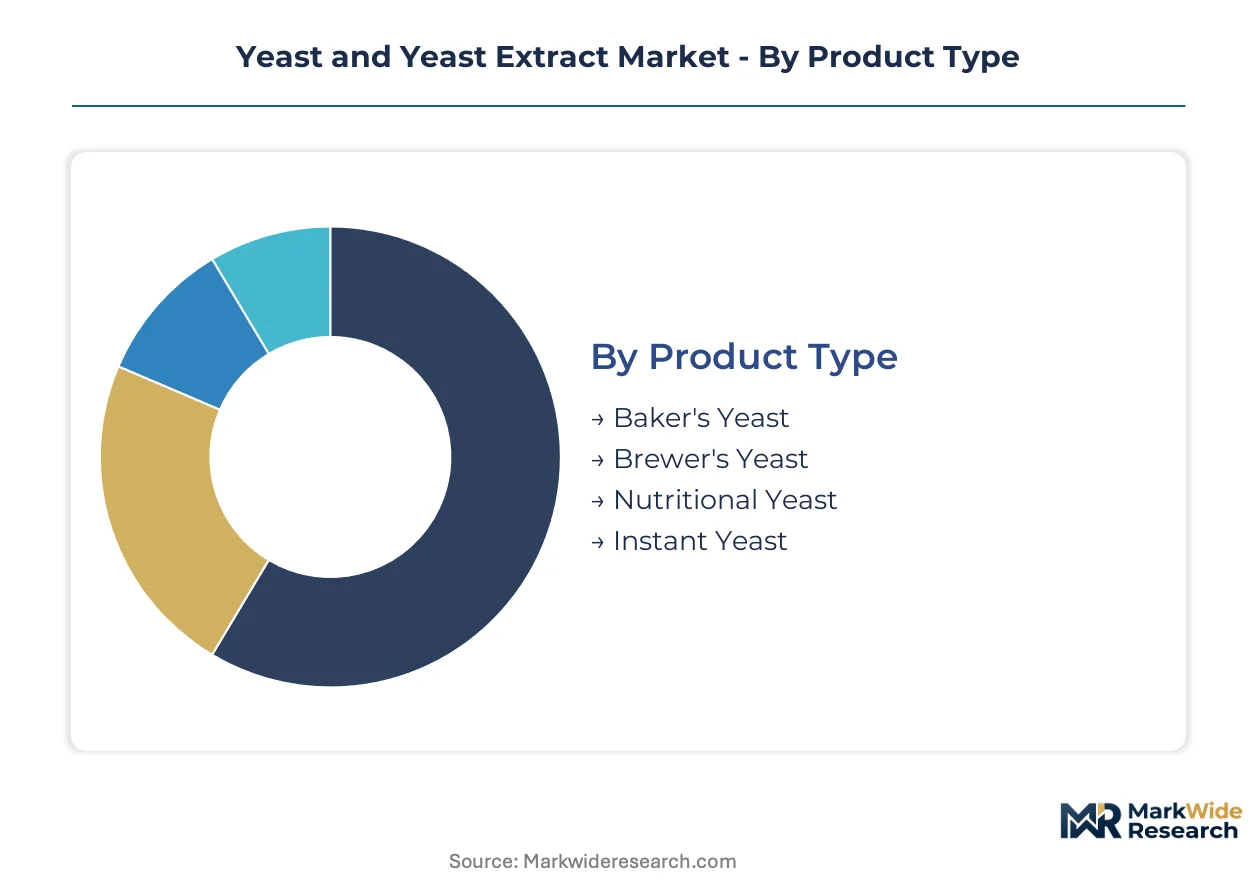
Segmentation in the Yeast and Yeast Extract Market reveals distinct capital requirements and margin profiles across product categories. Fermentation infrastructure investments vary dramatically between commodity baker's yeast and specialized nutraceutical derivatives.
Product Type:
Baker's yeast demands the heaviest upfront fermentation capacity, while precision-cultured strains for nutraceutical applications command premium equipment specifications.
- Baker's Yeast:Live Saccharomyces cerevisiae cultures propagated on molasses substrates for leavening applications. European industrial bakeries in Germany and France channel procurement through long-term supply contracts with Rhineland fermentation clusters. EFSA substrate traceability mandates are forcing documentation upgrades across legacy facilities.
- Nutritional Yeast:Inactive dried yeast with elevated B-vitamin and protein content for clean-label fortification. Supplement manufacturers in North America are pulling instant yeast derivatives for vegan protein matrices. FDA GRAS self-affirmation pathways govern strain approval timelines for new entrants.
- Brewer's Yeast:Spent fermentation biomass recovered from beer production with residual bitter compounds. Distinct flavor profile limits application scope to animal feed and select nutraceutical formulations.
- Instant Yeast:Low-moisture rapid-acting dried cultures with extended shelf stability. Home baking resurgence and artisanal bakery expansion are driving retail-format demand.
Most installed capacity flows through Baker's Yeast. Expansion is steepest in Nutritional Yeast.
Application:
Application segmentation tracks how fermentation outputs align with distinct processing economics and regulatory exposure across food manufacturing verticals.
- Baking:Leavening applications in bread, pastry, and fermented dough systems. Industrial bakeries in Germany and Italy consolidate procurement through vertically integrated yeast suppliers to secure margin control.
- Brewing:Primary fermentation for ethanol production and flavor development in beer manufacturing. Craft brewery proliferation in the United States is fragmenting demand across smaller batch sizes.
- Fermentation:Industrial biotechnology applications including bioethanol, biochemical precursors, and enzyme production. Capital intensity here exceeds food-grade specifications by an order of magnitude.
- Food Preservation:Natural antimicrobial applications leveraging yeast cell wall derivatives. Clean-label reformulation pressure is displacing synthetic preservatives in European savory applications.
Volume concentrates in Baking. Steepest expansion trajectory belongs to Fermentation biotechnology applications.
End User:
End-user segmentation exposes divergent procurement patterns between price-sensitive commodity buyers and specification-driven nutraceutical compounders.
- Food Industry:Industrial bakeries, savory formulation houses, and processed food manufacturers. German and French procurement clusters dominate European demand with stringent EFSA disclosure requirements.
- Nutraceuticals:Dietary supplement manufacturers and functional food formulators. Direct procurement from fermentation facilities is displacing traditional distributor networks among large-scale North American compounders.
- Beverage Industry:Breweries, wineries, and distilled spirits producers. Craft segment fragmentation is compressing order sizes while expanding SKU complexity.
- Animal Feed:Livestock nutrition and aquaculture feed formulations. Brewer's yeast byproduct streams compete with dedicated feed-grade production on cost.
Food Industry channels the majority of volume. Nutraceuticals is climbing the fastest on margin expansion.
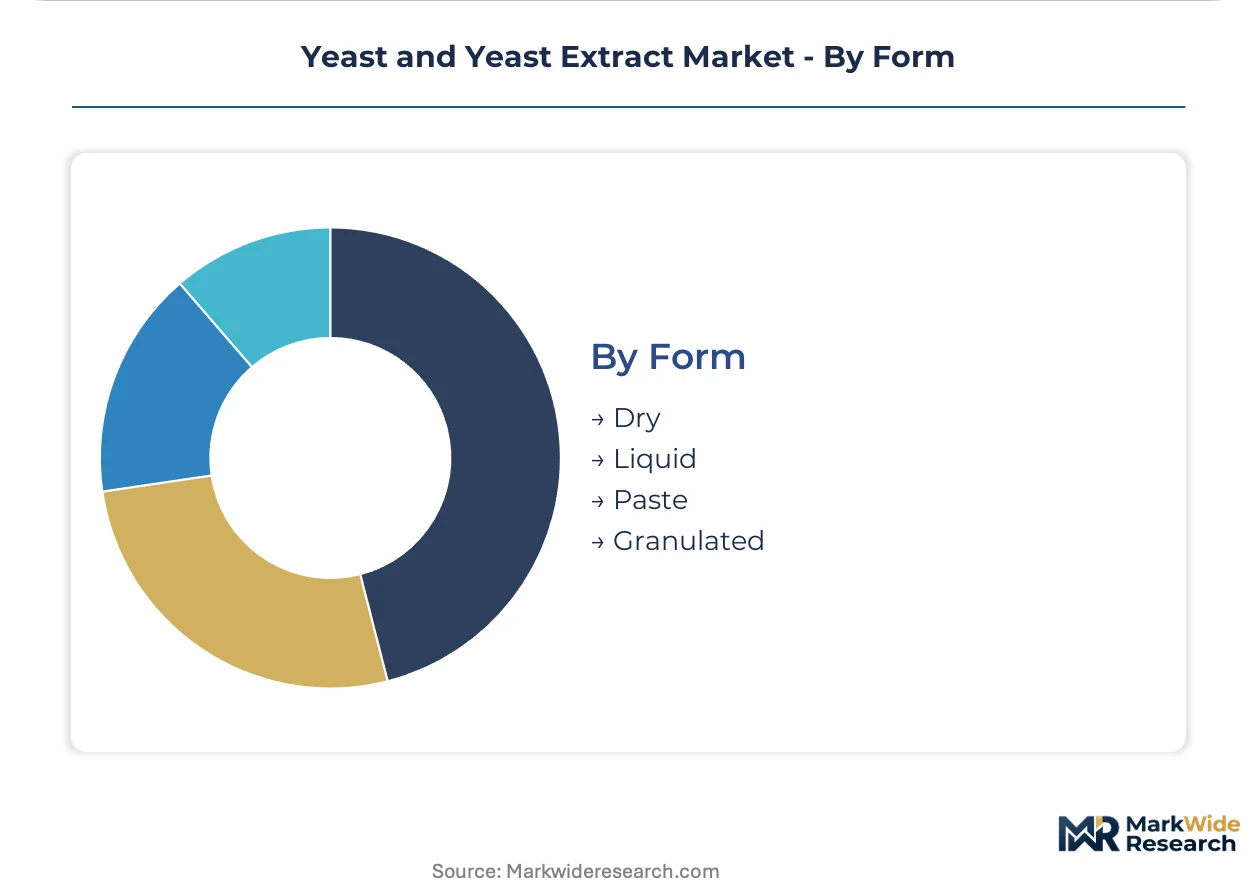
Form:
Form factor segmentation reflects supply chain configuration differences between bulk liquid logistics and shelf-stable dried formats.
- Dry:Dehydrated yeast cultures with extended ambient stability for distributed supply chains. Retail and foodservice channels favor this format for inventory flexibility.
- Liquid:Cream yeast and compressed fresh cultures for high-volume industrial baking. Proximity to fermentation facilities determines economic viability given cold-chain requirements.
- Paste:Intermediate moisture content formats for specific industrial processing applications. Limited adoption outside specialized European bakery traditions.
- Granulated:Free-flowing dried particles optimized for automated dispensing systems. Industrial scale baking operations in Germany favor this format for process consistency.
Dry forms dominate installed capacity. Granulated formats are gaining share fastest on automation adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates more fermentation biotechnology capacity than any other European country, while China operates the largest molasses-based production complexes outside Europe. India is emerging as a regulatory harmonization beneficiary for standardized extract imports.
Germany
Industrial bakeries in the Rhineland corridor drive sustained procurement of baker's yeast and specialty extracts. EFSA substrate traceability mandates are forcing documentation upgrades across legacy fermentation facilities. The Mannheim-Ludwigshafen biotechnology cluster anchors European supply chain consolidation through vertically integrated production networks.
China
Molasses refining infrastructure in Shandong and Hubei provinces supports cost-competitive baker's yeast output for domestic and export markets. SAMR food additive regulations govern strain approval timelines and labeling requirements for yeast-derived ingredients. Zhengzhou-based fermentation complexes are expanding capacity to serve Asia-Pacific nutraceutical formulators.
United States
Supplement manufacturers in North Carolina and Utah are pulling instant yeast derivatives for vegan protein and B-vitamin fortification matrices. FDA GRAS self-affirmation pathways extend product launch cycles for new extract entrants. Direct procurement from fermentation facilities is displacing traditional distributor networks among large-scale compounders.
India
Domestic bakery sector expansion in Maharashtra and Karnataka is driving volume demand for compressed fresh yeast formats. FSSAI regulatory harmonization is opening import pathways for standardized yeast extract grades from European suppliers. Gujarat-based food processing corridors are developing captive fermentation partnerships to secure supply continuity.
France
Artisanal bakery traditions in Île-de-France and Auvergne-Rhône-Alpes sustain premium positioning for fresh cream yeast. EU organic processing standards reward early certification investments with price premiums in clean-label savory applications. Lesaffre Group's vertical integration from fermentation to finished extract anchors national supply security.
Yeast and Yeast Extract Market Competitive Environment
European producers anchor one tier through vertically integrated fermentation-to-extract operations; Asia-Pacific specialists hold scale-driven positions in commodity baker's yeast. The vendor base stratifies across three archetypes: multinational fermentation conglomerates with strain banking capabilities, regional molasses-based volume producers, and niche extract refiners serving clean-label savory formulators. Dominant competitive moves include backward integration into captive substrate sourcing and capacity expansion in precision fermentation infrastructure.
Within the multinational tier, Lesaffre Group and Lallemand Inc. exemplify vertically integrated archetypes that control margin capture across fermentation and finished extract stages. Angel Yeast Co., Ltd. represents the Asia-Pacific scale specialist position, anchoring regional supply through large-scale production complexes. These three entities collectively illustrate how geographic origin and structural integration determine competitive positioning in procurement negotiations with industrial bakeries and nutraceutical compounders.
| Leading Market Players |
|---|
| Lesaffre Group |
| Angel Yeast Co., Ltd. |
| Lallemand Inc. |
| Kerry Group plc |
| Koninklijke DSM N.V. |
| Associated British Foods plc |
| Biorigin |
| Ohly |
| Synergy Flavors, Inc. |
| Others |
Value Chain & Pricing Dynamics
Molasses price volatility on global sugar markets cascades through fermentation economics into three distinct procurement tiers. Industrial bakeries in Germany and France negotiate long-term offtake contracts that buffer spot-market swings, while nutraceutical compounders absorb premium pricing for strain-documented extracts under EFSA transparency mandates.
Pricing Analysis
Distributor margin compression is reshaping how yeast derivatives reach end-users, with direct procurement from Rhineland fermentation clusters displacing traditional wholesale channels for volume buyers. Three-tier pricing structure across premium, standard, and economy levels separates certified organic extracts from conventional food-grade material and commodity baker's yeast. Pricing pressure stems from hydrolyzed vegetable proteins and mushroom-derived umami compounds capturing clean-label savory share. Industrial bakeries exhibit highest price sensitivity due to thin margins on leavening applications, while nutraceutical compounders accept premium positioning for B-vitamin fortification matrices.
Supply Chain Analysis
EU organic processing standards and FSSAI import harmonization in India are reshaping sourcing decisions for substrate-provenance documentation. Geographic supply concentrates in Germany, China, and France, with Rhineland biotechnology corridors anchoring European extract capacity and Shandong province molasses refining feeding Asia-Pacific volume. Raw material dependencies center on sugar beet molasses, carbohydrate feedstock substrates, and cryopreservation infrastructure for strain banking. Single-source vulnerability runs through German fermentation clusters given EFSA disclosure mandate concentration. Distribution runs through vertically integrated producer networks for industrial accounts and specialized ingredient distributors for mid-scale formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Yeast and yeast extract procurement is a late-cycle quality story as EFSA strain-level transparency requirements and FDA GRAS documentation burdens filter out undercapitalized suppliers. Premium specification demand from nutraceutical compounders is accelerating margin capture for incumbents with certification infrastructure already deployed.
For Market Incumbents: Anchor strain banking capabilities and genomic characterization facilities as defensive moats against precision fermentation entrants. Deepen backward integration into captive molasses sourcing to buffer sugar beet harvest volatility. Prioritize EFSA organic certification maintenance to sustain premium positioning as EU processing standards tighten disclosure requirements for substrate provenance. For New Entrants and Emerging Players: Contract manufacturers serving North American supplement corridors offer the most penetrable channel for instant yeast derivatives bypassing legacy distributor networks. Target India's FSSAI-harmonized import pathways for standardized extract grades before domestic Gujarat fermentation partnerships mature. Lead with precision fermentation hybridization narratives to differentiate from conventional autolysis incumbents in clean-label savory pitches. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale extract refiners possessing EFSA documentation infrastructure and captive organic substrate sourcing. Five-to-ten year viability hinges on consolidation into vertically integrated fermentation-to-extract platforms capable of serving both food and nutraceutical procurement clusters. Watch for FDA GRAS self-affirmation timeline compression as signal that documentation-capable assets are commanding scarcity premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Substrate Sourcing | Molasses supply security buffers sugar beet harvest variability for Rhineland fermentation operators. |
| Precision Fermentation Infrastructure Investment | Cell-culture hybridization enables novel bioactive peptide streams for nutraceutical fortification matrices. |
| EFSA Organic Certification Program | Early certification investments capture premium positioning under tightening EU processing standards. |
| Direct Procurement Channel Development | Bypassing distributor networks secures margin control with large-scale North American compounders. |
| Strain Banking Capacity Expansion | Cryopreservation infrastructure defends against substitution pressure from mushroom-derived umami compounds. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with fermentation plant managers, procurement leads at industrial bakeries, regulatory affairs specialists navigating EFSA novel food pathways, and nutraceutical formulation scientists with secondary validation against SAMR food additive filings, FSSAI import harmonization circulars, EFSA transparency guidance documents, and customs trade data for molasses-derived ingredient flows. Bottom-up capacity assessments and top-down demand modeling were cross-checked for convergence.
Segment-weighting approaches applied differential growth assumptions across product type, application, end user, and form factor dimensions, with explicit modeling of fermentation biotechnology convergence and clean-label reformulation trajectories. CAGRs were derived from installed capacity expansion timelines, regulatory approval pathway velocities, and procurement pattern shifts documented across the analysis window. Molasses price elasticity and strain banking capex intensity were incorporated as industry-specific forecast sensitivities.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EFSA strain disclosure mandate evolution, precision fermentation cost curves, and substitution dynamics from alternative umami sources. Forecasts reflect documented assumptions about regulatory timeline stability and substrate supply continuity. A small set of triggers—FDA GRAS affirmation acceleration, FSSAI import standard revisions, and German biotechnology cluster disruption—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Cold-Pressed Coconut Oil Market
Ingredients
Cacao Bean Market
Ingredients
Edible Halal Gelatin Market
Ingredients
Mediterranean Marine Ingredients for Pet Health Market
Ingredients
Europe Vegetable Oil Market
Ingredients
China Beer Adjuncts Market
Ingredients
Collagen Casings Market
Ingredients
Food Colors Market
Ingredients
Siraitia Grosvenorii Extract Market
Ingredients
Oyster Shell Powder Market
Ingredients
All Purpose Flour Market
Ingredients
Soy Protein Hydrolysate Market
Ingredients
Almond Ingredients Market
Ingredients
Europe Edible Oil Market
Ingredients
Refined Coconut Oil Market
Ingredients
Omega 9 Market