
 Low Fat Oil Market | 2026-2036
Low Fat Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Low Fat Oil Market Analytics
Food chemist and lipid technologist talent is rotating toward enzymatic interesterification and fractionation capabilities as brands race to lower saturated fat without sacrificing oxidative stability. Cargill Incorporated leverages its integrated oilseed processing network to secure consistent feedstock for low-linolenic and high-oleic varieties. Wilmar International Ltd anchors Southeast Asian palm oil fractionation capacity while competing in European specialty fat markets through controlled crystallization expertise.
Low fat oil comprises refined vegetable oils engineered through blending, fractionation, or enzymatic modification to deliver reduced total fat or saturated fat content per serving while maintaining functional properties such as smoke point above 200°C and oxidative stability indices suitable for extended frying cycles. Olive oil and canola oil dominate premium positioning in retail channels where monounsaturated fat claims command shelf space, while sunflower oil extends volume in food manufacturing applications where neutral flavor and cost efficiency matter. The baking and margarine segments concentrate margin pools as these applications require precise solid fat content curves that only advanced fractionation achieves.
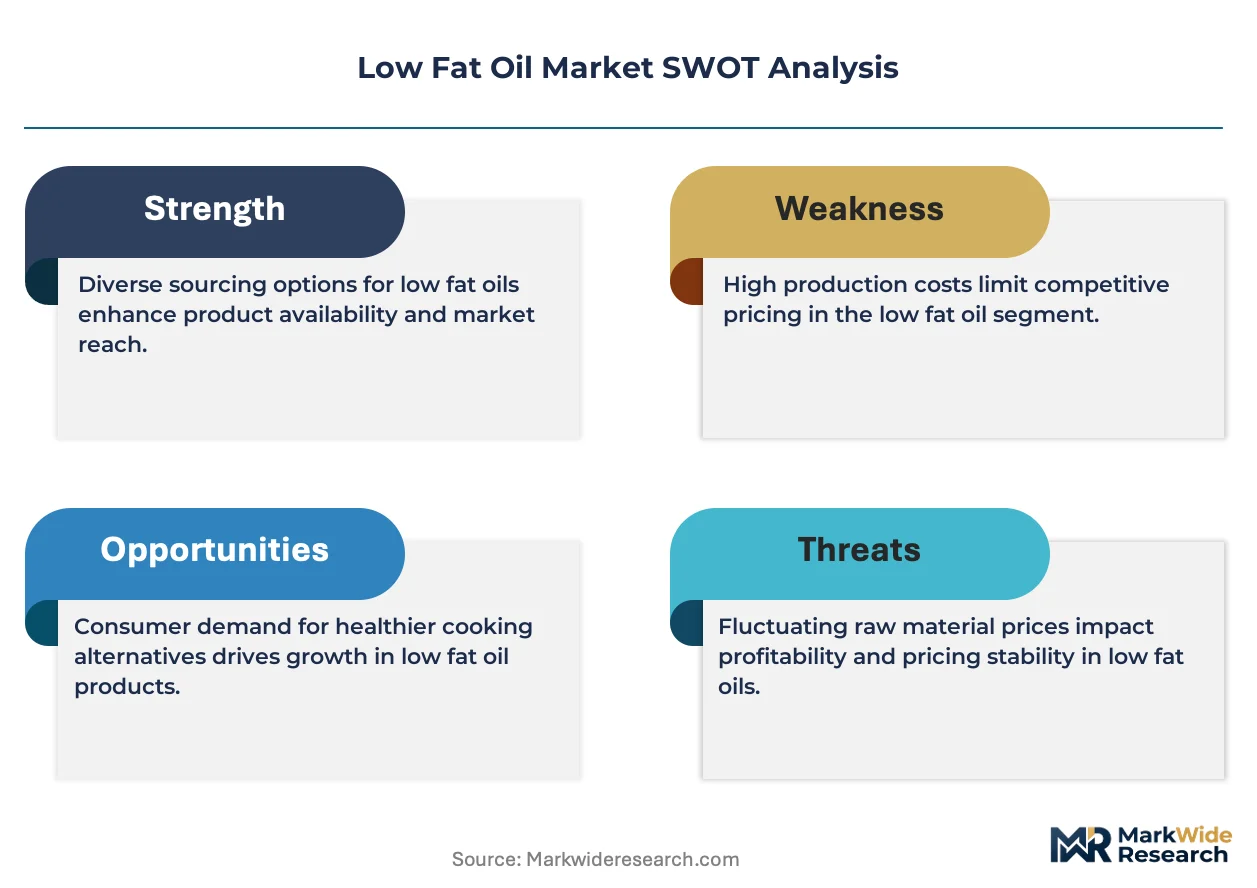
FDA nutrition labeling rules and the USDA Dietary Guidelines shape American product formulation thresholds, while EU REACH compliance and EFSA health claim authorization determine which fat-modification technologies gain market access across Europe. India's FSSAI standards for edible oil fortification and labeling create additional compliance layers for exporters targeting food manufacturers in Mumbai and Delhi. Stakeholders must monitor evolving trans-fat elimination deadlines and novel food ingredient classifications that could reclassify enzymatically modified oils ahead of reformulation cycles.
Market Dynamics
Enzymatic interesterification is compressing reformulation timelines as bakery and margarine producers race to eliminate trans fats while preserving solid fat functionality. This single process shift is redrawing competitive boundaries between integrated oilseed processors and specialty fat blenders.
Growth Catalysts
- EU F-Gas Regulation:Refrigeration-dependent fractionation facilities face phase-down mandates, accelerating investment in enzymatic processes that operate at ambient temperatures.
- Bakery segment reformulation:Industrial bakeries in Germany and France are retrofitting production lines to handle high-oleic sunflower and low-linolenic canola bases.
- Enzymatic modification:Lipase-catalyzed restructuring delivers precise solid fat content curves without hydrogenation, opening clean-label positioning in premium retail channels.
Market Restraints
- Palm oil feedstock concentration:Southeast Asian crude palm oil supply volatility transmits directly into European fractionation margins.
- EFSA novel food classification:Enzymatically modified oils face extended safety evaluation timelines, delaying market entry for reformulated products.
- Olive oil substitution pressure:Extra virgin olive oil's entrenched health halo limits price elasticity for blended low-fat alternatives in Mediterranean retail markets.
Strategic Opportunities
- India FSSAI fortification mandates:Edible oil blending regulations create entry points for micronutrient-enhanced low-fat formulations targeting food manufacturers in Mumbai and Delhi.
- Controlled crystallization:Convergence of ultrasound-assisted processing and membrane filtration enables bespoke fat structuring for plant-based meat analogues.
- Direct-to-manufacturer channels:Bulk tanker delivery bypassing traditional distributor networks captures margin from institutional foodservice accounts.
Industry Challenges
- Fractionation operator scarcity:Crystallization kinetics expertise and enzymatic process control skills command premium compensation in European talent markets.
- REACH registration timelines:New chemical entities in modified oil compositions trigger multi-year dossier preparation before commercial deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low Fat Oil Market |
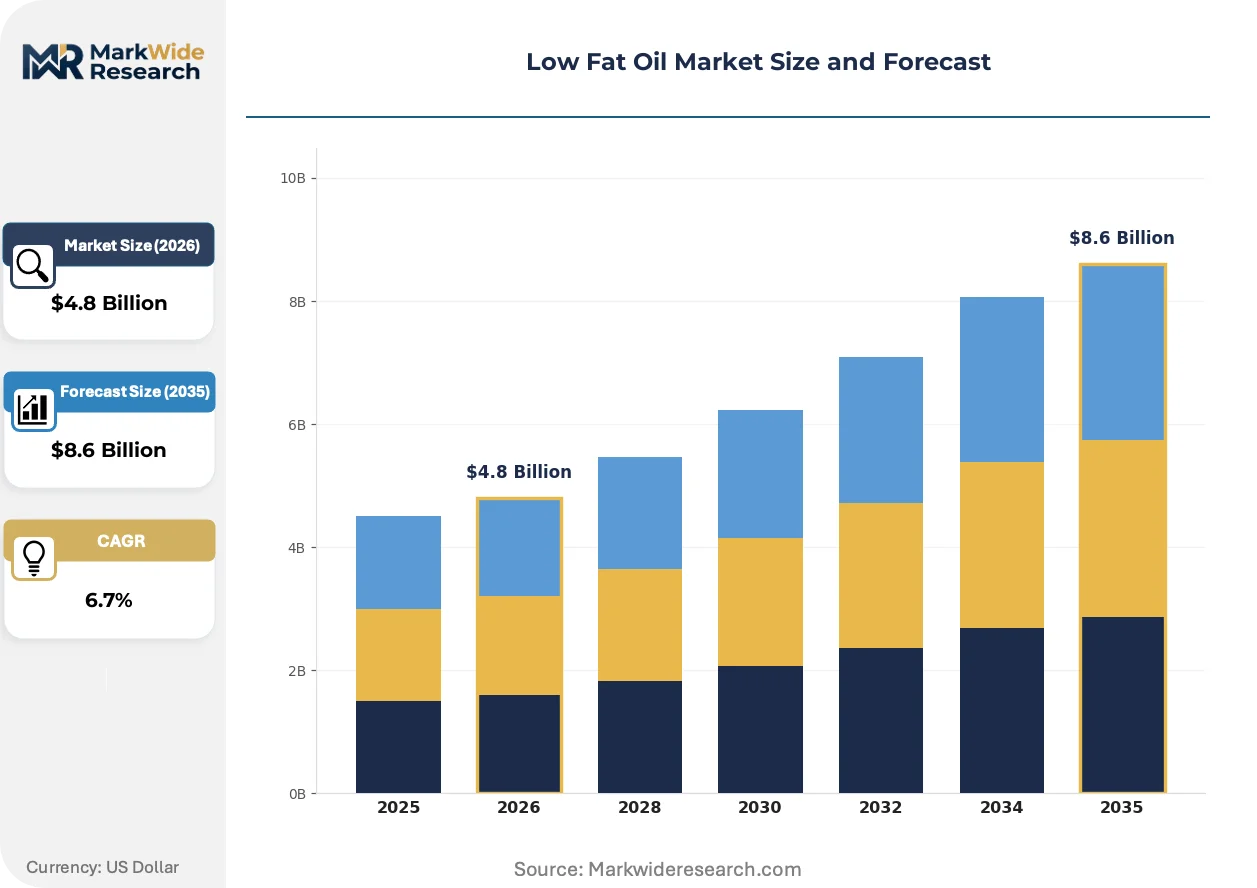
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Olive Oil, Coconut Oil, Sunflower Oil, Canola Oil Application: Cooking, Baking, Dressings, Margarine Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Wholesale End User: Households, Restaurants, Food Manufacturers, Catering Services |
| Companies Covered | Archer Daniels Midland Company, Wilmar International Ltd, Cargill Incorporated, Bunge Limited, Fuji Oil Holdings Inc., Olam Group, AAK AB, Musim Mas Holdings, IOI Corporation Berhad, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low Fat Oil Market Evolving Landscape
Process intensification and regulatory alignment are compressing product development cycles. Three forces are restructuring how low-fat oils are engineered, certified, and procured.
Continuous enzymatic interesterification systems are displacing batch hydrogenation in European margarine plants. Unilever and Bunge have retrofitted facilities in the Netherlands and Germany to run immobilized lipase columns. This hardware shift is displacing nickel catalyst infrastructure and enabling same-day product changeovers between spread and shortening formulations.
EFSA health claim authorization pathways are tightening evidentiary standards for saturated fat reduction claims. Manufacturers must now submit human intervention studies rather than fatty acid compositional data alone. The bakery segment is most affected, with reformulated puff pastry margarines requiring new clinical substantiation before premium positioning.
Long-term offtake contracting is replacing spot purchasing among German and French industrial bakery groups. Buyers are locking in eighteen-month supply agreements with specified oxidative stability indices and solid fat content tolerances. This pattern is most visible in the frozen dough sector, where consistency failures halt production lines.
Low Fat Oil Market Segmentation
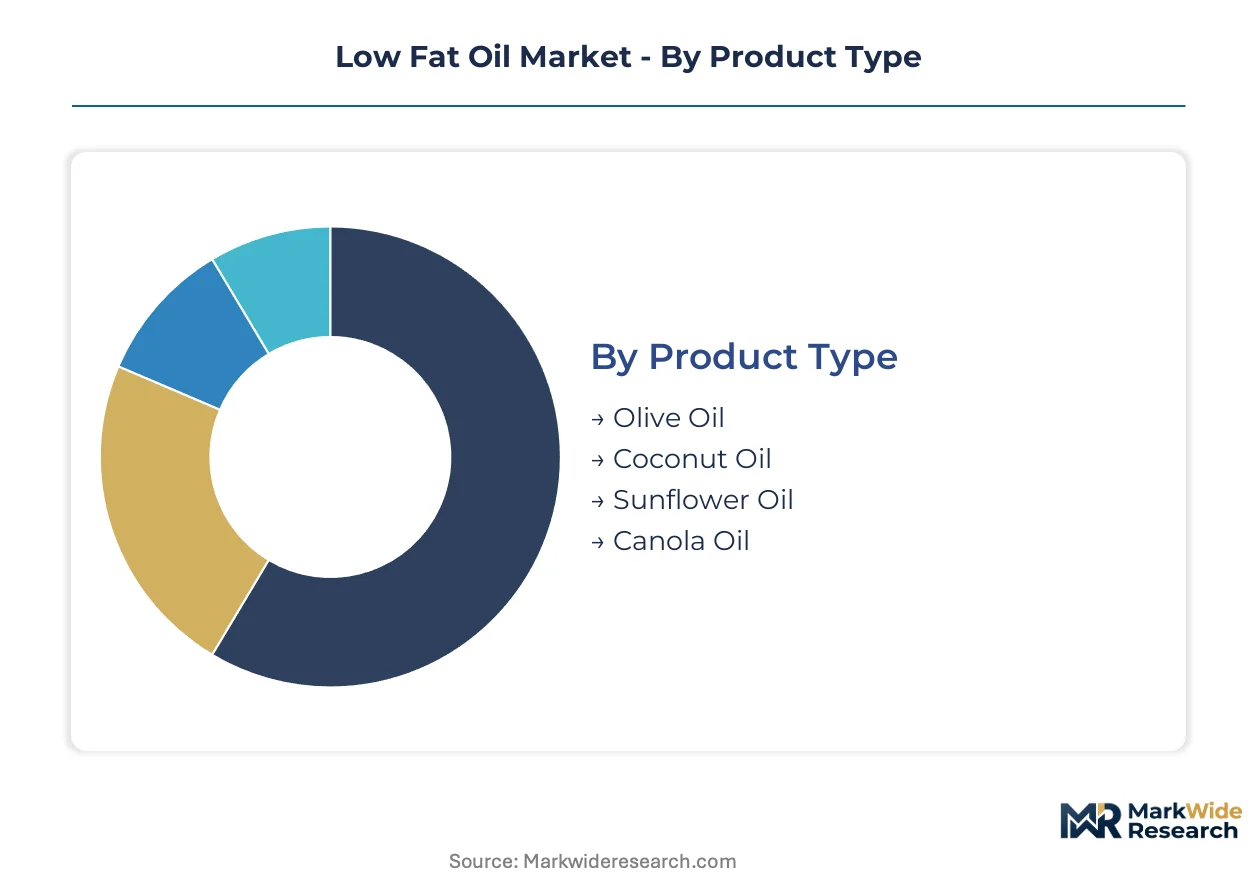
Low fat oil segmentation reveals how formulation chemistry, procurement scale, and channel economics fragment demand across distinct technical specifications and buyer workflows. Understanding these divides clarifies where enzymatic modification investments concentrate versus where commodity blending suffices.
Product Type:
EFSA health claim authorization and FDA nutrition labeling rules create divergent compliance burdens across oil varieties, shaping which grades command premium positioning in regulated markets.
- Olive Oil:Extra virgin and refined grades deliver high monounsaturated fat content with oxidative stability indices above 20 hours. German and French retail chains prioritize EFSA-substantiated health claims for premium shelf placement, though Mediterranean consumer loyalty to traditional extra virgin limits blended low-fat variant penetration.
- Canola Oil:Low-linolenic acid varieties engineered through seed breeding achieve smoke points exceeding 230°C while maintaining neutral flavor profiles. North American food manufacturers specify high-oleic canola for extended frying cycles in institutional foodservice accounts.
- Sunflower Oil:High-oleic hybrids dominate industrial bakery applications in Germany where solid fat content curves must align with frozen dough processing windows.
- Coconut Oil:Fractionated MCT oils serve niche functional food positioning despite saturated fat content challenges under EU nutrition labeling requirements.
Olive oil handles the majority of throughput; canola oil is the fastest mover on share.
Application:
Functional requirements around solid fat content, smoke point, and oxidative stability stratify demand by end-use, with baking and margarine commanding the most sophisticated fractionation capabilities.
- Baking:Industrial puff pastry and laminated dough production requires precise solid fat content curves between 20°C and 35°C that only enzymatic interesterification achieves. German bakery groups are retrofitting production lines to handle high-oleic sunflower and low-linolenic canola bases under tightened trans-fat elimination deadlines.
- Margarine:Spread and shortening formulations demand controlled crystallization kinetics for mouthfeel and shelf stability. Unilever and Bunge have retrofitted Dutch and German facilities with immobilized lipase columns displacing nickel catalyst infrastructure.
- Cooking:Extended frying cycles in foodservice drive demand for high-oleic oils with oxidative stability indices specified in eighteen-month supply agreements.
- Dressings:Cold-application formulations prioritize flavor neutrality and emulsion stability over thermal performance, opening entry points for blended low-fat variants.
Baking commands the deepest technical requirements; margarine is expanding most quickly as trans-fat elimination deadlines compress reformulation timelines.
Distribution Channel:
Procurement scale and buyer technical sophistication determine channel economics, with bulk tanker delivery bypassing traditional distributor networks in institutional accounts.
- Wholesale:Direct-to-manufacturer bulk supply captures margin from food manufacturers and catering services specifying oxidative stability indices and solid fat content tolerances in long-term offtake contracts. German frozen dough sector buyers lock in eighteen-month agreements with defined performance parameters.
- Supermarkets:Retail shelf space allocation follows EFSA health claim authorization and clean-label positioning, with monounsaturated fat claims commanding premium placement in French and German chains.
- Online Retail:Direct-to-consumer channels concentrate in premium positioning where enzymatic modification and fractionation credentials support price premiums.
- Specialty Stores:Mediterranean retail markets favor traditional extra virgin olive oil, limiting blended low-fat alternative penetration despite reformulation investment.
Wholesale channels move the largest volumes; online retail is gaining share fastest as clean-label credentials support direct consumer education.
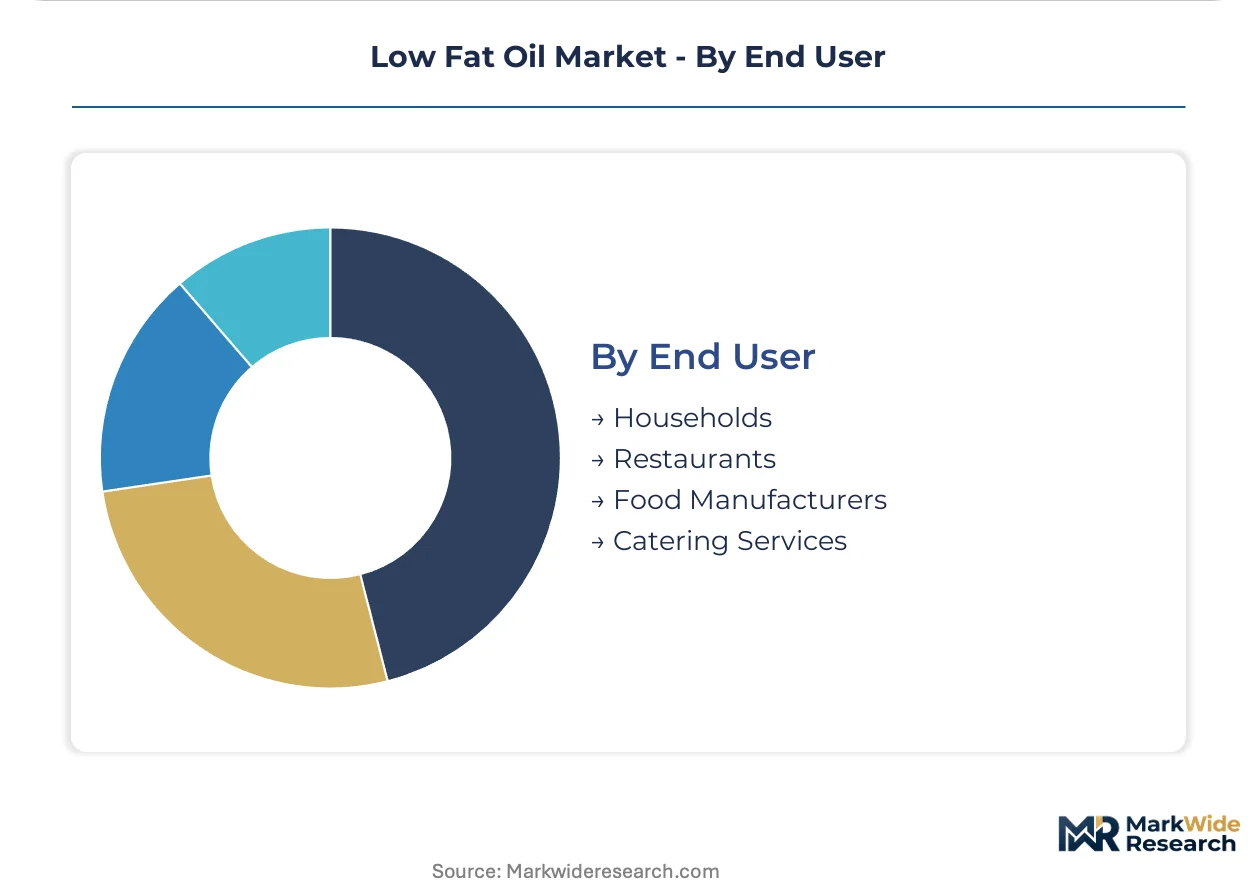
End User:
Technical specification depth and procurement scale fragment end-user economics, with food manufacturers demanding certified oxidative stability while households respond to health claim positioning.
- Food Manufacturers:Industrial bakery and margarine producers specify enzymatically modified oils with documented solid fat content curves and REACH-compliant chemical dossiers. Mumbai and Delhi operations face additional FSSAI fortification and labeling compliance layers.
- Restaurants:Institutional foodservice accounts prioritize smoke point performance and supply consistency over health claim substantiation, favoring high-oleic canola and sunflower in extended frying applications.
- Households:Retail purchasing responds to EFSA-authorized health claims and clean-label positioning, with German and French consumers showing strongest engagement for reformulated low-fat variants.
- Catering Services:Volume procurement through wholesale channels emphasizes cost efficiency and supply reliability over technical differentiation.
Food manufacturers represent the most demanding specification environment; restaurants are climbing the fastest as institutional foodservice scales direct procurement relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German bakery and margarine producers command premium pricing power through enzymatic fractionation expertise, while Indian food manufacturers absorb cost volatility from palm oil feedstock exposure. This asymmetry shapes regional investment patterns across reformulation cycles.
Germany
Industrial puff pastry and laminated dough producers in Lower Saxony and North Rhine-Westphalia drive enzymatic interesterification adoption. The EU F-Gas Regulation accelerates ambient-temperature process investment. Unilever and Bunge facilities in the Netherlands and Germany retrofit with immobilized lipase columns.
United States
North American food manufacturers specify high-oleic canola for extended frying cycles in institutional foodservice. FDA nutrition labeling rules and USDA Dietary Guidelines shape formulation thresholds. Midwest oilseed processing clusters supply consistent low-linolenic feedstock to reformulation programs.
India
Mumbai and Delhi food manufacturers face FSSAI fortification mandates and labeling compliance layers for edible oil blending. Bakery and snack producers retrofit production lines for high-oleic sunflower bases. Palm oil price volatility transmits directly into margin pressure for fractionation-dependent operations.
France
French retail chains prioritize EFSA-substantiated health claims for premium shelf placement of monounsaturated fat products. Industrial bakeries in the Île-de-France region invest in solid fat content curve precision for frozen dough applications. Clean-label positioning commands price premiums in Paris metro distribution.
Netherlands
Dutch margarine plants pioneer continuous enzymatic interesterification systems displacing batch hydrogenation. Rotterdam-area fractionation facilities navigate EU REACH registration timelines for modified oil compositions. The cluster serves as a technology export hub for bakery segment reformulation across Northern Europe.
Low Fat Oil Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes in the low fat oil market. Integrated oilseed processors with captive crushing and fractionation assets compete against specialty fat blenders with enzymatic modification expertise. Three archetypes dominate: upstream-integrated agricultural conglomerates, enzymatic technology specialists, and regional palm oil fractionators. Competitive moves concentrate on enzymatic process licensing agreements and long-term offtake contracting with industrial bakery groups.
Within the integrated processor tier, Cargill Incorporated and Archer Daniels Midland Company exemplify upstream control over low-linolenic and high-oleic seed varieties. Wilmar International Ltd anchors Southeast Asian palm oil fractionation capacity while competing in European specialty fat markets. Bunge Limited occupies a position between agricultural origination and enzymatic modification technology deployment.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Wilmar International Ltd |
| Cargill Incorporated |
| Bunge Limited |
| Fuji Oil Holdings Inc. |
| Olam Group |
| AAK AB |
| Musim Mas Holdings |
| IOI Corporation Berhad |
| Others |
Value Network & Pricing Analysis
Eighteen-month offtake contracts with specified oxidative stability indices concentrate pricing power among German frozen dough producers while compressing spot-market margins for fractionation-dependent suppliers. This lead-time structure rewards buyers who lock in volume commitments with enzymatic technology specialists, leaving commodity blenders exposed to palm oil feedstock volatility.
Pricing Analysis
The customization-premium spread separates enzymatically interesterified bakery fats from standard blended oils by roughly the cost of REACH compliance documentation and solid fat content certification. Long-term offtake contracting dominates industrial procurement, with price differentiation driven by oxidative stability guarantees and crystallization kinetics precision. Pricing pressure intensifies in the commodity blending tier as Southeast Asian palm oil supply volatility transmits directly into European margin compression. Food manufacturers with frozen dough operations show least price sensitivity due to production line consistency requirements, while institutional foodservice accounts prioritize cost efficiency over technical specification depth.
Supply Chain Analysis
Strategic stockpiling of high-oleic seed varieties prevails among North American processors, while European buyers favor just-in-time enzymatic modification to minimize refrigeration-dependent inventory exposure under EU F-Gas Regulation phase-down mandates. Geographic supply concentration centers on Malaysia and Indonesia for crude palm oil fractionation feedstock, with Ukraine and Argentina anchoring high-oleic sunflower and low-linolenic canola seed supply. Raw material dependencies include immobilized lipase enzymes, nickel catalyst displacement infrastructure, and crystallization kinetics monitoring equipment. Supply chain risk crystallizes around single-source vulnerability for specialty enzymatic catalysts manufactured by limited European suppliers. Distribution runs through direct-to-manufacturer bulk tanker networks that bypass traditional distributor markups for institutional accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service contracts for enzymatic process optimization and solid fat content curve calibration are expanding faster than commodity oil sales, creating recurring revenue attachment opportunities for technology-forward suppliers. This service layer commands premium pricing as bakery producers retrofit production lines under compressed trans-fat elimination deadlines.
For Market Incumbents: Consolidate enzymatic modification capacity in the Netherlands and Germany to capture retrofit demand from industrial puff pastry producers facing EU F-Gas Regulation compliance costs. Backward integration into high-oleic seed breeding programs secures feedstock consistency against Ukrainian supply disruption. Threat substitution from novel food classification delays at EFSA demands preemptive clinical substantiation investment for saturated fat reduction claims. For New Entrants and Emerging Players: Post-sales technical support for crystallization kinetics tuning represents an incumbent underservice gap where specialized enzymatic process engineers command premium compensation. White-space targets include Mumbai and Delhi food manufacturers navigating FSSAI fortification mandates with limited local fractionation expertise. The most penetrable segment is mid-size Indian bakery producers retrofitting for high-oleic sunflower bases without in-house lipid technology capabilities. Go-to-market through direct technical service partnerships with existing oilseed distributors bypasses capital-intensive fractionation infrastructure requirements. For Investors and Strategic Acquirers: Carve-out targets emerge from agricultural conglomerates divesting non-core specialty fat blending operations to focus on upstream seed crushing. Long-term viability hinges on enzymatic technology licensing revenue streams displacing commodity trading margins. Acquisition archetypes include European enzymatic process specialists with immobilized lipase column installations and documented REACH dossiers. The signal to watch is EFSA novel food classification timeline compression for enzymatically modified oils, which would accelerate consolidation pressure on technology-limited blenders.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Process Licensing | Technology transfer agreements with German bakery groups accelerate trans-fat elimination retrofit timelines. |
| Backward Integration into Seed Breeding | Captive high-oleic canola and sunflower varieties secure oxidative stability performance guarantees for institutional accounts. |
| Long-term Supply Agreement | Eighteen-month offtake contracts with specified solid fat content tolerances lock in frozen dough sector volume. |
| REACH Compliance Investment | Preemptive chemical dossier preparation for modified oil compositions prevents multi-year market entry delays. |
| Technical Service Expansion | On-site crystallization kinetics optimization commands premium pricing from industrial margarine producers. |
Research Methodology
The analysis maps enzymatic interesterification technology tiers, fractionation capability clusters, and end-use application specifications, each validated through lipid technologists, bakery production engineers, and procurement leads at industrial food manufacturers. Primary interviews with enzymatic catalyst suppliers, fractionation facility operators, and FSSAI compliance consultants combined with secondary validation from EU REACH registration databases, EFSA novel food classification records, and edible oil customs trade data. Bottom-up capacity and utilization estimates triangulated against top-down demand modeling from bakery and margarine segment consumption patterns.
Consistency checks validated volume and value outputs against oxidative stability index procurement specifications and solid fat content curve requirements documented in long-term offtake agreements. Segmentation dimensions modeled include oil variety, application functional requirements, distribution channel procurement scale, and end-user technical sophistication across the projection horizon. CAGRs derived from regression analysis of enzymatic modification adoption rates and fractionation capacity expansion timelines. Industry-specific forecast inputs encompass EU F-Gas Regulation compliance cost trajectories and EFSA health claim authorization pipeline status.
Forecasts assume regulatory continuity in EU REACH and F-Gas frameworks, FDA nutrition labeling enforcement, and FSSAI fortification mandate implementation; material policy shifts would require re-modeling of technology adoption curves and feedstock sourcing patterns. Revision becomes warranted when enzymatic catalyst supply constraints or palm oil price volatility crosses thresholds that alter fractionation versus blending economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
China Corn Glucose Market
Ingredients
Brewer's Yeast Market
Ingredients
Food Grade Hydrolyzed Casein Market
Ingredients
Buckwheat Groat Flour Market
Ingredients
Gelatin Substitutes Market
Ingredients
Dark Yeast Extract Market
Ingredients
Middle East & Africa Prebiotic Ingredients Market
Ingredients
Licorice Root Market
Ingredients
Algae Omega-3 Ingredients Market
Ingredients
South America Malt Ingredient Market
Ingredients
Homecare Ingredients Market
Ingredients
North America Corn Starch Market
Ingredients
Cottonseed Oil Market
Ingredients
Africa Soy Protein Ingredients Market
Ingredients
Citrus Based Dietary Fibers Market
Ingredients
Mussel Oil and Powder Market