
 PVDF Resin Market | 2026-2036
PVDF Resin Market Size, Share, and Industry Trends Forecast 2026-2036
PVDF Resin Market Intelligence
China is fragmenting its PVDF resin capacity across multiple fluorochemical industrial parks in Jiangsu and Shandong provinces. Daikin Industries leverages captive fluorine supply chains to sustain cost discipline in high-purity grades. Arkema S.A. anchors European demand through backward integration into hydrogen fluoride feedstock. Solvay S.A. competes on membrane-grade specialization for water treatment and semiconductor applications.
PVDF resin is a semi-crystalline fluoropolymer synthesized from vinylidene fluoride monomer, typically exhibiting 59% fluorine content by weight and melting points between 140°C and 180°C depending on crystallinity. The material delivers chemical inertness, piezoelectric response, and ultraviolet stability for coatings, membranes, and lithium-ion battery binders. Powder grades lead volume shipments for electrode binder applications in battery manufacturing, while membrane forms capture premium pricing in semiconductor water purification systems. High-purity and specialty grades represent the fastest-expanding margin pools as semiconductor fabs and battery cell producers tighten contamination specifications.
China's MEE enforces fluorochemical emission caps that constrain expansion permits for VDF monomer plants, while REACH and the EU F-Gas Regulation restrict high-GWP precursor chemistries in European supply chains. FDA and EPA standards govern PVDF contact surfaces in US food processing and potable water infrastructure, creating compliance moats for certified producers. Stakeholders must monitor feedstock fluorite concentrate availability and regional carbon border adjustment mechanisms to secure cost-competitive, regulation-aligned supply positions.
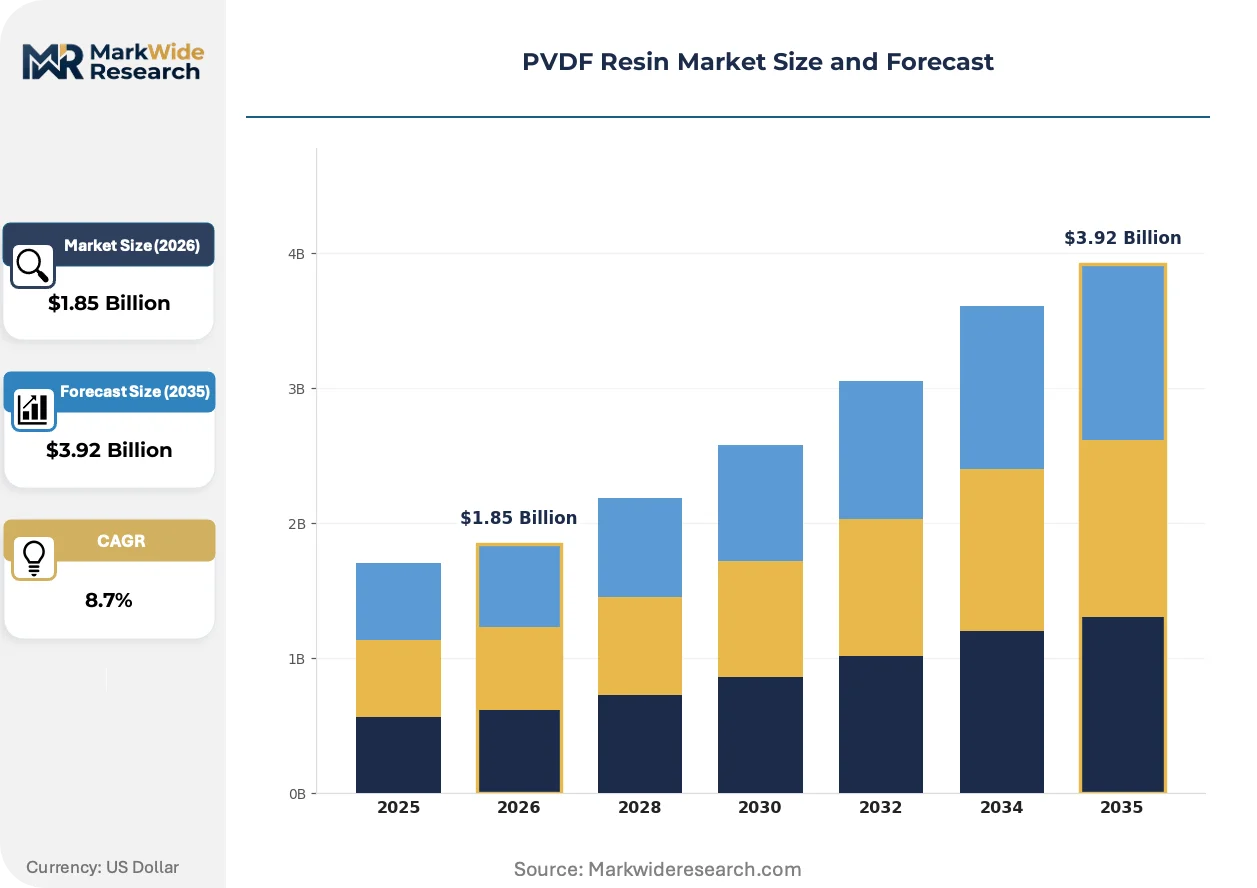
Market Dynamics
China's MEE fluorochemical emission caps are constraining VDF monomer expansion permits while lithium-ion battery electrode binder demand accelerates, creating a structural supply-demand tension that rewards producers with backward-integrated fluorite access.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of high-GWP refrigerants redirects fluoropolymer investment toward low-emission process routes, expanding PVDF capacity for battery and membrane applications.
- Lithium-ion electrode binders:Cell manufacturers are specifying PVDF powder grades for cathode adhesion as energy density targets tighten across automotive and stationary storage segments.
- Jiangsu province clustering:Integrated fluorochemical parks in Changzhou and Taixing concentrate VDF-to-PVDF conversion capacity, reducing logistics costs for semiconductor and battery fab customers.
Market Restraints
- Fluorite concentrate volatility:Acid-grade fluorspar supply from Mexico and Mongolia faces export quota uncertainty, transmitting cost instability to hydrogen fluoride and VDF monomer pricing.
- High-purity purification capex:Semiconductor-grade PVDF requires sub-ppb metal ion removal systems that extend plant commissioning timelines and strain balance sheets.
- Alternative binder chemistries:Water-based polyacrylic acid formulations are displacing PVDF in low-voltage lithium iron phosphate cells, compressing addressable volume in cost-sensitive segments.
Strategic Opportunities
- India PLI scheme:Cell manufacturing incentives under the ACC program are attracting PVDF resin suppliers to establish localized compounding operations for domestic battery producers.
- Semiconductor water treatment membranes:Ultrapure water systems in advanced logic fabs are adopting PVDF hollow fiber configurations for chemical resistance and extended service intervals.
- Dual carbon alignment:Producers with renewable-powered VDF cracking and membrane filtration upgrades can secure preferential offtake from battery OEMs with Scope 3 reduction mandates.
Industry Challenges
- Fluoropolymer process engineering talent:Specialized expertise in suspension polymerization kinetics and melt rheology remains concentrated at legacy producers, constraining new entrant scale-up.
- REACH registration timelines:European market access requires extensive dossier preparation for VDF monomer and oligomer impurities, delaying commercial launches by 18-24 months.
- Legacy equipment retrofit complexity:Existing PTFE and FEP production lines require substantial reconfiguration to achieve PVDF grade purity specifications, complicating portfolio diversification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PVDF Resin Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.92 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granules, Powder, Sheets, Films End Use Industry: Aerospace, Chemical Processing, Electronics, Water Treatment Form: Coatings, Membranes, Tubes, Rods Grade: Standard, High Purity, Specialty, Modified |
| Companies Covered | Daikin Industries Ltd., Kureha Corporation, Arkema S.A., Zhejiang Juhua Co., Ltd., SABIC, Solvay S.A., Dongyue Group Ltd., Gujarat Fluorochemicals Ltd., 3M Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PVDF Resin Market Strategic Shifts & Innovations
Process analytical technology and closed-loop solvent recovery are compressing PVDF production costs while contamination detection advances unlock semiconductor-grade qualification pathways.
Advanced online spectroscopy is digitizing real-time molecular weight monitoring during VDF suspension polymerization. Korean and Chinese battery material producers are deploying these systems to tighten batch-to-batch consistency for high-nickel cathode binders. The technology is digitizing quality assurance workflows, reducing offline lab testing cycles from hours to minutes and compressing rejection rates at cell manufacturer incoming inspection.
REACH authorization requirements for perfluorinated precursor substances are forcing reformulation of conventional VDF production chemistries. European PVDF producers are investing in alternative initiator systems and aqueous-phase polymerization routes to maintain registration compliance. Membrane-grade product lines face the tightest substance scrutiny, with semiconductor fabs now requiring full supply chain disclosure of fluorinated process aids.
Consolidated procurement desks at tier-one battery cell producers are unbundling resin supply from technical service contracts. Large-scale cathode manufacturers in Zhejiang province are negotiating direct PVDF powder offtakes with fluorochemical parks, bypassing traditional distribution channels. This pattern concentrates volume commitments among integrated producers with captive VDF supply, marginalizing merchant resin traders without backward integration into monomer production.
PVDF Resin Market Segmentation
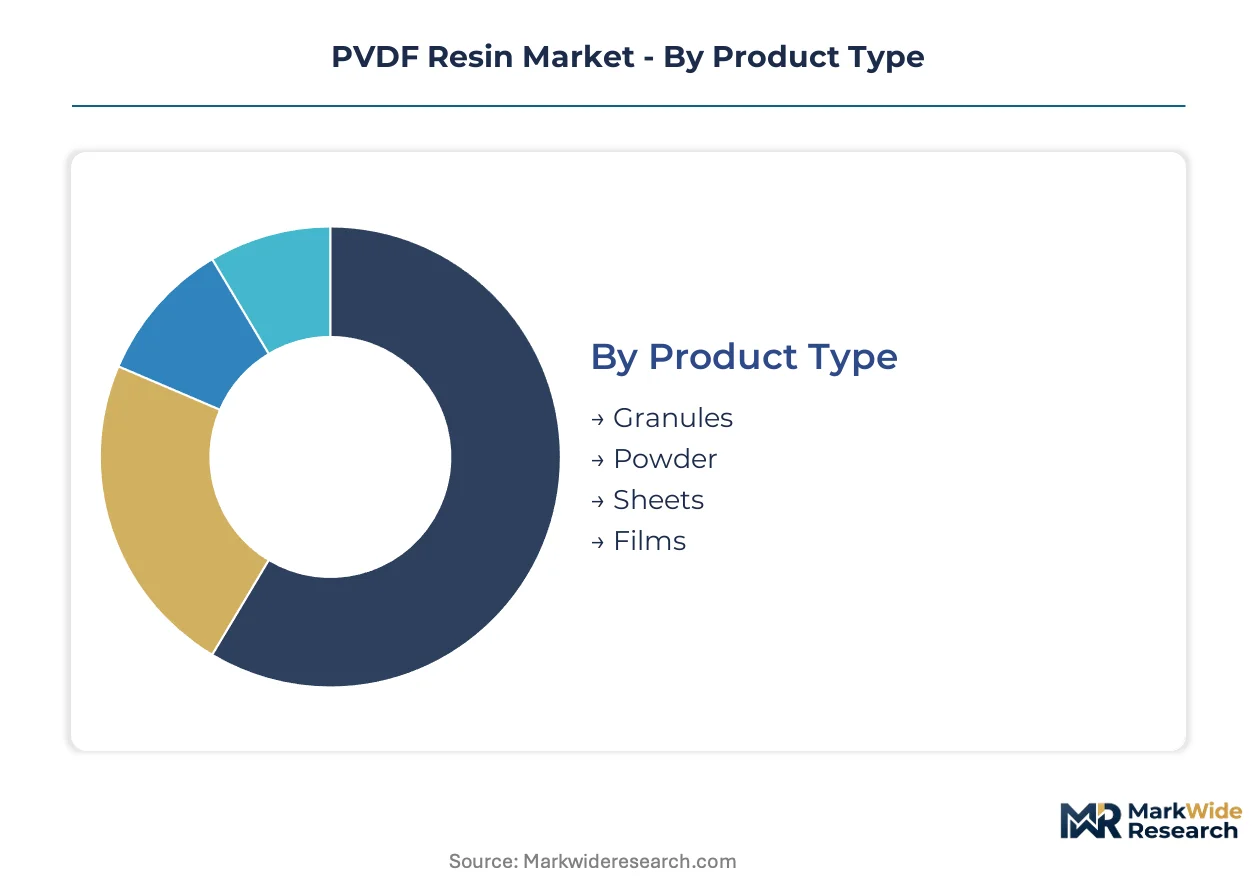
PVDF resin segmentation reflects divergent purity requirements across battery electrodes, semiconductor membranes, and industrial coatings. Manufacturers configure polymerization conditions and post-processing steps to match end-use contamination thresholds and mechanical specifications.
Product Type:
Powder and granule formats serve distinct processing workflows across extrusion, compression molding, and solution casting operations.
- Powder:Fine particulate morphology enables uniform dispersion in N-methyl-2-pyrrolidone solvent systems for lithium-ion cathode slurries. Battery material producers in Changzhou specify powder grades with controlled particle size distributions to optimize electrode coating thickness uniformity.
- Granules:Pelletized feedstock feeds twin-screw extrusion lines for membrane hollow fiber spinning and injection molding of chemical processing components. Semiconductor water treatment equipment manufacturers source granules for melt-processing into ultrapure water filtration modules.
- Sheets:Calendered plate stock supplies gasket and lining fabricators serving chlor-alkali and sulfuric acid handling infrastructure.
- Films:Biaxially oriented and cast film grades serve piezoelectric sensor laminates and architectural facade cladding systems.
Established volume favors powder; emerging adoption favors granules.
End Use Industry:
Application-specific certification requirements fragment procurement specifications across regulated sectors.
- Electronics:Semiconductor fabs specify sub-ppb metallic impurity limits for membrane-grade PVDF in ultrapure water loops. Korean and Taiwanese logic chip manufacturers drive qualification protocols for hollow fiber membrane configurations.
- Water Treatment:Municipal and industrial reverse osmosis pre-treatment systems deploy PVDF membranes for chlorine resistance and extended service intervals. China's MEE discharge standards tighten membrane replacement cycles in chemical park wastewater facilities.
- Chemical Processing:Lining and gasket applications exploit fluoropolymer inertness against concentrated acids and halogenated solvents.
- Aerospace:Wire insulation and fuel system components leverage low smoke density and flame resistance characteristics for cabin safety compliance.
Water treatment commands the steepest expansion trajectory; electronics captures the highest margin premiums.
Form:
Physical configuration determines installation method and performance envelope in target equipment.
- Membranes:Hollow fiber and flat-sheet geometries dominate semiconductor ultrapure water and biopharmaceutical filtration. Advanced logic fabs in Hsinchu specify PVDF membranes for aggressive chemical cleaning protocols.
- Coatings:Solvent-borne and powder coating systems protect chemical processing vessels and architectural metal substrates from UV degradation and corrosive attack.
- Tubes:Extruded tubing serves analytical instrumentation fluid handling and pharmaceutical transfer applications.
- Rods:Machinable stock shapes support seal and bearing fabrication for pump and valve components.
Membrane forms extract premium pricing; coating volumes scale with infrastructure investment cycles.
Grade:
Purity tiering aligns resin specifications with contamination sensitivity and regulatory exposure.
- High Purity:Semiconductor-grade resin undergoes multi-stage washing and ion exchange to achieve sub-ppb sodium, potassium, and iron levels. REACH substance scrutiny and full supply chain disclosure requirements concentrate production among integrated fluorochemical producers with captive VDF supply.
- Specialty:Modified grades incorporate functional comonomers or fillers for enhanced piezoelectric response, radiation resistance, or adhesion promotion. Medical device and sensor manufacturers specify specialty grades for implantable and diagnostic applications.
- Standard:General-purpose resin serves industrial coating and chemical processing applications with less stringent contamination limits.
- Modified:Alloy and filled variants tailor mechanical properties and surface characteristics for specific OEM requirements.
High purity grades gain share fastest; standard grades defend volume in cost-sensitive industrial segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MEE emission caps in China anchor regional supply dynamics, while battery and semiconductor demand pulls capacity toward East Asian industrial clusters. Regulatory divergence across major economies is fragmenting qualification standards and procurement patterns.
China
Lithium-ion cathode manufacturers in Changzhou and Taixing drive powder-grade consumption for high-nickel battery chemistries. MEE fluorochemical emission caps constrain VDF monomer expansion permits, tightening feedstock availability for non-integrated producers. Jiangsu province's integrated fluorochemical parks concentrate backward-integrated PVDF capacity serving domestic battery and semiconductor fabs.
United States
Semiconductor water treatment membrane demand from advanced logic fabs sustains premium-grade imports. FDA and EPA standards govern PVDF contact surfaces in food processing and potable water infrastructure, creating compliance barriers for uncertified suppliers. Texas and Arizona fab clusters source membrane-grade resin through specialized distributors with established qualification protocols.
Germany
EU F-Gas Regulation phasedown redirects fluoropolymer investment toward low-emission process routes. REACH authorization requirements for perfluorinated precursors force reformulation of conventional VDF production chemistries. Chemical parks in North Rhine-Westphalia and Bavaria host membrane-specialized compounders serving European semiconductor and water treatment equipment manufacturers.
Japan
Piezoelectric sensor and lithium-ion battery material producers sustain demand for high-purity powder grades. METI industrial policy supports domestic fluorochemical supply chain resilience amid import dependency concerns. Osaka and Nagoya industrial corridors concentrate PVDF processing for electronics and automotive tier-one suppliers.
South Korea
Battery cell producers specify PVDF cathode binders as energy density targets tighten across automotive and stationary storage segments. MFDS and environmental regulators enforce fluorochemical discharge standards at industrial complexes. Gyeonggi-do and Chungnam province host integrated cathode-PVDF procurement desks consolidating volume commitments among captive VDF suppliers.
PVDF Resin Market Key Industry Players
Backward-integrated chemical conglomerates and specialty fluoropolymer houses split the market into distinct capability tiers. Consolidation concentrates volume among producers with captive fluorite-to-VDF supply chains, while merchant resin traders face margin compression. Japanese and European incumbents anchor premium-grade positioning through proprietary purification protocols. Chinese state-affiliated and private fluorochemical groups scale powder-grade output for domestic battery material integration. Competitive moves center on hydrogen fluoride feedstock security and membrane-grade qualification timelines.
Among Japanese incumbents, Daikin Industries Ltd. and Kureha Corporation occupy positions defined by captive fluorine chemistry expertise and long-standing semiconductor customer relationships. European specialists Arkema S.A. and Solvay S.A. exemplify membrane-grade specialization archetypes, with backward integration into hydrogen fluoride feedstock distinguishing their supply security profiles. Chinese producers Zhejiang Juhua Co., Ltd. and Dongyue Group Ltd. represent state-affiliated and private scaling models respectively, both leveraging integrated fluorochemical park infrastructure to serve domestic battery material demand growth.
| Leading Market Players |
|---|
| Daikin Industries Ltd. |
| Kureha Corporation |
| Arkema S.A. |
| Zhejiang Juhua Co., Ltd. |
| SABIC |
| Solvay S.A. |
| Dongyue Group Ltd. |
| Gujarat Fluorochemicals Ltd. |
| 3M Company |
| Others |
Cost & Logistics Intelligence
Acid-grade fluorspar concentration in Mexico and Mongolia anchors margin capture downstream, with hydrogen fluoride and VDF monomer pricing transmitting volatility directly to PVDF resin tiers. Battery cathode manufacturers and semiconductor fabs absorb differential cost pass-through based on grade certification and volume scale.
Pricing Analysis
Chinese Jiangsu province commands a 15-20% discount to European membrane-grade quotations due to integrated fluorochemical park economics. Three-tier pricing structure across semiconductor-grade, battery-grade, and industrial-grade levels separates sub-ppb purity resin from standard powder formulations. Cost compression in battery-grade powder is intensifying because water-based polyacrylic acid binders are displacing PVDF in lithium iron phosphate cells. Automotive cell manufacturers exhibit highest price sensitivity; logic fabs with qualification lock-in show lowest.
Supply Chain Analysis
Tariff exposure between China and the United States dominates strategic planning for membrane-grade distributors serving Arizona and Texas fab clusters. VDF monomer production concentrates in China, Japan, and South Korea, with each node drawing from distinct fluorite concentrate supply agreements. Hydrogen fluoride, acid-grade fluorspar, and perchloroethylene feedstock dependencies create single-source vulnerability when Mongolian export quotas tighten. Distribution runs through integrated fluorochemical parks in Changzhou and Taixing, bypassing traditional merchant resin channels for volume cathode producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Water-based polyacrylic acid formulations threaten PVDF's cathode binder dominance in cost-sensitive lithium iron phosphate segments, forcing incumbents to defend through purity differentiation and qualification depth.
For Market Incumbents: Build certification moats around semiconductor-grade qualification protocols to lock out merchant resin traders lacking captive VDF supply. Deepen backward integration into hydrogen fluoride feedstock to absorb fluorspar volatility and sustain margin pools in battery-grade powder. Anchor long-term offtake with Korean and Chinese cell producers consolidating procurement through direct fluorochemical park relationships.
For New Entrants and Emerging Players: India's ACC program under the PLI scheme offers underpenetrated white-space for localized PVDF compounding serving domestic cathode manufacturers. Target membrane-grade hollow fiber configurations for European water treatment equipment producers seeking REACH-compliant alternative supply. Pursue joint qualification pathways with tier-two semiconductor fabs in Hsinchu and Gyeonggi-do to bypass incumbent qualification lock-in.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed specialty fluoropolymer houses in Germany and Japan holding membrane-grade customer relationships but lacking captive fluorite supply. Five-to-ten year viability hinges on hydrogen fluoride feedstock security and REACH registration completion timelines. Monitor VDF monomer expansion permit approvals under China's MEE emission caps as inflection signal for supply-constraint pricing power.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hydrogen Fluoride | Captive feedstock supply from Mexican and Mongolian fluorspar agreements insulates margin pools from export quota volatility. |
| Semiconductor-Grade Purification Capacity | Sub-ppb metal ion removal systems unlock qualification with advanced logic fabs in Hsinchu and Austin. |
| India PLI Localization | Domestic compounding operations under ACC program incentives capture cathode manufacturer volume commitments. |
| REACH Alternative Chemistry Reformulation | Aqueous-phase polymerization routes maintain European market access amid perfluorinated precursor substance scrutiny. |
| Renewable-Powered VDF Cracking | Carbon-free energy sourcing secures preferential offtake from battery OEMs with Scope 3 reduction mandates. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted across the primary research phase, combining structured interviews with cathode material procurement directors, fluorochemical plant managers, semiconductor fab water treatment engineers, and membrane equipment OEM technical leads. Secondary validation drew from customs trade data, MEE emission permit disclosures, REACH registration dossiers, and SEC filings from listed fluorochemical conglomerates. Bottom-up volume modeling from end-use application demand and top-down supply capacity triangulation were cross-referenced for convergence.
Calibration against historical price differentials between Chinese integrated park output and European specialty compounder quotations anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include grade tier purity specifications, end-use industry contamination thresholds, physical form factor processing requirements, and regional regulatory cluster alignment. CAGRs were derived from elasticity-adjusted demand curves incorporating battery cell capacity buildout schedules and semiconductor fab water treatment membrane replacement cycles.
Practitioners should monitor Mongolian fluorspar export quota announcements, MEE VDF monomer permit issuance rates, and water-based binder adoption curves in lithium iron phosphate cells for early signals of forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Non-Ionic Polyacrylamide Market
Polymers & Resins
Global Polycarbonate Market
Polymers & Resins
South America Polyvinyl Chloride (PVC) Market
Polymers & Resins
Vinyl Acetate Ethylene (VAE) Market
Polymers & Resins
Europe Polyamide Market
Polymers & Resins
C5 Resin Market
Polymers & Resins
Global High Temperature Resin Market
Polymers & Resins
Global Microcellular Polyurethane Foam Market
Polymers & Resins
Aromatic Ketone Polymer Market
Polymers & Resins
Polycarbonate Diols Market
Polymers & Resins
South America Polyethylene Terephthalate (PET) Resin Market
Polymers & Resins
Acrylonitrile Butadiene Styrene (ABS) Market
Polymers & Resins
Polycaprolactone Polyols Market
Polymers & Resins
Polyurethane (PU) Foam Market
Polymers & Resins
North America Polymer Emulsion Market
Polymers & Resins
Polymer Memory Market