
 FBE Coatings Market | 2026-2036
FBE Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
FBE Coatings Market Insights
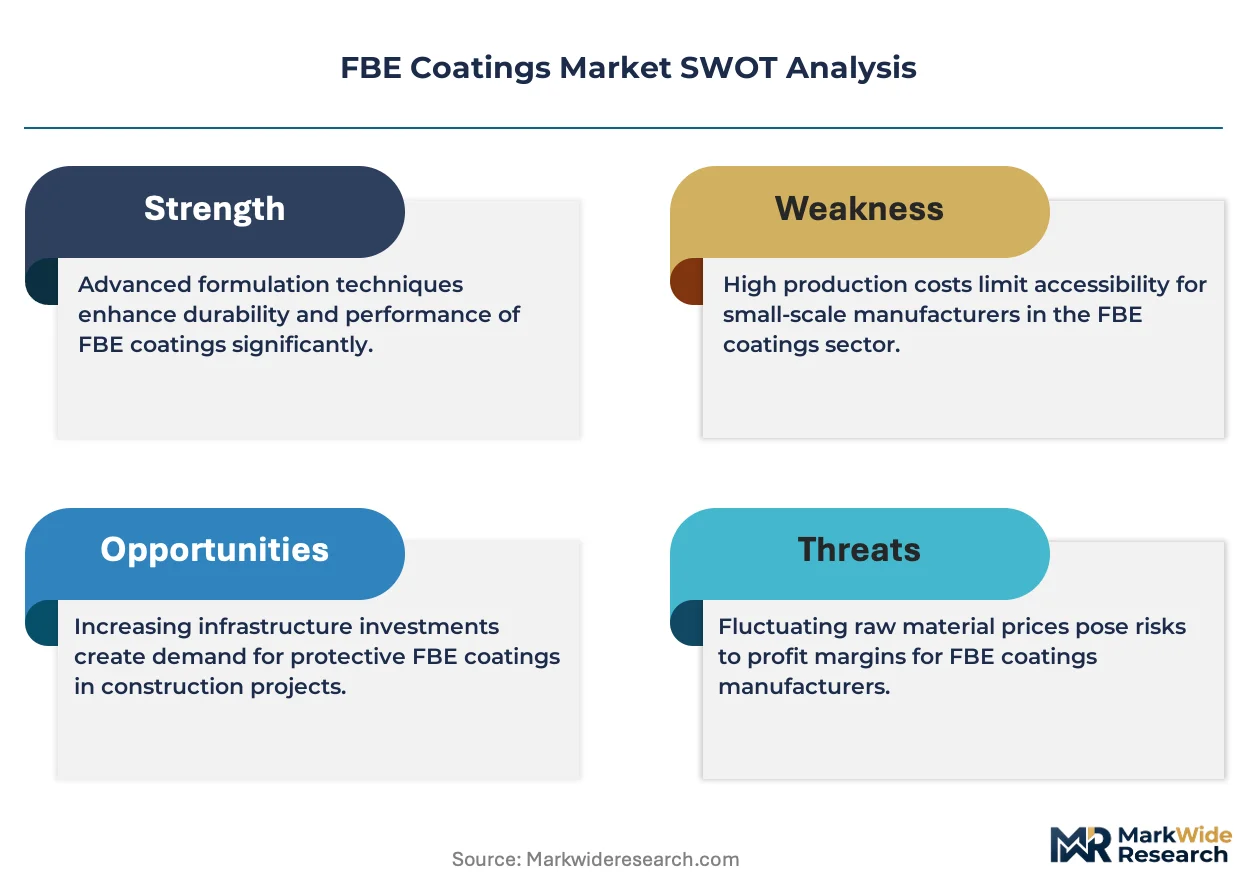
NACE SP0169 qualification is bifurcating the competitive landscape into certified applicators and marginal suppliers. Shawcor leverages its integrated pipe coating services to dominate North American pipeline projects. Akzo Nobel N.V. anchors its position through specialized marine-grade FBE formulations. Jotun competes aggressively in offshore infrastructure with high-temperature-resistant powder systems.
Fusion bonded epoxy coatings are thermosetting powders applied to heated steel substrates, typically 250-500 microns thick, that cure to form chemically resistant barriers against cathodic disbondment and soil corrosion. Their primary purpose is extending asset life in buried and submerged steel structures. The oil and gas end user segment leads in absolute volume due to pipeline replacement cycles, while marine applications represent the fastest-growing margin pool as offshore wind foundations multiply. Spray coating technology dominates field application workflows, though electrostatic application gains share in controlled factory settings for storage tank fabrication.
API specification requirements and NACE SP0169 govern product performance benchmarks in the United States, while ISO 21809 frames international interoperability for pipeline coating systems. These standards directly determine which applicators qualify for major energy infrastructure contracts. The EPA's evolving VOC regulations for industrial coatings are pushing reformulation toward lower-emission powder chemistries. Stakeholders must monitor qualification credential expiration cycles and pre-position testing capacity ahead of anticipated infrastructure procurement waves.
Market Dynamics
Pipeline replacement cycles across North American energy infrastructure are tightening NACE SP0169 certification timelines, compressing applicator qualification windows and concentrating procurement among pre-qualified coating contractors.
Growth Catalysts
- Offshore wind foundation deployment:European North Sea and US Atlantic Coast projects are specifying marine-grade FBE systems for monopile corrosion protection, expanding addressable demand beyond traditional oil and gas.
- NACE SP0169:The standard's tightened disbondment resistance testing is disqualifying marginal applicators, steering contract volume toward certified specialists with in-house laboratory capacity.
- Polyethylene copolymer blends:Modified powder chemistries with enhanced cathodic disbondment thresholds are qualifying for deeper burial applications in sour gas pipelines.
Market Restraints
- Epoxy resin feedstock volatility:Bisphenol-A and epichlorohydrin price swings squeeze applicator margins during fixed-price infrastructure contracts.
- Applicator concentration on the US Gulf Coast:Three integrated coating facilities control the majority of domestic large-diameter pipe throughput, creating bottleneck risk during procurement surges.
- Three-layer polyethylene (3LPE) substitution:Pipeline operators in high-temperature transport are specifying 3LPE for operating conditions exceeding 85°C, capping FBE penetration in certain trunk line segments.
Strategic Opportunities
- India pipeline buildout:The country's National Gas Grid expansion targets 30,000 kilometers of new steel pipeline, with BIS standards converging toward ISO 21809 equivalency for imported coating systems.
- Carbon capture transport infrastructure:CO2 pipeline specifications are mandating enhanced chemical resistance profiles that favor next-generation FBE formulations with modified amine curing agents.
- Electrostatic application automation:Robotics integration in controlled factory environments is reducing film thickness variability below 50 microns, qualifying applicators for storage tank and structural steel contracts.
Industry Challenges
- NACE SP0169 qualification backlog:Third-party laboratory testing capacity constraints are extending certification timelines to 14-18 months, delaying contractor eligibility for federal infrastructure procurement windows.
- High-temperature powder storage:Seasonal humidity spikes in coastal applicator facilities degrade unconditioned powder inventory, requiring climate-controlled warehousing capex that marginal operators cannot absorb.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | FBE Coatings Market |
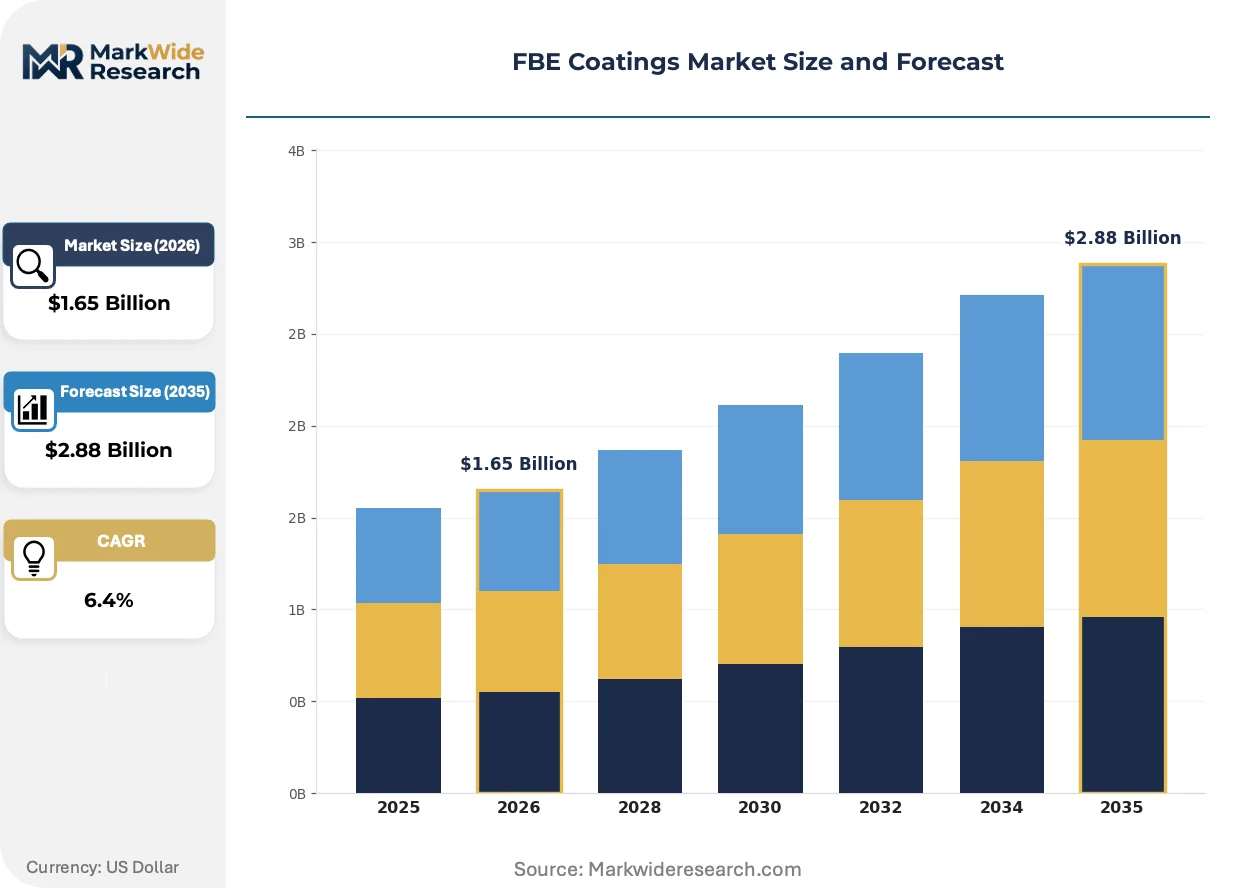
| Market Size in 2026 | $1.65 Billion |
| Market Size in 2035 | $2.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fusion Bonded Epoxy, Powder Coatings, Liquid Coatings, High-Performance Coatings End User: Oil & Gas, Infrastructure, Marine, Power Generation Application: Pipelines, Structural Components, Storage Tanks, Industrial Equipment Technology: Spray Coating, Brush Coating, Dip Coating, Electrostatic Application |
| Companies Covered | 3M, The Sherwin-Williams Company, Akzo Nobel N.V., Axalta Coating Systems, Jotun, PPG Industries, Shawcor, BASF SE, Arkema Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
FBE Coatings Market Trends and Innovations
Active reformulation of powder chemistries and automation of application workflows are compressing coating variability while regulatory tightening in multiple jurisdictions elevates performance verification requirements.
Hybrid epoxy-phenolic powder systems are fragmenting the conventional FBE category by delivering superior chemical resistance for sour gas service. Midstream operators in the Permian Basin and Alberta oil sands are specifying these blends for gathering lines with H2S concentrations above 5%. The technology is fragmenting procurement specifications into performance-tiered categories rather than single-product standards.
EPA VOC regulations for industrial coatings are forcing applicators toward lower-emission powder formulations with reduced solvent content during surface preparation. The agency's National Emission Standards for Hazardous Air Pollutants (NESHAP) Subpart HHHHHH directly affects coating facility permitting in Texas and Louisiana. Applicators are responding by investing in closed-loop abrasive blasting recovery systems to maintain throughput under tighter emission budgets.
Asset owner engineering teams are unbundling coating specification from pipe mill procurement, issuing separate RFPs for field joint coating and mainline application. This pattern compresses single-source contractor relationships and elevates third-party inspection requirements. The shift is most visible in US interstate pipeline projects where FERC certificate conditions mandate independent coating verification.
FBE Coatings Market Segmentation
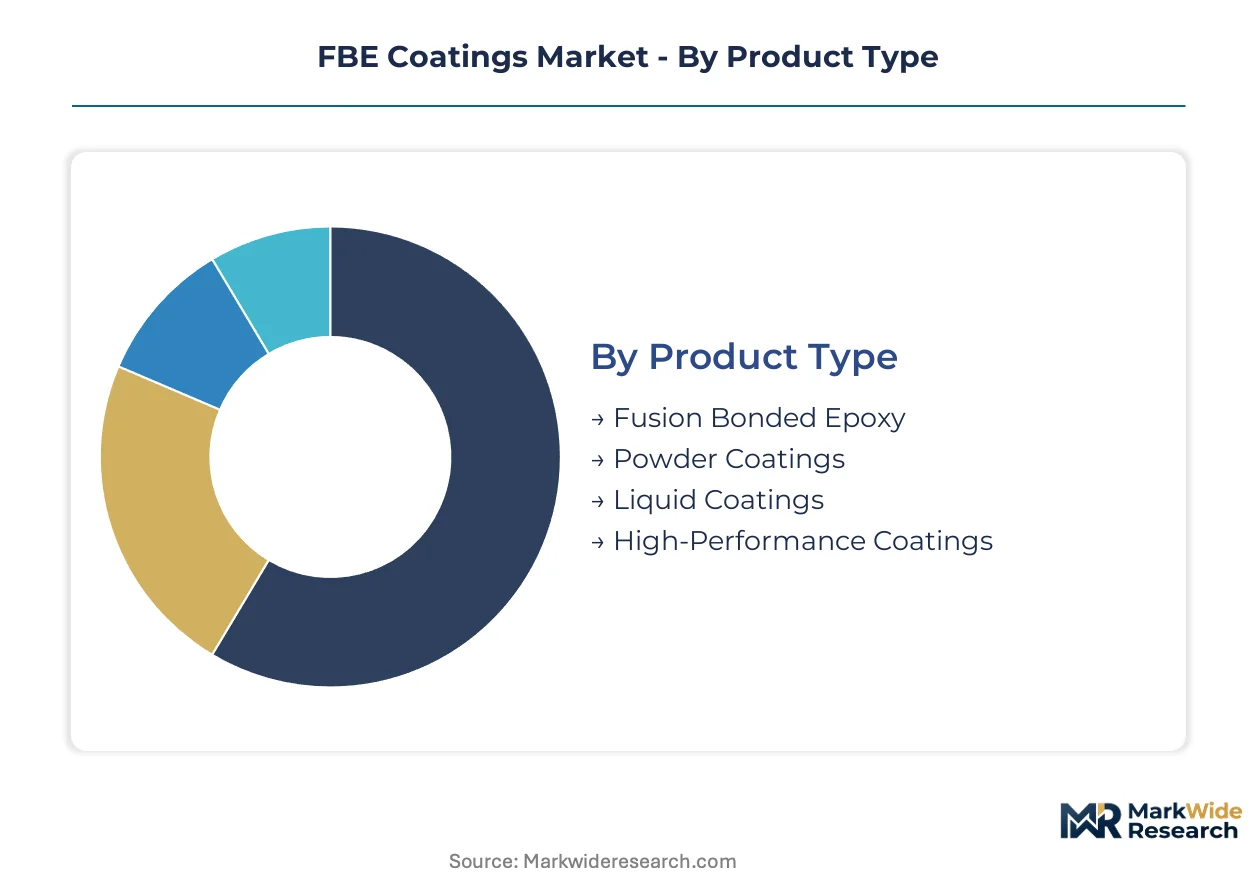
Segmentation in the FBE Coatings Market reveals how substitution pressures and qualification barriers reshape procurement patterns across product tiers. Understanding these divisions exposes where applicators can defend margin pools and where volume concentrates among certified specialists.
Product Type:
Three-layer polyethylene systems exert the strongest substitution pressure on conventional FBE formulations, particularly in high-temperature transport segments exceeding 85°C operating thresholds.
- Fusion Bonded Epoxy:Thermosetting powder systems cure at 180-250°C to form 250-500 micron barriers against cathodic disbondment. Pipeline operators in the United States Gulf Coast petrochemical corridor specify these for buried steel replacement cycles under NACE SP0169 protocols.
- Powder Coatings:Epoxy-phenolic hybrid chemistries deliver enhanced chemical resistance for sour gas service with H2S concentrations above 5%. Permian Basin and Alberta oil sands operators are fragmenting procurement specifications toward these performance-tiered categories.
- Liquid Coatings:Solvent-based and waterborne alternatives serve touch-up and repair applications where field heating infrastructure is unavailable.
- High-Performance Coatings:Modified amine-cured formulations target carbon capture transport infrastructure with enhanced CO2 resistance profiles.
Fusion Bonded Epoxy retains volume leadership; High-Performance Coatings holds the steepest expansion curve.
End User:
Cost tier stratification separates asset owners with in-house laboratory capacity from those dependent on third-party qualification, concentrating contract awards among vertically integrated service providers.
- Oil & Gas:Midstream operators drive absolute volume through pipeline replacement cycles and new gathering line construction. FERC certificate conditions on US interstate projects mandate independent coating verification, unbundling specification from pipe mill procurement.
- Marine:Offshore wind foundation deployment in the European North Sea and US Atlantic Coast specifies marine-grade systems for monopile corrosion protection. This segment commands premium pricing beyond traditional oil and gas applications.
- Infrastructure:Bridge and highway structural steel protection operates under less stringent qualification requirements, opening procurement to marginal applicators.
- Power Generation:Cooling water system and structural protection for thermal and renewable assets.
Oil & Gas dominates contract value; Marine generates the highest margin expansion trajectory.
Application:
Application geometry determines whether automated factory workflows or manual field techniques prevail, with cylindrical surfaces favoring electrostatic methods and complex joints requiring spray adaptation.
- Pipelines:Mainline and field joint coating for transmission and distribution networks. Separate RFPs for these functions are compressing single-source contractor relationships and elevating third-party inspection requirements.
- Storage Tanks:Electrostatic application in controlled factory environments reduces film thickness variability below 50 microns, qualifying applicators for aboveground storage tank fabrication contracts.
- Structural Components:Bridge girders, offshore platforms, and industrial frameworks requiring corrosion protection under ISO 12944 atmospheric corrosivity categories.
- Industrial Equipment:Process vessels, heat exchangers, and rotating machinery with complex geometries demanding brush or dip coating adaptation.
Pipelines anchor procurement volume; Storage Tanks climbs fastest on automation adoption.
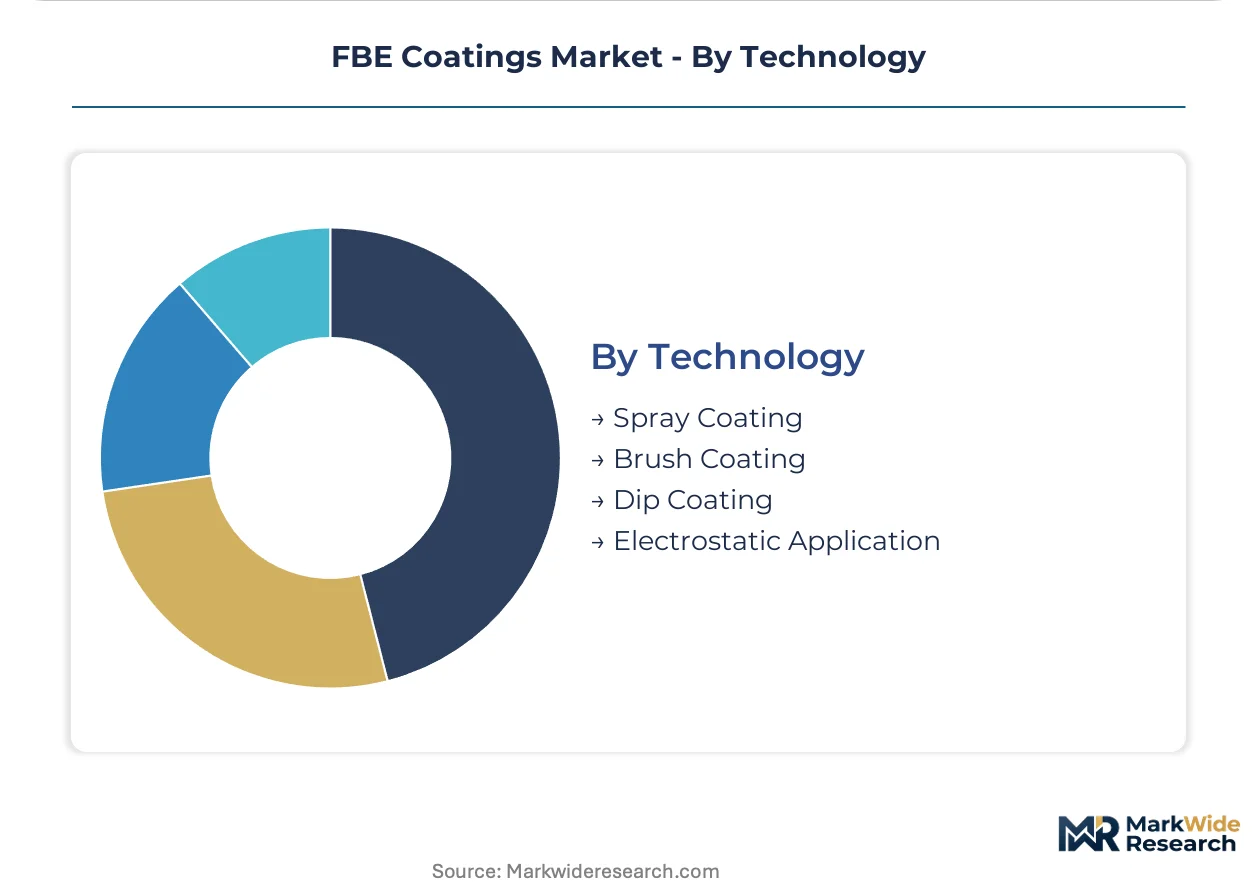
Technology:
Technology selection tracks the facility control spectrum, with open-air field operations constrained to spray methods and climate-controlled factories capturing electrostatic efficiency gains.
- Spray Coating:Dominates field application workflows for in-situ pipeline rehabilitation and large-diameter pipe exteriors. Seasonal humidity spikes in coastal facilities degrade unconditioned powder inventory, requiring climate-controlled warehousing capital expenditure.
- Electrostatic Application:Gains share in controlled factory settings through robotics integration that compresses coating variability. EPA NESHAP Subpart HHHHHH emission budgets favor these closed-loop systems in Texas and Louisiana permitting jurisdictions.
- Brush Coating:Manual application for touch-up, repair, and complex geometric areas inaccessible to automated systems.
- Dip Coating:Batch processing for small-diameter fittings and prefabricated structural elements with uniform geometry.
Spray Coating maintains deployment scale; Electrostatic Application expands most quickly on factory automation investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pipeline infrastructure renewal programs and offshore wind foundation specifications are redrawing procurement geography. Regulatory tightening on cathodic disbondment performance is concentrating contract awards near qualified applicator clusters.
United States
The Gulf Coast petrochemical corridor drives replacement cycle procurement for buried transmission lines. EPA NESHAP Subpart HHHHHH constrains coating facility permitting in Texas and Louisiana. Houston-area integrated applicators dominate large-diameter pipe throughput for FERC-regulated interstate projects.
Germany
North Sea offshore wind expansion specifies marine-grade systems for monopile corrosion protection. ECHA REACH compliance requirements govern epoxy resin formulation chemistry. Hamburg and Bremerhaven port clusters anchor coating application capacity for North Sea foundation deployment.
India
The National Gas Grid targets 30,000 kilometers of new steel pipeline construction. BIS standards convergence toward ISO 21809 equivalency shapes imported coating system qualification. Gujarat and Maharashtra industrial corridors concentrate domestic applicator development for trunk line projects.
Saudi Arabia
Master Gas System expansion and petrochemical export infrastructure sustain demand for high-temperature-resistant formulations. The national hydrocarbon regulator mandates coating performance verification for sour service pipelines. Jubail Industrial City hosts integrated pipe coating facilities serving GCC export markets.
Brazil
Pre-salt offshore field development requires subsea pipeline corrosion protection systems. ANVISA chemical registration requirements affect epoxy resin import logistics. Rio de Janeiro and São Paulo coastal clusters coordinate marine-grade application capacity for deepwater project procurement.
FBE Coatings Market Competitive Landscape
Player mix skews toward integrated pipe coating service providers and specialized marine-grade formulators. Market structure concentrates procurement influence among applicators with captive laboratory qualification capacity. Strategic archetypes include Gulf Coast integrated service providers, European marine specialists, and diversified industrial coatings conglomerates. Dominant competitive moves encompass backward integration into powder manufacturing and geographic expansion toward offshore wind development zones.
Within the integrated service tier, Shawcor anchors North American pipeline project positioning through combined pipe mill and coating facility operations. Akzo Nobel N.V. and Jotun occupy specialist positions in marine-grade and high-temperature-resistant formulation segments. These three represent the archetype spectrum from vertically integrated infrastructure services to focused performance chemistry development.
| Leading Market Players |
|---|
| 3M |
| The Sherwin-Williams Company |
| Akzo Nobel N.V. |
| Axalta Coating Systems |
| Jotun |
| PPG Industries |
| Shawcor |
| BASF SE |
| Arkema Group |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake contracts between Gulf Coast petrochemical operators and integrated coating facilities lock in powder supply access while fixing price visibility across 36-60 month infrastructure replacement cycles. These arrangements concentrate procurement leverage among NACE SP0169-certified applicators with captive laboratory capacity, compressing margin flexibility for marginal suppliers exposed to spot resin markets.
Pricing Analysis
Certification level (NACE SP0169/ISO 21809-grade) creates the primary spread between premium applicators and standard-tier competitors. Project-based pricing dominates large-diameter pipeline contracts, with differentiation driven by in-house qualification capacity and cathodic disbondment performance guarantees. Cost compression in standard-grade field joint applications is intensifying because polyethylene copolymer blends are qualifying for deeper burial specifications. Midstream operators with FERC-mandated independent verification show least price sensitivity; infrastructure contractors without captive laboratory access face acute margin pressure.
Supply Chain Analysis
Climate-controlled powder inventory cycles of 90-120 days dominate working capital deployment for coastal applicators facing seasonal humidity exposure. Epoxy resin feedstock draws from United States Gulf Coast petrochemical complexes, European specialty chemical producers, and Northeast Asian manufacturing hubs. Bisphenol-A and epichlorohydrin price volatility presents the core structural risk for fixed-price infrastructure contracts. Distribution runs through integrated pipe mill coating facilities and third-party applicator networks serving field rehabilitation projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The FBE coatings market is entering a cyclical recovery phase as North American pipeline replacement cycles accelerate and offshore wind foundation deployment expands procurement beyond traditional oil and gas. Infrastructure investment waves in carbon capture transport and sour gas gathering systems are extending contract visibility for qualified applicators.
For Market Incumbents: Fortify NACE SP0169 qualification capacity through in-house laboratory investment ahead of anticipated federal infrastructure procurement windows. Deepen backward integration into powder manufacturing to offset bisphenol-A feedstock volatility. Secure long-term offtake arrangements with Permian Basin and Alberta oil sands operators specifying hybrid epoxy-phenolic chemistries for sour service. For New Entrants and Emerging Players: Lead with electrostatic application automation for storage tank fabrication contracts where film thickness variability below 50 microns qualifies new market participants. Target India's National Gas Grid expansion where BIS standards convergence toward ISO 21809 equivalency creates entry pathways for imported coating systems. Position through joint venture structures with established Gulf Coast applicators to bypass 14-18 month qualification backlogs. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated service providers with captive laboratory capacity and established FERC-regulated interstate project relationships. The 5-10 year viability window favors applicators positioned for carbon capture transport infrastructure and offshore wind foundation deployment. Monitor EPA NESHAP Subpart HHHHHH permitting trends in Texas and Louisiana as inflection indicators for facility expansion feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Powder Manufacturing | Captures margin from bisphenol-A volatility while securing supply for NACE SP0169-qualified facilities. |
| Electrostatic Application Automation | Reduces film thickness variability below 50 microns for storage tank and structural steel contracts. |
| Marine-Grade Formulation Development | Qualifies applicators for North Sea and US Atlantic Coast offshore wind monopile protection specifications. |
| Joint Venture with Regional Applicators | Accelerates market entry in India and Brazil where qualification timelines and ANVISA registration create barriers. |
| Closed-Loop Abrasive Blasting Recovery | Maintains throughput under EPA NESHAP emission budgets in Texas and Louisiana permitting jurisdictions. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, customs and trade data, and industry association reports. Pipeline operators, coating facility plant managers, NACE-certified inspection engineers, and petrochemical procurement leads provided operational perspective. SEC 10-K disclosures, EPA enforcement databases, FERC certificate filings, and ISO 21809 qualification registries supplied validation. Bottom-up project pipeline analysis triangulates against top-down market sizing across product type, end user, application, and technology dimensions.
Segmentation dimensions modeled include coating chemistry tier, end-use industry vertical, application geometry, and regional regulatory cluster. CAGRs derive from regression analysis of historical replacement cycle patterns and projected infrastructure procurement waves. Forecast inputs incorporate pipeline mileage expansion targets, offshore wind capacity additions, and carbon capture transport infrastructure development timelines across the analysis window.
Forecasts assume regulatory continuity in EPA NESHAP enforcement, FERC certificate conditions, and ECHA REACH compliance requirements; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Global Floor Coatings Market
Coatings
Coatings and Fillings Market
Coatings
Global Polytetrafluoroethylene (PTFE) Coatings Market
Coatings
France Protective Coatings Market
Coatings
Protective Antimicrobial Coatings for High-Touch Surfaces Market
Coatings
North America Coil Coatings Market
Coatings
Corrosion Protective Coatings and Acid Proof Lining Market
Coatings
Breathable Antimicrobial Coatings Market
Coatings
High Performance Epoxy Coating Market
Coatings
Concrete Floor Coatings Market
Coatings
Tablet Coatings Market
Coatings
Sustained Release Coatings Market
Coatings
Asia-Pacific Coil Coatings Market
Coatings
Silicone Coating Market
Coatings
Global Fire-Resistant Coating Market
Coatings
Global UV-Cured Coatings Market