
 PTFE Membrane Market | 2026-2036
PTFE Membrane Market Size, Share, and Industry Trends Forecast 2026-2036
PTFE Membrane Market Analysis
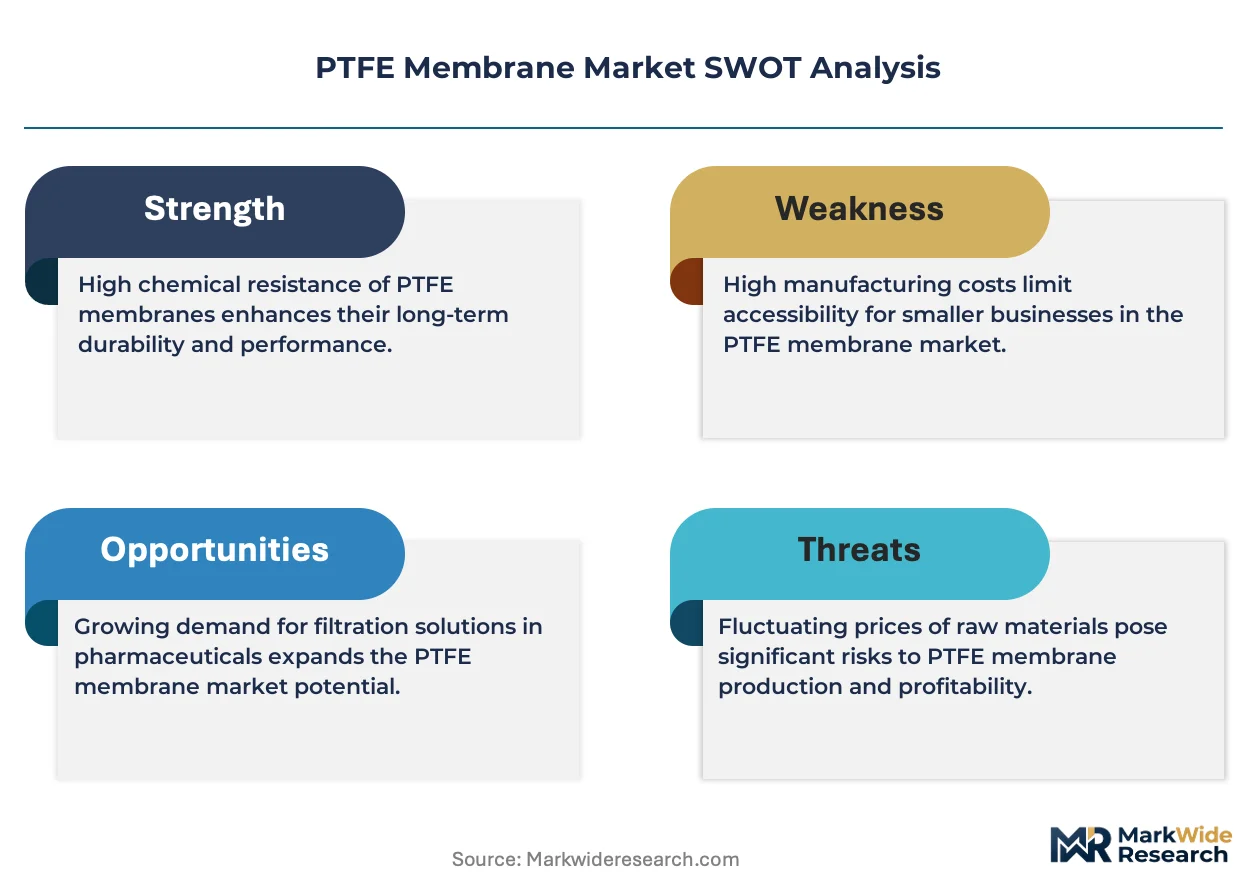
Buyer concentration in pharmaceutical filtration is rebalancing as contract manufacturing organizations fragment procurement across specialized membrane suppliers while large biopharma houses consolidate vendor lists. W. L. Gore & Associates leverages its fluoropolymer heritage to dominate high-purity venting applications. Pall Corporation anchors its position through deep integration with bioprocessing workflows. Saint-Gobain competes aggressively on membrane architecture for aggressive chemical environments.
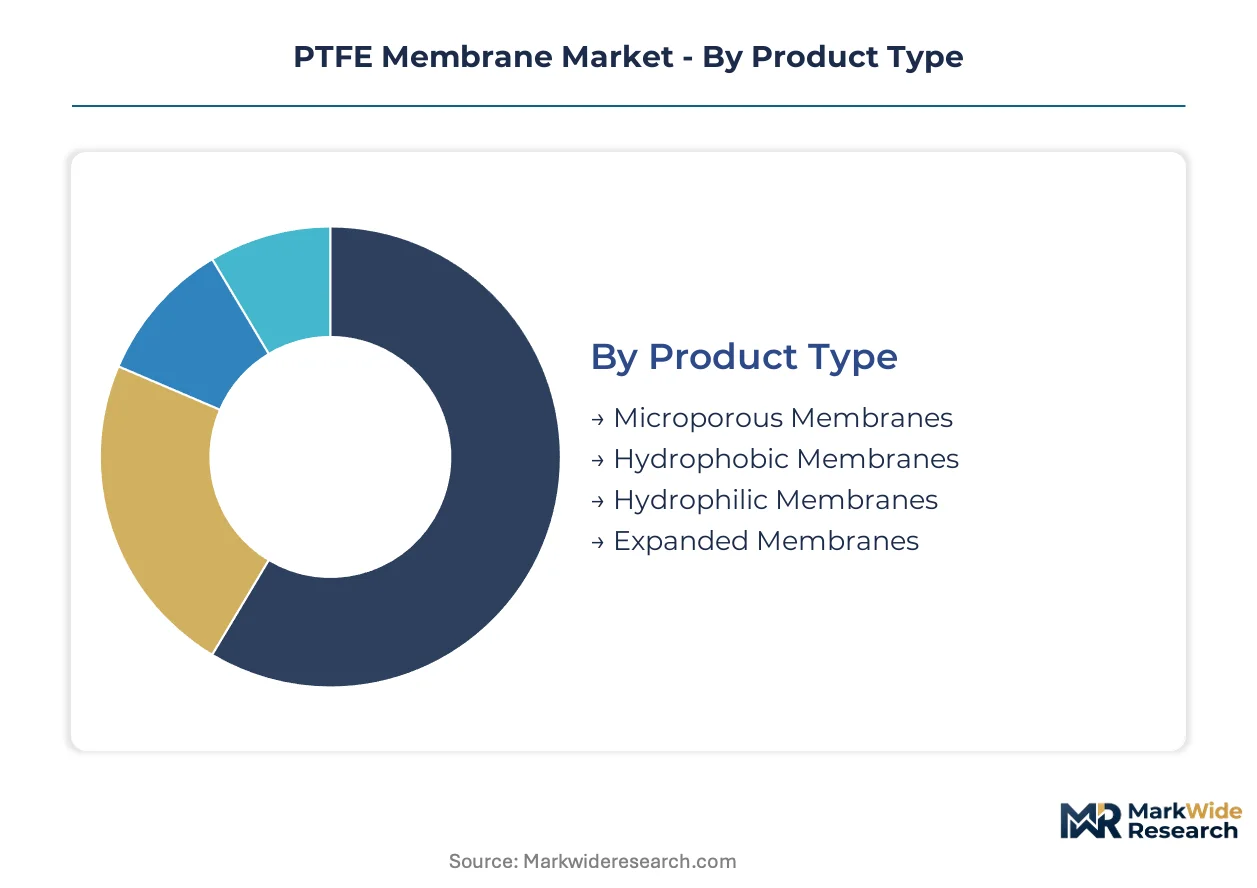
PTFE membranes are thin, porous films manufactured from polytetrafluoroethylene polymer, typically produced through mechanical stretching or phase-inversion processes to achieve pore sizes ranging from 0.02 to 10 micrometers, serving primarily as chemically inert barriers for filtration, separation, and protective venting across corrosive and high-purity process streams. Hydrophobic membranes command the largest revenue pool due to their dominance in industrial chemical processing and pharmaceutical venting, while hydrophilic variants represent the fastest-expanding category as drug manufacturers seek direct aqueous filtration without pre-wetting protocols. Expanded membranes occupy a specialized niche where mechanical durability under thermal cycling creates premium pricing power.
The EPA enforces stringent emissions controls that mandate PTFE-based filtration in chemical processing stacks, while the FDA governs biocompatibility and extractables testing for membranes contacting parenteral drugs. China's NMPA and GB standards increasingly dictate membrane qualification protocols for imported medical devices and semiconductor process equipment entering that market. Stakeholders must monitor evolving pharmaceutical purity standards and regional certification divergence to align R&D spending with addressable demand pools.
Market Dynamics
Biologics manufacturing expansion is compressing membrane qualification timelines as drug sponsors demand single-use filtration trains with validated extractables profiles. Contract manufacturers now specify membrane architecture during early-phase development, locking suppliers into multi-year qualification cycles before commercial scale-up begins.
Growth Catalysts
- FDA extractables testing mandates:Parenteral drug sponsors must document organic compound leach rates from all fluid-contact materials, accelerating replacement of legacy polypropylene with PTFE in high-purity venting.
- Semiconductor wet chemistry:Advanced node fabrication requires ultrapure chemical delivery systems where hydrophobic PTFE membranes prevent moisture ingress into aggressive acid and solvent process streams.
- China's dual carbon goals:MEE emissions standards for chemical processing stacks mandate PTFE-based filtration media to capture fluorinated process gases and particulate matter.
Market Restraints
- Fluorspar supply concentration:Acid-grade fluorspar feedstock for PTFE polymerization concentrates in Mexico and China, exposing processors to export quota volatility and freight cost spikes.
- Membrane architecture IP thickets:Expanded PTFE stretching protocols remain encumbered by patent estates held by incumbent fluoropolymer specialists, limiting new entrant process freedom.
- Per- and polyfluoroalkyl substance scrutiny:ECHA restriction proposals under REACH threaten downstream liability for PTFE membrane manufacturers serving European medical device and food contact applications.
Strategic Opportunities
- India's PLI scheme for medical devices:Domestic manufacturing incentives attract membrane converters to establish sterile packaging and filtration assembly operations near Hyderabad and Bangalore pharmaceutical clusters.
- Hydrophilic surface modification:Plasma grafting and chemical etching technologies enable direct aqueous filtration without ethanol pre-wetting, opening parenteral drug formulation applications previously served by PVDF and nylon.
- Cell and gene therapy viral vector filtration:Gene therapy sponsors require sterile venting and clarification membranes compatible with low-protein-binding requirements in plasmid and AAV manufacturing workflows.
Industry Challenges
- Polymer science talent scarcity:Fluoropolymer extrusion and biaxial stretching expertise concentrates among aging specialists in Japan and the United States, constraining capacity expansion at new manufacturing sites.
- Validation documentation burden:Biopharma sponsors require batch-specific extractables data, endotoxin testing, and particulate certification that extends membrane lot release timelines to eight weeks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PTFE Membrane Market |
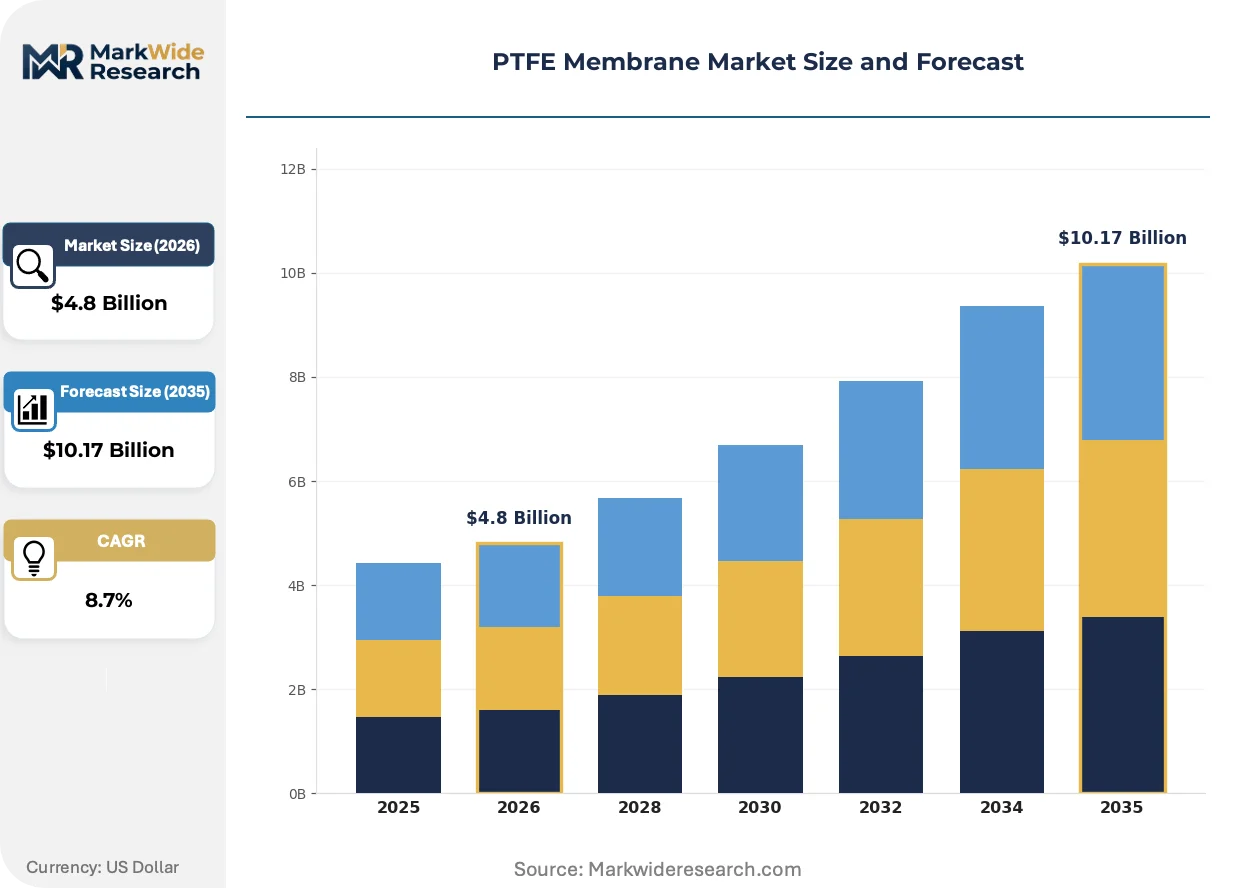
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microporous Membranes, Hydrophobic Membranes, Hydrophilic Membranes, Expanded Membranes Application: Filtration, Separation, Venting, Gasket Sealing End User: Pharmaceuticals, Medical Device, Food Processing, Electronics Technology: Membrane Technology, Coating Technology, Composite Technology, Ultrasonic Technology |
| Companies Covered | Saint-Gobain, Cytiva, W. L. Gore & Associates, Sumitomo Electric Industries, Ltd., Sartorius AG, Pall Corporation, Merck Millipore, Markel Corporation, Donaldson Company, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PTFE Membrane Market Emerging Trajectories
Membrane architecture is converging with digital process control as manufacturers embed sensors within filtration housings to monitor differential pressure and predict replacement cycles. This fusion of materials science and instrumentation compresses maintenance windows and reduces unplanned downtime in continuous bioprocessing.
Multi-layer composite membranes are unifying hydrophobic and hydrophilic functionality within single film structures, eliminating lamination steps in vent filter assembly. Gene therapy manufacturers in Boston and Basel are qualifying these integrated films for sterile gas filtration in single-use bioreactors. The technology is unifying what were previously separate procurement categories for process engineers, reducing vendor qualification overhead and simplifying supply chain management.
REACH F-Gas Regulation amendments are phasing down hydrofluorocarbon blowing agents used in PTFE foam production, forcing membrane manufacturers to qualify nitrogen expansion or mechanical stretching alternatives. European chemical processors must recertify filtration systems under updated MEE emissions protocols, accelerating membrane replacement cycles in Germany and the Netherlands. Medical device exporters to the EU are preemptively adopting fluoropolymer-free alternatives in non-critical applications to mitigate regulatory liability.
Biopharma procurement teams are consolidating membrane specifications across legacy small-molecule and emerging biologics portfolios, reducing qualified supplier lists from twelve vendors to four. Large molecule sponsors in North Carolina and Massachusetts now mandate single-source membrane architectures from clinical through commercial phases. This concentration is most visible in monoclonal antibody manufacturing, where platform process standardization drives specification harmonization across multiple drug candidates.
PTFE Membrane Market Segmentation
PTFE membrane specifications diverge sharply across purity grades and mechanical requirements, forcing suppliers to maintain parallel production lines for pharmaceutical venting versus industrial chemical processing. Procurement teams in biologics manufacturing now specify membrane architecture during early-phase development, locking qualification cycles years before commercial scale-up begins.
Product Type:
Customization intensity spans from commodity expanded films to precision-engineered hydrophilic surfaces requiring plasma grafting protocols.
- Hydrophobic Membranes:These films repel aqueous penetration without chemical pre-treatment, serving chemical processing stacks and pharmaceutical tank venting where moisture exclusion protects process integrity. Demand concentrates in China's semiconductor wet chemistry corridors, where fabs at Hsinchu and Shanghai mandate ultrapure acid delivery systems.
- Hydrophilic Membranes:Surface-modified through chemical etching or plasma grafting, these variants enable direct aqueous filtration without ethanol pre-wetting. Drug manufacturers in Massachusetts and North Carolina are qualifying these for parenteral formulation lines previously served by PVDF.
- Microporous Membranes:Engineered with pore sizes from 0.02 to 10 micrometers through mechanical stretching or phase-inversion processes.
- Expanded Membranes:Biaxially stretched PTFE films commanding premium pricing for thermal cycling durability in aggressive chemical environments.
Most installed capacity flows through Hydrophobic Membranes. Expansion is steepest in Hydrophilic Membranes.
Application:
Volume concentration tracks regulatory enforcement intensity, with emissions mandates in China and purity standards in the United States driving replacement cycles.
- Filtration:Clarification and sterilization of process fluids in biologics manufacturing, where FDA extractables testing mandates accelerate PTFE adoption over polypropylene in high-purity venting. China's MEE emissions standards for chemical processing stacks mandate PTFE-based media to capture fluorinated gases.
- Venting:Sterile gas exchange in single-use bioreactors and storage vessels, requiring hydrophobic barriers that prevent microbial ingress while equalizing pressure differentials. Gene therapy sponsors in Basel and Boston are qualifying integrated multi-layer films for AAV manufacturing workflows.
- Separation:Phase separation in corrosive process streams across chemical processing and electronics manufacturing.
- Gasket Sealing:Static sealing applications in aggressive chemical environments where elastomer degradation risks process contamination.
Filtration commands the largest revenue pool. Venting is gaining share fastest as single-use bioprocessing scales.
End User:
Customer sophistication varies from standardized industrial procurement to validated pharmaceutical supply chains requiring batch-specific documentation.
- Pharmaceuticals:Biologics manufacturers specifying membrane architecture during clinical-phase development, locking suppliers into multi-year qualification cycles before commercial scale-up. FDA parenteral drug regulations and EMA extractables guidelines drive specification harmonization across monoclonal antibody platforms.
- Electronics:Semiconductor fabs requiring ultrapure chemical delivery systems where hydrophobic membranes prevent moisture ingress into aggressive acid and solvent streams. China's advanced node fabrication investments at Hsinchu and Shanghai accelerate demand for high-purity venting solutions.
- Medical Device:Sterile packaging and implantable device applications where biocompatibility certification extends lot release timelines.
- Food Processing:Venting and filtration in aggressive cleaning environments, with EFSA and national regulators monitoring fluoropolymer contact compliance.
Pharmaceuticals absorb the majority of qualified supply. Electronics is climbing the fastest on semiconductor capacity expansion.
Technology:
Process control sophistication separates commodity converters from qualified pharmaceutical suppliers, with validation documentation burden extending lead times.
- Membrane Technology:Core mechanical stretching and phase-inversion processes producing porous films with controlled pore size distributions. Japan and United States specialists concentrate fluoropolymer extrusion expertise, constraining capacity expansion at new manufacturing sites.
- Composite Technology:Multi-layer structures unifying hydrophobic and hydrophilic functionality within single films, eliminating lamination steps in vent filter assembly. Gene therapy manufacturers are qualifying these integrated films for sterile gas filtration in single-use bioreactors.
- Coating Technology:Surface modification protocols for enhanced chemical resistance or protein binding reduction.
- Ultrasonic Technology:Bonding and sealing methods for membrane integration into filtration housings and device assemblies.
Membrane Technology anchors existing production. Composite Technology shows the steepest expansion trajectory as multi-layer films displace laminated alternatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's semiconductor fabrication investments outpace United States biologics capacity expansion, yet both geographies impose divergent regulatory burdens on membrane qualification timelines. The United States FDA extractables mandates compress vendor validation cycles, while China's NMPA and GB standards create parallel certification tracks for imported medical devices. Germany and Japan anchor European and Asian specialty chemical demand, with Switzerland and South Korea emerging as precision manufacturing clusters.
United States
FDA parenteral drug regulations and EPA emissions controls drive membrane replacement in pharmaceutical venting and chemical processing stacks. The agency's extractables testing mandates accelerate PTFE adoption over legacy polypropylene in high-purity applications. North Carolina's Research Triangle and Massachusetts' Greater Boston corridor concentrate monoclonal antibody manufacturing, where platform standardization forces specification harmonization across multiple drug candidates.
China
Semiconductor wet chemistry demand and MEE emissions standards for fluorinated process gases dominate procurement priorities. The country's dual carbon goals tighten enforcement of stack filtration requirements in chemical processing corridors. Shanghai and Hsinchu fabrication hubs mandate ultrapure acid delivery systems, where hydrophobic membranes prevent moisture ingress into aggressive solvent streams at advanced node facilities.
Germany
ECHA REACH restriction proposals on per- and polyfluoroalkyl substances create downstream liability exposure for medical device and food contact applications. The F-Gas Regulation amendments phase down hydrofluorocarbon blowing agents, forcing membrane manufacturers to qualify nitrogen expansion alternatives. The Rhine-Ruhr industrial belt and Bavarian chemical clusters recertify filtration systems under updated protocols, accelerating replacement cycles.
Japan
Fluoropolymer extrusion and biaxial stretching expertise concentrates among aging specialists, constraining capacity expansion at new manufacturing sites. METI industrial standards and JIS certification requirements govern membrane qualification for semiconductor and pharmaceutical exports. The Chubu region around Nagoya and Kansai corridor near Osaka host precision polymer processing facilities serving regional electronics and biologics supply chains.
India
The PLI scheme for medical devices attracts membrane converters to establish sterile packaging and filtration assembly operations near pharmaceutical clusters. CDSCO import substitution policies and domestic manufacturing incentives reshape procurement patterns for imported process equipment. Hyderabad and Bangalore biologics manufacturing corridors specify membrane architecture during early-phase development, locking suppliers into multi-year qualification cycles.
PTFE Membrane Market Vendor Landscape
United States producers anchor the premium qualification tier; Japanese specialists hold process technology advantages in precision stretching protocols. The vendor base separates into fluoropolymer heritage incumbents, bioprocessing-integrated filtration houses, and industrial chemical converters. Three archetypes dominate: platform-integrated suppliers capturing biologics workflows, materials-science purists commanding venting premiums, and diversified industrials competing on chemical processing volume. Consolidation concentrates procurement power among large biopharma houses, while contract manufacturing organizations fragment orders across specialized membrane suppliers.
Within the fluoropolymer heritage tier, W. L. Gore & Associates exemplifies materials-science positioning through its Delaware-rooted operations. Pall Corporation and Cytiva occupy the bioprocessing-integrated vector, representing platform-locked supply relationships with monoclonal antibody sponsors. Saint-Gobain anchors the diversified industrial segment, with its French corporate structure reflecting European chemical processing concentration. These three entities collectively illustrate how qualification depth, regulatory documentation capacity, and polymer science expertise partition addressable demand pools.
| Leading Market Players |
|---|
| Saint-Gobain |
| Cytiva |
| W. L. Gore & Associates |
| Sumitomo Electric Industries, Ltd. |
| Sartorius AG |
| Pall Corporation |
| Merck Millipore |
| Markel Corporation |
| Donaldson Company, Inc. |
| Others |
Supply Flow & Price Mechanics
Captive fluoropolymer resin production anchors supply positions and pricing power for heritage PTFE membrane manufacturers, with backward integration into acid-grade fluorspar processing insulating W. L. Gore and Japanese incumbents from Mexico-China export quota volatility that squeezes converters dependent on merchant polymer feedstock.
Pricing Analysis
Capacity additions in China's semiconductor corridors are reshaping price floors for high-purity hydrophobic membranes, yet pharmaceutical qualification documentation burdens sustain premium tiers for FDA-validated suppliers. Pricing stratifies across validated pharmaceutical-grade, industrial chemical-grade, and commodity venting tiers, with certification level and batch-specific extractables data commanding the steepest premiums. Cost compression in industrial-grade membranes is intensifying as Chinese converters scale expanded PTFE output for chemical processing stacks. Contract manufacturing organizations exhibit the sharpest price sensitivity, while monoclonal antibody sponsors prioritize single-source qualification depth over unit cost.
Supply Chain Analysis
Certification gating through FDA extractables protocols and China's NMPA medical device standards fragments supply chains into qualified pharmaceutical tiers and unqualified industrial channels. Acid-grade fluorspar concentrates in Mexico and China, PTFE polymerization expertise clusters in Japan and the United States, and membrane conversion capacity expands in India and Germany. Supply chain risk hinges on single-source vulnerability for pharmaceutical-grade resin qualified to specific drug sponsor extractables profiles. Distribution runs through direct bioprocessing platform partnerships for qualified tiers and industrial distribution networks for chemical processing applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
PTFE membrane economics favor margin expansion as hydrophilic surface modification technologies unlock premium parenteral drug applications previously served by lower-margin PVDF alternatives, compressing qualification timelines for suppliers with validated plasma grafting protocols.
For Market Incumbents: Hedge against per- and polyfluoroalkyl substance regulatory liability by accelerating fluoropolymer-free alternative qualification for non-critical European medical device applications, while deepening backward integration into captive fluorspar processing to defend polymer cost positions against Mexican export quota volatility. For New Entrants and Emerging Players: Launch via sterile packaging assembly partnerships near India's Hyderabad and Bangalore pharmaceutical clusters, exploiting PLI scheme incentives and CDSCO import substitution tailwinds to bypass entrenched qualification cycles in saturated North American monoclonal antibody markets. For Investors and Strategic Acquirers: Consolidation pressure builds where gene therapy viral vector filtration demands outstrip qualified membrane supply, with acquisition targets clustering among plasma surface modification specialists possessing validated low-protein-binding architectures for AAV manufacturing workflows. Watch for inflection signals in ECHA REACH restriction finalization timelines that would accelerate fluoropolymer-free substitution mandates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluorspar Processing | Captive acid-grade feedstock supply insulates PTFE polymerization costs from Mexico-China export quota volatility. |
| Plasma Grafting Technology Qualification | Surface modification protocols enable hydrophilic membrane penetration of parenteral drug formulation lines. |
| India PLI Manufacturing Footprint | Domestic sterile packaging assembly captures CDSCO import substitution incentives near Hyderabad clusters. |
| Multi-Layer Composite Film Development | Integrated hydrophobic-hydrophilic structures eliminate lamination steps for gene therapy single-use bioreactors. |
| Fluoropolymer-Free Alternative Portfolio | ECHA REACH restriction hedging opens non-critical medical device applications previously closed to PTFE. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with bioprocessing platform engineers, pharmaceutical procurement directors, fluoropolymer extrusion specialists, and chemical processing plant managers with secondary validation against FDA 510(k) filings, EPA emissions compliance databases, ECHA REACH restriction proposals, and customs trade flow records for acid-grade fluorspar and PTFE resin. Bottom-up membrane demand modeling by application and end-use segment was cross-checked against top-down fluoropolymer industry production capacity assessments.
Historical reference periods anchored volume and value projections across the modeling period, with segmentation dimensions spanning hydrophobic versus hydrophilic membrane type, pharmaceutical versus electronics versus chemical processing end-use, and validated versus unqualified supply tiers. CAGRs were derived from fitted growth curves incorporating semiconductor fabrication capacity expansion timelines, biologics manufacturing platform standardization rates, and regulatory enforcement intensity trajectories for emissions control and pharmaceutical purity mandates.
Several conditions sit outside the modeled scope, including unforeseen ECHA restriction scope expansion beyond current per- and polyfluoroalkyl substance proposals, abrupt fluorspar export policy shifts in China or Mexico, and gene therapy clinical trial failure rates that would compress viral vector filtration demand. A model refresh is warranted upon material change in FDA extractables testing protocol revisions or China's NMPA medical device import certification streamlining.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Membrane Materials
North America Single-Ply Membrane Market
Membrane Materials
Hollow Fibers Membrane Market
Membrane Materials
Polyarylsulfone (PAS) Market
Membrane Materials
Global Breathable Membranes Market
Membrane Materials
Oxygen Barrier Films Market
Membrane Materials
Global Membrane Water and Wastewater Treatment Market
Membrane Materials
Nanoporous Membranes Market
Membrane Materials
Global Membrane Structures Market
Membrane Materials
Global Polymer Nanomembrane Market
Membrane Materials
Global Membrane Separation Technology Market
Membrane Materials
Global Tubular Membranes Market
Membrane Materials
Breather Membranes Market
Membrane Materials
Single-Ply Membranes Market
Membrane Materials
Global Bitumen Membranes Market
Membrane Materials
Specialty Breathable Membranes Market
Membrane Materials
North America Roofing Membranes Market