
 Breather Membranes Market | 2026-2036
Breather Membranes Market Size, Share, and Industry Trends Forecast 2026-2036
Breather Membranes Market Analytics
Aftermarket service revenue for membrane inspection and replacement is reshaping margin distribution across the value chain. DuPont leverages its fluoropolymer heritage to sustain premium positioning in high-performance breathable barriers. Kingspan Group PLC anchors its competitive stance through integrated insulation-membrane systems for commercial envelopes. Soprema Group specializes in bituminous-compatible breather layers that dominate European roofing retrofit channels.
Breather membranes are thin, semi-permeable sheets engineered from polypropylene, polyethylene, or polyester substrates with microporous structures that permit water vapor diffusion while blocking liquid water ingress, typically rated at 0.01–0.1 mm thickness with vapor resistance values below 0.6 MNs/g. These materials serve primarily to manage moisture accumulation within wall and roof assemblies, preventing mold degradation and thermal bridging in conditioned buildings. Vapor-permeable products lead volume shipments across temperate climates where seasonal humidity differentials stress envelope durability. Polypropylene formulations represent the fastest-growing material category due to their recyclability and compatibility with automated construction workflows. Building construction applications concentrate the largest value pool, though roofing retrofits are gaining share as energy renovation mandates intensify across aging European housing stock.
REACH compliance in Europe and EPA construction material standards in the United States shape product formulation requirements, restricting certain phthalate plasticizers and mandating VOC emission disclosures for installed membrane systems. CE marking under the EU Construction Products Regulation governs market access for breathable underlays sold across member states, creating a harmonized testing baseline that non-European exporters must satisfy. Stakeholders must monitor evolving national building codes that are tightening airtightness targets and reclassifying membrane performance tiers, as these regulatory shifts will determine which material platforms and certification investments yield durable competitive advantage.
Market Dynamics
Energy-efficient envelope mandates across developed economies are compressing specification cycles for breather membranes, forcing manufacturers to validate performance under stricter airtightness regimes before products reach construction sites.
Growth Catalysts
- REACH Phase-Down of Hazardous Plasticizers:ECHA restrictions on phthalate-based additives accelerate migration toward polypropylene and polyester substrate platforms that bypass compliance costs.
- Roofing Retrofit Mandates:Germany's federal building energy efficiency regulations and France's RE2020 environmental code drive replacement demand across aging European housing stock.
- Automated Construction Workflows:Roll-fed membrane dispensing systems on commercial building sites favor polypropylene formulations with consistent tensile properties for robotic handling.
Market Restraints
- Petrochemical Feedstock Volatility:Polypropylene and polyethylene resin prices fluctuate with naphtha and natural gas liquid markets, compressing margin predictability for membrane converters.
- Regional Supply Concentration:European microporous film extrusion capacity clusters in Germany and Belgium, creating single-point vulnerability for just-in-time construction supply chains.
- Technical Performance Ceilings:Current microporous structures hit diffusion rate limits around 0.6 MNs/g vapor resistance, constraining applications in tropical high-humidity envelopes.
Strategic Opportunities
- CE Marking Harmonization Gaps:Non-European manufacturers lacking EU Construction Products Regulation certification face barrier-to-entry that accredited Asian producers can exploit for market share capture.
- Integrated Insulation-Membrane Systems:Convergence of vacuum insulation panels with vapor-permeable barriers opens specification channels in net-zero commercial envelopes.
- Aftermarket Inspection Services:Building envelope commissioning requirements under Germany's Energy Saving Ordinance create recurring revenue streams independent of new construction cycles.
Industry Challenges
- Multilayer Lamination Expertise Shortage:Skilled technicians capable of calibrating co-extrusion lines for sub-0.1 mm tolerance membranes command premium wages that smaller converters struggle to match.
- CE Marking Testing Backlogs:Notified body capacity constraints in France and Italy delay product launches by 8-14 months, freezing R&D amortization schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Breather Membranes Market |
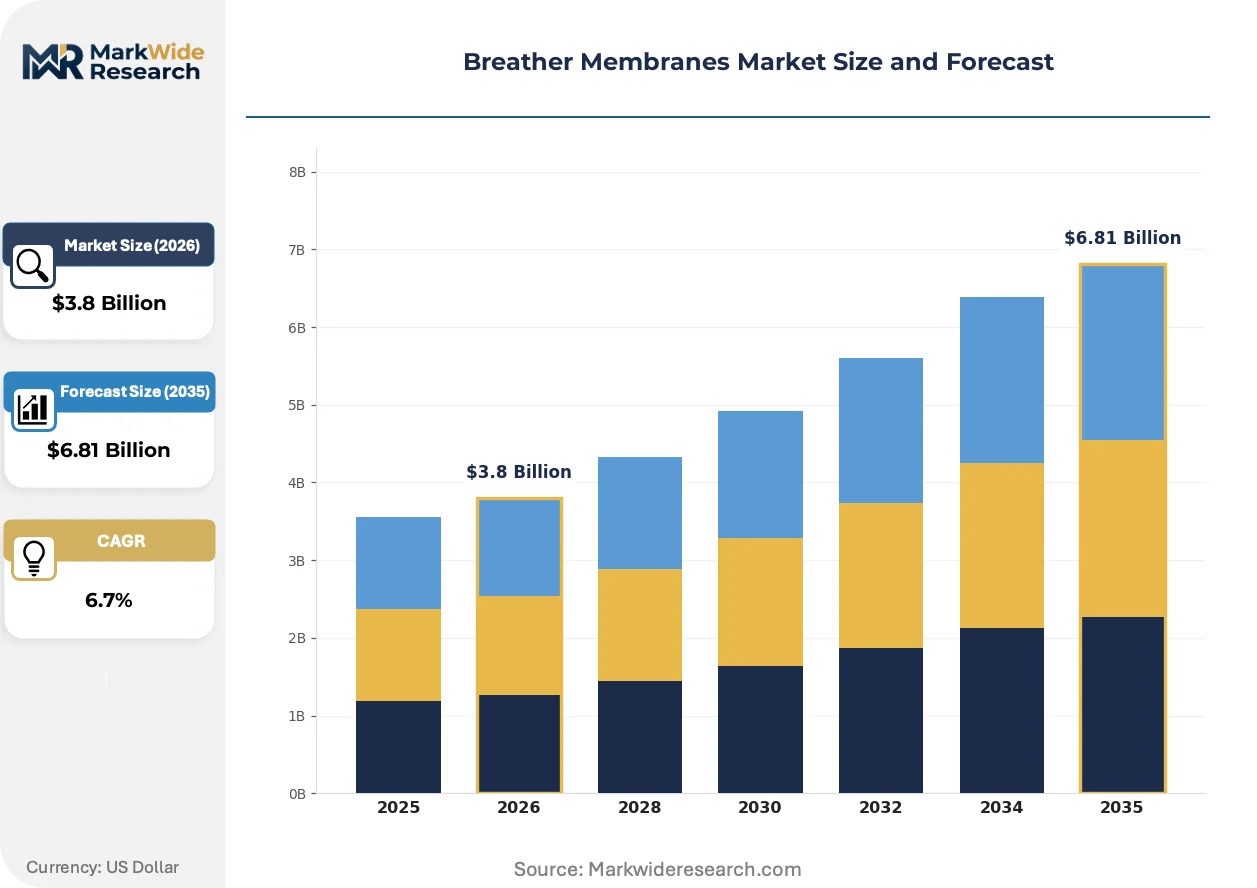
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vapor Permeable, Waterproof, Breathable, Insulating Material: Polypropylene, Polyethylene, Polyester, Fiberglass Application: Building Construction, Roofing, Walls, Packaging End User: Manufacturers, Contractors, Distributors, Retailers |
| Companies Covered | DuPont, RKW Group, PIL Membranes Ltd., Kingspan Group PLC, Saint-Gobain, Soprema Group, Klober, Nitto Denko Corporation, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Breather Membranes Market Evolving Landscape
Synthetic polymer engineering and regulatory chemistry are converging to redefine breather membrane performance tiers. Material scientists and building envelope specifiers now prioritize vapor diffusion rates alongside circular economy credentials.
Monolithic thermoplastic polyurethane films are hybridizing with traditional microporous polypropylene substrates to create continuous-pore structures that maintain liquid water resistance across wider temperature ranges. Commercial roofing contractors in Northern Europe specify these hybrid laminates for membrane integrity in freeze-thaw cycling conditions. The technology is hybridizing product categories that previously separated breathable underlays from waterproofing barriers, collapsing specification silos and forcing manufacturers to compete across both domains.
REACH authorization requirements for persistent organic pollutants now extend to perfluorinated compounds used in surface treatments for water repellency. ECHA's 2023 restriction proposal forces reformulation of durable water-repellent chemistries toward silicone and hydrocarbon alternatives. Membrane producers serving Scandinavian markets face accelerated retesting timelines as Sweden and Denmark adopt stricter national implementations ahead of EU harmonization deadlines.
Building envelope commissioning contracts now unbundle membrane performance warranties from general contractor liability, shifting risk assessment to specialized forensic engineering firms. Commercial developers in the United Kingdom and Netherlands engage these third-party validators during design phases to preempt airtightness test failures. This behavioral shift concentrates specification influence among a narrow tier of certified building physicists who prioritize tested vapor resistance data over manufacturer marketing claims.
Breather Membranes Market Segmentation
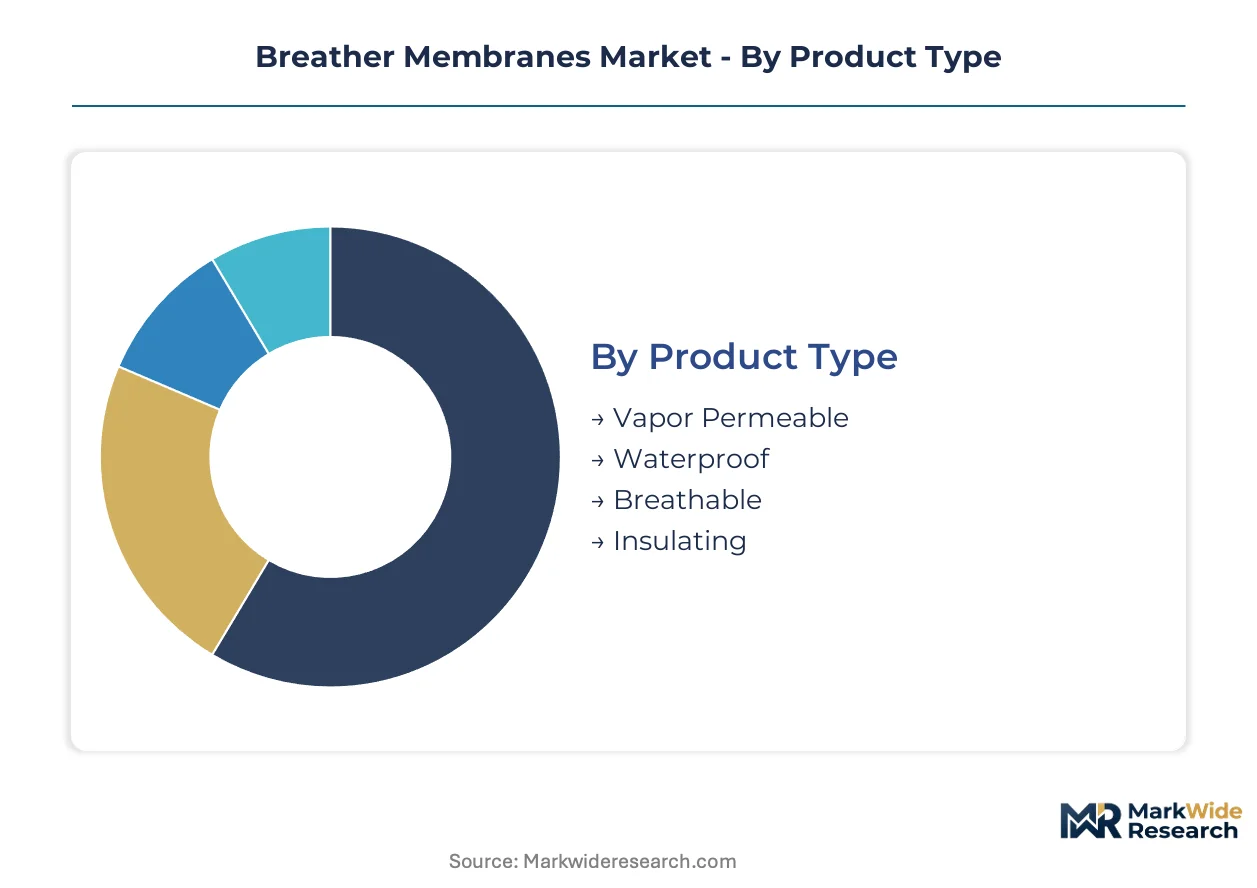
Breather membrane specification hinges on vapor resistance thresholds, substrate chemistry, and installation workflow compatibility. Procurement patterns diverge sharply between new construction and retrofit channels, with regulatory pressure compressing product lifecycles across all tiers.
Product Type:
Cost tier differentiation separates commodity underlays from performance-certified systems commanding specification premiums in airtightness-mandated envelopes.
- Vapor Permeable:Microporous polypropylene structures rated below 0.6 MNs/g vapor resistance dominate temperate climate wall assemblies. German Energy Saving Ordinance enforcement drives substitution of traditional bituminous felt in residential retrofits across Bavaria and North Rhine-Westphalia.
- Waterproof:Hybrid laminates combining thermoplastic polyurethane films with breathable substrates collapse the historical separation between moisture management and liquid barrier functions. Northern European roofing contractors specify these for freeze-thaw cycling integrity in commercial flat roof assemblies.
- Breathable:Standard microporous sheets serve cost-sensitive pitched roof applications where CE marking compliance satisfies minimum regulatory thresholds without premium performance validation.
- Insulating:Vacuum insulation panel integration creates composite envelope systems for net-zero commercial buildings in France and the Netherlands, though technical complexity limits adoption to specialized building physics consultants.
Vapor Permeable holds installed capacity. Waterproof is rotating up the share rankings.
Material:
Application requirements dictate substrate selection, with recyclability credentials and automated handling compatibility now filtering procurement decisions ahead of pure cost metrics.
- Polypropylene:Recyclable thermoplastic with consistent tensile properties enabling robotic roll-fed dispensing on commercial construction sites. REACH Phase-Down of hazardous plasticizers accelerates migration from phthalate-treated alternatives in German and Belgian extrusion clusters.
- Polyethylene:Lower-cost alternative for temporary weather protection and packaging applications where vapor resistance specifications remain permissive. UK housing association bulk procurement favors this tier for social housing roof replacements under national retrofit funding.
- Polyester:Higher mechanical strength suits mechanically fastened roofing systems in high-wind zones along France's Atlantic coast. ECHA restriction timelines on perfluorinated water repellents force accelerated reformulation toward silicone-based surface treatments.
- Fiberglass:Reinforced substrates serve fire-rated commercial envelope assemblies in London and Paris high-rise construction where building safety regulations mandate non-combustible membrane backings.
Polypropylene captures the steepest expansion trajectory as converters retool extrusion lines for circular economy compliance.
Application:
Volume concentration varies by construction cycle phase, with retrofit mandates redirecting shipment patterns toward replacement channels independent of new build permit volatility.
- Building Construction:Integrated wall and roof systems for residential and commercial envelopes. France's RE2020 environmental code and Germany's federal building energy efficiency regulations compress specification cycles for high-performance vapor control layers.
- Roofing:Pitched and flat roof underlays represent the largest value pool, with aging European housing stock driving replacement demand. UK commercial developers engage third-party envelope commissioning validators to preempt airtightness test failures.
- Walls:Timber frame and masonry cavity constructions in Scandinavian markets require hygrothermal modeling validation before membrane specification. Sweden's stricter national implementation of REACH restrictions accelerates retesting timelines.
- Packaging:Industrial protective wrapping for moisture-sensitive goods during transport. Lower performance thresholds permit polyethylene substitution, though sustainability reporting requirements increasingly demand recyclable substrate disclosure.
Building Construction anchors volume shipments. Roofing is climbing the fastest as energy renovation mandates intensify.
End User:
Customer type determines purchasing behavior, with specification influence concentrating among building physicists and forensic engineers as risk unbundling reshapes liability structures.
- Manufacturers:Integrated building product companies sourcing membrane substrates for composite insulation systems. Kingspan Group PLC and similar firms anchor demand through captive specification of insulation-membrane bundles.
- Contractors:Installation firms selecting membranes based on automated workflow compatibility and warranty terms. Roll-fed dispensing system adoption on German commercial sites favors polypropylene formulations with consistent tensile properties.
- Distributors:Regional stockists managing inventory for just-in-time construction supply chains. Single-point vulnerability from Belgian and German microporous film extrusion concentration shapes procurement hedging strategies.
- Retailers:Merchant outlets serving residential renovation DIY segments and small builder trade counters. Price sensitivity dominates, though CE marking awareness is rising among UK and Netherlands consumers.
Manufacturers hold specification control. Contractors are gaining share fastest as risk unbundling concentrates influence with installation validators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Microporous film extrusion capacity clusters heavily in Germany and Belgium, creating supply vulnerability for just-in-time construction supply chains across Western Europe. This concentration shapes procurement hedging strategies and redirects investment toward secondary production nodes.
Germany
Federal building energy efficiency regulations drive replacement demand across aging housing stock in Bavaria and North Rhine-Westphalia. The Energy Saving Ordinance enforces airtightness targets that compress specification cycles for high-performance vapor control layers. The Cologne-Düsseldorf corridor hosts major extrusion facilities serving Central European distribution networks.
United Kingdom
Commercial developers engage third-party envelope commissioning validators to preempt airtightness test failures in London and Southeast construction projects. National retrofit funding programs channel bulk procurement toward social housing roof replacements. Midlands distribution hubs manage inventory for just-in-time supply chains serving residential renovation channels.
France
The RE2020 environmental code redirects specification toward net-zero envelope systems in Île-de-France commercial development. ANSM and national building safety regulators tighten fire-rated membrane requirements for Paris high-rise construction. Atlantic coast wind zones around Nantes and Bordeaux drive demand for mechanically fastened roofing systems with higher tensile strength.
Sweden
Timber frame construction in Scandinavian markets requires hygrothermal modeling validation before membrane specification. Stricter national implementation of REACH restrictions accelerates retesting timelines for silicone-based water repellent formulations. Stockholm and Gothenburg building physics consultants concentrate specification influence for envelope commissioning contracts.
Netherlands
Vacuum insulation panel integration creates composite envelope demand in Randstad commercial net-zero buildings. Third-party forensic engineering firms unbundle membrane performance warranties from general contractor liability in Rotterdam and Amsterdam developments. Eindhoven Region automation suppliers serve roll-fed membrane dispensing systems for commercial construction sites.
Breather Membranes Market Competitive Landscape
Integrated building product conglomerates and specialized membrane converters split the market along specification control versus manufacturing efficiency lines. The vendor base concentrates around three strategic archetypes: captive specification bundlers, independent substrate specialists, and regional distribution-integrated fabricators. Consolidation pressures favor players with in-house polymer extrusion and multilayer lamination capabilities. Competitive moves center on backward integration into resin compounding and strategic partnerships with automated construction equipment suppliers.
Within the captive specification tier, Kingspan Group PLC and DuPont occupy positions that exemplify divergent approaches to envelope system integration. Soprema Group sits within the regional specialist archetype, leveraging bituminous compatibility expertise for European roofing retrofit channels. These three anchors represent how competitive positioning stratifies across integrated systems, material science heritage, and application-specific technical depth.
| Leading Market Players |
|---|
| DuPont |
| RKW Group |
| PIL Membranes Ltd. |
| Kingspan Group PLC |
| Saint-Gobain |
| Soprema Group |
| Klober |
| Nitto Denko Corporation |
| BASF SE |
| Others |
Value Network & Pricing Analysis
The Cologne-Düsseldorf corridor concentrates microporous film extrusion capacity for Central European distribution networks, granting incumbent converters pricing leverage over just-in-time construction supply chains dependent on German and Belgian production nodes. This geographic clustering amplifies margin capture for integrated manufacturers while exposing downstream distributors to single-source vulnerability during feedstock volatility cycles.
Pricing Analysis
Aftermarket inspection and membrane replacement services now drive lifetime value capture across the value chain. Three-tier pricing structure across premium, standard, and economy levels separates CE-marked performance tiers from commodity underlays, with certification grade and automated handling compatibility commanding specification premiums. Pricing pressure stems from petrochemical resin volatility compressing converter margins. Social housing procurement teams in the United Kingdom exhibit highest price sensitivity, while forensic engineering validators in the Netherlands and Germany prioritize tested performance data over cost minimization.
Supply Chain Analysis
REACH authorization requirements for persistent organic pollutants function as de facto export controls limiting technology flows from European extrusion clusters to non-compliant Asian producers. Polypropylene resin compounding draws from naphtha and natural gas liquid markets centered on German petrochemical complexes, with silicone-based water repellent formulations facing accelerated retesting timelines under ECHA restrictions. Single-source vulnerability from Belgian and German microporous film concentration creates structural risk for just-in-time construction supply chains. Distribution runs through regional stockists managing inventory hedging strategies for commercial building sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The breather membranes market sits in cyclical recovery as energy renovation mandates across aging European housing stock compress replacement cycles independent of new construction permit volatility.
For Market Incumbents: Pre-empt specification influence erosion by anching captive bundling relationships with insulation-membrane systems. Deepen backward integration into polypropylene resin compounding to offset feedstock volatility exposure. Accelerate multilayer lamination technician training programs to counter skilled calibration specialist shortages threatening production line uptime.
For New Entrants and Emerging Players: Pursue CE marking harmonization gaps as accredited Asian producers exploit barrier-to-entry for market share capture in underserved Southern European distribution channels. Target aftermarket inspection services in Germany and the Netherlands where building envelope commissioning requirements create recurring revenue streams decoupled from construction cycle volatility. Lead with robotic roll-fed dispensing compatibility to penetrate automated commercial construction workflows.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory compliance play because REACH Phase-Down timelines and national building code tightening reclassify membrane performance tiers every specification cycle. Target converters with in-house polymer extrusion and multilayer lamination capabilities positioned to amortize certification investments across tightening airtightness regimes. Watch ECHA restriction implementation velocity as the inflection signal determining which material platforms yield durable competitive advantage.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive polypropylene supply insulates margin predictability from naphtha volatility cycles. |
| CE Marking Certification Investment | EU Construction Products Regulation compliance unlocks specification access across member state procurement. |
| Automated Dispensing System Partnerships | Robotic roll-fed compatibility anchors specification preference on German commercial construction sites. |
| Aftermarket Service Capability Buildout | Envelope commissioning contracts under Germany's Energy Saving Ordinance generate recurring revenue. |
| Silicone-Based Water Repellent Reformulation | ECHA perfluorinated compound restrictions force retesting timelines that compliant producers can exploit. |
Research Methodology
Operator-level perspectives from membrane extrusion plant managers, building envelope commissioning engineers, commercial developer procurement leads, and regional distribution stockists anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews with secondary validation against customs and trade data, SEC filings from listed building product conglomerates, national building code regulatory databases, and ECHA restriction proposal documentation. Bottom-up shipment estimates from converter facilities triangulated against top-down construction permit and retrofit funding allocation data.
Scenario-bracketing around regulatory implementation timelines and petrochemical feedstock volatility shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include vapor resistance tier, substrate chemistry, installation workflow compatibility, and regional regulatory cluster. CAGRs derived from elasticity-adjusted demand curves incorporating building stock age profiles, energy efficiency mandate enforcement intensity, and automated construction equipment penetration rates. Forecast inputs weighted ECHA authorization timelines and national airtightness target trajectories.
Sensitivities concentrate around REACH restriction implementation velocity, microporous film extrusion capacity expansion decisions, and construction automation adoption curves. Forecasts reflect documented assumptions on regulatory harmonization progress and feedstock price regime stability. Material shifts in ECHA perfluorinated compound restriction scope or German federal building energy efficiency regulation enforcement intensity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Membrane Materials
Polyvinyl Butyral (PVB) Films and Sheets Market
Membrane Materials
North America Ceramic Membranes Market
Membrane Materials
Oxygen Barrier Materials Market
Membrane Materials
Global Gas Separation Membranes Market
Membrane Materials
Global Membrane Separation Technology Market
Membrane Materials
Nanoporous Membranes Market
Membrane Materials
Global Membrane Filters Market
Membrane Materials
North America Single-Ply Membrane Market
Membrane Materials
Global Microfiltration Membranes Market
Membrane Materials
Vapor Barrier Films Market
Membrane Materials
Asia Pacific Waterproofing Membrane Market
Membrane Materials
Membrane Polymers Market
Membrane Materials
Polysulfone Market
Membrane Materials
Membrane Touch Switch Material Market
Membrane Materials
Bitumen Waterproofing Membrane Market
Membrane Materials
Gas Barrier Membranes Market