
 High-Purity Epoxy Resin Market | 2026-2036
High-Purity Epoxy Resin Market Size, Share, and Industry Trends Forecast 2026-2036
High-Purity Epoxy Resin Market Foresight
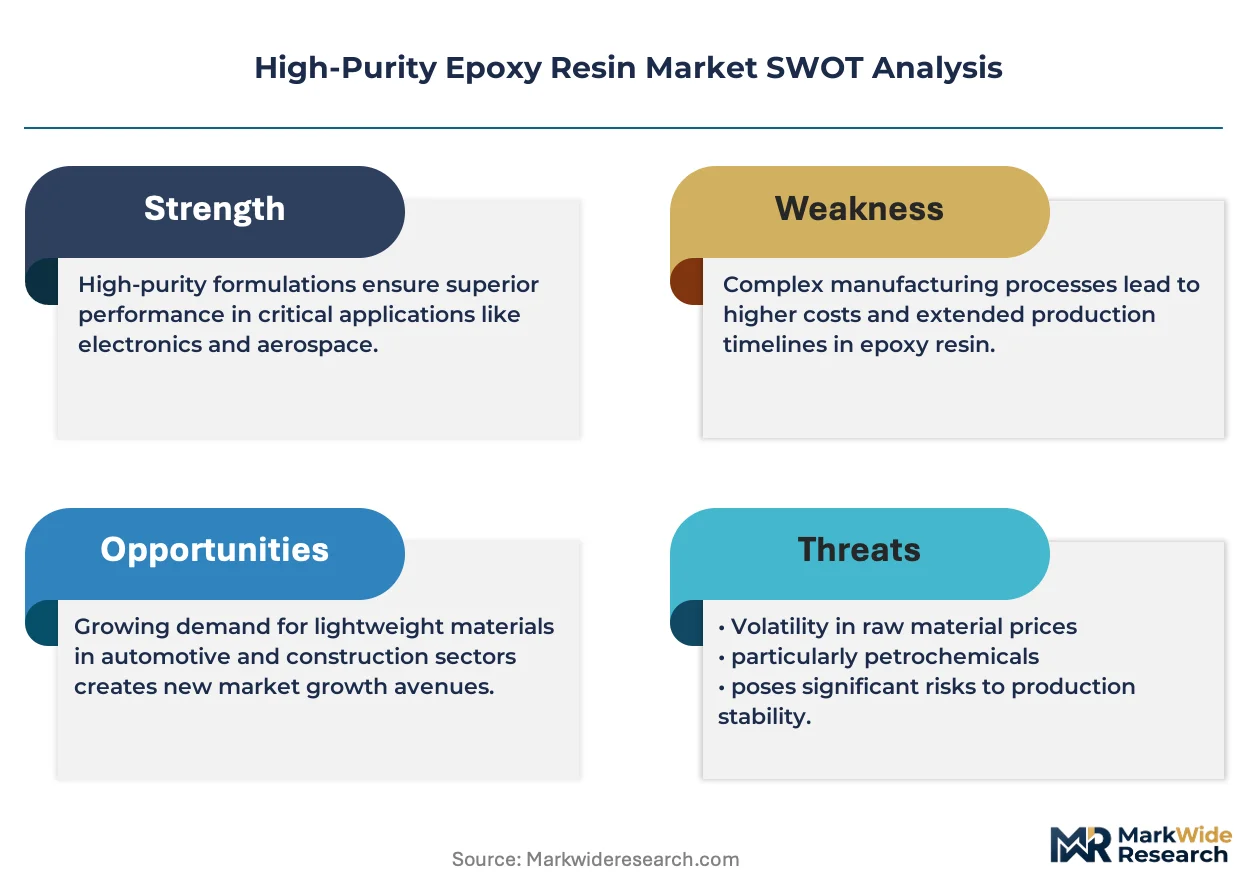
A shift from single-source to dual-source procurement of specialty monomers is restructuring supply relationships across the high-purity epoxy resin value chain. Merck KGaA leverages captive bisphenol purification to sustain margin control in electronic-grade formulations. Albemarle Corporation anchors North American supply through integrated flame-retardant precursor production. HOKKO CHEMICAL INDUSTRY CO., LTD. competes on episulfide-based ultra-low chlorine specifications for advanced semiconductor molding compounds.
High-purity epoxy resin denotes epoxide polymers refined to sub-ppm ionic and halogen contamination, typically achieved through multi-stage crystallization, molecular distillation, or catalytic hydrogenation of standard diglycidyl ether intermediates. These materials serve primarily as thermoset matrices in semiconductor encapsulation, printed circuit board laminates, and aerospace structural composites where electrical insulation integrity and thermal stability are critical. Liquid-grade formulations dominate current volume owing to their compatibility with automated dispensing systems in chip packaging, while solid-grade segments command premium pricing in high-layer-count PCB applications where viscosity control during hot-melt processing determines yield. Hybrid grades that blend cycloaliphatic and bisphenol-F chemistries represent the fastest-expanding category as substrate designers pursue balanced dielectric performance and moisture resistance.
EPA regulations on halogenated flame retardants and REACH restrictions on chlorinated intermediates are elevating compliance costs for non-integrated compounders while creating preferential market access for producers with certified low-halogen product lines. FDA oversight of indirect food-contact coatings and IEC standards for electrical insulation materials further segment qualification requirements across end-use applications. Stakeholders must monitor evolving purity specifications from semiconductor foundries and assess backward integration into specialty epichlorohydrin refining as a defensive capability against feedstock volatility.
Market Dynamics
Semiconductor foundries are consolidating their supplier base around ultra-low halogen specifications, forcing resin compounders to invest in captive purification infrastructure or exit electronic-grade supply entirely.
Growth Catalysts
- Advanced Packaging Migration:Chiplet architectures and 3D stacking in Pyeongtaek and Yongin clusters are consuming higher volumes of liquid-grade molding compounds with sub-ppm ionic thresholds.
- REACH RoHS Convergence:Tightening European purity thresholds for imported resins are locking out non-compliant Asian compounders and creating preferential access for certified low-halogen producers.
- Hybrid Chemistry Adoption:Substrate designers blending cycloaliphatic and bisphenol-F chemistries are opening new formulation windows balancing dielectric performance against moisture resistance.
Market Restraints
- Epichlorohydrin Volatility:Feedstock price swings tied to propylene-chlorine integration economics compress margin predictability for non-integrated compounders.
- Specialty Monomer Concentration:Dual-source procurement remains structurally limited by the small number of qualified ultra-pure bisphenol-A and bisphenol-F refiners in Japan and Germany.
- Flame-Retardant Substitution Ceiling:Phosphorus-based alternatives face thermal stability limits in high-layer-count PCB applications, trapping designers in halogenated systems despite regulatory pressure.
Strategic Opportunities
- India Semiconductor Mission:Domestic packaging investments in Gujarat and Karnataka are creating first-mover advantages for resin suppliers qualifying with local OSATs before supply lines harden.
- Aerospace Composite Qualification:Out-of-autoclave processing for satellite structures is validating high-purity epoxy prepregs with NASA and ESA outgassing certifications.
- Green Chemistry Incentives:EU Green Deal funding streams for bio-based epichlorohydrin routes are subsidizing capital costs for hydrogenation-capable refiners.
Industry Challenges
- Analytical Metrology Bottleneck:Sub-ppb detection of ionic contaminants requires inductively coupled plasma mass spectrometry capabilities that few compounders possess in-house.
- Foundry Qualification Timelines:TSMC and Samsung validation cycles for new resin grades extend 18-24 months, freezing formulation innovation windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High-Purity Epoxy Resin Market |
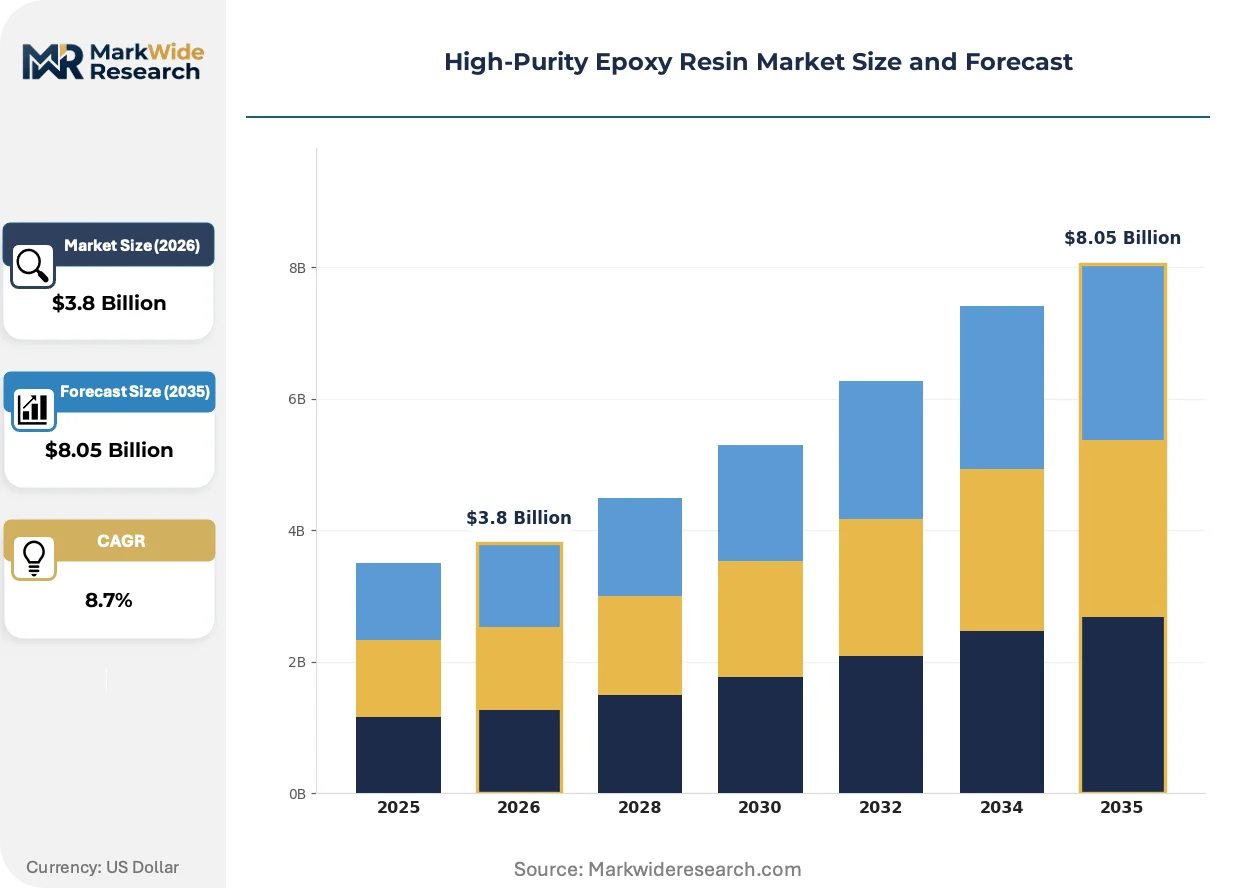
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Solid, Hybrid, Coating Application: Aerospace, Electronics, Automotive, Construction End User: Manufacturers, Contractors, Distributors, Retailers Market Segment: Industrial, Commercial, Residential, Others |
| Companies Covered | HOKKO CHEMICAL INDUSTRY CO., LTD., FAR Chemical, Merck KGaA, Boulder Scientific Group, PMC Group, Inc., Albemarle Corporation, CHEMIUM srl, Neogen Chemicals Ltd., WeylChem International GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High-Purity Epoxy Resin Market Shifts & Advancements
Multi-stage purification technologies and alternative synthesis routes are compressing the viable supplier set while enabling performance thresholds previously unattainable with conventional distillation.
Episulfide-based cycloaliphatic resins is electrifying the ultra-low chlorine segment by achieving sub-10 ppm halogen levels without sacrificing thermal stability. Advanced packaging houses in South Korea are qualifying these materials for memory chip molding compounds at accelerated timelines. The technology is electrifying competitive positioning by rendering legacy hydrogenation routes economically marginal for sub-20 ppm specifications.
REACH restrictions on chlorinated intermediates and EPA scrutiny of halogenated flame retardants are forcing compounders to revalidate entire formulation libraries. European importers now face documentary evidence requirements for ppm-level certification that non-integrated Asian suppliers struggle to satisfy. Solid-grade PCB laminates are absorbing the steepest compliance cost inflation as hot-melt viscosity specifications tighten simultaneously.
Dual-source contracting for specialty monomers is replacing sole-source relationships as procurement risk management takes priority over volume discounts. Semiconductor packaging manufacturers are inserting audit rights over bisphenol purification steps directly into supply agreements. This behavioral shift is most visible in South Korea, where Samsung and SK Hynix procurement teams are qualifying secondary Japanese refiners for electronic-grade bisphenol-F supply.
High-Purity Epoxy Resin Market Segmentation
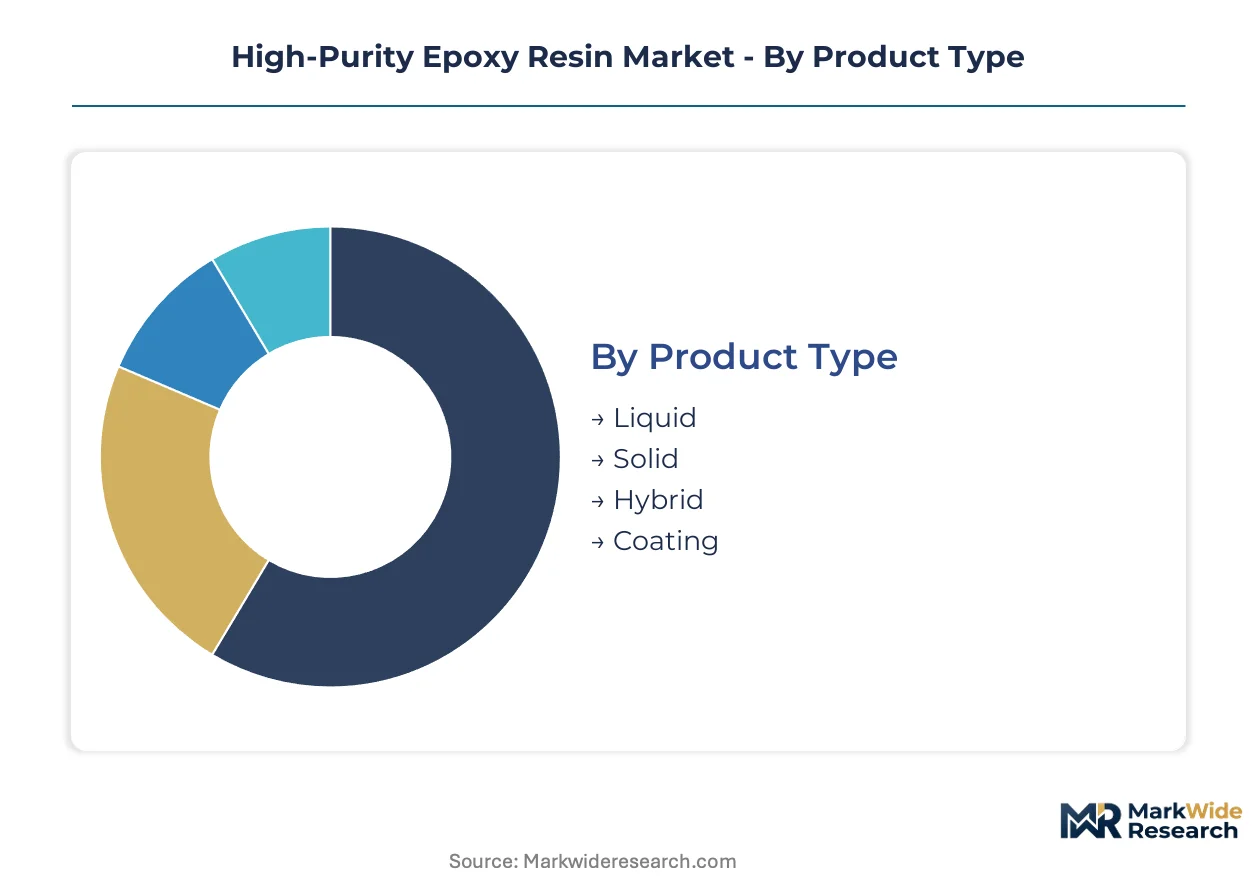
High-purity epoxy resin segmentation tracks how purity thresholds, processing methods, and qualification requirements split demand across incompatible use cases. Semiconductor foundries, aerospace primes, and automotive tier-1s each enforce distinct contamination limits that reshape supplier economics.
Product Type:
Liquid-grade formulations absorb the majority of volume owing to automated dispensing compatibility, while hybrid chemistries capture expanding share in premium substrate applications.
- Liquid:Low-viscosity diglycidyl ether formulations enable precision dispensing in chip packaging equipment. Demand concentrates in South Korea's Pyeongtaek and Yongin semiconductor clusters where Samsung and SK Hynix molding compound specifications require sub-ppm ionic thresholds for memory device encapsulation.
- Solid:Hot-melt processable resins with controlled molecular weight distribution serve high-layer-count PCB laminates. REACH and RoHS compliance costs in Europe are compressing margins for non-integrated compounders supplying German and French laminate producers.
- Hybrid:Cycloaliphatic-bisphenol-F blends balance dielectric constant against moisture absorption in advanced substrate designs.
- Coating:Solvent-borne and powder systems for corrosion protection in industrial infrastructure.
Mature deployment sits with Liquid grades in established semiconductor packaging. Newer deployment is concentrated in Hybrid formulations for next-generation chiplet architectures.
Application:
Electronics dominates revenue concentration, though aerospace qualification timelines are extending contract durations and pricing power.
- Electronics:Semiconductor encapsulation, PCB laminates, and passive component coatings require progressively tighter halogen specifications. TSMC and Samsung validation cycles spanning 18-24 months lock qualified suppliers into multi-year supply agreements with limited price renegotiation.
- Aerospace:Out-of-autoclave prepregs for satellite structures demand NASA and ESA outgassing certifications. Episulfide-based ultra-low chlorine resins from Japanese suppliers are penetrating this segment at accelerated qualification timelines.
- Automotive:Battery module encapsulation and power electronics thermal management.
- Construction:Structural adhesives and corrosion-resistant coatings for infrastructure.
Electronics commands the steepest purity premiums. Aerospace is climbing the fastest as satellite constellation deployment accelerates.
End User:
Direct procurement by manufacturers is displacing distributor channels as foundries impose audit rights over upstream purification steps.
- Manufacturers:Semiconductor packaging houses and laminate producers source electronic-grade resins under dual-source contracts with direct bisphenol purification oversight. Samsung and SK Hynix procurement teams in South Korea are qualifying secondary Japanese refiners to reduce sole-source dependency.
- Contractors:Construction and infrastructure project specialists.
- Distributors:Technical chemical distributors serving mid-tier electronics assemblers.
- Retailers:Limited presence given certification requirements.
Procurement centralization favors Manufacturers with in-house analytical metrology. Distributor relevance persists in lower-specification construction applications.
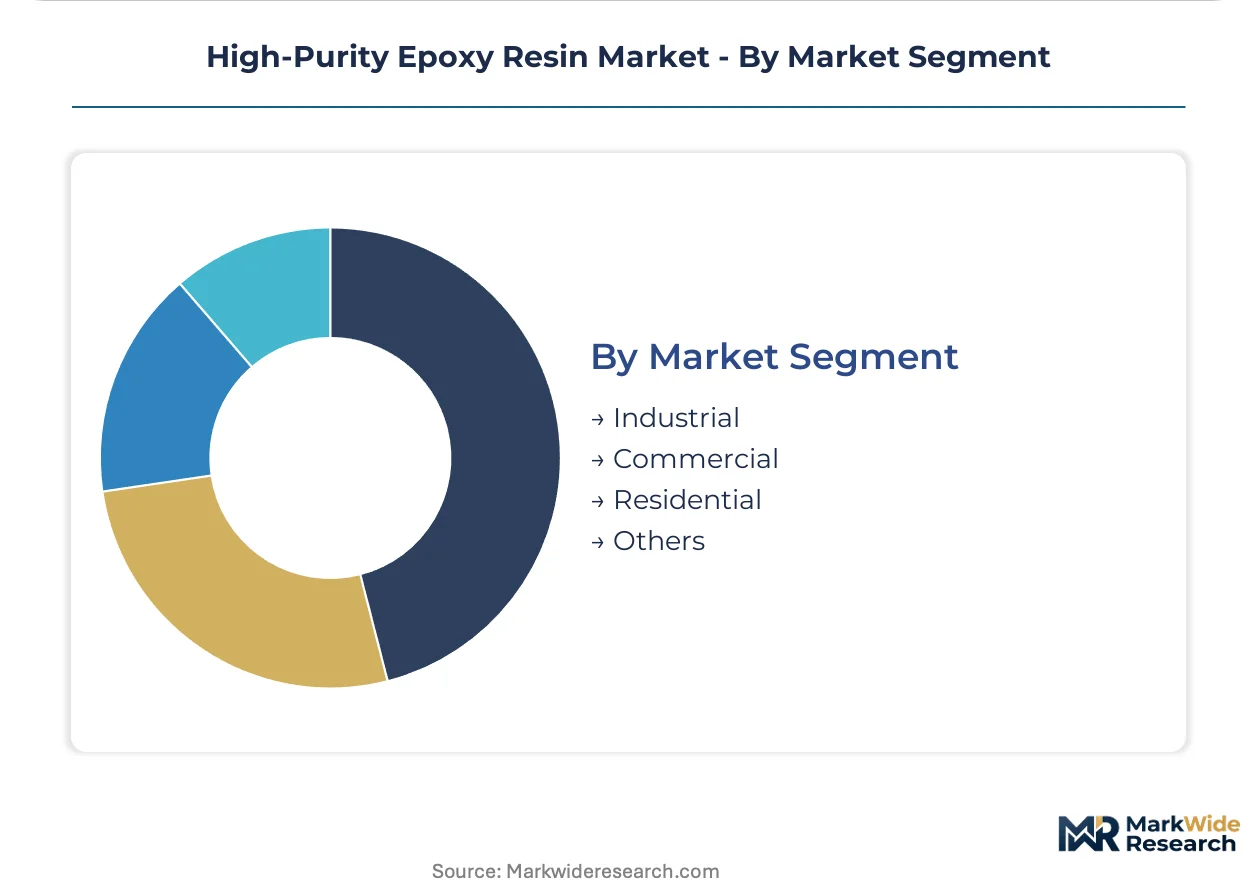
Market Segment:
Industrial-grade specifications absorb volume, though commercial segments are tightening purity thresholds as data center and telecommunications infrastructure upgrades accelerate.
- Industrial:Semiconductor fabrication, aerospace manufacturing, and automotive production lines constitute the core demand base. EPA regulations on halogenated flame retardants and REACH restrictions on chlorinated intermediates are elevating compliance costs for compounders serving multi-jurisdictional customers.
- Commercial:Data center infrastructure and telecommunications equipment.
- Residential:Minimal penetration given performance requirements.
- Others:Research institutions and specialty equipment producers.
Industrial segments anchor current revenue. Commercial applications are expanding most quickly as hyperscale data center construction drives substrate demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Epichlorohydrin refining capacity concentrates in Germany and Japan, anchoring the upstream supply geography for electronic-grade epoxy intermediates. These locations feed compounders serving semiconductor clusters across three continents.
South Korea
Samsung and SK Hynix are expanding orders for ultra-low halogen molding compounds in Pyeongtaek and Yongin. The Korea Ministry of Trade, Industry and Energy (METI-equivalent) supports domestic material localization under the K-Semiconductor Belt initiative. Foundry procurement teams are qualifying secondary Japanese bisphenol refiners to reduce sole-source dependency.
Germany
Merck KGaA leverages captive bisphenol purification to supply laminate producers in Bavaria and Baden-Württemberg. REACH and RoHS compliance thresholds are tightening purity requirements for imported resins. The Eindhoven-Twente corridor across the Dutch border absorbs German electronic-grade output for advanced packaging applications.
United States
Albemarle Corporation anchors North American supply through integrated flame-retardant precursor production in the Southeast. EPA regulations on halogenated flame retardants are elevating compliance costs for compounders serving multi-jurisdictional customers. NASA and ESA outgassing certification work for aerospace prepregs concentrates in Colorado and California satellite manufacturing corridors.
Japan
HOKKO CHEMICAL INDUSTRY CO., LTD. competes on episulfide-based ultra-low chlorine specifications from Chubu region facilities. METI industrial standards for electronic materials enforce sub-ppm ionic contamination thresholds. The Nagoya-Osaka manufacturing belt supplies advanced semiconductor molding compounds to South Korean packaging houses at accelerated qualification timelines.
India
Domestic packaging investments in Gujarat and Karnataka are creating first-mover advantages for resin suppliers qualifying with local OSATs. The India Semiconductor Mission allocates capital subsidies for materials ecosystem development. Neogen Chemicals Ltd. and other specialty chemical producers are positioning for foundry validation cycles before supply lines harden.
High-Purity Epoxy Resin Market Competitive Landscape
Capacity expansion dominates the current landscape as compounders invest in captive purification infrastructure to meet foundry qualification requirements. The supplier base segments into three tiers: integrated chemical conglomerates with upstream bisphenol control, mid-scale specialists with episulfide or hydrogenation capabilities, and regional compounders serving industrial-grade applications. Strategic archetypes include backward-integrated refiners, technology-licensing specialists, and geography-focused qualifiers. M&A activity and dual-source contracting are the principal competitive moves reshaping supply relationships.
Among integrated chemical conglomerates, Merck KGaA and Albemarle Corporation exemplify the backward-integrated archetype with captive control over critical feedstock purification. HOKKO CHEMICAL INDUSTRY CO., LTD. occupies a specialist position within the ultra-low chlorine segment, representing the technology-differentiated tier that competes on specification rather than scale. These three anchors illustrate how competitive positioning stratifies between upstream control, specialty chemistry expertise, and foundry qualification depth.
| Leading Market Players |
|---|
| HOKKO CHEMICAL INDUSTRY CO., LTD. |
| FAR Chemical |
| Merck KGaA |
| Boulder Scientific Group |
| PMC Group, Inc. |
| Albemarle Corporation |
| CHEMIUM srl |
| Neogen Chemicals Ltd. |
| WeylChem International GmbH |
| Others |
Supply & Pricing Matrix
Semiconductor packaging houses in South Korea and Taiwan concentrate procurement power, enforcing contract-based long-term offtake agreements that lock in volume commitments against foundry qualification timelines. This buyer concentration elevates pricing power for certified suppliers while squeezing margins for non-integrated compounders lacking captive bisphenol purification.
Pricing Analysis
Certification-grade warranties bundle analytical metrology documentation and regulatory compliance guarantees into base pricing, with unbundled spot purchases carrying substantial risk premiums. Three-tier pricing structure across electronic-grade, industrial-grade, and coating-grade levels separates qualified foundry suppliers from construction-focused distributors. Cost compression in industrial-grade segments is intensifying because REACH documentation requirements now demand sub-ppm certification that regional compounders cannot self-verify. Construction contractors exhibit highest price sensitivity, while aerospace primes absorbing NASA outgassing certification costs show lowest elasticity.
Supply Chain Analysis
Reverse-logistics flows for spent analytical standards and expired certification batches create specialized handling requirements that concentrate with German and Japanese refiners possessing in-house ICP-MS capabilities. Epichlorohydrin feedstock draws from propylene-chlorine integration economics in Germany, Japan, and the United States, with specialty bisphenol-A and bisphenol-F monomers sourcing from captive purification operations in Bavaria and Chubu. Single-source vulnerability pervades ultra-pure monomer supply, as only three qualified refiners globally meet sub-ppb ionic thresholds. Distribution runs through direct manufacturer contracts with audit rights over upstream steps, displacing traditional distributor channels in electronic-grade segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ultra-low halogen purification capacity operates at binding constraints, with foundry qualification timelines extending 18-24 months and freezing supplier switching. This bottleneck props pricing premiums for certified incumbents while elevating barriers for aspirants.
For Market Incumbents: Anchor defensive positioning through backward integration into specialty epichlorohydrin hydrogenation and episulfide chemistry capabilities. Threats from episulfide-based ultra-low chlorine substitutes render legacy hydrogenation routes economically marginal; incumbents should prioritize captive bisphenol-F purification investments in Japan or Germany to sustain margin control against emerging Japanese specialists. For New Entrants and Emerging Players: Begin with qualification in India's Gujarat and Karnataka semiconductor packaging corridors before Samsung and SK Hynix procurement teams harden supply lines around incumbent relationships. The most penetrable white-space sits with domestic OSATs under India Semiconductor Mission capital subsidies; pursue foundry validation cycles through episulfide-based formulations that bypass hydrogenation capital intensity. For Investors and Strategic Acquirers: The window for entry favors technology-differentiated mid-scale specialists with episulfide or advanced hydrogenation capabilities over commodity-scale compounders. Long-term viability centers on regulatory certification depth rather than volume scale. Watch for EPA enforcement actions on halogenated flame retardants as inflection signal accelerating phosphorus-substitution chemistry adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bisphenol Purification | Merck KGaA's captive Bavarian refining sustains margin control against feedstock volatility. |
| Episulfide Chemistry Scale-Up | HOKKO CHEMICAL's Chubu facilities achieve sub-10 ppm halogen without hydrogenation capital burden. |
| Dual-Source Contracting Expansion | Samsung procurement teams qualify secondary Japanese refiners to reduce sole-source dependency. |
| India OSAT Qualification | Neogen Chemicals positions for Gujarat foundry validation before supply lines harden. |
| Green Chemistry Certification | EU Green Deal subsidies for bio-based epichlorohydrin routes reduce hydrogenation-capable refiner capital costs. |
Research Methodology
Multi-period observation of foundry qualification timelines, REACH compliance threshold evolution, and epichlorohydrin price volatility anchored the trend analysis, supplemented by interviews with semiconductor packaging procurement managers, specialty chemical plant managers, epoxy resin R&D directors, and aerospace composite qualification engineers. Secondary validation drew from ECHA REACH registration databases, SEC 10-K filings of integrated chemical conglomerates, Japan Chemical Industry Association trade statistics, and Korea Trade-Investment Promotion Agency import records. Bottom-up segment sizing triangulated against top-down chemical industry consumption estimates.
Segment-weighting across liquid-grade, solid-grade, and hybrid chemistry formulations calibrated the analytical framework, with purity tier and end-use industry as orthogonal dimensions. Electronics, aerospace, automotive, and construction applications received distinct contamination-limit coefficients. CAGRs derived from elasticity-adjusted demand projections tied to semiconductor packaging capital expenditure cycles and PCB laminate layer-count trends. Forecast inputs incorporated EPA regulatory enforcement probability and EU Green Deal subsidy allocation trajectories.
Underlying measurement precision varies by segment; semiconductor encapsulation grades carry tighter precision than construction coating applications due to foundry audit documentation density. Forecasts reflect assumptions about REACH threshold stability and epichlorohydrin supply continuity that regulatory acceleration or feedstock disruption could revise. Practitioners should monitor EPA enforcement calendars and India Semiconductor Mission subsidy disbursement rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Global Impregnating Resins Market
Polymers & Resins
Thermoplastic Micro Molding Market
Polymers & Resins
Global Specialty Polystyrene Resin Market
Polymers & Resins
Asia-Pacific Polyvinylpyrrolidone (PVP) Market
Polymers & Resins
Natural Polymers Market
Polymers & Resins
Solid-Grade Thermoplastic Acrylic (Beads) Resin Market
Polymers & Resins
South America Engineering Plastics Market
Polymers & Resins
Germany Polymer Emulsion Market
Polymers & Resins
Hydrocarbon Resins Market
Polymers & Resins
Global Polyolefin Resins Market
Polymers & Resins
Isosorbide-Based Engineering Polymer Monomers Market
Polymers & Resins
Global Epoxy Primer Market
Polymers & Resins
Polyimide Resin Market
Polymers & Resins
Conductive Polymers Market
Polymers & Resins
Global PEEK Market
Polymers & Resins
Europe Geopolymer Market