
 South America Polyethylene Terephthalate (PET) Resin Market | 2026-2036
South America Polyethylene Terephthalate (PET) Resin Market Size, Share, and Industry Trends Forecast 2026-2036
South America Polyethylene Terephthalate (PET) Resin Market Analytics
Food-grade resin specifications is redrawing competitive boundaries across the South America PET resin landscape. Alpek, S.A.B. de C.V. leverages its captive PTA supply to secure feedstock cost advantages. Indorama Ventures Public Company Limited anchors regional capacity through integrated PET polymerization assets in Brazil. DAK Americas differentiates via bottle-grade resin specialization for carbonated soft drink bottlers.
Polyethylene terephthalate resin is a thermoplastic polyester synthesized through esterification of terephthalic acid with ethylene glycol, yielding a polymer with intrinsic viscosity typically ranging from 0.70 to 0.84 dL/g for bottle-grade applications. Its primary commercial purpose centers on producing lightweight, barrier-enhanced packaging for carbonated beverages, edible oils, and personal care products. Blow molding dominates application-level value capture due to its alignment with high-volume beverage bottling infrastructure. Packaging end users command the largest demand block, while film and sheet extrusion represents the fastest-expanding product type as flexible food packaging requirements intensify.
ANVISA governs food-contact polymer purity standards in Brazil, directly elevating compliance costs for imported resin batches. The country's national environmental regulator enforces post-consumer PET recycling quotas that reshape raw material sourcing for domestic converters. REACH-aligned substance restrictions from Mercosur trade negotiations further filter permissible additive chemistries. Stakeholders must track regulatory divergence between Brazilian federal standards and emerging provincial recycling mandates across Argentina and Chile.
Market Dynamics
ANVISA's tightening food-contact purity standards are forcing converters to requalify resin suppliers, while southeastern Brazil's manufacturing corridor concentrates production capacity and bottler procurement power.
Growth Catalysts
- Beverage bottling infrastructure:Carbonated soft drink and bottled water packaging lines across São Paulo and Minas Gerais states absorb volume-grade resin at scale.
- Recycled content mandates:Brazil's national environmental regulator enforces post-consumer PET quotas that pull rPET into virgin resin formulations.
- Flexible packaging conversion:Film and sheet extrusion for edible oils and personal care products expands addressable resin tonnage beyond blow molding.
Market Restraints
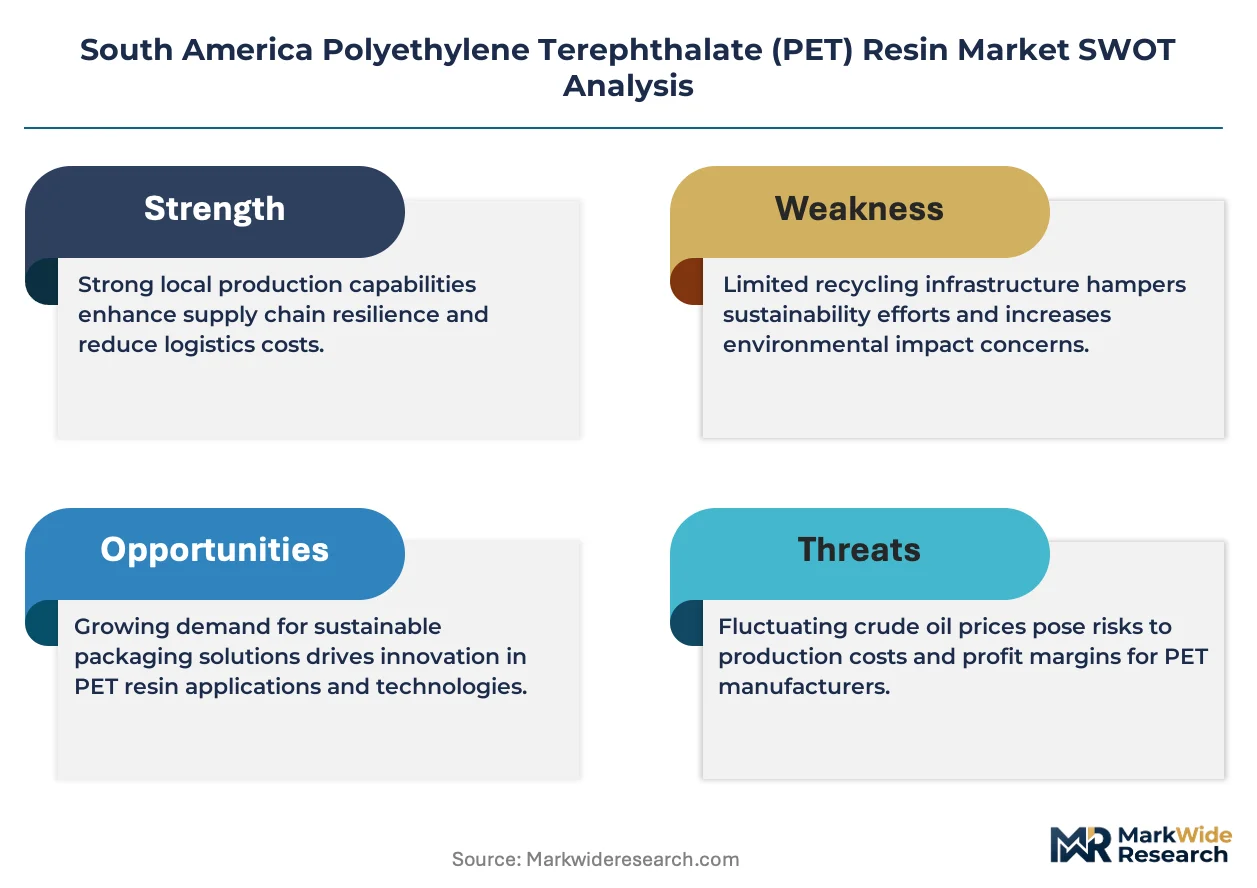
- PTA feedstock volatility:Terephthalic acid price swings transmit directly to resin economics, squeezing converter margins during upstream petrochemical cycles.
- Import dependency for specialty grades:Food-contact certified resin batches from outside Mercosur face extended ANVISA clearance timelines.
- HDPE substitution in non-barrier applications:High-density polyethylene captures share in non-carbonated beverage segments where oxygen transmission requirements relax.
Strategic Opportunities
- Chilean and Argentine provincial recycling mandates:Emerging state-level collection targets in Santiago and Buenos Aires provinces create rPET offtake agreements for Brazilian exporters.
- Hot-fill bottle-grade specialization:Resin formulations with enhanced crystallinity for juice and isotonic beverages command price premiums over standard CSD grades.
- Digital inventory platforms:Spot resin procurement through B2B marketplaces reduces working capital burdens for mid-tier converters in Curitiba and Porto Alegre.
Industry Challenges
- Polymer chemist talent scarcity:Formulation expertise for IV stability and acetaldehyde control concentrates among retiring technical staff at legacy producers.
- Continuous polymerization line capex:Solid-state polymerization reactors and crystallization units demand eight-figure investments with decade-long depreciation horizons.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Polyethylene Terephthalate (PET) Resin Market |
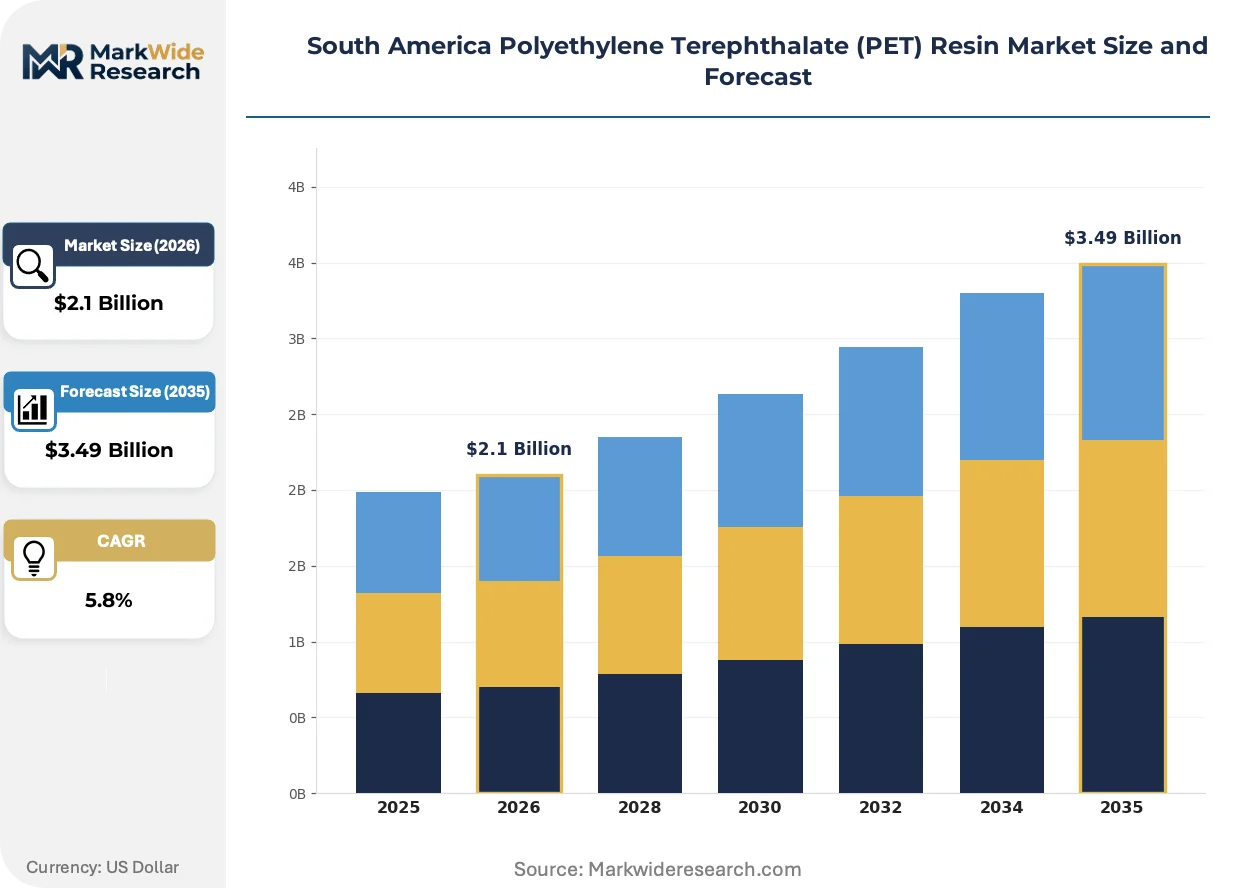
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.49 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injection Molding, Extrusion, Blow Molding, Film & Sheet Application: Bottles, Fiber, Containers, Films End User: Packaging, Textiles, Automotive, Electronics Distribution Channel: Direct Sales, Retail, E-commerce, Distributors |
| Companies Covered | Alpek, S.A.B. de C.V., Indorama Ventures Public Company Limited, DAK Americas, Braskem, Valgroup, ALPLA, Reciclar S.A., Berry Global Inc., Omnigreen, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Polyethylene Terephthalate (PET) Resin Market Evolving Landscape
Process intensification and regulatory chemistry restrictions are compressing legacy production methods while opening formulation white space for compliant alternatives.
Lightweighting-grade PET with enhanced mechanical properties is displacing heavier preform designs across Brazilian bottler operations. Coca-Cola FEMSA and Ambev procurement teams specify 0.72 IV resins that maintain burst pressure at reduced gram weights. This material transition is displacing conventional 0.80 IV formulations in 500ml still water segments.
REACH-aligned substance restrictions from ongoing Mercosur-EU trade negotiations are filtering antimony catalyst residues and heavy metal colorants from approved additive lists. ANVISA is harmonizing its positive list with these emerging standards, forcing reformulation of nucleating agents and toners. Bottle-grade resin producers serving export markets are pre-emptively certifying compliance to avoid batch rejection at Chilean and Argentine customs.
Converters are consolidating supplier relationships around integrated producers with captive PTA and polymerization assets. Mid-tier blow molders in Campinas and Sorocaba clusters now contract directly with resin manufacturers rather than distributors, securing volume commitments in exchange for technical service support. This procurement concentration is most visible among second-tier beverage brands seeking formulation stability amid raw material volatility.
South America Polyethylene Terephthalate (PET) Resin Market Segmentation
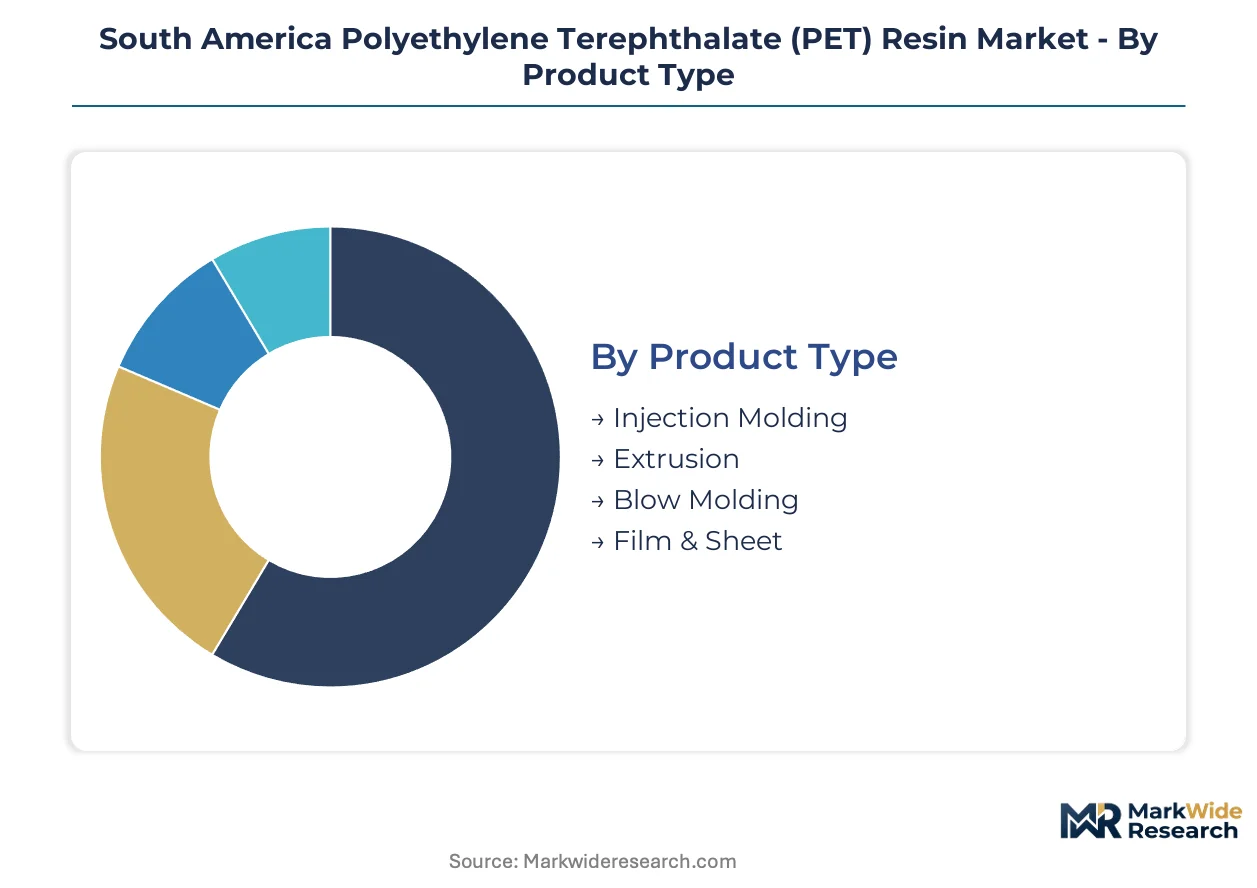
PET resin segmentation across South America reflects divergent technical specifications and regulatory compliance burdens. Each category maps distinct value capture mechanisms to specific converter capabilities and end-use requirements.
Product Type:
Blow molding faces the most acute substitution pressure from HDPE in still water applications, while extrusion-grade resin contends with polypropylene in flexible food packaging.
- Blow Molding:Bottle-grade resin with intrinsic viscosity ranging 0.72-0.84 dL/g dominates carbonated beverage preform production. São Paulo bottlers specify lightweight 0.72 IV formulations for 500ml water bottles to reduce gram weight without sacrificing burst pressure performance. Demand concentrates among Coca-Cola FEMSA and Ambev procurement networks across southeastern Brazil.
- Film & Sheet:Amorphous PET with lower crystallinity serves edible oil and personal care flexible packaging. Argentine converters in Buenos Aires province are expanding thermoforming lines for oven-ready trays, pulling resin tonnage from traditional blow molding allocations.
- Injection Molding:High-flow resin grades feed preform manufacturing for hot-fill juice applications.
- Extrusion:Sheet extrusion for blister packs and pharmaceutical trays requires enhanced clarity specifications.
Blow molding anchors the volume base while Film & Sheet gains share at the steepest rate.
Application:
Cost tier stratification separates commodity bottle applications from specialty fiber and technical film segments requiring certification overhead.
- Bottles:Carbonated soft drink and bottled water packaging absorbs the largest resin tonnage, with ANVISA food-contact purity standards elevating supplier qualification costs. Brazilian converters in Minas Gerais state are consolidating procurement around integrated producers with captive PTA supply to secure formulation stability.
- Films:Biaxially oriented PET film for flexible electronics and solar backsheet applications commands price premiums over commodity packaging grades. Chilean importers in Santiago province are qualifying Asian suppliers for specialty film resin with controlled acetaldehyde levels.
- Fiber:Textile-grade resin with lower IV specifications serves polyester staple fiber production.
- Containers:Wide-mouth jars for peanut butter and spreads compete with glass and polypropylene.
Bottles capture the dominant revenue share while Films expand most quickly as electronics manufacturing migrates to regional free trade zones.
End User:
Customer type concentration in packaging creates procurement leverage that textile and automotive segments cannot replicate.
- Packaging:Beverage bottlers, edible oil processors, and personal care manufacturers consume the majority of regional resin output. Southeastern Brazil's manufacturing corridor concentrates converter operations, enabling direct mill relationships that bypass distributor markups.
- Textiles:Polyester fiber producers in Argentina's Córdoba province source lower-IV resin grades for carpet and nonwoven applications with less stringent purity requirements than food-contact specifications.
- Automotive:Underhood electrical connectors and lighting housings utilize glass-filled PET compounds.
- Electronics:Film substrates for capacitors and flexible circuits require ultra-low oligomer content.
Packaging dominates procurement volume while Electronics achieves the highest per-kilogram margins.
Distribution Channel:
Supply concentration in southeastern Brazil shapes logistics economics and channel selection for converters outside the manufacturing corridor.
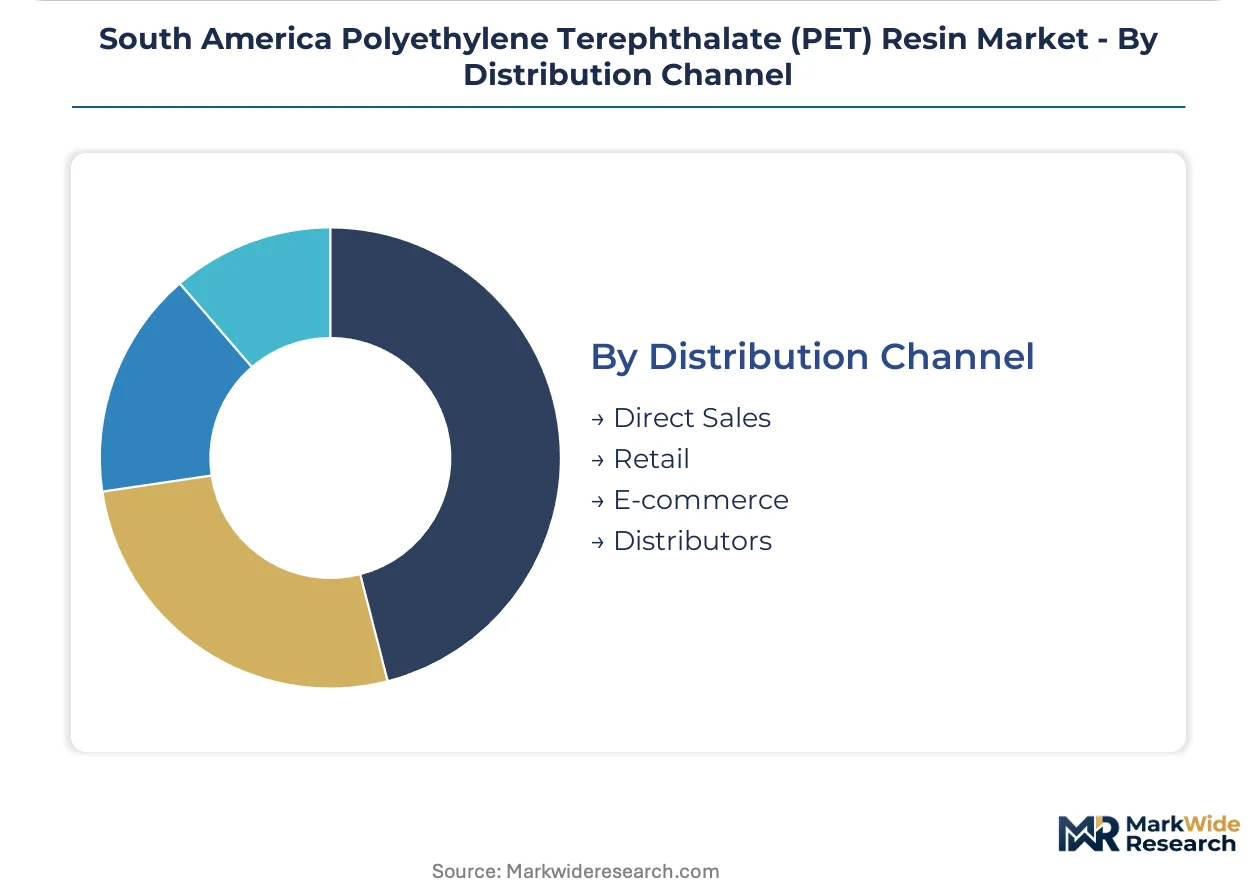
- Direct Sales:Integrated resin producers with captive polymerization assets in Brazil contract directly with large-volume blow molders in Campinas and Sorocaba clusters. These arrangements bundle technical service support with volume commitments to stabilize formulation performance amid PTA feedstock volatility.
- Distributors:Regional stockists serve mid-tier converters in Curitiba and Porto Alegre with smaller batch sizes and extended payment terms.
- E-commerce:B2B marketplaces for spot resin procurement are emerging among price-sensitive converters.
- Retail:Limited to small-scale processors purchasing bagged resin for specialty applications.
Direct sales command the volume base while E-commerce climbs the fastest as digital procurement platforms reduce working capital burdens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated PTA-to-PET assets cluster in southeastern Brazil, creating a supply hub that serves converters across Mercosur trade corridors. ANVISA's food-contact standards and provincial recycling mandates in neighboring states reshape procurement patterns. Each national market presents distinct regulatory and infrastructure profiles.
Brazil
Beverage bottlers Coca-Cola FEMSA and Ambev anchor resin consumption across São Paulo and Minas Gerais states. ANVISA enforces tightening purity standards for food-contact materials that elevate compliance costs for imported batches. The Campinas-Sorocaba manufacturing corridor concentrates blow molding operations and direct mill procurement relationships.
Argentina
Buenos Aires province drives flexible packaging demand through expanding thermoforming lines for oven-ready trays. The national environmental regulator enforces emerging post-consumer collection targets that create rPET offtake opportunities for Brazilian exporters. Córdoba's polyester fiber producers source lower-IV grades for carpet and nonwoven applications.
Chile
Santiago province imposes state-level recycling mandates that reshape resin qualification requirements for imported material. Specialty film converters qualify Asian suppliers for electronics-grade resin with controlled acetaldehyde specifications. Free trade zones in northern regions attract biaxially oriented PET film investment for solar backsheet applications.
Colombia
Bogotá-based bottlers absorb volume-grade resin for carbonated beverage and bottled water segments. The national standards body aligns food-contact polymer regulations with Mercosur-EU trade negotiation frameworks. Antioquia's emerging packaging cluster sources through distributor networks rather than direct mill relationships.
South America Polyethylene Terephthalate (PET) Resin Market Competitive Landscape
Concentration sits with integrated petrochemical conglomerates possessing captive PTA supply and in-house polymerization assets. The market structure tiers between these upstream-integrated producers and regional distributors serving mid-volume converters. Two strategic archetypes dominate: backward-integrated resin manufacturers controlling feedstock costs, and specialty-grade importers navigating ANVISA clearance timelines. Capacity expansion and direct procurement contracting constitute the primary competitive moves, as converters bypass distributors to secure volume commitments.
Within the integrated producer tier, Alpek, S.A.B. de C.V. and Indorama Ventures Public Company Limited anchor regional supply through Brazilian manufacturing positions. DAK Americas occupies a specialist position focused on bottle-grade resin formulations. These three entities exemplify the archetype of producers leveraging captive PTA supply to secure converter relationships amid feedstock volatility.
| Leading Market Players |
|---|
| Alpek, S.A.B. de C.V. |
| Indorama Ventures Public Company Limited |
| DAK Americas |
| Braskem |
| Valgroup |
| ALPLA |
| Reciclar S.A. |
| Berry Global Inc. |
| Omnigreen |
| Others |
Value Network & Pricing Analysis
Captive PTA-to-PET integration at southeastern Brazilian facilities generates 15-20 point cost advantages over merchant feedstock buyers, compressing price floors for non-integrated converters while elevating entry barriers for import-dependent competitors. This scale concentration allows Alpek and Indorama to undercut spot resin offers during PTA downcycles, forcing distributors in Curitiba and Porto Alegre to absorb margin compression or lose volume commitments.
Pricing Analysis
ANVISA food-contact certification dictates the pricing tier structure across Brazilian PET resin procurement, separating premium validated batches from economy grades lacking import clearance documentation. Three-tier pricing stratifies across food-contact certified, industrial-grade, and recycled-content formulations, with Coca-Cola FEMSA and Ambev procurement teams commanding 12-18 point discounts on annual offtake contracts. Pricing pressure intensifies in standard bottle-grade segments as lightweight 0.72 IV formulations displace heavier legacy resins, while specialty hot-fill and film-grade resins maintain margin insulation through technical service bundling. Mid-tier converters in Campinas exhibit highest price sensitivity due to working capital constraints, whereas electronics-grade film buyers in Santiago prioritize acetaldehyde consistency over unit cost.
Supply Chain Analysis
Port congestion at Santos and Paranaguá elevates inbound logistics costs for PTA feedstock and specialty additive imports, adding 8-12 day variability to production scheduling at non-integrated facilities. Supply concentrates in Brazil, with secondary sourcing corridors through Argentina and Chile serving as contingency channels during Brazilian capacity outages. Raw material dependencies center on purified terephthalic acid from Mexican and Asian refiners, ethylene glycol from US Gulf Coast petrochemical complexes, and antimony-free catalyst systems for REACH-aligned formulations. Single-source vulnerability sits with Brazilian southeastern polymerization assets, where any unplanned outage redirects demand to extended ANVISA clearance timelines for Mercosur imports. Distribution runs through direct mill relationships for volume blow molders, with regional distributors capturing mid-tier converters requiring smaller batch flexibility.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as provincial recycling mandates across Argentina and Chile create rPET qualification niches that integrated incumbents under-serve, while lightweighting-grade formulation demands splinter technical service requirements beyond standardized bottle-resin portfolios.
For Market Incumbents: Fortify converter relationships through captive technical service teams embedded in Campinas and Sorocaba manufacturing clusters, preempting distributor disintermediation by mid-tier blow molders seeking formulation stability amid PTA volatility. Expand hot-fill and film-grade certification assets to capture margin premiums eroding in commoditized CSD segments, while securing rPET offtake agreements with Buenos Aires and Santiago provincial collection programs before specialty recyclers consolidate feedstock access. For New Entrants and Emerging Players: Digital inventory platform gaps in spot resin procurement present white-space entry points for B2B marketplace operators targeting working capital-constrained converters in Curitiba and Porto Alegre with transparent pricing and extended payment terms. Target Argentine thermoforming expansion in Buenos Aires province for extrusion-grade resin qualification, leveraging ANVISA equivalency agreements to bypass extended clearance timelines that disadvantage Asian importers. Pursue direct mill bypass strategies through regional stockist partnerships rather than greenfield polymerization investments. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialty-grade compounders with acetaldehyde control and IV stability expertise, as lightweighting-grade formulation complexity outpaces retiring technical staff capacity at legacy producers. Long-term viability hinges on backward integration into rPET flake processing or forward integration into preform manufacturing to capture value chain margin compression. Watch for ANVISA-EU REACH harmonization announcements as inflection indicators triggering reformulation capex cycles and specialist acquisition premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into rPET Flake Processing | Captures recycling mandate value streams across Buenos Aires and Santiago provincial programs. |
| Hot-Fill Grade Specialization | Commands price premiums from juice and isotonic bottlers beyond commoditized CSD formulations. |
| Digital B2B Marketplace Launch | Reduces working capital burdens for mid-tier converters in Curitiba through spot procurement transparency. |
| Technical Service Team Embedding | Secures direct mill relationships with Campinas blow molders seeking formulation stability guarantees. |
| Provincial Recycling Partnership | Locks rPET offtake agreements ahead of Argentine and Chilean state-level collection target enforcement. |
Research Methodology
Cross-validation between primary interviews with PET resin plant managers, beverage bottler procurement directors, and ANVISA regulatory affairs specialists anchors the qualitative findings against secondary validation from Brazilian customs trade data, SEC 10-K petrochemical segment disclosures, and ANVISA food-contact polymer registration databases. Bottom-up triangulation across converter tonnage estimates and top-down reconciliation against PTA feedstock consumption patterns ensures demand-side integrity.
Sensitivity analysis frames volume and value outputs across the projection horizon, with segmentation dimensions spanning product type (blow molding, film and sheet, injection molding, extrusion), application grade (bottle, film, fiber, container), and end-user industry (packaging, textiles, automotive, electronics). CAGRs derive from historical capacity utilization trends and demand elasticity modeling against carbonated soft drink consumption patterns, with specific inputs including PTA price volatility indices and provincial recycling mandate implementation timelines.
Underlying assumptions cover ANVISA certification continuity, Mercosur trade corridor stability, and PTA feedstock supply elasticity, with deviation risk concentrated in REACH-aligned additive restriction acceleration and unplanned Brazilian polymerization asset outages. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Marine-grade Polyurethane Market
Polymers & Resins
Global HBPA Epoxy Resin Market
Polymers & Resins
Polymer Colloids Market
Polymers & Resins
Global Styrene Acrylic Emulsion Polymer Market
Polymers & Resins
Epoxy Resin Reactive Diluent Market
Polymers & Resins
Global Polyanionic Cellulose (PAC) Market
Polymers & Resins
Polyvinyl Butyral (PVB) Market
Polymers & Resins
Polyacrylic Acid Market
Polymers & Resins
Beverage Processing Polymers Market
Polymers & Resins
Global Polymer Dispersion Market
Polymers & Resins
Middle-East and Africa Fluoropolymers Market
Polymers & Resins
Thermoplastic Polyurethane (TPU) Market
Polymers & Resins
Asia-Pacific Epoxy Resins Market
Polymers & Resins
Oman PVC Products Market
Polymers & Resins
Global Polyethyleneimine Market
Polymers & Resins
Polyalkylene Glycols (Pags) Market