
 Global Polyolefin Powders Market | 2026-2036
Global Polyolefin Powders Market Size, Share, and Industry Trends Forecast 2026-2036
Global Polyolefin Powders Market Intelligence
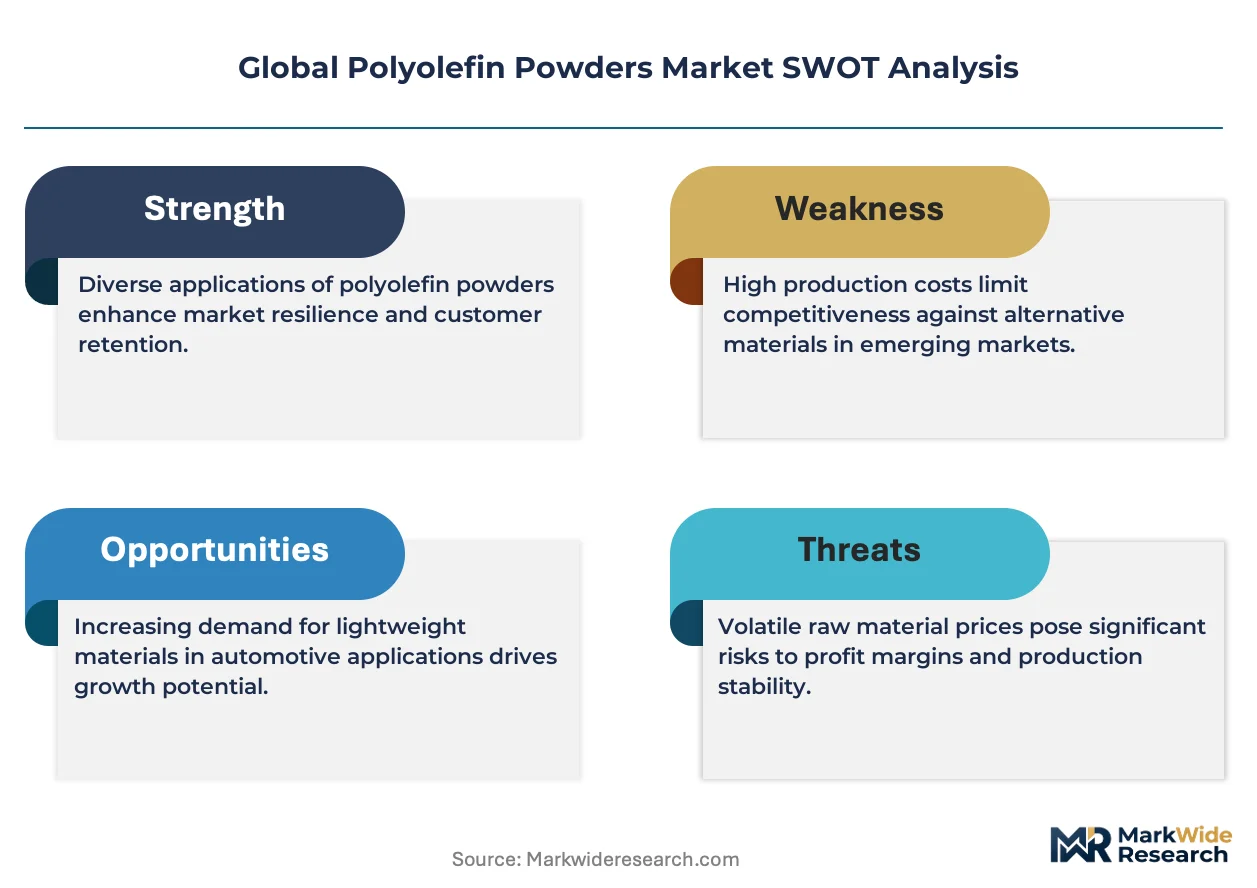
Custom formulation and application development support is restructuring how polyolefin powders are sold to specialized end-users. LyondellBasell Industries N.V. leverages its extensive production scale to serve high-volume commodity segments. In contrast, BASF SE specializes in performance-driven powders for demanding applications like automotive and industrial coatings. SABIC sustains a strong position through its integrated petrochemical supply chain in the Middle East, ensuring consistent feedstock availability.
Polyolefin powders are finely ground thermoplastic polymers, primarily polyethylene and polypropylene, with controlled particle size distribution. These materials are essential for manufacturing processes like rotational molding and powder coating, where uniform melting and flow are critical for final part quality. Within product types, polypropylene powders exhibit strong demand for applications requiring higher stiffness and temperature resistance. Rotational molding remains the dominant application, consuming large volumes for producing tanks, containers, and complex hollow parts for various end-user industries.
Market access is governed by stringent chemical safety and material contact regulations, including the EU's REACH framework and specific US FDA requirements for food-contact applications. In China, compliance with national GB standards for plastics and additives is mandatory for all producers. Future competitive advantage will depend on developing cost-effective polyolefin powders derived from recycled feedstocks or bio-based sources to meet sustainability mandates from consumer goods producers and regulators.
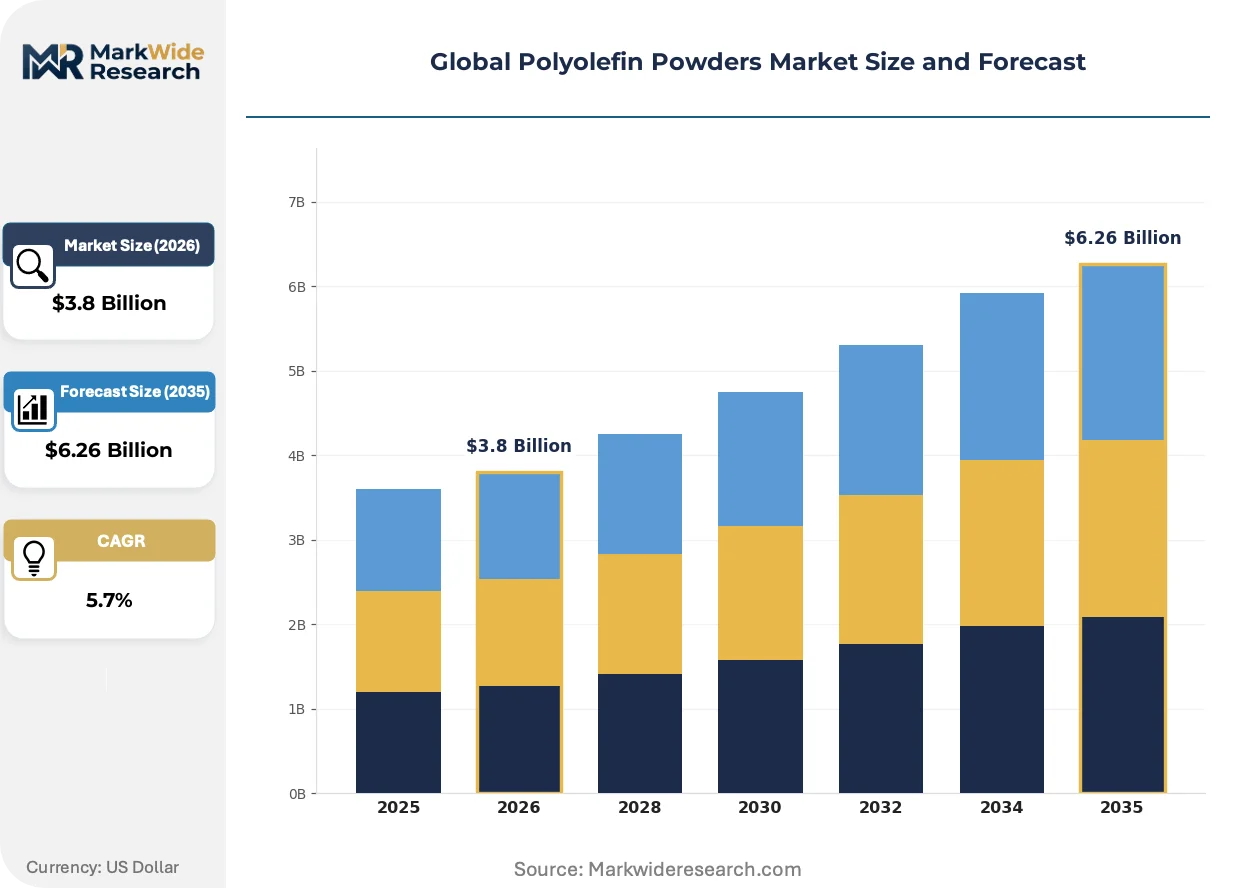
Market Dynamics
The imperative for circularity, driven by regulatory frameworks like the European Union's Green Deal and sustainability targets from major consumer brands, is the central force shaping the polyolefin powders market, compelling innovation in recycled and bio-based feedstocks.
Growth Catalysts
- Rotational Molding Expansion:Demand from the automotive sector for complex, lightweight components like air intake ducts and fluid tanks, manufactured via rotational molding, stimulates consumption of specialized polyethylene and polypropylene powders.
- EU Green Deal:This policy framework accelerates development of polyolefin powders with higher recycled content and improved recyclability, creating new value streams for materials that meet circular economy criteria.
- China's Industrial Base:The country's vast and advanced manufacturing ecosystem, particularly in export-oriented sectors like industrial packaging and consumer goods, consumes significant volumes of polyolefin powders for containers and components.
Market Restraints
- Feedstock Price Volatility:The cost of polyolefin powders is directly linked to the price of ethylene and propylene monomers, which are derived from volatile crude oil and natural gas markets, creating margin pressure for producers.
- Regulatory Compliance Burden:Manufacturers selling globally must navigate a complex web of chemical safety regulations, including the EU's REACH framework and the US FDA's stringent requirements for food-contact materials.
- Threat from Alternative Processes:In certain applications, processes like blow molding or thermoforming for simpler hollow parts can offer faster cycle times and lower costs, presenting a competitive alternative to rotational molding.
Strategic Opportunities
- Bio-Based and Recycled Powders:Developing cost-effective powders from certified recycled or bio-based feedstocks offers a significant opportunity to capture demand from brand owners committed to sustainability goals.
- Powder-Based Additive Manufacturing:The use of polyolefin powders in selective laser sintering (SLS) and other powder-bed fusion 3D printing technologies is an emerging area for rapid prototyping and custom part production.
- Industrialization in Southeast Asia:Expanding manufacturing and infrastructure development in countries like Vietnam and Indonesia creates new demand for rotationally molded products such as water storage tanks and industrial containers.
Industry Challenges
- Particle Size Control:Achieving and maintaining a consistent, narrow particle size distribution during the grinding process is a persistent technical challenge that directly impacts melt flow, processing efficiency, and final part quality.
- Food-Contact Certification Delays:The extensive testing and documentation required to secure food-contact approvals from bodies like the EFSA in Europe or the FDA in the US can create long lead times for new product introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Polyolefin Powders Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Density Polyethylene, Low-Density Polyethylene, Polypropylene, Linear Low-Density Polyethylene, Ethylene Vinyl Acetate Application: Injection Molding, Rotational Molding, Coating, Adhesive Production, Masterbatch Manufacturing End User Industry: Packaging Manufacturers, Consumer Goods Producers, Electronics Assemblers, Textile Fabricators, Building Materials Suppliers Form: Powder, Granule, Pellet, Flakes, Chips |
| Companies Covered | LyondellBasell Industries N.V., SABIC, ExxonMobil Corporation, BASF SE, Borealis AG, INEOS Group AG, Chevron Phillips Chemical Company LLC, TotalEnergies SE, Braskem S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Polyolefin Powders Market Strategic Shifts & Innovations
A fundamental shift toward performance-driven materials and sustainable production models is defining the competitive landscape. This evolution is driven by both sophisticated end-user requirements for tailored material properties and mounting regulatory pressure to incorporate circular economy principles into the supply chain.
Metallocene-catalyzed polyolefin powders offer superior mechanical properties, including enhanced impact strength and stress crack resistance, compared to conventional alternatives. Automotive and industrial tank manufacturers are adopting these advanced materials to produce more durable and lightweight parts. This technology is absorbing market share from traditional Ziegler-Natta powders in high-specification applications where performance and longevity justify a price premium.
China's GB standards for plastics, which govern everything from material composition to safety for food-contact use, are creating a distinct regulatory environment. Compliance forces producers to tailor formulations and conduct specific testing for the Chinese market, impacting product development timelines and costs. This affects polypropylene powders most acutely, given their extensive use in consumer appliances and packaging sold within China.
End-user procurement is evolving from transactional purchases of standard-grade powders to collaborative development of custom-formulated materials. This change disrupts traditional distribution channels, as specialized manufacturers in sectors like medical equipment and aerospace increasingly bypass intermediaries to work directly with powder producers. This direct engagement model is most evident in Germany and Italy, where technical precision is paramount.
Global Polyolefin Powders Market Segmentation
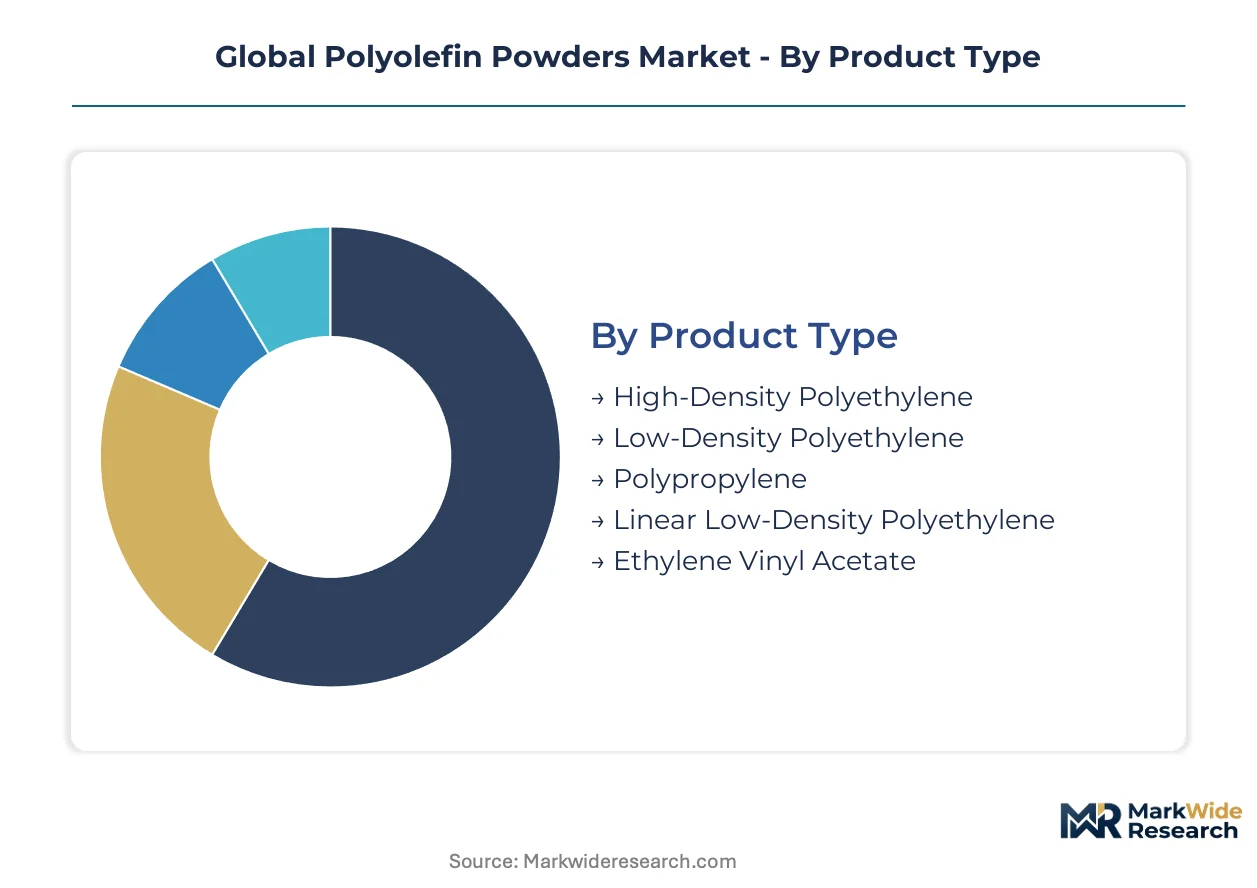
The polyolefin powders market segments across various dimensions, reflecting the diverse material specifications and processing requirements of end-user industries. Understanding these distinctions is critical for producers to tailor formulations and optimize supply chain strategies for specialized applications.
Product Type:
The polyolefin powders market exhibits a spectrum from highly customized specialty formulations to standardized commodity grades. This differentiation influences production scale and distribution channels for various product types.
- Polypropylene:These powders provide superior stiffness and elevated temperature resistance, making them suitable for demanding applications. Demand concentrates in the automotive sector for interior components and fluid reservoirs, particularly in Germany.
- High-Density Polyethylene:Characterized by high strength-to-density ratio and impact resistance, these powders are extensively used in rotational molding. Consumption is significant for industrial tanks and large containers across North America and China.
- Low-Density Polyethylene:Offering good flexibility and processability, these powders find use in film applications and certain coating processes. Packaging manufacturers utilize these materials for protective layers.
- Linear Low-Density Polyethylene:Known for its enhanced tensile strength and puncture resistance compared to LDPE, this type serves heavy-duty film and rotational molding applications. Agricultural containers benefit from its durability.
- Ethylene Vinyl Acetate:This copolymer delivers flexibility, toughness, and good adhesion properties. EVA powders are employed in hot-melt adhesives and specific foam applications.
Leading the category by volume: High-Density Polyethylene. Growing fastest: Polypropylene.
Application:
Application requirements dictate the specific material properties and particle size distributions needed for polyolefin powders. Performance across different processing methods drives material selection and innovation.
- Rotational Molding:This process consumes large volumes of polyolefin powders for producing seamless, hollow plastic parts like water tanks and automotive ducts. The uniform melt flow of powders is critical for final part integrity.
- Coating:Polyolefin powders are applied as protective and decorative layers in industrial and automotive coatings, offering chemical resistance and durability. Specialty formulations are crucial for consistent surface finish.
- Injection Molding:While less common than other forms, some fine polyolefin powders are used in injection molding for specific part geometries or composite formulations. Precision components for consumer goods utilize this method.
- Adhesive Production:Polyolefin powders serve as a key component in hot-melt adhesives, providing strong bonding and flexibility across various substrates. Packaging and textile industries use these adhesives.
- Masterbatch Manufacturing:Powders are incorporated into masterbatches to introduce color, additives, or performance enhancers into polymer blends. This ensures consistent dispersion of functional ingredients.
Market share for polyolefin powders concentrates in rotational molding applications. Coating applications show the steepest expansion trajectory.
End User Industry:
The diverse needs of end-user industries shape the demand for specific polyolefin powder types and their performance characteristics. Procurement patterns vary significantly across these sectors.
- Packaging Manufacturers:This industry utilizes polyolefin powders for creating durable containers, films, and protective packaging solutions. Food-contact regulations like US FDA and EU EFSA are paramount for these applications.
- Consumer Goods Producers:Polyolefin powders are essential for manufacturing a wide array of consumer products, including toys, household appliances, and sporting goods. Product aesthetics and safety standards are key considerations.
- Building Materials Suppliers:Powders are integrated into construction components such as pipes, insulation, and geomembranes, offering durability and chemical resistance. Infrastructure projects in Southeast Asia drive this demand.
- Automotive Sector:Polyolefin powders enable the production of complex, lightweight automotive components like fuel tanks, air ducts, and interior trim. Metallocene-catalyzed polyolefins offer enhanced impact strength.
- Textile Fabricators:In this sector, polyolefin powders are used in non-woven fabrics, technical textiles, and as binders. Specific melt flow properties are required for consistent fiber bonding.
Demand from Packaging Manufacturers secures the largest market share. The Automotive sector demonstrates the most significant growth potential.
Form:
The physical form of polyolefin materials, particularly particle size and shape, directly influences processing efficiency and final product quality. Cost tiers can also vary by form.
- Powder:Characterized by fine particle size and controlled distribution, powders are critical for rotational molding and powder coating applications. Uniform melting is essential for these processes.
- Granule:These small, irregular particles are commonly used in compounding and general plastics processing, offering good flow characteristics. They serve as a base for many downstream products.
- Pellet:Standardized, uniform particles widely used in various polymer processing techniques like extrusion and injection molding. Pellets are the most common form for bulk polymer shipments.
- Flakes:Often derived from recycled materials, flakes represent an intermediate form that requires further processing or compounding before final application. Circularity initiatives increase flake utilization.
- Chips:Similar to flakes, chips are typically larger and also often originate from recycled or reprocessed polyolefin materials. They are used in lower-grade applications or as feedstock for further grinding.
The Powder form accounts for the largest share due to specialized processing needs. Flakes and Chips are gaining share as recycled content mandates increase.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global polyolefin powders market exhibits a clear division between major production hubs and significant consumption centers. Feedstock availability often drives manufacturing concentration in certain regions, while advanced industrialization and regulatory frameworks shape demand in others. This dynamic interplay influences material flow and localized innovation.
China
China's vast manufacturing ecosystem drives substantial demand for polyolefin powders, particularly in export-oriented industrial packaging and consumer goods. Compliance with national GB standards for plastics and additives is mandatory for all producers. The Yangtze River Delta region exemplifies this, hosting numerous facilities for component manufacturing and assembly.
Germany
German automotive and industrial sectors require high-performance polyolefin powders for complex components and specialized coatings. The EU Green Deal accelerates demand for formulations with higher recycled content and improved recyclability. Bavaria's automotive manufacturing hubs increasingly adopt metallocene-catalyzed polyolefins for lightweight parts.
United States
The United States consumes large volumes of polyolefin powders for industrial tanks and critical food-contact packaging applications. US FDA requirements impose stringent material contact regulations on producers. The Gulf Coast region, a major petrochemical center, supplies key feedstocks for polyolefin powder manufacturing and processing.
Saudi Arabia
Saudi Arabia sustains a strong position through its integrated petrochemical supply chain, ensuring consistent feedstock availability for polyolefin production. National industrialization programs encourage the development of downstream processing capabilities. Jubail Industrial City serves as a major hub for large-scale polymer production and export.
Vietnam
Expanding industrialization in Vietnam creates new demand for rotationally molded products such as water storage tanks and industrial containers. National environmental protection laws influence material selection and processing standards. The Ho Chi Minh City area drives consumption with its growing base of manufacturing and consumer goods producers.
Global Polyolefin Powders Market Key Industry Players
Capital-heavy producers compete with asset-light designers in the polyolefin powders market, creating a tiered competitive structure. The industry sees large integrated petrochemical companies alongside specialized performance material providers. Strategic archetypes include global commodity suppliers, niche performance specialists, and regional feedstock-advantaged players. Companies primarily engage in capacity expansion and strategic partnerships to secure market position.
At the scale-driven end of the market, LyondellBasell Industries N.V. represents a global commodity supplier leveraging extensive production scale for high-volume segments. SABIC occupies a strong position through its integrated petrochemical supply chain in the Middle East, anchoring consistent feedstock availability and broad regional market access. BASF SE exemplifies the performance-driven specialist, focusing on demanding applications like automotive and industrial coatings within its portfolio where custom formulations are critical. These players demonstrate the varied strategic approaches within the polyolefin powders sector, from volume-centric production to high-value application expertise. Their presence highlights the importance of both raw material control and application-specific innovation.
| Leading Market Players |
|---|
| LyondellBasell Industries N.V. |
| SABIC |
| ExxonMobil Corporation |
| BASF SE |
| Borealis AG |
| INEOS Group AG |
| Chevron Phillips Chemical Company LLC |
| TotalEnergies SE |
| Braskem S.A. |
| Others |
Cost & Logistics Intelligence
The European Union's Green Deal mandates for circularity gate qualified polyolefin powder supply, driving premium-tier pricing for materials meeting stringent sustainability criteria. This regulatory push incentivizes investment in recycled and bio-based feedstocks, influencing both material availability and market value across the supply chain.
Pricing Analysis
Margin pressure intensifies in commodity polyolefin powder segments as feedstock price volatility directly impacts production costs. The dominant pricing model incorporates contract-based long-term offtake agreements for specialized formulations and transactional spot pricing for standard grades. Price differentiation stems from quality grade, specific regulatory certifications like US FDA approval, and the level of customization required. Automotive and medical applications exhibit lower price sensitivity compared to high-volume packaging manufacturers.
Supply Chain Analysis
National GB standards in China reshape polyolefin powder sourcing, compelling producers to tailor formulations and testing for the domestic market. Geographic supply concentration centers in the Middle East, particularly Saudi Arabia, and the US Gulf Coast, which leverage integrated petrochemical supply chains. The market relies heavily on ethylene and propylene monomers, making it vulnerable to crude oil and natural gas price fluctuations. Distribution runs through a hybrid model combining direct sales to specialized end-users with regional distributors for broader market access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a supply-constrained environment, where limited capacity for advanced metallocene-catalyzed polyolefin powders props up premium pricing and incentivizes specialized production.
For Market Incumbents: Anchor market share by investing heavily in sustainable feedstocks and advanced catalyst technologies, especially metallocene-based systems. This defends against regulatory shifts like the EU Green Deal and emerging threats from alternative processes. Deepen vertical integration into feedstock production and secure critical certifications such as REACH and US FDA approvals to reinforce market position.
For New Entrants and Emerging Players: Launch via specialized distribution channels, focusing on niche, high-value applications like powder-based additive manufacturing or medical device components. The most penetrable segments include bio-based polyolefin powders and customized formulations for industrialization in Southeast Asia. A direct technical support model, offering custom formulation development, provides a strong go-to-market angle.
For Investors and Strategic Acquirers: Significant uptake of recycled-content polyolefins in automotive or packaging applications is the leading indicator that the market is transitioning to a new growth phase. The long-term viability of this sector remains strong, driven by essential manufacturing needs and sustainability mandates. Target niche specialists with proprietary technology in advanced materials or innovative recycling processes for strategic acquisitions.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Increasing production capacity addresses growing demand from the automotive sector for lightweight components. |
| Backward Integration | Securing feedstock supply through backward integration mitigates risks from volatile monomer prices. |
| Green Manufacturing Transition | Adopting green manufacturing processes aligns with global sustainability goals and regulatory requirements. |
| Long-term Supply Agreement | Establishing long-term supply agreements ensures consistent material availability for key end-users. |
| Joint Venture | Forming joint ventures with technology providers accelerates the development of bio-based or recycled polyolefin powders. |
Research Approach
Document review covered EU REACH filings, US FDA guidance documents, China GB standards, and petrochemical industry reports, complemented by interviews with industry stakeholders. Primary research involved discussions with R&D directors, procurement leads at rotational molders, regulatory compliance officers, and materials engineers. This approach facilitated bottom-up and top-down triangulation of market data.
The quantitative model produced detailed market sizing and forecast projections across the analysis window, segmented by product type, application, end-user industry, and regional consumption patterns. Compound annual growth rates were derived from historical growth analysis and projected demand drivers. Key forecast inputs included feedstock price trends and evolving regulatory mandates for recycled content.
The model assumes a particular technology adoption path; alternative pathways for bio-based polyolefins would alter the outlook. Forecasts reflect assumptions regarding geopolitical stability and economic growth. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Global PEEK Market
Polymers & Resins
Fluorine Polymer Films Market
Polymers & Resins
Africa Polyamide Market
Polymers & Resins
Low Density Polyethylene Market
Polymers & Resins
Circular Polymers Market
Polymers & Resins
Solid State Resins Market
Polymers & Resins
TPEE in Automotive Industry Market
Polymers & Resins
BPA-Free Epoxy Resins Market
Polymers & Resins
Rigid Spray Polyurethane Foam Market
Polymers & Resins
High Density Polyethylene (HDPE) Market
Polymers & Resins
Europe Superabsorbent Polymers Market
Polymers & Resins
Biopolymer Tubes Market
Polymers & Resins
Polymer Resin Market
Polymers & Resins
US Polycarbonate Market
Polymers & Resins
South America Polyamide Market
Polymers & Resins
Water Soluble Polymers Market