
 Light Curing Adhesives Market | 2026-2036
Light Curing Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
Light Curing Adhesives Market Outlook
Buyer concentration is shifting as medical device OEMs consolidate adhesive procurement across fewer qualified suppliers while electronics contract manufacturers fragment demand across specialized regional formulators. Henkel AG & Co. KGaA leverages its European dental and industrial formulation footprint to anchor high-margin segments. Dymax Corporation specializes in UV and LED curing systems for precision electronics assembly. Dow competes on material science integration, extending photopolymer expertise from coatings into adhesive architectures.
Light curing adhesives are photochemically reactive formulations that polymerize upon exposure to ultraviolet, visible, or LED radiation within seconds, typically achieving handling strength in under 30 seconds and full cure depths up to 13 millimeters depending on photoinitiator concentration and substrate transparency. Their primary industrial purpose is to bond heat-sensitive substrates where thermal curing would distort components or degrade adjacent materials. UV technology dominates installed curing equipment bases but LED technology captures the fastest growth trajectory due to lower energy consumption and elimination of mercury arc lamp disposal costs. Industrial applications generate the deepest revenue pools from automotive sensor encapsulation and display lamination, while medical devices command premium pricing through biocompatibility certifications and sterilization resistance requirements.
FDA 21 CFR Part 175.105 indirect food contact regulations and EPA Toxic Substances Control Act reporting obligations shape product development pathways for North American suppliers, while REACH Annex XVII restrictions on acrylate monomer classifications constrain European formulation flexibility. ISO 10993 biocompatibility testing protocols and MDR CE marking requirements create barrier-to-entry dynamics for medical-grade product lines. Stakeholders must monitor photoinitiator regulatory reclassification proceedings across multiple jurisdictions and assess captive LED curing equipment deployment against third-party tolling economics.
Market Dynamics
LED curing systems are displacing mercury arc lamp infrastructure across precision manufacturing clusters, forcing formulators to redesign photoinitiator packages around narrower wavelength spectra while medical device OEMs consolidate qualified supplier lists.
Growth Catalysts
- REACH Annex XVII acrylate restrictions:European chemical classification revisions are accelerating mercury-free photoinitiator R&D, opening formulation partnerships between adhesive producers and LED equipment manufacturers.
- Catheter and syringe assembly lines:Medical device manufacturers in Germany's Baden-Württemberg corridor are expanding procurement of LED-curing systems to bond heat-sensitive polymer substrates without thermal distortion.
- Mercury elimination mandates:RoHS compliance deadlines across EU member states are pushing industrial users toward visible-light curing chemistries that eliminate hazardous waste disposal costs.
Market Restraints
- Photoinitiator supply concentration:Specialty chemical production for Type I cleavage photoinitiators concentrates among German and Japanese suppliers, creating input cost volatility during energy price spikes.
- Substrate transparency requirements:UV and visible light penetration limits constrain bond line depth to 13 millimeters maximum, excluding opaque or heavily pigmented component assemblies.
- Thermal curing substitution:Two-part epoxy systems retain cost advantages in non-temperature-sensitive automotive structural bonding where cure speed is secondary to shear strength.
Strategic Opportunities
- India's PLI scheme for medical devices:Domestic manufacturing incentives are attracting catheter and diagnostic equipment producers seeking localized adhesive supply chains with biocompatibility certifications.
- Dual-cure formulation development:Hybrid UV-moisture curing systems are enabling shadow-cure capabilities in complex electronics housings where light access remains incomplete.
- ISO 10993-5 cytotoxicity testing protocols:Streamlined biocompatibility certification pathways are reducing time-to-market for medical-grade adhesive launches in Class II device applications.
Industry Challenges
- Photochemistry specialization gap:Formulation chemists with expertise in free-radical polymerization kinetics remain scarce relative to demand from expanding LED curing system deployments.
- MDR CE marking timelines:Extended technical documentation review periods for medical device adhesives are compressing product launch windows and tying up regulatory affairs capacity.
- Legacy mercury arc equipment stranded assets:Industrial users face write-down pressure from installed UV lamp bases as LED retrofit economics improve and disposal regulations tighten.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Light Curing Adhesives Market |
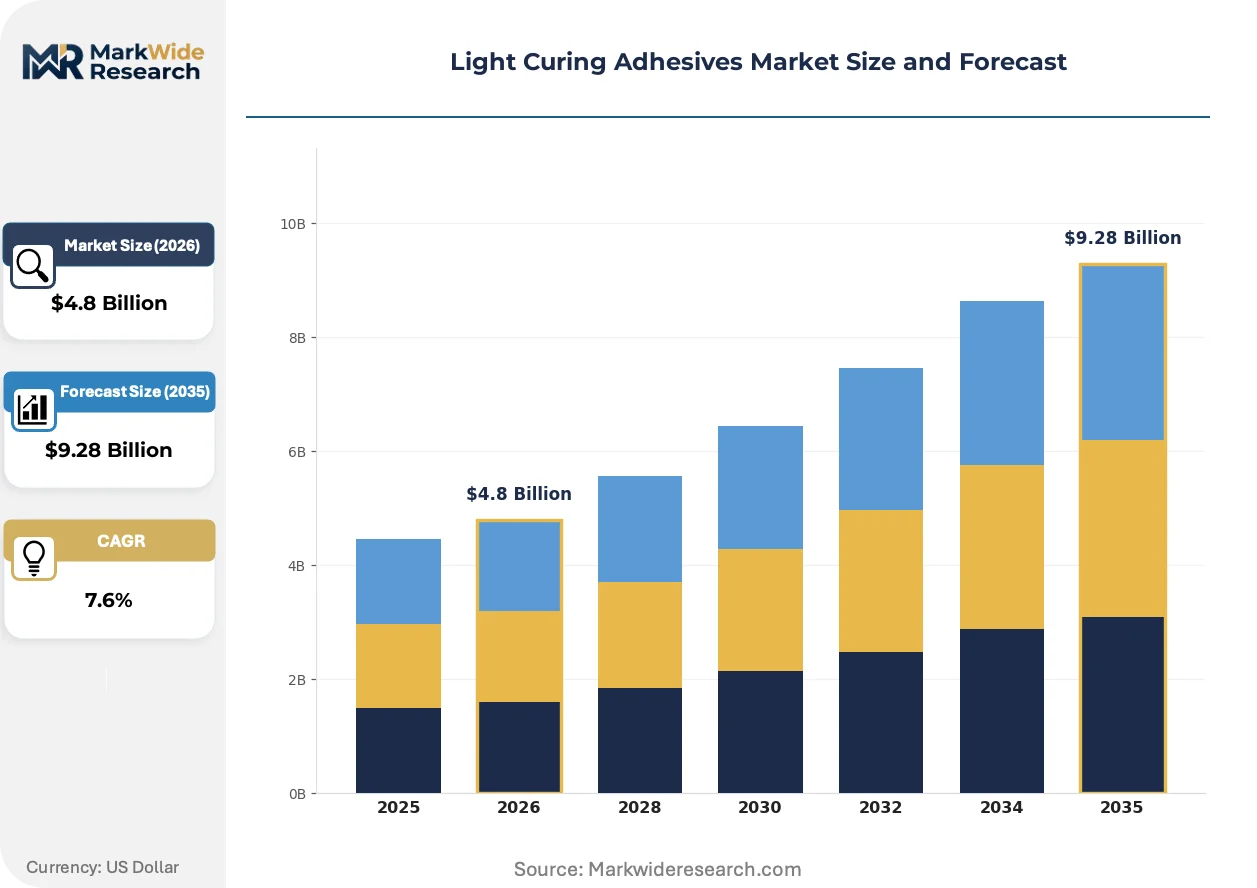
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.28 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Orthopedic, Dental, Industrial, Cosmetic Application: Electronics, Automotive, Construction, Medical Devices End User: Manufacturers, Healthcare Providers, DIY Consumers, Service Providers Technology: UV, LED, Laser, Others |
| Companies Covered | 3M Company, Henkel AG & Co. KGaA, Dymax Corporation, H.B. Fuller Company, Permabond LLC, DELO Industrial Adhesives, Dow, Epoxy Technology Inc., Panacol-Elosol GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Light Curing Adhesives Market Strategic Shifts
Photoinitiator chemistry and curing equipment architecture are converging around narrow-band LED spectra, while regulatory pressure on mercury compounds accelerates formulation platform transitions and procurement criteria harden around biocompatibility documentation.
Visible-light activated photoinitiator systems operating at 405 nanometers are decentralizing curing station placement on electronics assembly floors. Automotive sensor manufacturers in Stuttgart and Munich are adopting these systems for encapsulation of camera modules and LiDAR housings. The shift is compressing capital equipment footprints and eliminating ozone ventilation requirements that constrained floor layout flexibility.
REACH restrictions on acrylate monomer classifications are forcing reformulation of industrial-grade light curing adhesives across European manufacturing facilities. ECHA substance evaluation proceedings are creating uncertainty around existing product registrations, prompting adhesive suppliers to accelerate bio-based monomer screening programs. Medical device formulators are responding by locking in dual-source supply agreements for photoinitiator raw materials.
Buyer concentration among consolidated medical device OEMs is fragmenting regional adhesive demand into specialized formulation contracts. Electronics contract manufacturers in Taiwan and South Korea are disintermediating distributors to negotiate direct supply relationships with photopolymer producers. The pattern is most visible in display lamination applications where volume scale and technical service intensity drive supplier selection criteria.
Light Curing Adhesives Market Segmentation
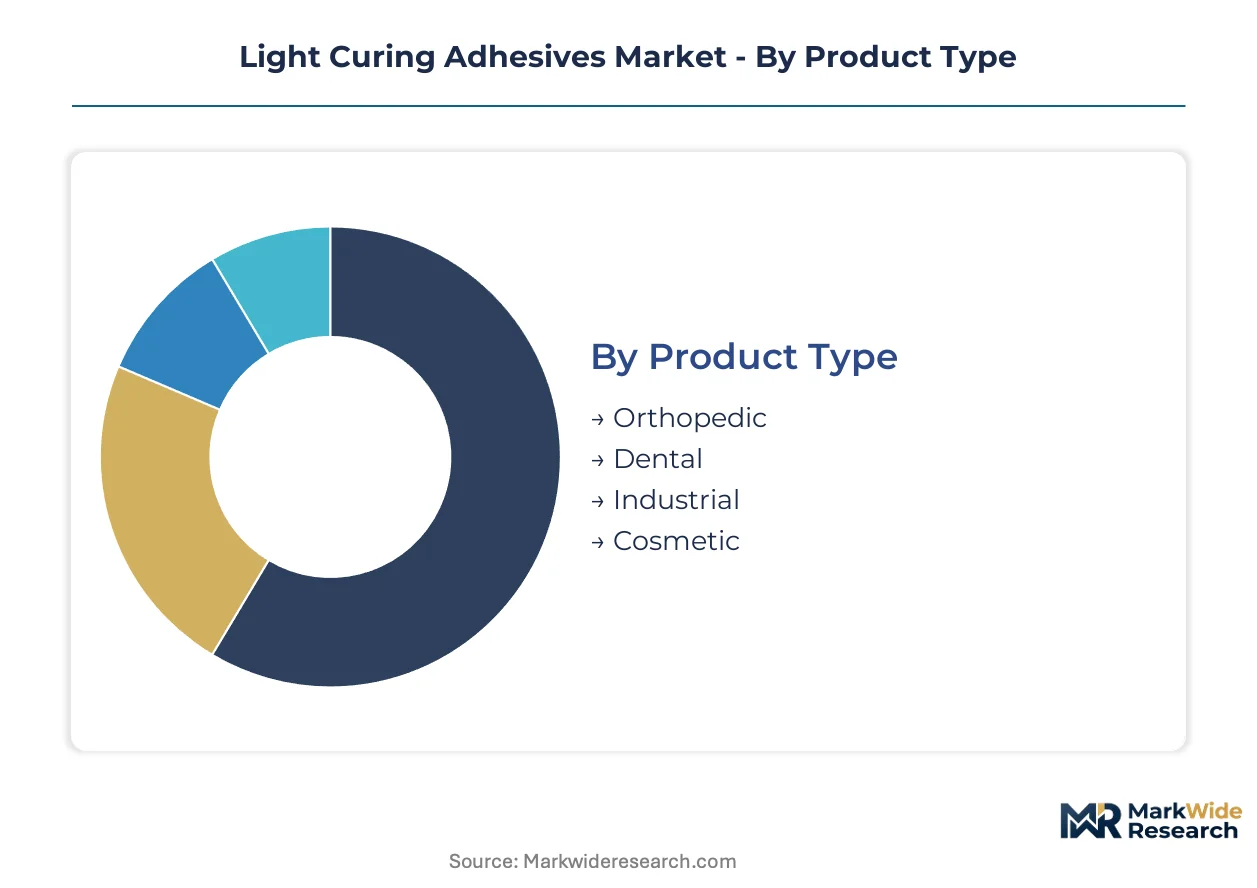
Light curing adhesives span divergent certification burdens across medical, industrial, and consumer domains. Product positioning hinges on matching photoinitiator chemistry to end-use regulatory requirements rather than performance optimization alone.
Product Type:
ISO 10993 biocompatibility testing and FDA 510(k) clearance requirements concentrate heavily in medical-grade segments, while industrial formulations navigate REACH Annex XVII acrylate restrictions.
- Orthopedic:Load-bearing bone cement formulations polymerize under 405nm LED exposure for joint replacement assembly. German orthopedic OEMs in the Baden-Württemberg corridor specify sterilization-resistant grades for implantable device fixation.
- Dental:Visible-light curable composites dominate restorative applications with handling strength under 20 seconds. Chairside curing systems in Stuttgart dental clinics drive demand for shade-matched, radiopaque formulations.
- Industrial:High-speed bonding of heat-sensitive substrates in automotive sensor encapsulation. RoHS compliance mandates mercury-free photoinitiator packages across EU manufacturing facilities.
- Cosmetic:Nail gel formulations and skincare device assembly represent price-sensitive demand with minimal regulatory burden.
Leading the category by volume: Industrial. Growing fastest: Orthopedic.
Application:
End-use sectors separate by cure speed requirements and substrate thermal sensitivity, with medical devices commanding premium pricing through sterilization validation protocols.
- Electronics:Display lamination and camera module encapsulation demand sub-30-second handling strength. Taiwan contract manufacturers specify narrow-band LED curing to eliminate thermal distortion in flexible PCB assemblies.
- Automotive:LiDAR housing sealing and sensor potting require depth-of-cure exceeding 10 millimeters. Munich OEMs specify dual-cure formulations for shadowed bond lines in complex electronics housings.
- Construction:Structural glass bonding and decorative fixture assembly tolerate longer cure windows. Cost pressure from two-part epoxy substitution limits penetration in load-bearing applications.
- Medical Devices:Catheter assembly and syringe bonding command highest margins through MDR CE marking requirements. Baden-Württemberg manufacturers consolidate qualified supplier lists for biocompatible grades.
Revenue concentrates in Electronics. Steepest expansion trajectory: Medical Devices.
End User:
Procurement patterns diverge between consolidated OEMs seeking technical service partnerships and fragmented service channels prioritizing distributor availability.
- Manufacturers:Direct supply relationships with photopolymer producers for high-volume electronics lamination. Volume scale drives specification lock-in and multi-year formulation contracts.
- Healthcare Providers:Dental clinics and hospital systems procure through specialized medical distributors with ISO 13485 quality system requirements.
- DIY Consumers:Retail-channel nail gels and repair kits represent price-elastic demand with minimal technical support requirements.
- Service Providers:Electronics repair shops and industrial maintenance contractors source through regional distributors with rapid replenishment capabilities.
Manufacturers capture highest absolute spend. DIY Consumers expand most quickly through e-commerce penetration.
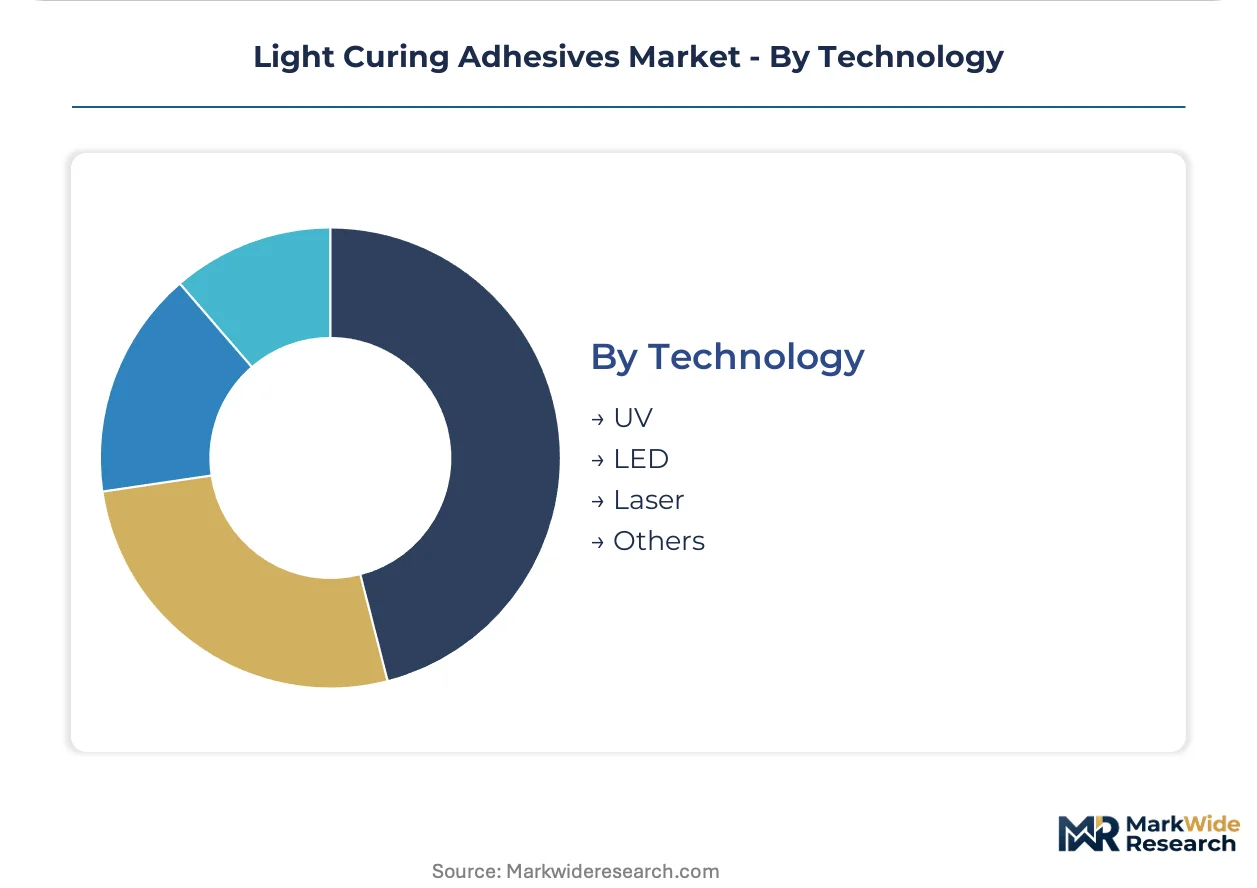
Technology:
Equipment architecture choices determine photoinitiator formulation compatibility and capital expenditure trajectories across installed manufacturing bases.
- UV:Mercury arc lamp systems dominate legacy installed bases with broad spectral output. EU disposal regulations and energy efficiency mandates accelerate replacement cycles.
- LED:Narrow-band 365-405nm systems eliminate ozone ventilation and reduce energy consumption. Stuttgart automotive clusters specify LED curing for floor layout flexibility in sensor assembly.
- Laser:Point-source curing for micro-scale medical device bonding with precision depth control. Swiss orthopedic manufacturers deploy laser systems for catheter tip assembly.
- Others:Visible daylight curing and dual-cure moisture-UV hybrid systems address shadow-cure limitations in complex geometries.
UV retains largest installed base. LED gains share fastest through retrofit economics and regulatory pressure on mercury elimination.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for light curing adhesives concentrates in precision manufacturing clusters where medical device and automotive electronics OEMs co-locate with formulation R&D facilities. Germany's Baden-Württemberg corridor anchors European procurement volumes, while East Asian electronics contract manufacturers fragment supply relationships across specialized regional formulators.
United States
Medical device OEMs in Minneapolis and Boston consolidate qualified supplier lists for catheter bonding applications. FDA 21 CFR Part 175.105 indirect food contact regulations shape photoinitiator selection for packaging adhesives. The Pacific Northwest electronics cluster specifies LED curing systems for display lamination to eliminate thermal distortion in flexible assemblies.
Germany
Automotive sensor manufacturers in Stuttgart and Munich drive specification of dual-cure formulations for LiDAR housing encapsulation. REACH Annex XVII acrylate restrictions and RoHS mercury elimination mandates accelerate mercury-free photoinitiator R&D partnerships. The Baden-Württemberg manufacturing corridor concentrates orthopedic OEM demand for sterilization-resistant bone cement grades.
China
Display lamination contract manufacturers in the Yangtze River Delta specify narrow-band LED curing for high-volume electronics assembly. NMPA medical device registration requirements create compliance pathways for domestic adhesive producers seeking biocompatibility certifications. Shenzhen-area electronics clusters disintermediate distributors to negotiate direct supply relationships with photopolymer producers.
Japan
Precision electronics assemblers in the Nagoya-Chubu region deploy laser curing systems for micro-scale medical device bonding with depth control. METI energy efficiency standards accelerate LED retrofit cycles in legacy mercury arc lamp installations. Osaka-based dental equipment manufacturers drive demand for visible-light curable composites with sub-20-second handling strength.
India
Domestic catheter and diagnostic equipment producers expand manufacturing capacity under the PLI scheme for medical devices. CDSCO medical device regulations align with ISO 10993 biocompatibility testing protocols for Class II adhesive applications. Maharashtra and Gujarat manufacturing zones attract localized adhesive supply chains seeking sterilization-resistant formulation capabilities.
Light Curing Adhesives Market Competitive Environment
German producers anchor the premium formulation tier; American specialists hold positions in precision electronics curing systems. Market structure reflects buyer consolidation among medical device OEMs alongside fragmentation across electronics contract manufacturers. Three archetypes dominate: diversified chemical conglomerates with photopolymer expertise, dedicated adhesive formulators with LED equipment integration capabilities, and regional specialists serving single-industry verticals. Competitive moves center on strategic partnerships between adhesive producers and LED equipment manufacturers, plus accelerated bio-based monomer screening programs responding to ECHA substance evaluation uncertainty.
Within the diversified chemical tier, Henkel AG & Co. KGaA and Dow exemplify players extending material science capabilities from coatings into adhesive architectures. Dymax Corporation occupies a position among equipment-integrated specialists, representing the narrow-band LED curing system segment where formulation and hardware convergence accelerates. These three anchors illustrate how competitive positioning depends on photoinitiator chemistry alignment with regulatory compliance requirements rather than performance metrics alone.
| Leading Market Players |
|---|
| 3M Company |
| Henkel AG & Co. KGaA |
| Dymax Corporation |
| H.B. Fuller Company |
| Permabond LLC |
| DELO Industrial Adhesives |
| Dow |
| Epoxy Technology Inc. |
| Panacol-Elosol GmbH |
| Others |
Value Chain & Pricing Dynamics
Photoinitiator raw material costs cascade through three distinct pricing tiers that separate medical-grade ISO 10993-certified formulations from industrial RoHS-compliant grades and price-sensitive cosmetic applications. German and Japanese specialty chemical suppliers anchor upstream pricing power for Type I cleavage photoinitiators, while LED curing equipment bundling increasingly shapes downstream margin capture.
Pricing Analysis
Volume-margin splits concentrate high-unit-value capture in medical device segments where MDR CE marking and FDA 510(k) pathways justify premium positioning, while electronics lamination runs on thin margins at scale. Pricing stratifies across premium, standard, and economy tiers based on certification grade and volume scale. Cost compression in industrial grades intensifies because two-part epoxy systems retain cost advantages in non-temperature-sensitive bonding. DIY consumers in nail gel applications exhibit highest price sensitivity; orthopedic OEMs in Baden-Württemberg show least sensitivity due to sterilization validation requirements.
Supply Chain Analysis
Dual-sourcing requirements now dominate procurement protocols as medical device OEMs lock in qualified supplier pairs for photoinitiator raw materials amid ECHA substance evaluation uncertainty. Supply concentrates in Germany, Japan, and China for specialty photoinitiator production. Formulation draws from acrylate monomer feedstocks, LED curing equipment components, and biocompatibility testing services. Single-source vulnerability persists for narrow-band LED chip supply from East Asian semiconductor foundries. Distribution runs through direct supply relationships for high-volume electronics manufacturers and specialized medical distributors for healthcare providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race where captive LED curing equipment production and in-house photoinitiator synthesis determine margin sustainability. Players are pursuing backward integration into specialty chemical production to escape input cost volatility.
For Market Incumbents: Extend formulation-equipment bundling partnerships to lock in specification control against emerging Asian LED curing specialists. Deepen captive photoinitiator production capabilities in Germany's Baden-Württemberg corridor to offset energy price spikes. Consolidate regional distributor networks in North American medical device clusters to defend channel position against direct-sourcing trends from contract manufacturers. For New Entrants and Emerging Players: Capture white-space in India's PLI-subsidized medical device manufacturing zones where localized adhesive supply chains remain underdeveloped. Target dual-cure formulation gaps in automotive sensor encapsulation where shadow-cure limitations constrain incumbent portfolios. Pursue toll manufacturing partnerships with established European formulators to bypass MDR CE marking timeline barriers. For Investors and Strategic Acquirers: ECHA photoinitiator reclassification proceedings are the leading indicator that formulation platform transitions will accelerate acquisition premiums for mercury-free chemistry specialists. Long-term viability hinges on bio-based monomer screening capabilities and LED wavelength alignment expertise. Acquisition targets should display captive photoinitiator R&D and hospital GPO contract access. Watch for LED curing equipment retrofit cycle inflection as mercury arc lamp disposal regulations tighten.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Photoinitiator Production | German formulators gain input cost control against Japanese specialty chemical suppliers. |
| Dual-Cure Formulation Development | Hybrid UV-moisture systems unlock shadow-cure capabilities in Stuttgart automotive sensor housings. |
| ISO 10993-5 Certification Fast-Track | Streamlined cytotoxicity testing reduces time-to-market for Baden-Württemberg orthopedic OEMs. |
| LED Equipment Bundling Partnerships | Narrow-band 405nm system integration locks in specification control with electronics contract manufacturers. |
| India PLI Zone Manufacturing Scale-Up | Domestic catheter producers in Maharashtra seek localized sterilization-resistant adhesive supply chains. |
Study Parameters
Trade databases, REACH registration filings, and FDA 510(k) clearance records formed the secondary backbone, supplemented by customs data on photoinitiator raw material flows. Primary interviews with adhesive formulation chemists, LED curing equipment procurement managers at automotive OEMs, medical device regulatory affairs leads, and hospital GPO contracts managers validated demand assumptions. Bottom-up and top-down triangulation cross-checked segment sizing against equipment installation bases and formulation production volumes.
Bottom-up modeling anchored volume projections to LED curing system deployment rates, photoinitiator consumption per bond line, and medical device assembly line expansions across the projection horizon. Segmentation dimensions spanned product type, application, end user, and technology with regional regulatory cluster overlays. CAGR derivation weighted historical equipment replacement cycles against RoHS mercury elimination mandate timelines. Industry-specific inputs included ECHA substance evaluation proceeding status and NMPA medical device registration pathway developments.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to photoinitiator regulatory reclassification timing and LED chip supply concentration risks. Deviation in REACH Annex XVII acrylate restriction implementation schedules would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Tobacco and Cigarette Adhesives Market
Adhesives & Sealants
Europe Sealants Market
Adhesives & Sealants
Global Bone Cement and Glue Market
Adhesives & Sealants
Wood Adhesives Market
Adhesives & Sealants
Asia-Pacific Flock Adhesives Market
Adhesives & Sealants
Wood Glue Market
Adhesives & Sealants
Middle-East and Africa Cyanoacrylate Adhesives Market
Adhesives & Sealants
Asia-Pacific EVA Adhesives Market
Adhesives & Sealants
Europe Contact Adhesives Market
Adhesives & Sealants
Cold Seal Adhesives Market
Adhesives & Sealants
South America Polyurethane (PU) Adhesives Market
Adhesives & Sealants
Acrylate Market
Adhesives & Sealants
South Korea Adhesives Market
Adhesives & Sealants
Wood Repair Epoxy Market
Adhesives & Sealants
PVA Glue Market
Adhesives & Sealants
Asia-Pacific Bone Glue Market