

Debonding-on-Demand Adhesive Tapes for Electronics Dismantling Market Size, Share, and Industry Trends Forecast 2026-2036
Debonding-on-Demand Adhesive Tapes for Electronics Dismantling Market Insights
German specialty chemical producers is repositioning capacity toward debonding tape substrates as circular-economy mandates tighten across the European electronics sector. Henkel leverages its adhesive formulation heritage to dominate thermally activated product development. tesa sustains precision coating capabilities that anchor its position in display assembly applications. 3M competes through geographic breadth and deep R&D reserves across multiple activation chemistries.
Debonding-on-demand adhesive tapes for electronics dismantling are pressure-sensitive or heat-reactive bonding systems engineered with controlled-release interfaces, typically 25–100 μm thick, that enable clean separation of electronic components without substrate damage during repair, recycling, or remanufacturing operations. Thermally activated tapes command the largest current volume as established PCB removal workflows favor predictable heat-triggered release, while UV-curable formats represent the fastest-expanding segment due to their compatibility with temperature-sensitive semiconductor packaging where localized energy input prevents thermal degradation. Deployment through automated systems concentrates margin pools, though semi-automated lines retain substantial share in mid-scale refurbishment facilities balancing throughput flexibility against capital constraints.
The EU Green Deal and REACH frameworks impose design-for-recycling obligations that directly expand addressable demand for certified debonding solutions, while EPA hazardous waste rules in the United States elevate compliance costs for solvent-based alternatives and redirect procurement toward cleaner activation chemistries. Japan's METI circular-economy guidelines for electronics further standardize dismantling protocols that favor validated tape systems. Stakeholders must monitor how rapidly evolving right-to-repair legislation across multiple jurisdictions reshapes specification requirements and certification burdens for adhesive suppliers.
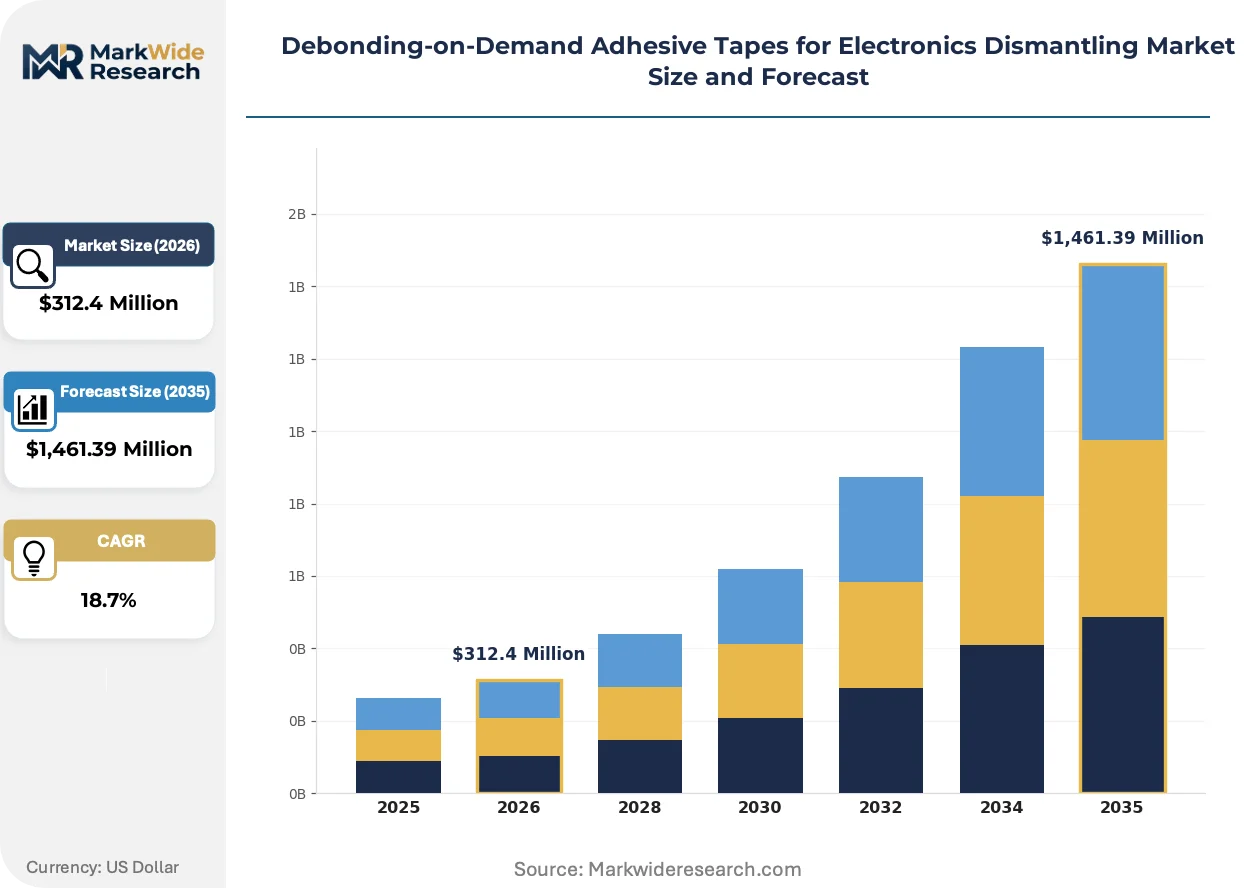
Market Dynamics
The EU Green Deal's design-for-recycling mandates are compressing specification cycles for adhesive suppliers as electronics manufacturers must certify dismantlable bonding systems before product launch. This regulatory pressure is forcing tape formulators to validate thermal release profiles against standardized removal protocols.
Growth Catalysts
- Right-to-repair legislation:The EU's expanding repairability requirements and similar U.S. state-level bills mandate component-level replaceability, creating certified demand for clean-release bonding systems in smartphone and laptop assembly.
- Circular economy frameworks:Japan's METI guidelines standardize electronics dismantling protocols, validating tape-based removal as preferred methodology over solvent dissolution in precision module recovery.
- Reflow soldering thermal budgets:Semiconductor packaging workflows now integrate thermally activated debonding layers that release within existing temperature windows, eliminating secondary processing steps.
Market Restraints
- Acrylic monomer supply concentration:Asian petrochemical producers control key pressure-sensitive adhesive feedstocks, exposing tape manufacturers to input cost volatility and geographic supply risk.
- UV-curable formulation complexity:Photoinitiator shelf-life limitations and oxygen-inhibition challenges constrain reliable field performance in ambient-activated formats.
- REACH substance restrictions:ECHA's evolving candidate list of substances of very high concern threatens legacy release-agent chemistries, forcing costly reformulation cycles.
Strategic Opportunities
- Indian refurbishment clusters:Emerging electronics repair hubs in Gujarat and Tamil Nadu lack standardized dismantling infrastructure, creating first-mover advantage for tape system suppliers offering technician training packages.
- EV battery module remanufacturing:Thermal runaway protection requirements in automotive battery packs favor thermally triggered separation layers that enable safe cell replacement without full pack destruction.
- AI-driven predictive bonding:Integration of machine-vision release monitoring with smart tape formulations that signal bond-state transition enables automated dismantling line integration.
Industry Challenges
- Cross-material certification timelines:Validating debonding performance across substrate combinations—glass, aluminum, FR-4, LCP—extends qualification periods and fragments R&D resources.
- Technician skill standardization:Refurbishment facilities in emerging markets lack trained personnel for heat-gun temperature control and dwell-time management, causing substrate damage that discredits tape-based methods.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Debonding-on-Demand Adhesive Tapes for Electronics Dismantling Market Trends and Innovations
Electronics dismantling workflows are converging on precision energy delivery systems that eliminate mechanical prying and solvent exposure. This shift favors adhesive formats with tightly calibrated activation windows.
Induction-responsive magnetic nanoparticle-doped tapes are rewriting thermal release paradigms by enabling localized, contactless heating. Semiconductor packaging houses in South Korea and Taiwan are piloting these systems for temperature-sensitive die-attach removal. The technology is compressing heat-affected zones from millimeters to sub-hundred-micron precision, protecting adjacent components.
REACH authorization requirements for diisocyanates and certain organotins are forcing formulators toward bio-based release chemistries derived from terpenes and plant oils. ECHA's 2023 restriction proposals triggered accelerated R&D programs at European specialty chemical producers. The regulatory pressure is elevating compliance costs for solvent alternatives while validating tape-based clean-release methods.
Refurbishment procurement is consolidating around certified dismantling partners as OEM warranty programs and insurance-backed repair networks demand auditable component recovery rates. This buyer concentration is displacing informal repair channels in Germany and France. The shift is most visible in smartphone display replacement, where authorized service providers now specify thermally validated tape systems to maintain substrate integrity guarantees.
Debonding-on-Demand Adhesive Tapes for Electronics Dismantling Market Segmentation
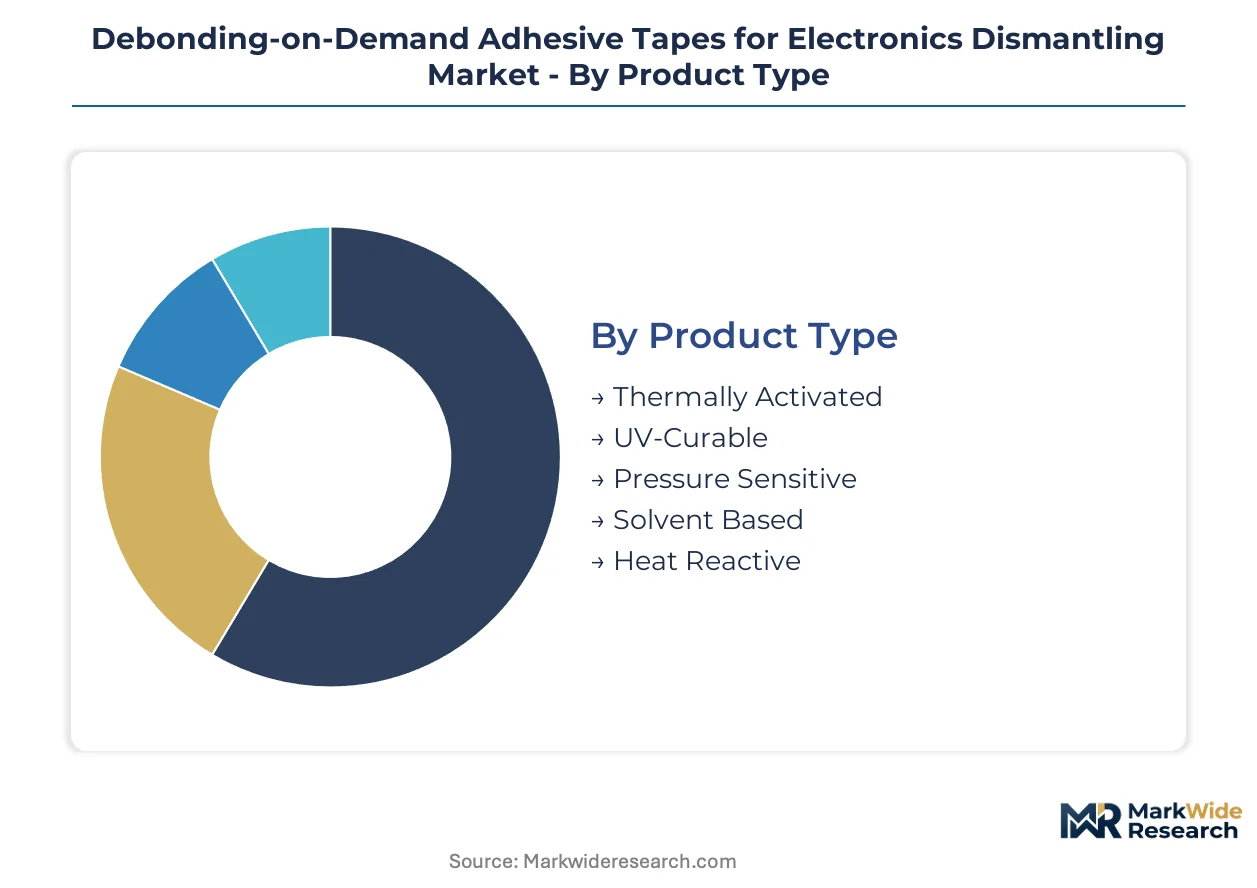
Debonding-on-demand adhesive tapes serve divergent workflow requirements across electronics dismantling operations. Tape selection hinges on thermal budget constraints, substrate fragility, and automation compatibility. Specification mismatches between product format and application drive costly rework or component damage.
Product Type:
Thermally activated formats dominate volume shipments while UV-curable products command premium positioning for temperature-sensitive applications.
- Thermally Activated:Heat-triggered release layers, typically 50–80 μm thick, incorporate engineered phase-change interfaces. PCB removal workflows in German refurbishment facilities favor these formats for predictable release profiles within standardized temperature windows.
- UV-Curable:Photoinitiator-activated systems enable localized bond disruption without thermal propagation. Semiconductor packaging houses in Taiwan and South Korea specify these for die-attach removal where adjacent components cannot tolerate heat exposure.
- Pressure Sensitive:Room-temperature tack with peelable release characteristics suits rapid prototyping and temporary fixture applications.
- Solvent Based:Chemical dissolution mechanisms face declining adoption as REACH substance restrictions elevate compliance burdens.
- Heat Reactive:Modified thermal chemistries with lower activation thresholds serve display assembly where glass substrates risk thermal shock.
Mature deployment sits with thermally activated formats. Newer deployment is concentrated in UV-curable segments.
Application:
Repair-driven applications generate recurring demand while manufacturing-integrated applications anchor contract volumes.
- PCB Removal:Board-level separation from housings and heat sinks requires controlled release without pad lifting or trace damage. Japanese electronics service providers specify validated tape systems for warranty-compliant smartphone motherboard extraction.
- Component Recycling:Precious metal recovery from obsolete devices demands clean substrate separation. EU WEEE directive compliance drives certified dismantling protocol adoption across French and Italian processing facilities.
- Display Assembly:OLED and LCD panel bonding applications require optical-grade clarity and residue-free release for rework scenarios.
- Semiconductor Packaging:Die-attach and underfill replacement in advanced packaging workflows favors precision activation formats.
- Module Repair:Camera, sensor, and connector module replacement in compact devices demands sub-millimeter placement accuracy.
High-throughput deployment concentrates in PCB removal. Precision-critical deployment is expanding fastest in semiconductor packaging.
End User:
OEM-integrated procurement drives specification standardization while independent service channels prioritize cost flexibility.
- Electronics Manufacturers:Design-for-recycling mandates from the EU Green Deal require dismantlable bonding validation before product launch. Original equipment manufacturers in Germany and the Netherlands now specify debonding tape systems in supplier quality agreements.
- Refurbishment Facilities:Authorized repair networks demand auditable component recovery rates. Certified dismantling partners in France and Germany consolidate procurement around validated tape suppliers to maintain warranty program eligibility.
- Repair Centers:Independent service operations balance tape cost against technician training requirements.
- Research Labs:Prototyping and failure analysis applications drive small-volume demand for experimental formulations.
- Quality Assurance Units:Incoming inspection and reliability testing protocols require controlled bond separation for destructive analysis.
Contracted volume concentrates with electronics manufacturers. Emerging demand is accelerating in refurbishment facilities.
Deployment:
Capital intensity separates high-volume automated installations from flexible manual operations.
- Automated Systems:Conveyor-integrated heat stations with machine-vision alignment enable sub-second cycle times. South Korean display panel producers deploy these lines for mass-production rework stations.
- Manual Processes:Hand-held heat guns and peel fixtures dominate low-volume repair shops where capital constraints prevent automation investment.
- Robotic Integration:Six-axis arms with force-feedback peeling adapt to component geometry variation. Taiwan semiconductor packaging houses pilot these systems for die-attach replacement.
- Semi-Automated Lines:Benchtop stations with programmable thermal profiles balance throughput and flexibility for mid-scale refurbishment operations.
- Portable Units:Battery-powered induction heating tools serve field repair scenarios without facility infrastructure.
Margin concentration aligns with automated systems. Capability expansion is proceeding fastest in robotic integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Acrylic monomer feedstock concentration across Northeast Asian petrochemical corridors shapes regional supply security calculations for tape formulators worldwide.
Germany
Smartphone refurbishment operations in Bavaria and North Rhine-Westphalia are scaling adhesive tape procurement as the EU Green Deal mandates design-for-recycling standards. ECHA's REACH substance restrictions force legacy release-agent reformulation toward bio-based terpene chemistries. Henkel and tesa anchor precision coating capabilities in Düsseldorf and Hamburg metropolitan clusters.
China
Electronics dismantling protocol tightening by MIIT is redirecting informal recycling channels toward certified tape-based methodologies. The country's national environmental regulator enforces hazardous waste rules that elevate compliance costs for solvent alternatives. Yangtze River Delta precision electronics clusters in Jiangsu and Shanghai favor thermally activated formats for module repair workflows.
Japan
METI circular-economy guidelines for electronics standardize dismantling protocols that validate tape systems over solvent dissolution. Osaka and Nagoya precision electronics clusters concentrate demand for thermally activated formats with predictable release profiles. Nitto Denko and LINTEC maintain formulation heritage serving semiconductor packaging houses in Kyushu.
South Korea
Display panel producers in Gyeonggi Province deploy automated conveyor-integrated heat stations for mass-production rework. The country's national industrial regulator supports pilot programs for induction-responsive magnetic nanoparticle-doped tapes enabling contactless heating. Seoul Capital Area semiconductor packaging houses are testing UV-curable formats for die-attach removal.
United States
State-level right-to-repair bills in California and New York mandate component-level replaceability creating certified demand for clean-release bonding systems. EPA hazardous waste rules elevate compliance costs for solvent-based alternatives redirecting procurement toward cleaner activation chemistries. Austin and Boston metropolitan refurbishment networks consolidate around authorized service provider specifications.
Debonding-on-Demand Adhesive Tapes for Electronics Dismantling Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialty activation chemistries and regional certification partnerships. The supplier base concentrates among diversified adhesive formulators with precision coating infrastructure and electronics industry qualification heritage. Three archetypes dominate: heritage chemical conglomerates with adhesive divisions, specialized tape manufacturers with coating capabilities, and diversified materials science multinationals. Competitive moves center on bio-based formulation R&D and geographic expansion into emerging refurbishment clusters.
Among heritage chemical conglomerates, Henkel and 3M exemplify scale-driven positioning through formulation breadth and geographic coverage. Specialized tape manufacturers tesa and Nitto Denko occupy positions anchored in precision coating capabilities and regional electronics cluster proximity. These four represent the competitive core, with Lohmann and LINTEC sitting within mid-tier specialist archetypes serving module-specific applications.
| Leading Market Players |
|---|
| Henkel |
| tesa |
| Lohmann |
| 3M |
| Nitto Denko |
| LINTEC |
| Avery Dennison |
| Saint-Gobain |
| Intertape Polymer Group |
| Others |
Pricing and Supply Chain Analysis
EU Green Deal certification requirements for dismantlable bonding systems are compressing supplier qualification timelines and forcing tape formulators to absorb validation costs, which concentrates margin pressure on mid-tier producers lacking scale economies. This specification tightening rewards incumbents with established ECHA REACH dossiers while fragmenting procurement among authorized service networks that demand auditable recovery rates.
Pricing Analysis
Warranty-backed service bundling separates premium-tier tape suppliers from commodity competitors, with authorized refurbishment networks in Germany and France paying 15-25% markups for validated thermal-release profiles and technician training packages. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale, with OEM-integrated procurement least sensitive to unit cost and independent repair shops in emerging markets driving aggressive price negotiation. Pricing pressure stems from acrylic monomer feedstock volatility concentrated among Asian petrochemical producers, compressing margins for formulators without backward integration into adhesive resin production.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Singapore, and Los Angeles anchor hub-and-spoke patterns serving precision electronics clusters, with inventory positioning critical to meeting just-in-time refurbishment schedules. Acrylic monomer production concentrates in South Korea, Japan, and China, while precision coating capabilities cluster in Germany and Japan, creating geographic interdependency across formulation and substrate manufacturing. Single-source vulnerability runs through photoinitiator supply for UV-curable segments, where Japanese and German specialty chemical producers control key patent-protected molecules. Distribution runs through authorized distributor networks serving certified dismantling partners, with direct procurement relationships emerging for high-volume OEM contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around REACH-compliant formulators as ECHA substance restrictions eliminate legacy release-agent suppliers lacking reformulation capacity. Weaker players without precision coating infrastructure or electronics industry qualification heritage face forced exit.
For Market Incumbents: Hedge against bio-based chemistry transition costs by securing terpene feedstock partnerships with European agricultural processors before REACH authorization deadlines tighten. Incumbent tape manufacturers must accelerate backward integration into release-agent synthesis to defend margin position against specialty chemical suppliers capturing value from reformulation cycles. Capacity expansion in Indian refurbishment clusters offers geographic diversification as EU specification cycles compress domestic growth. For New Entrants and Emerging Players: E-commerce direct procurement channels serving independent repair shops in Gujarat and Tamil Nadu bypass entrenched distributor relationships that lock out unqualified suppliers. New entrants should target semi-automated refurbishment facilities seeking cost-flexible alternatives to Henkel and tesa premium positioning, with technician training bundles as the primary go-to-market wedge. UV-curable die-attach removal for semiconductor packaging houses in Taiwan and South Korea represents the most penetrable white-space segment. For Investors and Strategic Acquirers: The window for entry favors precision coating specialists with existing electronics qualification heritage rather than de novo adhesive formulators facing extended certification timelines. Acquisition targets should demonstrate validated thermal-release profiles across substrate combinations and established supplier quality agreements with German or Japanese OEMs. The signal to watch is MIIT enforcement intensity in China, which will determine whether certified tape-based methodologies displace informal solvent dissolution channels at scale.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylic Monomer Production | Captive supply from South Korean petrochemical corridors insulates margin pressure from feedstock volatility. |
| REACH-Compliant Bio-Based Formulation R&D | Terpene-derived release chemistries from European agricultural processors preempt ECHA authorization restrictions. |
| Technician Training Package Deployment | Certified dismantling protocols in Indian refurbishment clusters create switching costs and recurring revenue. |
| Induction-Responsive Magnetic Nanoparticle Tape Development | Contactless heating systems piloted in South Korean display panel producers enable sub-hundred-micron precision. |
| Long-Term Supply Agreement with OEM Authorized Service Networks | Auditable component recovery rates in French and German warranty programs lock out informal repair channels. |
Research Methodology
Multi-period observation of debonding tape procurement volumes, ECHA REACH regulatory filings, and OEM supplier quality agreement disclosures anchored the trend analysis, supplemented by interviews with plant managers at German precision coating facilities, procurement leads at Taiwanese semiconductor packaging houses, distribution channel partners serving Indian refurbishment clusters, and technical R&D directors at specialty chemical producers. Secondary validation drew from customs and trade data tracking acrylic monomer flows, SEC 10-K filings of diversified adhesive formulators, and MIIT electronics dismantling protocol enforcement records. Bottom-up segment sizing triangulated against top-down market construction from end-use electronics production data.
Input-output matrices modeled tape demand as a function of smartphone refurbishment volumes, PCB removal workflows, and semiconductor packaging growth across product type, application, end user, and deployment mode dimensions. CAGRs derived from regression analysis of historical procurement patterns projected forward against regulatory mandate implementation schedules and right-to-repair legislative expansion. Forecast inputs incorporated reflow soldering thermal budget constraints and induction-responsive activation technology adoption curves without assuming technology substitution timelines.
Inputs from ECHA regulatory databases and OEM supplier quality agreement registries were available through the study window; gaps in informal recycling channel volume estimates and technician training completion rates introduce uncertainty bands around emerging market penetration assumptions. Forecasts reflect documented assumptions regarding REACH substance restriction implementation and MIIT enforcement intensity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.