
 Spain Sealants Market | 2026-2036
Spain Sealants Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Sealants Market Analytics
Technical advisory and specification services is decoupling product sales from pure volume metrics across the Spain sealants landscape. Dow leverages its silicone chemistry portfolio to anchor specification relationships with large infrastructure consortia. Sika AG competes through construction-system bundling that extends beyond standalone sealant SKUs into waterproofing and concrete repair. Henkel AG & Co. KGaA differentiates via automotive OEM direct channels, sustaining higher-margin positions in bonded glazing applications.
Sealants are polymeric materials formulated to fill joints, gaps, and seams while maintaining elastomeric properties across temperature cycles from minus forty to plus one hundred fifty degrees Celsius; they cure through moisture reaction, solvent evaporation, or UV initiation to form impermeable barriers against air, water, and chemical ingress. Silicone formulations dominate commercial building envelopes due to superior UV resistance and movement accommodation, while polyurethane anchors industrial flooring and automotive seam-sealing where abrasion resistance and paint compatibility matter. Acrylic occupies the cost-sensitive DIY renovation tier through retail channels, though its limited elongation constrains structural joint applications.
Spain's Technical Building Code (CTE) and the Ministry of Transport's RD 314/2006 framework mandate thermal bridge mitigation and airtightness testing, directly expanding specification-grade sealant volumes in new construction and deep retrofit projects. CE marking under the Construction Products Regulation (CPR) and EPDM compliance with REACH chemical restrictions shape import competitiveness and domestic formulation requirements. Stakeholders must monitor how Spain's transposition of the EU Green Deal renovation wave targets into regional building permit conditions will redirect demand toward high-performance hybrid sealants capable of fifty-year service life claims.
Market Dynamics
Spain's Technical Building Code (CTE) mandates stricter energy efficiency standards for building envelopes, forcing specification-grade sealant volumes upward in new construction and deep retrofit projects across Mediterranean coastal provinces.
Growth Catalysts
- CTE airtightness mandates:Thermal bridge mitigation requirements under RD 314/2006 expand specification-grade silicone volumes in Madrid and Barcelona residential towers.
- Tourism-driven renovation cycles:Mediterranean coastal provinces accelerate replacement schedules for hospitality facades and resort infrastructure.
- Low-VOC formulation shifts:Madrid and Barcelona contractors specify zero-solvent silicones for indoor air quality compliance in premium residential.
Market Restraints
- Silicone monomer supply concentration:European precursor manufacturing clusters in Germany and Belgium create import dependency for Spanish formulators.
- Acrylic substitution ceiling:Limited elongation properties prevent acrylic sealants from penetrating structural movement joints in commercial envelopes.
- REACH compliance friction:ECHA substance restrictions on tin catalysts force reformulation cycles and registration costs for hybrid polyurethane-silicones.
Strategic Opportunities
- Andalusian hospitality retrofit wave:Costa del Sol resort municipalities face accelerated facade renewal timelines tied to tourism license renewals.
- EU Green Deal renovation targets:Spain's transposition of 2030 building stock efficiency goals redirects public procurement toward fifty-year service life hybrid sealants.
- Direct contractor specification channels:Technical advisory services decouple sealant sales from distributor volume metrics in large infrastructure consortia.
Industry Challenges
- Certified applicator scarcity:CE marking under CPR demands trained installation crews for structural glazing, constraining project throughput in Galicia and Asturias.
- Multi-substrate compatibility testing:Deep retrofit projects require validated adhesion across legacy concrete, new insulation, and metal flashings, extending specification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Sealants Market |
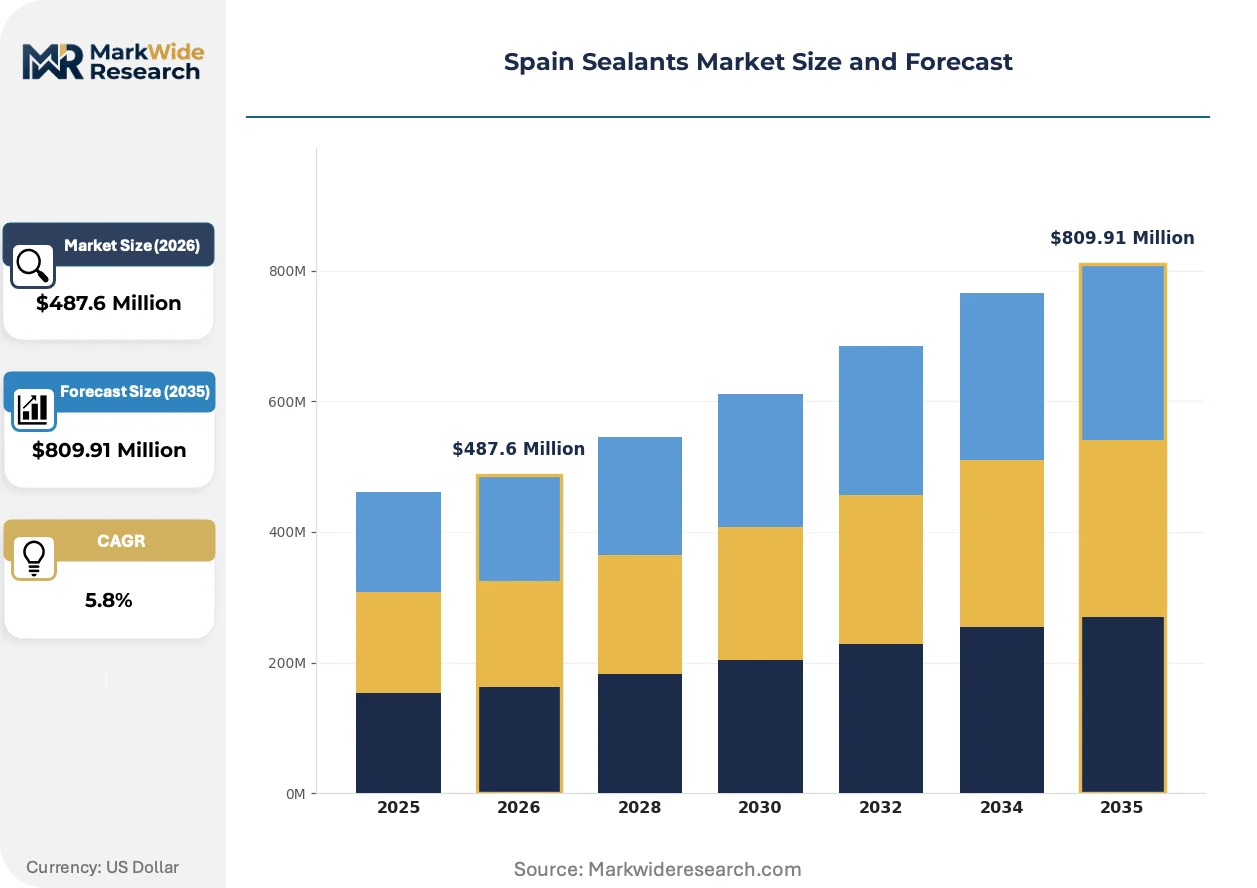
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $809.91 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylic, Polyurethane, Silicone, EPDM Application: Construction, Automotive, Electronics, Marine End User: Contractors, OEMs, Manufacturers, DIY Distribution Channel: Online, Retail, Wholesale, Direct Sales |
| Companies Covered | Dow, Henkel AG & Co. KGaA, Sika AG, Grupa Selena, MAPEI S.p.A., 3M, H.B. Fuller Company, BASF SE, Arkema SA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Sealants Market Evolving Landscape
Formulation chemistry and specification workflows are converging around performance guarantees and automated quality assurance, compressing traditional procurement cycles in Spanish construction.
Hybrid silyl-terminated polyurethane technology is automating specification decisions through predictive service life modeling. Large Madrid infrastructure consortia now require fifty-year performance warranties backed by accelerated aging data. This automation is compressing supplier qualification timelines and favoring formulators with in-house rheology and weathering laboratories.
Spain's transposition of EU Green Deal renovation wave targets into regional building permit conditions is redirecting public procurement budgets. Municipalities in Barcelona province now mandate EPD-certified sealants for facade renovation subsidies. Deep retrofit contractors respond by pre-qualifying hybrid formulations with published environmental product declarations.
Technical specification unbundling from product distribution is reshaping procurement relationships in Spanish construction. Large residential developers in Valencia and Alicante provinces now contract directly with formulator technical service teams for joint design and warranty packages. This pattern concentrates specification authority with manufacturers possessing in-house building physics expertise and certified installation training networks.
Spain Sealants Market Segmentation
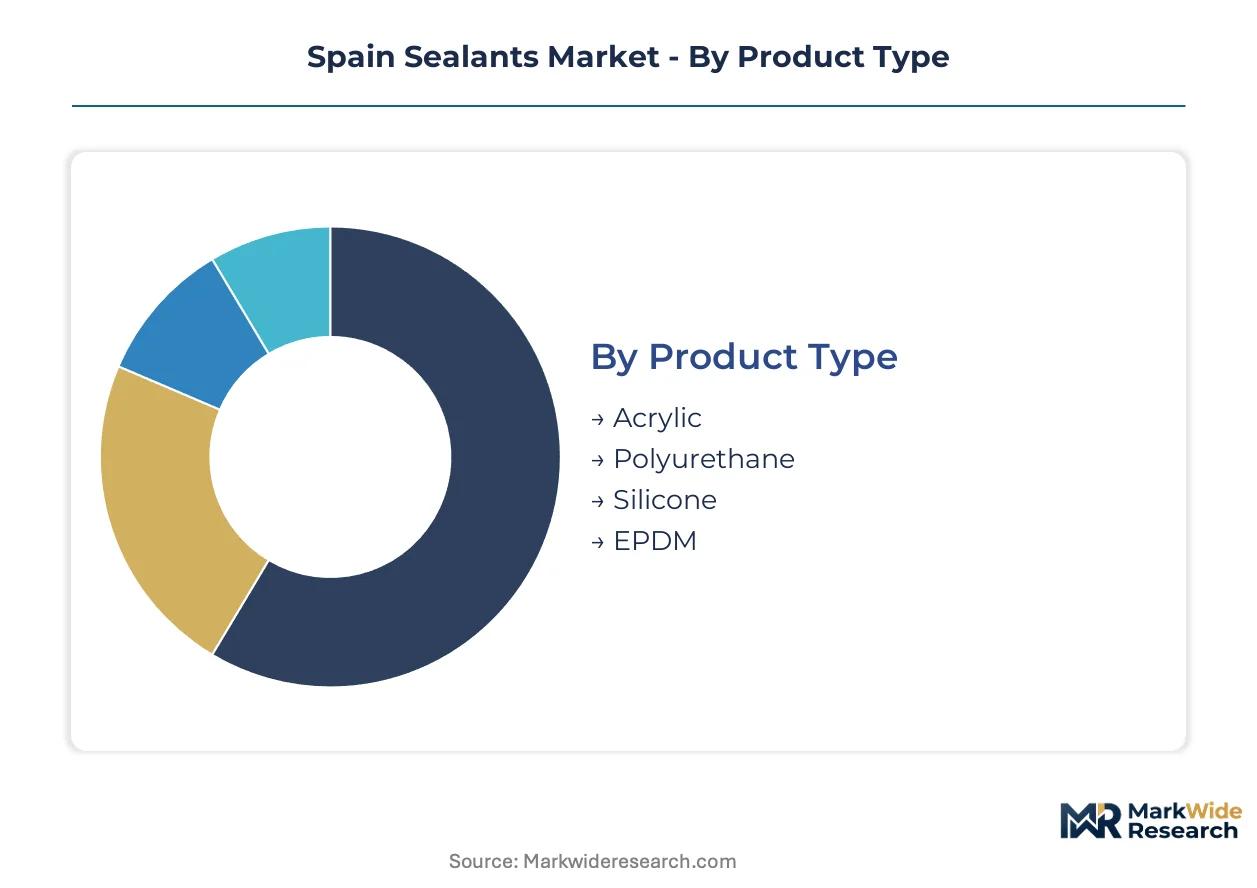
Segmentation in Spain's sealants market tracks how regulatory certification requirements split across product chemistries and end-use applications. CE marking under the Construction Products Regulation and EPDM compliance with REACH substance restrictions create divergent compliance burdens that reshape procurement priorities for contractors and industrial buyers.
Product Type:
CE marking mandates and REACH catalyst restrictions impose tiered certification burdens across sealant chemistries, with structural glazing applications demanding the most intensive documentation.
- Silicone:Moisture-curing polysiloxane formulations deliver UV resistance and movement accommodation exceeding fifty percent. Madrid and Barcelona residential towers specify zero-solvent grades for CTE airtightness compliance, with large infrastructure consortia now requiring fifty-year performance warranties backed by accelerated aging data.
- Polyurethane:Isocyanate-terminated prepolymers cure through atmospheric moisture to form abrasion-resistant elastomers. Industrial flooring and automotive seam-sealing in Basque Country manufacturing clusters favor these formulations where paint compatibility and mechanical durability outweigh UV exposure concerns.
- Acrylic:Water-based emulsions serve cost-sensitive DIY renovation through retail channels in Valencia province, though limited elongation constrains structural joint penetration.
- EPDM:Ethylene-propylene-diene monomer rubber compounds face ECHA substance restrictions on tin catalysts that force reformulation cycles for Spanish formulators.
Silicone sits at the top of the volume ranking, with polyurethane climbing the fastest as Basque automotive and industrial flooring specifications expand.
Application:
End-use applications diverge sharply in specification authority, with construction channeling technical advisory through formulator-direct relationships while automotive maintains OEM-controlled qualification protocols.
- Construction:Building envelope sealing dominates specification-grade volumes, driven by CTE thermal bridge mitigation and deep retrofit projects across Mediterranean coastal provinces. Costa del Sol resort municipalities face accelerated facade renewal timelines tied to tourism license renewals.
- Automotive:Bonded glazing and seam-sealing applications sustain higher-margin positions through direct OEM channels, with Henkel AG maintaining specification relationships with Basque Country assembly plants.
- Electronics:Potting and encapsulation demand concentrates in Catalonia's semiconductor packaging subcontractors, where REACH compliance on residual isocyanates shapes import competitiveness.
- Marine:Below-deck sealing and hull bonding applications in Galicia and Asturias shipyards require certified applicator networks that constrain project throughput.
Construction commands the largest specification volume, with marine gaining share fastest as Galicia port infrastructure investments accelerate.
End User:
Procurement authority concentrates differently across user types, with contractors exercising growing technical specification influence while OEMs retain tight formulation control.
- Contractors:Large residential developers in Valencia and Alicante provinces now contract directly with formulator technical service teams for joint design and warranty packages, decoupling sealant sales from distributor volume metrics.
- OEMs:Automotive and electronics manufacturers enforce captive qualification protocols that lock in approved supplier lists for multi-year production cycles.
- Manufacturers:Industrial sealant consumers in Basque Country and Catalonia prioritize in-house building physics expertise for multi-substrate compatibility validation.
- DIY:Retail-channel purchasers in Madrid and Barcelona metropolitan areas drive acrylic volumes through home improvement chains, with limited elongation awareness constraining application scope.
Contractors represent the most influential specification channel, with manufacturers expanding procurement authority fastest through backward integration into technical advisory.
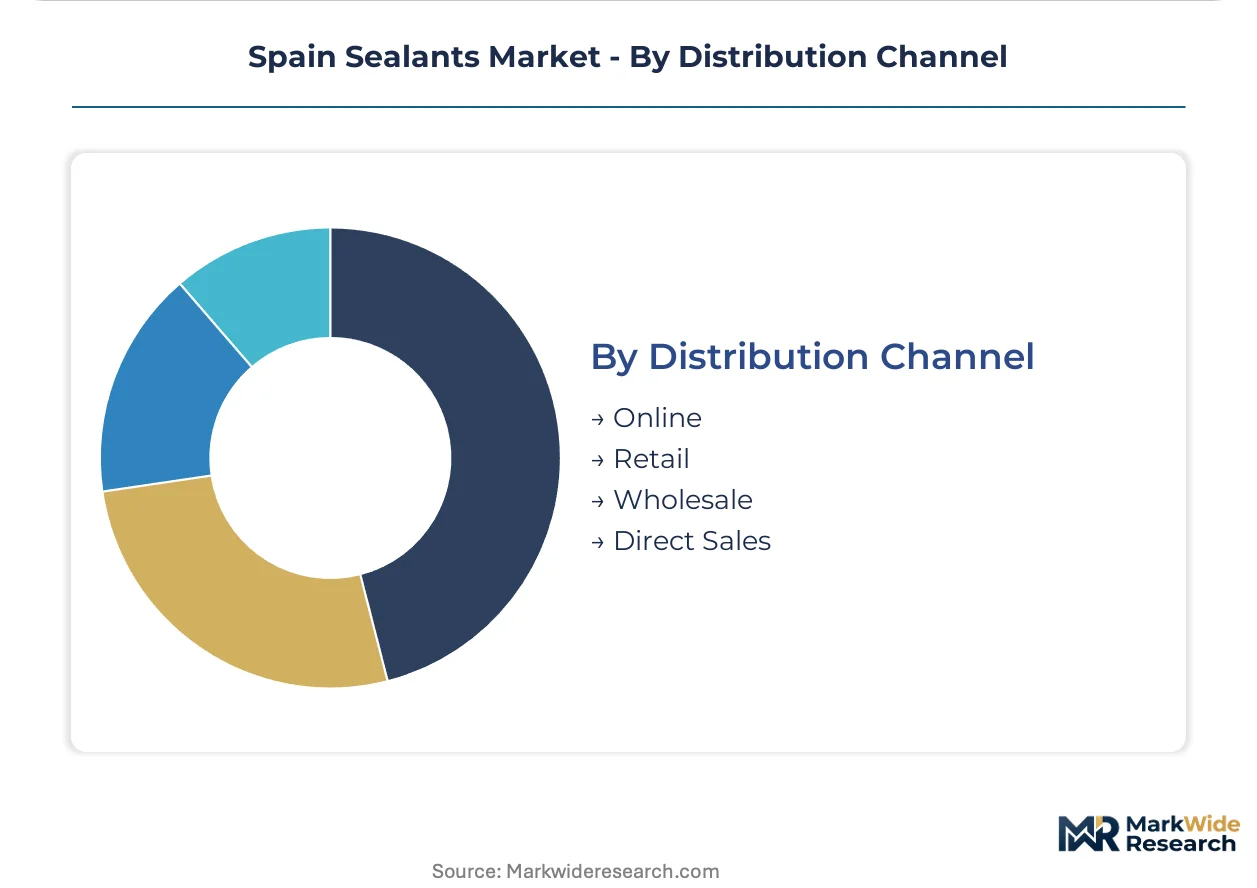
Distribution Channel:
Channel structure reflects the unbundling of technical specification from physical distribution, with direct sales capturing premium warranty relationships.
- Direct Sales:Formulator technical service teams engage large infrastructure consortia and residential developers for joint design, compressing traditional distributor procurement cycles.
- Wholesale:Construction merchant distributors serve mid-tier contractors in Andalusia and Murcia with stocked silicone and polyurethane SKUs.
- Retail:Home improvement chains and specialized building material stores channel acrylic formulations to DIY renovators in urban centers.
- Online:E-commerce platforms capture specification-grade procurement for standardized construction applications with documented CE marking.
Direct sales leads in value concentration, with online expanding most quickly as standardized product data sheets reduce specification friction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates silicone precursor manufacturing while Spain channels demand through Mediterranean coastal renovation cycles. Construction chemical formulators navigate divergent regulatory timelines across European member states.
Madrid
Residential tower contractors specify zero-solvent silicone grades for CTE airtightness compliance. RD 314/2006 thermal bridge mandates expand specification-grade volumes. Large infrastructure consortia demand fifty-year performance warranties backed by accelerated aging data.
Catalonia
Barcelona's premium residential developers contract directly with formulator technical service teams. EPD-certified sealants are mandated for facade renovation subsidies under EU Green Deal transposition. Semiconductor packaging subcontractors in the region drive electronics potting demand.
Basque Country
Automotive assembly plants sustain bonded glazing specifications through direct OEM channels. Industrial flooring applications favor polyurethane formulations where abrasion resistance outweighs UV exposure. Manufacturing clusters prioritize paint compatibility in seam-sealing applications.
Andalusia
Costa del Sol resort municipalities face accelerated facade renewal timelines tied to tourism license renewals. Hospitality-driven renovation cycles compress replacement schedules for sealant applications. Wholesale distributors serve mid-tier contractors with stocked silicone and polyurethane SKUs.
Valencia
Large residential developers decouple sealant sales from distributor volume metrics through direct formulator relationships. Retail channels channel acrylic formulations to DIY renovators in metropolitan areas. Home improvement chains capture cost-sensitive renovation demand.
Spain Sealants Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with specification-grade construction applications concentrating authority among technical service providers. The vendor base organizes around chemistry expertise, construction-system bundling, and automotive OEM direct channels. Three archetypes dominate: silicone chemistry specialists, construction-system integrators, and automotive adhesive direct suppliers. M&A activity targets formulation technology access, while capacity investments concentrate in hybrid silyl-terminated polyurethane production.
Among diversified chemical conglomerates, Dow and BASF SE anchor positions through materials science portfolios spanning silicone and polyurethane chemistries. Sika AG exemplifies the construction-system bundling archetype, extending beyond standalone sealant SKUs into adjacent waterproofing and concrete repair. Henkel AG & Co. KGaA occupies the automotive direct-channel position, sustaining specification relationships with OEM assembly networks. Grupa Selena and MAPEI S.p.A. represent regional specialists with concentrated Southern European market presence.
| Leading Market Players |
|---|
| Dow |
| Henkel AG & Co. KGaA |
| Sika AG |
| Grupa Selena |
| MAPEI S.p.A. |
| 3M |
| H.B. Fuller Company |
| BASF SE |
| Arkema SA |
| Others |
Value Network & Pricing Analysis
Hybrid silyl-terminated polyurethane technology is compressing specification timelines while simultaneously concentrating production economics among formulators with captive rheology laboratories. This chemistry transition rewards backward integration into silicone precursor streams and in-house weathering capabilities, tightening margin structures for distributors lacking technical advisory capacity.
Pricing Analysis
Capacity additions in Germany and Belgium are reshaping price floors for silicone monomer feedstocks reaching Spanish formulators. Three-tier pricing structure across premium, standard, and economy levels separates fifty-year warranty hybrid formulations from commodity silicone and DIY acrylic tiers. Cost compression in standard-grade silicone is intensifying because Madrid infrastructure consortia now demand bundled technical service packages. DIY renovators in Valencia metropolitan areas exhibit highest price sensitivity, while Basque automotive OEMs accept premium positioning for bonded glazing qualifications.
Supply Chain Analysis
Spain's CTE airtightness mandates and EU Green Deal renovation targets are reshaping sourcing priorities toward EPD-certified domestic formulators. Silicone precursor manufacturing concentrates in Germany, Belgium, and France, with Spanish compounders drawing from these clusters. Tin catalyst restrictions under ECHA REACH compliance create formulation dependencies on alternative curing systems. Single-source vulnerability runs through German silicone monomer clusters. Distribution runs through direct technical service teams for large infrastructure consortia, wholesale merchants for mid-tier Andalusian contractors, and retail chains for metropolitan DIY demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spain's sealants market functions as a regulatory compounder where CTE thermal bridge mandates and EU Green Deal transposition create sustained specification-grade demand. RD 314/2006 and municipal facade renovation subsidies generate multi-year procurement visibility for compliant formulators.
For Market Incumbents: Anchor specification authority through certified installation training networks in Galicia and Asturias where applicator scarcity constrains project throughput. Deepen backward integration into silyl-terminated polyurethane chemistry to capture fifty-year warranty premiums. Defend against hybrid formulation entrants by locking large Madrid infrastructure consortia into joint design contracts that bundle technical advisory with volume commitments. For New Entrants and Emerging Players: The price-point gap between premium hybrid warranties and economy acrylic tiers creates entry space for mid-grade silicone formulations with published EPDs. Target Andalusian hospitality retrofit contractors facing accelerated facade renewal timelines tied to tourism license renewals. Pursue direct specification relationships with Valencia residential developers who have already decoupled procurement from traditional distributor channels. For Investors and Strategic Acquirers: Valuations sit cheapest among regional construction chemical specialists lacking in-house building physics expertise. Five-to-ten-year viability favors formulators with captive rheology laboratories and EPD certification capabilities. Watch for inflection when Costa del Sol municipalities begin withholding tourism licenses from properties failing facade airtightness testing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicone Precursor Supply | German and Belgian monomer clusters anchor cost structures for Spanish formulators seeking margin control. |
| EPD Certification Investment | Barcelona province subsidies now mandate environmental product declarations for facade renovation eligibility. |
| Certified Applicator Network Expansion | CE marking under CPR demands trained crews for structural glazing in Galicia and Asturias shipyards. |
| Hybrid Formulation R&D Scale-Up | Silyl-terminated polyurethane technology automates specification decisions through predictive service life modeling. |
| Direct Contractor Channel Development | Large Valencia and Alicante developers now contract directly with formulator technical service teams for warranty packages. |
Research Methodology
Coverage spans Madrid, Catalonia, Basque Country, Andalusia, and Valencia, with primary inputs from each autonomous community. Primary interviews with construction chemical plant managers, procurement leads at residential developers, distribution channel partners, and technical R&D directors combined with secondary validation from Spanish customs data, Ministry of Transport regulatory filings, and Construction Products Regulation certification databases. Bottom-up demand modeling and top-down supply triangulation cross-validated volume estimates.
Rate-of-change decomposition across the projection horizon isolates CTE mandate impacts, tourism cycle effects, and chemistry substitution elasticities. Segmentation dimensions include formulation chemistry, end-use application, procurement authority type, and regional construction permit velocity. CAGRs derive from fitted adoption curves for hybrid sealants and replacement cycle compression in Mediterranean coastal provinces. Industry-specific inputs incorporate Basque automotive production schedules and Costa del Sol hospitality license renewal data.
Caveats apply where ECHA catalyst restriction enforcement or EU Green Deal funding allocation delays could materially shift the outlook. Forecasts reflect assumptions about regulatory transposition timelines and certified applicator training throughput. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
South America Electronics Adhesives Market
Adhesives & Sealants
De-Seamable Adhesives Market
Adhesives & Sealants
Japan Adhesives Market
Adhesives & Sealants
Gasket and Seal Material Market
Adhesives & Sealants
Fabric Glue Market
Adhesives & Sealants
Adhesives and Sealants Distribution Market
Adhesives & Sealants
Australia Sealants Market
Adhesives & Sealants
Global Bioadhesive Market
Adhesives & Sealants
Global Dental Adhesives and Sealants Market
Adhesives & Sealants
Global Adhesives Market
Adhesives & Sealants
Low VOC Adhesive Market
Adhesives & Sealants
North America Waterborne Adhesives Market
Adhesives & Sealants
Roofing Adhesive Market
Adhesives & Sealants
China Sealants Market
Adhesives & Sealants
Aviation Adhesives and Sealants Market
Adhesives & Sealants
South America Polyurethane (PU) Hot-Melt Adhesives Market