
 Leather Glue Market | 2026-2036
Leather Glue Market Size, Share, and Industry Trends Forecast 2026-2036
Leather Glue Market Analytics
Modular adhesive kits that pair leather glue with surface prep agents and applicator tools are broadening buyer choice across small-batch furniture workshops and independent cobblers. Bhiwadi Polymers Ltd. anchors its position through captive manufacturing of synthetic resin intermediates in Rajasthan. Hunan Magpow Adhesive Group dominates water-based formulations for the domestic footwear export sector. Atlas Adhesives differentiates via specialized bonding systems for automotive upholstery trim.
Leather glue comprises adhesive formulations engineered to bond collagen-based hides and skins to substrates including rubber, foam, metal, and textile layers, typically achieving peel strengths between 3.5 and 8.0 N/mm depending on formulation chemistry and curing mechanism. Water-based acrylic and polyurethane dispersions now lead volume in regulated markets where VOC thresholds have tightened, while hot melt adhesives are gaining fastest in automated footwear assembly lines due to instant tack and elimination of drying stages. Solvent-based neoprene contact cements retain margin concentration in luxury leather goods where open-time flexibility and ultimate bond strength remain non-negotiable.
REACH in Europe and EPA TSCA in the United States restrict aromatic solvent content and isocyanate exposure limits, compelling reformulation toward low-VOC waterborne and reactive hot melt platforms. India's BIS certification for adhesive products adds a compliance gate for imported formulations entering the domestic leather goods supply chain. Stakeholders must monitor evolving chemical hazard classifications under ECHA SVHC candidate lists and calibrate R&D pipelines toward bio-based polyol feedstocks before regulatory thresholds harden into outright bans.
Market Dynamics
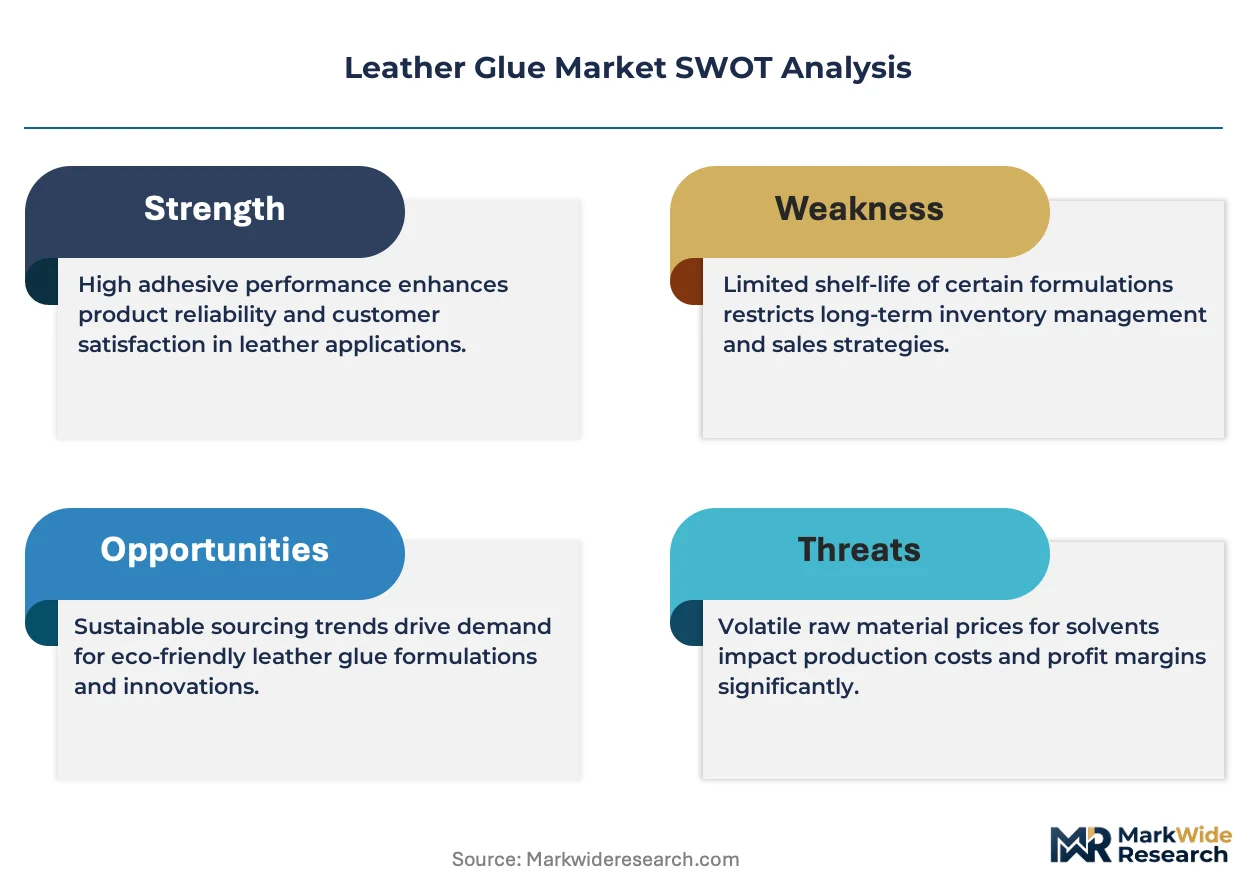
Water-based polyurethane dispersions are rewriting competitive positioning in leather glue as REACH solvent limits harden and footwear brands demand instant-tack alternatives to neoprene contact cements.
Growth Catalysts
- REACH VOC thresholds:European manufacturers face mandatory reformulation timelines that accelerate waterborne adhesive adoption across luxury goods workshops.
- India's PLI scheme for leather and footwear:Fresh capacity investments in Tamil Nadu and Uttar Pradesh are pulling adhesive demand from domestic and import sources alike.
- Hot melt systems:Automated footwear assembly lines in Vietnam and Ethiopia are eliminating drying stages through reactive polyurethane hot melts.
Market Restraints
- Petrochemical polyol volatility:Crude-linked input costs for synthetic resin intermediates compress margin predictability for captive manufacturers.
- Isocyanate exposure limits:EPA TSCA and ECHA classifications are restricting formulation chemistries that underpin high-strength solvent-based portfolios.
- Silane-modified polymer substitutes:Hybrid sealants are encroaching on automotive upholstery trim bonding where flexibility requirements overlap.
Strategic Opportunities
- Ethiopian bonded leather expansion:Mid-tier sneaker construction is creating first-mover advantage for adhesive suppliers with local technical service presence.
- Bio-based polyol feedstocks:Castor oil and lignin-derived intermediates align with EU Green Deal procurement criteria before mandates crystallize.
- Modular adhesive kits:Surface prep agents bundled with applicator tools are opening small-batch furniture workshops previously served by bulk industrial distributors.
Industry Challenges
- Formulation chemist scarcity:Expertise in reactive hot melt rheology and waterborne polyurethane stability is concentrating among a narrow specialist pool.
- BIS certification timelines:India's mandatory adhesive product testing creates entry friction for imported formulations targeting domestic leather goods supply chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Leather Glue Market |
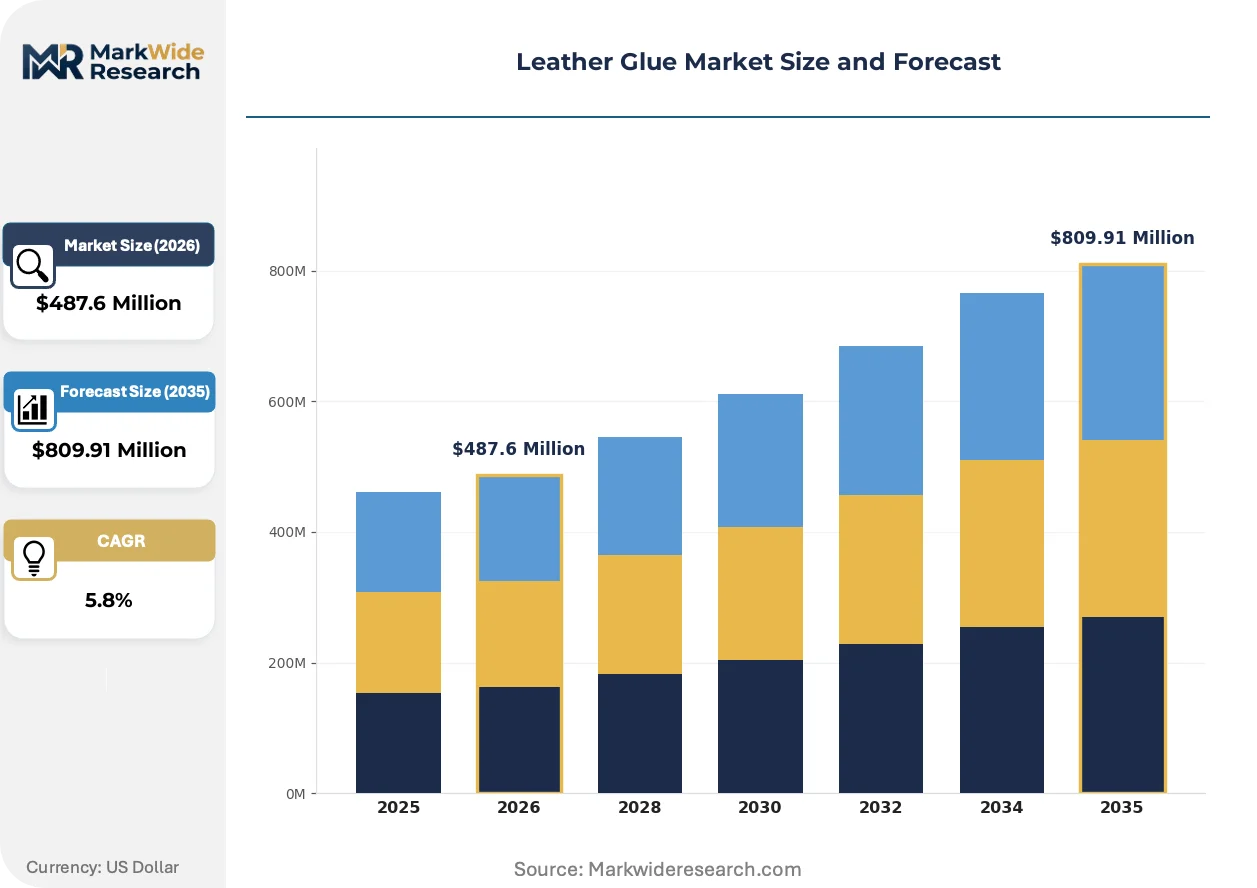
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $809.91 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water-Based, Solvent-Based, Hot Melt, Contact Adhesive End User: Shoe Manufacturers, Furniture Makers, Automotive, Accessories Application: Upholstery, Footwear, Leather Goods, Industrial Bonding Technology: Thermal, Pressure-Sensitive, Two-Part Adhesives, Reactive |
| Companies Covered | MARIO INDUSTRIES PRIVATE LIMITED, Hunan Magpow Adhesive Group, Bhiwadi Polymers Ltd., Fasto, HIGHNIC Group, Hydbond INC, Atlas Adhesives, KELVIN ADHESIVES, Bostik, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Leather Glue Market Evolving Landscape
Reformulation pressure from chemical hazard reclassifications is compressing development cycles while automation in footwear assembly redefines performance specifications for bond strength and open time.
Reactive hot melt polyurethane adhesives are rewriting the economics of high-volume footwear production. These systems combine instant green strength with moisture-cured durability, allowing Vietnamese and Ethiopian sneaker factories to eliminate clamping stations. Mid-tier brands are adopting these platforms fastest where line speed directly determines unit economics.
REACH SVHC candidate list expansion is forcing systematic portfolio reviews across European formulators. ECHA's evolving hazard classifications for isocyanates and aromatic solvents are triggering pre-emptive phase-outs before outright bans materialize. Luxury leather goods manufacturers are responding by qualifying waterborne alternatives that sacrifice some open-time flexibility for compliance security.
Small-batch procurement patterns are fragmenting traditional distribution channels. Independent cobblers and furniture workshops are bypassing industrial distributors through direct-to-craftsperson adhesive kits bundled with surface preparation agents and precision applicators. This behavioral shift is most visible in India's unorganized leather goods sector where BIS-certified domestic suppliers are building brand recognition through technical content and localized service.
Leather Glue Market Segmentation
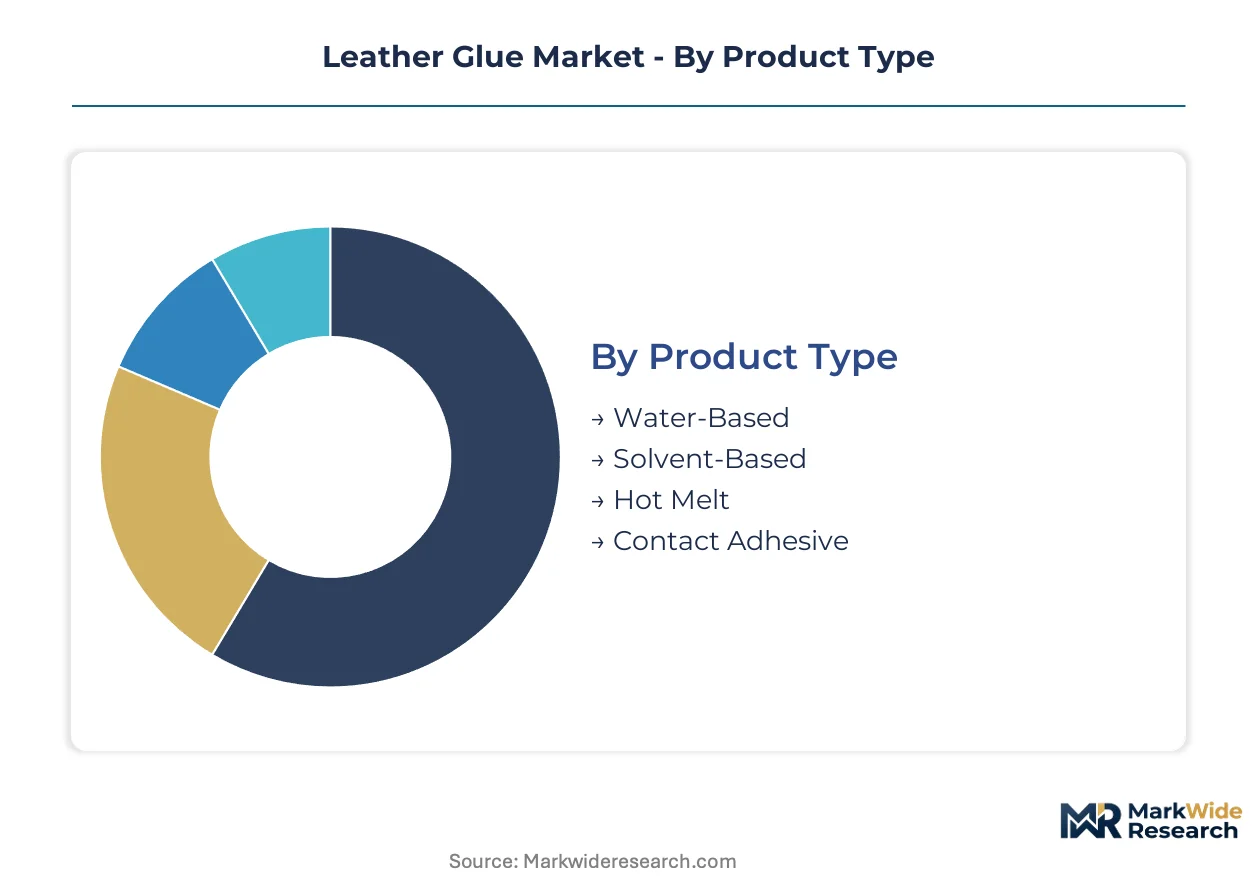
Leather glue segmentation reflects divergent technical requirements across regulated European workshops and high-volume Asian footwear factories. Formulation chemistry, curing mechanism, and end-use durability specifications create distinct procurement patterns that suppliers must address through specialized product lines.
Product Type:
Standardization dominates water-based and hot melt platforms, while solvent-based formulations retain customization for luxury applications requiring extended open times.
- Water-Based:Acrylic and polyurethane dispersions achieve peel strengths of 3.5–6.0 N/mm with zero aromatic solvent content. REACH VOC thresholds in Germany and France are accelerating qualification programs at tanneries supplying premium automotive seating.
- Solvent-Based:Neoprene contact cements deliver 6.5–8.0 N/mm ultimate bond strength through aromatic solvent carriers. Italian luxury leather goods manufacturers maintain demand despite ECHA SVHC pressure due to unmatched flexibility in complex assembly sequences.
- Hot Melt:Reactive polyurethane systems cure through atmospheric moisture to form thermoset bonds. Vietnamese sneaker factories are eliminating clamping stations through instant green strength.
- Contact Adhesive:Natural and synthetic rubber formulations in solvent or water carriers provide tack-and-bond workflows. Ethiopian bonded leather expansion is pulling technical service investment toward Addis Ababa industrial zones.
Most installed capacity flows through water-based platforms. Expansion is steepest in hot melt systems.
End User:
Volume concentration sits with automated footwear assembly, while margin capture favors specialized automotive trim operations.
- Shoe Manufacturers:High-speed bonding lines in Vietnam and Ethiopia demand adhesives with sub-30-second set times and 72-hour full cure windows. PLI scheme investments in Tamil Nadu are pulling domestic adhesive capacity expansion.
- Furniture Makers:Small-batch upholstery workshops require extended open times for complex leather-to-foam positioning. Modular adhesive kits with surface prep agents are penetrating India's unorganized sector through direct-to-craftsperson distribution.
- Automotive:Seating and interior trim applications specify fogging-resistant formulations meeting OEM volatile emission protocols. Atlas Adhesives anchors this segment through captive bonding system development.
- Accessories:Handbags, wallets, and small leather goods prioritize aesthetic bond lines and hand-tool compatibility. Artisan workshops in Florence and Chennai drive specification diversity.
Procurement scale peaks with shoe manufacturers. Technical complexity concentrates in automotive applications.
Application:
Durability requirements stratify across consumer-facing goods versus hidden structural bonds in industrial settings.
- Upholstery:Furniture and automotive seating applications demand fatigue-resistant bonds surviving 100,000+ compression cycles. Water-based polyurethane dispersions are displacing solvent systems in EU-regulated environments.
- Footwear:Outsole attachment, upper construction, and insole bonding each require distinct rheology profiles. Hot melt adoption is climbing fastest where line speed determines unit economics.
- Leather Goods:Luxury handbags and accessories prioritize invisible bond lines and hand-workability. Solvent-based neoprene retains share despite regulatory pressure.
- Industrial:Conveyor belts, gaskets, and protective equipment specify maximum chemical and abrasion resistance. Two-part reactive systems dominate this specification tier.
Volume leadership sits with footwear. Upholstery commands premium formulation investment.
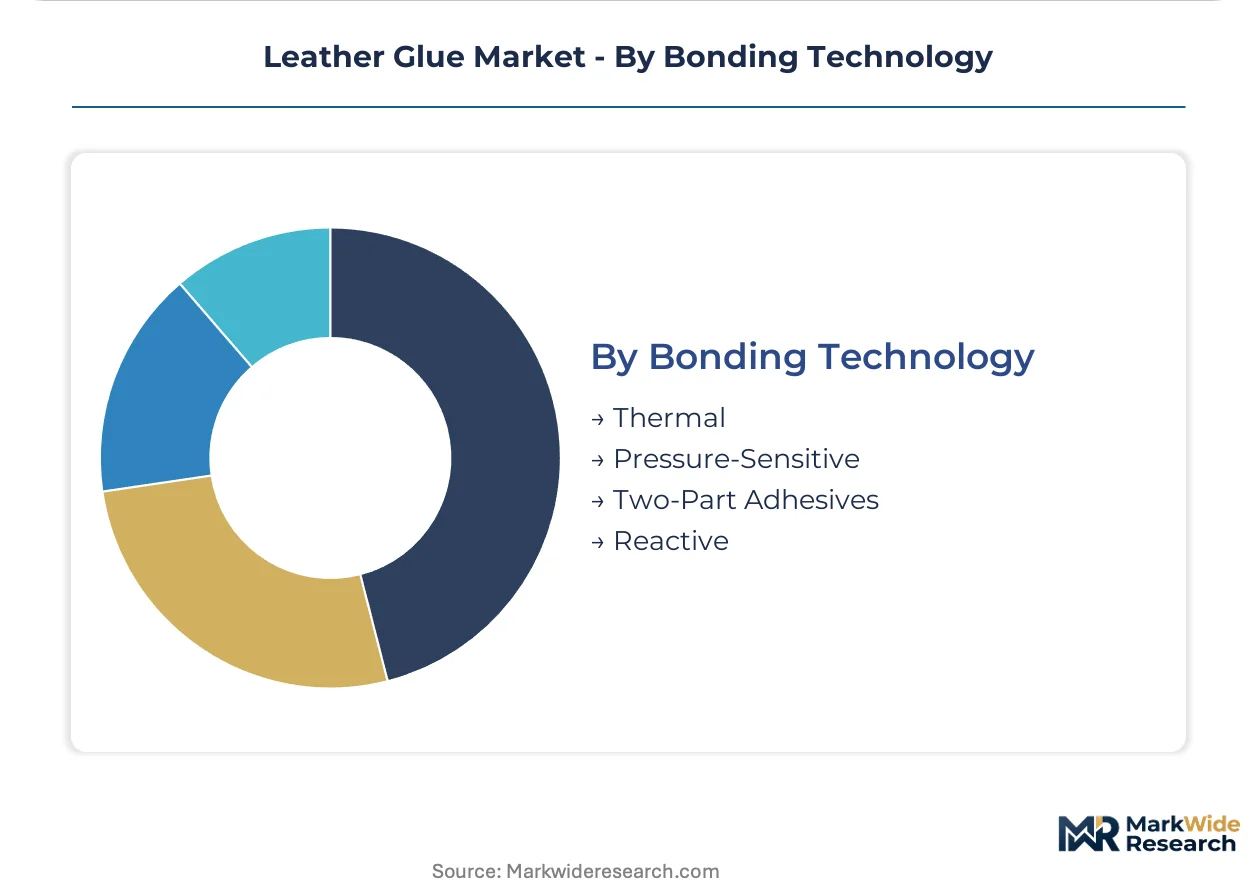
Bonding Technology:
Equipment integration requirements separate thermal and reactive platforms from manual pressure-sensitive applications.
- Thermal:Hot melt application requires heated tanks, hoses, and precision dispensing heads. Ethiopian and Vietnamese factory automation is standardizing around 120–160°C application temperatures.
- Pressure-Sensitive:Tackified formulations bond on contact without curing reactions. Accessory manufacturers favor these systems for repositionable assembly.
- Two-Part Adhesives:Epoxy and polyurethane systems mix resin and hardener at point of application. Industrial leather goods specify these for maximum chemical resistance.
- Reactive:Moisture-cure polyurethane and cyanoacrylate systems polymerize post-application. Footwear factories are adopting these for combined speed and durability.
Capital investment concentrates in thermal platforms. Reactive technology is gaining share fastest in high-volume footwear.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Leather adhesive manufacturing traces its industrial lineage to European tannery districts where solvent-based neoprene formulations first served luxury goods workshops in post-war Italy. Contemporary demand geography reflects this heritage while shifting toward Asian footwear production centers.
Italy
Florentine leather goods artisans sustain demand for extended open-time solvent formulations despite REACH SVHC pressure. ECHA hazard reclassifications are accelerating waterborne qualification programs among tanneries supplying premium automotive seating. The Arzignano tanning cluster in Veneto anchors reformulation R&D for luxury brands.
Germany
Automotive seating manufacturers specify fogging-resistant polyurethane dispersions meeting OEM volatile emission protocols. REACH VOC thresholds in Baden-Württemberg and Bavaria are eliminating aromatic solvent carriers from bonded leather construction. Stuttgart-area technical centers pilot reactive hot melt systems for next-generation upholstery.
Vietnam
Automated sneaker assembly lines in Ho Chi Minh City and Dong Nai Province demand sub-30-second set times from moisture-cure polyurethane platforms. Factory automation investments are standardizing around 120–160°C hot melt application temperatures. Technical service presence concentrates in Binh Duong industrial zones.
India
Tamil Nadu and Uttar Pradesh capacity expansion under the PLI scheme for leather and footwear is pulling adhesive demand from domestic and import sources. BIS certification creates entry friction for imported formulations targeting domestic supply chains. Kanpur and Ambur tanning clusters drive specification diversity.
Ethiopia
Addis Ababa industrial zones host expanding bonded leather construction for mid-tier sneaker exports. Local technical service presence determines supplier selection as production scales. The Eastern Industrial Park anchors foreign direct investment in footwear assembly.
Leather Glue Market Competitive Landscape
Premium-margin players sit above commodity-margin players across formulation complexity and regulatory compliance capability. The vendor base stratifies into three tiers: multinational chemical conglomerates with captive resin production, regional specialists dominating waterborne platforms, and local distributors serving unorganized craft sectors. Consolidation pressure concentrates among mid-scale formulators lacking backward integration into synthetic resin intermediates. Dominant competitive moves include geographic expansion into Ethiopian and Vietnamese production zones and portfolio diversification toward modular adhesive kits.
Within the regional specialist tier, Hunan Magpow Adhesive Group and Bhiwadi Polymers Ltd. exemplify divergent integration strategies. Hunan Magpow occupies a position among Chinese water-based formulation leaders serving domestic footwear export channels. Bhiwadi Polymers anchors its competitive posture through captive manufacturing of synthetic resin intermediates in Rajasthan. Atlas Adhesives represents the application-specialist archetype, with its bonding systems development targeting automotive upholstery trim specifications.
| Leading Market Players |
|---|
| MARIO INDUSTRIES PRIVATE LIMITED |
| Hunan Magpow Adhesive Group |
| Bhiwadi Polymers Ltd. |
| Fasto |
| HIGHNIC Group |
| Hydbond INC |
| Atlas Adhesives |
| KELVIN ADHESIVES |
| Bostik |
| Others |
Value Network & Pricing Analysis
Captive manufacturing of synthetic resin intermediates in Rajasthan anchors Bhiwadi Polymers' supply position while insulating its pricing power from petrochemical polyol volatility that compresses margin predictability for non-integrated competitors. This backward integration into resin production creates cost advantages that translate into competitive positioning across India's PLI-driven leather goods expansion.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates REACH-compliant waterborne formulations from solvent-based neoprene cements and commodity hot melts. Certification grade and volume scale drive price differentiation, with automotive OEM-grade polyurethane dispersions commanding premiums over furniture workshop grades. Cost compression in standard-tier waterborne products is intensifying because of crude-linked input volatility. Small-batch furniture workshops exhibit highest price sensitivity, while luxury leather goods manufacturers prioritize open-time performance over unit cost.
Supply Chain Analysis
BIS certification timelines for imported formulations create qualification gating that favors domestic Indian suppliers over European and Chinese competitors. Manufacturing concentrates in India, China, and Germany, with synthetic resin intermediates, petrochemical polyols, and isocyanate hardeners forming critical input dependencies. Single-source vulnerability around aromatic solvent supplies from specialized European refiners poses structural risk. Distribution runs through industrial chemical distributors serving tannery clusters, supplemented by direct-to-craftsperson channels for modular adhesive kits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The leather glue market functions as a geographic-arbitrage play where Ethiopian and Vietnamese production zones offer labor cost advantages against European regulatory compliance burdens, with REACH VOC thresholds adding 15-20% formulation cost premiums in Germany and Italy.
For Market Incumbents: Deepen technical service presence in Addis Ababa and Ho Chi Minh City industrial zones to capture bonded leather expansion for mid-tier sneaker exports. Invest in bio-based polyol R&D before ECHA SVHC hardens into outright isocyanate bans. Defensive consolidation through captive resin capacity protects margin structures against petrochemical volatility. For New Entrants and Emerging Players: Independent cobblers and small-batch furniture workshops in India's unorganized sector represent an underserved buyer archetype bypassing industrial distributors. Ethiopia's Eastern Industrial Park offers lowest competitive intensity for adhesive suppliers with local formulation capability. Direct-to-craftsperson distribution of modular adhesive kits provides viable go-to-market entry. For Investors and Strategic Acquirers: Roll-up economics work for regional waterborne specialists because BIS certification creates durable moats against import competition in India's domestic supply chain. Mid-scale Indian formulators with backward integration into synthetic resins represent priority acquisition targets. Watch ECHA's SVHC candidate list expansion velocity as inflection indicator for accelerated solvent-based phase-outs.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Intermediates | Captive polyol production insulates Bhiwadi Polymers from crude-linked cost volatility in Rajasthan. |
| REACH-Compliant Waterborne Reformulation | Italian tanneries in Arzignano cluster accelerate qualification programs ahead of ECHA SVHC bans. |
| Technical Service Expansion in Ethiopia | Local adhesive labs in Addis Ababa industrial zones capture bonded leather sneaker construction growth. |
| Modular Adhesive Kit Distribution | Direct-to-craftsperson channels penetrate India's unorganized furniture and cobbler sectors. |
| Bio-Based Polyol Feedstock Development | Castor oil-derived intermediates align with EU Green Deal procurement criteria for automotive seating. |
Research Methodology
Direct dialogue with adhesive formulation chemists, procurement leads at Vietnamese footwear OEMs, tannery technical directors in Tamil Nadu, and automotive seating engineers in Baden-Württemberg grounded qualitative findings. Secondary validation drew from ECHA SVHC candidate list publications, BIS certification registries, Indian PLI scheme disbursement records, and customs trade data for synthetic resin intermediates. Bottom-up segment sizing triangulated against top-down industry value-chain estimates.
Segment-level outputs across formulation chemistry, curing mechanism, end-use application, and bonding technology dimensions were generated through the projection horizon. CAGRs were derived from elasticity-adjusted demand modeling incorporating footwear production forecasts, automotive seating content per vehicle trends, and regulatory phase-out timelines. Inputs included REACH VOC threshold implementation schedules, PLI scheme capacity commissioning data, and hot melt equipment installation rates in Vietnamese factory automation.
Inputs from ECHA regulatory filings and Indian BIS certification databases were available through the study window; gaps in Ethiopian industrial park investment timelines introduce uncertainty bands around East African demand trajectories. Forecasts reflect assumptions on regulatory enforcement consistency and petrochemical feedstock price stability. A model refresh is warranted upon material change in ECHA's isocyanate hazard classification trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
North America Glue-Laminated Timber Market
Adhesives & Sealants
South America Waterborne Adhesives Market
Adhesives & Sealants
North America Adhesives and Sealants Market
Adhesives & Sealants
Butyl Adhesive Market
Adhesives & Sealants
Global Isobutyl Acrylate Market
Adhesives & Sealants
Global Adhesion Barrier Market
Adhesives & Sealants
Global Ethyl Methacrylate (97-63-2) Market
Adhesives & Sealants
Middle East & Africa Automotive Adhesives & Sealants Market
Adhesives & Sealants
Epoxy Curing Agents Market
Adhesives & Sealants
Global Spray Adhesive Market
Adhesives & Sealants
India Tile Adhesive Market
Adhesives & Sealants
Die Attach Materials Market
Adhesives & Sealants
Restorative Materials and Bonding Agents Market
Adhesives & Sealants
Asia-Pacific Adhesives Market
Adhesives & Sealants
Industrial Wood Adhesives Market
Adhesives & Sealants
Marine Sealants Market