
 Heterogeneous Catalyst Market | 2026-2036
Heterogeneous Catalyst Market Size, Share, and Industry Trends Forecast 2026-2036
Heterogeneous Catalyst Market Analytics
The performance gap between premium zeolite-based systems and commodity alumina carriers is expanding as refiners face diverging sulfur specifications. BASF SE leverages its integrated catalyst-precursor supply chain to sustain margin capture at the high end. Clariant International AG specializes in custom emission-control formulations that dominate European automotive catalyst niches.
A heterogeneous catalyst consists of a solid-phase active material dispersed on a porous support structure, typically operating with surface areas exceeding 100 square meters per gram to maximize reactant contact efficiency. These systems enable selective acceleration of chemical reactions without entering the product stream, serving as the backbone of petroleum refining, bulk chemical synthesis, and pollution abatement processes. Metal catalysts anchored on ceramic supports command the largest revenue share due to entrenched refinery demand, while organic catalysts gain traction in pharmaceutical asymmetric synthesis where enantioselectivity requirements tighten. Environmental applications represent the fastest-expanding application segment as stationary-source NOx regulations proliferate across industrial zones.
The US EPA and OSHA jointly shape catalyst specifications through refinery emission mandates and workplace exposure limits that force continuous formulation upgrades. REACH in Europe imposes substance registration burdens that favor established suppliers with dedicated compliance infrastructure over new entrants. Stakeholders must track evolving hydrogenation technology standards as renewable feedstock processing displaces conventional crude pathways.
Market Dynamics
Refinery operators face mounting pressure to process heavier, higher-sulfur crude slates while China's MEE tightens emission ceilings on catalytic cracking units, forcing simultaneous investment in hydroprocessing capacity and emission-control retrofits.
Growth Catalysts
- Dual carbon targets under China's MEE:Provincial refinery clusters in Shandong and Guangdong accelerate catalyst replacement cycles to meet carbon intensity benchmarks for FCC units.
- India's petrochemical corridor expansion:Gujarat's Dahej and Hazira industrial zones drive demand for ZSM-5 zeolite catalysts in propylene maximization units.
- Biofuel-compatible hydroprocessing:Co-processing of vegetable oils and waste fats with conventional feedstocks requires sulfur-tolerant, metal-resistant catalyst formulations.
Market Restraints
- Platinum group metal price volatility:Rhodium and palladium spot markets expose automotive catalyst manufacturers to margin compression during supply disruptions from South African concentrator outages.
- REACH substance registration burdens:ECHA's data requirements for novel catalytic precursors create compliance cost barriers that favor incumbent European suppliers with dedicated regulatory infrastructure.
- Alumina support supply concentration:High-purity gamma-alumina production clusters in the US Gulf Coast and Rotterdam, creating geographic single-source risk for catalyst formulators.
Strategic Opportunities
- Carbon capture integration in ammonia synthesis:Iron-based Haber-Bosch catalyst retrofits for blue hydrogen production open retrofit revenue streams at US Gulf Coast and Middle Eastern fertilizer complexes.
- India's PLI scheme for specialty chemicals:Domestic catalyst manufacturing incentives attract technology licensing agreements for refinery process technologies previously imported from European licensors.
- Electrified steam methane reforming:Plasma-assisted catalytic partial oxidation converges with renewable electricity sourcing to enable distributed hydrogen production at industrial clusters.
Industry Challenges
- Computational catalyst design talent scarcity:Density functional theory expertise and high-throughput screening capabilities concentrate at national laboratories and top-tier research universities, constraining private-sector R&D velocity.
- Extended pilot-plant validation timelines:Commercial-scale proof requirements for hydrocracking catalysts demand 18-24 month refinery trial periods before full supply contracts execute.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heterogeneous Catalyst Market |
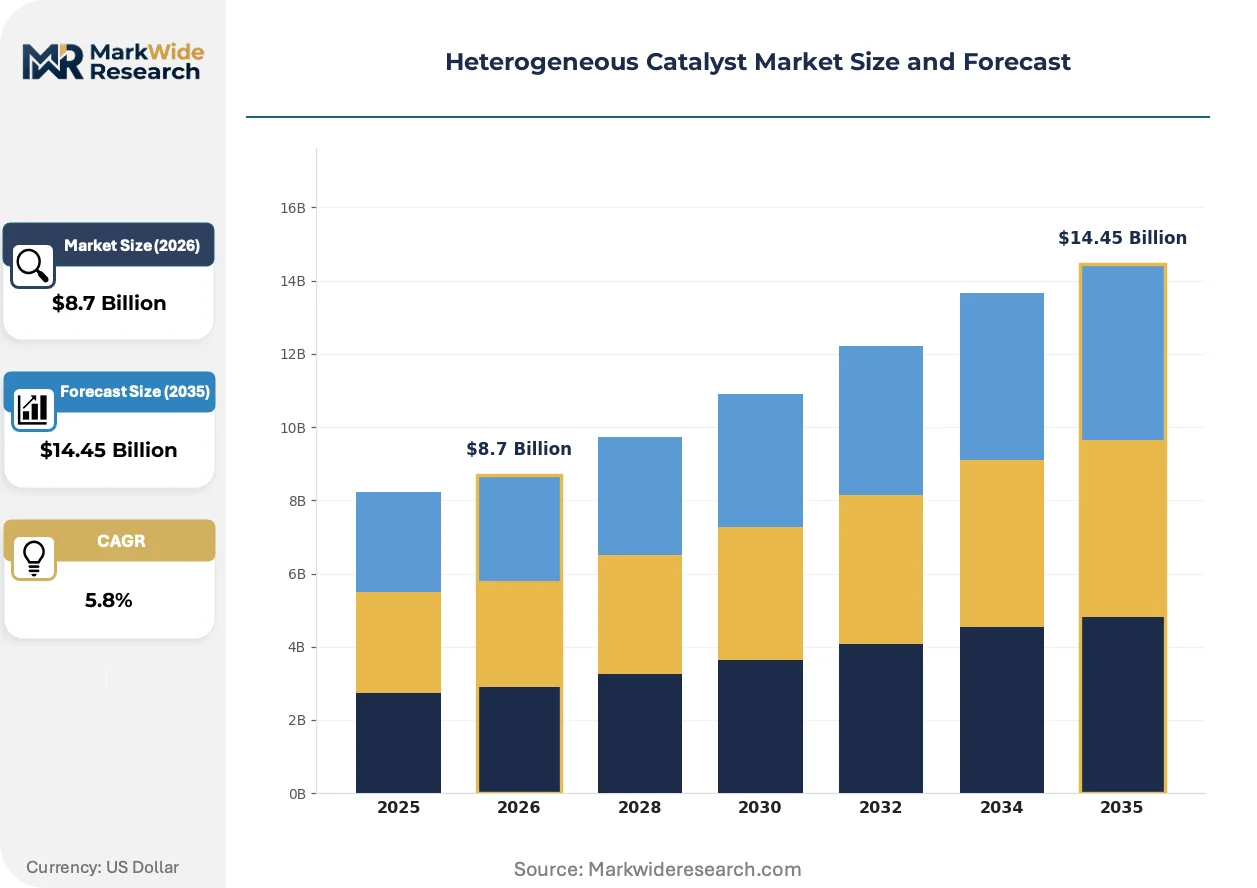
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metal Catalysts, Organic Catalysts, Organometallic Catalysts, Support Materials Application: Petrochemicals, Fine Chemicals, Environmental Applications, Energy Production End User: Chemical Industry, Oil & Gas, Pharmaceuticals, Biotechnology Technology: Supported Catalysis, Catalytic Reforming, Hydrogenation, Oxidation |
| Companies Covered | Albemarle Corporation, Clariant International AG, BASF SE, LyondellBasell Industries Holdings B.V., Umicore NV, Johnson Matthey Plc, Haldor Topsoe A/S, W.R. Grace & Co., Evonik Industries AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heterogeneous Catalyst Market Evolving Landscape
Digital design tools and electrochemical process integration are compressing traditional catalyst development cycles while regulatory mandates force simultaneous performance and sustainability upgrades across installed refinery bases.
Single-atom catalysis is integrating discrete metal centers onto nitrogen-doped carbon supports for selective hydrogenation of functionalized pharmaceuticals. Contract manufacturers in Basel and Boston metro areas pilot these systems for high-value active pharmaceutical ingredient synthesis. The technology is integrating enantioselective control previously requiring homogeneous precious-metal complexes into recyclable heterogeneous formats.
REACH authorization requirements for cobalt dichloride and nickel compounds force reformulation of oxidation catalysts used in terephthalic acid production. European PTA producers accelerate qualification of iron-manganese spinel alternatives at Antwerp and Rotterdam installations. Automotive exhaust catalyst suppliers face parallel substance restriction pressures under RoHS amendments targeting hexavalent chromium in coating layers.
Refinery procurement departments consolidate catalyst supply contracts into multi-year, full-refinery agreements bundling hydroprocessing, FCC, and sulfur recovery technologies. Integrated suppliers capture switching costs through embedded technical service teams co-located at buyer sites. This pattern concentrates most visibly at US independent refiners seeking to offset internal technical staffing reductions through vendor-managed inventory programs.
Heterogeneous Catalyst Market Segmentation
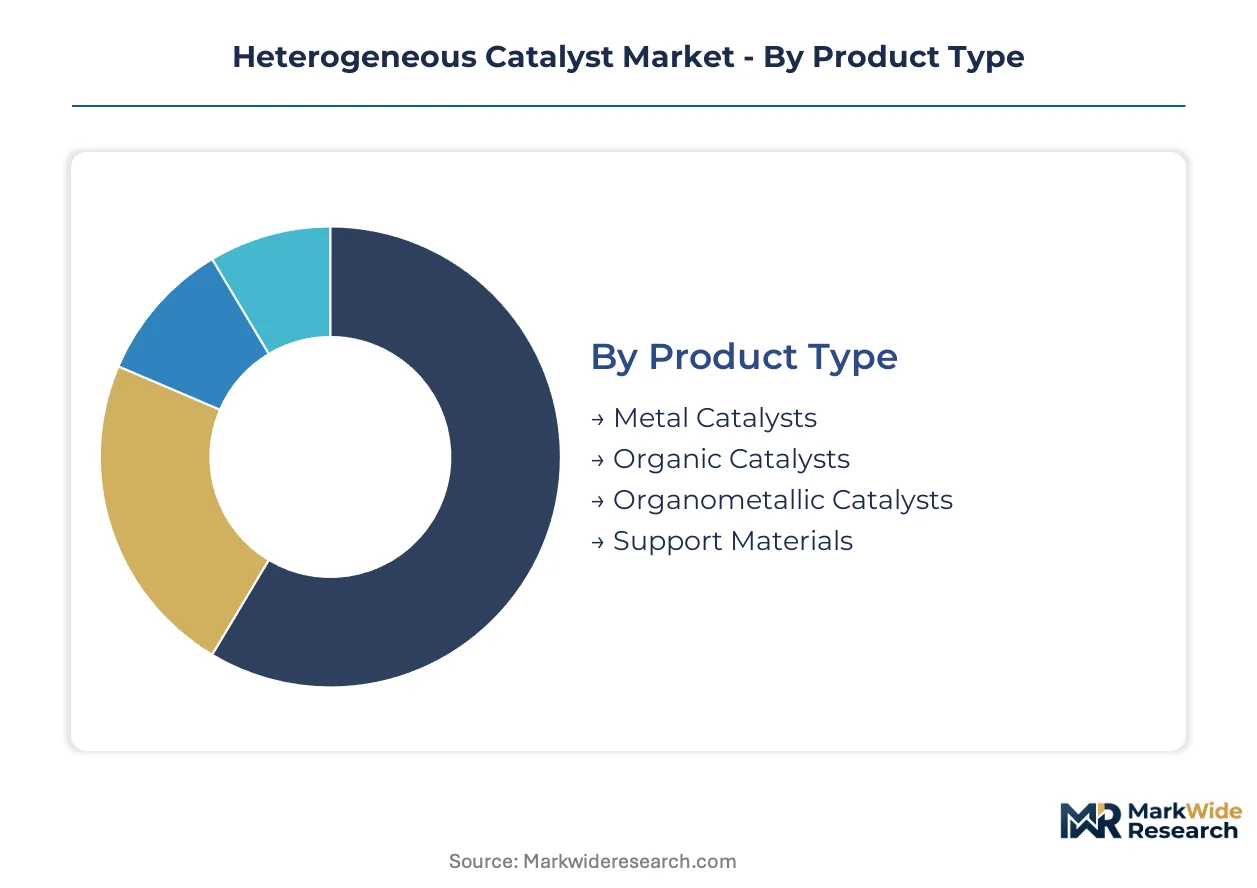
Heterogeneous catalyst procurement patterns diverge sharply between integrated refinery operators seeking full-process bundles and specialty chemical manufacturers requiring application-specific formulations. Segmentation reveals how catalyst architecture, deployment context, and technical service intensity reshape supplier-buyer relationships across distinct value chain positions.
Product Type:
Integration depth varies substantially—metal catalysts embed directly into continuous process units while support materials function as upstream inputs requiring further formulation.
- Metal Catalysts:Platinum-group and base-metal formulations anchored on ceramic supports dominate hydroprocessing and automotive emission control. Refinery operators in China's Shandong province accelerate replacement cycles to meet MEE carbon intensity benchmarks for FCC units.
- Organic Catalysts:Enzyme-derived and synthetic organic frameworks enable asymmetric synthesis with high enantioselectivity. Pharmaceutical manufacturers in the Basel metro area pilot these systems for active pharmaceutical ingredient production where chiral purity requirements tighten.
- Organometallic Catalysts:Transition metal complexes with organic ligands bridge homogeneous and heterogeneous catalysis for polymerization processes.
- Support Materials:High-purity gamma-alumina and zeolite substrates supply catalyst formulators; production concentrates on the US Gulf Coast and Rotterdam.
Metal catalysts lead volumes today; organic catalysts are gaining share fastest.
Application:
Cost tier separation distinguishes commodity-scale petrochemical deployments from precision environmental systems commanding technical service premiums.
- Petrochemicals:Steam cracking and polymerization catalysts process ethylene, propylene, and aromatics at massive throughput. India's Gujarat corridor around Dahej and Hazira drives ZSM-5 zeolite demand for propylene maximization units under the PLI scheme for specialty chemicals.
- Fine Chemicals:Low-volume, high-specification catalysts enable complex multi-step syntheses for agrochemical and pharmaceutical intermediates. Contract manufacturers in the Boston metro area qualify single-atom nitrogen-doped carbon systems for selective hydrogenation.
- Environmental Applications:Stationary-source NOx abatement and automotive exhaust treatment represent the steepest expansion trajectory as EPA and MEE emission ceilings tighten.
- Energy Production:Fuel cell and hydrogen generation catalysts support emerging clean energy infrastructure.
Petrochemical applications anchor revenue today; environmental applications are climbing the fastest.
End User:
Customer type determines procurement sophistication—oil and gas majors negotiate multi-year technical service bundles while biotechnology firms prioritize rapid catalyst screening capabilities.
- Chemical Industry:Commodity and specialty chemical producers operate the largest installed catalyst bases requiring continuous formulation upgrades. European PTA producers at Antwerp and Rotterdam accelerate iron-manganese spinel qualification as REACH restrictions force cobalt and nickel compound phase-outs.
- Oil & Gas:Integrated and independent refiners consolidate supply contracts into full-refinery agreements bundling hydroprocessing, FCC, and sulfur recovery technologies. US independent refiners offset internal technical staffing reductions through vendor-managed inventory programs.
- Pharmaceuticals:Batch-process manufacturers demand rapid catalyst customization for abbreviated development timelines.
- Biotechnology:Fermentation and biocatalysis applications require catalyst compatibility with aqueous biological systems.
Oil and gas leads procurement volumes today; biotechnology is expanding most quickly.
Technology:
Maturity gradients separate established hydrogenation platforms from emerging oxidation technologies still navigating extended pilot-plant validation requirements.
- Supported Catalysis:Active materials dispersed on porous structures with surface areas exceeding 100 square meters per gram maximize reactant contact efficiency. This architecture underpins petroleum refining, bulk chemical synthesis, and pollution abatement processes globally.
- Catalytic Reforming:Platinum-rhenium on alumina platforms upgrade naphtha to high-octane aromatics and hydrogen; refiners face pressure to process heavier, higher-sulfur crude slates.
- Hydrogenation:Selective saturation of unsaturated bonds serves edible oils, petrochemicals, and pharmaceutical intermediates. Biofuel-compatible formulations enabling vegetable oil and waste fat co-processing attract sulfur-tolerant, metal-resistant development.
- Oxidation:Partial oxidation and epoxidation technologies support terephthalic acid and propylene oxide production.
Supported catalysis dominates installed capacity today; oxidation is gaining traction fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Process engineers and catalytic chemists concentrate in industrial clusters where refining and petrochemical infrastructure anchors demand. Regional catalyst procurement patterns reflect local regulatory stringency and feedstock processing requirements.
United States
Independent refiners along the Gulf Coast consolidate catalyst supply contracts into multi-year technical service bundles. EPA refinery emission mandates force continuous formulation upgrades for hydroprocessing units. Vendor-managed inventory programs at Texas and Louisiana installations offset internal technical staffing reductions.
China
Provincial refinery clusters in Shandong and Guangdong accelerate catalyst replacement cycles to meet carbon intensity benchmarks. MEE dual carbon goals tighten emission ceilings on fluid catalytic cracking units. ZSM-5 zeolite demand concentrates in coastal petrochemical zones processing heavier crude slates.
Germany
REACH authorization requirements for cobalt and nickel compounds force reformulation of oxidation catalysts used in terephthalic acid production. ECHA data requirements favor established suppliers with dedicated compliance infrastructure. Antwerp and Rotterdam installations accelerate iron-manganese spinel qualification as alternatives.
India
Gujarat's Dahej and Hazira industrial zones drive demand for propylene maximization catalysts under the PLI scheme for specialty chemicals. BIS standards for refinery emissions tighten procurement specifications for domestic operators. Technology licensing agreements attract European process licensors to establish local catalyst manufacturing.
Saudi Arabia
Fertilizer complexes on the Gulf Coast explore iron-based Haber-Bosch catalyst retrofits for blue hydrogen production. The national industrial regulator enforces emission ceilings that accelerate catalyst replacement in ammonia synthesis units. Integrated refining and petrochemical zones demand bundled supply contracts covering full process trains.
Heterogeneous Catalyst Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across a tiered supplier base. Integrated chemical conglomerates with captive precursor supply chains capture margin at the premium end, while specialized formulators dominate emission-control niches. Strategic archetypes separate full-process bundlers, custom formulation specialists, and regional technology licensees. Competitive moves concentrate on multi-year refinery service contracts and embedded technical staffing at buyer sites.
Within the integrated conglomerate tier, BASF SE and Albemarle Corporation exemplify scale-driven positions anchored on upstream control over catalyst-precursor supply chains. Clariant International AG occupies a specialization-focused position among Swiss-based formulators, representing the custom emission-control archetype that dominates European automotive catalyst segments. Johnson Matthey Plc sits within the technology-licensor tier, reflecting British-based expertise in platinum-group metal systems for refining and environmental applications.
| Leading Market Players |
|---|
| Albemarle Corporation |
| Clariant International AG |
| BASF SE |
| LyondellBasell Industries Holdings B.V. |
| Umicore NV |
| Johnson Matthey Plc |
| Haldor Topsoe A/S |
| W.R. Grace & Co. |
| Evonik Industries AG |
| Others |
Value Network & Pricing Analysis
Rhodium and palladium spot price indices cascade through catalyst manufacturing tiers, compressing margins at automotive emission-control suppliers while amplifying pricing power for integrated producers with captive platinum-group metal hedging positions.
Pricing Analysis
Bundled technical service contracts versus unbundled catalyst-only supply splits the market into divergent pricing architectures. Multi-year refinery agreements embedding on-site technical teams command 15-25% premiums over transactional catalyst replacement orders. Price differentiation rests on certification grade for REACH-compliant formulations and geographic delivery cost from US Gulf Coast or Rotterdam production hubs. Cost compression in standard-grade alumina-supported systems intensifies as Chinese formulators expand export capacity. Independent refiners exhibit highest price sensitivity due to staffing reductions that force reliance on vendor-managed inventory programs.
Supply Chain Analysis
Workforce availability constraints in Basel and Boston metro areas limit single-atom catalyst pilot production scaling. Supply concentrates in Germany, the United States, and China for high-purity gamma-alumina substrates, platinum-group metal refining, and zeolite synthesis respectively. Raw material flows draw from South African PGM concentrators, US Gulf Coast petrochemical feedstocks, and Chinese rare earth processing nodes. Single-source vulnerability from South African concentrator outages exposes automotive catalyst manufacturers to rhodium and palladium supply disruptions. Distribution runs through integrated chemical conglomerates with direct refinery technical service deployments and specialized formulators serving pharmaceutical contract manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The heterogeneous catalyst market represents a late-cycle quality story as refinery operators prioritize premium zeolite-based systems over commodity alumina carriers to meet tightening sulfur specifications.
For Market Incumbents: Deepen backward integration into high-purity alumina precursor production to offset margin compression from platinum-group metal price volatility. Expand embedded technical service teams at Shandong and Guangdong refinery clusters to capture switching costs from China's MEE carbon intensity benchmarks. Prioritize REACH pre-registration of novel catalytic precursors to erect compliance barriers against emerging Asian formulators. For New Entrants and Emerging Players: Digital-channel catalyst screening platforms offer the lowest-friction entry vector for pharmaceutical contract manufacturers seeking rapid enantioselective formulation customization. Target India's petrochemical corridor under PLI scheme incentives for domestic manufacturing partnerships with European technology licensors. Pursue white-space positioning in biofuel-compatible hydroprocessing catalysts where sulfur-tolerant formulations face qualified supplier shortages. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized emission-control formulators holding REACH-compliant cobalt and nickel compound alternatives as regulatory restrictions phase out legacy oxidation catalysts. Five-to-ten year viability favors asset-light designers with density functional theory capabilities and national laboratory partnerships over capital-heavy integrated producers. Watch iron-manganese spinel qualification timelines at Antwerp and Rotterdam as the inflection signal for European PTA catalyst replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Supply | BASF SE's captive alumina production sustains margin capture at premium catalyst tiers. |
| Multi-Year Technical Service Bundling | US Gulf Coast refiners offset staffing cuts through vendor-managed inventory programs. |
| REACH-Compliant Formulation Development | Iron-manganese spinel alternatives capture European PTA producers facing cobalt restrictions. |
| Single-Atom Catalysis Scale-Up | Basel and Boston contract manufacturers pilot nitrogen-doped carbon systems for API synthesis. |
| India PLI Manufacturing Localization | Dahej and Hazira zones attract European licensors for ZSM-5 zeolite domestic production. |
Research Methodology
Multiple input streams — primary interviews with refinery procurement directors, catalyst R&D leads, and environmental compliance officers; secondary validation through ECHA substance registration databases, SEC 10-K filings of integrated chemical producers, and customs trade data for platinum-group metal flows — were reconciled through bottom-up and top-down triangulation.
Historical capacity expansion patterns were cross-referenced against expert panel inputs on hydroprocessing unit retrofit timelines. Segmentation dimensions modeled include catalyst architecture type, application end-use, procurement contract structure, and regional regulatory cluster throughout the forecast period. CAGRs were derived from installed base replacement cycles, emission regulation phase-in schedules, and petrochemical capacity expansion announcements.
The model assumes a particular technology adoption path; alternative pathways for electrified steam methane reforming and plasma-assisted catalytic partial oxidation would alter the outlook for hydrogen production catalyst demand. Forecasts reflect assumptions regarding MEE enforcement consistency, REACH authorization timelines, and PGM supply stability from South African concentrators. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Catalysts
Syngas to Ethylene Glycol Catalyst Market
Catalysts
Europe Refining Catalysts Market
Catalysts
Fuel Cell Catalyst Market
Catalysts
Hydrodesulfurization Catalyst Market
Catalysts
Middle-East and Africa Refining Catalysts Market
Catalysts
Solid Acid Catalysts Market
Catalysts
Stationary Catalytic Systems Market
Catalysts
Hydrodeoxygenation [HDO] Catalysts Market
Catalysts
Global VOC Catalysts Market
Catalysts
Global Boron Trifluoride Methanol Complex Market
Catalysts
Europe Homogeneous Precious Metal Catalyst Market
Catalysts
Asia and Middle East Polyolefin Catalyst Market
Catalysts
Inorganic Catalyst Market
Catalysts
Global Chemical Catalyst Market
Catalysts
North America Zeolite Market
Catalysts
Catalyst for Hydrogen Production from Water Electrolysis Market