
 Photocatalyst Market | 2026-2036
Photocatalyst Market Size, Share, and Industry Trends Forecast 2026-2036
Photocatalyst Market Intelligence
High-purity nano-grade titanium dioxide is rotating toward premium pricing as environmental compliance tightens across industrial zones. Mitsubishi Chemical Group Corporation leverages captive precursor supply to dominate pharmaceutical-grade photocatalyst output. KRONOS Worldwide Inc. anchors North American pigment-to-catalyst conversion with vertically integrated sulfate process capacity. TOTO Ltd. differentiates through proprietary hydrophilic surface patents that command specification-driven procurement in commercial construction.
Photocatalysts are semiconductor materials that generate electron-hole pairs upon light absorption, with titanium dioxide's bandgap of approximately 3.2 eV enabling oxidative degradation of organic pollutants under ultraviolet or visible illumination. Their primary commercial purpose spans environmental remediation, self-sustaining surface hygiene, and solar-driven chemical synthesis. Titanium dioxide formulations occupy the mature volume base, while visible light activation technologies capture the fastest expansion as doped tungsten oxide and nitrogen-modified structures displace UV-dependent systems. Water purification applications lead absolute revenue, though antimicrobial treatments in healthcare infrastructure concentrate margin pools due to validation requirements and contract stickiness.
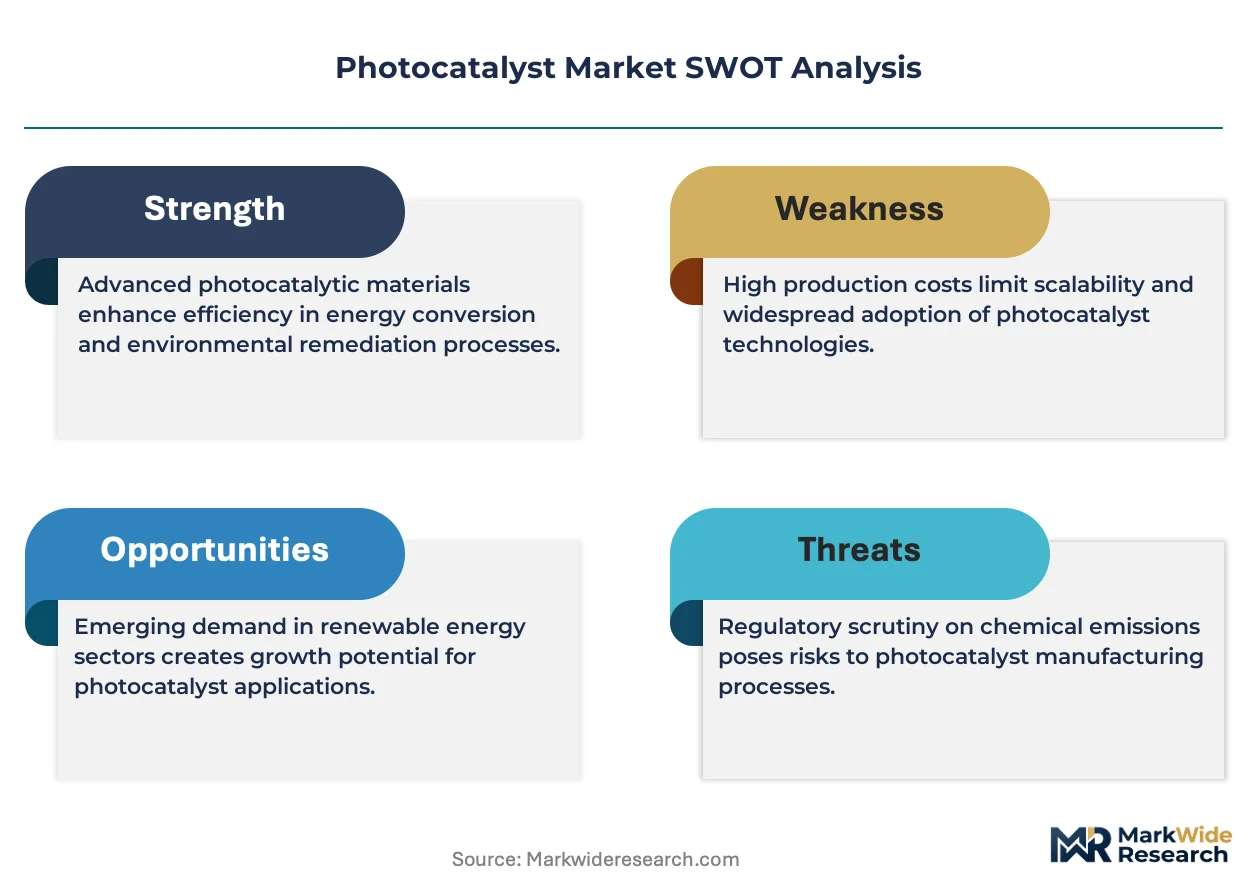
Japan's Ministry of Economy, Trade and Industry (METI) promotes photocatalytic building standards through JIS certification pathways, while the EPA's emerging contaminant framework in the United States elevates advanced oxidation process validation for drinking water utilities. The EU Green Deal's zero-pollution ambition accelerates REACH-compliant surface treatment adoption across member states. Stakeholders must monitor regulatory divergence between photocatalyst classification as active substances versus materials, as this determination reshapes registration burdens and market access timelines.
Market Dynamics
Visible-light activation is supplanting UV-dependent titanium dioxide across water treatment and construction applications, compressing the addressable market for legacy photocatalyst suppliers while elevating doped metal oxide specialists.
Growth Catalysts
- China's dual carbon goals:Stricter effluent standards under MEE mandates accelerate municipal adoption of graphitic carbon nitride variants in wastewater facilities.
- Japan's METI building standards:JIS certification pathways for photocatalytic construction materials drive specification-driven procurement in commercial real estate.
- Visible-light doping techniques:Nitrogen-modified tungsten oxide structures enable indoor antimicrobial coatings without UV infrastructure.
Market Restraints
- Precursor cost volatility:High-purity titanium tetrachloride supply concentrates in sulfate-process corridors, exposing formulators to chloride-route feedstock price swings.
- UV-activation lock-in:Legacy municipal water infrastructure requires capital-intensive retrofitting to accommodate visible-light catalysts.
- REACH registration burdens:ECHA's active substance versus material classification uncertainty extends market access timelines for novel nano-formulations.
Strategic Opportunities
- Healthcare infrastructure antimicrobial layers:Hospital-acquired infection protocols in South Korea and Japan validate premium pricing for certified photocatalytic surface treatments.
- EU Green Deal zero-pollution ambition:REACH-compliant surface treatment mandates create first-mover advantage for compliant coating suppliers.
- Solar-driven chemical synthesis:Convergence of photocatalysis with electrochemical reduction opens merchant hydrogen peroxide production pathways.
Industry Challenges
- Electron-hole recombination engineering:Formulation chemists with semiconductor interface expertise command scarcity premiums, constraining R&D velocity at mid-tier suppliers.
- ISO 27448 self-cleaning certification:Multi-year validation timelines for construction material coatings delay revenue recognition and tie up working capital.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Photocatalyst Market |
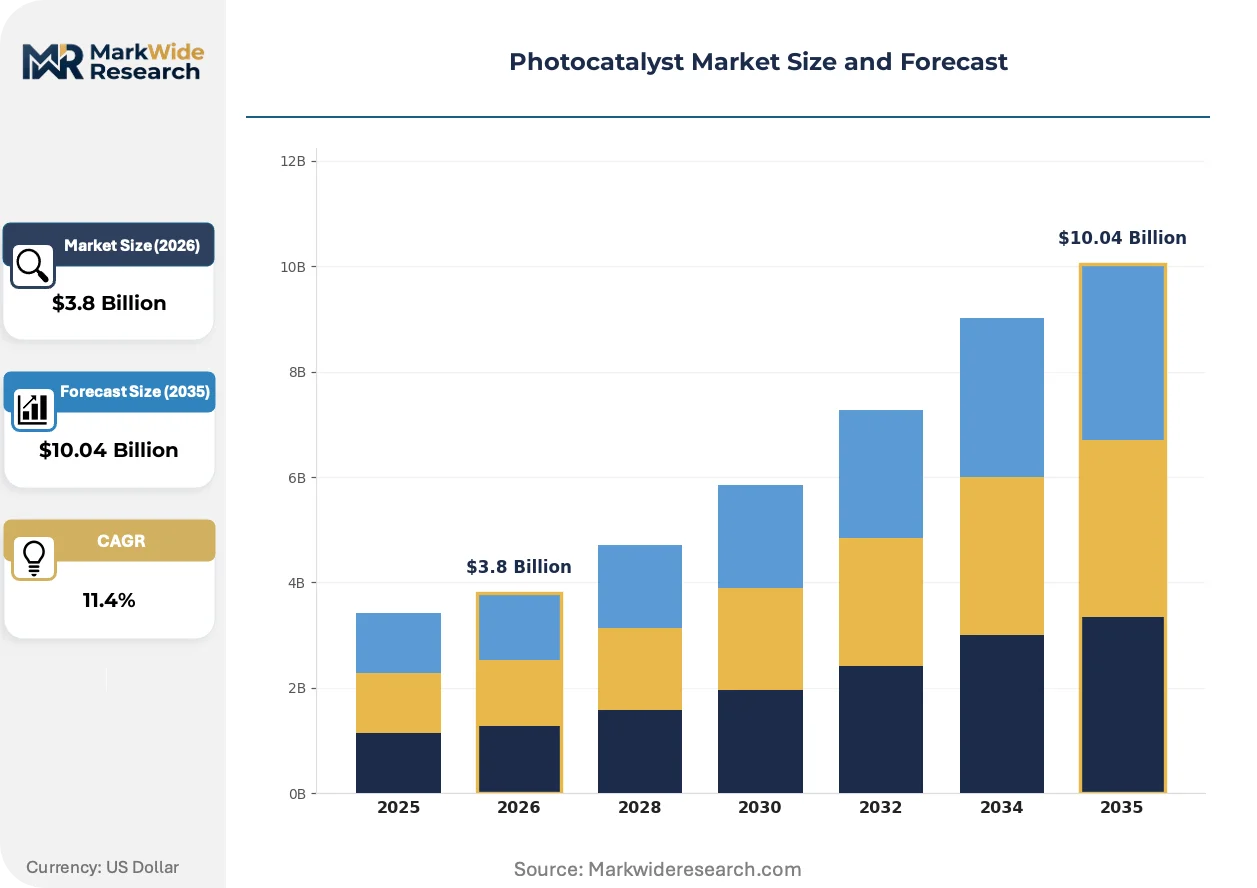
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Titanium Dioxide, Zinc Oxide, Graphitic Carbon Nitride, Bismuth Vanadate, Cadmium Sulfide Application: Water Purification, Air Decontamination, Self-Cleaning Surfaces, Antimicrobial Treatments, Solar Energy Conversion Technology: UV Light Activation, Visible Light Activation, Doping Modification, Heterojunction Construction, Surface Modification End User Industry: Environmental Services, Consumer Electronics, Construction Materials, Agriculture, Chemical Processing |
| Companies Covered | Mitsubishi Chemical Group Corporation, KRONOS Worldwide Inc., TOTO Ltd., Japan Photocatalyst Center Co. Ltd., Tayca Corporation, Showa Denko K.K., Evonik Industries AG, Sakai Chemical Industry Co. Ltd., Ishihara Sangyo Kaisha Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Photocatalyst Market Strategic Shifts & Innovations
Photocatalyst innovation vectors center on bandgap engineering, regulatory compliance automation, and procurement specification tightening that favors validated suppliers over commodity producers.
Nitrogen-doped titanium dioxide is supplanting undoped anatase in indoor air purification systems. Facility managers in Japanese commercial buildings specify these materials for HVAC-integrated modules. The shift is compressing margins for UV-reactor manufacturers while expanding the serviceable market for ambient-light-activated formulations.
EPA's emerging contaminant framework for drinking water utilities elevates advanced oxidation process validation requirements. Water treatment operators must now document photocatalytic degradation efficacy for PFAS and pharmaceutical residues. This regulatory pressure concentrates procurement authority among certified system integrators in California and Texas municipal districts.
Specification-driven buying now dominates commercial construction procurement in East Asian manufacturing clusters. General contractors in Osaka and Seoul require JIS-certified hydrophilic coatings with documented antimicrobial performance. The shift disadvantages uncertified commodity suppliers and extends contract durations for validated material providers.
Photocatalyst Market Segmentation
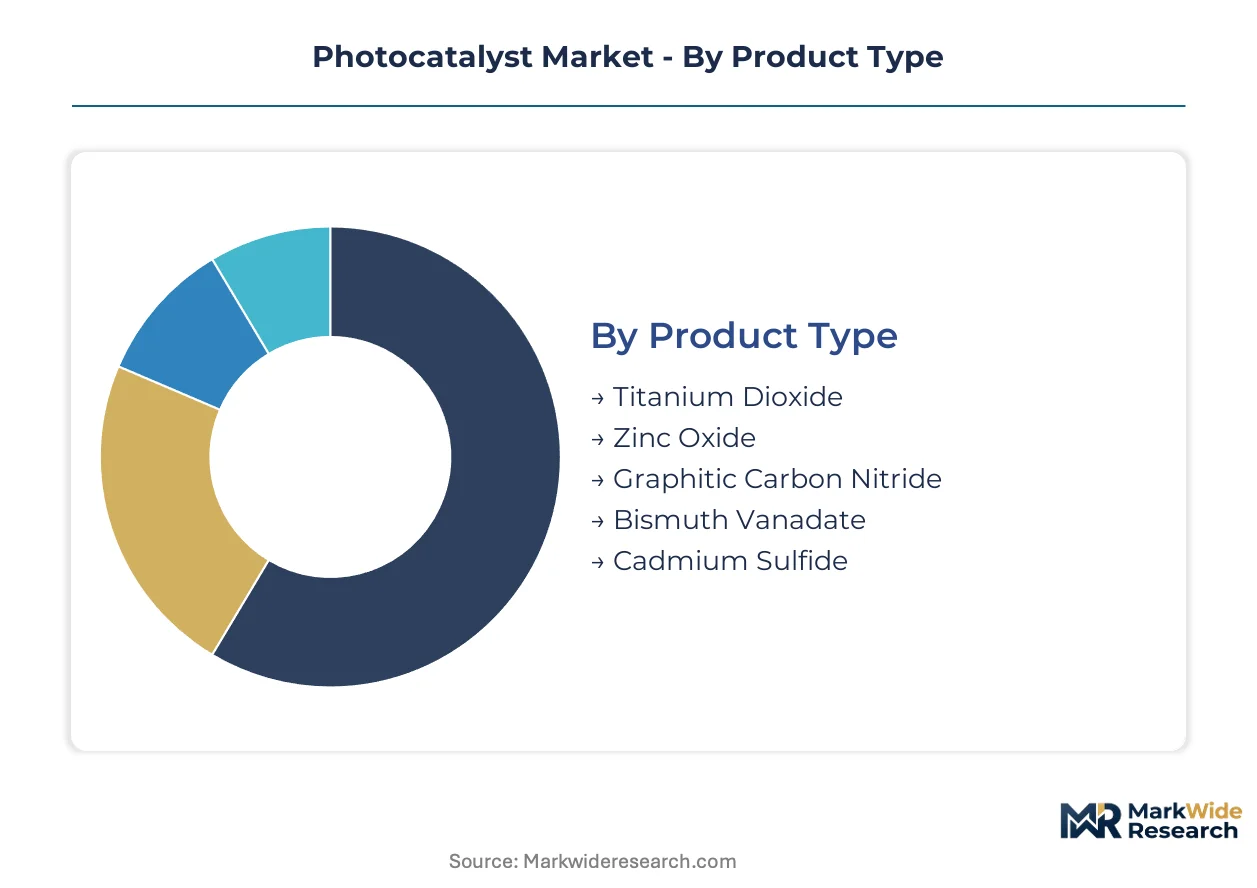
Photocatalyst procurement splits sharply between commodity titanium dioxide formulations and engineered variants commanding specification premiums. Understanding where margin pools concentrate across material chemistry, activation mechanism, and end-use validation requirements shapes supplier positioning and R&D allocation decisions.
Product Type:
Margin pools concentrate in visible-light-activated chemistries where doping expertise creates scarcity rents, while legacy UV-dependent materials face pricing compression from sulfate-process overcapacity.
- Titanium Dioxide:Anatase and rutile crystal structures dominate volume production, with nano-grade high-purity grades rotating toward premium pricing as environmental compliance tightens across industrial zones in China and Japan.
- Graphitic Carbon Nitride:Polymeric semiconductor with tunable bandgap around 2.7 eV enables visible-light-driven water splitting. China's MEE effluent mandates accelerate municipal adoption in wastewater treatment facilities across the Yangtze River basin.
- Zinc Oxide:Wide bandgap alternative with antibacterial properties finds use in consumer electronics coatings.
- Bismuth Vanadate:Narrow bandgap oxide increasingly specified for solar-driven chemical synthesis applications.
- Cadmium Sulfide:Toxicity concerns restrict deployment to sealed industrial photochemical reactors.
Titanium dioxide holds installed capacity. Graphitic carbon nitride is rotating up the share rankings.
Application:
Water purification commands absolute revenue scale, though antimicrobial surface treatments in healthcare infrastructure concentrate margin pools due to JIS and ISO validation requirements.
- Water Purification:Advanced oxidation processes degrade organic pollutants and pharmaceutical residues. EPA's emerging contaminant framework elevates validation requirements for PFAS treatment in California and Texas municipal districts.
- Antimicrobial Treatments:Hospital-acquired infection protocols in South Korea and Japan validate premium pricing for certified photocatalytic coatings on high-touch surfaces in Seoul and Osaka medical facilities.
- Air Decontamination:HVAC-integrated modules in Japanese commercial buildings specify nitrogen-doped formulations for ambient light activation.
- Self-Cleaning Surfaces:Hydrophilic coatings on construction materials require multi-year ISO 27448 certification timelines.
- Solar Energy Conversion:Photocatalytic water splitting and CO2 reduction remain pre-commercial despite laboratory efficiency gains.
Water purification anchors procurement volume. Antimicrobial treatments are climbing the fastest as certification barriers extend contract durations.
Technology:
Activation mechanism determines addressable market scope, with visible-light systems expanding into indoor applications previously closed to UV-dependent infrastructure.
- Visible Light Activation:Nitrogen-modified tungsten oxide and carbon nitride structures displace UV-dependent systems. Indoor antimicrobial coatings in Japanese commercial real estate bypass retrofit infrastructure requirements.
- Doping Modification:Metal and non-metal dopants engineer bandgap positions for specific wavelength absorption. Formulation chemists with semiconductor interface expertise command scarcity premiums constraining R&D velocity at mid-tier suppliers.
- UV Light Activation:Legacy titanium dioxide systems face market compression as municipal infrastructure retrofit costs delay upgrades.
- Heterojunction Construction:Composite interfaces suppress electron-hole recombination in high-performance environmental remediation systems.
- Surface Modification:Hydrophilic and oleophilic functionalization enables self-cleaning properties in construction material specifications.
UV light activation retains installed base. Visible light activation is expanding most quickly across water treatment and construction procurement.
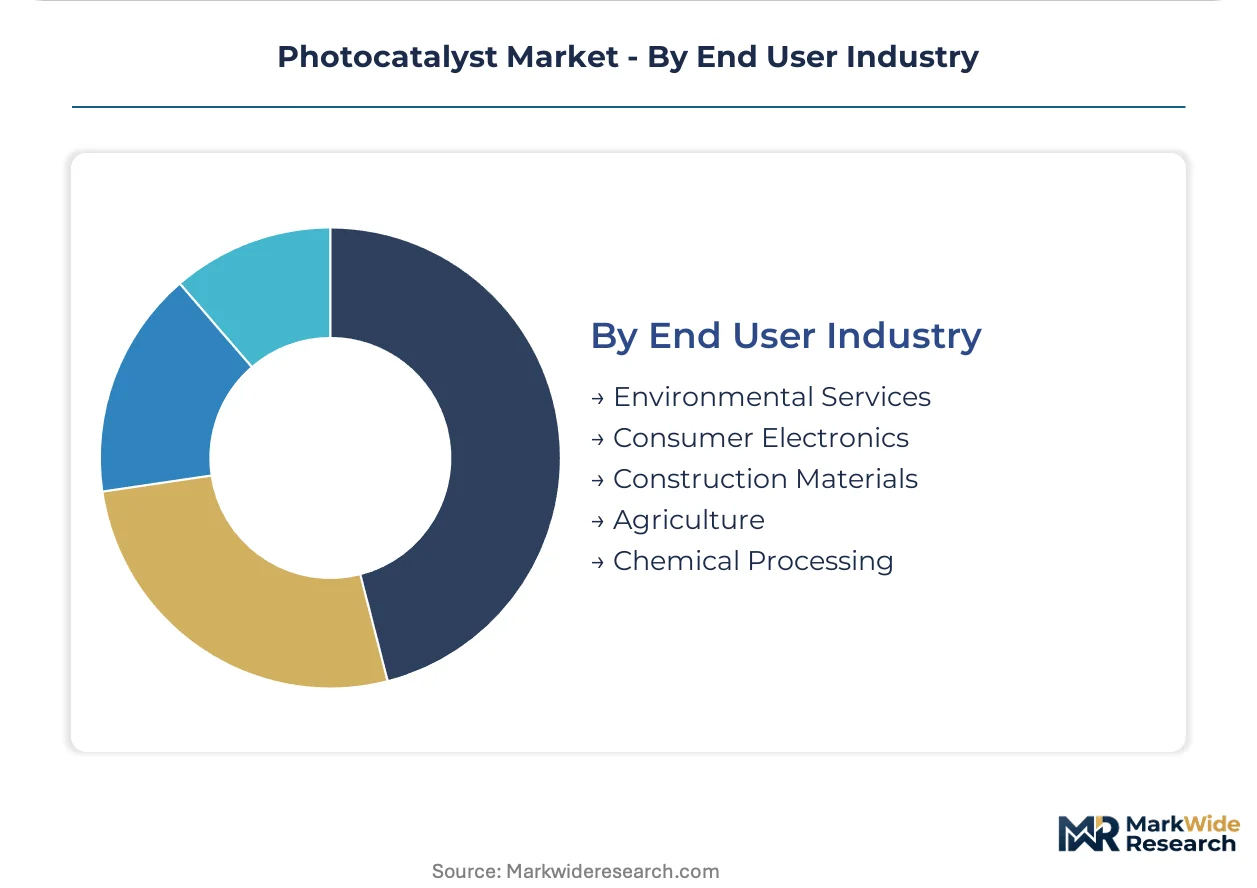
End User Industry:
Environmental services drive specification-driven procurement with regulatory validation requirements, while construction materials reward certified suppliers with multi-year contract stickiness.
- Environmental Services:Municipal wastewater and drinking water utilities mandate documented degradation efficacy. METI building standards in Japan and EPA frameworks in the United States create divergent certification pathways.
- Construction Materials:General contractors in Osaka and Seoul require JIS-certified hydrophilic coatings with documented antimicrobial performance, disadvantaging uncertified commodity suppliers.
- Consumer Electronics:Antibacterial coatings on touchscreens and casings integrate zinc oxide variants.
- Agriculture:Photocatalytic water treatment for irrigation and pesticide degradation remains nascent.
- Chemical Processing:Solar-driven synthesis of hydrogen peroxide and fine chemicals attracts pilot-scale investment.
Environmental services dominate contract value. Construction materials are gaining share fastest as certification requirements extend supplier lock-in.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Photocatalyst trade flows concentrate in East Asian manufacturing corridors, with Japan and South Korea running structural surpluses in high-value formulations while China scales domestic production to reduce import dependency. Europe and North America remain net importers of advanced visible-light-activated materials.
China
Municipal wastewater facilities across the Yangtze River basin deploy graphitic carbon nitride variants under MEE effluent mandates. The country's dual carbon goals accelerate substitution of imported UV-dependent catalysts with domestically manufactured visible-light systems. Production clusters in Jiangsu and Zhejiang provinces supply treatment plants in Shanghai and Nanjing with cost-competitive nano-grade formulations.
Japan
METI's JIS certification pathways for photocatalytic construction materials drive specification-driven procurement in commercial real estate development. Osaka-based general contractors require documented antimicrobial performance for high-touch surface coatings. The Kansai region anchors premium formulation output, with Nagoya and Tokyo metropolitan areas absorbing certified hydrophilic treatments for transit infrastructure.
South Korea
Hospital-acquired infection protocols validate premium pricing for certified photocatalytic surface treatments in Seoul medical facilities. MFDS regulatory alignment with international validation standards enables export qualification for domestic suppliers. The Busan-Ulsan industrial corridor concentrates manufacturing of construction-grade antimicrobial coatings for regional construction projects.
Germany
ECHA's active substance classification deliberations extend market access timelines for novel nano-formulations seeking REACH compliance. The EU Green Deal's zero-pollution ambition accelerates adoption of surface treatments in public building renovation programs. Industrial clusters in North Rhine-Westphalia supply advanced oxidation process components to municipal utilities across the Rhine-Ruhr metropolitan region.
United States
EPA's emerging contaminant framework elevates validation requirements for PFAS treatment in California and Texas municipal water districts. Drinking water utilities must document photocatalytic degradation efficacy for pharmaceutical residues. The Southwest and Gulf Coast regions concentrate procurement authority among certified system integrators serving large-scale treatment facilities.
Photocatalyst Market Key Industry Players
Listed leaders compete with private specialists across certification depth and captive precursor access. The vendor base stratifies between multinational chemical conglomerates with integrated sulfate-process capacity and regional specialists commanding scarcity rents in doping modification expertise. Three archetypes dominate: vertically integrated pigment-to-catalyst converters, JIS-certified construction material suppliers, and visible-light doping technology licensors. Competitive moves center on backward integration into high-purity titanium tetrachloride supply and multi-year ISO 27448 certification investments that extend contract stickiness.
Within the premium-tier vector, Mitsubishi Chemical Group Corporation and TOTO Ltd. exemplify divergent specialization strategies. Mitsubishi's captive precursor supply anchors pharmaceutical-grade output, while TOTO's proprietary surface patents command specification-driven procurement in Japanese commercial construction. KRONOS Worldwide Inc. occupies a position among North American sulfate-process integrators, converting pigment infrastructure into environmental catalyst capacity. These three entities collectively represent the tension between scale-driven commodity production and validation-dependent premium positioning.
| Leading Market Players |
|---|
| Mitsubishi Chemical Group Corporation |
| KRONOS Worldwide Inc. |
| TOTO Ltd. |
| Japan Photocatalyst Center Co. Ltd. |
| Tayca Corporation |
| Showa Denko K.K. |
| Evonik Industries AG |
| Sakai Chemical Industry Co. Ltd. |
| Ishihara Sangyo Kaisha Ltd. |
| Others |
Cost & Logistics Intelligence
Visible-light doping techniques replacing UV-dependent titanium dioxide formulations simultaneously shift supply geography toward East Asian semiconductor corridors and compress pricing power for legacy sulfate-process producers. Municipal buyers in China's Yangtze River basin now source graphitic carbon nitride variants from Jiangsu production clusters at cost structures that undercut imported nano-grade anatase by eliminating chloride-route precursor premiums.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Certification grade under JIS and ISO standards separates pharmaceutical-grade outputs from construction-grade commodities, while volume scale determines contract terms for municipal water utilities. Cost compression in UV-activated titanium dioxide intensifies because sulfate-process overcapacity in North America feeds spot-market liquidity. Environmental services procurement teams exhibit highest price sensitivity due to public-budget constraints; healthcare infrastructure buyers show lowest sensitivity given infection-protocol mandates.
Supply Chain Analysis
Container availability on the Shanghai-Rotterdam trade lane constrains inbound logistics for European formulators seeking East Asian doping precursors. Supply concentrates in China, Japan, and South Korea, with Jiangsu and Zhejiang provinces feeding domestic wastewater facilities while Kansai and Busan-Ulsan corridors export certified construction coatings. High-purity titanium tetrachloride, nitrogen-dopant feedstocks, and graphitic carbon nitride monomers constitute critical input dependencies. Single-source vulnerability runs through chloride-route precursor corridors controlled by integrated chemical conglomerates. Distribution runs through specification-driven procurement channels where JIS-certified system integrators dominate commercial construction.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Photocatalyst procurement is consolidating around platform economics where JIS certification pathways and EPA validation frameworks create interoperability standards that lock in supplier ecosystems. The shift from commodity titanium dioxide to engineered visible-light systems rewards ecosystem orchestrators over component vendors.
For Market Incumbents: Compound certification depth to extend contract stickiness. Invest multi-year working capital into ISO 27448 validation timelines for self-cleaning construction coatings before regional competitors achieve JIS equivalence. Backward integration into high-purity titanium tetrachloride supply insulates margin structures from chloride-route feedstock volatility.
For New Entrants and Emerging Players: Lead with doping modification expertise in visible-light activation as the most penetrable technical wedge. Target South Korean healthcare infrastructure where MFDS regulatory alignment enables export qualification faster than Japanese METI pathways. Pursue licensing arrangements with established construction material suppliers rather than direct specification battles.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional coating specialists holding JIS certifications but lacking global distribution. Five-to-ten-year viability hinges on regulatory divergence between photocatalyst classification as active substances versus materials across ECHA and EPA jurisdictions. Watch ECHA's nano-formulation classification deliberations as the signal for registration burden inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Supply | Mitsubishi Chemical's captive titanium tetrachloride production anchors pharmaceutical-grade output cost structures. |
| JIS Certification Investment | TOTO Ltd.'s proprietary hydrophilic surface patents command specification-driven procurement in Osaka commercial construction. |
| Visible-Light Doping Technology Licensing | Regional specialists monetize scarcity rents in nitrogen-modified tungsten oxide formulation expertise. |
| Healthcare Infrastructure Partnership | Seoul medical facility contracts validate premium pricing for antimicrobial surface treatments under infection protocols. |
| REACH Compliance Automation | First-mover advantage accrues to coating suppliers navigating ECHA's active substance classification uncertainty. |
Research Approach
Initial hypotheses were tested against primary input from plant managers at sulfate-process facilities, procurement leads at municipal water utilities, technical R&D directors specializing in bandgap engineering, and construction specification officers in Osaka and Seoul. These perspectives were refined against secondary validation from customs and trade data, METI and EPA regulatory filings, JIS certification registries, and SEC disclosures from listed chemical conglomerates. Bottom-up facility capacity assessments and top-down end-use demand estimates were triangulated to constrain variance.
Variance decomposition across the projection horizon isolates volume drivers by material chemistry, activation mechanism, and end-use validation tier. The analytical framework models titanium dioxide grade tier, visible-light versus UV activation technology, water purification versus antimicrobial application, and regional regulatory cluster as core segmentation dimensions. CAGRs were derived from fitted growth curves incorporating MEE effluent mandate implementation timelines and METI building standard adoption rates.
The analysis sits within stated boundaries; outcomes outside continued regulatory enforcement of dual carbon goals and emerging contaminant frameworks would require recalibration. Forecasts reflect assumptions about certification pathway stability and precursor supply concentration. Technological substitution in electron-hole recombination engineering or reclassification of nano-formulations under REACH could materially revise trajectory. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Catalysts
Catalyst Carrier Market
Catalysts
Europe Homogeneous Precious Metal Catalyst Market
Catalysts
Industrial Catalyst Market
Catalysts
Hydrogenation Catalyst Market
Catalysts
Residue Hydrodesulphurization Catalyst Market
Catalysts
Petrochemical Catalyst Market
Catalysts
Hydrodesulfurization Catalyst Market
Catalysts
CO2 Reforming Catalysts Market
Catalysts
Inorganic Catalyst Market
Catalysts
Refinery Catalyst Market
Catalysts
Marine Selective Catalytic Reduction Systems Market
Catalysts
Phosphorus Based Catalyst Market
Catalysts
Global VOC Catalysts Market
Catalysts
Organic Catalyst Market
Catalysts
Platinum and Palladium Carbon Catalyst Market
Catalysts
Polymerization Catalysts Market